
 Vacuum Truck Rentals Market | 2026-2036
Vacuum Truck Rentals Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Truck Rentals Market Insights
Heavy-duty specification-tier demand is collapsing into a narrower band of EPA-certified vacuum trucks with higher payload capacity and automated tank cleaning systems. Clean Harbors, Inc. leverages its integrated hazardous waste disposal network to bundle rental services with downstream processing. Veolia Environmental Services anchors European municipal contracts through long-term fleet service agreements. Federal Signal Corporation differentiates via in-house manufacturing of vacuum components that it supplies to its rental subsidiaries.
A vacuum truck rental denotes the temporary provision of suction-equipped commercial vehicles engineered to extract liquids, slurries, and semi-solids through negative-pressure systems typically generating 15 to 28 inches of mercury, with tank capacities ranging from 1,000 to 6,000 gallons depending on chassis configuration and DOT road-weight compliance. The equipment serves industrial cleaning, environmental remediation, and infrastructure maintenance where capital ownership proves uneconomical for intermittent or project-based demand. Heavy-duty vehicle types command the largest revenue share due to oilfield and refinery turnaround requirements, while emergency services within the service-type dimension generate premium pricing multiples during hurricane response and pipeline rupture events. Trailer-mounted configurations represent the fastest-expanding category as contractors seek transportable suction capacity without dedicated power-unit investment.
EPA regulations under the Resource Conservation and Recovery Act govern hazardous waste transport certification for rental operators, while OSHA standards mandate atmospheric monitoring and ventilation protocols for vacuum truck deployment in confined-space industrial cleaning. DOT Federal Motor Carrier Safety Administration rules further dictate driver qualification and vehicle inspection intervals that rental providers must embed in fleet management systems. Stakeholders should monitor state-level environmental enforcement intensity and municipal procurement shifts toward performance-based rental contracts rather than per-day rate structures.
Market Dynamics
Municipal wastewater departments across the United States are accelerating fleet rental adoption rather than capital ownership, compressing procurement cycles and forcing rental providers to embed EPA spill-response certification directly into standard contract terms.
Growth Catalysts
- OSHA Confined-Space Mandates:Stricter atmospheric monitoring and ventilation protocols for industrial cleaning operations are compelling contractors to rent certified vacuum trucks rather than retrofit owned fleets.
- Petrochemical Turnaround Intensity:Scheduled maintenance cycles at Gulf Coast refineries are generating concentrated demand for heavy-duty vacuum excavation capacity during narrow seasonal windows.
- Trailer-Mounted Configurations:Transportable suction systems without dedicated power-unit investment are expanding addressable demand among mid-size environmental remediation contractors.
Market Restraints
- DOT Driver Qualification Bottlenecks:Federal Motor Carrier Safety Administration rules extending vehicle inspection intervals and driver certification timelines are constraining fleet utilization rates.
- Steel and Chassis Input Volatility:Fluctuating commodity prices for specialized tank-grade steel and commercial truck chassis are compressing rental margin predictability.
- RCRA Certification Friction:Resource Conservation and Recovery Act hazardous waste transport requirements create multi-state operational complexity for rental operators seeking national coverage.
Strategic Opportunities
- Hurricane Response Prepositioning:Emergency services contracts with FEMA and state environmental agencies offer premium pricing multiples for rapid-deployment vacuum capacity along Atlantic and Gulf coasts.
- Automated Tank Cleaning Convergence:Integration of robotic interior cleaning systems with rental fleet telematics is reducing turnaround downtime between customers.
- Performance-Based Contracting:Municipal procurement offices in Texas and Louisiana are piloting cubic-yard-removed pricing models rather than per-day rate structures.
Industry Challenges
- Certified Vacuum Technician Scarcity:Operators with combined CDL credentials and hazardous materials endorsements command wage premiums that inflate fleet operating costs.
- Legacy Fleet Integration Complexity:Retrofitting older rental units with EPA-compliant vapor recovery systems requires extended downtime that conflicts with high-utilization business models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Truck Rentals Market |
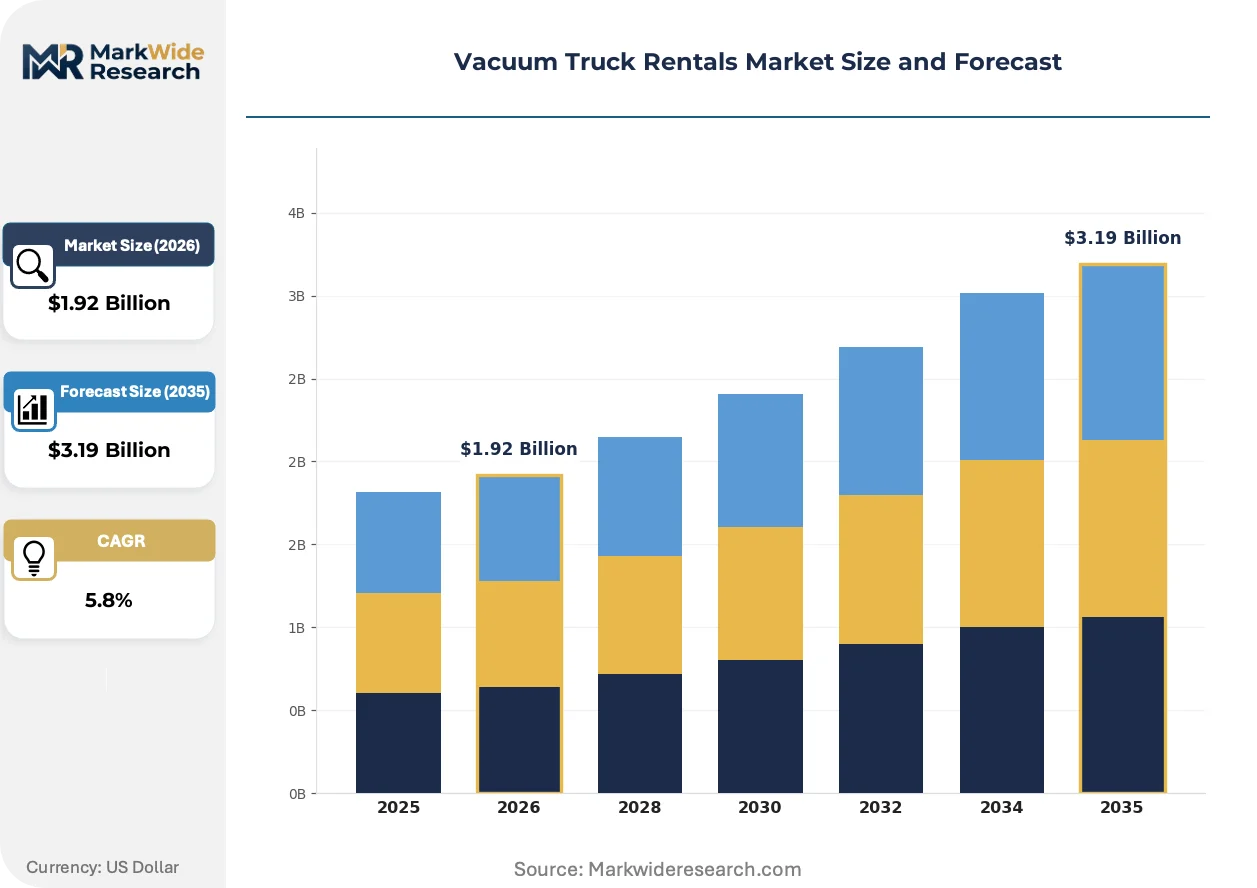
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.19 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Standard, Heavy-Duty, Compact, Trailer-Mounted Service Type: Short-Term Rental, Long-Term Rental, Emergency Services, Scheduled Maintenance End User: Construction, Municipalities, Oil & Gas, Environmental Services Application: Liquid Waste Removal, Spill Cleanup, Infrastructure Maintenance, Industrial Cleaning |
| Companies Covered | Clean Harbors, Inc., Waste Management, Inc., Veolia Environmental Services, GFL Environmental Inc., Republic Services, Inc., HydroChemPSC, Ranger Environmental Services, Federal Signal Corporation, Vac-Con, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Truck Rentals Market Trends and Innovations
Equipment specification is narrowing toward higher-payload automated systems, while contract structures evolve from daily rates to output-based metrics. Regulatory certification is becoming a competitive differentiator rather than a baseline requirement.
Telematics-enabled predictive maintenance is supplanting scheduled interval servicing across rental fleets. Oilfield service contractors in the Permian Basin are adopting sensor-equipped vacuum trucks that transmit tank levels and engine diagnostics in real time. This connectivity is compressing unplanned downtime and enabling dynamic fleet repositioning between active drilling sites.
EPA enforcement intensity under the Clean Water Act is tightening discharge documentation requirements for vacuum truck wastewater disposal. Rental providers must now embed chain-of-custody tracking into standard service agreements. Gulf Coast petrochemical facilities are responding by demanding bundled rental-plus-disposal contracts that transfer liability downstream.
Equipment-as-a-service contracting is displacing traditional dry-hire arrangements in municipal wastewater departments. Texas cities including Houston and Dallas are piloting multi-year fleet service agreements that bundle maintenance, certification renewal, and operator training. This procurement evolution concentrates purchasing authority with procurement officers rather than field operations managers.
Vacuum Truck Rentals Market Segmentation
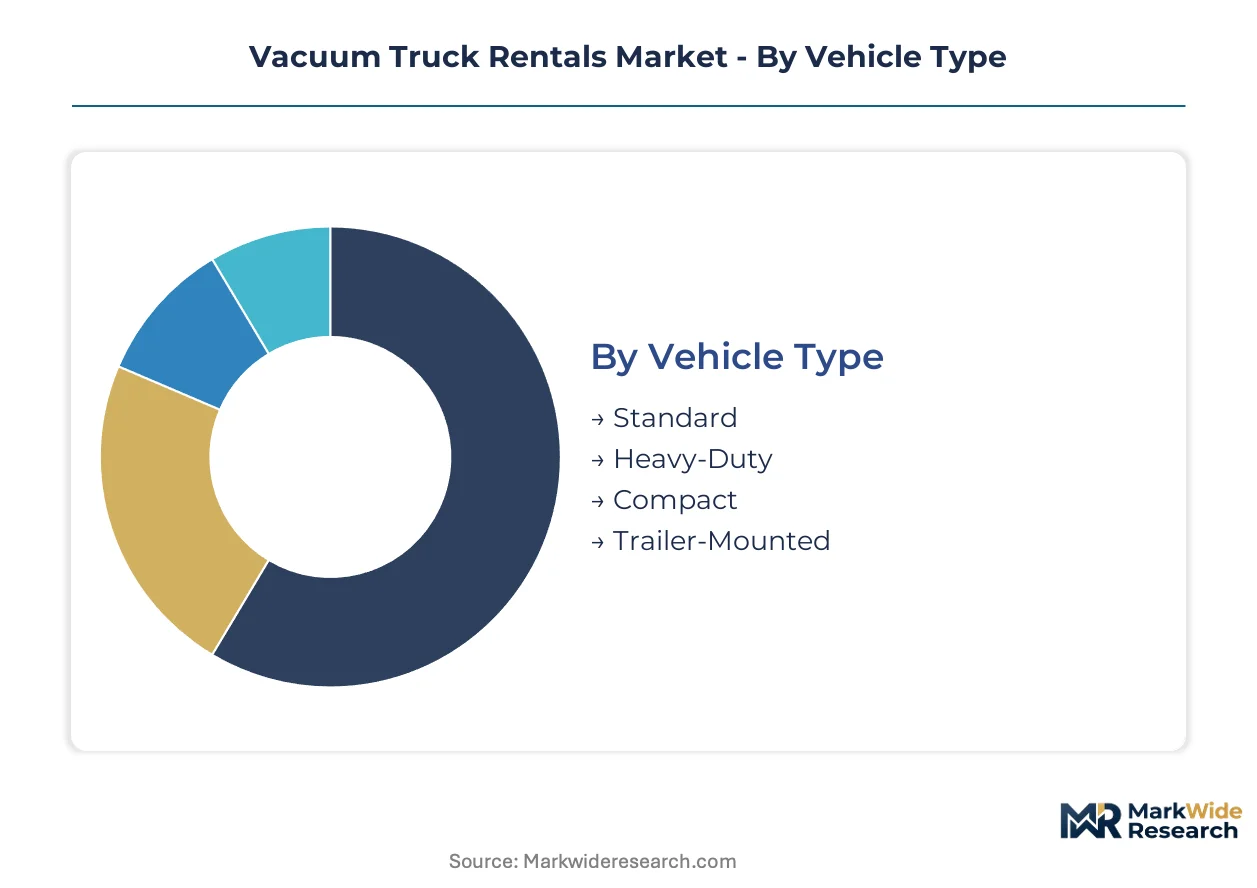
Equipment specification tiers and contract duration structures determine rental yield curves across the vacuum truck market. Segmentation reveals where capital-light operators can capture margin without fleet ownership burdens.
Vehicle Type:
Margin pools concentrate in chassis configurations that command premium day-rates through specialized payload certification.
- Heavy-Duty:These units integrate 6,000-gallon tank capacity with DOT-compliant weight distribution for refinery turnaround and oilfield produced-water evacuation. Demand clusters in Texas and Louisiana where EPA spill-response mandates require vapor-recovery-equipped fleets for petrochemical maintenance.
- Trailer-Mounted:Transportable suction systems decouple power-unit investment from tank capacity, enabling mid-size contractors to deploy 3,000-gallon recovery capacity behind standard CDL-licensed tractors. Permian Basin environmental remediation firms are expanding trailer fleets fastest.
- Standard:Municipal wastewater departments deploy these 1,500-2,500 gallon units for routine lift-station maintenance across Texas cities.
- Compact:Urban infrastructure contractors favor maneuverable chassis for confined-space utility vault cleaning in Dallas and Houston downtown cores.
The dominant share belongs to Heavy-Duty, while Trailer-Mounted is closing the gap fastest.
Service Type:
Contract duration structures separate steady-state municipal revenue from event-driven emergency premiums.
- Emergency Services:Hurricane response and pipeline rupture events trigger FEMA-activated deployments with pricing multiples exceeding routine rentals. Atlantic and Gulf Coast prepositioning contracts require 24-hour mobilization guarantees.
- Long-Term Rental:Multi-year fleet service agreements bundle maintenance, certification renewal, and operator training for municipal procurement offices in Houston and Dallas.
- Short-Term Rental:Project-based construction and industrial cleaning demand drives 30-90 day contract cycles with higher per-day rates.
- Scheduled Maintenance:Refinery turnaround seasons generate concentrated Gulf Coast demand during narrow spring and fall windows.
Emergency Services commands the steepest premium expansion trajectory, with Long-Term Rental securing the most predictable revenue base.
End User:
Customer-type segmentation tracks capital-conversion patterns as asset ownership gives way to operational expenditure models.
- Oil & Gas:Permian Basin operators and Gulf Coast refiners drive heavy-duty utilization through produced-water management and turnaround cleaning cycles.
- Municipalities:Texas and Louisiana wastewater departments are accelerating rental adoption over capital procurement, compressing vendor selection cycles.
- Environmental Services:Remediation contractors deploy trailer-mounted systems for hazardous waste site characterization and removal.
- Construction:Underground utility contractors utilize compact and standard units for trench dewatering and excavation support.
Oil & Gas retains the largest revenue concentration, though Municipalities are shifting procurement fastest toward performance-based contracting.
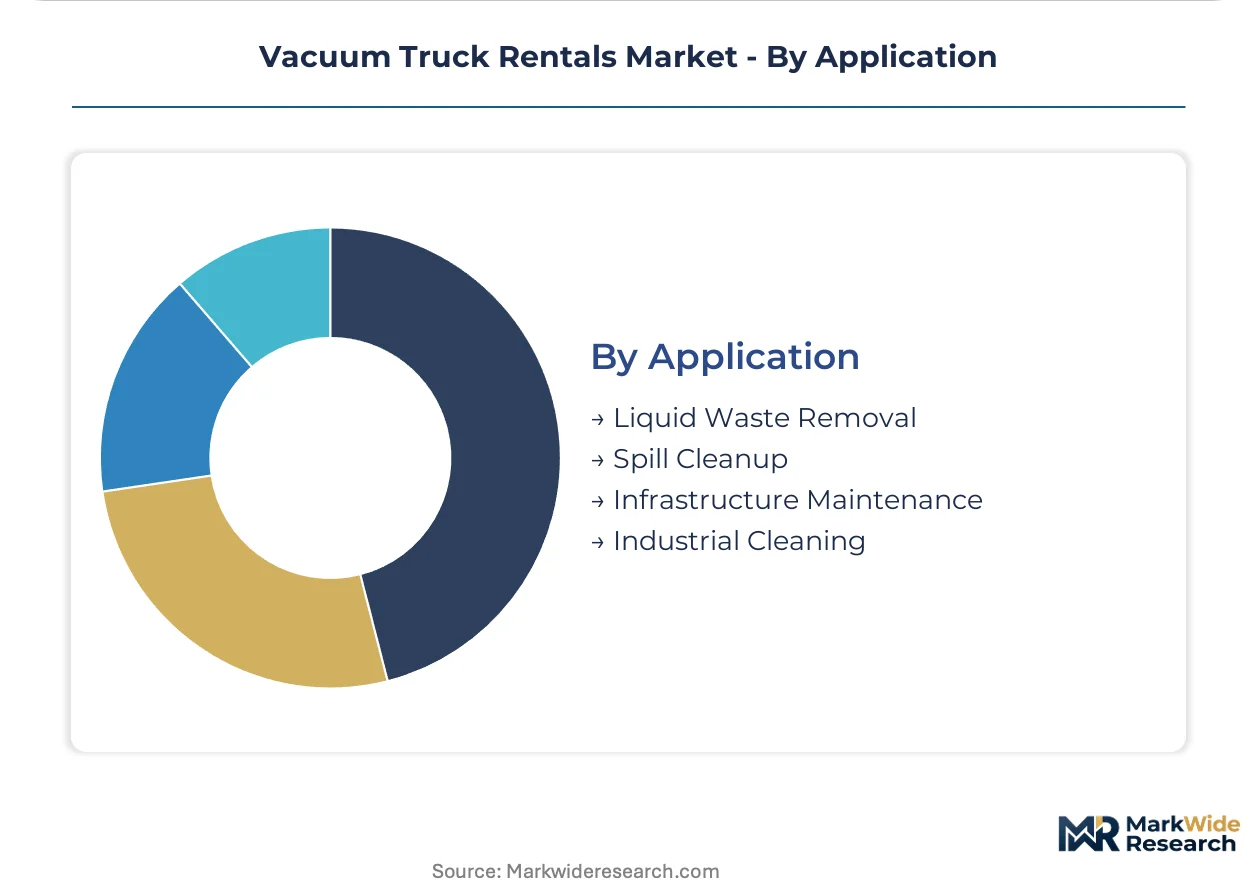
Application:
Use-case differentiation separates commodity liquid hauling from specialized industrial services with certification barriers.
- Industrial Cleaning:OSHA confined-space mandates drive demand for atmospheric monitoring-equipped trucks in petrochemical vessel entry and tank cleaning operations.
- Spill Cleanup:EPA RCRA certification requirements create vendor stickiness for hazardous material response, with bundled disposal contracts transferring liability downstream.
- Liquid Waste Removal:Routine septic, grease trap, and wastewater hauling represents volume-driven baseline demand with compressed margins.
- Infrastructure Maintenance:Municipal sewer line cleaning and storm drain recovery generates recurring seasonal demand patterns.
Industrial Cleaning captures the highest margin per deployment, while Spill Cleanup is expanding most quickly through regulatory enforcement intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural trade surplus in vacuum truck rental services, exporting specialized heavy-duty capacity to Canadian oil sands operators while importing compact urban units from European manufacturers. Cross-border equipment flows concentrate along the Texas-Mexico corridor and the Alberta-Montana pipeline maintenance corridor.
United States
EPA spill-response mandates and OSHA confined-space protocols drive fleet certification upgrades across Texas, Louisiana, and North Dakota oilfield basins. The Resource Conservation and Recovery Act creates multi-state operational complexity for rental operators seeking national coverage. Houston anchors Gulf Coast petrochemical turnaround demand, where Clean Harbors bundles rental services with downstream hazardous waste processing.
Canada
Alberta oil sands producers rent heavy-duty vacuum capacity for tailings pond management and produced-water evacuation during seasonal maintenance windows. Environment and Climate Change Canada regulations govern hazardous waste transport certification for cross-provincial fleet deployment. Calgary-based contractors source trailer-mounted systems from US manufacturers to avoid dedicated power-unit capital expenditure.
Mexico
Pemex refinery maintenance cycles and private-sector pipeline construction generate concentrated demand in Tamaulipas and Veracruz states. SEMARNAT environmental enforcement is tightening discharge documentation requirements for vacuum truck wastewater disposal. Monterrey industrial corridor contractors are adopting equipment-as-a-service contracting models previously piloted in Texas cities.
Germany
Chemical industry maintenance turnarounds at BASF Ludwigshafen and Bayer Leverkusen complexes drive scheduled rental demand with narrow seasonal windows. REACH regulations and EU Green Deal decarbonization targets mandate vapor-recovery-equipped fleets for petrochemical vessel cleaning. Ruhr Valley municipal wastewater departments are accelerating rental adoption over capital procurement.
Saudi Arabia
Aramco maintenance schedules and SABIC petrochemical turnaround cycles generate premium pricing for rapid-deployment vacuum capacity in the Eastern Province. Saudi Environmental Special Forces enforcement under Vision 2030 is tightening hazardous waste transport certification requirements. Jubail Industrial City contractors are piloting performance-based cubic-meter-removed pricing models rather than per-day rate structures.
Vacuum Truck Rentals Market Competitive Landscape
Concentration sits with integrated environmental services conglomerates that bundle rental capacity with downstream waste processing and disposal infrastructure. The vendor base stratifies across three tiers: national-scale hazardous waste specialists with captive rental fleets, regional equipment rental pure-plays focused on oilfield and municipal verticals, and manufacturer-captive rental subsidiaries leveraging in-house component production. Dominant competitive moves include M&A-driven geographic expansion into Permian Basin and Gulf Coast markets, and backward integration into vacuum pump and tank fabrication to control input costs.
Within the integrated services tier, Clean Harbors, Inc. and Veolia Environmental Services exemplify archetypes that combine rental fleet operations with hazardous waste disposal networks. Federal Signal Corporation occupies a manufacturer-integrated position, supplying vacuum components to rental subsidiaries from in-house production. These three entities anchor competitive positioning across North American and European markets.
| Leading Market Players |
|---|
| Clean Harbors, Inc. |
| Waste Management, Inc. |
| Veolia Environmental Services |
| GFL Environmental Inc. |
| Republic Services, Inc. |
| HydroChemPSC |
| Ranger Environmental Services |
| Federal Signal Corporation |
| Vac-Con, Inc. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day chassis delivery windows from Detroit manufacturers compress rental fleet expansion timelines and concentrate pricing power with domestic tank fabricators holding DOT-certified welding capacity. EPA vapor-recovery certification requirements create tiered entry barriers that segment day-rate structures between compliant heavy-duty units and legacy standard configurations. Municipal procurement officers in Houston and Dallas negotiate multi-year service agreements that lock in predictable margins for integrated providers while exposing pure-play rental operators to spot-market volatility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Gulf Coast petrochemical facilities, with pricing stratifying across EPA-certified premium, DOT-compliant standard, and non-certified economy tiers. Price differentiation rests on hazardous materials endorsement levels and bundled disposal liability transfer. Cost compression in the standard tier is intensifying because municipal budget constraints favor lowest-compliant-bid procurement. Environmental remediation contractors show highest price sensitivity due to project-based cash flow cycles, while integrated waste processors demonstrate lowest sensitivity through captive downstream margins.
Supply Chain Analysis
One-hundred-twenty-day lead times for specialized tank-grade steel from domestic mills tether fleet expansion schedules to commodity cycle volatility. Manufacturing concentrates in the United States, Canada, and Germany, with chassis assembly drawing from Detroit, Ontario, and Stuttgart production hubs. Raw material dependencies center on high-strength steel plate, vacuum pump components, and DOT-certified valve assemblies. Single-source vulnerability runs through EPA-certified tank fabrication facilities holding limited welding certifications. Distribution runs through regional equipment dealers and direct municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat where RCRA certification networks and EPA spill-response prequalification create switching costs that cement incumbent positions.
For Market Incumbents: Consolidate Gulf Coast and Permian Basin fleet density through targeted acquisitions of regional rental pure-plays lacking downstream disposal infrastructure. Retrofit legacy units with automated tank cleaning systems to compress turnaround downtime and defend utilization rates against trailer-mounted competitors. Backward integration into vacuum pump fabrication insulates margin pressure from chassis input volatility. For New Entrants and Emerging Players: Lead with trailer-mounted configurations targeting mid-size environmental remediation contractors in the Permian Basin and Monterrey industrial corridor. Equipment-as-a-service contracting models remain underpenetrated in municipal wastewater departments outside Texas pilot cities. Position through telematics-enabled predictive maintenance guarantees that differentiate against aging incumbent fleets. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory certification intensity and capital requirements favor scaled operators with integrated disposal networks. Target regional rental pure-plays holding EPA prequalification in high-enforcement states. Monitor state-level environmental enforcement intensity as the inflection signal for pricing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | In-house vacuum pump fabrication reduces exposure to chassis supplier pricing volatility. |
| Performance-Based Contracting | Cubic-yard-removed pricing models align municipal procurement with actual service output. |
| Telematics Fleet Integration | Real-time tank level transmission enables dynamic repositioning between active drilling sites. |
| RCRA Certification Expansion | Multi-state hazardous waste transport authorization unlocks national account coverage. |
| Emergency Response Prepositioning | FEMA-activated deployment contracts capture premium pricing multiples during hurricane season. |
Research Methodology
The analysis maps heavy-duty, trailer-mounted, standard, and compact vehicle configurations, each validated through fleet operations managers, municipal procurement officers, environmental remediation contractors, and petrochemical maintenance directors. Primary fieldwork combined structured interviews with secondary validation against EPA enforcement databases, DOT FMCSA inspection records, SEC 10-K filings from integrated waste processors, and state-level municipal procurement contract disclosures. Bottom-up fleet utilization modeling triangulated against top-down addressable demand estimates from oilfield service expenditure patterns.
Consistency checks validated volume and value outputs against external benchmarks including petrochemical turnaround scheduling databases and hurricane response deployment records across the analysis window. Segmentation dimensions modeled include vehicle type, service duration structure, end-user industry, and application use-case. CAGRs derived from equipment replacement cycles and regulatory compliance upgrade timelines. Forecast inputs incorporated chassis delivery lead times and EPA enforcement staffing levels as demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained oilfield activity levels or accelerated municipal procurement shifts would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and steel price normalization. Specific risk factors include DOT driver qualification bottlenecks and state-level environmental budget volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
Global Taxi Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
Vietnam Taxi Market
Transportation Services
Germany Car Rental Market
Transportation Services
India Taxi Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
India Car Rental Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
Ship Management Software Market
Transportation Services
North America International Express Service Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Scandinavia Car Rental Market