
 Russia Car Rental Market | 2026-2036
Russia Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Car Rental Market Analytics
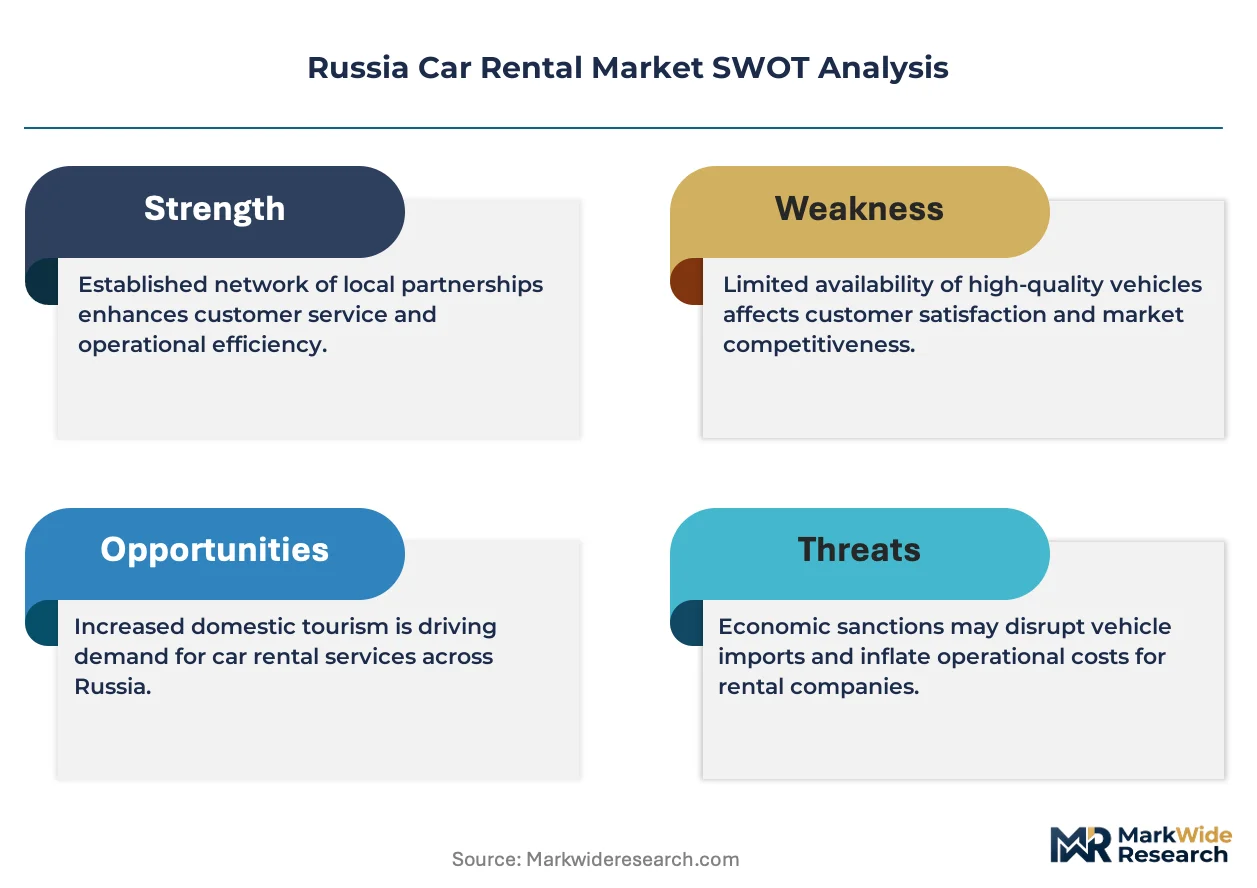
Asset-light leasing and subscription-based fleet financing is narrowing the capital barrier for new entrants in the Russia car rental sector. Delimobil leverages its integrated mobility platform to sustain density across Moscow's high-traffic zones. Yandex Drive anchors its position through data-driven fleet allocation and real-time demand matching. Rentmotors differentiates by specializing in airport-centric operations with dedicated terminal infrastructure.
A car rental operation constitutes a temporary vehicle use-right transfer where fleet owners retain title while customers obtain operational control for defined durations, with units typically maintained to manufacturer service intervals and regional safety inspection standards. The primary commercial purpose centers on converting fixed automotive assets into recurring revenue streams without transferring ownership. Short-term rentals dominate transaction volume during peak tourism and business travel windows, while long-term rentals capture sustained margin pools from corporate clients seeking fleet flexibility without depreciation exposure. Chauffeured services command premium pricing tiers in Moscow and Saint Petersburg where executive transport protocols require vetted driver credentials.
Russia's Federal Antimonopoly Service monitors pricing transparency and contract terms across mobility services, while GOST R standards enforce vehicle safety and emissions compliance for commercial fleet registration. The Ministry of Transport coordinates regional permitting that shapes where operators can establish pickup locations and cross-border service corridors. Stakeholders must weigh fleet electrification timelines against charging infrastructure gaps and evolving customs duties on imported vehicles.
Market Dynamics
Russia's updated technical regulation on vehicle safety compliance is accelerating fleet refresh cycles nationwide, forcing operators to retire aging inventory faster than depreciation schedules originally planned. Corporate clients now prioritize operational flexibility over asset ownership, redirecting capital toward subscription-based mobility services.
Growth Catalysts
- Corporate Fleet Outsourcing:Enterprises across Moscow and Saint Petersburg are shedding owned vehicle assets in favor of operational leases, converting fixed costs into variable expenditure.
- GOST R Standards Enforcement:Mandatory vehicle safety and emissions compliance for commercial fleet registration is creating replacement demand for non-compliant inventory.
- Airport Traffic Concentration:Sustained inbound travel through Sheremetyevo and Pulkovo terminals maintains utilization rates above regional averages.
Market Restraints
- Imported Vehicle Customs Duties:Evolving tariff structures on foreign-manufactured fleet additions inflate acquisition costs for operators dependent on non-domestic supply.
- Charging Infrastructure Gaps:Sparse high-speed charging networks outside Moscow and Saint Petersburg limit electrification timelines for commercial fleets.
- Regional Permitting Fragmentation:Ministry of Transport coordination requirements vary across federal subjects, complicating cross-corridor service establishment.
Strategic Opportunities
- Chauffeured Executive Transport:Premium pricing tiers in Moscow and Saint Petersburg reward operators with vetted driver credentialing protocols.
- Long-Term Corporate Leasing:Sustained margin pools await providers offering depreciation-free fleet flexibility to enterprise clients.
- Integrated Mobility Platforms:Technology convergence between car rental and ride-hailing is enabling density optimization across high-traffic urban zones.
Industry Challenges
- Certification Timeline Compression:Federal Antimonopoly Service monitoring of pricing transparency and contract terms demands accelerated compliance documentation.
- Depreciation Exposure Management:Rapid fleet refresh requirements strain balance sheets as residual values fluctuate with regulatory changes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Car Rental Market |
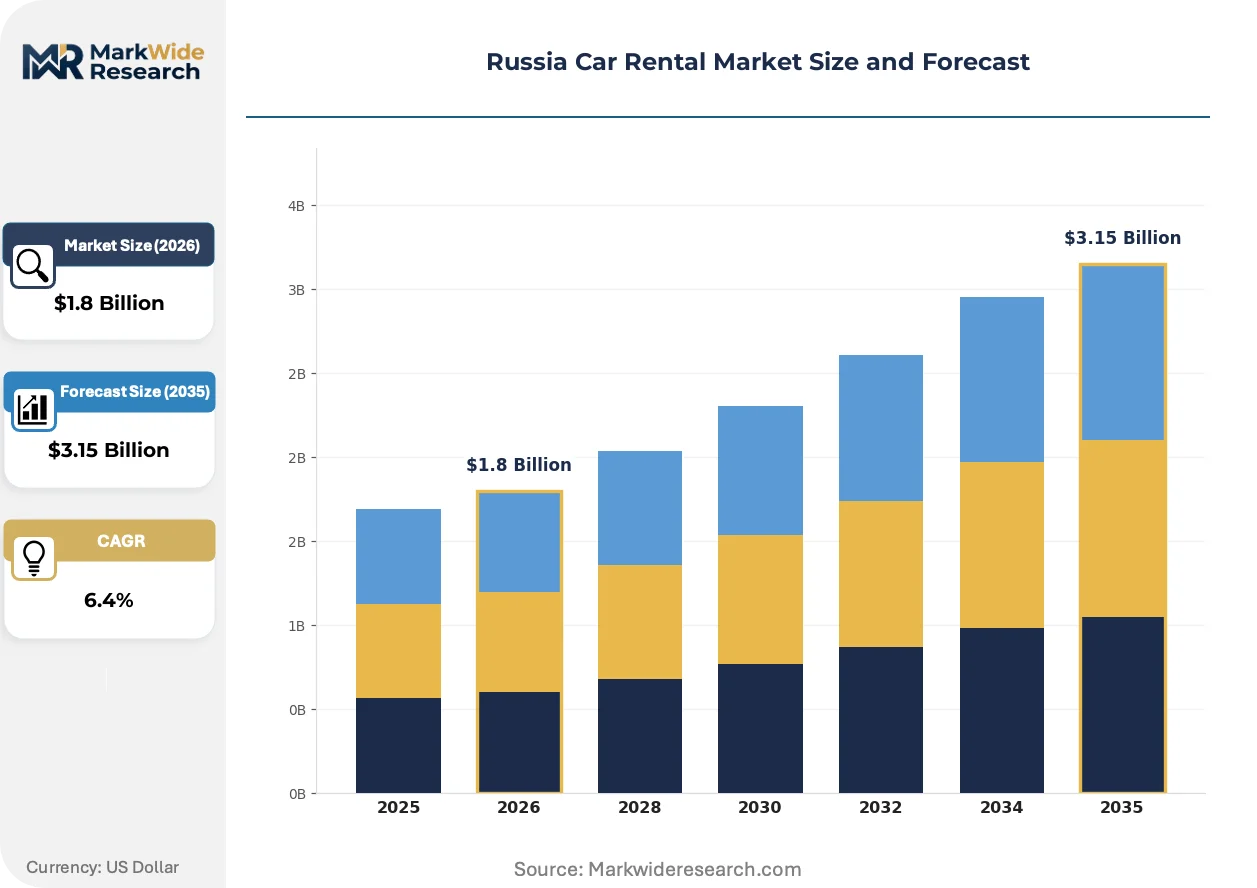
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-Term Rentals, Long-Term Rentals, Chauffeured Services, Leaseback Vehicle Type: Economy, Luxury, SUVs, Vans Customer Type: Corporate Clients, Tourists, Locals, Government Agencies Booking Channel: Online Platforms, Travel Agencies, Direct Rental Locations, Mobile Apps |
| Companies Covered | Delimobil, Yandex Drive, BelkaCar, Citydrive, Rentmotors, RexRent, YouDrive, Naprokat.ru, Avis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Car Rental Market Evolving Landscape
Digital fleet management systems are compressing operational decision cycles across Russia's car rental sector. Real-time demand matching algorithms now govern vehicle allocation. Subscription financing models are displacing traditional ownership structures.
Telematics-enabled predictive maintenance is rendering obsolete scheduled service intervals based on mileage alone. Corporate fleet managers in Moscow are adopting condition-based monitoring at accelerated pace. This shift is compressing downtime windows and extending productive asset life.
Russia's Federal Antimonopoly Service pricing transparency mandates are reshaping contract standardization across mobility services. Operators must now disclose tariff structures in machine-readable formats. Short-term rental segments are responding with simplified rate cards to reduce compliance friction.
Consumption patterns among Russian corporate clients are pivoting toward bundled mobility-as-a-service offerings. Traditional daily-rate rentals are losing ground to all-inclusive monthly subscriptions. This behavioral shift is most visible in Saint Petersburg's enterprise procurement channels.
Russia Car Rental Market Segmentation
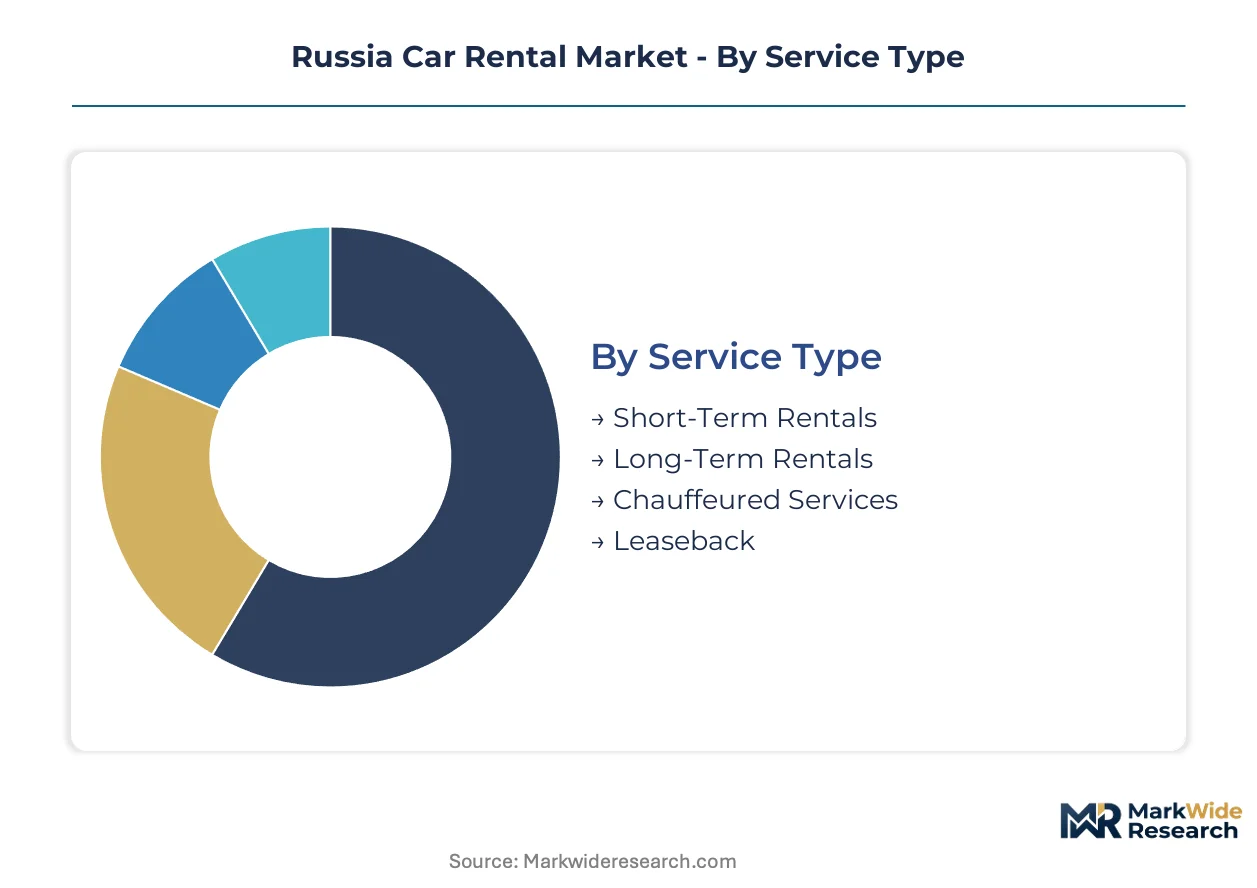
Segmentation in Russia's car rental market reveals how distinct customer workflows, vehicle specifications, and procurement channels create specialized operational requirements. Each dimension demands tailored fleet composition, pricing architecture, and service protocols to capture value across divergent use cases.
Service Type:
The use-case spectrum spans transactional mobility to embedded fleet solutions, with duration and control intensity defining operational models.
- Short-Term Rentals:Daily or weekly vehicle access with full customer operational control dominates airport corridors and city-center locations. Sheremetyevo and Pulkovo terminals sustain peak utilization during business travel and tourism windows, with operators optimizing turnaround logistics to maximize asset yield.
- Long-Term Rentals:Multi-month operational leases transfer vehicle control while retaining title with the fleet owner, converting corporate fixed costs into variable expenditure. Moscow enterprises favor these structures to eliminate depreciation exposure and GOST R compliance administration from their balance sheets.
- Chauffeured Services:Driver-supplied executive transport commands premium positioning in Saint Petersburg's diplomatic and financial districts.
- Leaseback:Sale-and-leaseback arrangements enable asset-heavy enterprises to monetize owned fleets while retaining operational access.
Established volume favors Short-Term Rentals; emerging adoption favors Long-Term Rentals.
Vehicle Type:
Cost tier differentiation separates mass-market accessibility from margin-intensive premium positioning across Russian fleet portfolios.
- Economy:Compact, fuel-efficient vehicles with minimal amenity specifications serve price-sensitive segments and high-frequency urban circulation. Demand concentrates in Moscow's dense metropolitan core where parking constraints and traffic density favor smaller footprints.
- Luxury:Premium-brand sedans and performance vehicles with elevated interior specifications target executive transport and high-net-worth individual segments. Saint Petersburg's hospitality and diplomatic channels sustain this tier despite higher per-unit acquisition costs.
- SUVs:All-terrain capability vehicles address Russia's climatic variability and road infrastructure heterogeneity.
- Vans:Multi-passenger and light-commercial configurations serve group transport and last-mile logistics requirements.
Volume concentration sits with Economy; margin expansion sits with Luxury.
Customer Type:
Procurement authority and budget predictability distinguish organizational demand from individual decision-making patterns.
- Corporate Clients:Enterprise procurement departments with negotiated master service agreements and centralized billing requirements drive contract-based revenue stability. Fleet outsourcing mandates from Moscow-headquartered companies are accelerating subscription model adoption.
- Tourists:Inbound travelers with episodic, destination-specific mobility needs generate seasonal demand spikes aligned with visa and aviation schedules.
- Locals:Resident individuals accessing supplemental mobility for specific life events or temporary vehicle replacement.
- Government Agencies:Public-sector procurement with mandated tender processes and compliance documentation requirements.
Contract predictability favors Corporate Clients; volume volatility sits with Tourists.
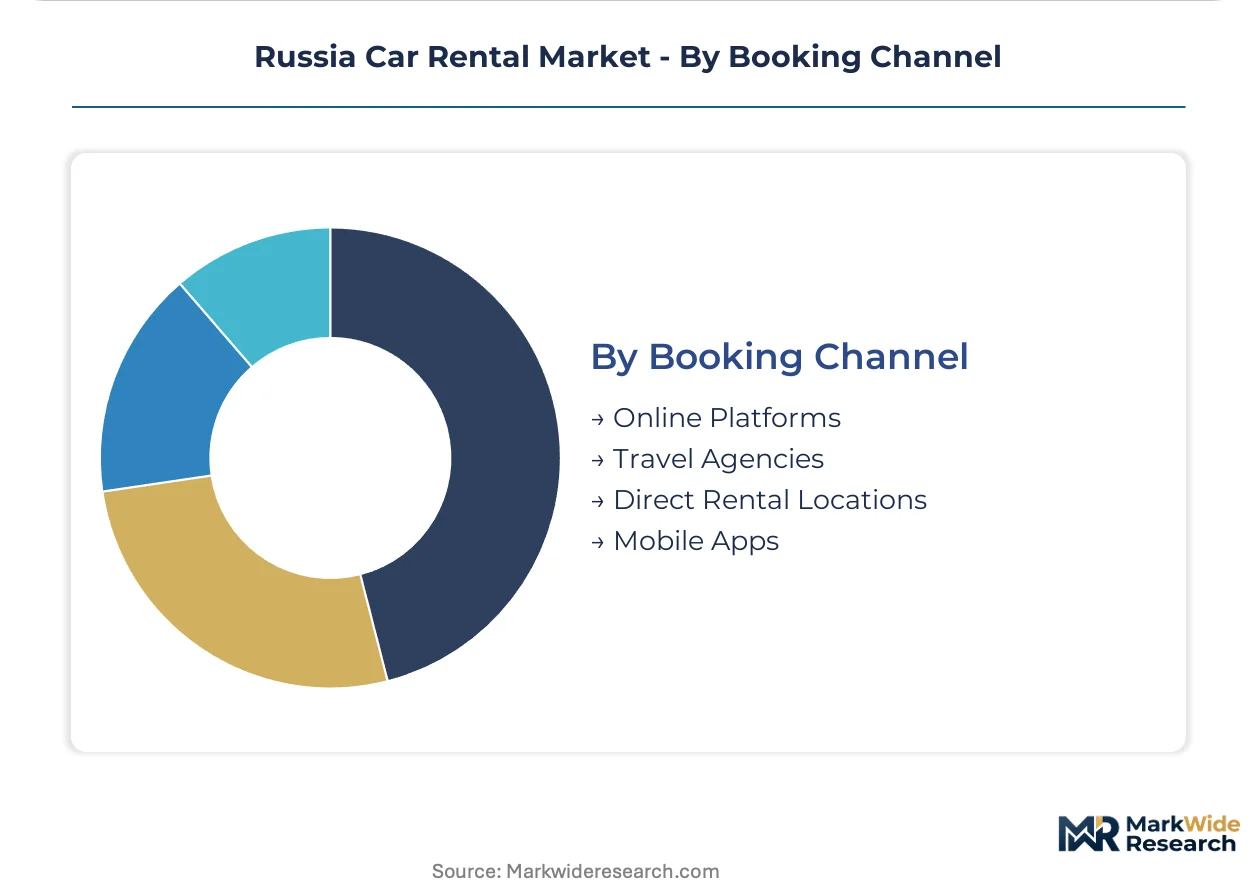
Booking Channel:
Technology penetration and intermediary economics reshape how customers initiate rental relationships across Russian urban centers.
- Online Platforms:Web-based reservation systems with real-time inventory visibility and automated confirmation reduce friction for pre-planned trips. Moscow's digitally native workforce favors these channels for transparency and rate comparison efficiency.
- Mobile Apps:Smartphone-native interfaces with geolocation-enabled vehicle discovery and keyless access integration are gaining share fastest among younger demographics. Saint Petersburg operators report accelerating app-driven bookings as integrated mobility platforms expand their user bases.
- Travel Agencies:Intermediary-booked rentals bundled with aviation and accommodation packages serve international inbound segments.
- Direct Rental Locations:Counter-based transactions at airport terminals and city depots capture walk-up demand.
Technology investment favors Mobile Apps; infrastructure legacy favors Direct Rental Locations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal subsidies for domestic automotive production are redirecting fleet procurement toward locally assembled vehicles. Regional transport authorities in major federal subjects are tightening commercial vehicle registration requirements. These policy shifts concentrate competitive activity in Russia's most economically developed territories.
Central Federal District
Moscow's congestion charging zones and parking restrictions sustain demand for flexible mobility alternatives over private vehicle ownership. The city's Department of Transport mandates telematics integration for all commercial fleet operators. Sheremetyevo and Domodedovo airports anchor the highest short-term rental utilization rates nationwide.
Northwestern Federal District
Saint Petersburg's diplomatic and financial districts generate premium chauffeured service demand from corporate and government clients. The regional committee on transport infrastructure enforces stricter emissions standards for commercial vehicle registration. Pulkovo Airport's international terminal expansion is attracting specialized airport-centric rental operators.
Southern Federal District
Sochi's seasonal tourism peaks create acute demand spikes for convertible and premium vehicle categories during summer months. Krasnodar Krai transport inspectors are accelerating GOST R compliance audits for rental fleets. The Black Sea coastal corridor is emerging as a testing ground for subscription-based mobility packages.
Volga Federal District
Nizhny Novgorod's industrial enterprises are converting owned vehicle pools to operational lease structures to free capital for core manufacturing. Regional economic development programs offer preferential licensing terms for fleet operators employing local residents. The city's river port and rail junction sustain intermodal logistics demand for commercial van rentals.
Ural Federal District
Yekaterinburg's mining and engineering sectors require ruggedized SUV fleets capable of accessing remote extraction sites. Sverdlovsk Oblast regulators are harmonizing cross-border vehicle documentation standards with Kazakhstan. The city's expanding conference and exhibition infrastructure is building business travel rental volume outside traditional Moscow-Saint Petersburg corridors.
Russia Car Rental Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Russia's mobility ecosystem. The market exhibits moderate consolidation with distinct tiering between integrated platform operators and single-service rental providers. Two strategic archetypes dominate: technology-anchored mobility platforms leveraging data-driven fleet allocation, and asset-heavy specialists concentrating on high-utilization corridor capture. Competitive intensity manifests through fleet refresh acceleration and airport terminal infrastructure锁定.
Within the integrated platform tier, Delimobil and Yandex Drive exemplify technology-native operators that have converted ride-hailing user bases into rental demand. Rentmotors occupies a position representing the airport-specialist archetype with dedicated terminal infrastructure investments. These three anchors illustrate how divergent capital deployment strategies—software density versus physical presence—can sustain viable competitive positions within the same regulatory environment.
| Leading Market Players |
|---|
| Delimobil |
| Yandex Drive |
| BelkaCar |
| Citydrive |
| Rentmotors |
| RexRent |
| YouDrive |
| Naprokat.ru |
| Avis |
| Others |
Value Network & Pricing Analysis
Imported vehicle customs duties on foreign-manufactured fleet additions concentrate upstream cost pressure on operators dependent on non-domestic supply, compressing margin pools at the economy tier while premium positioning retains pricing power through GOST R compliance differentiation. This structural tension between acquisition cost inflation and regulatory-driven fleet refresh requirements shapes how operators allocate capital across vehicle categories.
Pricing Analysis
GOST R certification tier creates the primary spread between economy and premium fleet positioning, with compliant vehicles commanding rate premiums of fifteen to twenty percent above non-certified inventory. Subscription-based monthly packages are displacing daily transactional rates among Moscow corporate clients, while airport walk-up segments remain price-sensitive with minimal brand loyalty. Pricing pressure stems from accelerated depreciation schedules as Federal Antimonopoly Service transparency mandates compress contract negotiation windows. Corporate procurement departments demonstrate lowest price sensitivity due to balance sheet optimization priorities, whereas individual tourists exhibit highest elasticity with rapid channel switching.
Supply Chain Analysis
Extended payment terms from domestic automotive assemblers are restructuring working capital requirements for fleet operators managing refresh cycles. Vehicle sourcing concentrates in Russia, China, and residual European channels, with locally assembled units gaining preference through federal production subsidies. Semiconductor components for telematics and infotainment systems draw from Taiwan and South Korea, creating single-source vulnerability for connected fleet specifications. Distribution runs through airport terminal concessions and urban mobility hubs, with mobile app intermediaries capturing growing share of customer acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Moscow-headquartered enterprise procurement departments with centralized fleet outsourcing mandates, fragmenting the customer base into a handful of volume negotiators with standardized contract terms. This shift elevates contract predictability value over transactional yield for operators seeking revenue stability.
For Market Incumbents: Build regulatory compliance moats through accelerated GOST R certification pipelines that newer entrants cannot replicate without eighteen-month lead times. Incumbents should deepen airport terminal infrastructure control at Sheremetyevo and Pulkovo while investing in telematics integration mandated by Moscow's Department of Transport. The threat of integrated mobility platforms converting ride-hailing users into rental demand requires fleet refresh acceleration to match their newer vehicle profiles.
For New Entrants and Emerging Players: Yekaterinburg's industrial corridor and Nizhny Novgorod's manufacturing base represent underpenetrated geographies with operational lease demand from capital-constrained enterprises. New entrants should target the Ural Federal District's mining sector with ruggedized SUV configurations absent from established Moscow-centric portfolios. A go-to-market angle through regional economic development preferential licensing terms can bypass the terminal infrastructure investments that anchor incumbent positions.
For Investors and Strategic Acquirers: Capital is best deployed toward technology-anchored mobility platforms with data-driven fleet allocation capabilities rather than asset-heavy single-service operators. Long-term viability across the analysis window favors integrated providers capable of converting subscription revenue into density-optimized vehicle positioning. Acquisition targets should demonstrate real-time demand matching algorithms and cross-modal user bases. The signal to watch is Federal Antimonopoly Service enforcement intensity on pricing transparency mandates, which would accelerate compliance cost divergence between scaled platforms and fragmented regional operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Integration Mandate Compliance | Moscow's Department of Transport requirements create regulatory barrier for non-compliant fleet operators. |
| Airport Terminal Infrastructure Lock-In | Sheremetyevo and Pulkovo concessions anchor utilization rates above regional market averages. |
| Subscription Financing Model Transition | Corporate procurement departments favor depreciation-free operational leases over ownership structures. |
| Integrated Mobility Platform Convergence | Ride-hailing user base conversion enables density optimization across high-traffic urban zones. |
| Domestic Vehicle Procurement Pivot | Federal subsidies for locally assembled fleet reduce customs duty exposure on foreign supply. |
Research Methodology
Cross-validation between fleet operator procurement directors and Ministry of Transport regional permitting officials anchors the qualitative findings on regulatory enforcement patterns. Primary interviews with car rental operations managers, corporate fleet procurement leads, airport concession administrators, and GOST R certification auditors combined with secondary validation from customs trade data, Federal Antimonopoly Service disclosure filings, and vehicle registration databases. Bottom-up triangulation across operator fleet composition and top-down reconciliation against regional economic output produced segment-level estimates.
Calibration against historical fleet refresh cycles and regulatory implementation timelines shaped the projection framework. The model segments by service type, vehicle category, customer archetype, and booking channel, with additional dimensioning across federal district regulatory clusters. CAGRs were derived from elasticity-adjusted demand curves incorporating corporate outsourcing propensity and tourism recovery patterns. Forecast inputs include GOST R compliance cost trajectories and charging infrastructure deployment schedules outside Moscow and Saint Petersburg.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology-native mobility platforms would shift outcomes beyond modeled parameters. Macroeconomic deviation in customs duty structures, regulatory acceleration in emissions standards, or breakthrough electrification infrastructure deployment would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
United States White Glove Delivery Service Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Cross Docking Services Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Australia Taxi Market
Transportation Services
Airline Passenger Service System Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Compact Road Sweepers Market
Transportation Services
Truck Sharing Market
Transportation Services
Car Rental Service Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
Multispace Parking Meter Market
Transportation Services
Thailand Car Rental Market
Transportation Services
Refuse Truck Market