
 India Taxi Market | 2026-2036
India Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
India Taxi Market Insights
Driver-partner availability across tier-2 and tier-3 cities is redrawing competitive boundaries for aggregators. ANI Technologies leverages its extensive offline onboarding network to sustain supply density outside major metros. BluSmart differentiates through its all-electric fleet commitment and captive charging infrastructure. Uber Technologies Inc. anchors premium airport transfer revenue through controlled slot allocations at Delhi and Hyderabad terminals.
An India taxi constitutes a licensed for-hire passenger vehicle operating under municipal permits or state transport authority regulations, typically governed by fare meters or dynamic digital pricing algorithms and subject to vehicle age and emission standards. The category serves urban mobility, tourism circuits, and corporate travel corridors where public transit coverage remains incomplete. App-based services now dominate booking volume as smartphone penetration crosses critical thresholds among daily commuters and occasional users. Electric cars represent the fastest-growing vehicle type segment as FAME II subsidies and state-level EV policies compress total cost of ownership for fleet operators. Compact cars retain the largest share of trip volume due to price-sensitive demand from budget-conscious tourists and routine office commuters.
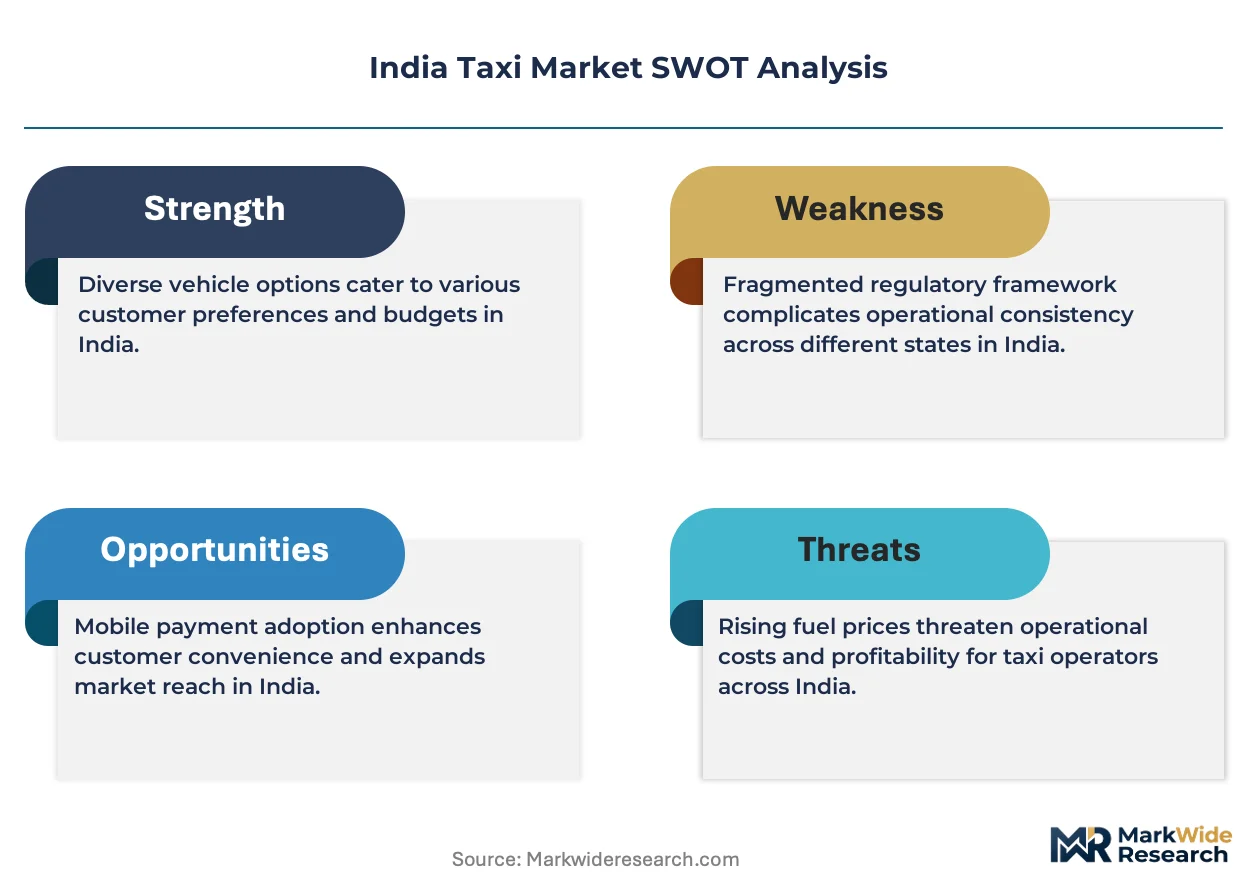
The Ministry of Road Transport and Highways enforces motor vehicle permit norms that determine fleet eligibility across state boundaries, while the Central Electricity Authority shapes charging infrastructure standards affecting EV taxi viability. BIS certification requirements for GPS and safety devices mandate hardware upgrades that filter out unorganized operators. State-level city taxi schemes in Maharashtra and Karnataka impose permit caps and fare control mechanisms that limit unconstrained platform expansion. Stakeholders must monitor evolving state EV policies and charging grid readiness as these variables determine whether electric fleet transitions achieve unit economics parity with conventional vehicles.
Market Dynamics
The FAME II subsidy regime is compressing total cost of ownership for electric fleet operators while state-level EV policies create uneven adoption terrain across Maharashtra, Karnataka, and Delhi.
Growth Catalysts
- Smartphone penetration thresholds:Daily commuters in Mumbai and Bengaluru now complete bookings predominantly through app interfaces, expanding addressable demand for platform services.
- Metro rail expansion:Last-mile connectivity gaps around Bengaluru Metro Phase 2 and Mumbai Metro Line 3 are generating captive taxi demand from transfer passengers.
- FAME II subsidies:Central government incentives for electric vehicle procurement are restructuring fleet economics for operators transitioning from conventional powertrains.
Market Restraints
- Permit cap mechanisms:Maharashtra and Karnataka city taxi schemes impose quantitative limits on fleet expansion, constraining platform density targets.
- Charging infrastructure gaps:CEA standards for grid-connected charging remain unevenly implemented across tier-2 cities, creating range anxiety for EV fleet operators.
- Driver-partner supply volatility:Earnings compression in tier-3 markets is accelerating churn among non-metro driver cohorts.
Strategic Opportunities
- Corporate travel corridors:Unpenetrated IT park shuttle contracts in Hyderabad and Pune offer recurring revenue streams with lower customer acquisition costs.
- Airport slot control:Controlled access to Delhi IGI and Hyderabad RGIA premium pickup zones enables margin protection on inter-city transfers.
- Captive charging infrastructure:Hub-and-spoke charging depot models in Bengaluru and Mumbai suburbs are reducing downtime for electric fleet operators below network-average levels.
Industry Challenges
- BIS certification timelines:GPS and safety device hardware upgrades mandated under automotive standards are filtering unorganized operators but creating compliance backlogs for small fleet owners.
- Driver onboarding friction:Offline verification networks required for background checks and permit documentation are constraining supply expansion velocity outside established metro hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Taxi Market |
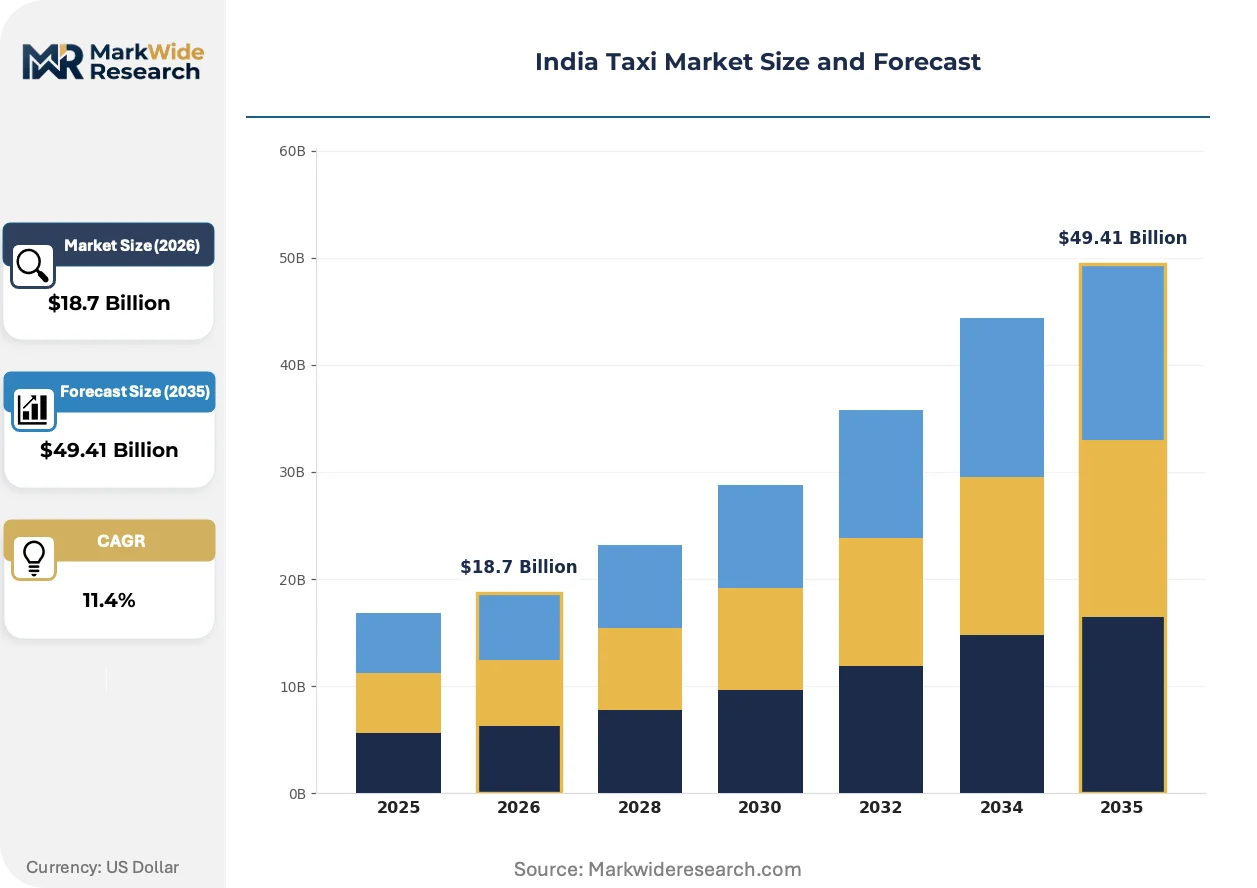
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Hailing, Car Rentals, App-Based Services, Metered Taxis Vehicle Type: Compact Cars, SUVs, Luxury Vehicles, Electric Cars Customer Type: Business Travelers, Tourists, Daily Commuters, Occasional Users Booking Channel: Mobile Apps, Website, Phone Reservations, Street Hailing |
| Companies Covered | Meru Mobility Tech Pvt Ltd, Namma Yatri, ANI Technologies Pvt Ltd (Ola Cabs), Savaari, Carzonrent India Pvt Ltd, Rapido, Sahkar Taxi Cooperative Limited, BluSmart, Uber Technologies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Taxi Market Trends and Innovations
Platform economics are restructuring around vehicle electrification mandates and captive infrastructure investments that separate capital-intensive operators from asset-light competitors.
Electric drivetrain technology is fragmenting fleet procurement patterns across the industry. Aggregators with dedicated charging depots in Bengaluru and Mumbai are securing preferential supply agreements with OEMs. This infrastructure concentration is compressing unit economics parity timelines between electric and conventional vehicle operations.
FAME II subsidy structures are redirecting state transport authority procurement criteria toward zero-emission vehicle categories. Fleet operators in Maharashtra and Karnataka are restructuring lease agreements to capture residual value benefits from extended EV depreciation schedules. Delhi's additional state-level EV policy is accelerating this transition in the National Capital Region relative to other markets.
Commuter booking behavior is pivoting toward subscription-based mobility packages for routine office corridors. Corporate HR departments in Mumbai and Bengaluru are displacing individual reimbursement models with centralized platform contracts. This shift is most visible among IT sector employers with large campus footprints in Hyderabad and Pune.
India Taxi Market Segmentation
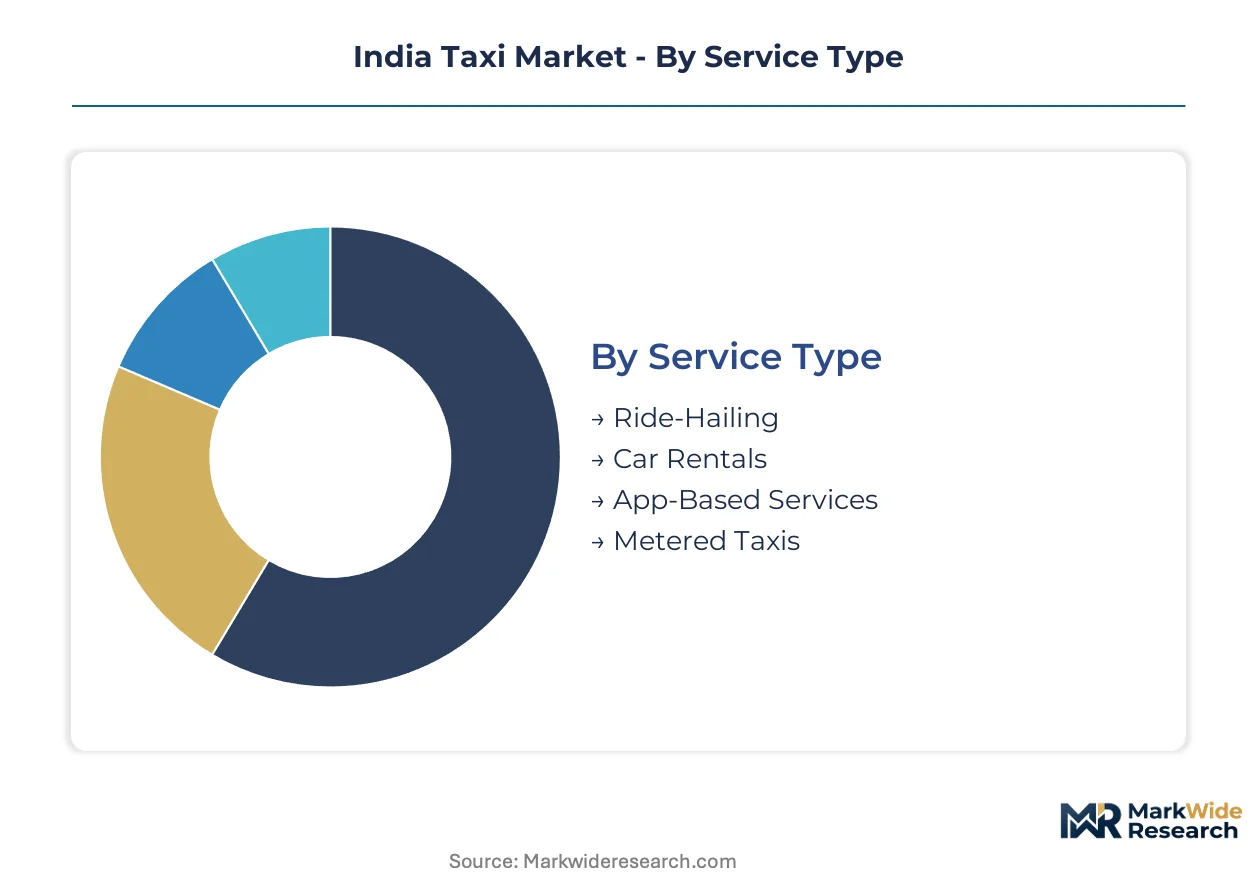
Segmentation in the India taxi market reveals how regulatory frameworks, infrastructure maturity, and pricing sensitivity fragment demand across distinct operational models. Fleet operators and platform aggregators calibrate vehicle procurement, driver onboarding, and pricing algorithms differently for each segment to align with municipal permit conditions and state-level EV mandates.
Service Type:
BIS certification requirements for GPS and safety devices create divergent compliance burdens across operational models, filtering unorganized operators from formal platform networks.
- Ride-Hailing:Platform-mediated dynamic pricing connects driver-partners with commuters through smartphone interfaces. Demand concentrates in Mumbai and Bengaluru where metro rail expansion generates last-mile dependency and smartphone penetration crosses critical thresholds among daily office commuters.
- Car Rentals:Outstation and inter-city hourly packages serve tourism circuits and corporate travel corridors. Maharashtra and Karnataka transport authorities impose permit caps that constrain fleet density for this segment, pushing operators toward contract-based B2B arrangements with IT parks in Hyderabad and Pune.
- App-Based Services:Smartphone-native booking interfaces dominate urban trip volume as municipal authorities in Delhi and Bengaluru mandate digital fare transparency.
- Metered Taxis:Conventional street-hail operations persist in tier-2 cities where platform penetration remains incomplete and state transport authorities enforce fare control mechanisms.
Established volume favors ride-hailing; emerging adoption favors app-based services as CEA charging infrastructure standards mature.
Vehicle Type:
FAME II subsidies and state-level EV policies restructure total cost of ownership calculations, compressing payback periods for electric fleet transitions in Maharashtra, Karnataka, and Delhi.
- Compact Cars:Price-sensitive demand from budget tourists and routine commuters sustains this as the largest trip volume category. Fleet operators in tier-2 cities prioritize compact hatchbacks to minimize capital deployment and maximize permit utilization under quantitative caps.
- Electric Cars:Zero-emission drivetrains with dedicated charging depot access. Maharashtra and Karnataka fleet operators are restructuring lease agreements to capture FAME II residual value benefits, with Delhi's supplementary state policy accelerating NCR transitions faster than other markets.
- SUVs:Six-to-seven seat configurations serve airport transfers and group outstation bookings where luggage capacity commands premium positioning.
- Luxury Vehicles:Premium sedans anchor corporate travel contracts and inter-city executive transfers from Delhi IGI and Hyderabad RGIA controlled pickup zones.
Compact cars dominate current fleet deployment; electric cars are climbing the fastest as CEA grid-connected charging standards achieve broader tier-1 implementation.
Customer Type:
Corporate HR departments in Mumbai and Bengaluru are displacing individual reimbursement models with centralized platform contracts, restructuring demand concentration patterns.
- Daily Commuters:Recurring office corridor travelers subscribing to mobility packages. IT sector employers with large Hyderabad and Pune campus footprints are consolidating individual bookings into enterprise contracts with lower customer acquisition costs for platforms.
- Business Travelers:Expense-account journeys requiring reliability and receipt documentation. Airport slot control at Delhi and Hyderabad terminals enables margin protection for this segment through premium pickup zone access.
- Tourists:Leisure visitors utilizing outstation packages and city tours across Maharashtra and Karnataka tourism circuits.
- Occasional Users:Intermittent demand from non-routine travelers in tier-3 markets where driver-partner supply volatility accelerates platform churn.
Business travelers sustain premium yield; daily commuters are gaining share fastest as subscription models disperse across IT corridors.
Booking Channel:
Smartphone penetration thresholds in Mumbai and Bengaluru have inverted the channel hierarchy, marginalizing traditional reservation methods in core urban markets.
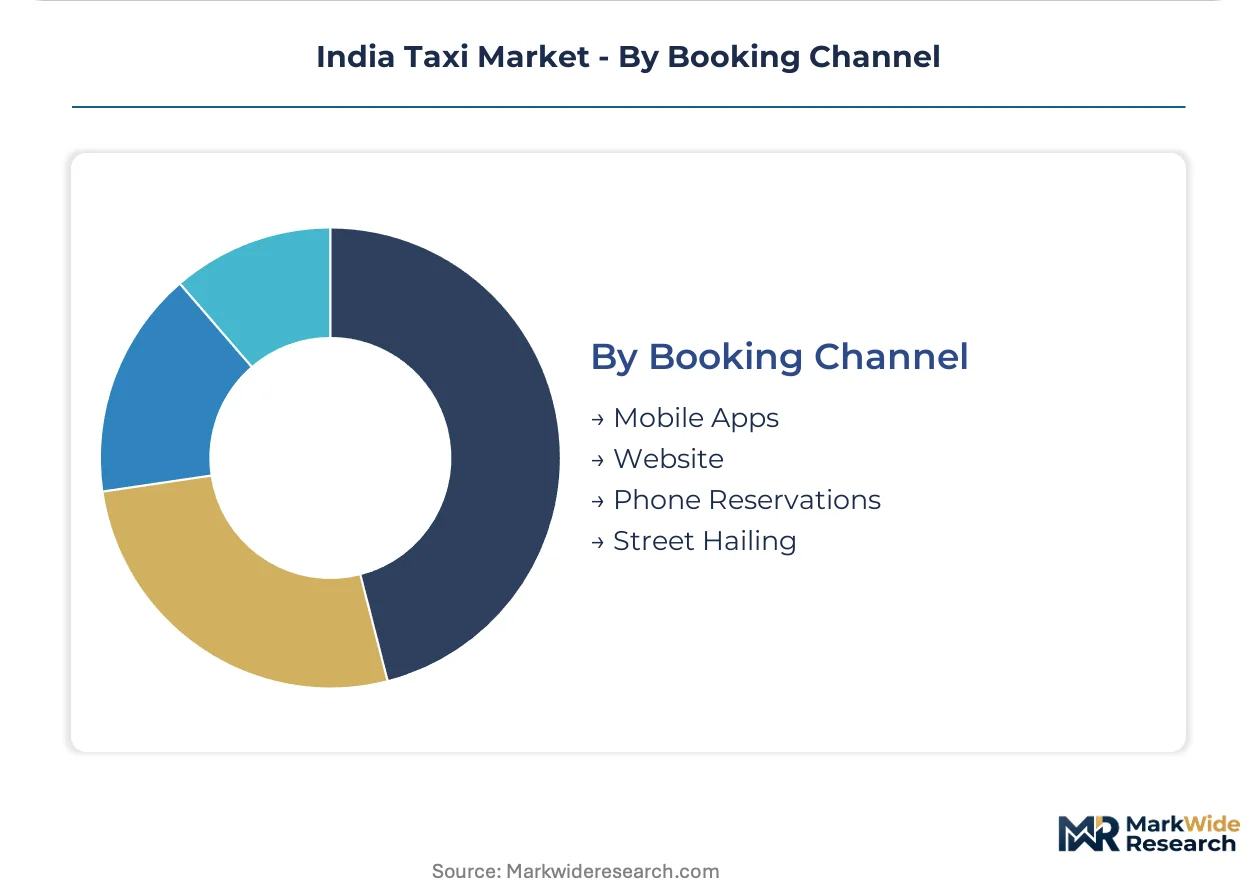
- Mobile Apps:Dominant interface for urban bookings with GPS-enabled dispatch and dynamic pricing algorithms. Bengaluru Metro Phase 2 and Mumbai Metro Line 3 transfer passengers drive adoption through last-mile connectivity gaps.
- Street Hailing:Persistent in tier-2 and tier-3 cities where platform density remains insufficient and offline driver verification networks constrain supply expansion velocity.
- Website:Corporate dashboard interfaces for centralized travel management and expense reconciliation.
- Phone Reservations:Declining channel serving elderly demographics and non-smartphone users in peripheral markets.
Mobile apps command current transaction volume; website bookings are expanding most quickly as corporate travel corridors consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification requirements for GPS and safety devices anchor fleet eligibility across state boundaries. The Ministry of Road Transport and Highways enforces motor vehicle permit norms that determine cross-state operations. State-level city taxi schemes in Maharashtra and Karnataka impose quantitative limits that constrain platform density targets.
Maharashtra
Mumbai Metro Line 3 construction generates last-mile taxi dependency among transfer passengers. The state transport authority imposes permit caps under city taxi schemes that limit unconstrained fleet expansion. Fleet operators in Mumbai suburbs are restructuring lease agreements to capture FAME II residual value benefits from extended EV depreciation schedules.
Karnataka
Bengaluru Metro Phase 2 expansion feeds captive taxi demand from commuters facing connectivity gaps. State-level EV policies complement central FAME II subsidies to compress total cost of ownership for electric fleet transitions. IT park shuttle contracts in Bengaluru and Hyderabad corridors offer recurring revenue streams with lower customer acquisition costs for platform aggregators.
Delhi-NCR
Daily commuters in the National Capital Region complete bookings predominantly through smartphone interfaces as penetration crosses critical thresholds. Delhi's supplementary state EV policy accelerates electric fleet transitions faster than other markets. Controlled access to Delhi IGI premium pickup zones enables margin protection on inter-city transfers for airport-focused operators.
Telangana
Corporate travel corridors in Hyderabad IT parks displace individual reimbursement models with centralized platform contracts. The state transport authority regulates permit issuance for outstation and inter-city hourly packages. Fleet operators target unpenetrated IT park shuttle contracts offering recurring revenue streams with predictable demand patterns.
Tamil Nadu
Tourism circuits across the state sustain demand for outstation packages and city tours. State transport regulations govern conventional street-hail operations where platform penetration remains incomplete. Chennai metro expansion generates last-mile connectivity gaps similar to patterns observed in Mumbai and Bengaluru.
India Taxi Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the India taxi market structure. Platform aggregators with captive charging infrastructure and offline onboarding networks command supply density advantages in tier-2 cities. Three archetypes dominate: asset-light technology platforms, fleet-heavy operators with owned vehicles, and cooperative models with driver-member ownership structures. Competitive moves concentrate on strategic partnerships for charging infrastructure and geographic expansion through localized permit acquisitions.
Among integrated platform operators, ANI Technologies Pvt Ltd and Uber Technologies Inc. exemplify the technology-led archetype with extensive driver-partner networks. BluSmart occupies a position within the asset-heavy electric fleet tier through its all-electric commitment and captive charging depot investments. Namma Yatri represents the cooperative driver-owned model that challenges conventional platform economics through member-governance structures.
| Leading Market Players |
|---|
| Meru Mobility Tech Pvt Ltd |
| Namma Yatri |
| ANI Technologies Pvt Ltd (Ola Cabs) |
| Savaari |
| Carzonrent India Pvt Ltd |
| Rapido |
| Sahkar Taxi Cooperative Limited |
| BluSmart |
| Uber Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
Fleet utilization rates above network-average thresholds in Mumbai and Bengaluru compress per-kilometer operating costs for platform aggregators, concentrating pricing power among operators with captive charging infrastructure and dense driver-partner networks. This scale dynamic establishes price floors that asset-light competitors struggle to match while rewarding vertical integration into vehicle procurement and energy supply.
Pricing Analysis
Mumbai-to-Pune corridors command premium positioning against tier-3 intracity routes, with three-tier pricing structure across premium, standard, and economy levels separating airport transfers from metro feeder trips from budget commuter rides. Price differentiation rests on permit scarcity under Maharashtra and Karnataka city taxi schemes and FAME II subsidy capture for electric fleet operators. Cost compression in economy tiers is intensifying because driver-partner churn accelerates earnings dilution. Daily commuters exhibit highest price sensitivity; corporate travel contracts anchored by IT park shuttles demonstrate lowest.
Supply Chain Analysis
Container availability constraints at JNPT and Chennai Port elevate inbound logistics costs for imported electric drivetrain components and GPS safety hardware mandated under BIS certification. Domestic manufacturing concentrates in Maharashtra, Tamil Nadu, and Gujarat for vehicle assembly, with lithium-ion battery cells drawing from China, South Korea, and Japan. Single-source vulnerability runs through semiconductor-dependent telematics modules. Distribution runs through hub-and-spoke depot models in Bengaluru and Mumbai suburbs feeding last-mile driver-partner allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India taxi market represents high-growth disruption as FAME II subsidies and state-level EV mandates restructure fleet economics faster than charging infrastructure deployment.
For Market Incumbents: Secure controlled slot allocations at Delhi IGI and Hyderabad RGIA terminals to protect premium transfer margins against emerging electric fleet competitors. Lock in long-term lease agreements capturing FAME II residual value benefits before subsidy phase-out compresses procurement incentives. For New Entrants and Emerging Players: Lead with captive charging depot investments in Bengaluru and Mumbai suburbs where hub-and-spoke models reduce EV downtime below network-average levels. Target unpenetrated IT park shuttle contracts in Hyderabad and Pune corridors with subscription-based corporate mobility packages displacing individual reimbursement models. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-heavy electric fleet operators with integrated charging infrastructure over asset-light technology platforms facing driver-supply volatility. Acquisition targets should demonstrate demonstrated unit economics parity between electric and conventional vehicle operations. The signal to watch is CEA grid-connected charging standard implementation velocity across tier-2 cities as inflection indicator for EV fleet scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Charging Infrastructure Deployment | Hub-and-spoke depot models in Bengaluru suburbs reduce EV fleet downtime below network-average operational thresholds. |
| Corporate Mobility Contract Consolidation | IT park shuttle agreements in Hyderabad and Pune corridors displace individual reimbursement with recurring revenue streams. |
| Airport Slot Control Acquisition | Controlled access to Delhi IGI premium pickup zones enables margin protection on inter-city transfer segments. |
| FAME II Subsidy Capture Restructuring | Extended EV depreciation schedules under central incentives compress total cost of ownership payback timelines. |
| Driver-Partner Retention Platform Investment | Offline onboarding networks in tier-2 cities constrain supply expansion velocity for competitors without established infrastructure. |
Research Methodology
A standing panel of fleet operations directors, state transport authority permit officers, platform supply managers, and charging infrastructure developers provided ongoing calibration against ground conditions. Primary interviews with driver-partner cohorts in Mumbai, Bengaluru, and Hyderabad supplemented secondary validation through Ministry of Road Transport and Highways permit databases, Central Electricity Authority charging infrastructure filings, and state-level EV policy notifications. Bottom-up trip volume estimates triangulated against top-down fleet deployment data.
Consistency checks validated model outputs against external benchmarks including vehicle registration data, platform transaction disclosures, and municipal transport authority fleet census reports. Segmentation dimensions across the modeling period encompassed service type, vehicle propulsion architecture, customer journey purpose, and booking channel preference. CAGRs were derived from fitted growth curves incorporating FAME II subsidy phase-out schedules and metro rail expansion timelines as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FAME II subsidy regimes and CEA charging standard implementation would require recalibration. Forecasts reflect documented assumptions regarding driver-partner supply elasticity, permit cap enforcement stringency, and EV battery cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
United States White Glove Delivery Service Market
Transportation Services
Brazil Vehicle Rental Market
Transportation Services
Scooter Rental Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Brazil Car Rentals Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Driving Vacation Market
Transportation Services
Waste Collection Vehicle Market
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
Cross Docking Services Market
Transportation Services
Full-Service Carrier Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Europe Refrigerated Truck Rental Market