
 Ship Management Software Market | 2026-2036
Ship Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Management Software Market Analysis
The gap between premium integrated suites and commodity point solutions is repositioning procurement patterns across maritime IT budgets. ABS Wavesight leverages its classification society heritage to anchor trust in compliance-heavy modules. ZeroNorth competes through carbon optimization algorithms that tie voyage economics to regulatory reporting. Software Mind sustains delivery capacity for mid-tier fleet operators seeking modular cloud migration without full ERP replacement.
Ship management software encompasses integrated digital platforms that coordinate vessel operations, maintenance scheduling, regulatory compliance, and crew administration through centralized databases accessible via satellite-linked terminals. These systems process real-time telemetry from engine performance sensors, GPS positioning, and fuel monitoring equipment to optimize routing and predict mechanical failures before port arrival. Cloud-Based deployment is capturing the fastest growth as satellite bandwidth costs decline and fleet operators abandon on-premise server installations that struggle with oceanic connectivity gaps. Compliance Tracking solutions command premium pricing because IMO DCS and EU ETS mandates require auditable emissions data chains that paper-based systems cannot satisfy. Maintenance Management retains the largest installed base among large enterprises running mixed fleets across multiple flag states with divergent inspection calendars.
The International Maritime Organization shapes product roadmaps through its Data Collection System and upcoming revised Carbon Intensity Indicator enforcement tiers. The European Maritime Safety Agency implements port state control protocols that reject vessels lacking certified digital logbooks, effectively mandating software upgrades for EU access. Flag administrations in Panama and Liberia have adopted harmonized e-certification standards that reduce documentation friction for compliant operators. Stakeholders must weigh the trade-off between building proprietary data lakes and subscribing to interoperable platforms as port authorities consolidate their single-window submission requirements.
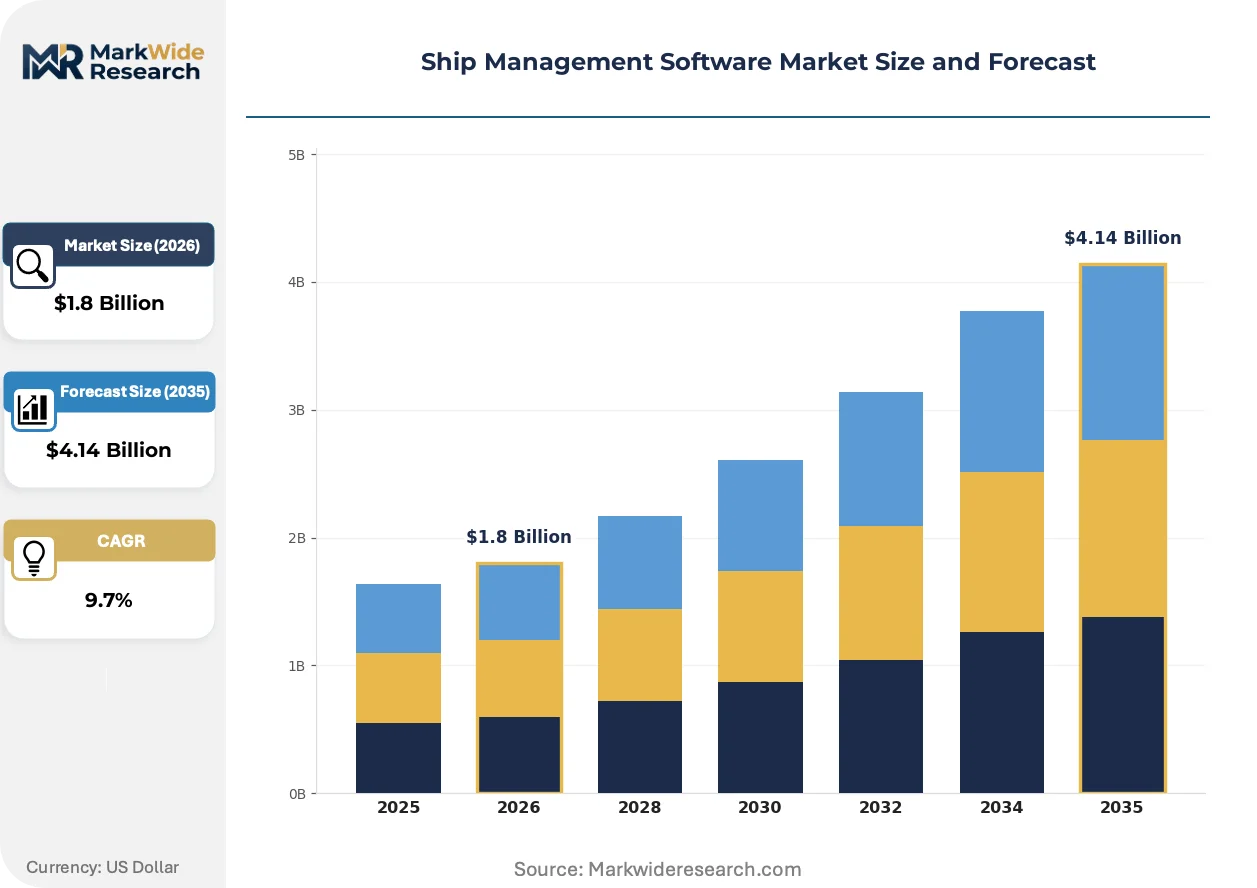
Market Dynamics
Carbon intensity regulations from the International Maritime Organization and the European Union are compressing procurement cycles as fleet operators scramble to deploy auditable emissions tracking before enforcement deadlines.
Growth Catalysts
- IMO Data Collection System:Mandatory fuel consumption reporting for vessels above 5,000 gross tonnage is forcing software upgrades across international fleets.
- Satellite bandwidth deflation:Declining connectivity costs are enabling real-time cloud synchronization for vessels operating in mid-ocean corridors previously served by batch data dumps.
- Singapore's digital port ecosystem:The Maritime and Port Authority's integrated platform is creating procurement pull effects across Southeast Asian fleet operators seeking interoperability.
Market Restraints
- Flag state fragmentation:Divergent inspection calendars and certification requirements across Panama, Liberia, and Marshall Islands registries multiply compliance module development costs.
- Legacy on-premise infrastructure:Capital-intensive server installations on vessels with intermittent connectivity create switching friction for cloud migration.
- Cyber insurance exclusions:Maritime underwriters are narrowing coverage for satellite-linked operational technology, raising total cost of ownership for connected platforms.
Strategic Opportunities
- EU Emissions Trading System expansion:Maritime inclusion in carbon markets creates demand for automated allowance tracking and verification modules.
- Predictive maintenance convergence:Integration of engine sensor telemetry with machine learning failure prediction opens premium pricing for condition-based monitoring.
- Small fleet digitization:Mid-tier operators running 10-50 vessels remain underpenetrated by integrated suites, presenting modular entry points.
Industry Challenges
- Maritime cybersecurity certification:IMO 2021 guidelines for onboard cyber risk management lack harmonized audit standards, delaying vendor product roadmaps.
- Crew digital literacy gaps:Interface complexity in integrated platforms generates operational resistance and underutilization of compliance features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Management Software Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Shipping Companies, Fleet Operators, Charterers, Port Authorities Solution: Maintenance Management, Voyage Planning, Compliance Tracking, Document Management Size: Small Enterprises, Medium Enterprises, Large Enterprises, Multi-National Corporations |
| Companies Covered | Computools, ElifTech, VoyageX AI, DBB Software, Software Mind, ABS Wavesight, Fingent, DreamzTech, ZeroNorth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Management Software Market Emerging Trajectories
Artificial intelligence is penetrating voyage optimization as fuel costs and carbon penalties converge, while regulatory data architectures are hardening around immutable audit trails.
Edge computing nodes deployed directly on vessel engine rooms are absorbing real-time sensor streams for localized anomaly detection before satellite uplink. Bulk carriers and tanker fleets with high fuel exposure are adopting these installations fastest. The technology is absorbing latency-sensitive processing tasks previously routed to shore-based cloud instances, compressing response windows for mechanical failure alerts.
The European Union's Monitoring, Reporting and Verification regulation now mandates structured emissions data submission through recognized software platforms for all port calls. This requirement is disqualifying paper-based logbook systems from EU market access. Container lines with dense European port rotations are prioritizing MRV-certified modules in procurement specifications.
Charterers are consolidating vendor relationships around platforms that unify voyage accounting with emissions performance guarantees. Spot market participants previously using fragmented point solutions are migrating toward integrated suites. Greek and Singaporean shipowners with mixed chartering exposure are driving this consolidation most visibly.
Ship Management Software Market Segmentation
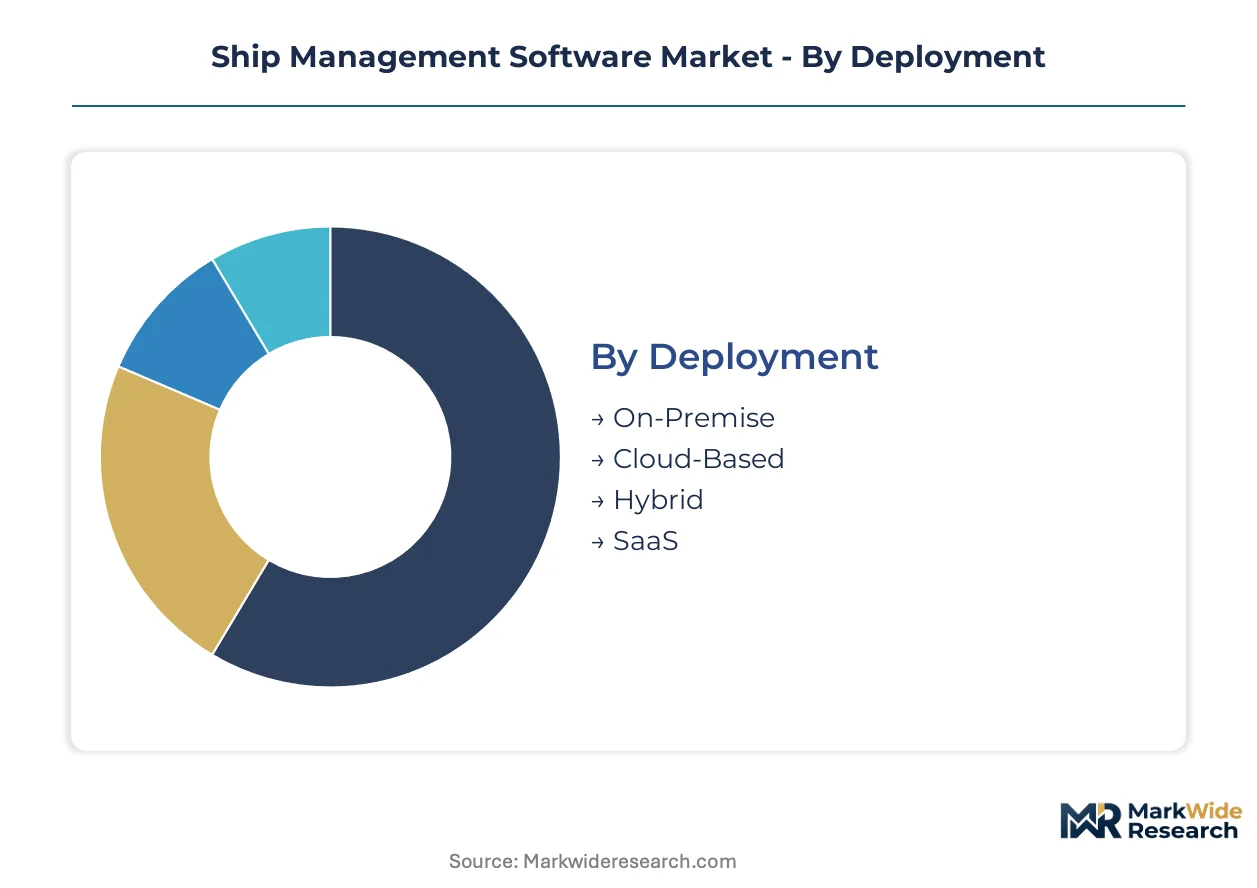
Ship management software procurement diverges sharply across fleet scale, regulatory exposure, and connectivity infrastructure. Deployment choices cascade through maintenance cadence, compliance burden, and charterer reporting obligations.
Deployment:
Customization demands intensify as satellite bandwidth economics reshape the standardization spectrum across oceanic connectivity constraints.
- Cloud-Based:Real-time synchronization via declining satellite bandwidth costs enables continuous voyage optimization and emissions data streaming. Singapore-based fleet operators with dense Southeast Asian port rotations are migrating fastest as the Maritime and Port Authority's digital ecosystem rewards interoperable cloud architectures.
- On-Premise:Localized server installations retain traction among vessels operating in bandwidth-starved corridors where intermittent connectivity disrupts cloud dependency. Operators in the Marshall Islands registry with aging satellite contracts cite switching friction and capital recovery cycles as binding constraints.
- Hybrid:Edge processing on vessel with periodic cloud batch upload balances latency-sensitive engine monitoring against shore-based analytics.
- SaaS:Subscription models lower entry barriers for mid-tier operators seeking modular compliance without ERP replacement.
Most installed capacity flows through On-Premise legacy systems. Expansion is steepest in Cloud-Based architectures.
End User:
Procurement authority concentrates differently across chartering models and regulatory direct exposure.
- Fleet Operators:Integrated suite buyers with mixed flag state fleets require harmonized inspection calendars across Panama, Liberia, and Marshall Islands registries. Greek operators with dense EU port exposure prioritize MRV-certified modules to satisfy European Maritime Safety Agency port state control protocols.
- Shipping Companies:Asset owners balance capital deployment against software TCO, with cyber insurance exclusions for satellite-linked operational technology narrowing vendor shortlists.
- Charterers:Voyage accounting unification with emissions performance guarantees drives platform consolidation among spot market participants.
- Port Authorities:Single-window submission mandates in Singapore and Rotterdam accelerate procurement of interoperable compliance modules.
Fleet Operators command the largest procurement volume. Charterers are gaining share fastest as voyage economics tighten.
Solution:
Module pricing stratifies across certification grade and audit trail immutability requirements.
- Compliance Tracking:IMO Data Collection System and EU ETS mandates require auditable emissions data chains with immutable timestamping. Premium pricing reflects regulatory deadline pressure and disqualification risk for paper-based systems at EU ports.
- Maintenance Management:Condition-based monitoring integrating engine sensor telemetry with machine learning failure prediction opens premium tiers for predictive modules. Large enterprises running mixed fleets across divergent flag state inspection calendars retain the largest installed base.
- Voyage Planning:Carbon optimization algorithms tying route economics to regulatory reporting gain traction among tanker fleets with high fuel exposure.
- Document Management:Digital logbook certification for Panama and Liberia e-certification harmonization reduces documentation friction.
Maintenance Management retains the deepest installed base. Compliance Tracking is climbing the fastest as enforcement deadlines compress.
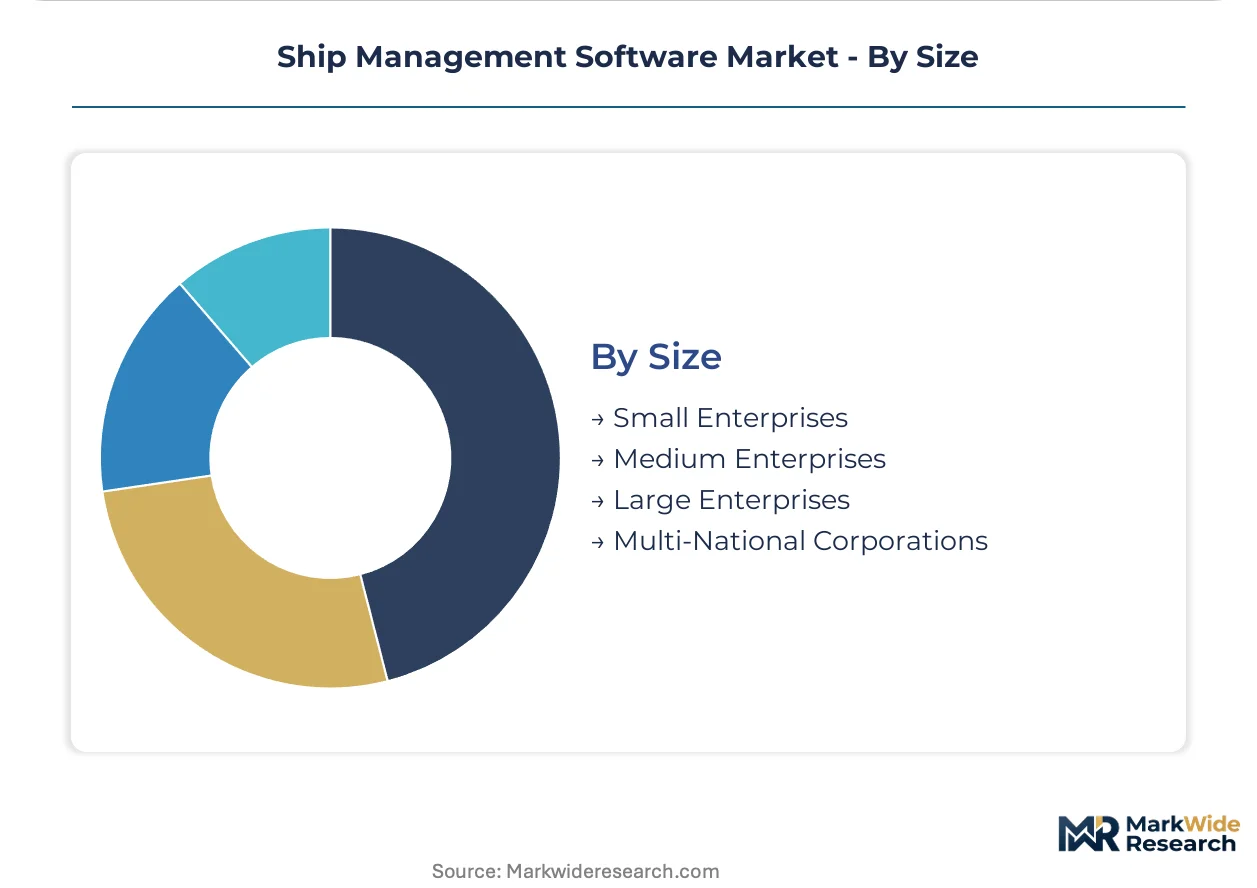
Size:
Enterprise scale determines ERP integration depth and modular versus suite procurement patterns.
- Large Enterprises:Full ERP replacement cycles with multi-flag state compliance modules and dedicated IT security staffing. Multi-national container lines with dense European rotations absorb highest per-seat licensing costs.
- Medium Enterprises:Modular cloud migration without full ERP replacement, targeting 10-50 vessel fleets underpenetrated by integrated suites.
- Small Enterprises:Point solution adoption constrained by crew digital literacy gaps and interface complexity resistance.
- Multi-National Corporations:Centralized procurement with regional customization for port authority single-window requirements across Singapore, Rotterdam, and Houston.
Large Enterprises deploy the most seats. Medium Enterprises represent the steepest expansion trajectory as digitization penetrates mid-tier fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maritime software talent clusters in port cities with dense regulatory exposure and chartering activity. Engineers and compliance specialists concentrate where fleet operators face overlapping IMO, EU, and flag state mandates.
Singapore
The Maritime and Port Authority's digital port ecosystem anchors Southeast Asian procurement decisions for cloud-based voyage planning suites. Operators migrating from paper-based systems seek interoperability with the authority's single-window submission platform. Jurong Port and Tuas Mega Port developments concentrate software implementation teams.
Greece
Greek shipowners with dense EU port rotations drive demand for MRV-certified compliance modules. The country's central bank monitors fleet digitalization as a credit risk factor for vessel financing. Piraeus hosts the largest concentration of maritime software procurement specialists outside Northern Europe.
Germany
Hamburg and Bremen harbor clusters sustain engineering demand for predictive maintenance algorithms integrating engine telemetry. German flag administrations enforce strict cyber risk management protocols that filter vendor shortlists. The country's national maritime regulator mandates certified digital logbooks for port state control clearance.
United States
Houston and New Orleans anchor Gulf Coast demand for emissions tracking software serving tanker fleets with high fuel exposure. The EPA's vessel general permit requirements intersect with IMO Data Collection System mandates for dual-flag operators. Pacific Northwest ports are piloting edge computing installations for localized anomaly detection.
Japan
Tokyo and Osaka house the engineering teams developing machine learning failure prediction for condition-based monitoring modules. METI's maritime digitalization grants subsidize cloud migration for mid-tier fleet operators. Yokohama's port authority mandates structured emissions data submission for all container line calls.
Ship Management Software Market Vendor Landscape
Capital-heavy platform developers compete with asset-light module specialists across divergent connectivity and compliance requirements. The vendor base stratifies between integrated suite providers serving multi-flag enterprises and point-solution vendors targeting modular cloud migration. Three archetypes dominate: classification society heritage players anchoring trust in compliance-heavy modules, carbon optimization algorithm specialists, and delivery capacity sustainers for mid-tier operators. Competitive moves concentrate on strategic partnerships with port authorities and portfolio diversification into predictive maintenance.
Within the classification society heritage tier, ABS Wavesight occupies a position exemplifying trust-based compliance module anchoring. Among carbon optimization specialists, ZeroNorth and VoyageX AI represent algorithm-driven voyage economics integration. Software Mind sits within the delivery capacity archetype, sustaining modular cloud migration for operators avoiding full ERP replacement cycles.
| Leading Market Players |
|---|
| Computools |
| ElifTech |
| VoyageX AI |
| DBB Software |
| Software Mind |
| ABS Wavesight |
| Fingent |
| DreamzTech |
| ZeroNorth |
| Others |
Supply Flow & Price Mechanics
Cloud migration architectures are compressing both development cost structures and vendor consolidation patterns across maritime IT procurement. The shift from vessel-hosted servers to satellite-synchronized platforms concentrates engineering talent in Singapore and Hamburg while fragmenting hardware supply relationships.
Pricing Analysis
The bundled-vs-unbundled service split separates compliance-heavy suites from modular point solutions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and audit trail immutability requirements. Price differentiation centers on IMO DCS certification tier and EU MRV verification status. Cost compression in the economy tier is intensifying because satellite bandwidth deflation enables new SaaS entrants. Small enterprises running under ten vessels show highest price sensitivity; large container lines absorb premium licensing with dedicated IT security staffing.
Supply Chain Analysis
Satellite connectivity hardware rests on specialized manufacturers in the United States, Norway, and Japan. The software stack draws from cloud infrastructure providers, maritime sensor fabricators, and classification society certification bodies. Single-source vulnerability concentrates in legacy engine telemetry interfaces proprietary to specific OEMs. Distribution runs through direct enterprise sales for large fleets and channel partners serving mid-tier operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as charterers consolidate around platforms unifying voyage accounting with emissions performance guarantees. Procurement authority is shifting toward buyers demanding immutable audit trails and certified digital logbooks.
For Market Incumbents: Deploy predictive maintenance algorithm investments to anchor platform stickiness against modular challengers. Deepen integration with port authority single-window systems in Singapore and Rotterdam to raise switching costs. Carbon optimization modules from emerging algorithm specialists threaten voyage planning margins; counter through backward integration into engine sensor telemetry partnerships. For New Entrants and Emerging Players: Edge computing nodes for localized anomaly detection offer technology-first wedge into tanker fleets with high fuel exposure. Target mid-tier operators running ten to fifty vessels in Southeast Asia, where Maritime and Port Authority interoperability requirements create procurement pull. Pursue SaaS subscription models with modular compliance entry points rather than full ERP replacement cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among delivery capacity sustainers serving modular cloud migration without classification society heritage premiums. The five-to-ten year viability window favors vendors with port authority certification relationships and proven satellite synchronization reliability. Acquisition targets should demonstrate established Maritime and Port Authority interoperability. Watch IMO cybersecurity certification harmonization as the signal for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Port Authority Systems | Interoperability with Singapore's Maritime and Port Authority secures procurement preference in Southeast Asian fleet decisions. |
| Predictive Maintenance Algorithm Development | Machine learning failure prediction opens premium pricing tiers for condition-based monitoring modules. |
| EU MRV Certification Investment | European Maritime Safety Agency port state control protocols disqualify non-certified systems from EU market access. |
| Edge Computing Node Deployment | Localized engine room processing absorbs latency-sensitive tasks previously routed to shore-based cloud instances. |
| Strategic Partnership with Classification Societies | ABS Wavesight demonstrates how heritage trust anchors compliance-heavy module procurement decisions. |
Methodological Framework
Coverage spans Singapore, Greece, Germany, the United States, and Japan, with primary inputs from each maritime cluster. The approach combines structured interviews with fleet operations directors, maritime software procurement specialists, classification society compliance officers, and port authority IT architects alongside secondary validation through IMO regulatory filings, EU EMSA port state control protocols, and flag administration e-certification standards. Customs data on satellite equipment imports, SEC filings from listed shipping companies, and Maritime and Port Authority procurement disclosures provided demand-side triangulation. Bottom-up vessel fleet segmentation and top-down IT spend estimates were cross-referenced for convergence.
Granularity-level framing modeled deployment mode, fleet size tier, solution module type, and regional regulatory exposure at the country level. The analytical framework projected adoption curves across the analysis window using penetration rates derived from enforcement deadline proximity and connectivity infrastructure maturity. CAGRs were computed from segment-level value estimates reconciled against aggregate market sizing. Forecast inputs incorporated satellite bandwidth cost decline trajectories and IMO Carbon Intensity Indicator tier implementation schedules.
The model holds under sustained regulatory enforcement timelines and stable satellite connectivity economics; deviation in cybersecurity certification harmonization pace or flag state e-certification fragmentation would shift vendor competitive positioning. Forecasts reflect documented assumptions on charterer platform consolidation behavior and mid-tier fleet digitization willingness. A small set of named triggers warrants ongoing watch: EU ETS maritime inclusion scope expansion, IMO 2021 cyber risk management audit standard finalization, and Maritime and Port Authority ecosystem interoperability mandate extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
ASEAN Car Rental Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
China Vehicle Rental Market
Transportation Services
Corporate Car Sharing Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
North America International Express Service Market
Transportation Services
Russia Car Rental Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Vietnam Taxi Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Scooter Rental Market
Transportation Services
Equipment Relocation Service Market
Transportation Services
Airport Handling Service Market
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
Asia-Pacific Rickshaw Ride Hailing Service Market
Transportation Services
Latin America Tourism Vehicle Rental Market