
 Indonesia Car Rental Market | 2026-2036
Indonesia Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Car Rental Market Outlook
Jakarta's fleet operators is recalibrating vehicle procurement around emission compliance and digital booking integration. TRAC Astra Rent A Car leverages its Astra International parent network to dominate corporate long-term contracts across Java and Sumatra. Blue Bird Group sustains premium positioning through integrated taxi-rental synergies and airport channel control. Europcar Indonesia differentiates via international loyalty program access serving expatriate and multinational demand.
Indonesia car rental denotes short-term to long-term vehicle provisioning without ownership transfer, encompassing daily hire through multi-year fleet leases with maintenance and insurance bundling. Fleet composition spans internal combustion sedans and SUVs to emerging electric vehicle categories, with telematics integration enabling real-time utilization tracking and predictive maintenance scheduling for commercial clients. Short-term rental and online platforms command the largest revenue pools, while electric car and mobile app segments represent the fastest expansion corridors as charging infrastructure proliferates in Jakarta, Surabaya, and Bandung. Corporate customer types anchor volume stability through negotiated annual contracts, whereas leisure and travel agency channels exhibit higher margin volatility tied to seasonal tourism flows in Bali and Yogyakarta.
Indonesia's Ministry of Transportation sets vehicle roadworthiness standards enforced through periodic inspection regimes, while the Financial Services Authority regulates leasing capital structures and consumer protection frameworks. BIS certification requirements for imported safety equipment indirectly shape fleet specification decisions for rental operators sourcing Japanese and Korean vehicle platforms. Stakeholders must monitor regulatory momentum around electric vehicle incentives and ride-hailing integration rules that could redraw competitive boundaries between traditional rental and mobility-as-a-service providers.
Market Dynamics
Corporate fleet outsourcing is restructuring Indonesia's car rental sector as enterprises abandon capital-intensive vehicle ownership in favor of operational lease structures with bundled maintenance and compliance management.
Growth Catalysts
- Ministry of Transportation safety mandates:Periodic inspection regimes force commercial operators toward professional fleet management partners with in-house compliance infrastructure.
- Java business travel density:Greater Jakarta and Surabaya generate sustained daily rental utilization through airport connectivity and inter-city corporate mobility requirements.
- Telematics integration:Real-time utilization tracking and predictive maintenance scheduling reduce total cost of ownership for commercial clients managing multi-vehicle deployments.
Market Restraints
- Import dependency for safety equipment:BIS certification requirements for Japanese and Korean vehicle platforms create procurement friction and extended lead times for fleet specification.
- Charging infrastructure gaps:Electric vehicle adoption outside Jakarta, Surabaya, and Bandung remains constrained by inadequate fast-charging network density.
- Seasonal tourism volatility:Leisure demand concentration in Bali and Yogyakarta generates margin instability compared to contracted corporate volumes.
Strategic Opportunities
- Electric vehicle incentive alignment:Regulatory momentum around EV incentives creates fleet electrification pathways for operators with capital deployment capacity.
- Mobility-as-a-service convergence:Ride-hailing integration rules are redrawing competitive boundaries between traditional rental and app-based mobility providers.
- Sumatra corporate expansion:Underpenetrated markets beyond Java offer long-term contract growth as resource and manufacturing investments deepen.
Industry Challenges
- Technician certification pipelines:EV maintenance competency and telematics system administration require workforce retraining at scale.
- Legacy reservation system integration:Digital booking platforms must interface with entrenched corporate procurement workflows and expense management systems.
- Multi-year contract renegotiation cycles:Annual rate adjustments against volatile fuel and insurance cost structures strain pricing predictability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Car Rental Market |
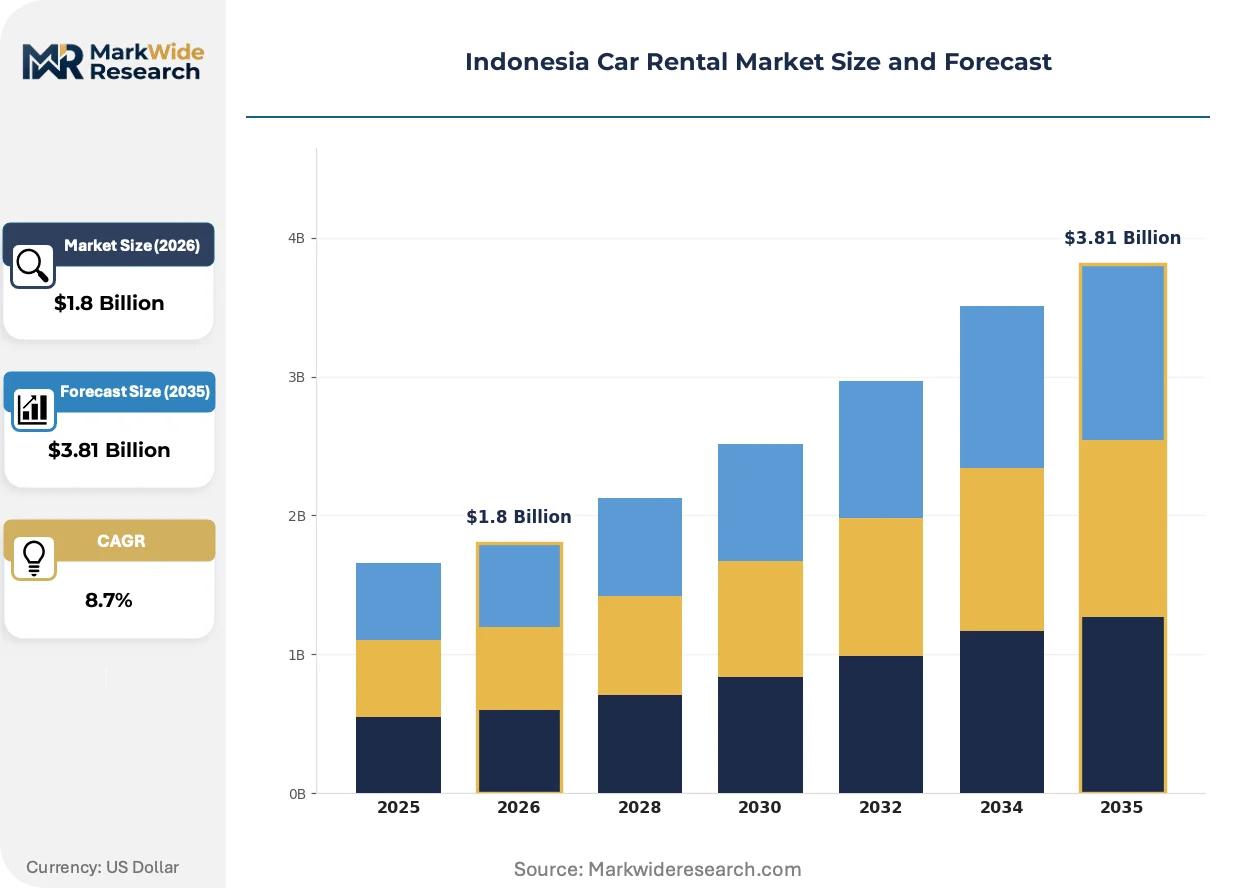
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-Term Rental, Long-Term Rental, Ride-Sharing, Luxury Rental Vehicle Type: Sedan, SUV, Van, Electric Car Customer Type: Corporate, Leisure, Travel Agencies, Local Residents Booking Channel: Online Platforms, Mobile Apps, Travel Agents, Walk-In |
| Companies Covered | Avis Budget Group, Indorent (PT Indomobil Multi Jasa), Blue Bird Group, Europcar Indonesia, Mitra Pinasthika Mustika Rent, TRAC Astra Rent A Car, The Hertz Corporation, Globe Rent a Car, Adi Sarana Armada Tbk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Car Rental Market Strategic Shifts
Digital platform architecture and electrification pathways are reconfiguring how Indonesian fleet operators acquire, deploy, and monetize vehicle assets across corporate and leisure segments.
Telematics-enabled fleet management is overtaking manual dispatch and paper-based utilization logging in corporate long-term contracts. Mining and manufacturing enterprises operating vehicle pools across multiple sites are adopting real-time location and diagnostic systems to compress idle time and optimize maintenance scheduling. This technology shift is enabling outcome-based pricing models where rental fees tie directly to kilometers delivered rather than calendar periods.
Indonesia's Ministry of Transportation vehicle roadworthiness standards are tightening enforcement through periodic inspection mandates. Fleet operators must now maintain dedicated compliance infrastructure or absorb third-party audit costs, raising barriers for informal rental providers. Commercial clients with duty-of-care obligations are responding by consolidating supplier relationships toward established operators with documented safety management systems.
Corporate procurement departments are unbundling after-sales service expectations from base rental rates. Multinational enterprises with regional headquarters in Jakarta are negotiating all-inclusive mobility budgets covering fuel, insurance, maintenance, and replacement vehicles within single contractual frameworks. This consumption-pattern shift is most visible in banking and pharmaceutical verticals where finance teams seek predictable operational expenditure structures.
Indonesia Car Rental Market Segmentation
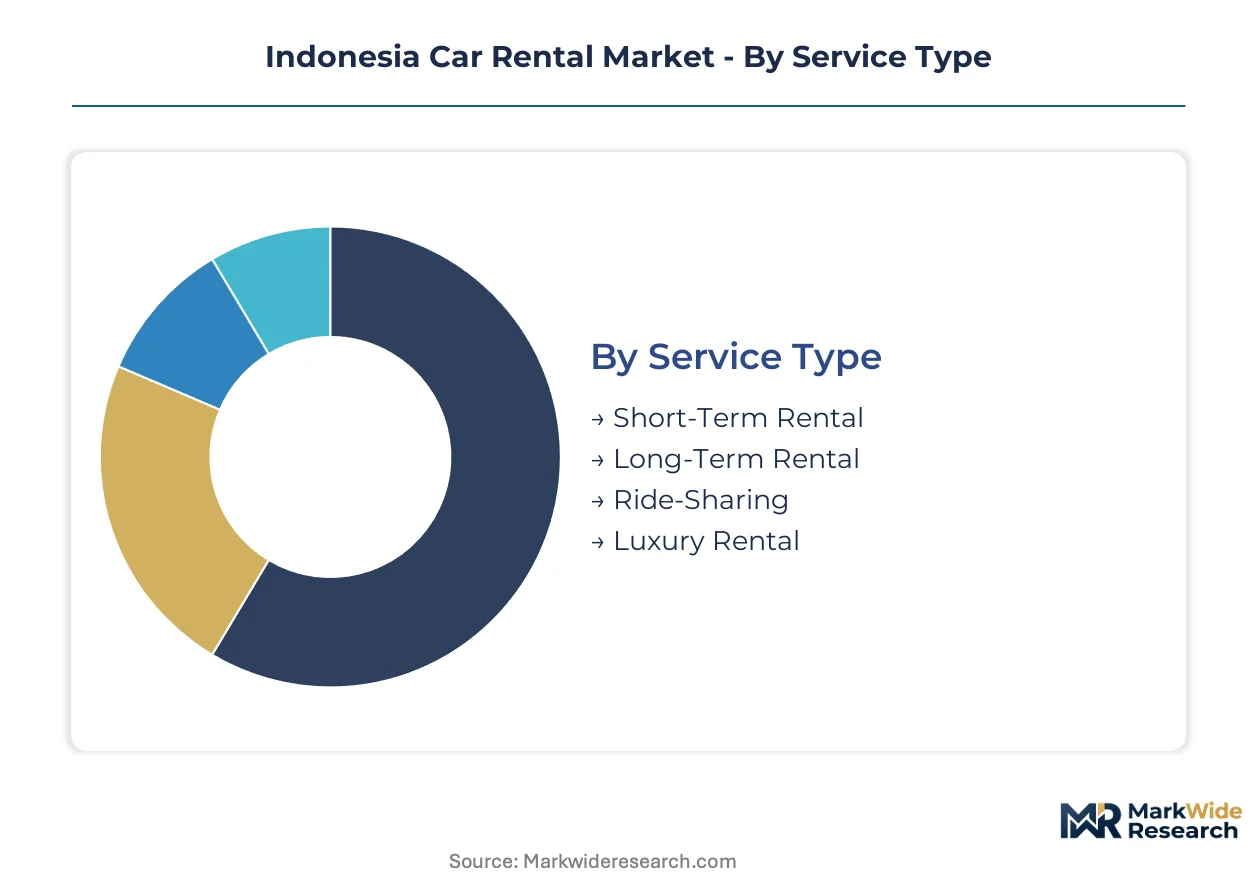
Indonesia's car rental market fragments across service duration, vehicle specification, customer procurement patterns, and booking interfaces. Each dimension carries distinct compliance obligations, margin structures, and technology integration requirements that reshape competitive positioning for fleet operators.
Service Type:
BIS certification requirements for imported safety equipment and Ministry of Transportation inspection mandates create divergent compliance burdens across service duration categories.
- Short-Term Rental:Daily to weekly vehicle provisioning with standardized insurance bundles and rapid turnaround protocols. Demand concentrates in Greater Jakarta and Surabaya airports where business travelers require immediate fleet access without long-term procurement cycles.
- Long-Term Rental:Multi-year operational leases bundling maintenance, compliance management, and telematics integration. Mining and manufacturing enterprises across Java outsource entire vehicle pools to specialized fleet managers with dedicated roadworthiness infrastructure.
- Ride-Sharing:Driver-supplied mobility services operating under distinct regulatory frameworks from traditional rental. Platform economics favor asset-light models with minimal direct fleet ownership.
- Luxury Rental:Premium vehicle segments serving expatriate executives and high-net-worth leisure demand in Bali and Jakarta. Imported platforms face extended lead times from BIS certification requirements.
Short-term rental sits at the top of the volume ranking, with long-term rental climbing the fastest as corporate procurement shifts toward operational lease structures.
Vehicle Type:
Cost tier differentiation separates mass-market internal combustion platforms from emerging electric alternatives with divergent total cost of ownership profiles.
- Sedan:Compact to mid-size passenger vehicles dominating corporate fleet specifications for executive transport. Banking and pharmaceutical verticals in Jakarta standardize on sedan categories for predictable operational expenditure budgeting.
- SUV:Higher-ground-clearance platforms serving inter-city corporate mobility and leisure tourism across Java's varied terrain. Mining sector demand in Sumatra favors SUV durability specifications for site access requirements.
- Van:Multi-passenger configurations addressing group logistics and crew transport for manufacturing operations. Fleet operators maintain dedicated van pools for contractual manufacturing clients.
- Electric Car:Battery-electric platforms constrained by charging infrastructure density outside Jakarta, Surabaya, and Bandung. Regulatory momentum around EV incentives is reshaping procurement roadmaps for capital-deployed operators.
Sedan categories anchor volume stability, while electric car segments are gaining share fastest where charging networks achieve commercial density.
Customer Type:
Application-specific requirements distinguish negotiated annual contracts from volatile seasonal demand patterns with divergent margin reliability.
- Corporate:Enterprises with duty-of-care obligations consolidating supplier relationships toward established operators with documented safety management systems. Multinational regional headquarters in Jakarta negotiate all-inclusive mobility budgets spanning fuel, insurance, and maintenance.
- Leisure:Individual travelers exhibiting seasonal concentration in Bali and Yogyakarta with higher margin volatility compared to contracted volumes. Tourism flows generate utilization spikes requiring flexible fleet scaling.
- Travel Agencies:Intermediary channels aggregating leisure demand with commission structures compressing direct operator margins. Package tour operators in Bali maintain preferred supplier arrangements with volume guarantees.
- Local Residents:Domestic demand for temporary vehicle access during personal events or repair periods. Price sensitivity drives platform selection toward mobile app interfaces with transparent rate comparison.
Corporate customer types dominate revenue predictability, with leisure channels expanding most quickly where tourism infrastructure deepens.
Booking Channel:
Customer maturity and technology adoption separate digital-native procurement from legacy relationship-based transactions with divergent customer acquisition economics.
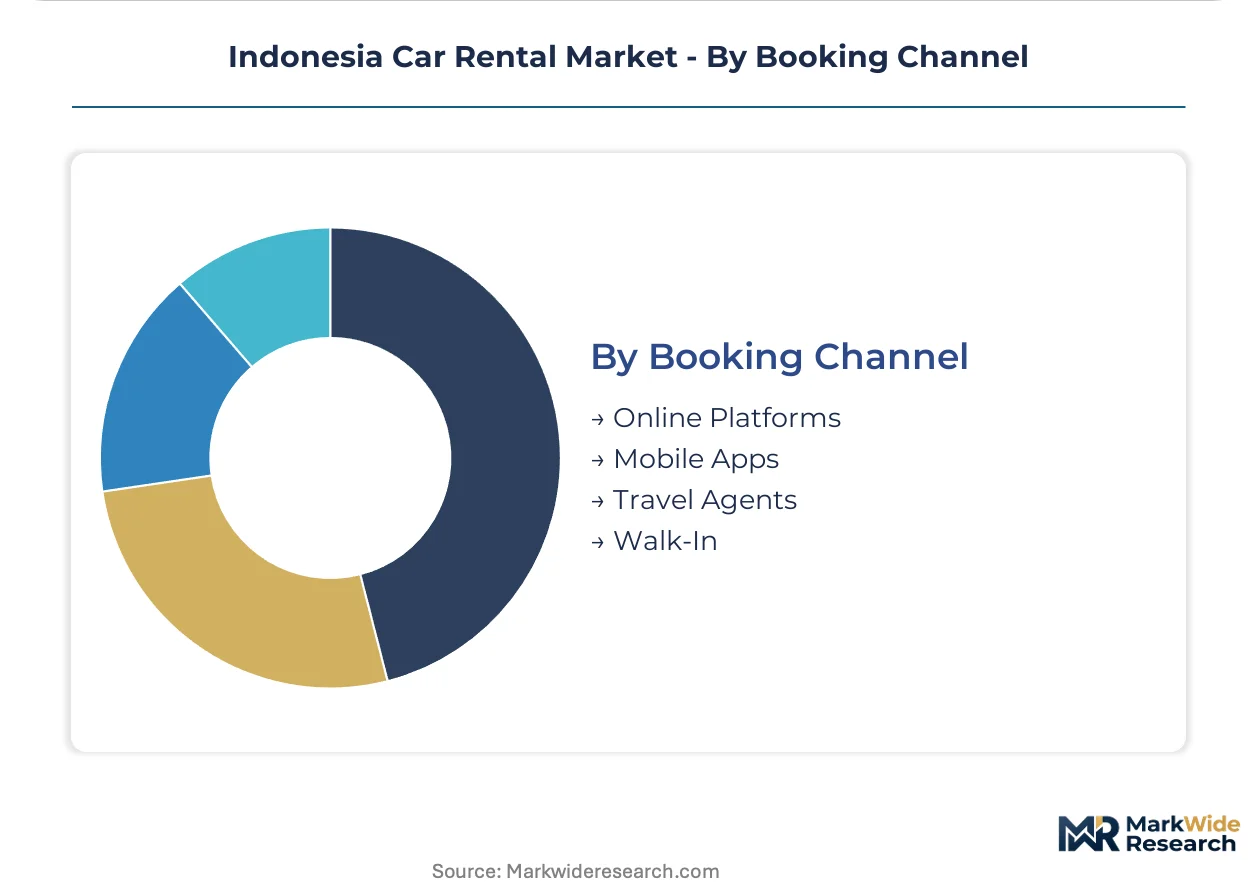
- Online Platforms:Web-based reservation systems integrating with corporate expense management workflows. Finance teams in banking verticals require automated receipt generation and cost center allocation.
- Mobile Apps:Smartphone-native interfaces enabling real-time availability checking and digital payment. Younger demographics and urban professionals favor app-based discovery with rating transparency.
- Travel Agents:Human intermediaries maintaining relationships with corporate travel managers and leisure package operators. Complex multi-leg itineraries still route through agent channels.
- Walk-In:Counter-based transactions at airport and hotel locations serving unplanned demand. Surabaya airport counters capture arriving business travelers without advance reservations.
Online platforms command the largest transaction volume, with mobile apps following the steepest expansion trajectory as smartphone penetration deepens across Indonesian urban centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping fleet deployment patterns as operators migrate vehicle procurement toward jurisdictions with streamlined compliance pathways and lower certification friction.
Greater Jakarta
Corporate headquarters concentration and airport connectivity generate sustained daily rental utilization. Ministry of Transportation inspection mandates force commercial operators toward professional fleet managers with dedicated roadworthiness infrastructure. Central Jakarta and Tangerang districts host the densest clustering of long-term contract operators serving banking and pharmaceutical verticals.
Surabaya
East Java's manufacturing base drives inter-city corporate mobility requirements and crew transport contracts. The provincial transport authority enforces vehicle safety standards through periodic inspection regimes that elevate barriers for informal rental providers. Gresik and Sidoarjo industrial corridors anchor fleet deployment for mining and manufacturing enterprises outsourcing vehicle pools.
Bandung
West Java's education and technology sectors generate mixed corporate-leisure demand with moderate seasonality. Local government electric vehicle incentive programs are accelerating charging infrastructure deployment in urban districts. Dago and Setiabudi corridors concentrate premium rental demand from expatriate professionals and domestic business travelers.
Bali
Tourism flows create utilization spikes requiring flexible fleet scaling across leisure and travel agency channels. The provincial transport department maintains distinct regulatory frameworks for ride-hailing integration that differ from Java-based operators. Kuta and Seminyak districts exhibit the highest concentration of short-term rental counters serving international arrivals.
Medan
North Sumatra's resource extraction investments deepen long-term contract opportunities beyond Java's saturated markets. National fleet safety regulations apply uniformly, though enforcement density remains lower than in Jakarta or Surabaya. Deli Serdang regency hosts emerging corporate fleet outsourcing demand from palm oil and rubber processing operations.
Indonesia Car Rental Market Competitive Environment
Java-based operators anchor the corporate long-term contract tier; regional specialists hold fragmented positions in leisure and emerging provincial markets. Market structure exhibits moderate consolidation around established fleet managers with compliance infrastructure, while informal providers retain residual share in tourism corridors. Three archetypes dominate: integrated automotive conglomerate subsidiaries, independent fleet operators with telematics capabilities, and international brand licensees serving expatriate demand. Competitive dynamics center on multi-year contract renegotiation cycles and electric vehicle fleet conversion timing.
Within the integrated conglomerate tier, TRAC Astra Rent A Car and Blue Bird Group exemplify operators leveraging parent network advantages for corporate contract capture. Europcar Indonesia occupies a position serving multinational mobility demand through international loyalty program access. These three entities represent distinct strategic postures: domestic conglomerate vertical integration, premium service integration across taxi-rental synergies, and global brand affiliation for expatriate market penetration.
| Leading Market Players |
|---|
| Avis Budget Group |
| Indorent (PT Indomobil Multi Jasa) |
| Blue Bird Group |
| Europcar Indonesia |
| Mitra Pinasthika Mustika Rent |
| TRAC Astra Rent A Car |
| The Hertz Corporation |
| Globe Rent a Car |
| Adi Sarana Armada Tbk |
| Others |
Value Chain & Pricing Dynamics
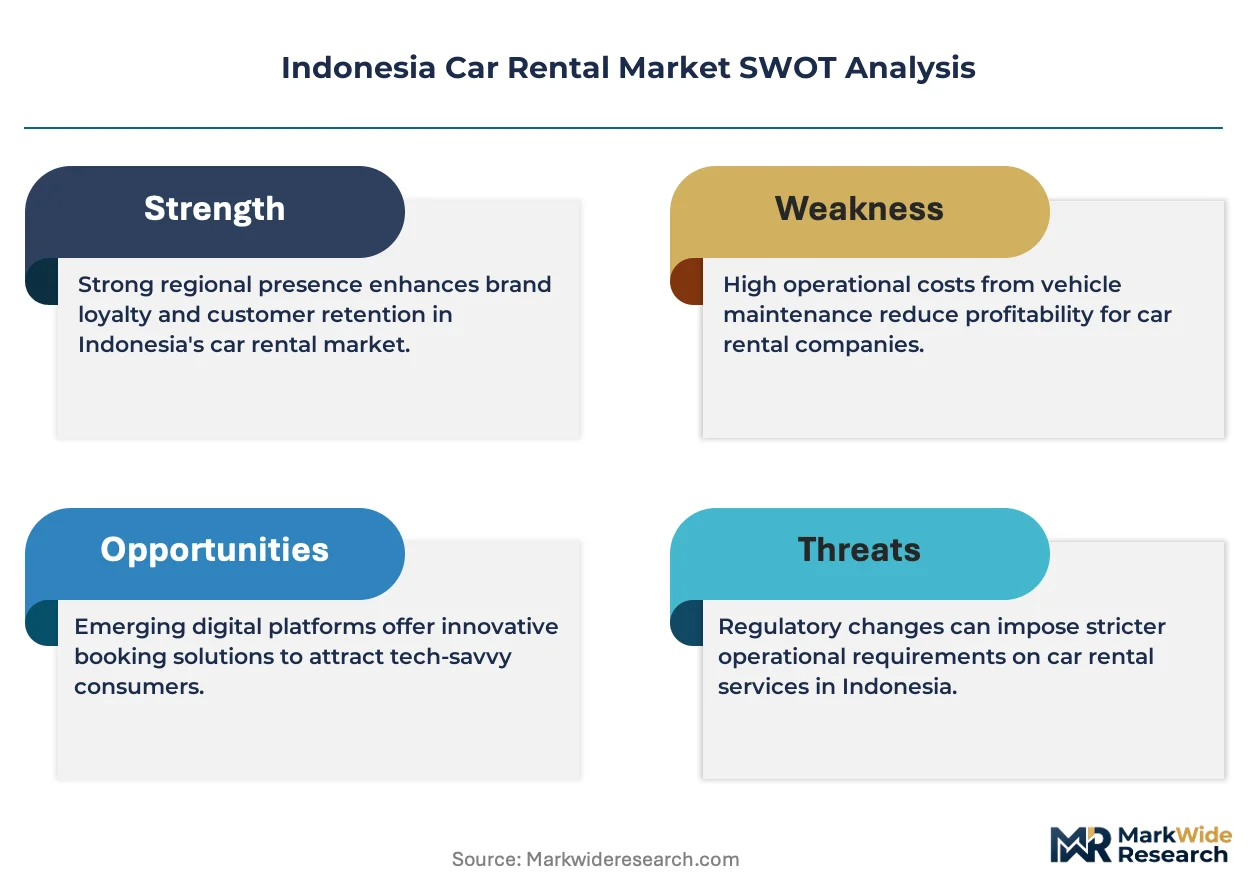
Certification-tier divergence between BIS-compliant fleet operators and informal rental providers splits pricing power across corporate contract tiers. Ministry of Transportation inspection mandates force commercial clients toward documented safety management systems, compressing margins for uncertified competitors while enabling premium capture by established fleet managers with dedicated compliance infrastructure.
Pricing Analysis
Corporate procurement discounts anchor the pricing architecture, with multinational enterprises in Jakarta negotiating all-inclusive mobility budgets bundling fuel, insurance, and maintenance. Price differentiation rests on telematics integration depth and after-sales service unbundling, where banking and pharmaceutical verticals pay premiums for predictive maintenance scheduling. Cost compression in short-term leisure channels intensifies as mobile app transparency enables rate comparison. Local residents exhibit highest price sensitivity, while corporate long-term contracts show lowest elasticity due to duty-of-care obligations.
Supply Chain Analysis
Hub-and-spoke distribution patterns concentrate vehicle procurement through Jakarta-based regional distribution centers serving Java and Sumatra operations. Fleet composition draws from Japanese and Korean manufacturing platforms, with BIS certification requirements for imported safety equipment creating procurement friction. Single-source vulnerability persists for telematics hardware and EV battery systems. Distribution runs through Astra International parent network channels for integrated conglomerate subsidiaries, while independent operators rely on direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's car rental market functions as a regulatory compounder where Ministry of Transportation safety mandates continuously elevate compliance barriers and redirect demand toward professional fleet managers.
For Market Incumbents: Anchor corporate long-term contract renewal cycles through embedded telematics integration and predictive maintenance outcomes. Defend against ride-hailing platform encroachment by accelerating electric vehicle fleet conversion ahead of charging infrastructure maturation in Surabaya and Bandung. Prioritize technician certification pipelines for EV maintenance competency as workforce scarcity emerges. For New Entrants and Emerging Players: AI-driven dynamic pricing algorithms offer entry leverage into fragmented leisure channels where incumbent legacy reservation systems lag mobile-native interfaces. White-space concentration exists in Medan and North Sumatra resource extraction corridors where corporate fleet outsourcing penetration trails Java. Pursue manufacturing verticals in Gresik and Sidoarjo with crew transport specialization. For Investors and Strategic Acquirers: Consolidation pressure builds where informal rental providers face escalating compliance infrastructure costs under periodic inspection mandates. Long-term viability favors operators with captive maintenance networks and documented safety management systems. Acquisition target archetype: regional specialists with telematics capabilities and underexploited corporate relationships in secondary cities. Monitor regulatory momentum around electric vehicle incentive disbursement as fleet electrification inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables outcome-based pricing tied to kilometers delivered rather than calendar periods. |
| Electric Vehicle Fleet Conversion | Aligns operator positioning with Ministry of Transportation regulatory momentum around EV incentives. |
| Technician Certification Pipeline Investment | Addresses emerging EV maintenance competency scarcity before workforce constraints harden. |
| Corporate Procurement System Integration | Captures multinational enterprise demand through automated expense management workflow compatibility. |
| Sumatra Geographic Expansion | Exploits underpenetrated corporate fleet outsourcing demand from palm oil and rubber processing operations. |
Study Parameters
Direct dialogue with fleet operations directors, corporate procurement managers, telematics platform engineers, and Ministry of Transportation compliance officers grounded qualitative insights. Secondary validation drew from BIS certification registries, Financial Services Authority leasing regulations, customs import data for vehicle platforms, and industry association fleet deployment surveys. Bottom-up contract volume analysis and top-down market sizing triangulated segment-level estimates.
Market projections across the analysis window reflect segmented modeling of service duration tiers, vehicle propulsion architectures, customer procurement patterns, and booking channel evolution. CAGRs derived from historical utilization trends, corporate outsourcing penetration rates, and charging infrastructure deployment trajectories in Jakarta, Surabaya, and Bandung. Electric vehicle adoption curves and ride-hailing regulatory frameworks informed scenario-weighted outcomes.
The model holds under continued enforcement of vehicle roadworthiness inspection regimes; deviation in EV incentive disbursement timing or ride-hailing integration rule finalization would shift fleet conversion trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Truck Sharing Market
Transportation Services
Vietnam Car Rental Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
United States Car Rental Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
Vehicle Management System Market
Transportation Services
Russia Car Rental Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
Water Truck Rental Market
Transportation Services
Spain Car Rental Market
Transportation Services
Scooter Rental Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Global Taxi Market
Transportation Services
ASEAN Taxi Market