
 Brazil Vehicle Rental Market | 2026-2036
Brazil Vehicle Rental Market Size, Share, and Industry Trends Forecast 2026-2036
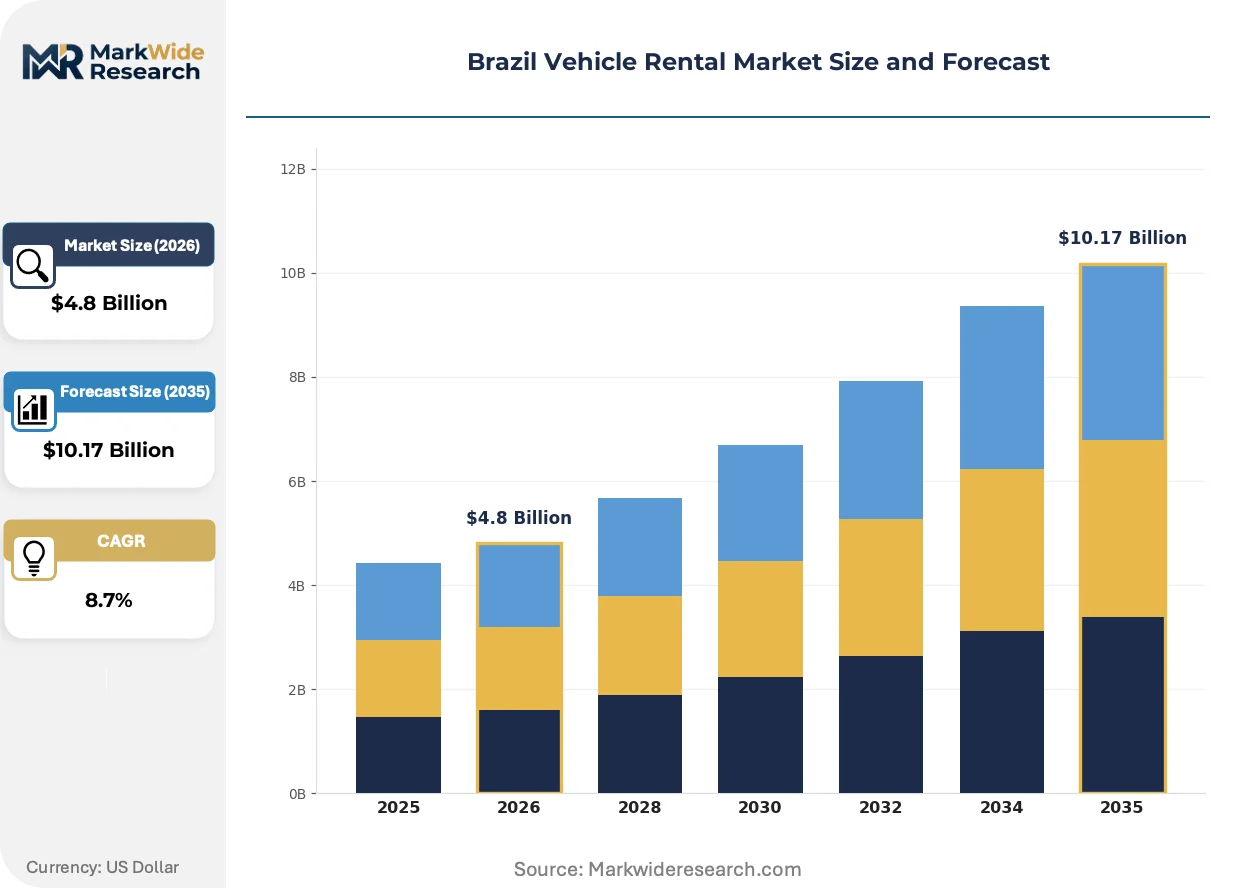
Brazil Vehicle Rental Market Outlook
Corporate fleet outsourcing is broadening as Brazilian enterprises reduce captive vehicle ownership. Localiza Rent a Car S.A. anchors nationwide coverage through its franchise-dealer hybrid model. Movida Participações S.A. leverages manufacturer partnerships for rapid fleet turnover. Sixt SE competes on premium positioning in São Paulo and Rio de Janeiro business districts.
Brazil vehicle rental encompasses short-term, long-term, car sharing, and luxury service formats across economy cars, SUVs, vans, and pickup trucks, with fleet composition governed by depreciation schedules, residual value forecasting, and manufacturer volume incentives. Online booking channels now dominate reservation flows, though corporate bookings retain higher per-transaction value and longer contract duration. Short-term rentals absorb peak tourism seasonality, while long-term rentals generate predictable revenue from enterprise accounts seeking balance-sheet flexibility.
ANVISA mandates commercial vehicle safety inspections, IBAMA enforces emissions compliance under CONAMA resolutions, and DENATRAN oversees driver certification standards that shape fleet eligibility and insurance pricing. Rental operators must synchronize fleet procurement with these overlapping requirements to maintain operating licenses and corporate contract eligibility. Stakeholders should monitor electric vehicle incentive structures and charging infrastructure rollout across southeastern state corridors.
Market Dynamics
Fleet electrification timelines are compressing as ANVISA safety mandates and IBAMA emissions protocols force rental operators to synchronize procurement with tightening compliance windows. This structural pressure is redrawing capital allocation priorities across São Paulo, Rio de Janeiro, and Belo Horizonte metropolitan corridors.
Growth Catalysts
- IBAMA CONAMA Resolution 492/2018:Phase-out schedules for high-emission commercial vehicles accelerate fleet turnover cycles. Rental operators capture volume incentives from manufacturers clearing combustion inventory.
- Ride-hailing platform integration:Driver supply pools in São Paulo's metropolitan corridor sustain utilization premiums above seasonal tourism baselines. Fleet operators monetize dead time through app-based dispatch.
- Corporate balance-sheet restructuring:Brazilian enterprises are shedding captive vehicle assets. Outsourced mobility contracts deliver predictable opex lines and transfer residual value risk to rental providers.
Market Restraints
- Residual value forecasting opacity:Accelerated electrification timelines distort depreciation schedules for internal combustion fleet segments. Lenders demand wider risk spreads on vehicle-backed financing.
- Charging infrastructure concentration:Southeastern state corridors dominate fast-charging deployment. Operators serving northern and central-west markets face range anxiety constraints on electric pilot programs.
- Import duty exposure on EV components:Local assembly requirements under ex-tarifário regimes inflate capital intensity for fleet electrification. Procurement teams must navigate MERCOSUR origin rules.
Strategic Opportunities
- Minas Gerais industrial corridor penetration:Underdeveloped long-term rental coverage in Belo Horizonte's manufacturing belt offers first-mover positioning. Mining and logistics enterprises seek flexible fleet solutions.
- ANVISA-aligned telematics integration:Real-time safety monitoring systems enable usage-based insurance pricing. Data streams differentiate corporate contract renewals.
- Airport hub density expansion:Viracopos, Guarulhos, and Santos Dumont terminals concentrate inbound business travel. On-site fleet positioning captures premium short-term rental yield.
Industry Challenges
- Technician certification gaps:DENATRAN commercial driver standards and emerging EV maintenance protocols strain training pipeline capacity. Fleet uptime suffers from qualified labor scarcity.
- Multi-regulator compliance synchronization:ANVISA inspection cycles, IBAMA emissions deadlines, and state-level traffic tribunal requirements create overlapping audit windows. Administrative burden fragments operational focus.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Vehicle Rental Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-Term Rentals, Long-Term Rentals, Car Sharing, Luxury Rentals Vehicle Type: Economy Cars, SUVs, Vans, Pickup Trucks Distribution Channel: Online Booking, Travel Agencies, Direct Rentals, Corporate Bookings Customer Type: Tourists, Business Travelers, Local Residents, Event Planners |
| Companies Covered | Enterprise Holdings, Sixt SE, Localiza Rent a Car S.A., Vamos Locacao, FOCO Rent a Car, Movida Participações S.A., Europcar Mobility Group, Turbi, Avis Budget Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Vehicle Rental Market Strategic Shifts
Connected fleet management systems are rewiring how rental operators price risk and deploy assets. Real-time utilization data is compressing the gap between short-term volatility and long-term contract stability.
Telematics-integrated fleet management platforms are rewriting competitive positioning in the Brazilian market. Corporate accounts now demand granular trip-level reporting for ESG disclosure requirements. Localiza and Movida are embedding hardware at scale to capture usage patterns that inform dynamic pricing algorithms. This data infrastructure is enabling outcome-based mobility contracts that transfer utilization risk from enterprise clients to fleet operators.
ANVISA's updated commercial vehicle safety inspection protocols are mandating onboard diagnostic connectivity for rental eligibility. IBAMA enforcement of CONAMA resolution timelines is tightening emissions documentation requirements. Fleet procurement teams must now synchronize vehicle acquisition with overlapping certification windows. São Paulo state operators face the steepest compliance density and are piloting automated audit preparation systems.
Subscription-based mobility models are displacing traditional long-term lease structures among mid-market enterprises. Brazilian finance teams prefer all-inclusive per-kilometer billing that eliminates residual value exposure. Channel conflict is emerging as direct fleet sales teams compete with rental affiliates for the same corporate accounts. This shift is most visible in Rio de Janeiro's professional services sector, where accounting and legal partnerships are consolidating vendor relationships.
Brazil Vehicle Rental Market Segmentation
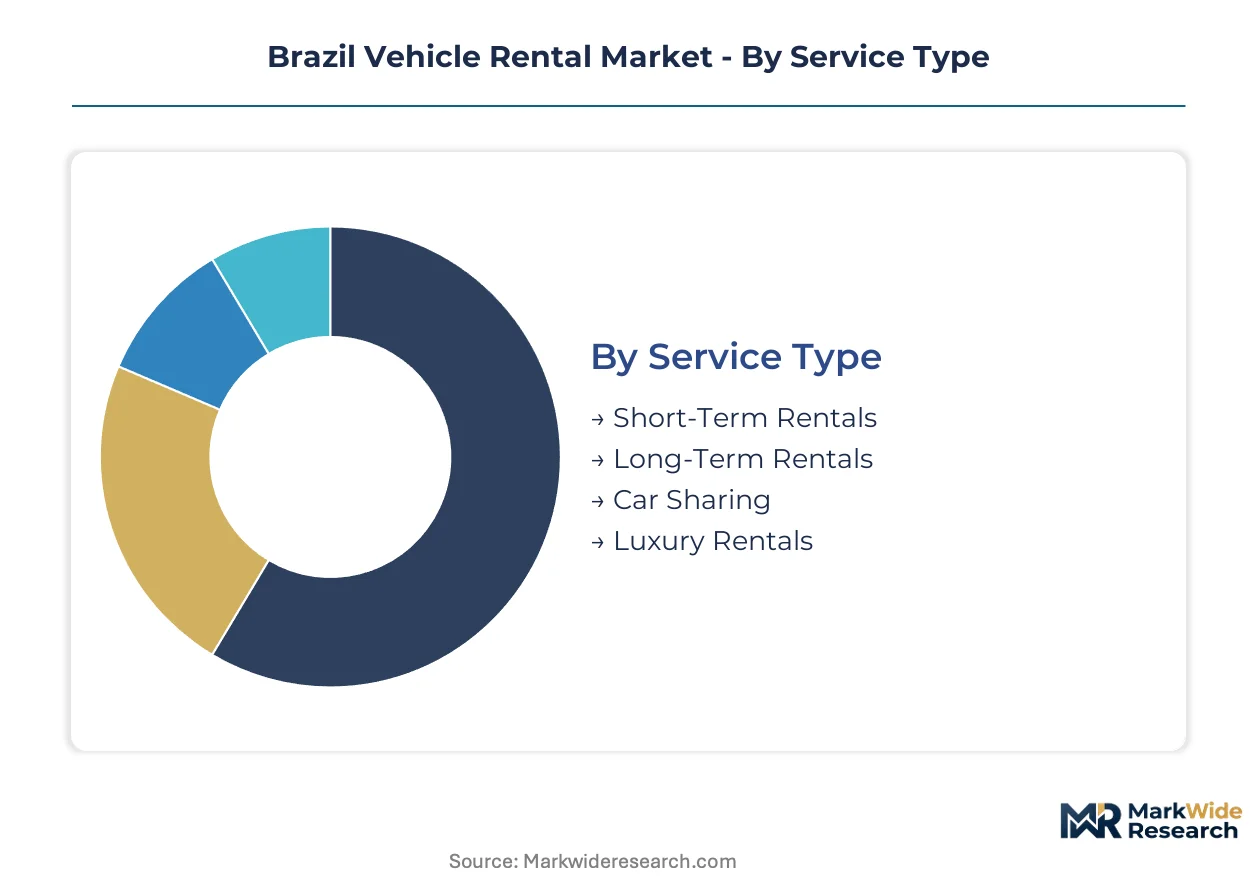
Fleet operators in Brazil calibrate procurement and pricing strategies around four intersecting dimensions. Each segment carries distinct ANVISA inspection cycles, IBAMA emissions documentation, and insurance underwriting profiles that shape capital allocation.
Service Type:
ANVISA mandates annual safety inspections for commercial short-term fleets, while long-term corporate contracts trigger quarterly telematics audits. Luxury rentals face heightened DENATRAN driver certification standards.
- Short-Term Rentals:Daily and weekly vehicle deployments absorb peak tourism seasonality at airport hubs. São Paulo's Guarulhos and Viracopos terminals concentrate inbound leisure demand where utilization premiums exceed corporate baselines during holiday windows.
- Long-Term Rentals:Multi-month enterprise contracts transfer residual value risk from Brazilian manufacturers and mining firms to fleet operators. Belo Horizonte's industrial corridor generates sustained contract volume from logistics enterprises seeking balance-sheet flexibility.
- Car Sharing:Hourly access models integrate with ride-hailing platforms in dense metropolitan zones. DENATRAN commercial driver requirements limit supply pool expansion.
- Luxury Rentals:Premium vehicle segments command specialized insurance tiers and chauffeur certification. Rio de Janeiro's business district anchors corporate executive transport demand.
Short-Term Rentals sits at the top of the volume ranking, with Car Sharing climbing the fastest.
Vehicle Type:
Procurement cost tiers stratify fleet composition, with economy segments capturing manufacturer volume incentives and premium categories absorbing electrification capital intensity.
- Economy Cars:Compact sedan and hatchback configurations dominate urban short-term rotation cycles. São Paulo metropolitan operators optimize fleet turnover around 18-month depreciation schedules aligned with IBAMA phase-out timelines.
- SUVs:Mid-size and full-size utility vehicles command higher per-day rates in leisure tourism corridors. Minas Gerais mining belt enterprises specify all-wheel-drive capability for site access contracts.
- Vans:Passenger and cargo configurations serve event logistics and workforce transport. ANVISA commercial inspection protocols apply to vehicles exceeding nine occupant capacity.
- Pickup Trucks:Light commercial utility segments penetrate agricultural and construction contractor accounts. Import duty exposure on diesel powertrains elevates financing spreads.
Economy Cars captures the highest transaction frequency, though SUVs is expanding most quickly in revenue per unit terms.
Distribution Channel:
Customer acquisition economics vary sharply across digital and relationship-driven channels, with corporate accounts delivering longer contract duration and lower churn.
- Online Booking:Mobile-optimized reservation platforms now dominate leisure traveler acquisition. Real-time inventory visibility compresses booking-to-pickup windows at airport locations.
- Travel Agencies:Tour operator partnerships bundle vehicle access with hospitality packages. Commission structures erode margin on standard vehicle categories.
- Direct Rentals:Walk-in counter transactions retain importance in secondary city markets. Staff-assisted upselling improves attachment rates for insurance and fuel products.
- Corporate Bookings:Negotiated master service agreements with Brazilian enterprises generate predictable recurring revenue. Procurement teams demand granular ESG reporting and telematics integration.
Online Booking leads transaction volume, while Corporate Bookings delivers the steepest expansion trajectory in contract value.
Customer Type:
Usage patterns and risk profiles diverge across leisure, commercial, and residential segments, informing dynamic pricing algorithms and fleet positioning.
- Tourists:International and domestic leisure travelers concentrate demand in coastal and cultural corridor routes. Seasonal peaks align with summer holiday and Carnival periods.
- Business Travelers:Corporate road warriors require guaranteed vehicle class availability and express pickup protocols. São Paulo-Rio de Janeiro air bridge connectivity sustains intercity rental flows.
- Local Residents:Supplemental vehicle access for special occasions and repair substitution generates weekend demand spikes. Price sensitivity exceeds business traveler tolerance thresholds.
- Event Planners:Conference and wedding logistics coordinators specify coordinated multi-vehicle deployments. Advance booking windows enable fleet pre-positioning.
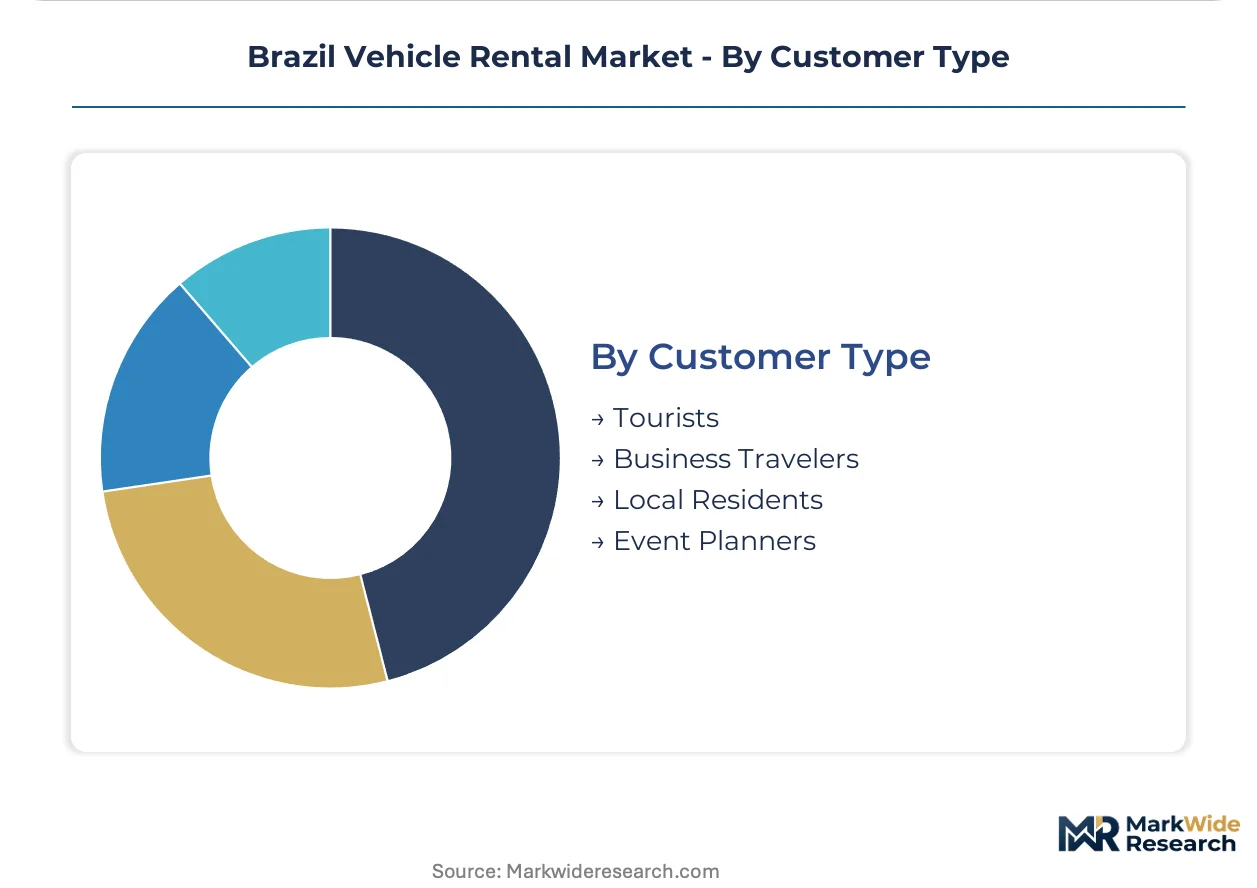
Business Travelers anchors revenue stability, with Event Planners gaining share fastest in premium vehicle deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA inspection cycles and IBAMA emissions deadlines create divergent compliance costs across Brazilian states. Fleet operators exploit these gaps by concentrating new vehicle registrations in jurisdictions with extended phase-out windows.
São Paulo
Corporate travel demand and airport hub density sustain premium utilization rates. The state's environmental agency CETESB enforces CONAMA resolution timelines more aggressively than northern counterparts. Guarulhos and Viracopos terminals anchor short-term rental yield during business travel peaks.
Rio de Janeiro
Leisure tourism seasonality and executive transport contracts drive luxury vehicle deployment. State-level traffic tribunal requirements add administrative burden to DENATRAN commercial certification. The metropolitan business district concentrates chauffeured service demand from legal and financial partnerships.
Minas Gerais
Industrial logistics and mining enterprise accounts generate long-term contract volume. Belo Horizonte's manufacturing belt exhibits underdeveloped fleet coverage relative to southeastern peers. Operators pilot subscription-based mobility models among mid-market contractors seeking balance-sheet flexibility.
Rio Grande do Sul
Agricultural and construction contractor demand elevates pickup truck financing spreads. State-level incentive programs for commercial vehicle renewal lag São Paulo timelines. Porto Alegre's metropolitan corridor offers expansion opportunity for car-sharing integration with regional logistics networks.
Bahia
Event logistics and cultural tourism create coordinated multi-vehicle deployment windows. Charging infrastructure deployment remains sparse outside Salvador's metropolitan core. Fleet operators face range anxiety constraints on electric pilot programs serving northern interior markets.
Brazil Vehicle Rental Market Competitive Environment
Strategic partnerships dominate the current landscape as operators seek manufacturer volume incentives and technology licensing. The market exhibits consolidated leadership at the national tier with fragmented regional coverage below. Three archetypes prevail: vertically integrated fleet owners, franchise-dealer hybrid networks, and platform-integrated mobility providers. Competitive intensity centers on airport hub positioning and corporate contract renewals rather than price-based rivalry.
Among nationally integrated operators, Localiza Rent a Car S.A., Movida Participações S.A., and Sixt SE exemplify distinct strategic postures. Localiza occupies a position anchored in franchise-dealer hybrid infrastructure. Movida represents manufacturer partnership-driven fleet turnover velocity. Sixt sits within premium-tier positioning concentrated in São Paulo and Rio de Janeiro business districts. These three anchors illustrate how capital intensity and regulatory compliance synchronization separate scalable national platforms from regional specialists.
| Leading Market Players |
|---|
| Enterprise Holdings |
| Sixt SE |
| Localiza Rent a Car S.A. |
| Vamos Locacao |
| FOCO Rent a Car |
| Movida Participações S.A. |
| Europcar Mobility Group |
| Turbi |
| Avis Budget Group |
| Others |
Value Chain & Pricing Dynamics
Franchise-dealer hybrid integration anchors both procurement scale and pricing power for Brazil's fleet operators, concentrating volume incentives from manufacturers while fragmenting downstream margin capture across metropolitan counter networks. This structure forces rental providers to absorb residual value volatility from accelerated IBAMA phase-out timelines while competing on utilization premiums at airport hubs.
Pricing Analysis
Distributor margin compression runs through São Paulo's airport hub network where online booking platforms disintermediate traditional travel agency commissions. Three-tier pricing structure across premium, standard, and economy levels stratifies around ANVISA inspection compliance tiers and telematics integration depth. Price erosion intensifies in short-term leisure segments as ride-hailing platform integration commoditizes dead-time fleet utilization. Corporate bookings exhibit lowest price sensitivity due to ESG reporting requirements and balance-sheet flexibility premiums.
Supply Chain Analysis
Single-source vulnerability sits with Chinese EV component suppliers subject to ex-tarifário import duty exposure under MERCOSUR origin rules. Fleet procurement draws from Brazil domestic assembly plants, Chinese battery cell manufacturers, and European premium vehicle exporters for luxury segments. Lithium-ion cell supply rests on concentrated Asian production capacity. Tariff exposure on EV powertrains elevates financing spreads for electrification pilots. Distribution runs through manufacturer-authorized dealer networks with direct fleet sales competing against rental affiliate channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's vehicle rental market reads as a late-cycle quality story where corporate demand shifts toward ANVISA-aligned telematics and IBAMA-certified low-emission fleets command contract renewal premiums.
For Market Incumbents: To counter technician certification gaps straining DENATRAN commercial driver pipelines, anchor defensive positioning through backward integration into captive maintenance training facilities and ANVISA audit preparation automation. Prioritize capacity addition in Belo Horizonte's underdeveloped industrial corridor before competitor preemption.
For New Entrants and Emerging Players: Airport ground transport partnerships offer the most penetrable channel entry, particularly at Viracopos and Santos Dumont terminals where incumbent fleet positioning remains thin. Target subscription-based mobility contracts among Minas Gerais mid-market contractors seeking balance-sheet flexibility. Deploy direct corporate sales teams with ESG reporting capabilities to bypass established affiliate networks.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with ANVISA-compliant maintenance infrastructure because CETESB enforcement timelines in São Paulo accelerate compliance-driven consolidation. Long-term viability centers on electrification capital intensity recovery through manufacturer volume incentives. Monitor charging infrastructure deployment velocity across southeastern state corridors as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | ANVISA-mandated diagnostic connectivity enables usage-based insurance pricing differentiation. |
| Electric Fleet Pilot Expansion | IBAMA CONAMA phase-out timelines force synchronization with manufacturer volume incentive windows. |
| Airport Hub Density Buildout | Guarulhos and Viracopos terminal positioning captures premium business travel utilization. |
| Subscription Mobility Model Launch | Per-kilometer billing transfers residual value risk from corporate clients to operators. |
| Maintenance Training Pipeline Investment | DENATRAN certification gaps constrain fleet uptime for competitors lacking captive technician capacity. |
Study Parameters
Direct dialogue with fleet procurement directors, ANVISA compliance officers, corporate travel managers, and IBAMA enforcement leads grounded qualitative assessment, cross-referenced with DENATRAN certification databases, CETESB emissions filings, vehicle registration statistics, and manufacturer incentive disclosure documents. Bottom-up and top-down triangulation validated segment-level assumptions across service type, vehicle category, and distribution channel dimensions.
Top-down macroeconomic anchoring informed fleet size elasticity to corporate travel expenditure cycles, while bottom-up unit economics modeled depreciation schedules against IBAMA phase-out timelines. Segmentation analysis spanned service type, vehicle class, distribution channel, and customer archetype across the projection horizon. CAGRs derived from utilization rate trajectories at airport hubs and corporate contract renewal velocity. Forecast inputs incorporated charging infrastructure rollout assumptions and MERCOSUR trade rule evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electric vehicle incentive structures and lithium supply chain volatility. Forecasts reflect documented assumptions regarding CETESB enforcement consistency and manufacturer volume incentive continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Global Taxi Market
Transportation Services
Drayage Services Market
Transportation Services
United States White Glove Delivery Service Market
Transportation Services
Vietnam Car Rental Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Car Rental Service Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
North America International Express Service Market
Transportation Services
Europe Van Rental Market
Transportation Services
Bike Rental Market
Transportation Services
Australia Taxi Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
Asia-Pacific Rickshaw Ride Hailing Service Market
Transportation Services
Asia Pacific Tourism Vehicle Rental Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
Thailand Car Rental Market