
 Global Moto Taxi Service Market | 2026-2036
Global Moto Taxi Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Moto Taxi Service Market Outlook
Electric two-wheeler integration into fleet operations is tilting capital allocation across the industry. Gojek tech anchors its Southeast Asian network through in-house battery-swapping infrastructure. Uber Technologies Inc. competes by leveraging its multimodal platform to cross-subsidize moto-taxi rides in price-sensitive corridors. Bolt Technology OÜ sustains expansion in African and European cities through localized driver recruitment and regulatory compliance teams.
A moto taxi service constitutes a commercial passenger transport arrangement where motorcycle-mounted operators ferry riders across short-to-medium urban distances, typically via app-mediated dispatch platforms with GPS tracking and dynamic fare algorithms. The primary commercial purpose centers on circumventing traffic congestion in dense metropolitan areas while offering lower per-trip costs than four-wheel alternatives. Ride-hailing dominates transaction volume due to instantaneous matching and minimal pre-planning friction, though subscription models are capturing corporate commuter contracts with predictable route patterns. Electric bikes within the vehicle type split are absorbing disproportionate fleet investment as municipalities impose emission restrictions on internal-combustion two-wheelers.
India's Motor Vehicles Act amendments and the country's central road safety regulator impose helmet and insurance mandates that reshape driver onboarding costs and liability structures. The EU Green Deal's urban mobility directives, coupled with REACH-compliant battery disposal rules, constrain fleet composition choices for operators serving European cities. Stakeholders must monitor evolving gig-worker reclassification rulings across Brazil's ANVISA-adjacent labor courts, Indonesia's transport ministry, and Nigerian state-level commercial vehicle authorities to anticipate cost-structure disruptions.
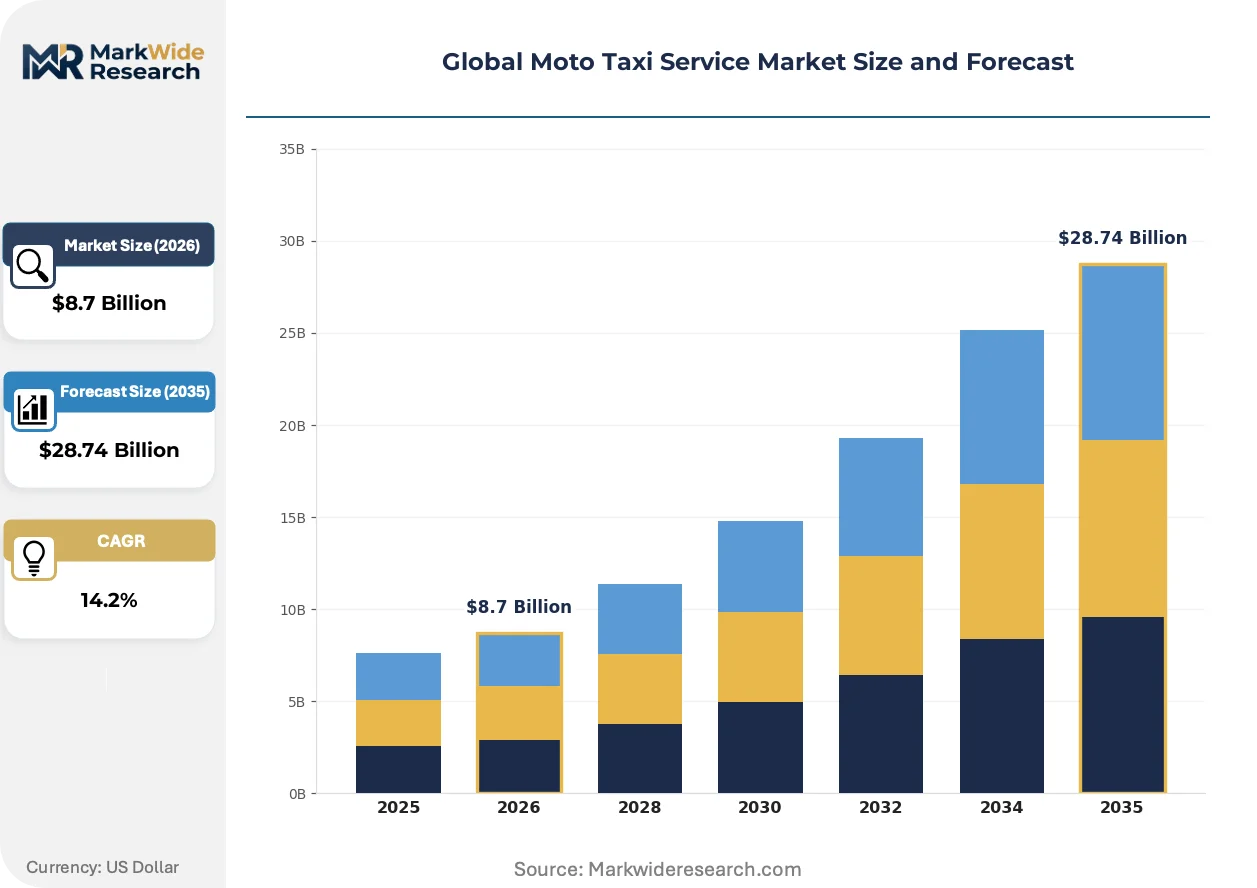
Market Dynamics
Electric two-wheeler mandates are compressing fleet economics across Southeast Asian, African, and Latin American operators, forcing capital reallocation toward battery-swapping infrastructure and away from internal-combustion asset depreciation cycles.
Growth Catalysts
- EU Green Deal urban mobility directives:European metropolitan emission zones are accelerating electric moto-taxi permits while restricting fossil-fuel two-wheeler access, creating regulatory pull for zero-emission fleet transitions.
- Battery-swapping infrastructure density:Station networks in Jakarta, Bangkok, and Ho Chi Minh City are eliminating range anxiety and enabling 18-hour daily utilization rates for electric fleet operators.
- First-mile-last-mile connectivity gaps:Metro rail expansion in São Paulo, Lagos, and Dhaka generates fixed-route feeder demand that motorcycle taxis serve more cost-effectively than microbuses or walking.
Market Restraints
- Lithium carbonate price volatility:Battery pack costs constitute 35-45% of electric two-wheeler acquisition outlays, exposing fleet operators to commodity swings without long-term offtake agreements.
- Driver supply concentration in informal channels:Unregistered operators in Nigerian, Indian, and Indonesian secondary cities capture 40-60% of trip volume, limiting platform pricing power and insurance attach rates.
- Helmet and passenger liability mandates:India's Motor Vehicles Act amendments impose per-trip insurance requirements and dual-helmet enforcement that inflate driver onboarding costs and reduce fleet elasticity.
Strategic Opportunities
- Corporate subscription contracts:Predictable commuter routes in Bangalore, Mexico City, and Nairobi business districts enable monthly pricing models with 20-30% lower customer acquisition costs than ad-hoc ride-hailing.
- Intermodal platform integration:Train-to-moto and bus-to-moto bundled ticketing in Jakarta, Manila, and Cairo captures transit-adjacent demand through API partnerships with municipal transport authorities.
- REACH-compliant battery second-life programs:European operators can monetize end-of-first-life powertrains through stationary energy storage, offsetting residual value risk against carbon credit revenues.
Industry Challenges
- Certification timeline compression for electric powertrains:Type-approval processes for novel battery chemistries and fast-charging systems lag 12-18 months behind product development cycles in EU and Indian markets.
- Gig-worker reclassification litigation:Brazilian labor courts, Indonesian transport ministry rulings, and Nigerian state commercial vehicle authorities are generating conflicting employment-status precedents that fragment compliance architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Moto Taxi Service Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Hailing, Pre-Booked, On-Demand, Subscription Payment Method: Cash, Credit Card, Digital Wallet, In-App Payment Vehicle Type: Standard Bikes, Electric Bikes, Scooters, Motorcycles Customer Segment: Commuters, Tourists, Delivery Services, Corporate Clients |
| Companies Covered | DiDi Global Inc., Bolt Technology OÜ, Uber Technologies Inc., Pathao Ltd., Ola, Grab Holdings Ltd., Rapido, SafeBoda, Gojek tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Moto Taxi Service Market Strategic Shifts
Platform economics are pivoting from pure ride-matching toward integrated energy and financial services, with battery-as-a-service models and embedded driver credit products emerging as margin drivers.
Silicon-anode battery chemistries are collapsing charging duration requirements for commercial two-wheeler fleets. Operators in Jakarta and Bangkok deploying 15-minute fast-swap stations report 23% higher daily trip completion versus overnight plug-in alternatives. This compression is eliminating the range-utilization tradeoff that previously constrained electric fleet penetration.
REACH battery disposal regulations are mandating producer-extended responsibility across European moto-taxi operations. Fleet managers must now contract certified recycling streams for end-of-life powertrains, adding 8-12% to total cost of ownership but unlocking circular material credits. Polish and Romanian operators are responding through vertical integration into battery collection networks.
Corporate procurement teams are consolidating commuter transport spend onto single-platform contracts with guaranteed service-level agreements. Multinational employers in Bangalore and São Paulo are displacing ad-hoc reimbursement models with prepaid monthly moto-taxi allocations, compressing vendor selection cycles and favoring operators with API-accessible expense reporting.
Global Moto Taxi Service Market Segmentation
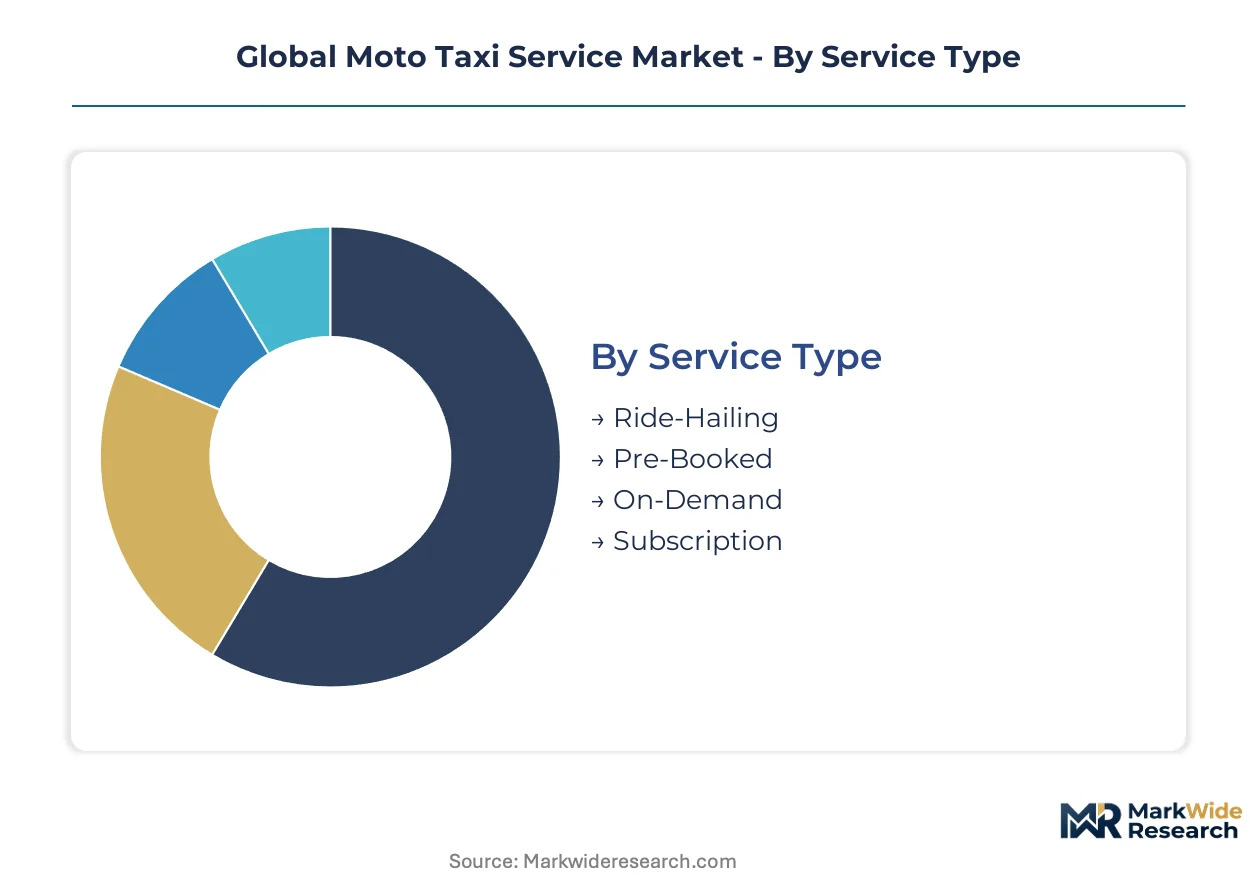
Moto taxi service segmentation reveals divergent capital intensity and margin profiles across dispatch models and powertrain technologies. Fleet operators calibrate vehicle composition and payment infrastructure to match urban density patterns and regulatory constraints in target metropolitan corridors.
Service Type:
Mature markets favor subscription lock-in while emerging corridors depend on on-demand liquidity to build driver supply density.
- Ride-Hailing:Instantaneous platform matching via GPS-enabled dispatch algorithms dominates transaction volume in Jakarta, Lagos, and São Paulo. Driver utilization rates peak during morning and evening commute windows when fixed-route transit capacity saturates.
- Subscription:Monthly commuter contracts with guaranteed availability clauses are capturing corporate procurement budgets in Bangalore and Mexico City business districts. Predictable route patterns reduce deadheading and improve driver earnings stability.
- Pre-Booked:Scheduled airport and intercity transfers serve price-insensitive travelers with luggage requirements in Ho Chi Minh City and Cairo.
- On-Demand:Ad-hoc street hailing without app mediation persists in Nigerian and Indonesian secondary cities where smartphone penetration lags.
Ride-Hailing retains volume leadership; Subscription holds the steepest expansion curve.
Payment Method:
Cost tier stratification separates cash-dependent informal operators from digitally integrated platforms capturing transaction data for credit underwriting.
- Digital Wallet:Embedded financial services through Gojek and Grab super-apps in Southeast Asia generate float revenue and reduce payment friction. Driver cash handling costs disappear while trip completion rates improve.
- In-App Payment:Card-on-file models with automated fare splitting enable corporate expense reconciliation for multinational employers in São Paulo and Nairobi.
- Cash:Unbanked rider segments and driver preference for immediate liquidity sustain paper transactions across African and South Asian markets.
- Credit Card:Direct card processing carries interchange costs that platforms in European cities absorb to attract business travelers.
Digital Wallet captures the fastest volume gains; Cash maintains residual dominance in informal corridors.
Vehicle Type:
Application requirements dictate powertrain selection, with emission mandates in European and Southeast Asian cities forcing electric transitions despite upfront capital penalties.
- Electric Bikes:Lithium-ion battery packs with swappable form factors enable 18-hour daily utilization in Jakarta and Bangkok station networks. EU Green Deal urban mobility directives restrict fossil-fuel permits in Amsterdam and Paris metropolitan zones.
- Standard Bikes:Internal-combustion two-wheelers with 100-150cc engines retain cost advantages in African markets lacking charging infrastructure. Driver acquisition costs remain 40% below electric equivalents.
- Scooters:Step-through frame designs with automatic transmissions serve short-distance tourist circuits in Barcelona and Rome historic centers.
- Motorcycles:Higher-displacement engines handle intercity routes and passenger-plus-luggage configurations on Indonesian and Philippine archipelago connections.
Standard Bikes retain volume leadership; Electric Bikes command the steepest expansion trajectory.
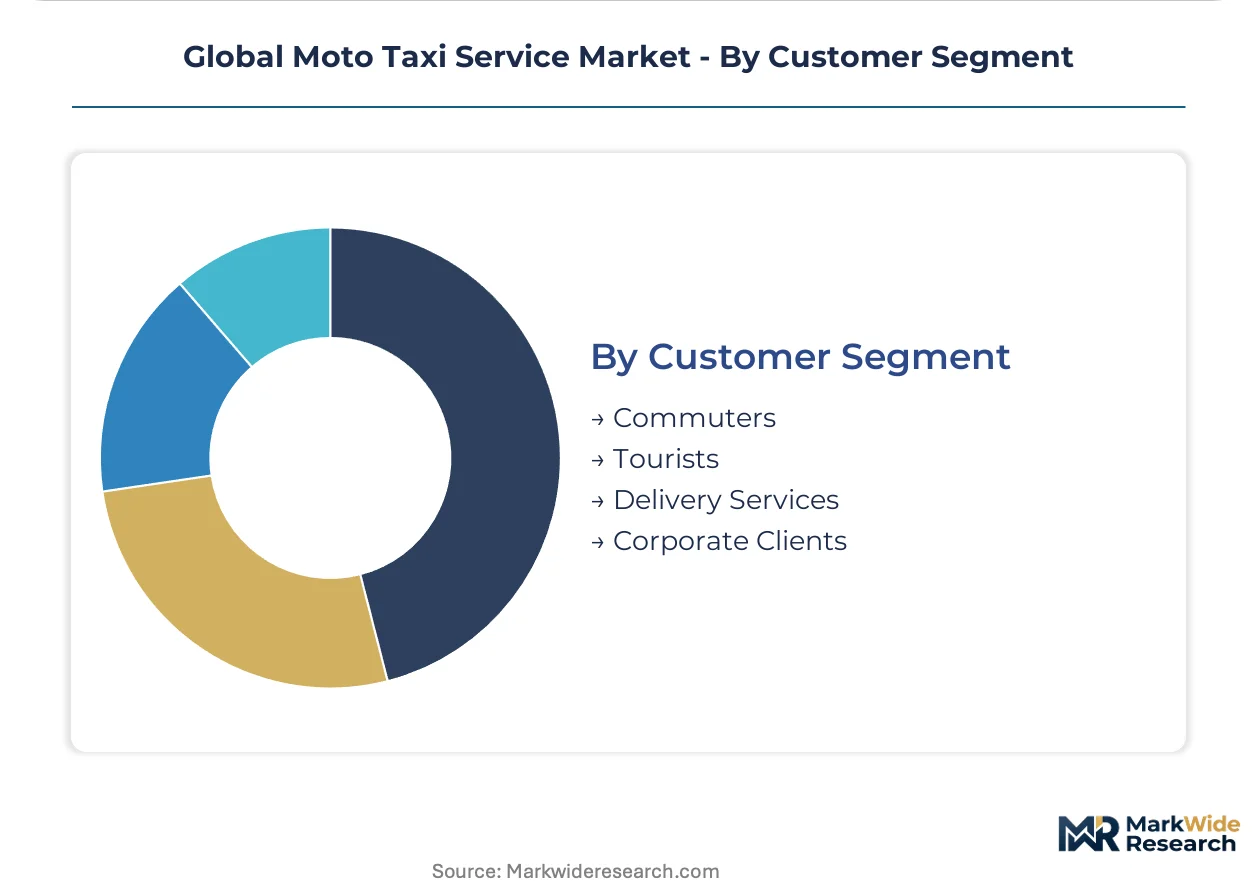
Customer Segment:
Customer type determines pricing power and retention economics, with corporate accounts offering superior lifetime value despite higher acquisition costs.
- Commuters:Daily work-trip regulars in Dhaka, Manila, and Lagos generate 60-70% of platform revenue through repeat booking patterns. Subscription bundling with metro rail passes deepens lock-in.
- Corporate Clients:Centralized procurement contracts with service-level agreements displace ad-hoc reimbursement in Bangalore and São Paulo technology parks. API-accessible expense reporting accelerates vendor consolidation.
- Tourists:Seasonal demand spikes in Barcelona, Rome, and Bali require surge pricing algorithms to balance fleet elasticity against driver supply.
- Delivery Services:Restaurant and parcel logistics operators in Mexico City and Nairobi utilize idle moto-taxi capacity during off-peak hours.
Commuters retain volume leadership; Corporate Clients deliver the fastest contract value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia exports battery-swapping infrastructure expertise to Vietnamese and Philippine operators expanding electric fleet networks. This trade-flow corridor accelerates zero-emission transitions across Southeast Asian metropolitan corridors while reshaping capital deployment patterns for charging infrastructure providers.
Indonesia
Jakarta's 18-hour daily utilization rates for electric fleets drive regional demand for fast-swap station networks. The country's transport ministry issues gig-worker reclassification rulings that reshape driver onboarding costs and liability structures. Surabaya and Bandung metropolitan clusters concentrate platform investment toward subscription commuter contracts with corporate procurement teams.
India
Bangalore technology parks generate concentrated corporate subscription demand with API-accessible expense reporting requirements. The Motor Vehicles Act amendments impose helmet and insurance mandates through the central road safety regulator. Delhi-NCR and Mumbai corridors absorb disproportionate fleet investment as operators navigate dual-helmet enforcement and per-trip insurance requirements.
Brazil
São Paulo metro rail expansion creates fixed-route feeder demand that motorcycle taxis serve more cost-effectively than microbus alternatives. ANVISA-adjacent labor courts generate conflicting employment-status precedents that fragment compliance architecture. Rio de Janeiro and Belo Horizonte clusters experience surge pricing algorithm deployment to balance fleet elasticity against driver supply constraints.
Nigeria
Lagos first-mile-last-mile connectivity gaps generate demand for motorcycle taxis serving transit-adjacent corridors. State-level commercial vehicle authorities issue conflicting gig-worker classification rulings that disrupt platform pricing power. Kano and Ibadan secondary cities retain 40-60% trip volume through unregistered operators, limiting insurance attach rates and formal platform penetration.
Germany
Berlin and Hamburg metropolitan emission zones accelerate electric moto-taxi permits while restricting fossil-fuel two-wheeler access. EU Green Deal urban mobility directives and REACH-compliant battery disposal rules constrain fleet composition choices. Munich and Frankfurt clusters drive corporate procurement consolidation onto single-platform contracts with guaranteed service-level agreements.
Global Moto Taxi Service Market Competitive Environment
Channel-controlling players compete with product-specialist players across a fragmented vendor base spanning ride-hailing platforms, battery infrastructure providers, and fleet management operators. The market structure tiers between integrated super-app operators with embedded financial services and single-vertical specialists focused on driver recruitment or charging networks. Three archetypes dominate: platform aggregators with multimodal integration, battery-as-a-service infrastructure owners, and regional compliance-focused operators. Competitive moves concentrate on strategic partnerships with municipal transport authorities and portfolio diversification into corporate subscription contracts.
Within the platform-aggregator tier, Gojek tech and Grab Holdings Ltd. exemplify super-app operators anchoring Southeast Asian networks through in-house infrastructure and embedded financial products. Uber Technologies Inc. occupies a position as a multinational platform leveraging cross-subsidization across mobility verticals. Bolt Technology OÜ sits within the regional-expansion archetype, with its Estonia-registered structure supporting localized compliance teams across African and European corridors. These three entities represent divergent geographic anchoring strategies rather than direct product competition.
| Leading Market Players |
|---|
| DiDi Global Inc. |
| Bolt Technology OÜ |
| Uber Technologies Inc. |
| Pathao Ltd. |
| Ola |
| Grab Holdings Ltd. |
| Rapido |
| SafeBoda |
| Gojek tech |
| Others |
Value Chain & Pricing Dynamics
Jakarta's battery-swapping station density anchors Southeast Asian fleet economics, with 18-hour daily utilization rates compressing per-trip costs and amplifying pricing power for operators controlling charging infrastructure. This supply-side concentration enables premium positioning against cash-dependent informal competitors while lithium carbonate volatility feeds cost pass-through pressures across electric fleet tiers.
Pricing Analysis
Internal-combustion-to-electric pricing gaps stratify fleet acquisition economics, with battery-pack premiums running 35-45% above standard bike outlays before infrastructure subsidies. Three-tier pricing structure across premium subscription, standard ride-hailing, and economy street-hailing levels reflects service-level differentiation and insurance attach rates. Cost compression in the electric tier is intensifying because lithium carbonate spot markets lack long-term offtake hedging. Corporate procurement teams in Bangalore and São Paulo exhibit lowest price sensitivity due to API-accessible expense reporting requirements, while unbanked commuters in Nigerian secondary cities drive cash-price elasticity.
Supply Chain Analysis
Extended payment terms from Chinese lithium-ion cell manufacturers and supply-chain finance facilities from Southeast Asian banking consortiums ease working capital burdens for fleet operators scaling electric transitions. Battery pack assembly concentrates in China, South Korea, and Japan, with cell chemistry innovation cycles resting on nickel-cobalt-manganese and emerging silicon-anode formulations. Single-source vulnerability runs through Indonesian nickel processing and Chilean lithium brine extraction, exposing fleet operators to commodity chokepoints. Distribution runs through platform-integrated driver financing networks that bundle vehicle acquisition with battery-as-a-service subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform fragmentation across regulatory jurisdictions and powertrain technologies creates white-space opportunities for specialists targeting underpenetrated corporate subscription segments and intermodal transit partnerships.
For Market Incumbents: Pre-empt driver supply erosion by locking exclusive battery-swapping access in Jakarta, Bangkok, and Ho Chi Minh City station networks before infrastructure saturation. Consolidate compliance architecture across Brazilian ANVISA-adjacent labor courts and Indonesian transport ministry rulings to neutralize gig-worker reclassification litigation. Vertical integration into REACH-certified battery recycling streams captures circular material credits and defends margin position against raw material volatility.
For New Entrants and Emerging Players: Kano and Ibadan's unregistered operator dominance—capturing 40-60% of Nigerian trip volume—offers conversion potential through mobile-money-integrated driver onboarding and micro-insurance bundling. Target corporate procurement consolidation in Bangalore technology parks and São Paulo business districts with guaranteed service-level agreements and API-accessible expense reporting. Go-to-market leverage rests on municipal transport authority partnerships for train-to-moto bundled ticketing.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because battery-swapping network density determines platform pricing power and driver retention economics across Southeast Asian metropolitan corridors. Acquisition targets should emphasize operators with captive charging infrastructure and corporate subscription contract books. Monitor EU Green Deal urban mobility directive implementation pace as inflection indicator for zero-emission fleet transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Swapping Infrastructure Buildout | Station density in Jakarta and Bangkok eliminates range anxiety and enables 18-hour fleet utilization. |
| Corporate Subscription Contract Capture | API-accessible expense reporting in Bangalore and São Paulo compresses vendor selection cycles. |
| Intermodal Transit Partnership | Train-to-moto bundled ticketing in Manila and Cairo captures fixed-route feeder demand. |
| REACH-Compliant Battery Recycling Integration | Polish and Romanian operators monetize end-of-life powertrains through circular material credits. |
| Regulatory Compliance Architecture Consolidation | Unified gig-worker classification protocols across Brazilian and Indonesian jurisdictions reduce legal fragmentation. |
Study Parameters
The analysis maps ride-hailing, subscription, and pre-booked service segments, each validated through fleet operations managers, driver cooperative leaders, municipal transport authority planners, and corporate procurement officers. Primary interviews with platform executives and charging infrastructure providers combined with secondary validation from EU Green Deal implementation filings, Indonesian transport ministry rulings, and Indian Motor Vehicles Act amendment records. Bottom-up trip volume modeling and top-down metropolitan mobility demand projections triangulate market sizing.
Assumptions held fixed include current regulatory trajectories for gig-worker classification and battery-swapping station deployment schedules, while electric vehicle penetration rates and lithium carbonate price paths were varied across sensitivity scenarios. Segmentation dimensions modeled encompass service type, payment method, vehicle powertrain, and customer segment across the projection horizon. CAGRs derive from driver supply elasticity estimates, fleet utilization rate projections, and corporate contract penetration curves calibrated against metro rail expansion timelines in São Paulo, Lagos, and Dhaka.
Practitioners should monitor gig-worker reclassification rulings across Brazilian labor courts and Nigerian state commercial vehicle authorities for early signals of cost-structure disruption. Forecasts reflect documented assumptions regarding battery chemistry cost decline curves and municipal emission zone expansion schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Europe Van Rental Market
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
Truck Rental Market
Transportation Services
Truck Sharing Market
Transportation Services
Scooter Rental Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
Thailand Car Rental Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Bulk Transportation Services Market
Transportation Services
Corporate Car Sharing Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Scandinavia Car Rental Market