
 Airline Passenger Service System Market | 2026-2036
Airline Passenger Service System Market Size, Share, and Industry Trends Forecast 2026-2036
Airline Passenger Service System Market Insights
Low-cost carriers is rebalancing toward hybrid deployment models as fare unbundling demands real-time inventory agility. Amadeus IT Group SA leverages its global distribution footprint to anchor premium carrier contracts across Europe. Sabre Corporation sustains North American market presence through specialized departure control modules. Travelsky Technology Ltd. dominates domestic Chinese airline procurement with state-mandated localization requirements.
An airline passenger service system constitutes an integrated software platform managing reservations, inventory, departure control, and customer relationship management through centralized data architectures operating on sub-second transaction processing thresholds. These systems enable airlines to synchronize seat availability, fare classes, and passenger manifests across global networks while maintaining operational continuity during peak booking windows. Cloud-based deployment captures the fastest-growing structural position as carriers shed capital-intensive on-premises infrastructure. The reservation component retains the deepest margin pool due to long-term contractual lock-in and switching costs. Hybrid architectures are concentrating among mid-tier airlines seeking phased migration paths without full legacy retirement.
The FAA mandates cybersecurity resilience standards for systems interfacing with U.S. air traffic management networks, while the EU AI Act imposes algorithmic transparency requirements on automated pricing and passenger profiling functions. IATA's NDC certification framework shapes product roadmap priorities by conditioning market access on standardized retailing capabilities. Stakeholders must monitor regulatory divergence between GDPR-driven European data localization and China's MIIT cybersecurity review protocols as these determine viable architecture choices for multi-national airline groups.
Market Dynamics
Cloud-native migration is compressing procurement cycles as full-service carriers retire legacy mainframe architectures, forcing incumbent vendors to rearchitect delivery models around containerized microservices and API-first retailing capabilities.
Growth Catalysts
- IATA NDC Certification:Mandated retailing standards accelerate carrier adoption of standardized merchandising interfaces, creating procurement pull for certified platform providers.
- EU CSRD Disclosure Mandates:Sustainability reporting requirements force airlines to demand carbon-footprint tracking modules embedded within passenger service architectures.
- Real-Time Inventory Agility:Fare unbundling across hybrid low-cost carriers necessitates sub-second availability synchronization between reservations and departure control systems.
Market Restraints
- Legacy Technical Debt:Decades-old COBOL-based reservation kernels impose integration friction that extends cloud migration timelines by 18-36 months for major carriers.
- Data Localization Requirements:China's MIIT cybersecurity review protocols and Russia's sovereign internet rules fragment cloud deployment architectures for multinational airline groups.
- Specialized Talent Scarcity:Deep expertise in airline-specific transaction processing protocols concentrates among aging engineering cohorts nearing retirement.
Strategic Opportunities
- India Aviation Expansion:UDAN regional connectivity schemes and privatized airport management create greenfield procurement opportunities among emerging full-service and ultra-low-cost entrants.
- AI-Driven Personalization:Convergence of machine learning inference engines with NDC retailing streams enables dynamic ancillary bundling at the point of sale.
- Sustainable Aviation Integration:EU Green Deal compliance modules for carbon offset calculation and sustainable aviation fuel tracking represent attachable revenue streams.
Industry Challenges
- Multi-Cloud Orchestration Complexity:Airlines pursuing hybrid deployments face operational continuity risks spanning AWS, Azure, and sovereign cloud instances with divergent service-level agreements.
- API Standardization Delays:Fragmented NDC implementation levels across carrier IT departments perpetuate retailing inconsistency and integration cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airline Passenger Service System Market |
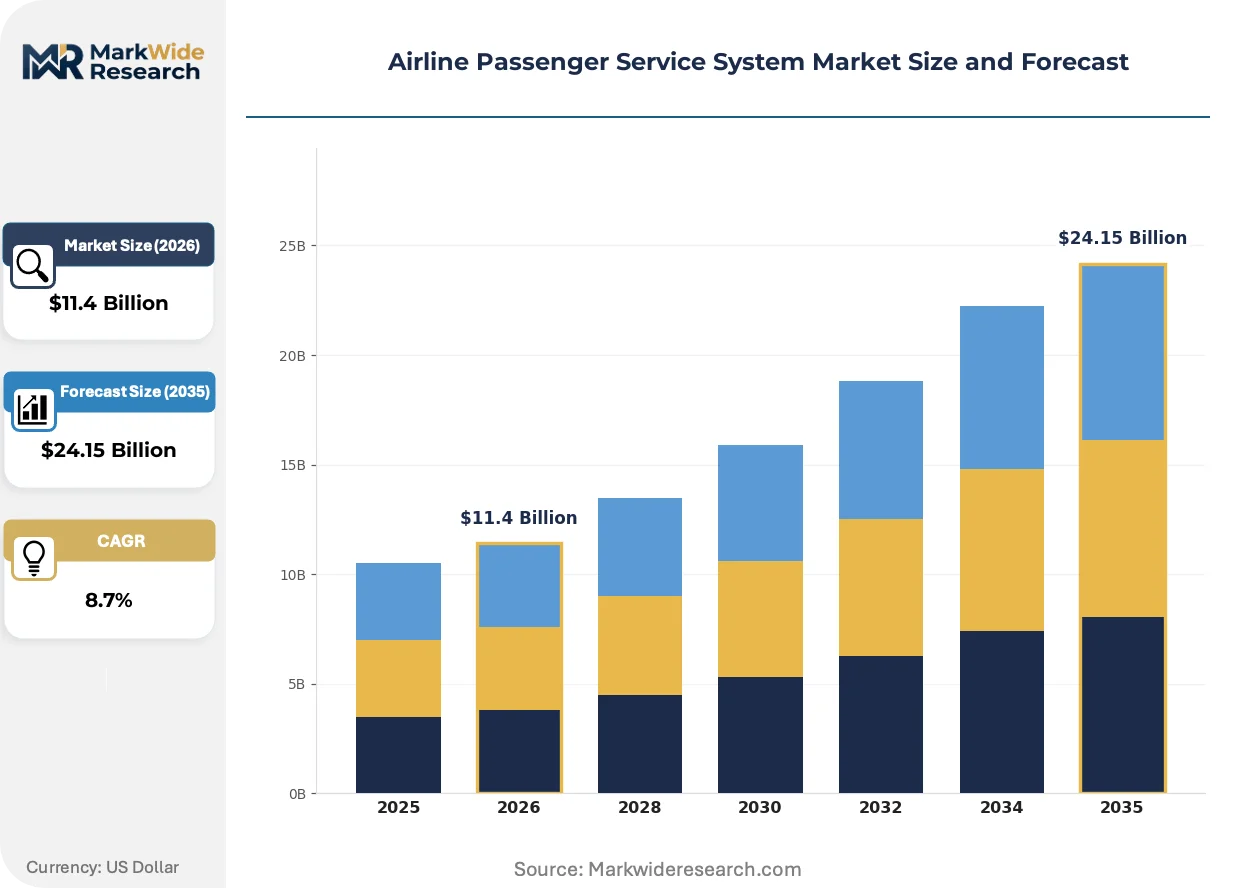
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted Component: Reservation, Inventory Management, Departure Control, Customer Relationship Management, Accounting Application: Check-In Management, Seat Assignment, Flight Scheduling, Passenger Profiling, Baggage Tracking End User: Airlines, Ground Handlers, Travel Agencies, Airport Authorities |
| Companies Covered | Hitit Computer Services, Travelsky Technology Ltd., Amadeus IT Group SA, Unisys Corporation, Radixx International, Sabre Corporation, Lufthansa Systems GmbH & Co. KG, Bravo Passenger Solutions Pte Limited, SITA NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airline Passenger Service System Market Trends and Innovations
Retailing architecture is pivoting from static fare filing toward continuous pricing engines, with artificial intelligence and distributed cloud infrastructure converging to enable individualized offer construction at scale.
Microservices-based passenger service platforms are rewriting competitive positioning by decoupling reservation, inventory, and departure control functions into independently scalable services. Low-cost carriers in Southeast Asia are adopting these architectures fastest, compressing vendor switching timelines from multi-year transformations to 12-18 month implementations. This modularization is enabling point-solution competition against historically dominant integrated suite providers.
The EU AI Act imposes algorithmic transparency requirements on automated pricing and passenger profiling functions, compelling vendors to deploy explainable machine learning models with auditable decision trails. Airlines operating European routes must now document how dynamic fare adjustments incorporate personal data, reshaping product roadmaps toward compliance-by-design architectures. Full-service carriers with complex hub networks face the steepest adaptation costs as their pricing engines rely on opaque multi-factor optimization.
Airline technology procurement is gravitating toward outcome-based commercial models where vendors assume operational risk for system uptime and retailing conversion metrics. This displaces traditional perpetual license structures with recurring revenue arrangements tied to passenger boarded or ancillary revenue captured. North American network carriers are piloting these contracts most aggressively, pressuring incumbent providers to restructure pricing and service delivery organizations.
Airline Passenger Service System Market Segmentation
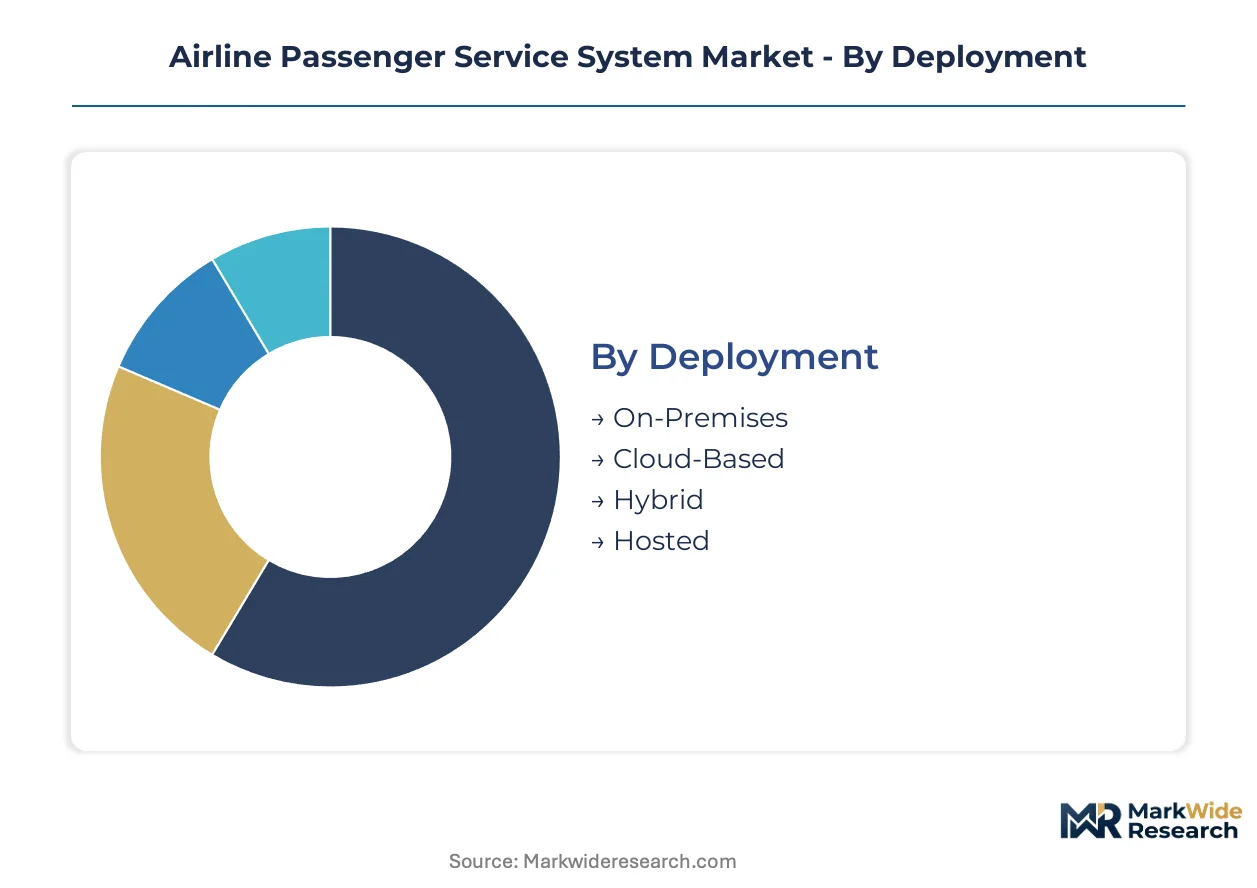
Passenger service system procurement varies sharply by carrier scale and operational complexity. Upgrade cycles differ fundamentally between legacy mainframe retirements and greenfield cloud-native deployments, fragmenting vendor engagement models across the market.
Deployment:
Migration timelines from legacy infrastructure create tiered replacement windows across carrier categories.
- Cloud-Based:Containerized microservices architectures enable elastic scaling during peak booking windows. Full-service carriers in Germany and the United States are consolidating procurement around AWS and Azure instances to shed data center capital obligations.
- Hybrid:Phased coexistence of on-premises reservation kernels with cloud-native retailing layers. Mid-tier airlines across Southeast Asia favor this path to preserve legacy integrations while modernizing passenger-facing functions.
- On-Premises:Capital-intensive owned infrastructure retained by carriers with sovereign data mandates or specialized latency requirements.
- Hosted:Third-party managed environments delivering dedicated instances without full cloud abstraction.
Volume placements concentrate in Hybrid; the faster expansion belongs to Cloud-Based.
Component:
Functional modules carry divergent switching costs and margin profiles that shape vendor contract structures.
- Reservation:Core transaction engines managing seat inventory, fare classes, and booking records through centralized database architectures. Long-term contractual lock-in at major network carriers in the United States sustains incumbent positions despite cloud migration pressures.
- Departure Control:Passenger manifest synchronization and gate management systems operating on sub-second processing thresholds. Ground handlers at Frankfurt and Dubai airports drive demand for modular point solutions.
- Inventory Management:Real-time seat availability and overbooking optimization engines.
- Customer Relationship Management:Loyalty program integration and passenger preference tracking modules.
- Accounting:Revenue recognition and interline settlement processing systems.
Contract durations extend furthest for Reservation; Departure Control is climbing the fastest as modular procurement gains traction.
Application:
Operational use cases determine integration complexity and API standardization requirements.
- Check-In Management:Multi-channel passenger processing spanning kiosks, mobile applications, and agent desktops. Low-cost carriers in India and Indonesia prioritize this function for rapid turnaround optimization.
- Passenger Profiling:Data aggregation for personalized retailing and security screening coordination. EU AI Act transparency mandates reshape development roadmaps for European route operators.
- Seat Assignment:Real-time cabin configuration and ancillary upselling interfaces.
- Flight Scheduling:Crew pairing and aircraft rotation optimization engines.
- Baggage Tracking:IATA Resolution 753 compliance and mishandled baggage recovery systems.
Procurement volumes cluster around Check-In Management; Passenger Profiling shows the steepest expansion trajectory amid NDC retailing investments.
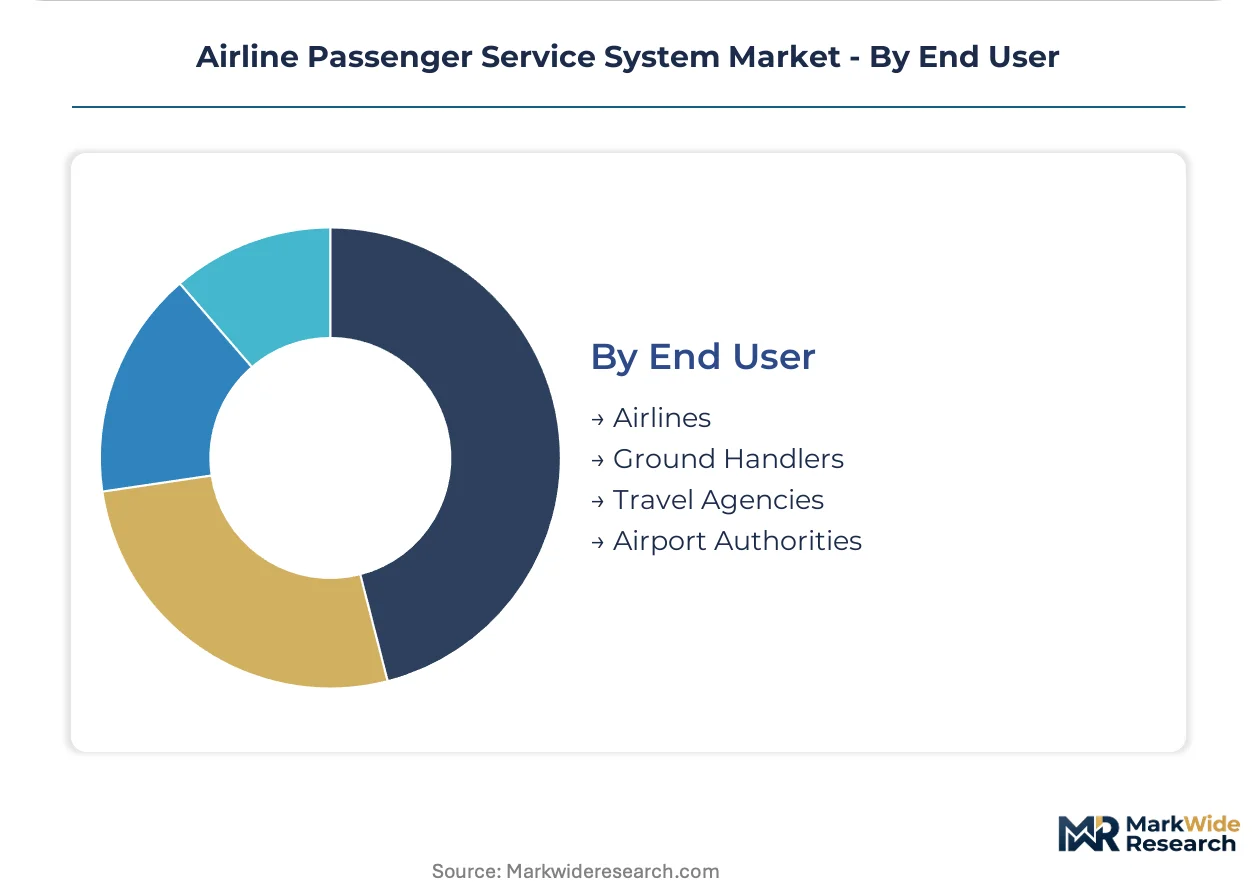
End User:
Buyer categories impose distinct contractual terms and implementation risk allocations.
- Airlines:Primary system owners requiring full-stack integration across reservations, inventory, and departure control. Full-service and low-cost carriers in China operate under MIIT-mandated localization requirements that constrain vendor selection.
- Ground Handlers:Specialized operators needing modular departure control and baggage management access. Swissport and dnata drive point-solution demand at hub airports in Germany and the United Arab Emirates.
- Travel Agencies:Intermediary booking platforms requiring GDS connectivity and NDC-compliant retailing interfaces.
- Airport Authorities:Common-use terminal infrastructure providers managing multi-tenant system access.
Revenue concentration sits with Airlines; Ground Handlers are gaining share fastest as outsourcing deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
System procurement concentrates where carrier consolidation meets regulatory modernization pressure. Demand generation runs through full-service network carriers shedding legacy infrastructure, while production capacity clusters around cloud hyperscaler regions and sovereign data zones.
United States
Network carriers at Dallas-Fort Worth and Atlanta hubs drive replacement cycles for aging mainframe reservation kernels. FAA cybersecurity resilience standards condition vendor eligibility for systems interfacing with national air traffic management networks. Seattle and San Francisco technology corridors host cloud-native development centers serving North American airline procurement.
Germany
Lufthansa Group's hub operations at Frankfurt and Munich anchor continental demand for integrated departure control and inventory management modules. EU CSRD disclosure mandates and GDPR data localization requirements shape vendor selection criteria toward compliance-embedded architectures. Berlin-Brandenburg corridor attracts specialized aviation software engineering talent from across Central Europe.
China
State-owned carriers under MIIT-mandated localization requirements sustain domestic procurement volume for sovereign passenger service platforms. MIIT cybersecurity review protocols constrain foreign vendor participation and enforce data residency within national cloud infrastructure. Beijing and Shanghai technology clusters concentrate Travelsky Technology's development and delivery operations.
India
UDAN regional connectivity schemes and privatized airport management at Delhi, Mumbai, and Bangalore generate greenfield procurement among emerging full-service and ultra-low-cost entrants. Directorate General of Civil Aviation operational directives accelerate modernization timelines for carriers expanding narrowbody fleets. Hyderabad and Pune software corridors supply implementation and integration engineering for domestic airline IT programs.
United Arab Emirates
Emirates and Etihad hub operations at Dubai and Abu Dhabi drive demand for premium-tier merchandising and passenger profiling capabilities aligned with IATA NDC certification frameworks. General Civil Aviation Authority interoperability standards condition system procurement for carriers serving European and Asia-Pacific routes. Dubai Airport Freezone concentrates ground handler technology procurement from Swissport and dnata for common-use terminal infrastructure.
Airline Passenger Service System Market Competitive Landscape
Top-tier vendors anchor integrated suite provision, while specialized point-solution providers capture modular procurement among low-cost carriers and ground handlers. Market structure reflects dual consolidation pressures: hyperscaler cloud partnerships reshape delivery economics, and NDC certification requirements erect compliance barriers for smaller entrants. Three archetypes dominate—legacy mainframe modernizers, cloud-native platform builders, and regional sovereignty specialists. Competitive intensity concentrates on M&A activity targeting niche departure control capabilities and strategic partnerships with AWS, Azure, and sovereign cloud operators.
Within the integrated platform tier, Amadeus IT Group SA and Sabre Corporation exemplify global-scale archetypes with established full-service carrier relationships. Travelsky Technology Ltd. occupies a distinct sovereignty-specialist position serving Chinese carriers under state-mandated localization requirements. These three entities represent divergent strategic paths—European-American global reach versus domestic Chinese market capture—each conditioned by regulatory geography rather than pure technology differentiation.
| Leading Market Players |
|---|
| Hitit Computer Services |
| Travelsky Technology Ltd. |
| Amadeus IT Group SA |
| Unisys Corporation |
| Radixx International |
| Sabre Corporation |
| Lufthansa Systems GmbH & Co. KG |
| Bravo Passenger Solutions Pte Limited |
| SITA NV |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure spot pricing indices cascade through vendor cost structures into three-tier pricing structures across premium, standard, and economy levels. Full-service carriers absorb premium SaaS tiers for guaranteed uptime SLAs, while low-cost operators select economy tiers with elastic scaling penalties during peak windows.
Pricing Analysis
Margin tightening in mid-tier SaaS subscriptions reflects hyperscaler compute cost pass-through and API transaction volume surcharges. Pricing stratifies across premium, standard, and economy tiers based on NDC certification level and after-sales implementation support depth. Cost compression in economy tiers accelerates because low-cost carriers negotiate volume-based transaction discounts. Ground handlers exhibit highest price sensitivity due to thin operational margins, whereas network carriers prioritize reliability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from major carriers mandate qualified backup vendors for reservation kernels and departure control modules, fragmenting procurement across Amadeus, Sabre, and regional specialists. Software development concentrates in Ireland, India, and Poland, while cloud infrastructure rests on AWS, Azure, and Alibaba sovereign instances. Single-source vulnerability persists for legacy COBOL engineering talent nearing retirement. Distribution runs through direct enterprise sales teams and systems integrators like Accenture and IBM for implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around NDC certification compliance, forcing sub-scale vendors without certified retailing engines toward exit or acquisition. IATA's mandated standards create winner-take-most dynamics in full-service carrier procurement.
For Market Incumbents: Acquire specialized departure control point-solution vendors to complete modular platform coverage against cloud-native challengers. Sabre and Amadeus should secure AWS and Azure strategic partnership tiers to lock in preferred pricing for carrier migrations. Incumbents must defend reservation module market share through long-term contractual extensions before hybrid architectures enable switching. For New Entrants and Emerging Players: Regional cloud service providers in Southeast Asia offer partnership pathways for microservices-based inventory management modules targeting UDAN-connected Indian carriers. Greenfield ultra-low-cost entrants in India and Indonesia represent the most penetrable segment due to absence of legacy mainframe baggage. New entrants should pursue API-first retailing layer specialization rather than full-stack competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular departure control specialists in Germany and the United Arab Emirates facing margin pressure from integrated suite vendors. Long-term viability hinges on NDC certification completion and cloud-native architecture conversion within a five-to-ten year carrier procurement window. Investors should monitor IATA NDC implementation level adoption rates as the primary inflection signal for platform switching velocity.| Strategic Initiative | Industry Significance |
|---|---|
| NDC Certification Completion | IATA certification unlocks full-service carrier procurement eligibility and merchandising revenue streams. |
| Cloud-Native Platform Migration | Containerized microservices architectures enable elastic scaling and compress implementation timelines for low-cost carriers. |
| Strategic Hyperscaler Partnership | AWS and Azure preferred partner status secures infrastructure cost advantages and co-selling access to airline CTOs. |
| Acquisition of Departure Control Specialist | Point-solution vendors like Hitit or Radixx fill modular gaps against integrated suite competitors at hub airports. |
| EU AI Act Compliance Investment | Explainable machine learning capabilities satisfy algorithmic transparency mandates for European route operators. |
Research Methodology
Multi-period observation of carrier procurement cycles, vendor contract announcements, and IATA NDC certification progress anchored the trend analysis, supplemented by interviews with airline CIOs, passenger service system product managers, aviation software engineers, and airport ground handling operations directors. Secondary validation drew from FAA cybersecurity directives, EU CSRD regulatory filings, MIIT localization notices, IATA resolution documents, and carrier annual reports. Bottom-up segment sizing triangulated against top-down market aggregation from cloud infrastructure spend disclosures.
Segment-weighting across deployment models, carrier tiers, and functional modules structured the analytical framework across the analysis window. CAGRs derived from logistic adoption curves for cloud migration and linear extrapolation of regulatory compliance deadlines. Industry-specific forecast inputs included narrowbody fleet delivery schedules and UDAN route authorization trajectories.
Caveats apply where IATA NDC implementation timeline delays or sovereign data localization rule expansions could materially shift the outlook. Deviation in carrier cloud migration velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Brazil Car Rentals Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Drayage Services Market
Transportation Services
Spain Car Rental Market
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
Corporate Car Sharing Market
Transportation Services
Bird Carriers Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
Water Truck Rental Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Europe Light Commercial Vehicle Rental Market
Transportation Services
Global Garbage Truck Market
Transportation Services
Full-Service Carrier Market
Transportation Services
Refrigerated Truck Rental Market