
 India Car Rental Market | 2026-2036
India Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
India Car Rental Market Insights
Peer-to-peer vehicle sharing is rewriting fleet economics across Indian mobility networks. Zoomcar leverages its technology stack to sustain asset-light operations in tier-1 cities. Avis India anchors premium chauffeur-driven services through direct airport counter presence. Revv competes on subscription flexibility, offering monthly swaps that reduce ownership friction for young professionals.
India car rental denotes the short-term commercial provision of automobiles against fixed-period contracts, encompassing self-drive, chauffeur-driven, and lease-operate arrangements where fleet owners retain asset ownership and maintenance liability. Vehicles undergo standardized insurance bundling, GPS telematics installation, and periodic fitness certification under Motor Vehicle Act norms before deployment. Self-drive rentals command widening consumer preference among urban millennials seeking weekend mobility without ownership burden, while corporate rentals sustain higher margin pools through negotiated annual contracts with volume guarantees. Chauffeur-driven segments dominate airport transfer and intercity routes where driver professionalism and route familiarity determine repeat booking rates.
BIS emission benchmarks and state-level RTO fitness mandates shape fleet turnover cycles and vehicle eligibility for commercial permits. The Motor Vehicles Act amendments and GST council rulings on lease taxation directly alter platform pricing architecture and interstate operational compliance costs. Stakeholders must monitor state-level EV policy rollouts and charging infrastructure tenders that will determine electric fleet viability in dense urban corridors.
Market Dynamics
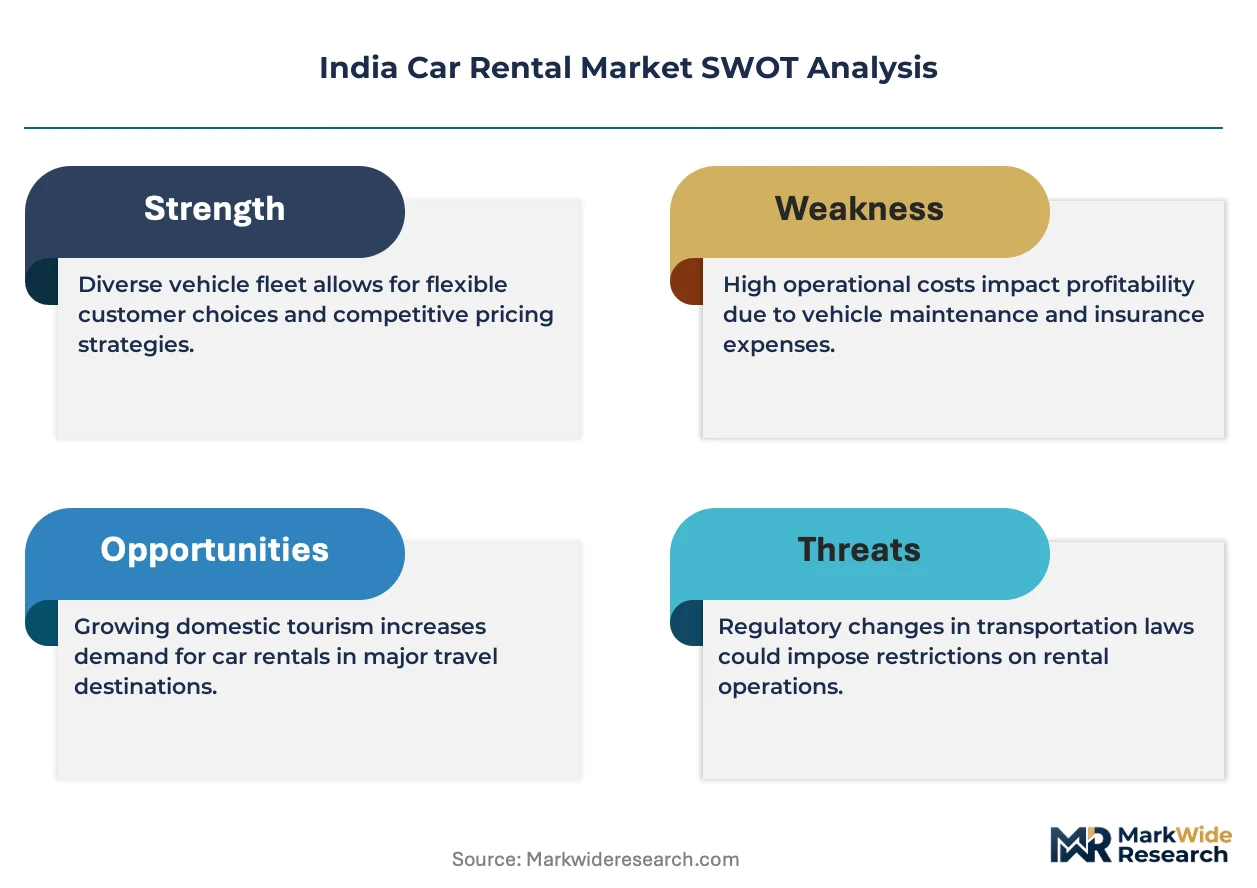
Asset-light fleet economics are compressing capital requirements across Indian mobility platforms, forcing operators to rebalance ownership models against telematics-enabled utilization tracking.
Growth Catalysts
- PLI Scheme for Automotive Manufacturing:Production-linked incentives reduce vehicle procurement costs for rental platforms expanding electric and hybrid fleets. Fleet operators recalibrate depreciation schedules around subsidy-adjusted acquisition prices.
- Corporate Travel Managers:Negotiated annual contracts with volume guarantees sustain higher-margin revenue pools. Multi-year service agreements embed telematics reporting and carbon accounting for ESG compliance.
- Maharashtra-Karnataka-Delhi NCR Corridors:Airport proximity and IT park density generate recurring rental volume with predictable demand patterns. Urban millennials in these clusters drive weekend self-drive bookings without ownership burden.
Market Restraints
- State-Level RTO Fitness Mandates:Heterogeneous compliance requirements across Indian states fragment fleet standardization. Operators maintain parallel documentation systems for interstate vehicle deployment.
- Petrol-Diesel Price Volatility:Fuel cost pass-through limitations compress margins on chauffeur-driven segments where rates are contractually fixed. Self-drive operators face customer resistance to dynamic fuel surcharges.
- Commercial Permit Concentration:Limited issuance of all-India tourist vehicle permits restricts fleet rotation flexibility. Permit scarcity forces operators to maintain state-specific sub-fleets with underutilized assets.
Strategic Opportunities
- Electric Fleet Viability:State-level EV policy rollouts and municipal charging infrastructure tenders enable zero-emission fleet pilots. BIS emission benchmarks will eventually disqualify older ICE vehicles from commercial permits.
- Subscription Flexibility Models:Monthly vehicle swaps reduce ownership friction for young professionals in Bangalore and Hyderabad. Revv-style flexibility is penetrating tier-2 cities with limited public transit.
- Airport Counter Presence:Direct premium chauffeur services at Delhi, Mumbai, and Bangalore terminals capture high-yield intercity routes. Avis India anchors this positioning through exclusive counter agreements.
Industry Challenges
- GST Council Lease Taxation Rulings:Interstate operational compliance costs fluctuate with periodic tax rate revisions. Platforms must reconfigure pricing architecture and invoice structures with each ruling.
- GPS Telematics Integration:Legacy fleet management systems require costly retrofitting for real-time utilization tracking. Smaller operators lack capital for unified telematics stacks.
- Driver Professionalism Certification:Chauffeur-driven segments depend on trained drivers with route familiarity, but standardized certification programs remain fragmented across states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Car Rental Market |
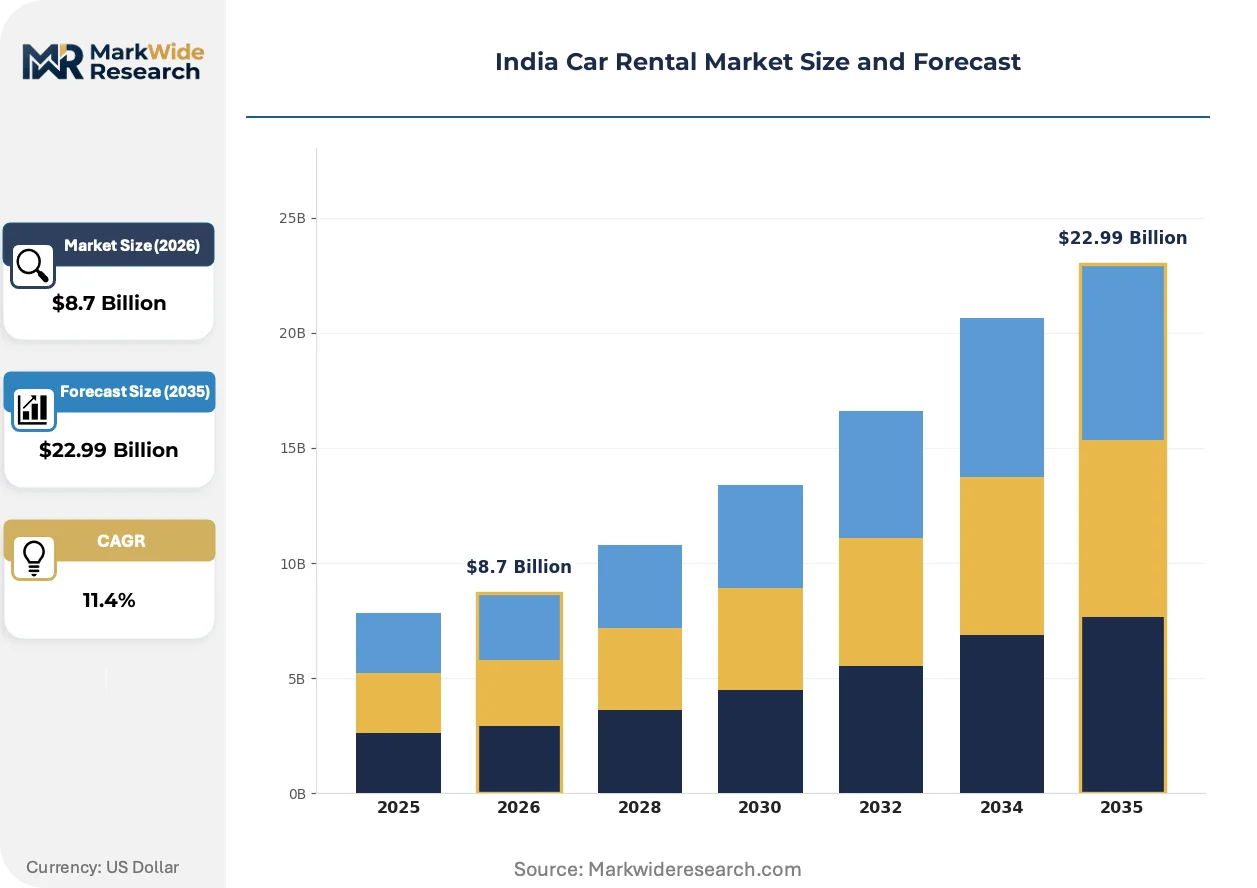
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Self-Drive, Chauffeur-Driven, Leasing, Corporate Rentals Vehicle Type: SUV, Sedan, Hatchback, Luxury Car Duration: Short-Term, Long-Term, Weekly, Monthly Customer Type: Tourists, Locals, Corporate Clients, Event Planners |
| Companies Covered | Avis India, Drivezy, Zoomcar, Carzonrent, MyChoize, Revv, Myles, Savaari Car Rentals, Ola Drive, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Car Rental Market Trends and Innovations
Telematics-enabled utilization tracking is compressing fleet turnover cycles while subscription models rewrite customer retention mechanics across Indian urban corridors.
Electric drivetrain technology is hybridizing operational strategies for Indian rental platforms. Battery-electric vehicles reduce per-kilometer operating costs for high-utilization airport routes. Zoomcar and similar operators pilot EV sub-fleets in Delhi-NCR and Bangalore where charging infrastructure is concentrating. The technology is hybridizing asset depreciation models as platforms weigh battery replacement reserves against fuel savings.
BIS emission benchmarks are accelerating fleet turnover timelines for commercial vehicle permits. Stricter particulate matter thresholds disqualify older diesel vehicles from renewal eligibility. Maharashtra and Delhi operators face compressed replacement cycles. Fleet managers respond by front-loading hybrid acquisitions to bridge compliance gaps.
Young professionals in Indian IT corridors are abandoning vehicle ownership for subscription-based mobility. Monthly rental commitments replace EMI burdens and maintenance liabilities. Corporate HR departments negotiate bulk subscription codes as retention perks. This pattern is most visible in Hyderabad and Pune where parking scarcity compounds ownership friction.
India Car Rental Market Segmentation
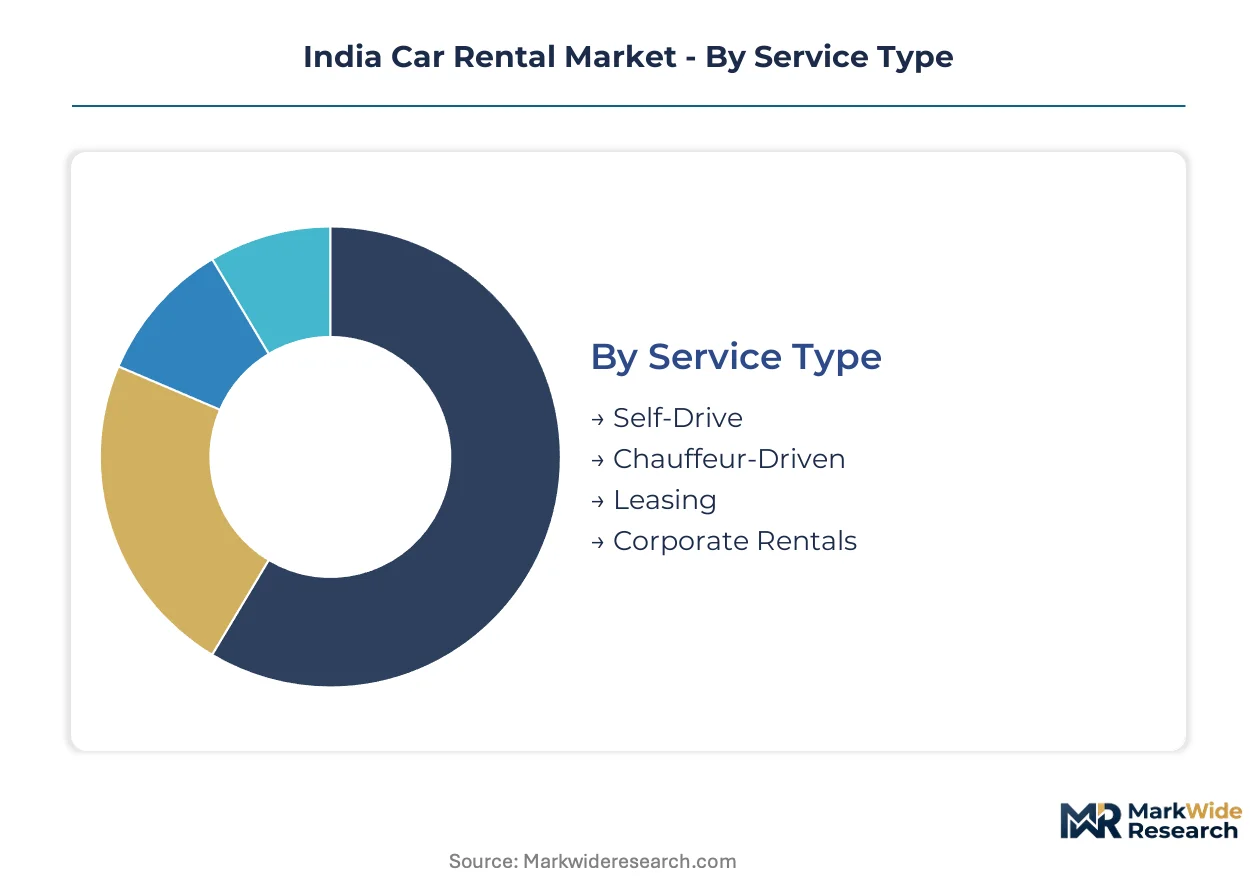
Segmentation in the India car rental market determines fleet configuration, pricing architecture, and capital deployment intensity. Operators align vehicle mix and contract structures against distinct utilization patterns and margin profiles across service tiers.
Service Type:
Mature segments dominate revenue concentration while emerging formats reshape capital efficiency.
- Self-Drive:Technology-enabled vehicle access where customers operate fleet assets without chauffeur accompaniment. Maharashtra and Karnataka urban clusters generate the highest booking density, driven by IT professionals seeking weekend mobility without ownership burden.
- Chauffeur-Driven:Professional driver-operated rentals serving airport transfers and intercity routes. Delhi-NCR corridors sustain premium yield through business traveler demand and route familiarity requirements.
- Leasing:Extended-term asset provision with maintenance bundling for corporate fleet replacement.
- Corporate Rentals:Negotiated annual contracts with volume guarantees and telematics reporting for ESG compliance.
Chauffeur-Driven handles the majority of throughput; Self-Drive is expanding most quickly on share.
Vehicle Type:
Cost tier differentiation separates premium positioning from utilitarian fleet economics.
- SUV:High-clearance multi-utility vehicles commanding rate premiums on intercity and leisure routes. Karnataka hill stations and Rajasthan tourist circuits drive concentrated demand for all-terrain capability.
- Sedan:Three-box passenger configuration anchoring corporate mobility and airport transfer segments. Delhi-NCR business corridors sustain predictable utilization through executive transport contracts.
- Hatchback:Compact urban mobility solution for budget-conscious self-drive customers.
- Luxury Car:Premium marque rentals serving wedding events and high-net-worth discretionary travel.
Sedan handles the majority of throughput; SUV is climbing the fastest on share.
Duration:
Contract length determines depreciation scheduling and customer acquisition cost recovery.
- Short-Term:Daily and hourly rentals serving impulse mobility needs and airport connectivity. Mumbai and Bangalore airport corridors generate recurring volume with high asset turns.
- Long-Term:Extended contracts spanning quarters to years with embedded maintenance and insurance. Corporate clients in Hyderabad and Pune reduce ownership friction through multi-year fleet substitution.
- Weekly:Seven-day blocks targeting leisure travelers and visiting professionals.
- Monthly:Thirty-day cycles enabling subscription-style mobility without EMI commitment.
Short-Term handles the majority of throughput; Long-Term is gaining share fastest.
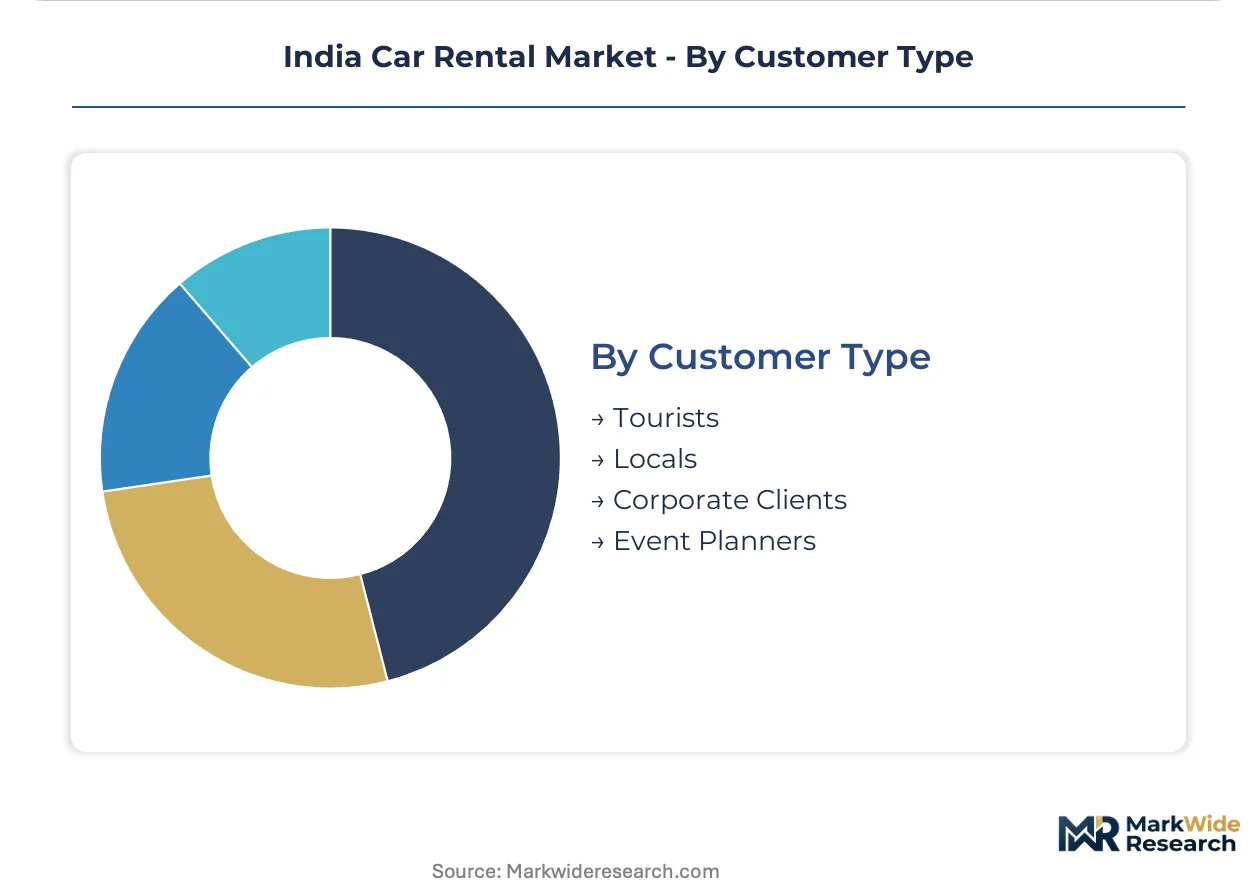
Customer Type:
Volume concentration varies sharply between discretionary travel and contracted enterprise demand.
- Tourists:Inbound and domestic leisure travelers generating seasonal demand spikes. Kerala and Goa coastal circuits sustain peak-season utilization with advance booking patterns.
- Corporate Clients:Enterprise accounts with negotiated rate cards and centralized billing. IT parks in Bangalore and Chennai anchor recurring weekday demand with predictable route profiles.
- Locals:Resident urban populations accessing vehicles for intermittent needs.
- Event Planners:Occasion-based rentals for weddings, conferences, and logistics coordination.
Corporate Clients handles the majority of throughput; Tourists is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Golden Quadrilateral highway network and dense airport corridor infrastructure underwrite India's position as the dominant South Asian mobility hub. Interstate expressways and metro rail interconnections concentrate rental demand in specific state clusters where IT parks and tourism circuits generate recurring volume.
Maharashtra
Mumbai-Pune Expressway traffic and Chhatrapati Shivaji Maharaj International Airport transfers sustain premium chauffeur-driven demand. The state transport department enforces commercial permit quotas under the Motor Vehicles Act. Fleet operators cluster around Mumbai's Bandra-Kurla Complex and Pune's Hinjewadi IT corridor for corporate contract fulfillment.
Karnataka
Kempegowda International Airport expansion and Electronic City tech parks generate self-drive bookings among young professionals. Karnataka's EV policy mandates and BESCOM charging infrastructure tenders enable electric fleet pilots. Bangalore's Whitefield and Koramangala sub-markets anchor subscription-model penetration for IT sector employees.
Delhi-NCR
Indira Gandhi International Airport handles the highest rental throughput in northern India for business traveler segments. Delhi's odd-even vehicle rationing scheme and GRAP air quality protocols periodically restrict private vehicle usage. Gurugram's Cyber Hub and Noida's Sector 62 office clusters sustain weekday corporate rental contracts.
Telangana
Rajiv Gandhi International Airport connectivity and Hyderabad's HITEC City expansion drive long-term corporate leasing demand. The state's EV policy framework and TSSPDCL charging station tenders support fleet electrification roadmaps. Gachibowli and Madhapur tech corridors concentrate subscription-model adoption among millennial professionals.
Tamil Nadu
Chennai International Airport and Sriperumbudur automotive manufacturing belt generate mixed leisure and business rental flows. Tamil Nadu's industrial policy incentives and TANGEDCO grid stability programs influence fleet composition decisions. OMR IT corridor and Mount Road commercial districts sustain recurring weekday demand patterns.
India Car Rental Market Competitive Landscape
On the supply side, the industry is fragmented across asset-light technology platforms and fleet-heavy traditional operators. The vendor base splits between peer-to-peer aggregators, corporate-focused leasing firms, and airport-centric premium service providers. Three strategic archetypes dominate: telematics-enabled self-drive platforms, chauffeur-driven airport specialists, and flexible subscription operators. Competitive intensity centers on M&A consolidation of regional fleet operators and strategic partnerships with hospitality and aviation channels.
Among technology-native platforms, Zoomcar and Revv exemplify the asset-light archetype through telematics-driven utilization optimization. Avis India occupies a position within the premium chauffeur-driven tier, leveraging airport counter exclusivity for intercity route capture. These three operators represent distinct strategic vectors: technology-first platform economics, premium service anchoring, and subscription flexibility respectively.
| Leading Market Players |
|---|
| Avis India |
| Drivezy |
| Zoomcar |
| Carzonrent |
| MyChoize |
| Revv |
| Myles |
| Savaari Car Rentals |
| Ola Drive |
| Others |
Pricing and Supply Chain Analysis
Maruti Suzuki and Hyundai Motor India anchor domestic vehicle supply for rental platforms, concentrating procurement leverage with two OEMs and compressing margin pools downstream for fleet operators negotiating volume discounts. Their dealership networks and direct fleet sales divisions determine vehicle availability timelines and residual value guarantees that shape rental pricing architecture across self-drive and chauffeur-driven segments.
Pricing Analysis
Volume-discount tiering structures dominate fleet procurement contracts, with operators securing steeper depreciation allowances above 500-unit annual commitments. Pricing stratifies across premium chauffeur-driven, standard corporate lease, and economy self-drive tiers based on vehicle age, insurance bundling depth, and telematics integration. Cost compression in the economy tier intensifies because fuel pass-through limitations prevent full surcharge recovery. Corporate clients exhibit lowest price sensitivity due to negotiated annual rate cards with ESG reporting requirements, while weekend leisure renters in tier-2 cities resist dynamic fuel adjustments most acutely.
Supply Chain Analysis
Tariff exposure between India and ASEAN trading partners dominates component cost volatility for fleet telematics hardware and GPS tracking modules. Domestic vehicle assembly draws from China, South Korea, and Japan for semiconductors, battery cells, and infotainment systems. Single-source vulnerability concentrates in lithium-ion battery supply for emerging electric sub-fleets. Distribution runs through OEM-certified dealership networks for new vehicle acquisition, parallel secondary auction channels for fleet turnover, and peer-to-peer aggregation platforms for asset-light utilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India car rental market represents high-growth disruption as BIS emission benchmarks and state-level EV mandates force fleet turnover timelines and electric drivetrain adoption.
For Market Incumbents: Build exclusive airport counter moats through direct terminal presence agreements with GMR and Adani airport operators. Consolidate regional fleet operators in Maharashtra and Karnataka to capture scale efficiencies in maintenance and permit compliance. Threaten subscription-model entrants like Revv by embedding monthly swap flexibility into existing corporate contracts. Leverage vertical integration into captive maintenance facilities to defend margin pools against asset-light technology platforms. For New Entrants and Emerging Players: Build out tier-2 city penetration in Indore, Kochi, and Chandigarh where public transit gaps and parking scarcity compound ownership friction. Target the monthly subscription segment among IT professionals aged 25-35 seeking EMI alternatives. Penetrate the corporate HR benefits channel through bulk subscription codes negotiated with Infosys, Wipro, and TCS campus operations. Anchor go-to-market through LinkedIn and urban coworking space partnerships rather than airport advertising. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fleet operators holding 200-500 vehicle portfolios in Delhi-NCR and Bangalore. Long-term viability hinges on electric fleet transition readiness and charging infrastructure partnerships with state electricity boards. Watch BIS emission benchmark revision announcements as the critical signal for accelerated ICE fleet obsolescence and replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Pilot Programs | BESCOM and TSSPDCL charging tenders enable zero-emission airport route trials in Bangalore and Hyderabad. |
| Telematics Platform Integration | Real-time utilization tracking from MapmyIndia and Bosch compresses fleet turnover cycles for operators. |
| Corporate Subscription Partnerships | HR-negotiated bulk codes at Infosys and Wipro campuses lock in recurring revenue with minimal acquisition cost. |
| Airport Counter Exclusivity Agreements | Direct presence at Delhi T3 and Mumbai T2 terminals captures premium intercity yield from business travelers. |
| Peer-to-Peer Aggregation Technology | Asset-light models reduce capital intensity while BIS fitness mandates shift liability to individual vehicle owners. |
Research Methodology
A standing panel of fleet operations directors, corporate travel managers at IT firms, RTO compliance officers, and airport ground transportation coordinators provided ongoing calibration across primary interview cycles. Secondary validation drew from Motor Vehicles Act amendments, state transport department permit issuance data, GST council rulings, and PLI scheme automotive sector disclosures. Bottom-up vehicle registration analysis and top-down mobility demand modeling were triangulated against telematics utilization benchmarks.
Scenario-bracketing framed volume projections across the analysis window, with segmentation dimensions spanning service type, vehicle class, contract duration, and customer archetype. CAGRs were derived from fitted growth curves against historical fleet expansion patterns and projected EV adoption S-curves. State-level policy rollout timelines and charging infrastructure tender awards served as industry-specific forecast inputs.
Stress conditions across fuel price volatility, permit issuance bottlenecks, and GST rate revision scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about PLI scheme continuity and state EV policy implementation pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Driving Vacation Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Refuse Truck Market
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
Europe Van Rental Market
Transportation Services
Car Rental Market
Transportation Services
Online Bus Ticketing Service Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
Cross Docking Services Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Equipment Relocation Service Market
Transportation Services
Benchmarking Services for Transportation Rates Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Compact Road Sweepers Market
Transportation Services
Canada White Glove Delivery Service Market