
 Aerial Lift Rental Services Market | 2026-2036
Aerial Lift Rental Services Market Size, Share, and Industry Trends Forecast 2026-2036
Aerial Lift Rental Services Market Insights
Certified boom and scissor lift operators is unwinding capacity constraints across North American rental yards. United Rentals leverages its national branch network to sustain same-day availability in major metro corridors. Ashtead Group anchors British and European coverage through Sunbelt Rentals, competing on fleet age and telematics integration. Herc Rentals differentiates with specialized industrial accounts, while Loxam dominates Southern European markets through localized depot density.
Aerial lift rental services supply temporary elevated work platforms—scissor lifts with vertical-only travel, boom lifts with articulated or telescopic reach, and trailer-mounted units for rapid deployment—enabling safe access at heights from twenty to over one hundred fifty feet for maintenance, installation, and construction tasks. Boom lifts command premium daily rates due to complex hydraulics and confined-site maneuverability, whereas scissor lifts generate volume through standardized slab applications in warehousing and retail fit-outs. Monthly rental structures capture the largest revenue share from general contractors seeking project-certain equipment without balance-sheet commitment, while hourly terms serve film production and event management with intermittent, precision-scheduled needs.
OSHA and ANSI A92 standards in the United States mandate documented operator training and annual equipment inspections, elevating compliance costs for independent fleet owners and consolidating demand toward national rental chains with in-house certification programs. The EU Machinery Directive and CE marking requirements impose parallel conformity obligations across European markets, favoring providers with standardized cross-border fleets. Stakeholders must weigh telematics-enabled predictive maintenance against residual value risk as electrification reshapes fleet composition and regional power infrastructure readiness.
Market Dynamics
Fleet electrification is compressing maintenance intervals and rewriting residual value curves across rental portfolios, forcing operators to rebalance holding periods against charging infrastructure investments.
Growth Catalysts
- Data Center Construction:Hyperscale facility builds in the United States and Germany consume extended-reach boom lift months at premium rates, tightening regional availability.
- ANSI A92.22:Updated safe-use standards in North America mandate telematics-equipped machines, accelerating replacement cycles toward connected fleet assets.
- Lithium-Ion Propulsion:Battery-electric scissor lifts eliminate indoor ventilation requirements, unlocking warehousing retrofit contracts previously served by vertical mast lifts.
Market Restraints
- Steel and Aluminum Volatility:Chassis fabrication costs swing with commodity indexes, complicating multi-year lease rate guarantees for fleet lessors.
- Component Supply Concentration:Hydraulic valve and joystick controller production clusters in Germany and Japan, exposing lead-time risk during trade disruptions.
- Used Equipment Glut:Post-2019 fleet expansion created secondary market oversupply, depressing trade-in values for internal combustion units.
Strategic Opportunities
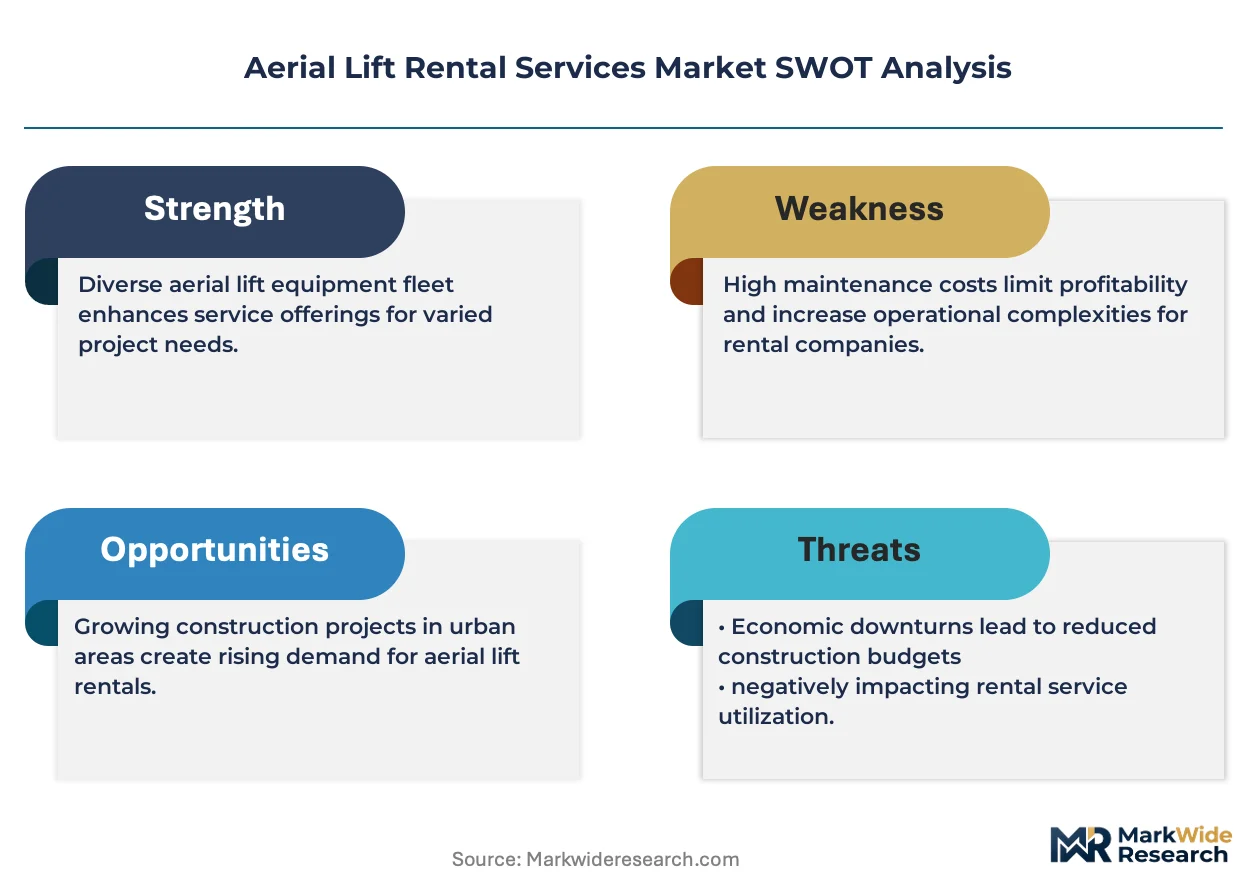
- Wind Turbine Servicing:Offshore and onshore blade maintenance contracts in Denmark and Scotland require 150-foot-plus boom reach rarely available from local depots.
- CE-MDR Convergence:Machinery Directive updates harmonize inspection documentation across EU member states, enabling cross-border fleet deployment without redundant certification.
- Telematics-Enabled Rental:Usage-based billing platforms capture intermittent demand from film production and event staging, displacing traditional monthly minimums.
Industry Challenges
- Certified Technician Scarcity:Hydraulic diagnostics and battery management system repair skills lag fleet electrification timelines, extending downtime for failed units.
- Multi-Standard Compliance:Operators must maintain parallel ANSI, CSA, and CE documentation for machines crossing US-Canada-Europe routes, multiplying administrative burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerial Lift Rental Services Market |
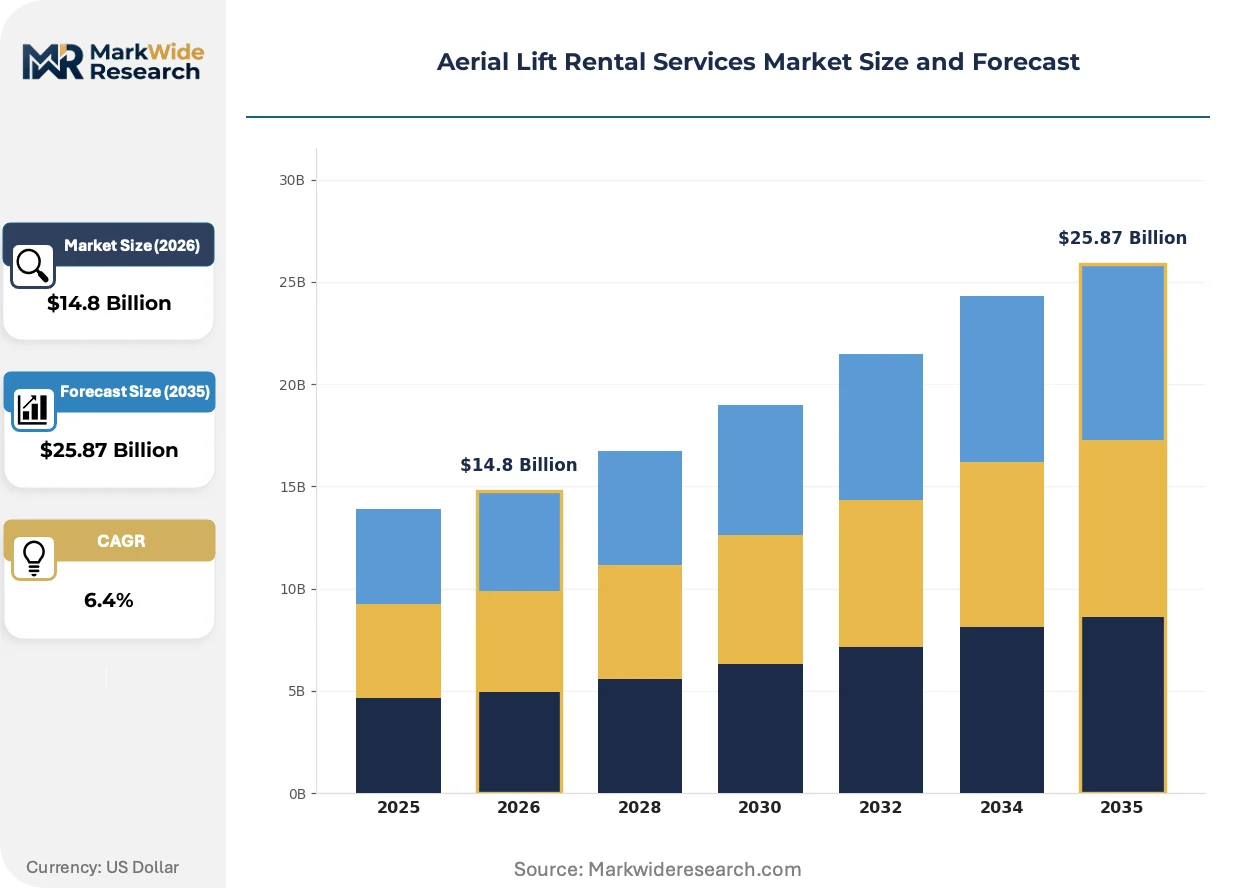
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Scissor Lifts, Boom Lifts, Vertical Mast Lifts, Trailer Mounted Lifts Application Sector: Construction, Telecommunications, Warehousing, Event Management Rental Duration: Hourly, Daily, Weekly, Monthly End User Industry: Manufacturing Plants, Utility Providers, Educational Institutions, Film Production |
| Companies Covered | United Rentals, Ashtead Group, Herc Rentals, Loxam, Aktio Corporation, Kiloutou, Riwal, Nishio Rent All, Kanamoto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerial Lift Rental Services Market Trends and Innovations
Digital fleet management and alternative powertrains are collapsing the distinction between equipment rental and full-service access solutions, repositioning providers as compliance and productivity partners rather than asset lessors.
Electric rough-terrain scissor lifts from JLG and Genie are displacing diesel equivalents in outdoor commercial construction, cutting fuel logistics and noise compliance costs for contractors working near residential zones or hospital campuses. General contractors in California and New York have adopted these units at accelerated pace, compressing diesel scissor residual values and shortening holding periods for legacy fleet.
OSHA's emphasis on documented operator training under 29 CFR 1926.453 is elevating in-house certification programs from cost center to competitive differentiator, particularly for national rental chains serving multi-state contractors. Rental providers with standardized ANSI-aligned training modules capture stickier relationships with safety-conscious buyers, while independent fleet owners face margin pressure from outsourced compliance administration.
Project-based procurement of aerial access is fragmenting across specialized brokers and manufacturer-direct rental arms, eroding traditional distributor relationships in metropolitan construction corridors. Tier-one contractors in Texas and Florida now source boom lifts through platform aggregators comparing real-time availability across competing fleets, compressing loyalty premiums and forcing depot operators toward guaranteed availability contracts.
Aerial Lift Rental Services Market Segmentation
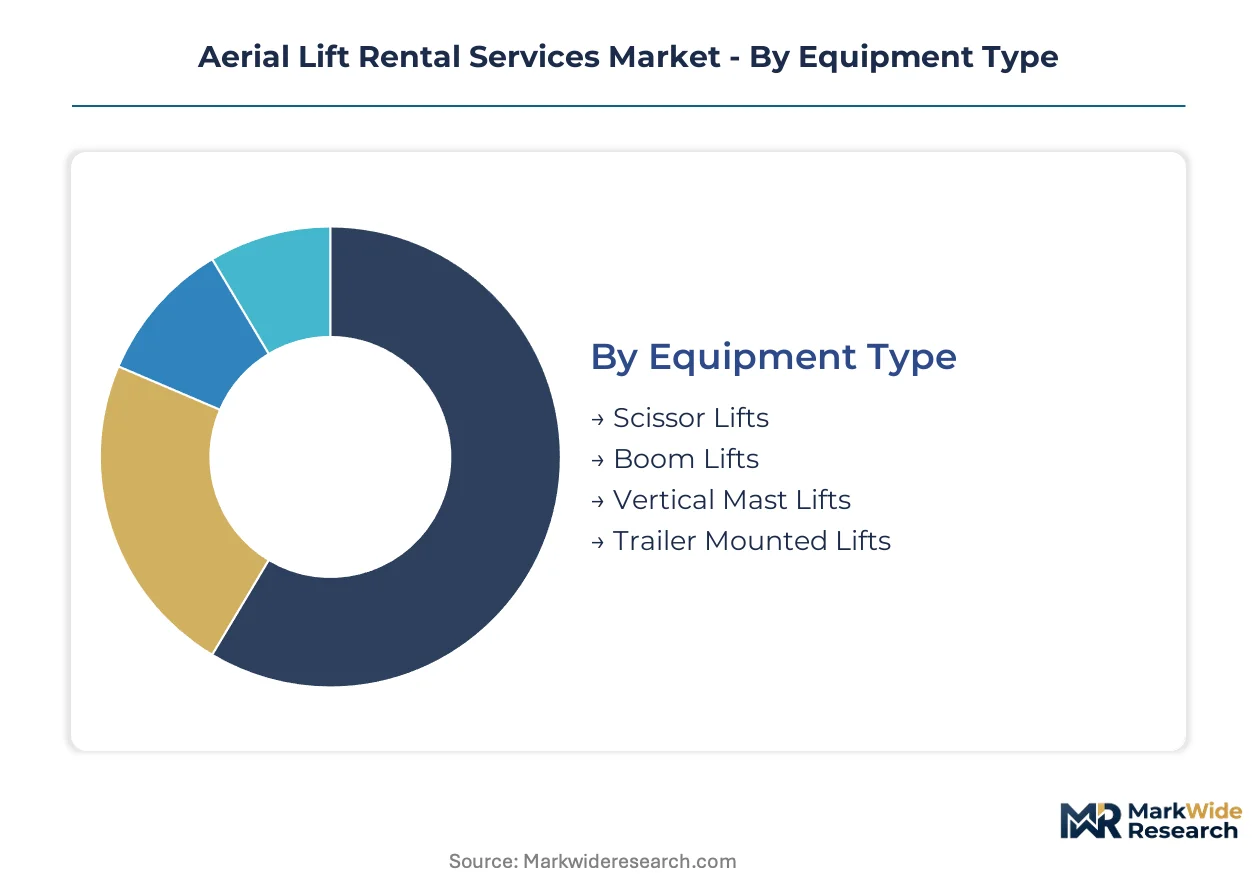
Rental providers structure fleet composition around equipment mobility characteristics and project duration patterns. Segmentation discipline determines depot density requirements and maintenance scheduling intensity across metropolitan corridors.
Equipment Type:
OSHA 29 CFR 1926.453 and ANSI A92.22 standards differentiate certification requirements between vertical-only and articulating platforms, shaping operator training investments.
- Boom Lifts:Articulating and telescopic booms extend reach beyond 150 feet with hydraulic precision for confined-site maneuverability. Hyperscale data center construction in Northern Virginia and Frankfurt consumes extended-reach units at premium rates, tightening regional availability during peak build cycles.
- Scissor Lifts:Vertical-only platforms with slab-style bases dominate standardized indoor applications through standardized deck dimensions and load ratings. Warehousing retrofit contracts in California and New York now specify lithium-ion electric units, eliminating diesel ventilation requirements and accelerating fleet turnover.
- Vertical Mast Lifts:Narrow chassis designs access aisle-width constraints in retail backrooms and maintenance corridors.
- Trailer Mounted Lifts:Rapid-deployment units serve intermittent maintenance on distributed infrastructure with highway-towable mobility.
Scissor lifts handle the majority of throughput; boom lifts are expanding most quickly on share.
Application Sector:
Project duration and site mobility requirements concentrate demand into distinct procurement patterns with varying rate structures.
- Construction:General contractors source monthly rental terms for project-certain equipment without balance-sheet commitment. Urban infrastructure renewal in Texas and Florida drives sustained fleet utilization through multi-phase commercial developments.
- Telecommunications:5G tower upgrades and fiber backbone expansion require rapid-response boom deployment across dispersed geographies.
- Warehousing:E-commerce fulfillment center construction favors electric scissor volume with standardized slab specifications.
- Event Management:Film production and stadium staging demand hourly precision scheduling with intermittent usage patterns.
Construction absorbs the dominant share of rental days; telecommunications is climbing the fastest as infrastructure buildouts accelerate.
Rental Duration:
Contract structure determines revenue recognition timing and fleet reallocation flexibility across depot networks.
- Monthly:Extended terms capture the largest revenue share from general contractors seeking equipment certainty across project phases without capital expenditure.
- Weekly:Mid-duration structures balance rate competitiveness with inventory turnover for maintenance windows and seasonal construction peaks.
- Daily:Short-cycle rentals serve emergency repairs and unplanned scope changes with premium per-day pricing.
- Hourly:Precision-scheduled terms dominate film production and live event staging where equipment sits idle between specific shot requirements or performance windows.
Monthly structures anchor revenue stability; hourly terms are gaining share fastest as usage-based billing platforms mature.
End User Industry:
Safety documentation requirements and operator certification standards vary sharply across institutional versus commercial account types.
- Manufacturing Plants:Scheduled maintenance turnarounds on processing equipment demand certified operators with site-specific safety clearances.
- Utility Providers:Transmission line and substation work requires insulated boom configurations with specialized dielectric testing documentation.
- Educational Institutions:Campus maintenance departments favor standardized scissor fleets with in-house operator training to minimize outsourced labor costs.
- Film Production:Location shoots combine hourly precision with rapid equipment repositioning across multiple set locations per production day.
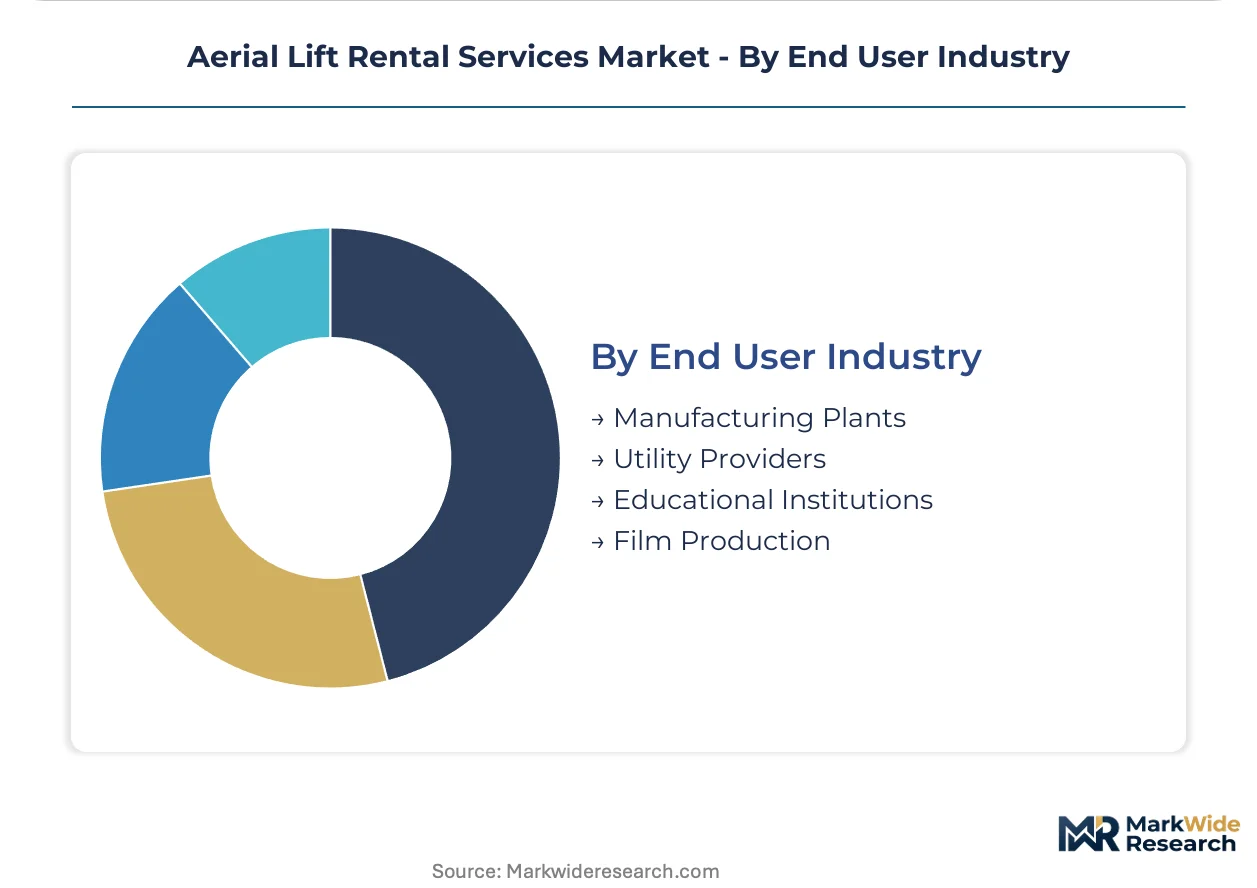
Manufacturing plants generate the steadiest recurring demand; film production shows the steepest expansion trajectory as content production volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA anchors regulatory stringency in the United States, where urban infrastructure renewal and data center construction compress fleet availability. ANSI A92.22 mandates telematics integration, accelerating replacement cycles toward connected assets across North American rental yards.
United States
Hyperscale data center builds in Northern Virginia and Texas consume extended-reach boom lifts at premium rates, tightening regional availability during peak construction windows. OSHA 29 CFR 1926.453 mandates documented operator training and annual equipment inspections, elevating compliance costs for independent fleet owners. The Dallas-Fort Worth metroplex anchors Sunbelt construction activity, where United Rentals sustains same-day availability through dense depot networks.
Germany
Wind turbine servicing contracts in the North Sea and Baltic coastlines demand 150-foot-plus boom reach rarely available from local depots, creating supply gaps for offshore blade maintenance. The EU Machinery Directive and CE marking requirements impose conformity obligations that favor providers with standardized cross-border fleets. The Frankfurt-Rhine-Main corridor concentrates logistics warehousing retrofits, where lithium-ion electric scissor lifts displace diesel equivalents under tightened F-Gas Regulation enforcement.
United Kingdom
Telecommunications infrastructure buildouts for 5G tower upgrades require rapid-response boom deployment across dispersed geographies, fragmenting procurement patterns toward platform aggregators. The Health and Safety Executive enforces LOLER and PUWER regulations for lifting equipment, parallel to EU machinery safety standards post-Brexit. Scotland's offshore wind clusters in Aberdeen and Dundee generate unmet demand for specialized high-reach units.
Japan
Manufacturing plant maintenance turnarounds demand certified operators with site-specific safety clearances, creating recurring demand for standardized training programs. METI promotes industrial equipment electrification through subsidy schemes that accelerate lithium-ion fleet turnover. The Chubu region around Nagoya anchors automotive supplier maintenance activity, where narrow-aisle vertical mast lifts access constrained production line corridors.
Australia
Mining sector maintenance on remote processing equipment favors trailer-mounted rapid-deployment units with highway-towable mobility across vast distances. The country's national workplace safety regulator enforces plant and equipment certification requirements that elevate documentation burdens for cross-state fleet movements. Western Australia's Pilbara region concentrates iron ore infrastructure maintenance, where diesel rough-terrain scissor lifts retain dominance despite electrification pressures.
Aerial Lift Rental Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the aerial lift rental services market, with national-scale depot networks commanding utilization premiums over regional operators. The structure rewards fleet standardization and in-house certification programs that absorb regulatory compliance costs. Three archetypes dominate: telematics-enabled fleet aggregators, industrial-account specialists, and cross-border European consolidators. Competitive intensity concentrates on guaranteed availability contracts and predictive maintenance capabilities.
Among North American integrated providers, United Rentals and Herc Rentals exemplify the scale-driven archetype with national branch density and standardized training modules. Ashtead Group occupies a position bridging Anglo-American coverage through Sunbelt Rentals, representing the cross-border consolidator model with telematics-integrated fleet management. These three entities anchor competitive dynamics around same-day metro availability and project-certain equipment certainty without balance-sheet commitment.
| Leading Market Players |
|---|
| United Rentals |
| Ashtead Group |
| Herc Rentals |
| Loxam |
| Aktio Corporation |
| Kiloutou |
| Riwal |
| Nishio Rent All |
| Kanamoto |
| Others |
Pricing and Supply Chain Analysis
Monthly minimum contracts with project-certain availability lock in fleet access for general contractors across Texas and Florida metro corridors, anchoring price visibility against spot-rate volatility during peak construction windows. This structure concentrates pricing power with national rental chains holding dense depot networks, while independent operators absorb margin compression from diesel-to-electric fleet turnover and telematics compliance investments.
Pricing Analysis
Geographic price spreads widen between Northern Virginia data center corridors and secondary Midwest markets, reflecting boom lift scarcity premiums during hyperscale build cycles. Three-tier pricing structure across premium telematics-equipped, standard compliant, and economy legacy tiers separates contractor segments by safety documentation requirements. Price differentiation hinges on fleet age and in-house certification bundling, with hourly terms for film production showing greatest price sensitivity against monthly construction commitments. Cost compression in diesel scissor categories is intensifying because California and New York electrification mandates accelerate residual value depreciation.
Supply Chain Analysis
Hydraulic valve production clustering in Germany and Japan creates component chokepoints that extend lead times for boom lift chassis assembly during trade disruptions. Manufacturing concentration draws from Chinese steel fabrication, German precision hydraulics, and Japanese joystick controller supply for fleet electronics. Supply chain risk centers on single-source vulnerability for lithium-ion battery management systems as electrification timelines outpace qualified technician training. Distribution runs through national depot networks with cross-border fleet pooling under CE marking harmonization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one general contractors in Texas and Florida who aggregate equipment demand across multi-phase developments, fragmenting procurement toward platform aggregators comparing real-time availability.
For Market Incumbents: Fortify depot density in Northern Virginia and Frankfurt-Rhine-Main corridors where data center and warehousing demand tightens availability premiums. Absorb ANSI A92.22 compliance costs through in-house certification programs that lock in sticky contractor relationships, while accelerating lithium-ion fleet turnover ahead of diesel residual value collapse. For New Entrants and Emerging Players: Differentiate on specialized high-reach boom deployment for Scotland and Denmark offshore wind servicing, where 150-foot-plus units face supply gaps against blade maintenance contracts. White-space concentration sits with trailer-mounted rapid-deployment units for Australian mining corridors and Japanese automotive supplier maintenance, bypassing entrenched national chain networks through highway-towable mobility. For Investors and Strategic Acquirers: Capital is best deployed toward telematics-integrated regional consolidators with cross-border CE marking standardization, capturing EU Machinery Directive harmonization benefits. Long-term viability frames around predictive maintenance platform differentiation and electrification-ready technician training infrastructure. The signal to watch is lithium-ion battery second-life valuation curves as fleet holding periods compress.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | ANSI A92.22 mandates connected fleet assets, accelerating replacement cycles toward usage-based billing. |
| Electric Fleet Transition | Lithium-ion scissor lifts unlock California and New York warehousing contracts under tightened ventilation rules. |
| Cross-Border Depot Consolidation | CE-MDR convergence enables fleet pooling across Germany, United Kingdom, and France without redundant certification. |
| Specialized High-Reach Capacity Addition | 150-foot-plus boom units capture Denmark and Scotland offshore wind blade maintenance premiums. |
| In-House Certification Program Expansion | OSHA 29 CFR 1926.453 compliance absorbs outsourced training costs, deepening contractor retention. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of equipment manufacturer production disclosures, rental operator utilization reports, and regulatory filing databases across OSHA, EU Machinery Directive, and METI jurisdictions. Primary interviews engaged fleet operations directors, plant maintenance engineers at manufacturing accounts, and procurement leads at tier-one construction contractors. Secondary validation drew from customs trade data for chassis component flows, SEC filings of listed rental operators, and ANSI/ISO standards documentation. Bottom-up depot density modeling and top-down construction spend allocation triangulate market sizing.
Segmentation dimensions modeled include equipment mobility characteristics, rental duration structures, and end-user industry safety requirements across the projection horizon. CAGRs derive from fleet replacement cycle analysis against electrification subsidy trajectories and telematics adoption curves. Industry-specific inputs incorporate data center construction pipeline tracking and wind turbine servicing contract visibility.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure investment levels or accelerated electrification timelines would require recalibration. Forecasts reflect assumptions on lithium-ion battery cost trajectories, steel and aluminum commodity stability, and cross-border trade continuity for hydraulic component sourcing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
Vehicle Management System Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
Europe Light Commercial Vehicle Rental Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Truck Sharing Market
Transportation Services
Thailand Car Rental Market
Transportation Services
Europe Van Rental Market
Transportation Services
Drayage Services Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Refuse Truck Market
Transportation Services
Indonesia Car Rental Market