
 Waterborne Automobile Coating Market | 2026-2036
Waterborne Automobile Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Waterborne Automobile Coating Market Outlook
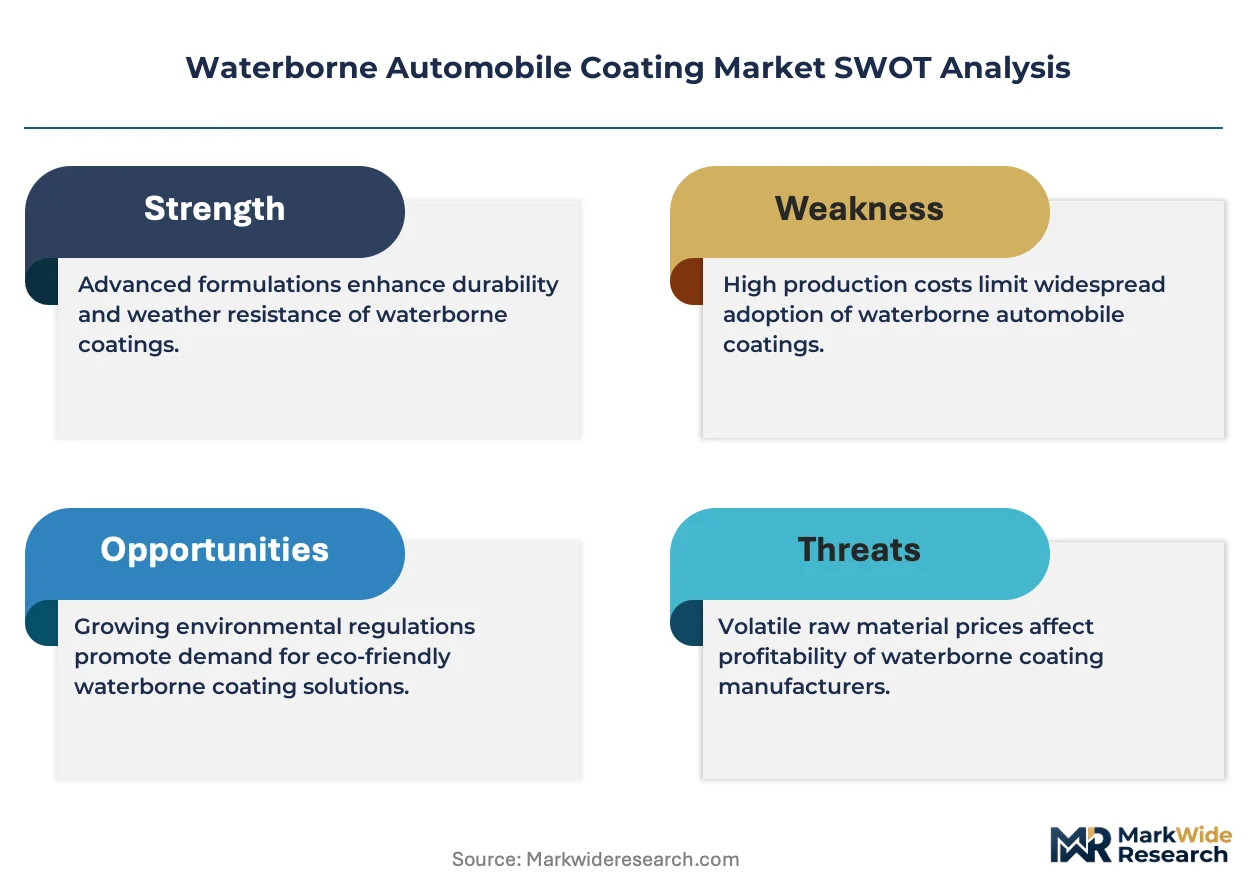
ISO 14001 environmental management certification is bifurcating the supplier base between qualified coating producers and legacy solvent-borne operators. BASF SE leverages its integrated resin-coating platform to control raw material quality and secure OEM supply agreements. PPG Industries Inc. anchors its position through electrostatic application technology leadership in North American assembly plants. Akzo Nobel N.V. differentiates via specialized primer systems that reduce bake-cycle energy consumption for European vehicle manufacturers.
Waterborne automobile coating comprises pigment-dispersed polymer emulsions—typically acrylic, polyurethane, or alkyd resins suspended in water with co-solvent levels below fifteen percent—applied to vehicle bodies for corrosion protection, aesthetic finish, and UV durability. The base coat segment dominates value contribution as color-layer formulations command premium pricing for metallic and pearlescent effects. Clear coat demand accelerates fastest among product types due to scratch-resistant nanocomposite formulations gaining preference in luxury passenger vehicles. Spray application technology leads volume deployment across OEM assembly lines, while electrostatic application captures margin concentration through transfer-efficiency gains exceeding ninety percent in modern facilities.
EPA VOC regulations in the United States, REACH compliance requirements administered by ECHA in Europe, and China's MEE emission standards collectively mandate waterborne system conversion across major automotive manufacturing jurisdictions. These frameworks impose per-liter solvent limits that disqualify conventional solvent-borne coatings from certified supplier status. Stakeholders must monitor regulatory tightening timelines and co-solvent threshold revisions that could trigger accelerated capital expenditure for coating line conversion.
Market Dynamics
OEM coating line conversions are compressing supplier qualification timelines as China's MEE emission standards and EPA VOC rules force simultaneous compliance across multiple manufacturing jurisdictions.
Growth Catalysts
- REACH Compliance Deadlines:European OEMs must complete waterborne system transitions by phased implementation milestones, accelerating coating procurement from certified suppliers.
- Automotive Electrification:Battery electric vehicle manufacturers favor waterborne chemistries for their lower bake temperatures, reducing energy intensity in new assembly plants.
- Yangtze River Delta Concentration:China's dominant automotive production cluster generates concentrated demand pull as domestic vehicle output expands.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic and polyurethane resin prices fluctuate with crude oil derivatives, compressing formulation margins unpredictably.
- Specialty Additive Supply Concentration:Rheology modifiers and UV stabilizers depend on limited German and Japanese chemical suppliers.
- Humidity-Sensitive Application Windows:Waterborne systems require controlled booth conditions between fifteen and twenty-five degrees Celsius, restricting deployment in uncontrolled environments.
Strategic Opportunities
- Indian PLI Scheme Alignment:Production-linked incentives for automotive manufacturing create coating demand in emerging domestic assembly capacity.
- Self-Healing Clear Coat Convergence:Nanocomposite and microcapsule technologies combine to enable scratch-recovery functionality in premium vehicle segments.
- Direct-to-OEM Digital Procurement:Platform-based coating specification and ordering bypass traditional distributor markups in North American supply chains.
Industry Challenges
- Electrostatic Application Certification:Transfer efficiency optimization requires specialized technician training that outpaces vocational program output.
- Legacy Solvent-Borne Line Retrofit:Existing spray booth ventilation and curing oven configurations demand capital-intensive reengineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterborne Automobile Coating Market |
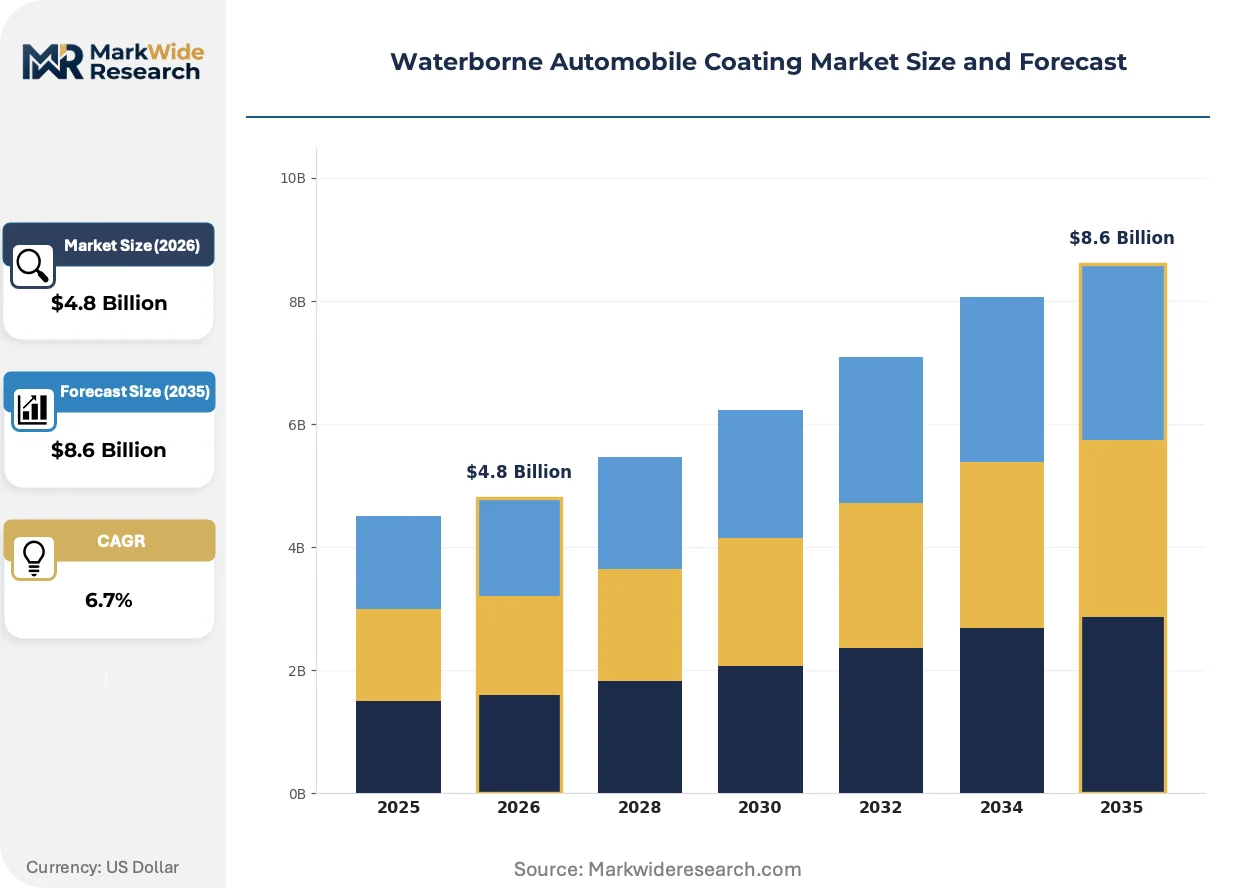
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Coat, Clear Coat, Primer, Top Coat Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Vehicles Technology: Spray Application, Roller Application, Brush Application, Electrostatic Application End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops |
| Companies Covered | Akzo Nobel N.V., BASF SE, Axalta Coating Systems, PPG Industries Inc., Sherwin-Williams Company, Nippon Paint Holdings Co. Ltd., Asian Paints Limited, RPM International Inc., Kansai Paint Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterborne Automobile Coating Market Strategic Shifts
Coating formulation science is pivoting toward functional performance layers that merge protection with sensory and interactive properties, redefining value propositions beyond basic corrosion resistance.
Nanoceramic additive packages are miniaturizing protective particle sizes to sub-fifty nanometer scales, enabling transparent UV barriers without optical haze. Luxury German OEMs specify these formulations for panoramic roof modules and exposed carbon fiber panels. The technology is miniaturizing traditional multilayer coating stacks into single-application systems, compressing booth cycle times and capital footprint per vehicle.
China's MEE emission standards are tightening co-solvent thresholds below ten percent by volume, disqualifying transitional waterborne formulations from new facility approvals. Domestic coating producers are reformulating acrylic-urethane hybrids to meet these limits ahead of enforcement deadlines. The passenger vehicle OEM segment faces the steepest compliance curve as existing plants retrofit spray application infrastructure.
Fleet operators and mobility service providers now specify coating durability warranties as standalone procurement criteria, decoupling finish quality from vehicle purchase negotiations. Tier-one suppliers to ride-hailing platforms in Southeast Asia demand extended chip-resistance guarantees that exceed traditional OEM terms. This specification elevation is most pronounced in Singapore and Thailand where fleet utilization rates accelerate wear exposure.
Waterborne Automobile Coating Market Segmentation
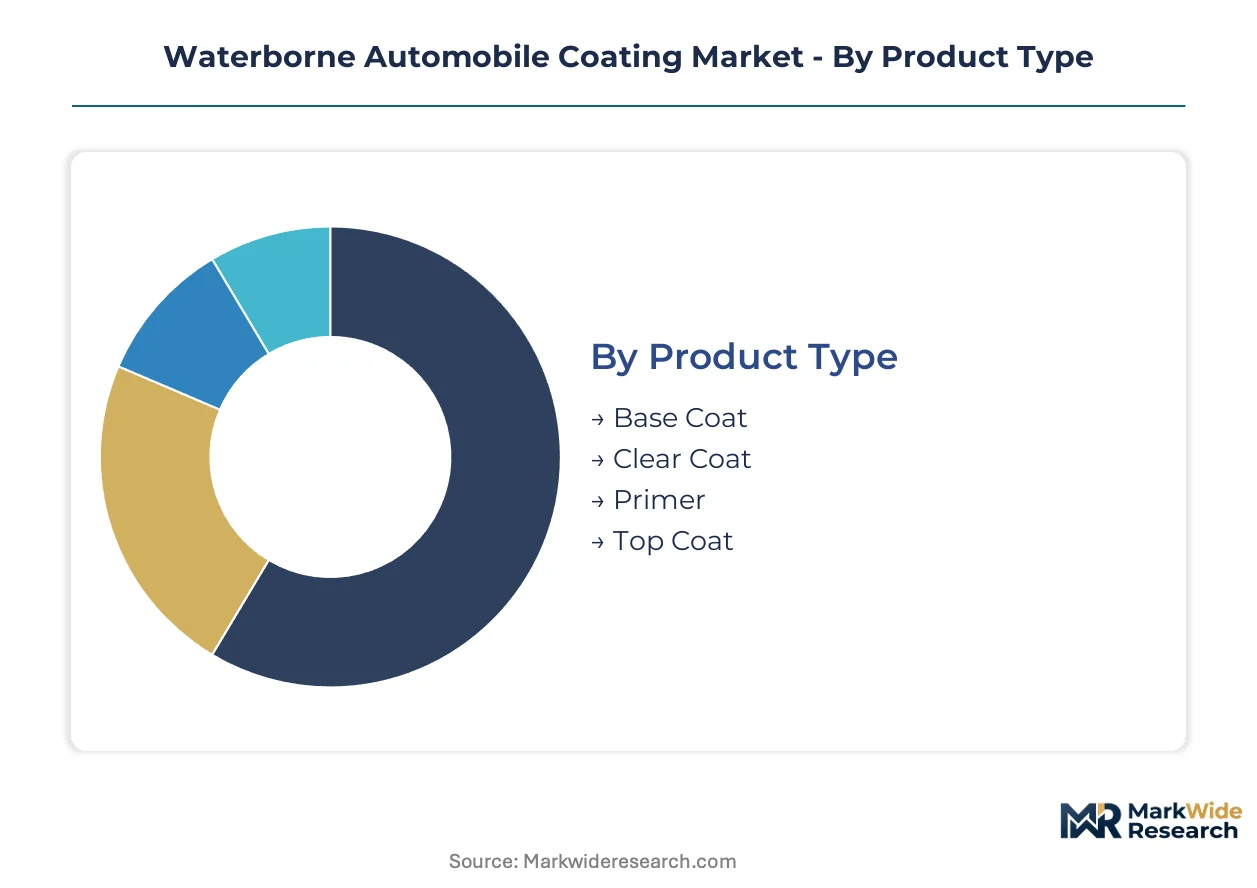
Waterborne automobile coating procurement patterns diverge sharply across product hierarchies and application contexts. OEM qualification protocols and aftermarket service economics create distinct margin architectures that suppliers must navigate simultaneously.
Product Type:
Margin pools concentrate in color-layer formulations where metallic and pearlescent effects command technical premiums over functional protective layers.
- Base Coat:Pigment-dispersed polymer emulsions deliver color saturation and optical depth through controlled flake orientation. Demand clusters in German and Chinese luxury passenger vehicle programs where multi-layer metallic finishes differentiate brand identity. The segment absorbs formulation R&D investment through OEM specification lock-in.
- Clear Coat:Scratch-resistant nanocomposite formulations provide UV durability and gloss retention for exposed vehicle surfaces. Luxury OEMs in North America and Europe specify these systems for extended warranty compliance. Bake-cycle energy reduction drives technology substitution in battery electric vehicle assembly plants.
- Primer:Corrosion-inhibiting resin systems establish adhesion between substrate and color layers.
- Top Coat:Final protective films integrate aesthetic and functional properties in simplified layer architectures.
Base Coat holds installed capacity. Clear Coat is rotating up the share rankings.
Application:
Volume concentration tracks vehicle production geography while margin capture depends on coating complexity and regulatory exposure.
- Passenger Vehicles:Multi-layer coating stacks with base-clear-primer sequences dominate value consumption. China's Yangtze River Delta automotive cluster generates concentrated demand pull as domestic output expands. MEE emission standards force waterborne system conversion across existing and greenfield facilities.
- Commercial Vehicles:Simplified coating protocols prioritize durability over aesthetic complexity in fleet procurement. Heavy truck manufacturers in the US and Europe specify high-build primer systems for chassis corrosion protection. Total cost of ownership calculations dominate supplier selection criteria.
- Two-Wheelers:Cost-optimized waterborne formulations address high-volume emerging market production.
- Heavy-Duty Vehicles:Extreme-duty corrosion resistance requirements drive specialized primer consumption.
Passenger Vehicles maintains volume leadership. Commercial Vehicles is climbing the fastest in value contribution.
Technology:
Application method selection determines transfer efficiency, booth cycle time, and capital intensity per unit output.
- Electrostatic Application:Charged particle deposition achieves transfer efficiency exceeding ninety percent in modern OEM facilities. North American and European assembly plants specify this technology for environmental compliance and material cost control. Technician certification requirements create supplier differentiation through training program depth.
- Spray Application:Conventional atomized delivery remains dominant in volume terms across global assembly lines. China's domestic OEMs deploy this technology in high-volume plants with controlled booth humidity between fifteen and twenty-five degrees Celsius. Capital retrofit requirements constrain conversion timelines.
- Roller Application:Continuous film deposition suits flat panel substrates in commercial vehicle manufacturing.
- Brush Application:Manual touch-up and repair operations in aftermarket service environments.
Electrostatic Application commands technology premiums. Spray Application retains volume dominance.
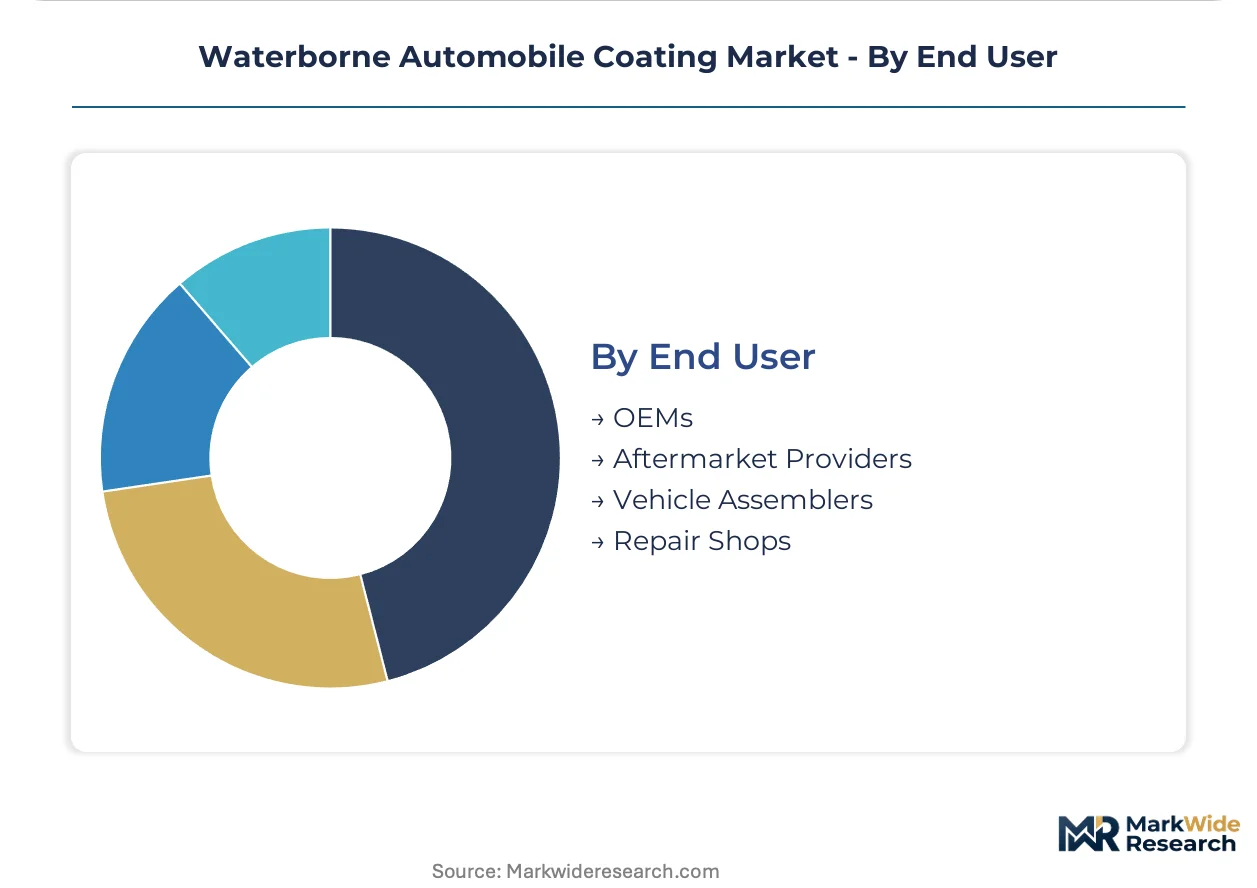
End User:
Procurement economics bifurcate between specification-driven OEM programs and price-sensitive aftermarket service operations.
- OEMs:Original equipment manufacturers impose qualification protocols that lock in certified suppliers for multi-year model cycles. European REACH compliance deadlines and China's MEE standards force simultaneous waterborne system transitions. Formulation approval timelines compress as regulatory enforcement dates approach.
- Aftermarket Providers:Collision repair and refinishing operations prioritize color match accuracy and application speed over bake-cycle optimization. North American distributor networks face disintermediation pressure from direct-to-OEM digital procurement platforms. Warranty specification elevation by fleet operators drives quality tiering.
- Vehicle Assemblers:Contract manufacturing operations serving multiple OEM brands with flexible coating specifications.
- Repair Shops:Independent service facilities with localized supplier relationships and inventory constraints.
OEMs anchor formulation development investment. Aftermarket Providers is gaining share fastest through fleet specification elevation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan Deep Water Port underwrites China's dominance in waterborne coating logistics, handling resin feedstock imports that supply the Yangtze River Delta automotive cluster. This maritime infrastructure connects German chemical exporters to Asian OEM assembly lines.
China
Domestic vehicle production in the Yangtze River Delta generates concentrated coating consumption as BYD and SAIC expand assembly capacity. The MEE emission standards mandate co-solvent thresholds below ten percent, forcing reformulation of acrylic-urethane hybrids. Shanghai Pudong and Jiangsu province host the densest coating application facility networks.
Germany
Luxury OEM specification of nanoceramic clear coats drives premium formulation demand from BMW and Mercedes-Benz programs. REACH compliance deadlines administered by ECHA accelerate waterborne system transitions across supplier tiers. Bavaria and Baden-Württemberg concentrate electrostatic application technology deployment.
United States
EPA VOC regulations impose per-liter solvent limits that disqualify solvent-borne coatings from certified supplier status. Detroit Three automakers retrofit existing assembly plants for waterborne compliance. Michigan and Ohio anchor North American coating consumption volume.
Japan
Automotive electrification favors waterborne chemistries for battery electric vehicle assembly plants requiring lower bake temperatures. METI industrial policy supports coating technology exports to Southeast Asian manufacturing investments. Toyota City and Nagoya manufacturing corridors concentrate domestic demand.
India
Production-linked incentive schemes for automotive manufacturing create coating demand in emerging domestic assembly capacity. Maruti Suzuki and Hyundai Motor India expand waterborne line conversions at Manesar and Chennai facilities. Gujarat and Tamil Nadu host the fastest-growing coating application infrastructure.
Waterborne Automobile Coating Market Competitive Environment
Listed leaders compete with private specialists across integrated resin-coating platforms versus application-technology niches. The supplier base consolidates around three tiers: multinational chemical conglomerates with captive resin production, regional coating specialists with OEM qualification depth, and application-technology vendors with electrostatic system expertise. Dominant competitive moves include backward integration into resin manufacturing and geographic expansion through qualification protocol replication.
Within the multinational chemical tier, BASF SE and PPG Industries Inc. exemplify integrated platform strategies that control raw material quality through upstream resin operations. Akzo Nobel N.V. occupies a differentiated position through specialized primer system expertise. These three companies anchor the competitive structure by representing distinct archetypes: resin-coating integration, application technology leadership, and energy-efficient formulation specialization.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| BASF SE |
| Axalta Coating Systems |
| PPG Industries Inc. |
| Sherwin-Williams Company |
| Nippon Paint Holdings Co. Ltd. |
| Asian Paints Limited |
| RPM International Inc. |
| Kansai Paint Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Acrylic-urethane hybrid reformulation for sub-ten-percent co-solvent compliance is displacing legacy waterborne formulations across China's Yangtze River Delta, simultaneously concentrating procurement power among MEE-certified domestic producers and compressing margins for transitional suppliers caught between specification tiers.
Pricing Analysis
Certification level creates the primary spread between qualified coating producers and legacy solvent-borne operators, with ISO 14001 environmental management tiers commanding formulation premiums. Three-tier pricing structure across OEM-specified, distributor-channel, and fleet-direct procurement levels reflects transfer efficiency gains and bake-cycle energy specifications. Cost compression in standard-grade base coats is intensifying because domestic Chinese producers are scaling acrylic resin captive production. Fleet operators exhibit the highest price sensitivity due to total cost of ownership calculations, while luxury German OEMs show minimal elasticity for nanoceramic clear coat warranties.
Supply Chain Analysis
Just-in-time resin feedstock delivery dominates OEM assembly line economics, though strategic stockpiling of rheology modifiers and UV stabilizers persists due to German and Japanese supplier concentration. Manufacturing capacity concentrates in China, Germany, and the United States, with the Shanghai Yangshan Deep Water Port anchoring Asia-Pacific logistics. Raw material dependencies center on petrochemical-derived acrylic resins, polyurethane precursors, and nanoceramic additive packages. Single-source vulnerability in specialty additive supply creates structural risk for formulation continuity. Distribution runs through certified supplier-direct channels for OEM programs and fragmented distributor networks for aftermarket collision repair.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as battery electric vehicle assembly plant construction accelerates waterborne chemistry adoption for lower bake temperature requirements.
For Market Incumbents: Consolidate backward integration into resin manufacturing to offset petrochemical feedstock volatility and secure raw material quality control against emerging domestic Chinese competitors. Expand electrostatic application certification programs to capture technician training premiums and lock in North American OEM supply agreements. Priority investment in nanoceramic clear coat R&D addresses luxury segment warranty specification elevation. For New Entrants and Emerging Players: MEE fast-track certification for sub-ten-percent co-solvent formulations opens immediate access to China's Yangtze River Delta greenfield facility approvals. Target India's PLI-aligned automotive assembly capacity as the most penetrable geography, where production-linked incentive schemes create coating demand without entrenched supplier relationships. Go-to-market through direct digital procurement platforms bypasses traditional distributor markups in North American supply chains. For Investors and Strategic Acquirers: The market sits at a regulatory enforcement phase that favors integrated resin-coating platforms over application-technology specialists. Long-term viability over the next decade rests on captive raw material production and multi-jurisdiction qualification depth. Acquisition target archetype: regional coating specialists with OEM qualification protocols replicable across China's MEE compliance deadlines and Europe's REACH implementation milestones. Watch for co-solvent threshold revision announcements as the signal triggering accelerated capital expenditure for coating line conversion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | BASF SE's captive acrylic production secures raw material quality and formulation consistency for OEM specifications. |
| Electrostatic Application Technology Deployment | PPG Industries Inc. achieves transfer efficiency exceeding ninety percent in modern North American assembly facilities. |
| Nanoceramic Clear Coat Formulation Development | Luxury German OEMs specify sub-fifty nanometer UV barriers for panoramic roof modules and carbon fiber panels. |
| MEE Compliance Fast-Track Certification | Domestic Chinese producers reformulate ahead of co-solvent threshold enforcement to capture greenfield facility approvals. |
| Direct-to-OEM Digital Procurement Platform Launch | Platform-based coating specification bypasses traditional distributor markups in North American aftermarket supply chains. |
Study Parameters
Desk research of customs trade data, chemical industry association reports, and regulatory filing databases preceded structured interviews with OEM coating procurement managers, Tier 1 supplier technical directors, electrostatic application equipment specialists, and aftermarket distributor network heads. Primary fieldwork across China's Yangtze River Delta, Germany's Bavaria and Baden-Württemberg corridors, and Michigan-Ohio manufacturing belts validated secondary estimates. Bottom-up vehicle production volume modeling and top-down coating consumption intensity metrics were triangulated against MEE and REACH compliance timeline assumptions.
Variance decomposition across product type, application, technology, and end-user segments drove forecast construction throughout the projection horizon. Analytical framework incorporated vehicle class stratification, propulsion architecture differentiation, content per vehicle coefficients, and regional production cluster dynamics. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs included OEM coating line conversion capital expenditure schedules and battery electric vehicle assembly plant commissioning timelines.
Decision-makers should treat outputs as directional under sustained regulatory enforcement timelines and petrochemical feedstock price stability assumptions; material deviation would warrant model refresh. Revision becomes warranted when co-solvent threshold revisions or electrostatic application certification backlogs cross operational disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Automotive Conformal Coatings Market
Coatings
Global Floor Coatings Market
Coatings
Rail Coatings Market
Coatings
Paper Coating Binders Market
Coatings
Coating Pigments Market
Coatings
Europe Coil Coatings Market
Coatings
Coatings Raw Materials Market
Coatings
South Korea Protective Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
Self-Healing Coatings Market
Coatings
Protective Coatings Market
Coatings
Topcoat Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Protective and Marine Coatings Market
Coatings
Radiation Curable Coatings Market
Coatings
PACVD-Based Coatings Market