
 Saudi Arabia Floor Coatings Market | 2026-2036
Saudi Arabia Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Floor Coatings Market Outlook
Modular coating system bundling is recalibrating buyer choice across Saudi Arabia's floor coatings market, as construction firms increasingly specify integrated primer-body-topcoat packages rather than standalone products. Sika AG leverages its Riyadh technical center to sustain specification relationships with major contractors. National Paints Factories Co. Ltd. anchors its position through domestic manufacturing scale and rapid delivery to Jeddah and Dammam project sites. Jazeera Paints competes on brand strength and channel control through its extensive Saudi distribution network.
Floor coatings are protective resinous systems applied to concrete substrates, typically formulated with epoxy, polyurethane, or acrylic polymers at film builds of 0.5–5 mm to resist abrasion, chemical attack, and moisture ingress in commercial and industrial environments. Epoxy coatings dominate volume in Saudi Arabia due to their hardness and chemical resistance for petrochemical and warehouse floors, while polyurethane coatings command premium positioning in areas requiring thermal cycling tolerance and UV stability. Water-based technology is gaining share as contractors navigate stricter VOC enforcement on project sites, though solvent-based systems retain footholds in heavy-duty industrial applications where rapid cure and solvent resistance remain critical.
The Saudi Standards, Metrology and Quality Organization (SASO) and the Saudi Food and Drug Authority (SFDA) regulate chemical composition and environmental release profiles for construction coatings, while the Saudi Building Code mandates slip resistance and fire performance ratings for commercial flooring installations. These frameworks push manufacturers toward reformulated low-VOC products and certified testing documentation to maintain market access. Stakeholders must monitor evolving SASO technical regulations and megaproject procurement shifts toward sustainability-linked specifications to align product development with buyer requirements.
Market Dynamics
Modular coating system bundling is compressing specification autonomy across Saudi Arabia's floor coatings market, as construction firms consolidate procurement around integrated primer-body-topcoat packages rather than component-level sourcing.
Growth Catalysts
- SFDA VOC enforcement:Tightening chemical safety protocols on solvent-based formulations are accelerating contractor migration toward water-based epoxy and polyurethane systems in Riyadh megaproject corridors.
- Petrochemical plant maintenance cycles:Eastern Province refineries and chemical processing facilities are driving specification upgrades for chemical-resistant floor systems during scheduled turnaround windows.
- Logistics hub construction:Saudi Arabia's warehouse and distribution center buildout is concentrating demand for abrasion-resistant coatings in Jeddah and Dammam industrial zones.
Market Restraints
- Raw material concentration:Epoxy resin supply dependence on Asian petrochemical feedstock exposes Saudi applicators to freight cost volatility and import duty fluctuations.
- Technical performance gaps:Water-based formulations still lag solvent systems in rapid cure speed and solvent resistance for heavy-duty chemical containment areas.
- Regulatory documentation burden:SASO certification requirements for low-VOC product lines extend manufacturer approval timelines and compress working capital cycles.
Strategic Opportunities
- Neom and Red Sea Project corridors:Northern Saudi megaproject zones remain undersupplied with certified coating applicators, creating first-mover specification advantages for trained contractors.
- Saudi Building Code alignment:Fire performance and slip resistance mandates are opening premium positioning for certified intumescent and textured coating systems in commercial flooring.
- UV-stable polyurethane convergence:Hybrid epoxy-polyurethane formulations are capturing outdoor industrial applications previously lost to concrete sealers and tile systems.
Industry Challenges
- Applicator certification gaps:Shortage of SASO-certified coating technicians delays project mobilization and quality assurance documentation in remote Eastern Province sites.
- Moisture tolerance testing:Concrete substrate vapor emission assessment requires specialized equipment that smaller Saudi contractors struggle to finance, limiting bid participation on high-specification jobs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Floor Coatings Market |
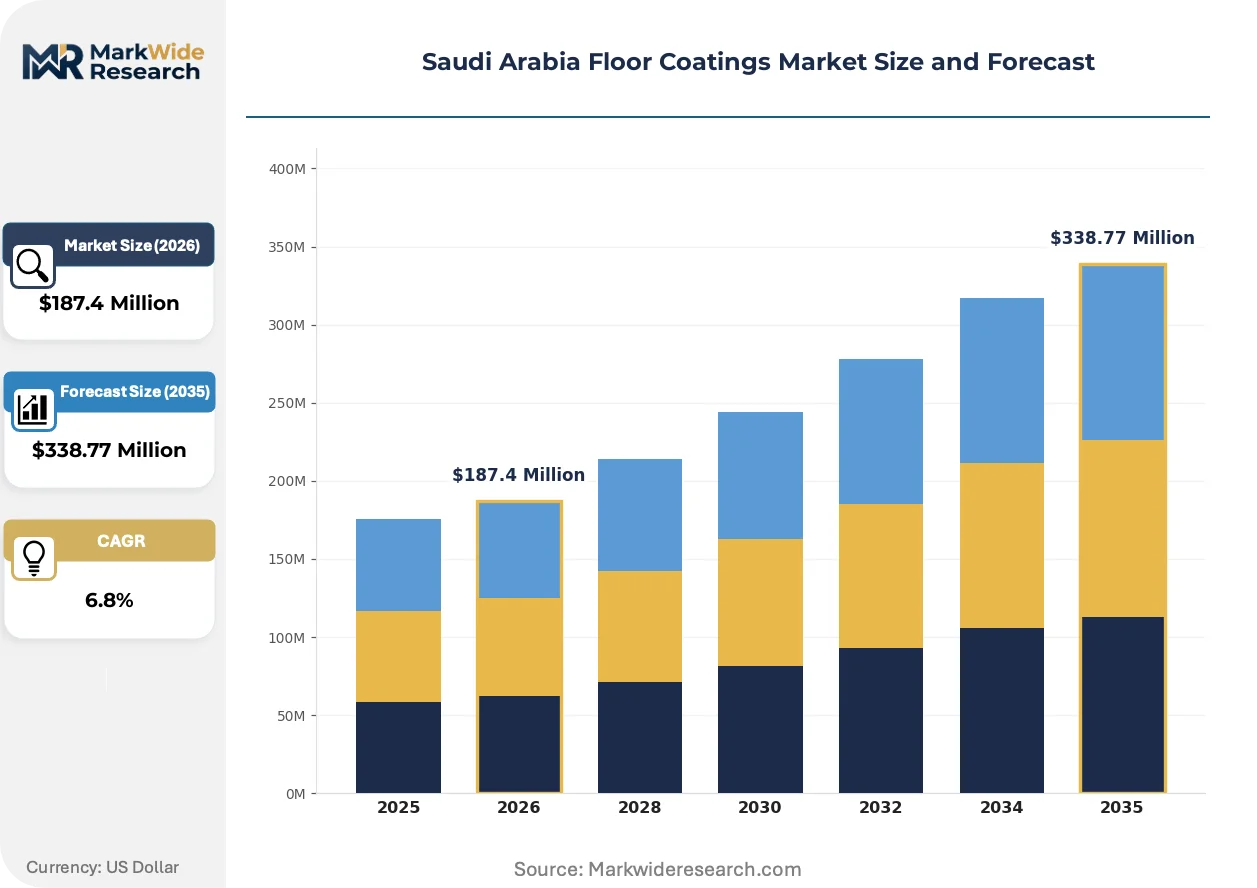
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Coatings, Polyurethane Coatings, Acrylic Coatings, Vinyl Coatings Application: Commercial Buildings, Industrial Facilities, Residential Spaces, Institutional Areas Technology: Water-Based, Solvent-Based, UV-Cured, Electrostatic End User: Construction Firms, Property Developers, DIY Consumers, Maintenance Service Providers |
| Companies Covered | National Paints Factories Co. Ltd., Sika AG, Akzo Nobel N.V., Hempel A/S, The Sherwin-Williams Company, Jotun, Jazeera Paints, Berger Paints India Limited, Kansai Paint Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Floor Coatings Market Strategic Shifts
Water-based epoxy technology is absorbing specification share from solvent systems as Saudi contractors navigate stricter site-level VOC monitoring and megaproject sustainability procurement requirements.
Water-based epoxy formulations are absorbing market position in medium-duty industrial applications where contractors previously defaulted to solvent systems. Eastern Province petrochemical maintenance teams are specifying these systems at expanding rates for warehouse and administrative areas. This absorption is compressing the addressable market for high-VOC solvent epoxies outside chemical containment zones where rapid cure remains non-negotiable.
SASO technical regulations on construction coating emissions are forcing manufacturer reformulation investments and third-party testing documentation. Industrial facilities in Riyadh and Jeddah now require certified low-VOC product data sheets as standard bid submission elements. Coating suppliers are responding by pre-certifying entire product portfolios rather than maintaining parallel solvent and water-based stockkeeping units.
Integrated system procurement is displacing component-level purchasing as Saudi construction firms consolidate vendor relationships around single-source coating packages. Major contractors in Dammam and Riyadh are negotiating annual framework agreements with technical service support included. This consolidation favors suppliers with domestic blending capacity and rapid-turn specification assistance over import-dependent distributors.
Saudi Arabia Floor Coatings Market Segmentation
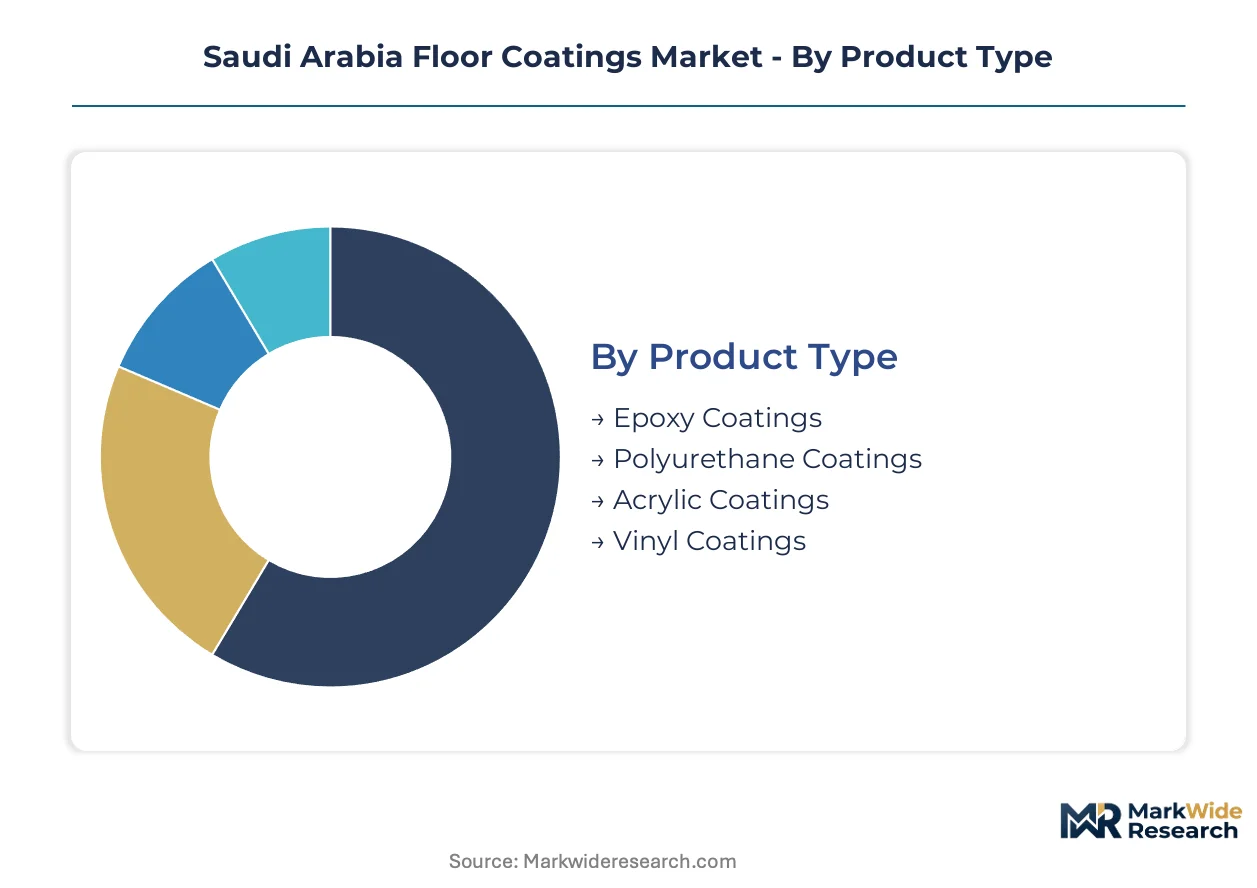
Specification patterns in Saudi Arabia's floor coatings market diverge sharply across product chemistry, installation setting, and contractor capability. Segmentation clarity enables suppliers to align formulation investments with the upgrade cycles and compliance pressures reshaping procurement decisions.
Product Type:
Upgrade cycles for industrial flooring in Eastern Province petrochemical facilities and Riyadh logistics hubs are driving differentiated specification behavior across resin chemistries.
- Epoxy Coatings:Thermosetting polymer systems formulated with bisphenol-A or bisphenol-F resins deliver film builds of 2–5 mm with exceptional chemical resistance and compressive strength. Demand concentrates in Jubail Industrial City and Yanbu refinery maintenance corridors where solvent-resistant containment areas require rapid-return-to-service specifications.
- Polyurethane Coatings:Aliphatic and aromatic isocyanate-cured systems provide elastomeric properties and UV stability for thermal cycling environments. Jeddah commercial developments and outdoor industrial applications in the Red Sea Project zone specify these systems where concrete expansion joints and sun exposure challenge rigid epoxy alternatives.
- Acrylic Coatings:Thermoplastic emulsion systems offering moderate abrasion resistance and rapid drying for light-duty commercial environments.
- Vinyl Coatings:PVC-based formulations providing seamless hygienic surfaces for healthcare and food processing institutional settings.
Volume placements concentrate in Epoxy Coatings; the faster expansion belongs to Polyurethane Coatings.
Application:
Cost tier differentiation separates specification requirements across Saudi Arabia's built environment, with compliance burdens and performance expectations scaling with facility complexity.
- Industrial Facilities:Heavy-duty resinous systems specified for chemical processing plants, warehouses, and manufacturing floors requiring impact resistance and containment integrity. Eastern Province turnaround maintenance windows drive concentrated procurement for chemical-resistant epoxies.
- Commercial Buildings:Medium-duty coatings for retail, office, and hospitality spaces where aesthetic finish and slip resistance dominate specification criteria. Riyadh megaproject retail components specify certified low-VOC systems under Saudi Building Code enforcement.
- Residential Spaces:Decorative and protective coatings for villas and apartment complexes, typically water-based acrylic or thin-film epoxy systems applied by smaller contractors.
- Institutional Areas:Hygienic and safety-rated flooring for hospitals, schools, and government facilities requiring fire performance certification and antimicrobial additives.
Industrial Facilities command the largest project values; Commercial Buildings show the steepest specification upgrade trajectory.
Technology:
Application method and cure chemistry determine contractor qualification requirements and project mobilization timelines across Saudi construction sites.
- Water-Based:Aqueous emulsion systems with VOC content below SASO regulatory thresholds, gaining share in Riyadh and Jeddah megaprojects where site-level emissions monitoring has tightened. Contractors favor these for occupied building renovations with ventilation constraints.
- Solvent-Based:High-solids formulations delivering rapid cure and superior solvent resistance for chemical containment areas in petrochemical facilities where water-based alternatives fail performance specifications.
- UV-Cured:Photoinitiator-activated systems enabling instant cure under ultraviolet lamps for high-throughput production environments.
- Electrostatic:Charged particle application methods for conductive flooring in electronics manufacturing and explosive atmosphere zones.
Water-Based systems are gaining specification share fastest; Solvent-Based retains critical footholds in chemical containment applications.
End User:
Customer type determines procurement scale, technical service requirements, and certification documentation burdens for Saudi coating suppliers.
- Construction Firms:Large contractors executing megaproject work packages specify integrated coating systems with framework agreements covering primer-body-topcoat combinations and applicator training support.
- Property Developers:Mixed-use and industrial project sponsors negotiating bulk procurement for multi-phase developments, increasingly requiring sustainability-linked product data and SASO certification documentation.
- DIY Consumers:Small-volume purchasers of retail-packaged coatings for residential garage and patio applications, price-sensitive and specification-light.
- Maintenance Service Providers:Specialized contractors bidding turnaround and refurbishment work for existing industrial facilities, requiring moisture tolerance testing capability and rapid mobilization.
Construction Firms dominate premium system procurement; Maintenance Service Providers represent the most fragmented and certification-challenged segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production capacity concentrates in Jeddah and Dammam industrial corridors, while consumption spreads across megaproject zones in Riyadh, the Eastern Province, and emerging northern developments. This geographic mismatch shapes logistics costs and specification relationships across the Kingdom.
Riyadh
Central Saudi Arabia's construction epicenter drives premium coating specifications for commercial towers, retail complexes, and logistics facilities. The Saudi Building Code enforcement tightens fire performance and slip resistance mandates on all new commercial flooring installations. Diriyah Gate and King Abdullah Financial District projects concentrate demand for certified low-VOC epoxy and polyurethane systems.
Eastern Province
Jubail Industrial City and Yanbu refinery corridors anchor heavy-duty industrial demand for chemical-resistant epoxy containment systems. Petrochemical maintenance turnaround cycles generate concentrated procurement windows for solvent-resistant formulations. Ras Tanura and Jubail manufacturing clusters specify rapid-cure systems during scheduled plant shutdowns.
Western Region
Jeddah commercial and residential developments prioritize aesthetic finish coatings for mixed-use towers and hospitality projects. Red Sea Project coastal installations drive UV-stable polyurethane specifications for outdoor industrial applications. King Abdullah Economic City logistics zones concentrate medium-duty warehouse flooring demand.
NEOM Northwest
The northern megaproject corridor remains undersupplied with certified coating applicators and SASO-compliant product distribution. Linear city and coastal tourism components specify sustainability-linked procurement requirements for low-emission systems. Oxagon industrial zone planning anticipates future resinous flooring demand for manufacturing and logistics tenants.
Saudi Arabia Floor Coatings Market Competitive Environment
The competitive structure tilts toward domestic manufacturing specialists with rapid-turn logistics capabilities. Sika AG and multinational chemical conglomerates occupy specification-intensive segments requiring technical service support. National Paints Factories Co. Ltd. and Jazeera Paints anchor volume positions through distribution density. Two dominant competitive moves define current positioning: domestic blending capacity expansion to compress delivery timelines, and framework agreement consolidation with major construction firms.
Within the domestic manufacturing tier, National Paints Factories Co. Ltd. and Jazeera Paints exemplify scale-driven positioning through Jeddah and Dammam production footprints. Among multinational specialists, Sika AG occupies a specification-relationship position leveraging its Riyadh technical center. Akzo Nobel N.V. and Hempel A/S represent additional European-origin coating conglomerates competing on certified product portfolios. The Sherwin-Williams Company and Jotun anchor North American and Scandinavian competitive vectors respectively. Kansai Paint Co., Ltd. and Berger Paints India Limited represent Asia-Pacific-origin participants with regional export positioning into Saudi project corridors.
| Leading Market Players |
|---|
| National Paints Factories Co. Ltd. |
| Sika AG |
| Akzo Nobel N.V. |
| Hempel A/S |
| The Sherwin-Williams Company |
| Jotun |
| Jazeera Paints |
| Berger Paints India Limited |
| Kansai Paint Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Bisphenol-A resin price indices from Asian petrochemical markets cascade through Saudi Arabia's floor coatings supply chain, compressing margin structures for import-dependent distributors while concentrating pricing power among domestic blenders with captive raw material storage.
Pricing Analysis
Cost-down pressure on water-based epoxy tiers accelerates because SASO certification investments inflate manufacturer fixed costs. Three-tier pricing structure across premium certified, standard compliant, and economy solvent-based levels separates specification-grade systems from commodity offerings. Brand premium and certification grade drive price differentiation, with multinational technical service packages commanding substantial uplifts over domestic equivalents. DIY residential segments exhibit highest price sensitivity, while petrochemical maintenance contractors prioritize performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Jeddah and Dammam anchor hub-and-spoke patterns serving Riyadh megaproject corridors and Eastern Province industrial zones. Epoxy resin feedstock draws from South Korea, China, and Singapore, while isocyanate precursors for polyurethane systems rest on German and Japanese chemical exports. Single-source vulnerability concentrates in specialty amine hardeners from limited Asian suppliers. Distribution runs through domestic manufacturing specialists with rapid-turn blending capacity rather than import-only distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's floor coatings market operates under applicator certification bottlenecks that constrain qualified installation capacity, propping pricing power for certified contractors and their preferred supplier partners.
For Market Incumbents: Anchor specification relationships through expanded Riyadh technical center capacity and SASO pre-certification of complete product portfolios. Water-based formulation gaps against solvent systems threaten premium positioning in chemical containment applications. Backward integration into regional amine hardener sourcing mitigates single-supplier exposure.
For New Entrants and Emerging Players: Maintenance service providers represent the most penetrable channel partner type, given their certification challenges and moisture tolerance testing equipment gaps. Neom and Red Sea Project corridors offer white-space entry points with undersupplied certified applicator networks. Framework agreement bundling with technical training support accelerates contractor adoption.
For Investors and Strategic Acquirers: The window for entry favors domestic manufacturing specialists with Jeddah or Dammam production footprints and established distributor relationships. Mid-term viability hinges on low-VOC regulatory alignment and megaproject sustainability procurement adoption. Watch for SFDA enforcement intensity shifts as inflection indicator for water-based technology penetration rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Hardener Sourcing | Captive supply of critical curing agents reduces exposure to Asian petrochemical export volatility. |
| SASO Pre-Certification Investment | Accelerated product approval timelines compress working capital cycles for low-VOC portfolio launches. |
| Technical Training Center Expansion | Certified applicator pipelines secure specification preference from major Dammam and Riyadh contractors. |
| Framework Agreement Consolidation | Annual procurement contracts with construction firms lock in volume commitments and reduce bid-cycle costs. |
| Hybrid Epoxy-Polyurethane Formulation Development | UV-stable systems capture outdoor industrial applications previously served by concrete sealers. |
Study Parameters
Independent corroboration across coating manufacturer technical directors, construction firm procurement managers, and SASO certification consultants underwrites the qualitative findings. Primary fieldwork encompassed plant managers at Jubail Industrial City facilities, distribution channel partners in Jeddah and Dammam, and technical R&D directors at domestic blending operations. Secondary validation drew from Saudi Customs import records, SASO technical regulation filings, and petrochemical maintenance contractor bid documentation. Bottom-up volume estimates triangulated against top-down construction spending allocations.
Comparable-period anchoring calibrated the projection horizon against historical megaproject procurement cycles and petrochemical turnaround maintenance windows. Segmentation modeling spanned resin chemistry, application intensity, technology compliance tier, and end-user procurement scale. CAGRs derived from construction output trajectories and specification upgrade elasticities. Forecast inputs incorporated SFDA enforcement intensity scenarios and Saudi Building Code amendment schedules.
Caveats apply where raw material freight cost spikes or SASO regulatory acceleration could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Spain Automotive OEM Coatings Market
Coatings
Hydrophilic Interior Glass Defogging Coatings Market
Coatings
Water Based Enamel Market
Coatings
Transparent Conductive Coatings Market
Coatings
Marine Nanocoating Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Europe Powder Coatings Market
Coatings
Anti-Corrosion Nanocoatings Market
Coatings
Fire Retardant Coatings Market
Coatings
Polyester Coatings Market
Coatings
Europe Protective Coatings Market
Coatings
Metallic Powder Coating Market
Coatings
Global Flat Glass Coatings Market
Coatings
Color-Shifting Coating Market
Coatings
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market
Coatings
Emulsion Coatings Market