
 Engine Starter Market | 2026-2036
Engine Starter Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Starter Market Insights
Asset-light leasing models for starter-generator systems is reconfiguring competitive entry barriers, allowing smaller suppliers to compete without heavy capital deployment. Robert Bosch GmbH leverages its manufacturing scale across integrated powertrain modules. Denso Corporation anchors its position through captive R&D in permanent magnet technologies. Valeo Group competes via specialized gear reduction architectures for hybrid platforms.
An engine starter is an electromechanical device that converts stored electrical energy into rotational mechanical force to initiate internal combustion engine operation, typically delivering cranking torque between 50 and 250 Nm depending on engine displacement. Its primary purpose is to overcome static friction and compression resistance during cold starts across automotive, marine, and industrial powertrain applications. Electric starters remain the dominant product type, though brushless technology segments are capturing margin pools as thermal durability requirements intensify. Passenger car applications constitute the largest vehicle type segment, while heavy-duty truck demand is shifting toward pneumatic starters for reliability in extreme climate operations.
EPA tailpipe regulations, Euro 7 emission frameworks, and China's MIIT dual carbon goals collectively mandate lower cold-start emissions, directly shaping starter motor efficiency specifications and material substitution toward rare-earth reduced designs. NHTSA safety standards in the United States additionally influence cranking reliability thresholds for commercial vehicle applications. Stakeholders must monitor how evolving ISO starter durability test cycles interact with regional electrification timelines to determine platform investment priorities.
Market Dynamics
Integrated starter-generator architectures are compressing traditional starter motor demand as 48V mild-hybrid systems consolidate cranking and generation functions into single electromagnetic assemblies. This consolidation is redrawing supplier relationships and forcing dedicated starter manufacturers to reposition toward powertrain-integrated offerings or exit.
Growth Catalysts
- Euro 7 cold-start emission limits:Tighter cranking speed tolerances are mandating precision torque delivery, expanding specification upgrades across European OEM platforms.
- Brushless permanent magnet motors:Rare-earth magnet formulations with enhanced thermal cycling resistance are penetrating heavy-duty truck specifications for extreme climate reliability.
- China's MIIT dual carbon goals:Domestic OEM localization mandates are accelerating captive production of high-efficiency starter systems for localized vehicle platforms.
Market Restraints
- Neodymium price volatility:Rare-earth magnet input costs fluctuate with Chinese export quota policies, compressing margin stability for permanent magnet starter producers.
- Supply concentration in wound-field starter manufacturing:Southeast Asian wound copper armature production clusters create single-source vulnerability for conventional starter variants.
- 48V integrated starter-generator substitution:Belt-driven integrated systems eliminate standalone starter demand in mild-hybrid powertrain configurations above 15kW electrical output.
Strategic Opportunities
- India commercial vehicle electrification:BIS efficiency mandates for Bharat Stage VI Phase II are creating specification upgrade cycles for pneumatic-to-electric starter conversions in medium-duty trucks.
- Marine outboard starter motor aftermarket:Salt-water corrosion-resistant sealed housing designs address underpenetrated recreational boating segments in coastal Mediterranean markets.
- IoT-enabled predictive maintenance integration:Sensor-embedded starters transmitting cranking current signatures enable fleet operator service interval optimization through telematics platforms.
Industry Challenges
- Power electronics integration skill gaps:Electromechanical starter engineering teams lack embedded software competency for 48V control algorithm development.
- ISO 16750-3 vibration test cycle compliance:Extended durability certification timelines delay platform approval for new starter variants in commercial vehicle applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Starter Market |
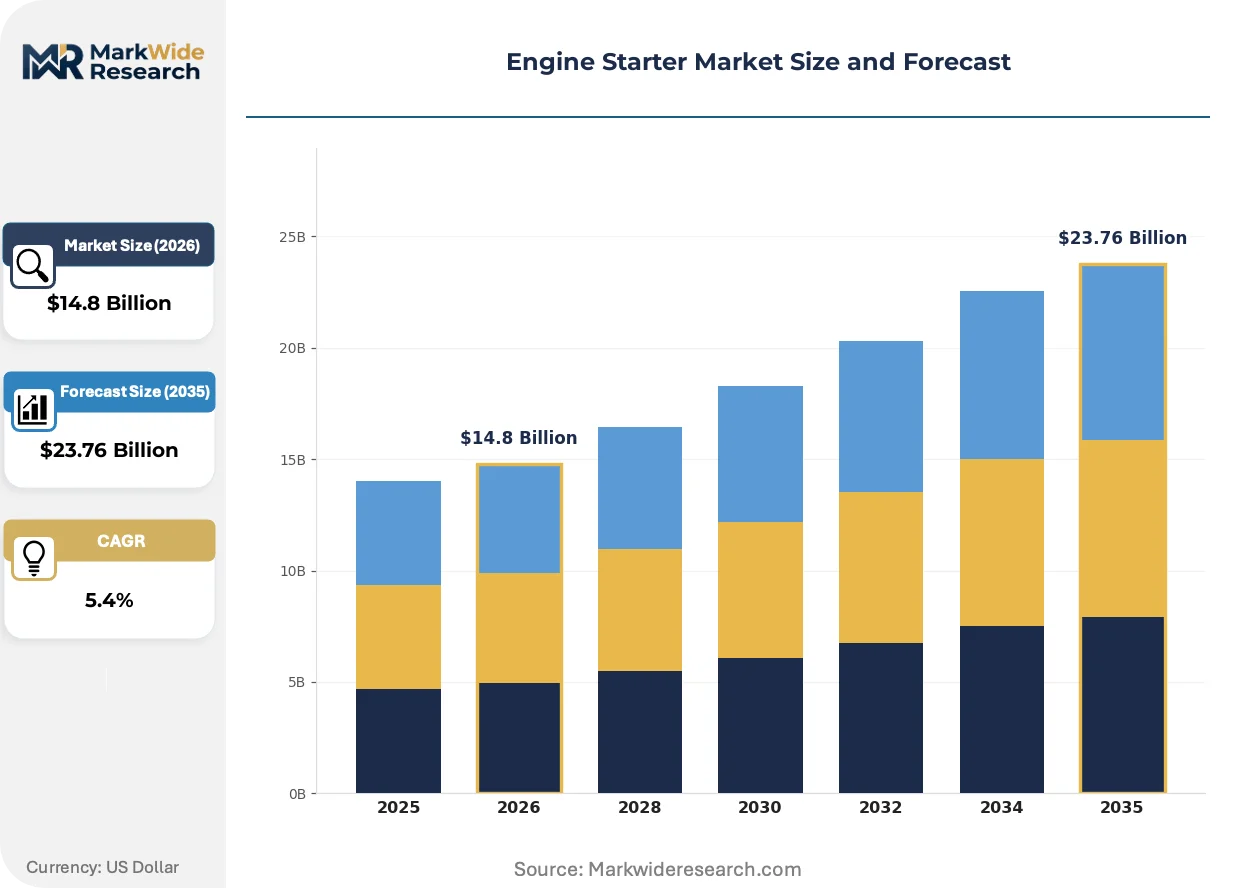
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Starters, Manual Starters, Pneumatic Starters, Hydraulic Starters Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Fuel Type: Gasoline, Diesel, Electric, Hybrid Technology: Brushless, Gear Reduction, Solenoid, Permanent Magnet |
| Companies Covered | Denso Corporation, Robert Bosch GmbH, Valeo Group, BorgWarner Inc., Mitsubishi Electric Corporation, Mitsuba Corporation, Hitachi Astemo Ltd., SEG Automotive, Lucas TVS Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Starter Market Trends and Innovations
Electrification architecture convergence is dissolving traditional boundaries between cranking systems, generation equipment, and torque-assist motors. This boundary dissolution is compressing product category definitions and forcing suppliers to requalify capabilities across integrated powertrain electromechanical domains.
Hairpin-wound stator configurations with rectangular copper conductor geometries are replacing conventional round-wire windings in high-torque density starter motors. European premium OEMs specify hairpin architectures for stop-start system duty cycles exceeding 600,000 events. Conventional random-wound stator production equipment is rendering obsolete across new platform tooling investments.
EPA greenhouse gas emission standards for model year 2027 heavy-duty engines mandate reduced cold-start fuel enrichment, directly tightening cranking torque precision requirements. Engine calibration teams now specify starter motors with closed-loop speed control rather than open-loop voltage application. North American heavy-duty truck powertrain divisions are absorbing these specifications into integrated starter-generator sourcing decisions.
Fleet operators are unbundling starter motor replacement from full powertrain service contracts, creating direct procurement relationships with component suppliers. Independent service channels capture aftermarket volume previously reserved for OEM dealer networks. Brazil's long-haul trucking corridors exhibit this disintermediation most acutely, where third-party logistics providers negotiate direct starter supply agreements with component manufacturers.
Engine Starter Market Segmentation
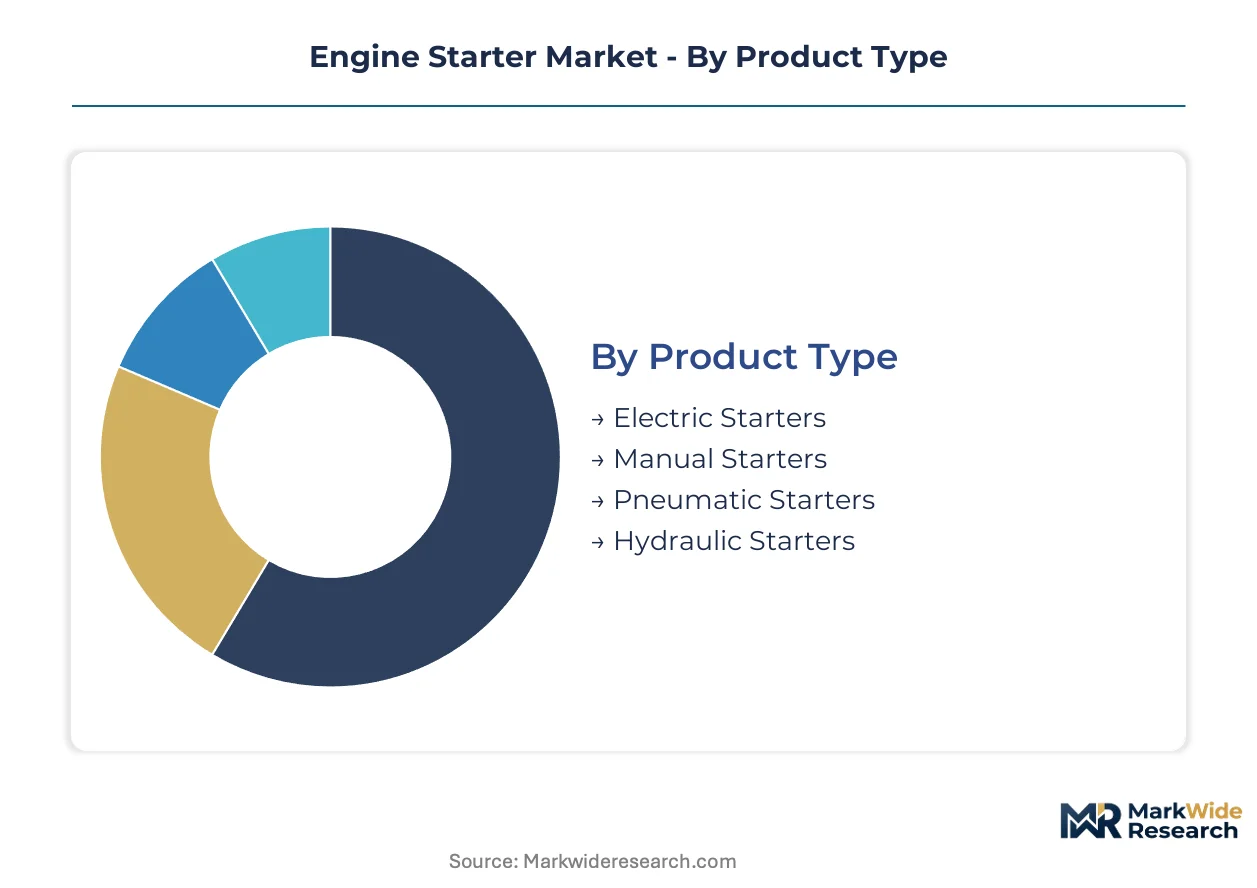
Starter motor replacement cycles and warranty exposure vary dramatically across product architectures, creating divergent service revenue pools and inventory risk profiles for distributors. Understanding these segment-specific aftermarket intensities shapes procurement and platform investment decisions.
Product Type:
Aftermarket service intensity climbs with electromagnetic complexity, driving divergent channel strategies for replacement parts and technical support infrastructure.
- Electric Starters:These electromechanical assemblies convert battery-stored DC power into rotational torque through series-wound or permanent magnet field configurations. Passenger car OEMs in China specify electric starters with enhanced duty cycles for stop-start systems, tightening thermal durability requirements.
- Manual Starters:Mechanical spring-wound or pull-cord mechanisms store human-generated kinetic energy for release into cranking motion. Recreational marine outboard applications in Mediterranean coastal markets sustain residual demand where electrical system weight penalties matter.
- Pneumatic Starters:Compressed air drives turbine or vane motors to achieve high initial torque without electrical current draw. Heavy-duty truck fleet operators in extreme climate zones specify pneumatic systems for cold-weather reliability where battery capacity degrades.
- Hydraulic Starters:Pressurized fluid actuates piston or gear motors through existing machinery hydraulic circuits. Industrial and mining equipment OEMs integrate hydraulic starters where electrical spark hazards preclude conventional electromagnetic solutions.
By volume, Electric Starters leads. By growth pace, Brushless variants within this category are expanding most quickly.
Vehicle Type:
Platform electrification timelines create asynchronous demand curves across vehicle categories, fragmenting supplier planning horizons.
- Passenger Cars:Stop-start system proliferation drives starter duty cycle specifications beyond 600,000 events. European premium OEMs specify hairpin-wound stator architectures for thermal management in dense urban traffic.
- Commercial Vehicles:Medium-duty truck specifications in India face BIS efficiency mandates under Bharat Stage VI Phase II, accelerating pneumatic-to-electric conversion cycles.
- Motorcycles:Compact permanent magnet starter motors integrate with engine casings for weight reduction. Southeast Asian production clusters dominate cost-optimized manufacturing for this segment.
- Heavy-Duty Trucks:North American EPA greenhouse gas standards for model year 2027 engines mandate closed-loop speed control rather than open-loop voltage application. Integrated starter-generator sourcing decisions now absorb these specifications.
Passenger Cars generates the largest absolute unit demand. Heavy-Duty Trucks exhibits the steepest specification upgrade trajectory.
Fuel Type:
Emission regulation stringency varies by fuel chemistry, redirecting starter motor efficiency investments toward gasoline direct-injection and hybrid architectures.
- Gasoline:Direct-injection systems require higher cranking speeds for fuel rail pressurization. Euro 7 cold-start emission limits tighten speed tolerance bands.
- Diesel:High compression ratios demand elevated cranking torque, sustaining demand for gear reduction starter configurations in commercial applications.
- Electric:Battery electric vehicles eliminate conventional starter function entirely, compressing addressable market scope for dedicated starter manufacturers.
- Hybrid:48V mild-hybrid systems consolidate cranking and generation into integrated starter-generator assemblies above 15kW electrical output.
Gasoline retains the largest installed base. Hybrid configurations are gaining share fastest as electrification architectures proliferate.
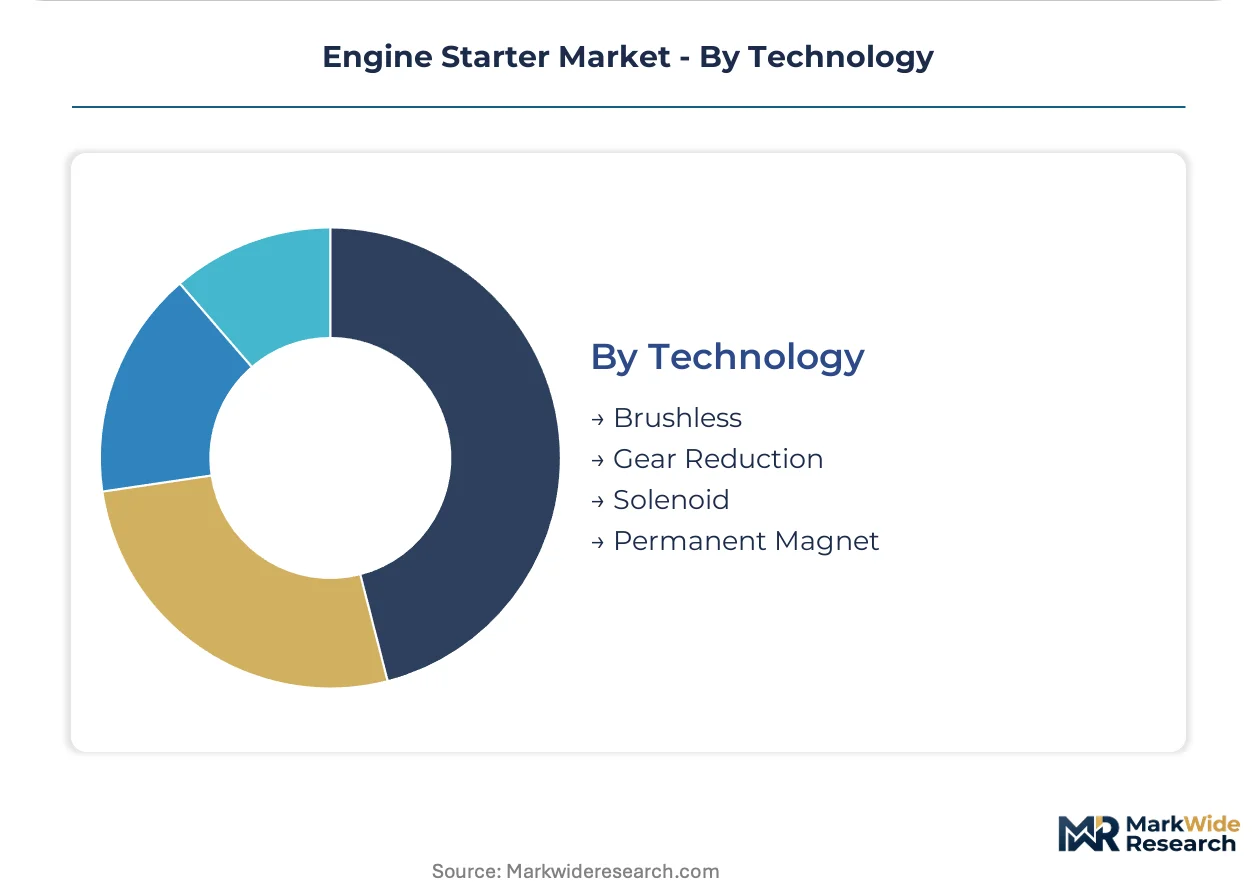
Technology:
Material substitution toward rare-earth reduced designs reshapes technology roadmaps as thermal durability requirements intensify.
- Brushless:Electronic commutation eliminates brush wear and enables precise speed control through embedded power electronics. China's MIIT dual carbon goals accelerate domestic OEM localization of brushless production.
- Gear Reduction:Planetary gear sets multiply motor torque for high-compression diesel applications. Heavy-duty truck specifications specify these architectures for cold-start reliability.
- Solenoid:Electromechanical actuators engage pinion gears with ring gears through high-current windings. Conventional wound-field designs face margin pressure from neodymium price volatility.
- Permanent Magnet:Rare-earth magnet formulations replace wound field windings for weight reduction and efficiency gains. Enhanced thermal cycling resistance specifications penetrate extreme climate duty cycles.
Gear Reduction dominates heavy-duty applications. Brushless architectures command the steepest expansion trajectory across new platform tooling investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade imbalances in starter motor components are reshaping regional manufacturing footprints as tariff exposure and localization mandates intensify. Export-oriented suppliers in East Asia face margin compression from currency volatility and shipping cost spikes. Import-dependent markets in South Asia and Latin America are accelerating captive production investments to reduce supply chain vulnerability.
China
Domestic OEMs are localizing brushless starter production under MIIT dual carbon goals and supply chain security directives. The Yangtze River Delta manufacturing corridor hosts concentrated permanent magnet motor fabrication for both domestic consumption and regional export. Shanghai and Suzhou industrial parks are absorbing technology transfer partnerships with European tier-one suppliers.
Germany
Euro 7 cold-start emission limits are forcing specification upgrades across premium passenger car platforms. The country's automotive regulator is tightening cranking speed tolerance bands for gasoline direct-injection systems. Stuttgart and Munich engineering clusters are integrating hairpin-wound stator architectures into next-generation stop-start system designs.
United States
EPA greenhouse gas standards for model year 2027 heavy-duty engines mandate closed-loop starter speed control. NHTSA commercial vehicle safety thresholds are elevating cranking reliability specifications for long-haul trucking applications. Detroit powertrain engineering centers are absorbing these requirements into integrated starter-generator sourcing decisions.
India
BIS efficiency mandates under Bharat Stage VI Phase II are driving pneumatic-to-electric starter conversions in medium-duty commercial vehicles. The country's automotive component regulator is enforcing localized content thresholds for government fleet procurement. Pune and Chennai manufacturing belts are expanding wound-field starter capacity for domestic truck OEMs.
Brazil
Long-haul trucking fleet operators are disintermediating OEM dealer networks through direct starter procurement agreements. ANVISA industrial equipment standards influence sealed housing specifications for extreme climate reliability. São Paulo state industrial corridors host the largest concentration of aftermarket starter distribution infrastructure in Latin America.
Engine Starter Market Competitive Landscape
On the supply side, the industry is consolidating around integrated powertrain electromechanical capabilities as standalone starter manufacturing becomes economically marginal. Tier-one automotive suppliers with captive R&D in permanent magnet technologies are absorbing market share from dedicated starter motor specialists. Two strategic archetypes dominate: diversified powertrain integrators with 48V system competencies, and regional cost-optimized manufacturers serving aftermarket replacement cycles. Competitive moves center on backward integration into rare-earth magnet supply chains and technology licensing agreements for hairpin-wound stator production.
Among Japanese diversified automotive component suppliers, Denso Corporation and Mitsubishi Electric Corporation exemplify the powertrain integrator archetype with embedded permanent magnet R&D capabilities. Robert Bosch GmbH anchors the European tier-one supplier tier through manufacturing scale across integrated electromechanical modules. These three entities represent contrasting geographic and structural approaches to the category's consolidation pressure.
| Leading Market Players |
|---|
| Denso Corporation |
| Robert Bosch GmbH |
| Valeo Group |
| BorgWarner Inc. |
| Mitsubishi Electric Corporation |
| Mitsuba Corporation |
| Hitachi Astemo Ltd. |
| SEG Automotive |
| Lucas TVS Ltd. |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility directly compresses margin pools for permanent magnet starter manufacturers while amplifying price differentiation between rare-earth tethered and rare-earth reduced motor architectures. Downstream fleet operators absorb these cost dynamics through contract structures that separate premium brushless specifications from economy wound-field alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates hairpin-wound stator configurations with ISO 16750-3 certification from conventional random-wound alternatives and commodity wound-field designs. Pricing pressure stems from neodymium price volatility under Chinese export quota policies. Aftermarket distributors exhibit highest price sensitivity due to inventory risk exposure, while captive OEM procurement teams prioritize thermal durability specifications over unit cost.
Supply Chain Analysis
Neodymium magnet feedstock draws from Chinese rare-earth processing clusters, Malaysian downstream separation facilities, and Australian mining operations. Copper armature winding and silicon steel laminations constitute secondary material dependencies. Single-source vulnerability concentrates in Southeast Asian wound-field armature production. Distribution runs through Tier 1 powertrain integrators with captive manufacturing footprints in Germany, China, and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards suppliers possessing embedded power electronics competency for 48V control algorithm development, a capability gap that separates integrated powertrain specialists from legacy electromechanical manufacturers. Platform consolidation around starter-generator architectures is compressing viable strategic options for dedicated starter producers.
For Market Incumbents: Build regulatory certification moats around Euro 7 cold-start emission compliance and EPA model year 2027 heavy-duty specifications. Absorb ISO 16750-3 vibration test cycle expertise through targeted R&D hiring in Stuttgart and Detroit engineering clusters. Defend against 48V integrated starter-generator substitution by anchoring long-term supply agreements with commercial vehicle fleet operators in Brazil and India. For New Entrants and Emerging Players: Establish a beachhead in marine outboard aftermarket segments where salt-water corrosion-resistant sealed housing designs face limited incumbent specialization. Target Mediterranean coastal markets with direct procurement relationships to recreational boating distributors. Leverage IoT-enabled predictive maintenance integration as a differentiated service layer around sensor-embedded starter hardware. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with orphaned starter motor divisions lacking 48V system integration roadmaps. Long-term viability hinges on powertrain-electronics convergence capabilities rather than standalone electromechanical manufacturing scale. Monitor MIIT dual carbon localization mandates as an inflection signal for Chinese supply chain restructuring opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Reduces neodymium price volatility exposure for permanent magnet starter producers. |
| Hairpin-Wound Stator Production Licensing | Enables European premium OEM compliance with 600,000-event stop-start duty cycles. |
| 48V Control Algorithm Development Partnership | Addresses power electronics integration skill gaps in electromechanical engineering teams. |
| Direct Fleet Procurement Channel Establishment | Captures aftermarket volume disintermediated from OEM dealer networks in Brazil. |
| IoT Sensor Embedding for Predictive Maintenance | Creates telematics-enabled service revenue streams for fleet operator optimization. |
Research Methodology
A standing panel of Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and commercial vehicle fleet operations directors provided ongoing calibration against secondary validation from EPA regulatory filings, Euro 7 proposal documents, MIIT policy circulars, and vehicle production databases. Bottom-up unit demand modeling triangulated against top-down powertrain electrification scenario analysis.
Scenario bracketing around mild-hybrid adoption rates and commercial vehicle electrification timelines shaped volume projections across the analysis window. Segmentation dimensions spanned product architecture, vehicle class, fuel type, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating technology substitution elasticities and OEM platform refresh cycles.
Sensitivities concentrate around rare-earth export policy shifts, 48V system cost reduction trajectories, and Bharat Stage VI Phase II enforcement timing. Cross-checking against IHS Markit vehicle registration data and customs trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Engine Actuators Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Automotive Crankshaft Sensor Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
Automotive Powertrain Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Automotive Fuel Pulsation Damper Market
Powertrain
Automotive Turbocharger Market
Powertrain
Power Seat Adjustment Motor Market
Powertrain
Global Automotive Powertrain Management System Market
Powertrain
Global Automotive Pumps Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Fuel Pumps Market
Powertrain
Japan Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Slipper Clutch Market