
 Automotive Turbo-Compounding System Market | 2026-2036
Automotive Turbo-Compounding System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Turbo-Compounding System Market Analysis
The EU Green Deal's binding CO₂ reduction targets for heavy-duty vehicles is rebalancing procurement priorities across European commercial vehicle fleets. Cummins Inc. leverages its integrated powertrain expertise to embed turbo-compounding within diesel and natural gas engine architectures. BorgWarner Inc. anchors its position through captive thermal management and exhaust energy recovery system production. Voith GmbH & Co. KGaA specializes in retrofit-compatible turbo-compounding kits for existing bus and coach fleets.
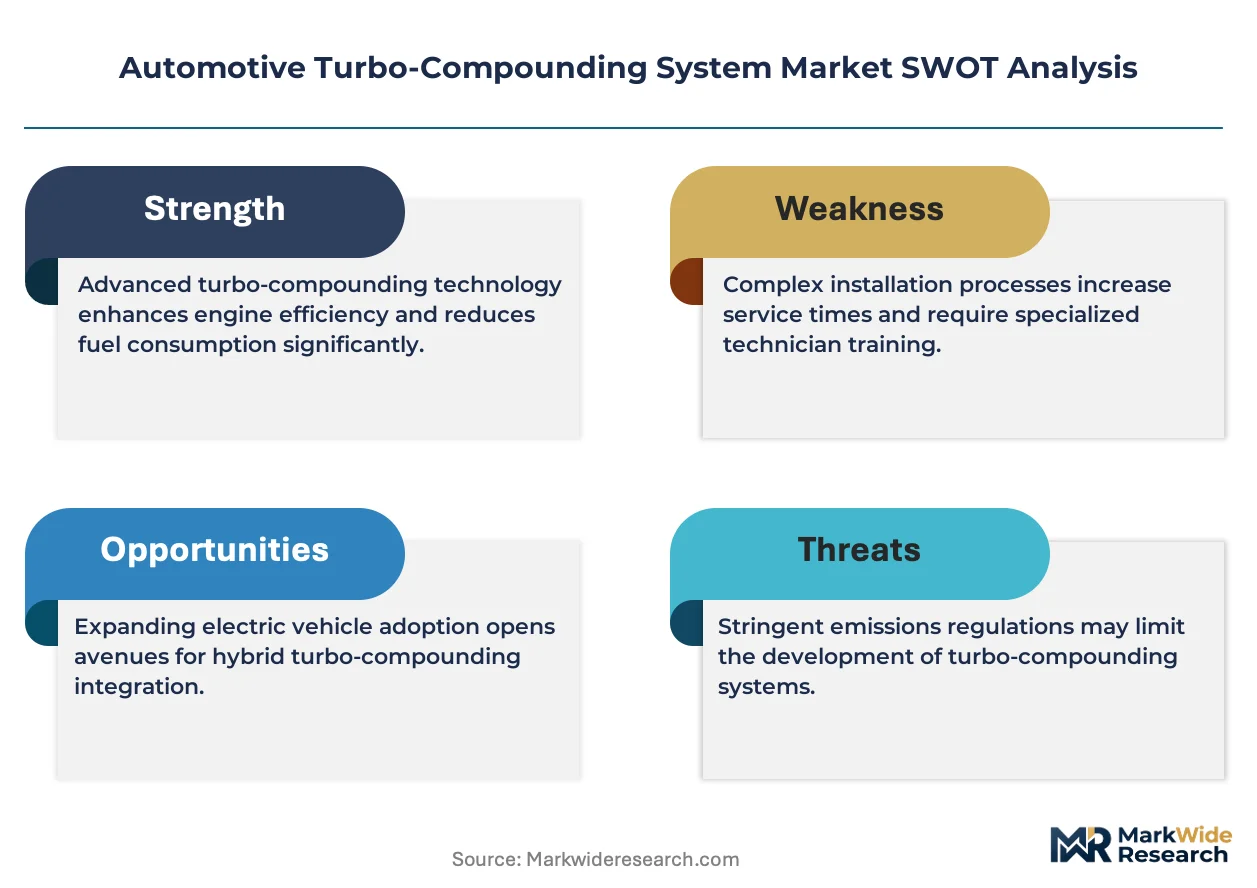
Automotive turbo-compounding systems capture residual exhaust gas energy through a power turbine mechanically or electrically coupled to the crankshaft, typically recovering 3-5% of otherwise wasted thermal energy at exhaust temperatures exceeding 500°C to improve brake thermal efficiency. Integrated Systems dominate current OEM installations due to their seamless coupling with engine management electronics and lower packaging penalties. Electrically Assisted technology represents the fastest-expanding segment, as 48V architectures enable decoupled turbine generators that bypass mechanical linkage constraints.
EPA Phase 2 standards in the United States and EU Green Deal CO₂ fleet targets enforced by the European Commission shape product development roadmaps and certification costs for suppliers. China's MIIT fuel consumption regulations for commercial vehicles and NMPA component homologation requirements add compliance layers for market entry. Stakeholders must monitor evolving e-fuel compatibility standards and hybrid-electric integration protocols that could redefine turbo-compounding's value proposition in next-generation powertrains.
Market Dynamics
The transition from mechanical to 48V electrically assisted turbo-compounding architectures is restructuring supplier relationships and procurement criteria across heavy-duty powertrain supply chains. This shift favors electronics-integrated system providers over traditional turbocharger specialists and compresses development cycles for next-generation thermal recovery solutions.
Growth Catalysts
- EPA Phase 2 CO₂ mandates:Binding fuel-efficiency standards for Class 8 trucks in the United States force fleet operators to specify exhaust energy recovery hardware to avoid penalties.
- Long-haul logistics economics:Freight carriers operating 500,000+ annual miles prioritize brake thermal efficiency gains that reduce diesel consumption per ton-mile.
- 48V electrical architecture proliferation:Decoupled turbine generator designs bypass mechanical linkage packaging constraints and enable flexible installation across multiple engine platforms.
Market Restraints
- High-temperature material costs:Inconel turbine wheels and ceramic bearing assemblies face price volatility tied to nickel and cobalt spot markets.
- German supply base concentration:Precision casting capacity for exhaust housings clusters in Baden-Württemberg and Bavaria, creating single-source vulnerability.
- Mechanical system substitution:Integrated starter-generator systems and mild-hybrid architectures compete for the same under-hood packaging volume and capital budgets.
Strategic Opportunities
- Retrofit bus and coach segments:Municipal transit authorities in Poland and Romania seek upgrade-compatible turbo-compounding kits to extend fleet life without full powertrain replacement.
- E-fuel compatibility certification:Emerging HVO and synthetic diesel standards create first-mover advantage for suppliers validating turbine durability with alternative combustion chemistries.
- Powertrain-as-a-service channels:Leasing providers and fleet management platforms embed efficiency hardware into monthly per-vehicle pricing, bypassing upfront capex barriers for small operators.
Industry Challenges
- Thermal-mechanical simulation expertise scarcity:Exhaust gas dynamics modeling and transient heat transfer analysis require specialized CAE competencies concentrated at Tier 1 suppliers.
- Multi-homologation certification timelines:Simultaneous EPA, EU Green Deal, and China MIIT approval processes extend product launch windows and strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Turbo-Compounding System Market |
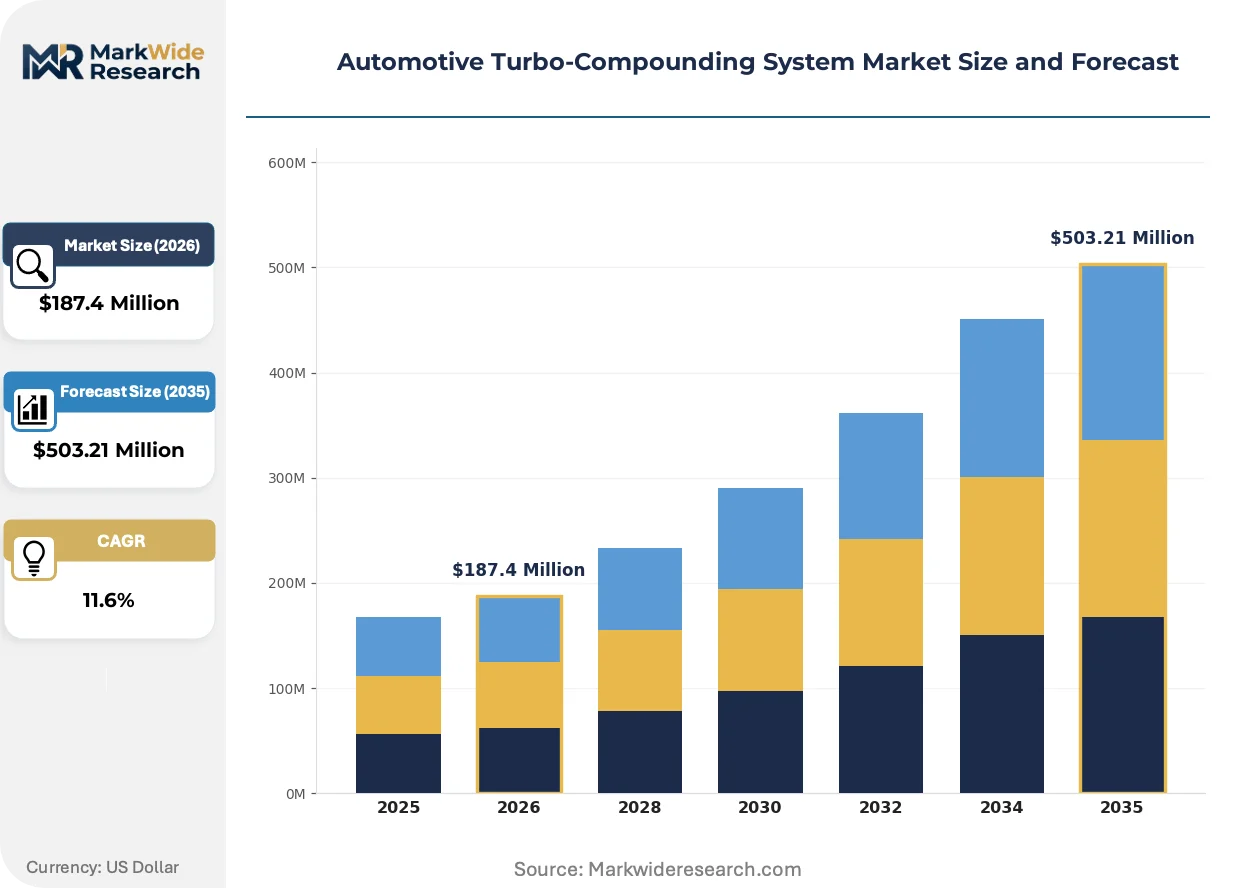
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Systems, Aftermarket Solutions, OEM Solutions Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Sports Cars Technology: Regenerative Turbocharging, Variable Geometry, Two-Stage Turbocharging, Electrically Assisted End User: Auto Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Research Institutions |
| Companies Covered | Voith GmbH & Co. KGaA, AB Volvo, MITEC Automotive AG, BorgWarner Inc., Cummins Inc., Honeywell International Inc., Garrett Motion, Bowman Power Group, Caterpillar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Turbo-Compounding System Market Emerging Trajectories
Thermal energy recovery hardware is migrating from standalone bolt-on components to embedded powertrain electronics, compressing supplier margins while expanding addressable efficiency gains. This integration demands new competencies in power electronics, real-time control algorithms, and vehicle-network cybersecurity.
Electrically assisted turbo-compounding is converging with 48V mild-hybrid architectures to create unified energy recovery and torque-assist systems. Heavy-duty truck OEMs in Germany and the United States are adopting this configuration for 2027 model year platforms. The technology is converging with existing alternator-starter locations, reducing wiring harness complexity and enabling shared cooling circuits.
The EU Green Deal's CO₂ fleet averaging mechanism tightens binding targets for heavy-duty vehicle manufacturers through 2030. Non-compliant OEMs face per-vehicle penalties that compound across high-volume segments. Long-haul tractor-trailer configurations bear the steepest compliance burden, accelerating specification of exhaust energy recovery in premium sleeper cab variants.
Fleet procurement departments now require documented fuel-economy improvement guarantees backed by telematics verification rather than laboratory test cycles. Third-party logistics providers operating transcontinental routes in North America lead this contractual shift. The practice compresses supplier liability windows and forces real-world durability validation before volume purchase commitments.
Automotive Turbo-Compounding System Market Segmentation
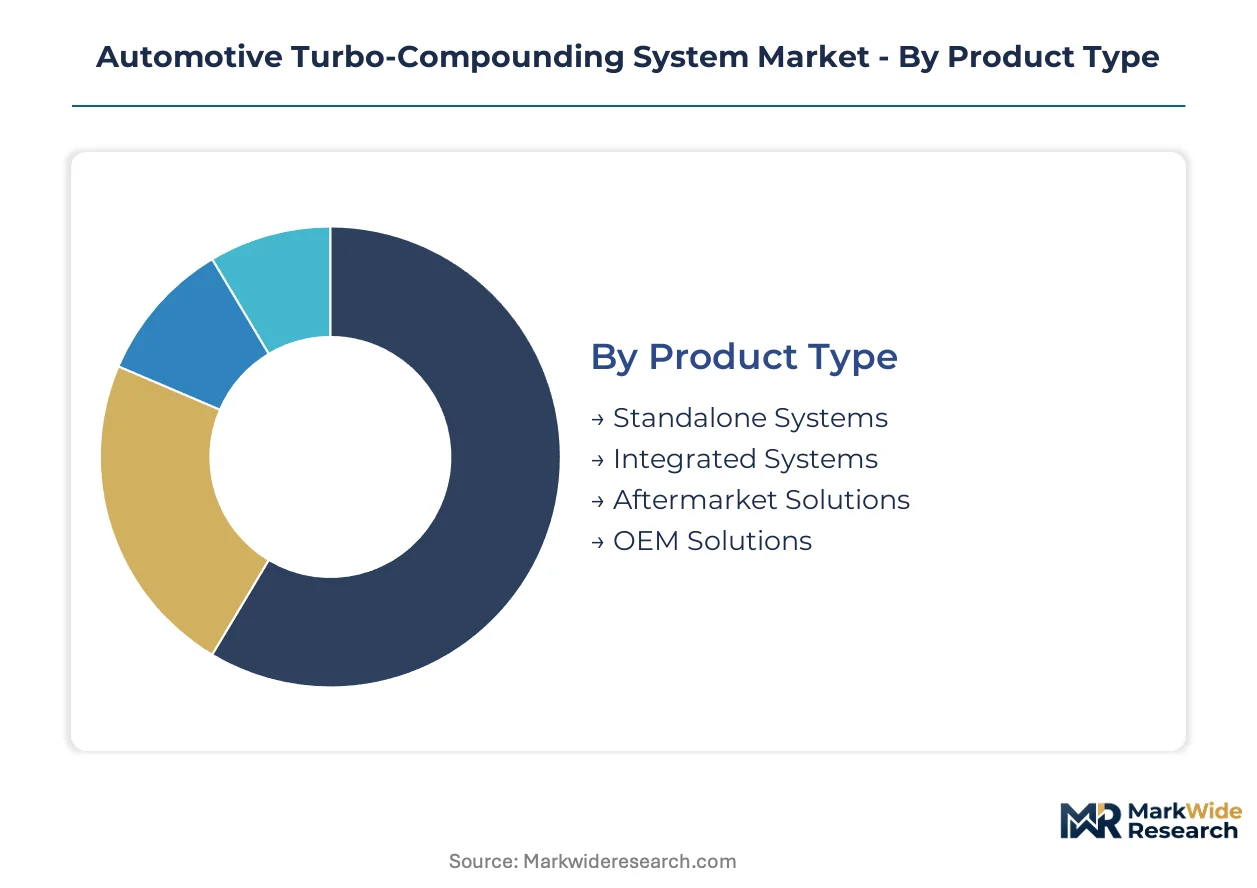
Turbo-compounding hardware varies dramatically in engineering complexity and upfront capital requirements across product architectures. Procurement patterns diverge sharply between fleet operators seeking retrofit compatibility and OEMs embedding thermal recovery into new powertrain designs.
Product Type:
Capital intensity clusters heavily in integrated manufacturing footprints, while aftermarket channels demand leaner inventory models and modular kit designs.
- Integrated Systems:These configurations embed turbine generators directly within engine management electronics, requiring synchronized thermal-mechanical simulation and captive casting capacity. Demand concentrates at German and US heavy-duty truck OEMs facing binding EPA Phase 2 and EU Green Deal fleet targets. The seamless crankshaft coupling eliminates packaging penalties but demands multi-year platform development cycles.
- Standalone Systems:Bolt-on architectures mount downstream of existing turbochargers, preserving engine block integrity and enabling retrofit applications. Municipal bus fleets in Poland and Romania specify these kits to extend vehicle life without full powertrain replacement. Lower integration depth reduces homologation complexity but sacrifices 1-2 percentage points of thermal efficiency versus embedded alternatives.
- Aftermarket Solutions:Distributors serving independent repair networks stock rebuild kits and replacement turbine wheels.
- OEM Solutions:Factory-installed hardware ships with powertrain warranties and telematics-enabled fuel economy guarantees.
Integrated Systems absorb the bulk of installed capacity; Aftermarket Solutions are expanding most quickly.
Application:
Vehicle duty cycles determine turbine sizing, exhaust temperature profiles, and payback period calculations for fleet operators.
- Heavy-Duty Trucks:Class 8 tractors operating 500,000+ annual miles generate sustained exhaust temperatures exceeding 500°C, maximizing energy recovery potential. Long-haul logistics carriers across the United States and Germany prioritize brake thermal efficiency gains that reduce diesel consumption per ton-mile. Sleeper cab variants bear the steepest compliance burden under tightening CO₂ mandates.
- Commercial Vehicles:Regional delivery trucks and vocational chassis face stop-start duty cycles that challenge transient heat transfer management. Urban freight operators in Germany balance emission zone access against hardware cost recovery timelines. The segment favors electrically assisted architectures that decouple turbine speed from engine RPM.
- Passenger Vehicles:Limited under-hood packaging and lower annual mileage compress the addressable market.
- Sports Cars:Thermal recovery serves performance augmentation rather than fuel economy in this niche.
Heavy-Duty Trucks dominate current procurement volumes; Commercial Vehicles show the steepest expansion trajectory.
Technology:
Electrification depth separates legacy mechanical linkages from decoupled generator architectures enabled by 48V infrastructure.
- Electrically Assisted:Decoupled turbine generators bypass mechanical coupling constraints, enabling flexible installation across multiple engine platforms. German and US truck OEMs are adopting this configuration for 2027 model year platforms, converging with existing alternator-starter locations. The technology demands power electronics competencies and real-time control algorithm development.
- Regenerative Turbocharging:Mechanical power turbines couple directly to the crankshaft through gear trains or hydraulic linkages. Established production lines in Baden-Württemberg supply precision-cast exhaust housings for these systems. Nickel and cobalt price volatility in Inconel turbine wheels creates material cost exposure.
- Variable Geometry:Adjustable vane angles optimize exhaust gas flow across engine speed ranges.
- Two-Stage Turbocharging:Sequential compressor arrangements address low-end torque and high-speed boost requirements.
Regenerative Turbocharging maintains the largest installed base; Electrically Assisted technology is climbing the fastest.
End User:
Supply chain position determines specification authority, warranty liability, and access to vehicle-network integration protocols.
- Auto Manufacturers:OEMs control platform architecture decisions and embedded software calibration, capturing efficiency gains within corporate fleet averaging calculations. German and US heavy-duty truck producers face binding per-vehicle penalties under EPA Phase 2 and EU Green Deal enforcement mechanisms. Thermal recovery specification has shifted from optional equipment to standard fitment in premium sleeper configurations.
- Tier-1 Suppliers:Integrated powertrain specialists manage exhaust energy recovery as one component within broader thermal management system responsibility. These firms concentrate CAE expertise for exhaust gas dynamics modeling and transient heat transfer analysis. Multi-homologation certification timelines strain engineering bandwidth across simultaneous EPA, EU, and China MIIT approval processes.
- Aftermarket Providers:Independent distributors serve fleet operators seeking retrofit compatibility.
- Research Institutions:Universities and national laboratories validate alternative fuel compatibility and durability protocols.
Auto Manufacturers command the largest share of specification authority; Tier-1 Suppliers are gaining procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg anchors turbo-compounding manufacturing capacity through precision casting clusters in Stuttgart and Heilbronn. This German industrial corridor supplies exhaust housings to heavy-duty truck OEMs across three continents.
United States
Class 8 truck fleets operating transcontinental routes generate sustained demand for brake thermal efficiency hardware. EPA Phase 2 mandates impose binding CO₂ reduction targets on manufacturers. Detroit's powertrain engineering centers integrate turbo-compounding into 2027 model year diesel platforms.
Germany
Long-haul logistics carriers prioritize total cost of ownership reductions across 500,000+ annual mile operations. EU Green Deal fleet averaging mechanisms enforce steep per-vehicle penalties for non-compliance. Munich and Stuttgart host captive thermal management production for integrated system architectures.
China
Commercial vehicle manufacturers face MIIT fuel consumption regulations tightening through 2025. The country's national automotive regulator enforces component homologation requirements that add compliance layers for market entry. Shandong Province concentrates casting capacity for exhaust energy recovery hardware.
Japan
Heavy-duty truck OEMs balance domestic emission standards with export market certification requirements. METI oversees fuel efficiency benchmarking for commercial vehicle segments. Nagoya's industrial corridor specializes in high-temperature material processing for turbine wheel applications.
India
Long-haul freight operators seek hardware compatibility with existing engine platforms amid infrastructure expansion. The Bureau of Indian Standards develops testing protocols for exhaust energy recovery systems. Maharashtra's automotive component clusters attract Tier-1 supplier investments in thermal management capabilities.
Automotive Turbo-Compounding System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across integration depth and thermal-mechanical simulation expertise. The supplier base concentrates around three strategic tiers: integrated powertrain specialists with captive casting capacity, electronics-integrated system providers leveraging 48V architectures, and retrofit-focused kit manufacturers serving municipal fleets. Dominant competitive moves include backward integration into precision exhaust housing production and strategic partnerships with fleet telematics platforms.
Among Germany-based engineering specialists, Voith GmbH & Co. KGaA occupies a position exemplifying retrofit-compatible system architecture. BorgWarner Inc. and Cummins Inc. represent the integrated powertrain tier, anchoring factory-installed hardware within corporate fleet averaging calculations. These three entities span distinct archetypes: retrofit kit provision, Tier-1 thermal management integration, and OEM captive powertrain development.
| Leading Market Players |
|---|
| Voith GmbH & Co. KGaA |
| AB Volvo |
| MITEC Automotive AG |
| BorgWarner Inc. |
| Cummins Inc. |
| Honeywell International Inc. |
| Garrett Motion |
| Bowman Power Group |
| Caterpillar |
| Others |
Supply Flow & Price Mechanics
EPA Phase 2 CO₂ mandates gate qualified supply and premium-tier pricing access by requiring certified thermal-mechanical simulation expertise that only Tier 1 suppliers possess. Fleet operators seeking documented fuel-economy guarantees backed by telematics verification must pay premiums for factory-installed hardware with embedded powertrain warranties, while retrofit-compatible kits serve price-sensitive municipal buyers.
Pricing Analysis
Value-based pricing anchored to brake thermal efficiency outcomes dominates factory-installed turbo-compounding hardware, with fleet operators contracting for documented fuel consumption reductions per ton-mile. Pricing stratifies across premium integrated systems with telematics-enabled guarantees, standard OEM-fitment configurations, and economy aftermarket kits for bus fleet retrofits. Cost compression in economy tiers intensifies because nickel and cobalt spot volatility in Inconel turbine wheels squeezes rebuild kit margins. Municipal transit authorities in Eastern Europe exhibit highest price sensitivity; long-haul logistics carriers in Germany and the United States prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Reverse-logistics flows for remanufactured turbine wheels and ceramic bearing assemblies extend asset life in aftermarket channels, particularly for municipal bus operators seeking to defer full powertrain replacement. Supply concentrates in Germany, China, and the United States, with precision casting capacity clustering in Baden-Württemberg and Shandong Province. The chain draws from Inconel superalloys, cobalt-bearing ceramics, and high-temperature steel forgings. Single-source vulnerability in German exhaust housing casting creates structural risk. Distribution runs through captive OEM supply agreements for integrated systems and independent aftermarket distributors for retrofit kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision casting capacity scarcity in Baden-Württemberg props pricing for qualified suppliers, constraining volume expansion regardless of fleet demand. Tier 1 thermal management specialists and OEM captive operations capture margin premiums while unqualified entrants face homologation barriers.
For Market Incumbents: Deploy backward integration into precision exhaust housing production to secure casting capacity against nickel price volatility and German supply base concentration. Incumbent suppliers must lock in multi-year platform development cycles with Detroit and Stuttgart engineering centers before 48V architecture proliferation accelerates. Defensive consolidation through captive thermal-mechanical simulation expertise blocks emerging electronics-integrated system providers from bypassing traditional turbocharger specialists. For New Entrants and Emerging Players: The price-point gap between premium integrated systems and economy aftermarket kits creates white-space opportunity for mid-tier electrically assisted architectures targeting regional delivery truck operators. New entrants should prioritize Poland and Romania municipal bus retrofit segments where homologation complexity remains lowest and procurement authority decentralizes to transit authorities. A go-to-market angle through powertrain-as-a-service leasing channels bypasses upfront capex barriers for small fleet operators. For Investors and Strategic Acquirers: First-mover e-fuel compatibility certification with HVO and synthetic diesel standards is the leading indicator that turbine durability validation capabilities will command acquisition premiums. Long-term viability hinges on 48V mild-hybrid convergence positioning exhaust energy recovery within unified torque-assist architectures rather than standalone bolt-on components. Acquisition targets should concentrate on Tier 1 suppliers with captive CAE competencies for transient heat transfer analysis. Practitioners should monitor EPA Phase 2 penalty enforcement intensity and EU Green Deal fleet averaging compliance rates for early demand signals.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Casting Capacity Expansion | Captive exhaust housing production in Baden-Württemberg secures supply against German supply base concentration. |
| 48V Architecture Platform Integration | Convergence with alternator-starter locations reduces wiring complexity for Detroit and Stuttgart OEMs. |
| E-Fuel Compatibility Certification | HVO and synthetic diesel validation creates first-mover advantage as EU Green Deal tightens. |
| Telematics-Enabled Performance Guarantees | Real-world fuel economy verification meets fleet procurement demands for documented ton-mile efficiency. |
| Retrofit Kit Distribution Partnerships | Channel access to Polish and Romanian municipal transit authorities extends hardware life without powertrain replacement. |
Methodological Framework
Document review covered EPA certification filings, EU Green Deal enforcement documentation, MIIT fuel consumption regulations, and SEC 10-K disclosures from listed automotive suppliers, complemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet telematics operators. Secondary validation drew from vehicle production databases, IHS Markit registration data, and customs records for Inconel and cobalt trade flows. Bottom-up unit economics triangulated against top-down fleet penetration assumptions.
Segment-level outputs across product architecture, vehicle application, electrification depth, and supply chain position were generated through the modeling period. CAGRs were derived from installed base projections and replacement cycle analysis. Forecast inputs incorporated EPA Phase 2 compliance penalty schedules, EU fleet averaging mechanism stringency trajectories, and 48V electrical architecture adoption curves in heavy-duty platforms.
Inputs from OEM engineering centers and Tier 1 supplier thermal management divisions were available through the study window; gaps in real-world durability validation data for e-fuel combustion chemistries introduce uncertainty bands around turbine material life assumptions. Forecasts reflect documented homologation timelines and assumed nickel price volatility within historical ranges. Practitioners should monitor EPA enforcement discretion, EU per-vehicle penalty levels, and China MIIT fuel consumption regulation revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Water Pump Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Turbocharger Actuators Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Global Automotive Pumps Market
Powertrain
Timing Belt Kits Market
Powertrain
United States Automotive Engine Oils Market
Powertrain
Automotive Oil Sump Market
Powertrain
Axle Shaft Market
Powertrain
CNG Powertrain Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Global Automotive Clutch Market
Powertrain
Automotive Coil Spring Market
Powertrain
Automotive Cylinder Block Market
Powertrain
Automotive Carburetor Market
Powertrain
Gear Reduction Starter Market