
 North America Automotive Engine Oils Market | 2026-2036
North America Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Engine Oils Market Analytics
Asset-light leasing models for lubricant blending and distribution infrastructure are rewriting competitive entry dynamics in the North America automotive engine oils landscape. ExxonMobil leverages its integrated refining and additive manufacturing footprint to sustain margin capture across the value chain. Valvoline anchors its position through quick-lube service channel control, while Phillips 66 competes on geographic proximity to mid-continent feedstock sources.
North America automotive engine oils comprise base oil stocks blended with performance additive packages to achieve specific viscosity grades, thermal stability thresholds, and wear protection metrics for internal combustion engines. These formulations reduce friction, dissipate heat, and suspend combustion byproducts to extend engine operational life. Synthetic oils command premium positioning due to extended drain intervals and severe-service temperature performance, while the aftermarket provider channel captures recurring revenue through vehicle-age-driven replacement cycles. High-mileage oils occupy a growing niche addressing seal conditioning in aging US and Canadian vehicle parc.
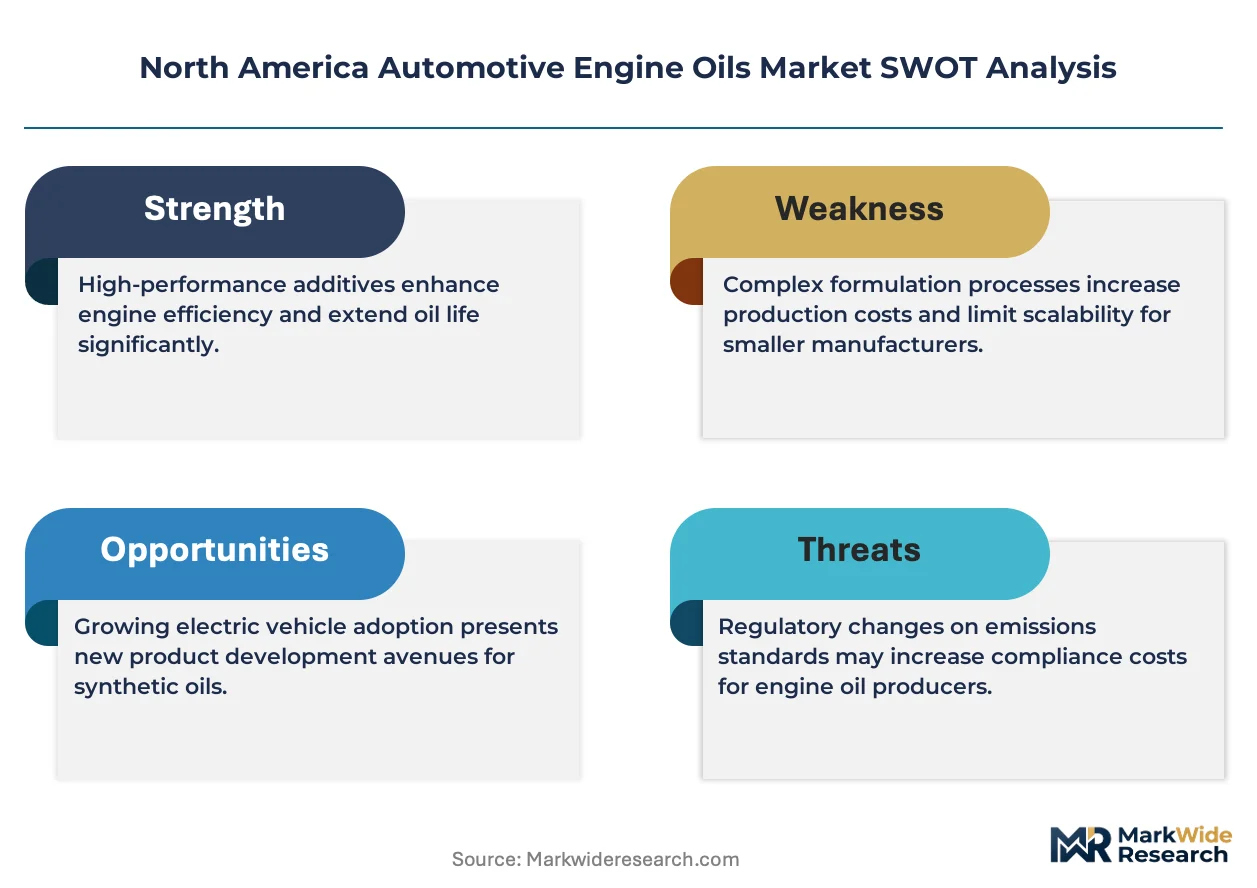
The US EPA, API, and NHTSA collectively shape product formulation mandates through emissions compliance pathways and fuel economy standards that cascade into lubricant specifications. California's CARB regulations frequently prefigure broader North American requirements, creating a de facto lead-market dynamic for low-viscosity, low-volatility oil categories. Stakeholders must monitor the pace of electrification-driven displacement against sustained internal combustion fleet lubrication demand to calibrate capacity and portfolio bets.
Market Dynamics
Fleet electrification timelines and EPA Phase 3 greenhouse gas standards are compressing investment windows for combustion-engine lubricant portfolios across North America. Blenders must simultaneously serve legacy internal combustion demand while calibrating capacity for hybrid-optimized formulations.
Growth Catalysts
- API SP/ILSAC GF-6 specifications:The tightened oxidation stability and deposit control mandates are forcing drain interval extensions. Synthetic penetration accelerates as conventional formulations fail new performance thresholds.
- Class 8 truck fleet synthetic conversion:Long-haul operators are consolidating procurement around 10W-30 and 5W-30 full synthetics to reduce downtime and extend engine rebuild cycles.
- US Gulf Coast base oil refining cluster:Concentrated Group II/III capacity in Texas and Louisiana lowers feedstock logistics costs for regional blenders serving the Midwest automotive belt.
Market Restraints
- Group III base oil import dependence:North American refiners lack sufficient high-viscosity index capacity, forcing reliance on Korean and Middle Eastern suppliers subject to freight rate volatility.
- Electrification displacement curve:Battery electric vehicle sales penetration in California and the Pacific Northwest is compressing long-term passenger car lubricant demand visibility.
- Additive package concentration:Four global suppliers control 80% of detergent-inhibitor and anti-wear chemistry, creating input cost pass-through vulnerability for independent blenders.
Strategic Opportunities
- Mexico aftermarket expansion:Vehicle parc aging in Monterrey and Guadalajara industrial corridors creates demand for high-mileage seal-conditioning formulations currently underserved by domestic suppliers.
- Hybrid-optimized low-viscosity segments:Stop-start engine wear patterns and thermal cycling stress are opening specification gaps between conventional passenger car oils and dedicated hybrid lubricants.
- California CARB low-volatility pathway:The state's evaporative emissions regulations for crankcase ventilation are prefiguring North American volatility limits that favor advanced base oil investments.
Industry Challenges
- Formulation chemist talent scarcity:Retirement waves among tribology specialists with 20-plus years of additive synergy experience are outrunning university pipeline replenishment.
- Dual-certification timeline compression:Simultaneous API SP-Resource Conserving and ILSAC GF-6B testing protocols are extending new product validation cycles by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Engine Oils Market |
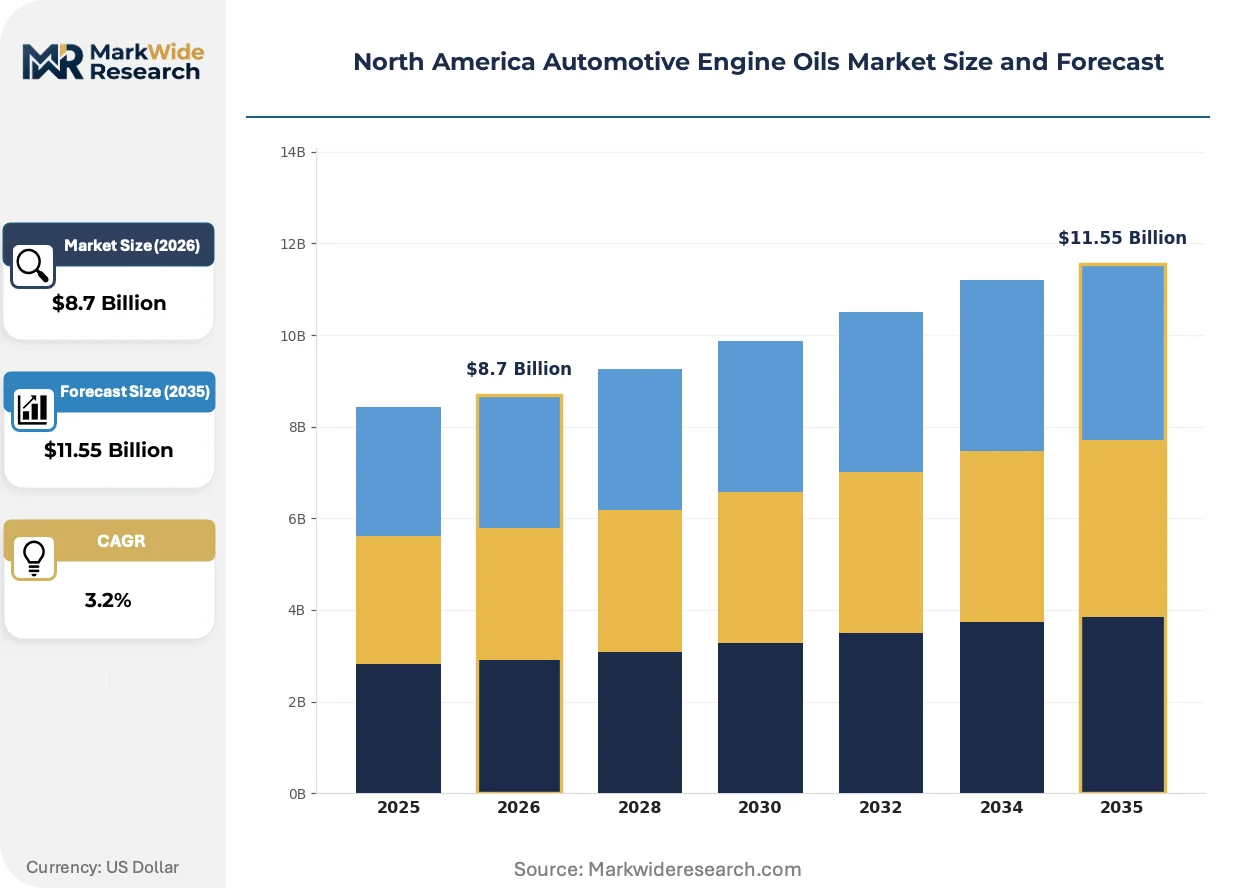
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.55 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
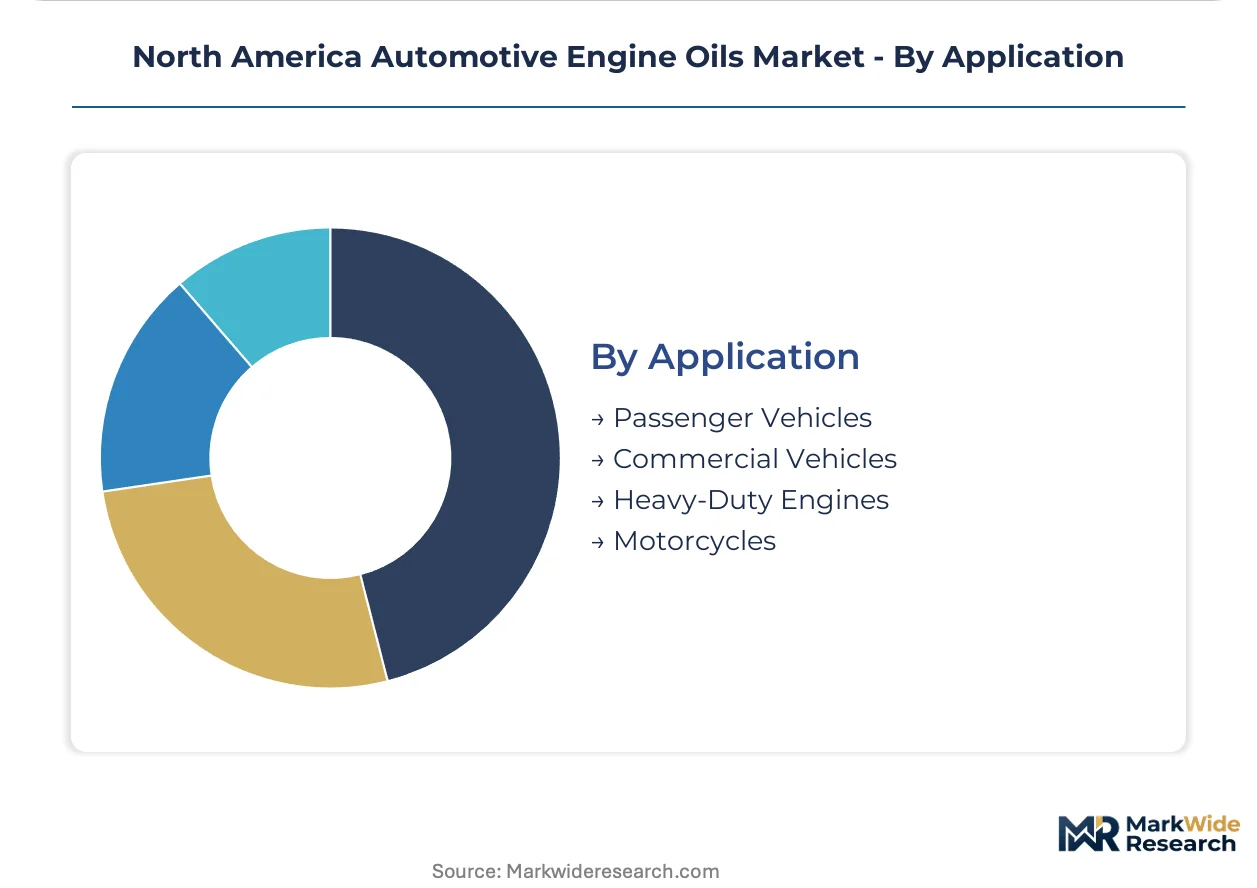
| Segmentation | Product Type: Synthetic Oils, Conventional Oils, High-Mileage Oils, Additives End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Packaging Type: Bottles, Drums, Bulk, Sachets Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Engines, Motorcycles |
| Companies Covered | ExxonMobil, Shell, BP Castrol, Chevron, TotalEnergies, Phillips 66, Fuchs, LUKOIL, Valvoline, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Engine Oils Market Evolving Landscape
Digital integration of lubricant condition monitoring with fleet management platforms is redefining value capture models. Real-time viscosity degradation tracking and predictive drain algorithms are shifting revenue from volume sales to performance-based service contracts.
Sensor-embedded oil analysis systems are digitizing maintenance scheduling for Class 8 fleets and municipal bus operators. These devices measure oxidation byproducts, soot loading, and fuel dilution in real time. Adoption concentrates among asset-heavy operators with centralized depot infrastructure. The technology is digitizing how lubricant suppliers contract with customers, compressing traditional bulk procurement into usage-optimized subscription models.
EPA Phase 3 greenhouse gas standards for heavy-duty trucks are cascading into viscosity grade mandates. The regulations penalize engine friction losses, pushing OEM fill specifications toward 0W-20 and 5W-30 grades previously reserved to passenger vehicles. Detroit Three powertrain divisions are most affected, accelerating reformulation of legacy 15W-40 portfolios. Blenders are responding with additive package redesigns to maintain wear protection at reduced high-temperature high-shear viscosity.
Quick-lube channel consolidation is altering aftermarket access patterns. National chains are capturing share from independent service bays through standardized menu pricing and loyalty program lock-in. The shift is most visible in Texas and Florida metropolitan corridors where vehicle density supports hub-and-spoke logistics. Smaller operators face equipment upgrade burdens to handle new synthetic grades, accelerating exit decisions and channel concentration.
North America Automotive Engine Oils Market Segmentation
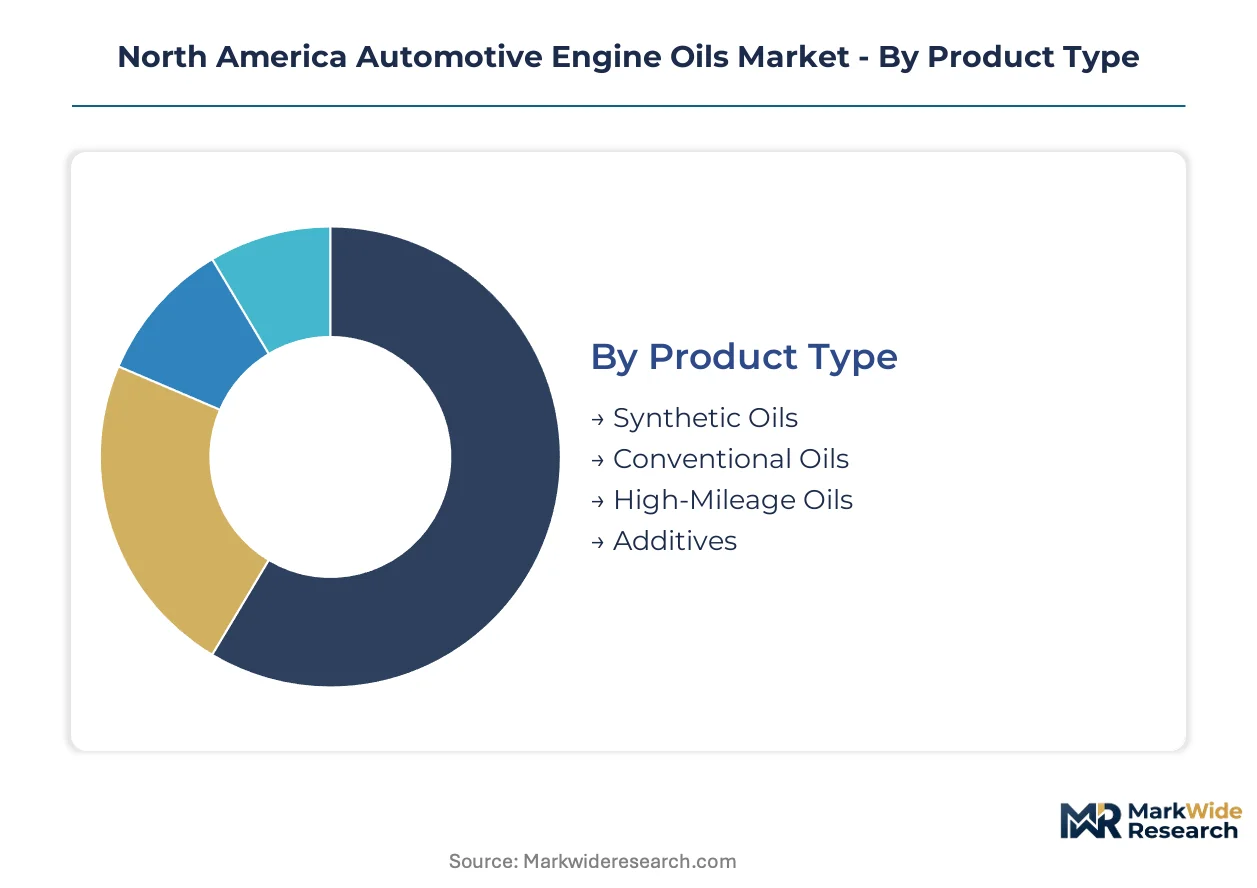
Segmentation in North America automotive engine oils reveals how formulation chemistry, procurement patterns, and vehicle duty cycles fragment demand across distinct value pools. Understanding these divisions exposes where margin concentrates and which channels face electrification pressure first.
Product Type:
Cycle times vary dramatically across lubricant chemistries, with synthetic drain intervals stretching three to five times longer than conventional formulations while high-mileage oils track vehicle aging curves rather than fixed schedules.
- Synthetic Oils:Group III and Group IV base stocks blended with advanced additive packages deliver extended thermal stability and oxidation resistance. Fleet operators in Texas and the US Midwest are consolidating procurement around 5W-30 and 10W-30 full synthetics to compress maintenance downtime and extend engine rebuild intervals. EPA Phase 3 friction reduction mandates are accelerating OEM fill specifications toward these grades.
- Conventional Oils:Mineral base stocks with standard detergent-inhibitor packages serve price-sensitive consumer segments and legacy vehicle populations. Demand concentrates among individual consumers in rural Canadian provinces and older vehicle parc in Mexico's secondary cities where drain interval discipline remains loose.
- High-Mileage Oils:Seal conditioners and anti-leak additives address compression loss and gasket degradation in vehicles exceeding 120,000 kilometers. The aging US vehicle fleet and extended ownership cycles in Ontario's manufacturing belt sustain this niche.
- Additives:Supplemental friction modifiers and viscosity index improvers enable custom blending for severe-service applications. Independent quick-lube operators in Florida and California use these to differentiate service menus.
Conventional oils anchor the volume base while synthetic formulations gain share at the steepest rate.
End User:
Procurement scale and specification authority separate these demand pools, with fleet operators wielding consolidated purchasing power against fragmented individual consumer decision-making.
- OEMs:Factory-fill specifications for Detroit Three and transplant assembly plants in Tennessee, Kentucky, and Ontario determine initial lubricant chemistry exposure. Powertrain warranty requirements lock in approved supplier relationships and viscosity grade mandates.
- Aftermarket Providers:Quick-lube chains and independent service bays capture recurring revenue through vehicle-age-driven replacement cycles. National chains in Texas and Florida metropolitan corridors are consolidating channel share through loyalty program lock-in.
- Fleet Operators:Class 8 long-haul operators and municipal bus systems negotiate bulk supply contracts with usage-based pricing. These buyers prioritize total cost of ownership metrics over per-unit lubricant cost.
- Individual Consumers:Price-sensitive purchasers selecting from retail automotive channels with limited technical specification knowledge. California and Pacific Northwest EV adoption curves compress this segment's long-term growth trajectory.
Fleet operators concentrate margin capture while aftermarket providers face the steepest channel consolidation pressure.
Packaging Type:
Logistics economics and consumption velocity determine format selection, with bulk infrastructure requiring depot density that only major metropolitan corridors sustain.
- Bottles:One-quart and five-quart retail formats dominate consumer DIY maintenance and small independent service bays. Shelf space competition in Walmart and AutoZone networks drives private-label penetration.
- Drums:55-gallon steel containers serve quick-lube chains and fleet maintenance depots with moderate throughput. Ontario's automotive service corridor and US Gulf Coast refining proximity lower drum logistics costs.
- Bulk:Tanker and tote deliveries to high-volume fleet operators and national quick-lube hubs eliminate packaging waste and per-unit handling cost. Requires dedicated storage infrastructure concentrated in Texas, California, and Illinois distribution clusters.
- Sachets:Single-use pouches for emergency top-off and motorcycle roadside service. Limited penetration in North America outside Mexico's informal service economy.
Bulk delivery anchors industrial-scale economics while bottle formats expand most quickly in Mexico's retail modernization.
Application:
Engine architecture and duty severity create distinct formulation requirements, with heavy-duty thermal loading and stop-start passenger car cycles demanding opposing viscosity strategies.
- Passenger Vehicles:Light-duty gasoline engines requiring low-viscosity 0W-20 and 5W-20 grades for CAFE fuel economy compliance. California CARB volatility regulations prefigure broader North American specifications favoring advanced base oils.
- Commercial Vehicles:Medium-duty delivery and regional haul trucks operating on 10W-30 synthetic blends. Last-mile electrification in urban California and Pacific Northwest corridors compresses long-term demand visibility.
- Heavy-Duty Engines:Class 8 long-haul and vocational equipment subject to EPA Phase 3 greenhouse gas standards. Friction reduction mandates are pushing viscosity grades previously reserved for passenger vehicles into this segment.
- Motorcycles:Small-displacement engines with shared sump lubrication requiring shear-stable viscosity grades. Niche demand concentrated in recreational vehicle markets of Florida, Arizona, and Southern California.
Heavy-duty engines anchor current formulation investment while passenger vehicle applications face the steepest electrification displacement curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and OEM factory-fill specifications concentrate lubricant demand across three distinct national markets. Each jurisdiction presents unique regulatory pressures and industrial clustering patterns that shape procurement behavior.
United States
Class 8 long-haul fleets and municipal bus systems drive synthetic oil procurement at scale. EPA Phase 3 greenhouse gas standards mandate friction-reducing low-viscosity grades for heavy-duty engines. The US Gulf Coast refining corridor in Texas and Louisiana anchors Group II/III base oil production for regional blenders.
Canada
Ontario's automotive manufacturing belt sustains factory-fill demand from Detroit Three transplant assembly plants. Environment and Climate Change Canada regulations align with EPA emissions pathways while maintaining distinct cold-weather viscosity specifications. Alberta's oil sands operations create specialized severe-service lubricant demand for mining equipment fleets.
Mexico
Monterrey and Guadalajara industrial corridors exhibit vehicle parc aging that outpaces domestic high-mileage formulation supply. PROFEPA environmental enforcement tightens used oil disposal standards for quick-lube operators. Northern border states concentrate maquiladora fleet maintenance depots serving cross-border logistics corridors.
North America Automotive Engine Oils Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented aftermarket and consolidated OEM supply tiers. The market structure exhibits dual concentration: additive package chemistry rests with four global suppliers, while finished lubricant blending fragments across regional operators and integrated majors. Strategic archetypes include integrated refiners capturing margin across base oil and additive production, service-channel operators locking in recurring revenue through quick-lube real estate control, and independent blenders competing on geographic feedstock proximity. Dominant competitive moves span backward integration into base oil refining and strategic partnerships with fleet telematics providers to embed lubricant monitoring into usage-based contracts.
Among integrated majors, ExxonMobil and Shell occupy positions exemplifying full-value-chain capture from base oil production through retail distribution. Valvoline represents the service-channel archetype, with its position anchored in quick-lube network density rather than upstream refining assets. These three companies illustrate how divergent strategic postures—vertical integration versus downstream control—coexist within the same market structure.
| Leading Market Players |
|---|
| ExxonMobil |
| Shell |
| BP Castrol |
| Chevron |
| TotalEnergies |
| Phillips 66 |
| Fuchs |
| LUKOIL |
| Valvoline |
| Others |
Value Network & Pricing Analysis
Texas and Louisiana's concentrated Group II/III base oil refining corridor anchors North American supply capacity, translating feedstock proximity into pricing leverage for regional blenders serving Midwest automotive and Gulf Coast fleet demand. This geographic clustering enables integrated majors to capture margin across upstream production and downstream formulation while independent operators face cost pass-through vulnerability from Korean and Middle Eastern Group III import dependence.
Pricing Analysis
Cost-plus contracts indexed to Group II/III base oil spot markets dominate procurement between blenders and fleet operators, with Korean export parity and US Gulf Coast postings serving as reference benchmarks. Price differentiation rests on synthetic certification grade and volume scale, with full synthetic 5W-30 formulations commanding premium positioning against mineral-based conventional grades. Pricing pressure stems from additive package concentration among four global suppliers, forcing independent blenders to absorb detergent-inhibitor cost volatility. Fleet operators exhibit lowest price sensitivity due to total cost of ownership procurement frameworks, while individual DIY consumers in Mexico's secondary markets remain most responsive to per-quart retail pricing.
Supply Chain Analysis
Supplier-financing structures including 60-90 day extended payment terms and supply-chain finance facilities lubricate working capital for quick-lube chains and independent distributors. Geographic supply concentration centers on the United States, South Korea, and the Middle East, with North American refiners lacking sufficient high-viscosity index capacity. Raw material dependencies draw from Group II/III base oil stocks, detergent-inhibitor additive packages, and viscosity index improvers. Single-source vulnerability in anti-wear chemistry creates input cost pass-through exposure. Distribution runs through bulk tanker deliveries to fleet depots, drum shipments to quick-lube chains, and retail bottle formats through automotive aftermarket retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation around synthetic conversion programs has shifted buyer power toward volume-consolidated Class 8 operators, fragmenting pricing leverage previously held by blenders. Quick-lube channel concentration in Texas and Florida metropolitan corridors accelerates this dynamic.
For Market Incumbents: Entrench position through captive additive package manufacturing partnerships and quick-lube real estate control in high-vehicle-density corridors. Electrification displacement curves threaten passenger car lubricant demand, requiring capacity reallocation toward hybrid-optimized formulations. Backward integration into Group II/III base oil refining secures feedstock cost stability against Korean import volatility. For New Entrants and Emerging Players: Mexico's aging vehicle parc in Monterrey and Guadalajara industrial corridors offers white-space penetration for high-mileage seal-conditioning formulations currently underserved by domestic suppliers. Hybrid-optimized low-viscosity segments present specification gaps between conventional passenger car oils and dedicated hybrid lubricants. Fleet telematics integration partnerships enable usage-based service contracting that bypasses traditional bulk procurement relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because additive package chemistry concentration and quick-lube channel control favor scaled operators with integrated supply positions. Acquisition targets include regional blenders with Gulf Coast feedstock proximity and independent quick-lube networks in underserved Mexican industrial corridors. Fleet electrification penetration rates in California and Pacific Northwest corridors signal demand inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Refining | Captive Group II/III supply secures margin against Korean import price volatility for Texas-based blenders. |
| Quick-Lube Channel Acquisition | Real estate control in Florida metropolitan corridors locks in recurring synthetic conversion revenue streams. |
| Hybrid-Optimized Formulation Launch | API SP-Resource Conserving certification addresses stop-start wear patterns in Detroit Three hybrid platforms. |
| Fleet Telematics Partnership | Sensor-embedded oil analysis enables predictive maintenance contracts with Class 8 operators in Illinois distribution clusters. |
| Mexico Aftermarket Expansion | High-mileage seal-conditioning formulations target compression loss in aging Guadalajara industrial corridor vehicle parc. |
Research Methodology
Desk research of customs trade data, API certification registries, and EPA regulatory filings preceded structured interviews with lubricant blending plant managers, Class 8 fleet procurement directors, quick-lube chain operations executives, and additive package technical directors. Primary fieldwork captured formulation specification trends, fleet conversion timelines, and channel consolidation dynamics. Secondary validation drew from base oil production databases, automotive registration statistics, and refinery capacity disclosures. Bottom-up volume modeling triangulated against top-down market sizing across synthetic, conventional, and high-mileage product categories.
Analytical assumptions held electrification penetration curves and EPA Phase 3 implementation pathways fixed while varying hybrid adoption rates and Group III import tariff scenarios across the projection horizon. Segmentation modeling incorporated product chemistry, end-user procurement scale, packaging logistics economics, and application duty severity. CAGRs derived from segment-level volume trajectories weighted by base oil cost pass-through dynamics and synthetic premium realization. Forecast inputs included vehicle parc aging curves, OEM factory-fill specification shifts, and quick-lube channel throughput metrics.
Practitioners should monitor California CARB regulatory prefiguration and Pacific Northwest BEV sales penetration for early signals of passenger car lubricant demand compression. Forecasts reflect documented assumptions regarding fleet synthetic conversion rates and hybrid-optimized formulation adoption. Macroeconomic freight demand contraction, accelerated EPA Phase 3 stringency, or breakthrough battery chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Transmission Mounting Brackets Market
Powertrain
Engine Actuators Market
Powertrain
Tuning Box Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Car Active Purge Pump Market
Powertrain
Automotive Driveline Market
Powertrain
South America Automotive Market
Powertrain
EV Drivetrain Systems Market
Powertrain
Electrically Powered Hydraulic Steering Market
Powertrain
Powertrain Testing Market
Powertrain
CNG Powertrain Market
Powertrain
Fuel Injection Systems Market
Powertrain
Global Automotive Engine Belt and Hose Market