
 UAE Automotive Engine Oils Market | 2026-2036
UAE Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Automotive Engine Oils Market Analytics
API SP and ACEA C3 specification upgrades are unwinding across the UAE blender network, pulling formulation chemistry toward lower-viscosity, higher-durability base stocks. Royal Dutch Shell PLC leverages its in-house Group III+ base oil supply to secure consistent product availability across Abu Dhabi and Dubai service bays. ADNOC anchors its position through backward integration into refinery-grade feedstocks, insulating margins from imported base oil volatility. Gulf Oil International competes on distribution density, occupying a broad retail footprint that extends into secondary emirate markets.
Automotive engine oils are lubricating formulations comprising base oils and additive packages designed to reduce friction, dissipate heat, and neutralize combustion byproducts in internal combustion engines, with viscosity grades such as 5W-30 and 0W-20 representing the dominant specifications for modern passenger vehicle architectures. Synthetic product types command the premium tier as OEM fill requirements shift toward extended drain intervals, while conventional grades retain volume in older fleet segments where cost sensitivity dominates procurement decisions. The 5W-30 viscosity grade leads volume throughput across passenger vehicle service channels, though 0W-20 is gaining ground among Japanese and Korean import dealerships operating in Dubai and Sharjah.
MOHAP oversees pharmaceutical and chemical product standards that intersect with lubricant safety labeling, while the Emirates Authority for Standardization and Metrology enforces UAE-specific quality marks that restrict market access for uncertified imports. EPA-aligned emissions benchmarks for heavy-duty commercial vehicles indirectly shape engine oil specifications, as fleet operators select formulations that protect aftertreatment systems. Stakeholders must monitor how Euro 6-equivalent tailpipe regulations propagate through the UAE's commercial vehicle renewal cycle, as this will determine whether low-SAPS additive packages displace conventional high-ash chemistry in the heavy-duty segment.
Market Dynamics
The UAE Automotive Engine Oils Market pivots on synthetic formulation mandates from commercial fleet operators seeking extended drain intervals under punishing Gulf thermal loads. Emirates Authority for Standardization and Metrology certification requirements compress blender margins while elevating technical barriers for imported conventional grades.
Growth Catalysts
- API SP specification uptake:Passenger vehicle service channels in Dubai and Sharjah accelerate adoption of lower-viscosity, higher-durability chemistries to meet OEM warranty requirements.
- Logistics corridor expansion:Commercial fleet density along the Dubai-Abu Dhabi freight axis drives synthetic oil procurement for reduced vehicle downtime.
- MOHAP safety labeling convergence:Unified chemical product standards streamline lubricant import clearance and accelerate blender network modernization.
Market Restraints
- Group III+ base oil import dependency:UAE blenders remain exposed to feedstock price volatility from Asian and European refinery sources.
- Emirates Authority for Standardization and Metrology certification backlog:Extended testing timelines delay product launches for new market entrants.
- Conventional grade inventory overhang:Older fleet segments in secondary emirates resist premium synthetic conversion, trapping working capital.
Strategic Opportunities
- Ras Al Khaimah and Fujairah service bay penetration:Secondary emirate markets show synthetic underpenetration relative to Dubai benchmarks.
- 0W-20 viscosity grade expansion:Japanese and Korean import dealerships represent untapped volume for ultra-low viscosity formulations.
- Euro 6-equivalent tailpipe alignment:Anticipated commercial vehicle emissions benchmarks will mandate low-SAPS additive packages for heavy-duty protection.
Industry Challenges
- Formulation chemist scarcity:Specialized lubricant engineering talent concentrates with established blenders, constraining independent product development.
- Additive package integration complexity:Multi-functional chemistry requirements for high-temperature Gulf operating conditions extend R&D validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Automotive Engine Oils Market |
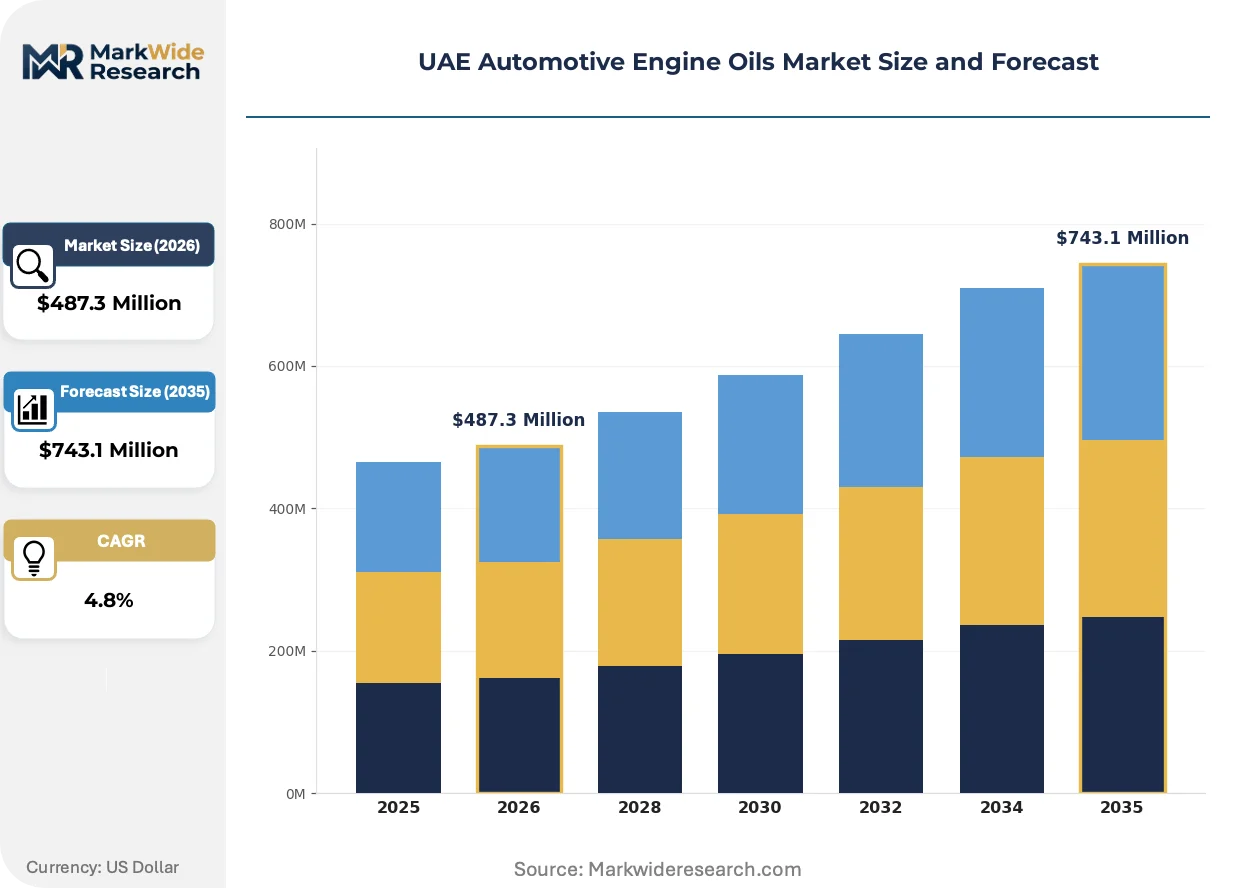
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Conventional, High-Mileage Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Additive Type: Detergents, Antioxidants, Friction Modifiers, Rust Inhibitors End User: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles |
| Companies Covered | Royal Dutch Shell PLC, ExxonMobil Corporation, ADNOC, Gulf Oil International, Emarat, Emirates Lube Oil Co. Ltd, TotalEnergies, Sharjah National Lube Oil Co. LLC (SHARLU), EPPCO Lubricants, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Automotive Engine Oils Market Evolving Landscape
Formulation chemistry across the UAE blender network is pivoting toward lower-viscosity, higher-durability architectures. Three distinct movements are compressing legacy supply models.
Group III+ synthetic base stocks are supplanting conventional mineral oils in passenger vehicle service channels. Dubai and Sharjah quick-lube operators now stock 5W-30 and 0W-20 grades as default recommendations. This chemistry shift compresses drain interval frequency and redirects aftermarket revenue toward premium product tiers.
Emirates Authority for Standardization and Metrology tightened lubricant quality benchmarks force reformulation across the blender network. The regulatory friction elevates technical compliance costs for imported conventional grades. Domestic blenders with captive laboratory certification capacity capture disproportionate shelf space in Abu Dhabi service bays.
Commercial fleet procurement now bundles lubricant supply with predictive maintenance telemetry. Large logistics operators in Dubai's Jebel Ali corridor negotiate volume contracts tied to oil analysis services. This unbundling of product from aftermarket service compresses traditional distributor margins while rewarding vertically integrated suppliers with diagnostic capabilities.
UAE Automotive Engine Oils Market Segmentation
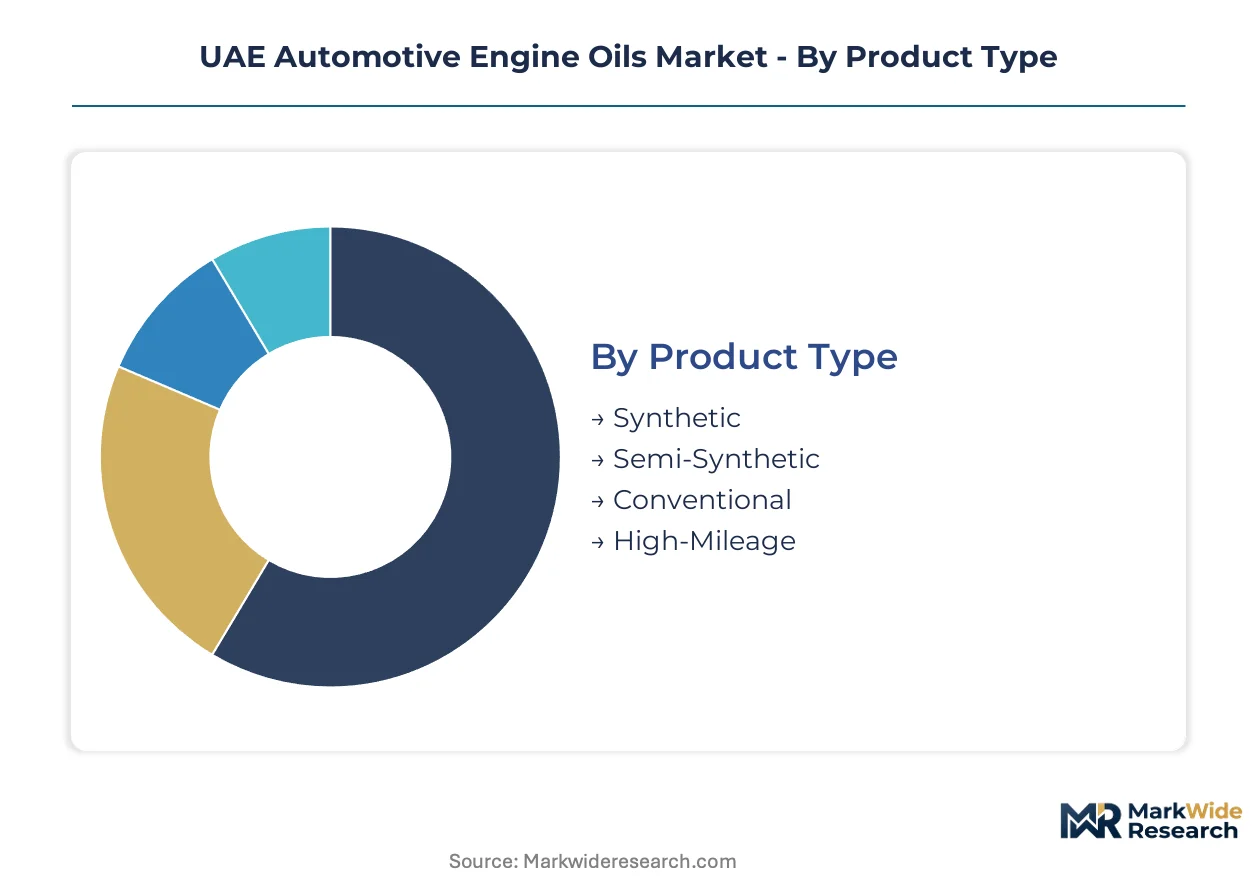
The UAE Automotive Engine Oils Market segments along four dimensions that determine channel strategy and margin structure. Product type and viscosity grade dictate formulation investment, while additive chemistry and end-user category shape procurement patterns across Dubai's service bays and secondary emirate distributors.
Product Type:
Channel mix varies sharply by product tier, with synthetic grades flowing through OEM-affiliated service centers while conventional oils dominate independent retail.
- Synthetic:Formulated from Group III+ or PAO base stocks with engineered additive packages for extended drain intervals and thermal stability under Gulf operating conditions. Dubai's logistics corridor fleets and Japanese import dealerships in Sharjah concentrate procurement here, driven by OEM warranty compliance and reduced vehicle downtime requirements.
- Semi-Synthetic:Blends mineral and synthetic base stocks offering intermediate performance at moderate price points. Volume concentrates in Abu Dhabi passenger vehicle service channels where cost-conscious consumers seek upgrade paths from conventional grades without full synthetic premiums.
- Conventional:Mineral-based formulations serving older fleet segments and price-sensitive secondary emirate markets.
- High-Mileage:Seal conditioners and anti-wear additives targeting vehicles exceeding 100,000 kilometers.
By volume, Conventional leads. By growth pace, Synthetic is expanding most quickly.
Viscosity Grade:
Cost tier stratification runs through this category, with lower viscosity grades commanding formulation premiums and higher grades serving value segments.
- 0W-20:Ultra-low viscosity synthetic formulations engineered for modern gasoline direct injection and hybrid powertrains. Japanese and Korean import dealerships in Dubai and Sharjah represent the demand concentration, as these OEMs specify 0W-20 for fuel economy and cold-start protection.
- 5W-30:The workhorse specification balancing fuel economy and high-temperature protection across diverse engine architectures. Dubai quick-lube operators and Abu Dhabi fleet service bays stock this as the default recommendation for passenger vehicles.
- 10W-40:Higher viscosity grade retaining volume in older European and domestic vehicle parc.
- 15W-50:Heavy-duty specification for high-performance and severe-service applications.
By volume, 5W-30 dominates service channel throughput. By growth pace, 0W-20 is gaining share fastest.
Additive Type:
Application-specific requirements drive additive package design, with each chemistry family addressing distinct engine protection functions.
- Detergents:Alkaline compounds neutralizing combustion acids and dispersing sludge deposits to maintain piston cleanliness. Critical for UAE's high-temperature stop-and-go driving patterns.
- Antioxidants:Phenolic and aminic compounds inhibiting base oil oxidation and viscosity thickening over extended drain intervals.
- Friction Modifiers:Organo-molybdenum and fatty acid derivatives reducing boundary friction for fuel economy gains.
- Rust Inhibitors:Polar compounds protecting ferrous surfaces from moisture corrosion during intermittent vehicle use.
By formulation spend, Detergents absorb the largest additive budget. By specification intensity, Friction Modifiers are climbing fastest.
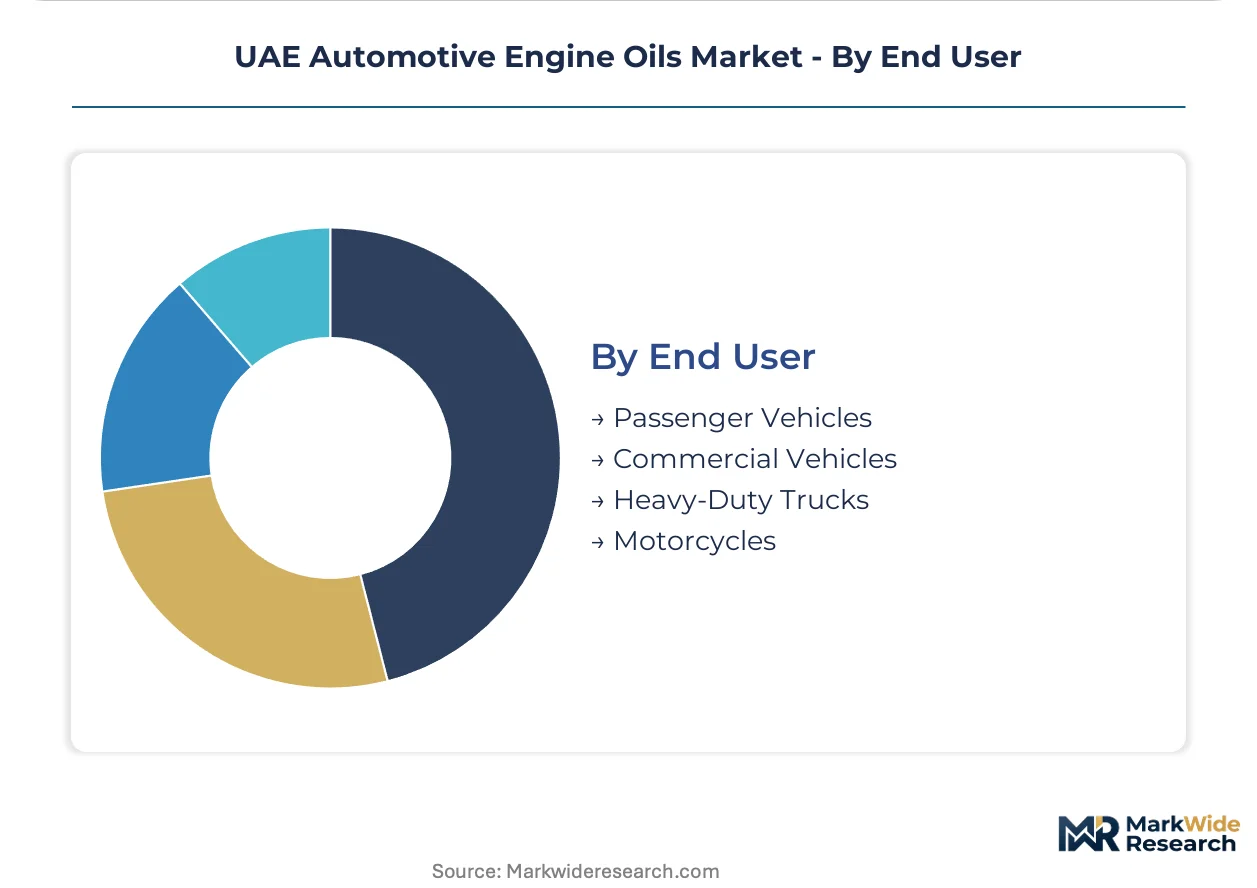
End User:
Customer type determines procurement scale and service integration, from individual retail transactions to enterprise fleet contracts.
- Passenger Vehicles:Individual owners and lease operators maintaining sedans, SUVs, and crossovers. Dubai and Sharjah quick-lube chains capture volume through convenience positioning.
- Commercial Vehicles:Light commercial fleets operating vans and pickups across urban delivery routes. Ras Al Khaimah and Fujairah show synthetic underpenetration relative to Dubai benchmarks.
- Heavy-Duty Trucks:Long-haul freight operators along the Dubai-Abu Dhabi corridor negotiating lubricant supply bundled with oil analysis services.
- Motorcycles:Two-wheeler service channels in dense urban zones with distinct wet-clutch compatibility requirements.
By volume, Passenger Vehicles dominate. By contract value concentration, Heavy-Duty Trucks are pulling ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery-grade feedstock availability clusters along the Arabian Gulf coastline, with blenders positioning formulation capacity near port infrastructure and industrial zones. Domestic base oil production insulates regional supply chains from Asian import volatility.
Dubai
Logistics corridor density drives synthetic oil procurement at scale, with Jebel Ali freight operators negotiating predictive maintenance bundles. Emirates Authority for Standardization and Metrology certification requirements accelerate blender network modernization across Dubai's service bay clusters. Quick-lube chains in Al Quoz and Deira stock 5W-30 and 0W-20 as default recommendations for Japanese and Korean import vehicles.
Abu Dhabi
Backward integration into refinery feedstocks anchors domestic blender margins against imported base oil price swings. ADNOC's captive laboratory certification capacity secures disproportionate shelf space in capital region service channels. Industrial zones around Musaffah concentrate formulation capacity serving both passenger vehicle and heavy-duty fleet segments.
Sharjah
Secondary emirate markets show synthetic underpenetration relative to Dubai benchmarks, creating upgrade pathways from conventional grades. Sharjah National Lube Oil Co. occupies established distribution infrastructure extending into northern emirate territories. Import dealership clusters along the Dubai-Sharjah corridor accelerate 0W-20 specification uptake for Korean vehicle parc.
Northern Emirates
Ras Al Khaimah and Fujairah service bays retain conventional grade inventory overhangs where cost sensitivity dominates older fleet procurement. Extended testing timelines for Emirates Authority for Standardization and Metrology certification delay product launches for new market entrants in these territories. Secondary logistics routes connecting to Oman border crossings concentrate heavy-duty truck service demand.
UAE Automotive Engine Oils Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UAE blender network. Vertically integrated national oil companies command feedstock security and laboratory certification capacity, while international majors leverage global formulation libraries and brand equity in premium service channels. Three archetypes dominate: refinery-integrated domestic producers, multinational lubricant specialists with regional blending assets, and independent distributors competing on retail footprint density. Competitive moves center on backward integration into base oil supply and predictive maintenance service bundling for fleet contracts.
Among multinational lubricant specialists, Royal Dutch Shell PLC and ExxonMobil Corporation exemplify technology-forward positioning through in-house Group III+ base oil access and OEM warranty alignment. ADNOC represents the refinery-integrated archetype, anchoring domestic supply security through captive feedstock production and Emirates Authority for Standardization and Metrology certification infrastructure. Gulf Oil International occupies the distribution-density tier, extending retail presence into secondary emirate markets where synthetic conversion remains incomplete.
| Leading Market Players |
|---|
| Royal Dutch Shell PLC |
| ExxonMobil Corporation |
| ADNOC |
| Gulf Oil International |
| Emarat |
| Emirates Lube Oil Co. Ltd |
| TotalEnergies |
| Sharjah National Lube Oil Co. LLC (SHARLU) |
| EPPCO Lubricants |
| Others |
Value Network & Pricing Analysis
Emirates Authority for Standardization and Metrology certification requirements gate both supply qualification and price differentiation simultaneously, compressing margins for uncertified imports while elevating premiums for laboratory-validated formulations across Abu Dhabi and Dubai service channels.
Pricing Analysis
Emirates Authority for Standardization and Metrology dictates the pricing tier structure across the UAE blender network. Pricing stratifies across premium synthetic, semi-synthetic, and conventional mineral tiers based on base oil grade and certification mark possession. Cost compression in conventional grades is intensifying because older fleet segments in Ras Al Khaimah and Fujairah resist synthetic conversion. Commercial fleet operators show least price sensitivity due to downtime cost calculus, while independent retail channels in secondary emirates exhibit highest sensitivity.
Supply Chain Analysis
South Korea and Singapore anchor Group III+ base oil production for UAE blenders seeking synthetic feedstock security. Formulation chemistry draws from polyalphaolefin stocks, detergent additive packages, and viscosity modifier polymers. Single-source vulnerability concentrates in Asian refinery supply for premium base stocks. Distribution runs through Jebel Ali port consolidation points into quick-lube chains, OEM-affiliated service centers, and secondary emirate distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from predictive maintenance telemetry bundling that unbundles product from service revenue, requiring defensive repositioning around diagnostic capabilities.
For Market Incumbents: Fortify captive laboratory certification capacity to secure shelf space in Emirates Authority for Standardization and Metrology-regulated channels. Deepen upstream control over Group III+ base oil supply to insulate margins from Asian refinery volatility. Expand predictive maintenance service bundling to defend against telemetry-based fleet procurement models eroding traditional distributor margins.
For New Entrants and Emerging Players: Differentiate on ultra-low viscosity 0W-20 formulations targeting Japanese and Korean import dealerships in Sharjah where specification penetration lags Dubai benchmarks. Penetrate Ras Al Khaimah and Fujairah service bays through conventional-to-synthetic upgrade programs. Pursue white-label supply agreements with quick-lube chains seeking certified product without blender network investment.
For Investors and Strategic Acquirers: Euro 6-equivalent tailpipe alignment reshapes the acquisition landscape toward low-SAPS additive package capabilities. Long-term viability centers on blenders with backward integration into refinery feedstocks and captive certification infrastructure. Target domestic producers with laboratory assets and distribution density in secondary emirates. Monitor commercial vehicle emissions regulation timing as inflection signal for heavy-duty formulation demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | ADNOC's captive refinery feedstock production insulates margins from import price swings. |
| Laboratory Certification Capacity Expansion | Domestic blenders with in-house Emirates Authority for Standardization and Metrology testing secure faster product launches. |
| Predictive Maintenance Service Bundling | Jebel Ali fleet operators now negotiate lubricant contracts tied to oil analysis telemetry. |
| Ultra-Low Viscosity Formulation Investment | 0W-20 chemistry captures Japanese and Korean import dealership specifications in Dubai and Sharjah. |
| Secondary Emirate Distribution Buildout | Synthetic underpenetration in Ras Al Khaimah and Fujairah creates upgrade pathway volume. |
Research Methodology
Desk research of trade customs records, refinery output disclosures, and Emirates Authority for Standardization and Metrology certification registries preceded structured interviews with lubricant blenders, quick-lube chain procurement managers, fleet maintenance directors, and additive package suppliers. Primary fieldwork across Dubai, Abu Dhabi, and Sharjah service channels combined with secondary validation from base oil import manifests and OEM technical service bulletins. Bottom-up volume estimates triangulated against top-down market sizing from production and trade flow analysis.
Variance decomposition across product type, viscosity grade, additive chemistry, and end-user category shaped the analytical framework over the projection horizon. Modeled dimensions included synthetic penetration rates, specification upgrade velocities, and fleet contract structures. CAGRs derived from segment-level growth trajectories weighted by base year volume shares. Forecast inputs incorporated thermal load severity indices for Gulf operating conditions and commercial vehicle parc renewal cycles.
The analysis sits within stated boundaries; outcomes outside sustained synthetic conversion momentum or accelerated emissions regulation timelines would require recalibration. Forecasts reflect assumptions about certification backlog resolution and base oil import price stability. Specific risks include extended Emirates Authority for Standardization and Metrology testing delays and Asian refinery supply disruptions. Recalibration cycles align with material shifts in regulatory enforcement intensity and fleet procurement contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Fuel Injection Pump Market
Powertrain
Diesel Engine Catalyst Market
Powertrain
Japan Electro Hydraulic Power Steering Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Automotive Brake Booster Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Turbine Housing for Automobile Market
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Automotive Cylinder Block Market
Powertrain
Powertrain Domain Control Unit Platforms Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Transmission Shift Actuator Market
Powertrain
Automatic Transmission Solenoid Pack Market
Powertrain
Steering Damper Market
Powertrain
Transmission Control System Market