
 Transmission Oil Pumps Market | 2026-2036
Transmission Oil Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission Oil Pumps Market Outlook
China is reconfiguring its transmission component supply base through state-backed capacity expansion in Jiangsu and Zhejiang provinces. Denso Corporation leverages its integrated motor-pump systems to anchor hybrid transmission programs across East Asian OEM supply chains. Continental AG competes through precision gear pump specialization for dual-clutch architectures. BorgWarner Inc. extends its variable displacement vane pump technology to serve electrified drivetrain thermal management requirements.
Transmission oil pumps are positive displacement or dynamic fluid machines engineered to circulate lubricating oil at pressures typically ranging from 2 to 20 bar through automatic transmission valve bodies, torque converters, and cooling circuits. Gear pumps dominate current volume production due to their cost-efficient two-lobe or three-lobe rotor designs and tolerance for transmission fluid contamination, though vane pumps are capturing structural margin in premium applications requiring variable flow control. The end user landscape shows automotive OEMs commanding the largest value pool through captive sourcing, while aftermarket providers occupy a fragmented but profitable channel serving aging automatic transmission fleets.
EPA fuel economy standards and NHTSA safety regulations in the United States are compelling pump manufacturers to reduce parasitic losses through electronically controlled variable displacement architectures. China's MIIT dual carbon goals and GB/T energy efficiency standards are tightening domestic sourcing requirements for transmission subsystems. India's BIS automotive component certification and PLI scheme for advanced automotive technology are reshaping supplier qualification thresholds. Stakeholders must monitor how electrification transitions redefine fluid circuit architectures across hybrid, PHEV, and dedicated EV platforms.
Market Dynamics
Electrification of drivetrains is fragmenting fluid circuit architectures, forcing pump suppliers to engineer for thermal management in hybrid systems rather than conventional automatic transmission lubrication alone.
Growth Catalysts
- ECE Regulation Lubrication Efficiency Mandates:Germany's passenger vehicle electrification programs are tightening efficiency benchmarks for transmission subsystems, compelling OEMs to specify higher-performance pump architectures.
- Integrated Pump Architectures:China's MIIT mandates are accelerating demand for consolidated motor-pump systems in domestic automatic transmissions, reducing component count and assembly complexity.
- Tamil Nadu Sourcing Localization:India's automotive corridor is deepening captive procurement relationships, creating pull-through demand for regionally manufactured transmission oil pumps.
Market Restraints
- Specialized Alloy Input Volatility:Precision gear pump manufacturing depends on controlled-grade steel alloys subject to commodity price swings and import dependency in several production regions.
- Technical Limitation in Contamination Tolerance:Variable displacement vane pumps offer flow control advantages but demonstrate reduced durability in transmission fluid environments with elevated particulate loads.
- Substitution Threat from Dry Clutch Architectures:Electrified drivetrain designs are eliminating torque converter circuits entirely, removing the primary lubrication load in dedicated EV platforms.
Strategic Opportunities
- Underpenetrated Thermal Management Applications:Battery electric vehicle cooling circuits represent an adjacent white space where pump suppliers can redeploy existing vane and gear pump expertise.
- Regulatory Tailwind from PLI Scheme:India's production-linked incentive scheme for advanced automotive technology is subsidizing capital investment in component localization, qualifying transmission pump manufacturing.
- Technology Convergence of Electronics and Hydraulics:Electronically controlled variable displacement architectures are opening margin expansion through software-enabled flow optimization and predictive maintenance integration.
Industry Challenges
- Electromechanical Systems Integration Complexity:Combining motor drives with hydraulic pumps requires cross-functional expertise spanning power electronics, fluid dynamics, and embedded control systems that remains scarce in traditional pump engineering teams.
- Dual Certification Timeline Compression:Suppliers must simultaneously qualify for automotive OEM production part approval processes and emerging EV thermal management standards, stretching validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission Oil Pumps Market |
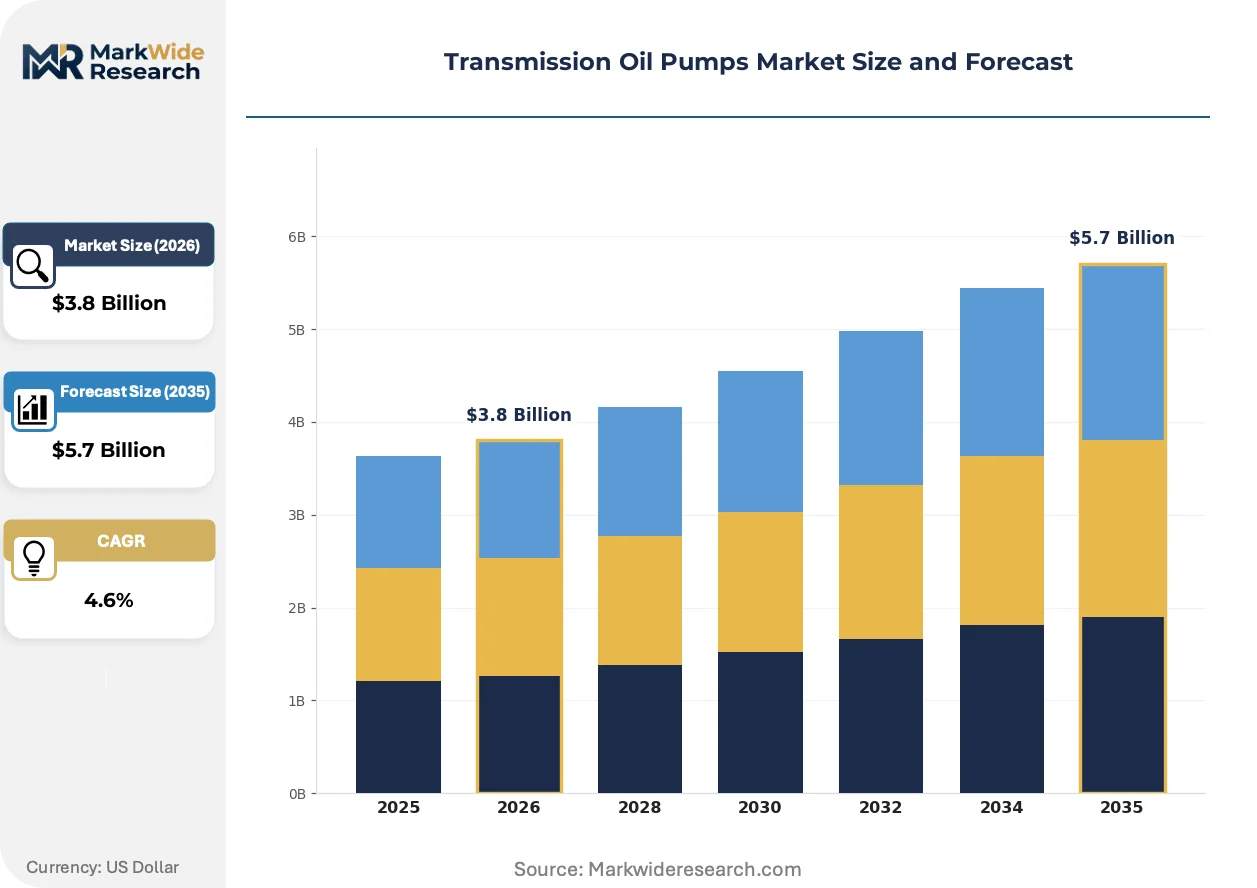
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Pump, Vane Pump, Screw Pump, Piston Pump End User: Automotive OEMs, Aftermarket Providers, Commercial Vehicles, Industrial Equipment Installation Type: Integrated, Standalone, Mobile, Fixed Distribution Channel: Direct Sales, Online Retail, Authorized Dealers, Wholesalers |
| Companies Covered | Denso Corporation, Continental AG, Aisin Corporation, Nidec Corporation, BorgWarner Inc., Bosch, Magna International, ZF Friedrichshafen, Schaeffler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission Oil Pumps Market Strategic Shifts
Active materials and control architectures are redefining what constitutes a transmission pump, with mechanical simplicity giving way to electromechanical sophistication across the product spectrum.
Electronically actuated variable displacement vane pumps are rendering obsolete fixed-output gear pump dominance in premium drivetrain applications. Hybrid transmission programs across East Asian OEM supply chains are specifying these architectures for their parasitic loss reduction capabilities. The technology is compressing supplier margins in commodity gear pump segments while opening value capture in integrated system design.
EPA fuel economy standards and NHTSA safety regulations in the United States are compelling pump manufacturers to reduce parasitic losses through electronically controlled variable displacement architectures. The industrial consequence is accelerated R&D allocation toward motor-pump integration and smart control algorithms. Passenger vehicle OEMs serving the US market are responding by qualifying suppliers with demonstrated electrification program experience.
Buyer concentration among automotive OEMs is consolidating sourcing decisions into fewer platform engineering teams with cross-regional authority. Tier-1 suppliers are losing direct specification influence as OEM captive engineering groups internalize pump selection criteria. This pattern is most visible in Germany and Japan, where drivetrain platform decisions now route through centralized electrification strategy committees rather than regional procurement offices.
Transmission Oil Pumps Market Segmentation
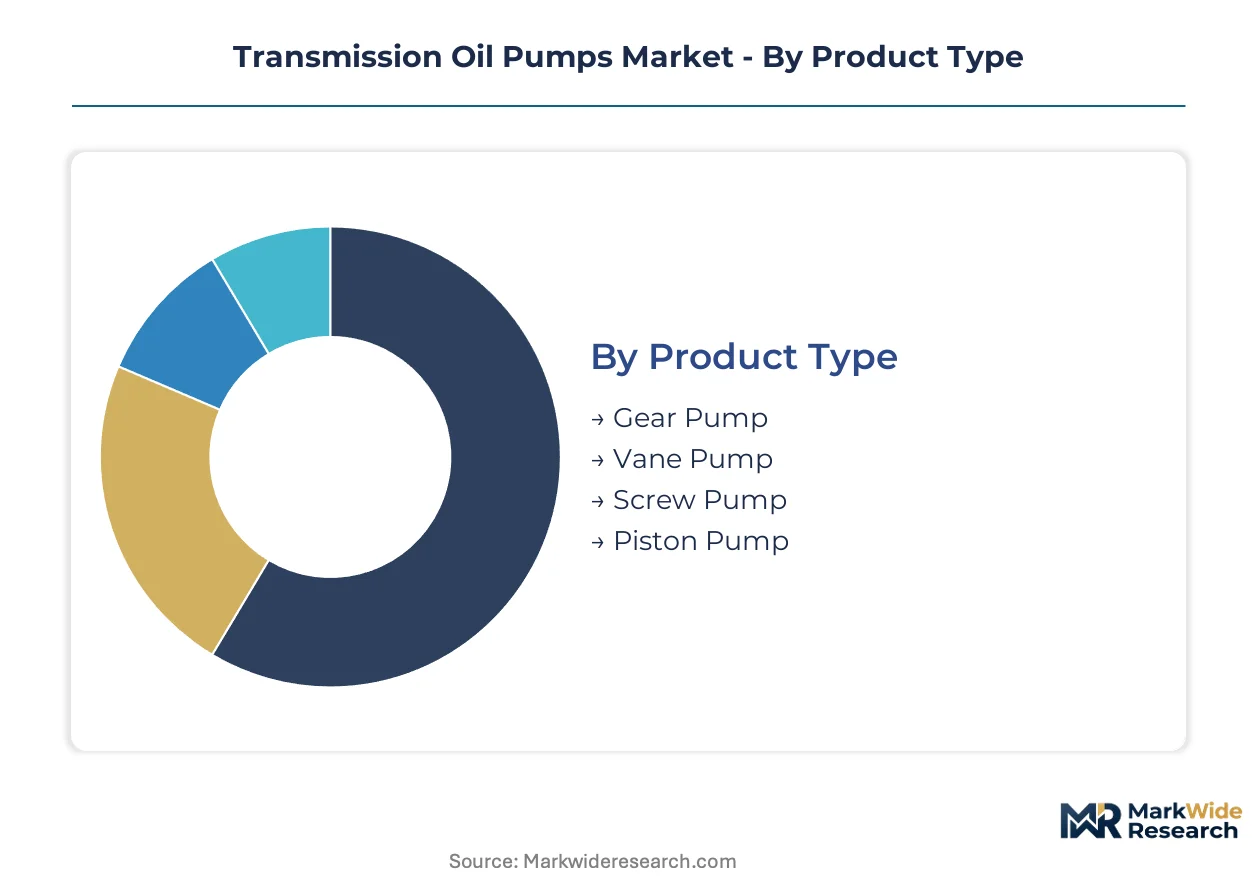
Transmission oil pump architectures fragment across multiple technical and commercial dimensions. Understanding these partitions reveals where value concentrates and how electrification is redrawing category boundaries.
Product Type:
Cost tier differentiation separates commodity displacement mechanisms from precision variable-flow architectures commanding premium positioning.
- Gear Pump:Two-lobe and three-lobe rotor designs deliver cost-efficient positive displacement with tolerance for contaminated transmission fluid. Demand concentrates in India's Tamil Nadu automotive corridor where OEM sourcing localization prioritizes proven durability over flow control sophistication.
- Vane Pump:Variable displacement architectures enable electronically controlled flow modulation, reducing parasitic losses in hybrid drivetrain thermal management. China's MIIT dual carbon mandates are accelerating specification of these systems in domestic automatic transmission programs.
- Screw Pump:Axial and twin-screw configurations handle high-viscosity lubricants with minimal pulsation, serving heavy-duty commercial vehicle applications requiring continuous duty cycles.
- Piston Pump:Radial and axial piston designs deliver precise pressure control for advanced dual-clutch transmission architectures, though manufacturing complexity limits volume penetration.
Gear pump holds installed capacity. Vane pump is rotating up the share rankings.
End User:
Customer type determines procurement authority, with captive OEM engineering groups displacing tier-1 supplier influence in specification decisions.
- Automotive OEMs:Platform engineering teams with cross-regional authority now internalize pump selection criteria, consolidating sourcing decisions into centralized electrification strategy committees. Germany's ECE regulation lubrication efficiency mandates are tightening specification thresholds for transmission subsystems.
- Commercial Vehicles:Fleet operators prioritize total cost of ownership metrics, driving demand for extended-service-interval pump architectures in long-haul and vocational applications.
- Aftermarket Providers:Fragmented channel serving aging automatic transmission fleets captures profitable replacement demand as vehicle parc ages in North American and European markets.
- Industrial Equipment:Off-highway machinery and material handling systems require ruggedized pump designs with enhanced sealing for multi-shift operating environments.
Automotive OEMs command specification authority. Commercial vehicles are expanding most quickly as fleet electrification creates thermal management requirements.
Installation Type:
Application context dictates whether pump systems integrate with motor drives or maintain mechanical independence from powertrain electronics.
- Integrated:Motor-pump consolidation reduces component count and assembly complexity, aligning with China's MIIT mandates for domestic automatic transmission architecture simplification. Denso Corporation anchors hybrid transmission programs across East Asian OEM supply chains with these systems.
- Standalone:Conventional mechanical drive configurations persist in cost-sensitive applications where electrification penetration remains limited.
- Mobile:Portable hydraulic power units for service and diagnostic applications require compact, self-contained pump modules.
- Fixed:Stationary transmission test benches and manufacturing line equipment utilize permanent-mount pump installations with dedicated cooling infrastructure.
Integrated holds installed capacity. Mobile is climbing the fastest as field service electrification expands.
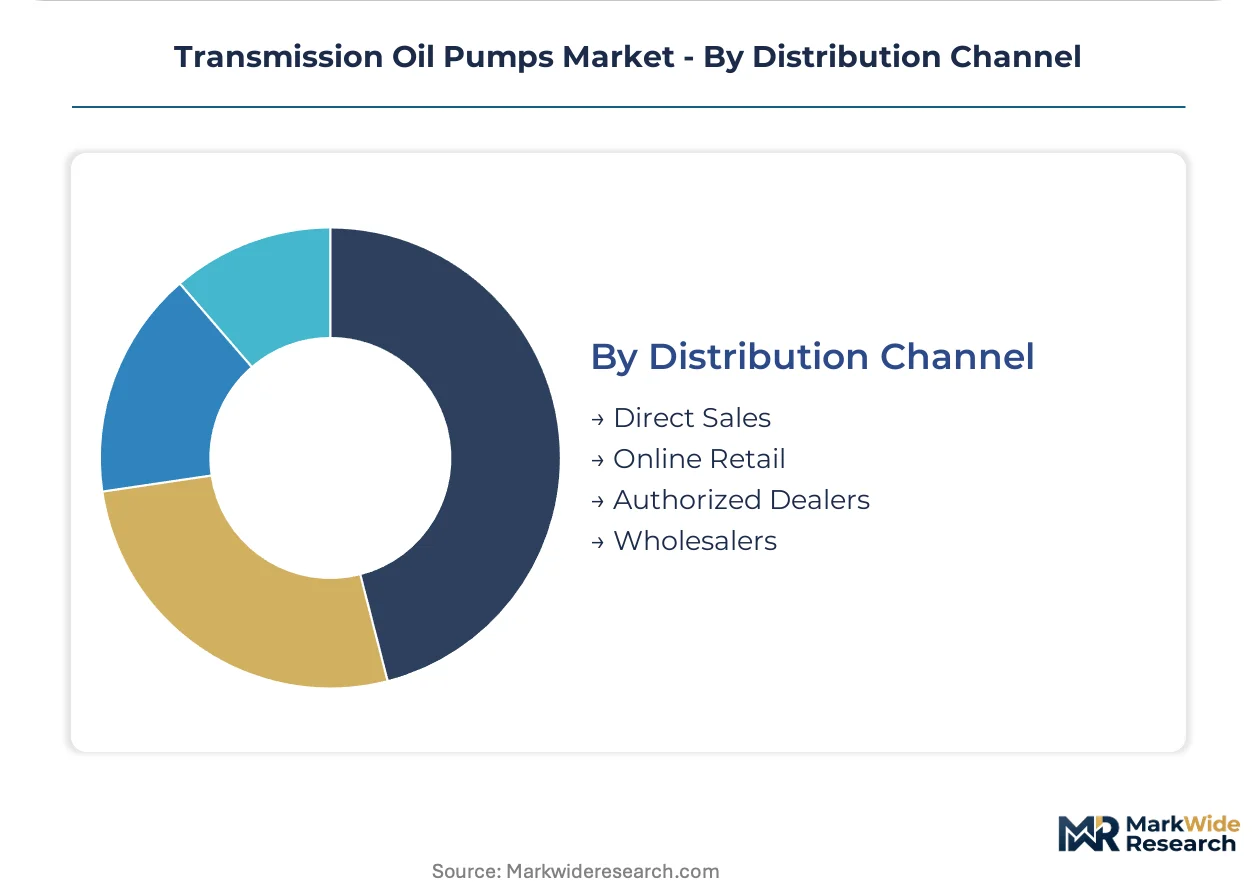
Distribution Channel:
Supply concentration patterns vary sharply between direct OEM procurement and fragmented aftermarket intermediation.
- Direct Sales:OEM captive sourcing relationships dominate value capture, with platform engineering teams negotiating multi-year supply agreements. India's PLI scheme for advanced automotive technology is subsidizing capital investment qualifying transmission pump manufacturing for direct OEM qualification.
- Authorized Dealers:Branded distribution networks maintain technical support capabilities for complex variable displacement system installation and calibration.
- Wholesalers:Volume intermediaries serve independent repair facilities with standardized gear pump replacements for legacy automatic transmission fleets.
- Online Retail:Digital channels are gaining traction for standardized aftermarket components, though technical complexity limits penetration in integrated system categories.
Direct sales holds installed capacity. Online retail is gaining share fastest as catalog standardization progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transmission oil pump consumption patterns diverge sharply by geography. Germany prioritizes precision variable-flow architectures for hybrid drivetrains. China and India favor cost-optimized gear pump designs for volume automatic transmission production.
United States
EPA fuel economy standards and NHTSA safety regulations compel pump manufacturers to reduce parasitic losses through electronically controlled variable displacement architectures. Domestic OEMs are qualifying suppliers with demonstrated electrification program experience. Detroit's automotive engineering corridor is consolidating platform decisions into centralized electrification strategy committees.
Germany
ECE regulation lubrication efficiency mandates are tightening specification thresholds for transmission subsystems in passenger vehicle electrification programs. KBA enforces type approval requirements that favor precision gear pump specialization for dual-clutch architectures. Stuttgart and Munich engineering clusters are deepening captive procurement relationships with integrated motor-pump system providers.
China
MIIT dual carbon goals and GB/T energy efficiency standards are accelerating demand for consolidated motor-pump systems in domestic automatic transmission programs. State-backed capacity expansion in Jiangsu and Zhejiang provinces is reconfiguring the transmission component supply base. Shanghai-based OEM engineering groups are internalizing pump selection criteria for hybrid platform programs.
India
BIS automotive component certification and the PLI scheme for advanced automotive technology are reshaping supplier qualification thresholds for transmission pump manufacturing. Tamil Nadu's automotive corridor is deepening captive procurement relationships with regionally manufactured gear pump suppliers. Chennai-based OEM sourcing offices are prioritizing proven durability over flow control sophistication.
Japan
METI industrial policy frameworks support hybrid transmission technology development requiring precision thermal management components. JIS standards govern automotive fluid power system interoperability. Nagoya and Tokyo metropolitan engineering centers are specifying integrated motor-pump architectures for East Asian OEM supply chain programs.
Transmission Oil Pumps Market Competitive Environment
Capability concentration sits with integrated system architects; scale advantage sits with precision component specialists. The vendor base organizes around three tiers: multinational drivetrain suppliers with captive pump divisions, independent hydraulic component specialists, and regional fabricators serving cost-sensitive replacement markets. Dominant competitive moves include backward integration into motor-drive electronics and strategic partnerships for thermal management system co-development.
Among Japan-based integrated system architects, Denso Corporation and Nidec Corporation occupy positions exemplifying electromechanical convergence. Germany's Continental AG and ZF Friedrichshafen represent the precision component specialist tier with heritage in automotive hydraulic systems. These four entities anchor the competitive structure across hybrid drivetrain electrification programs in their respective home markets.
| Leading Market Players |
|---|
| Denso Corporation |
| Continental AG |
| Aisin Corporation |
| Nidec Corporation |
| BorgWarner Inc. |
| Bosch |
| Magna International |
| ZF Friedrichshafen |
| Schaeffler Group |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Ningbo port corridor's container freight volatility feeds directly into landed cost spreads between gear pump suppliers in Jiangsu province and vane pump fabricators in Stuttgart engineering clusters, compressing margin buffers for commodity-grade suppliers while amplifying pricing power for integrated motor-pump system architects serving hybrid transmission programs.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between automotive OEM platform teams and Tier-1 pump suppliers, insulating precision component specialists from spot market alloy price swings while exposing commodity gear pump fabricators to raw material pass-through volatility. Price differentiation hinges on ISO/TS 16949 certification tier and volume scale commitments, with electrified drivetrain thermal management systems commanding premium positioning over legacy automatic transmission lubrication architectures. Pricing pressure stems from China's MIIT dual carbon mandates accelerating domestic sourcing consolidation, forcing margin compression in non-integrated supply tiers. Fleet operators and aftermarket distributors exhibit highest price sensitivity, whereas captive OEM engineering groups prioritize flow control sophistication over unit cost minimization.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities anchor working capital structures for precision gear pump manufacturers in Germany and integrated motor-pump assemblers in Japan, while Jiangsu and Zhejiang province fabricators operate on cash-advance terms with steel alloy distributors. Controlled-grade steel alloys, rare-earth magnet components for motor integration, and specialized bearing assemblies constitute critical input dependencies. Single-source vulnerability concentrates in precision-machined rotor supplies from specialized German tooling houses. Distribution runs through OEM captive procurement channels for integrated systems, with independent aftermarket wholesalers handling legacy gear pump replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification of drivetrain architectures constitutes a high-growth disruption, with EPA fuel economy standards and China's MIIT dual carbon goals eliminating fixed-displacement pump specifications from premium platform programs within the analysis window.
For Market Incumbents: Build switching-cost moats through embedded software control algorithms and predictive maintenance integration that locks OEM platform engineering teams into multi-year thermal management system partnerships. Deepen backward integration into rare-earth magnet supply chains to insulate motor-pump consolidation programs from commodity volatility. Denso Corporation's hybrid transmission anchoring across East Asian OEM supply chains exemplifies this defensive posture against emerging electromechanical specialists. For New Entrants and Emerging Players: Pursue battery electric vehicle cooling circuit applications as the most penetrable white space, redeploying existing vane and gear pump expertise toward thermal management architectures where incumbent automotive hydraulic specialists lack established specification relationships. Target India's Tamil Nadu automotive corridor for capital-efficient manufacturing qualification under the PLI scheme for advanced automotive technology. Lead with software-enabled flow optimization capabilities to differentiate from mechanical-only legacy suppliers. For Investors and Strategic Acquirers: Electromechanical convergence specialists with demonstrated motor-drive electronics integration and automotive OEM program qualification represent the priority acquisition archetype for exposure to hybrid drivetrain content expansion. Long-term viability centers on thermal management system addressability across PHEV, BEV, and fuel cell platforms rather than legacy automatic transmission lubrication dependence. Monitor EPA and MIIT regulatory acceleration timelines as the critical inflection signal for integrated system specification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Motor-Pump Integration Investment | Captures MIIT-mandated architecture simplification demand in domestic Chinese automatic transmission programs. |
| Software-Defined Flow Control Development | Enables parasitic loss reduction qualifying suppliers for EPA fuel economy compliance pathways. |
| Tamil Nadu Manufacturing Localization | Qualifies for India's PLI scheme subsidies while deepening OEM captive procurement relationships. |
| Rare-Earth Magnet Supply Agreement | Secures input cost predictability for integrated motor-pump system cost competitiveness. |
| Thermal Management System Partnership | Extends specification authority from transmission lubrication into adjacent BEV battery cooling circuits. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineering directors, Tier-1 supplier procurement leads, aftermarket distribution channel managers, and thermal management system R&D heads, then refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed drivetrain suppliers, and MIIT regulatory disclosure archives. Bottom-up segment sizing triangulated against top-down macroeconomic anchoring to ensure internal consistency across regional demand projections.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning pump architecture type, propulsion system integration depth, vehicle class content per unit, OEM captive versus aftermarket channel, and regional production cluster concentration. CAGRs were derived from installed base evolution, replacement cycle compression, and electrification penetration curves specific to hybrid transmission thermal management requirements.
Sensitivities concentrate around EPA regulatory acceleration, MIIT dual carbon timeline adjustments, and rare-earth supply disruption scenarios. Forecasts embody documented assumptions regarding electrification adoption velocity and alloy price normalization. Macroeconomic contraction, regulatory delay, or breakthrough solid-state thermal management technologies would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
Global Automotive Tappet Market
Powertrain
Fuel Injection Systems Market
Powertrain
Axle Shaft Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Timing Chain and Belt Market
Powertrain
Japan Electro Hydraulic Power Steering Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Automotive Hydrostatic Fan Drive System Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Fuel Cell Powertrain Market
Powertrain
Mexico Electrically Powered Hydraulic Steering Market
Powertrain
Small Gas Engine Market
Powertrain
North America Torque Vectoring Market
Powertrain
North America Precision Gearbox Market