
 UK Freight Forwarding Market | 2026-2036
UK Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
UK Freight Forwarding Market Insights
The EU Green Deal is restructuring carbon accountability across UK-EU trade corridors. Kuehne + Nagel leverages its digital booking platforms to manage emissions reporting for shippers. DHL Global Forwarding anchors its UK operations around pharmaceutical cold-chain certification. DB Schenker competes through multimodal rail-sea corridors into continental Europe.
Freight forwarding encompasses the coordination of cargo movement across international borders through carrier negotiation, customs brokerage, and documentation management, typically governed by FIATA-standard bills of lading and Incoterms 2020 rules. Sea freight dominates UK-EU volume flows but faces margin compression from fuel surcharge volatility, while pharmaceutical applications command premium pricing due to GDP-compliant temperature validation requirements. Online platforms for direct booking are displacing traditional freight broker intermediaries in the SME customer segment.
HM Revenue and Customs enforces the UK Global Tariff and post-Brexit rules of origin declarations, while the UK's Medicines and Healthcare products Regulatory Agency mandates GDP standards for pharmaceutical shipments. The Driver and Vehicle Standards Agency enforces cabotage and drivers' hours rules affecting road freight capacity. Stakeholders must monitor how the UK's developing border operating model and potential alignment shifts with EU customs systems reshape routing economics and compliance costs.
Market Dynamics
Post-Brexit customs restructuring is fragmenting established UK-EU trade corridors and forcing freight forwarders to rebuild compliance infrastructure around the UK Global Tariff and rules of origin declarations. This regulatory rupture is redrawing routing economics and carrier relationships.
Growth Catalysts
- E-commerce cross-border expansion:Online retailers are scaling international fulfillment networks, creating sustained demand for customs brokerage and last-mile coordination services.
- GDP pharmaceutical certification:Temperature-validated cold-chain requirements for biologics and vaccines are commanding premium forwarding margins.
- EU Green Deal carbon accounting:Emissions reporting mandates are driving shipper demand for forwarders with verified calculation and offset capabilities.
Market Restraints
- Fuel surcharge volatility:Marine fuel price swings are compressing sea freight margins and destabilizing contract pricing.
- Driver capacity constraints:DVSA enforcement of cabotage and hours rules is limiting road freight availability on UK-EU lanes.
- Customs documentation burden:Post-Brexit border operating model requirements are inflating administrative overhead per shipment.
Strategic Opportunities
- Northern Ireland protocol specialization:Distinct customs arrangements create arbitrage potential for forwarders mastering dual-regime compliance.
- Rail-sea multimodal corridors:DB Schenker and competitors are building continental European connectivity bypassing Channel congestion.
- SME digital platform access:Direct booking interfaces are capturing small shipper segments previously served by traditional brokers.
Industry Challenges
- Customs broker talent scarcity:Specialized expertise in UK Global Tariff classification and origin determination is concentrated among veteran practitioners.
- Legacy system integration:Established forwarders face friction connecting mainframe-based operations to API-driven customer platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Freight Forwarding Market |
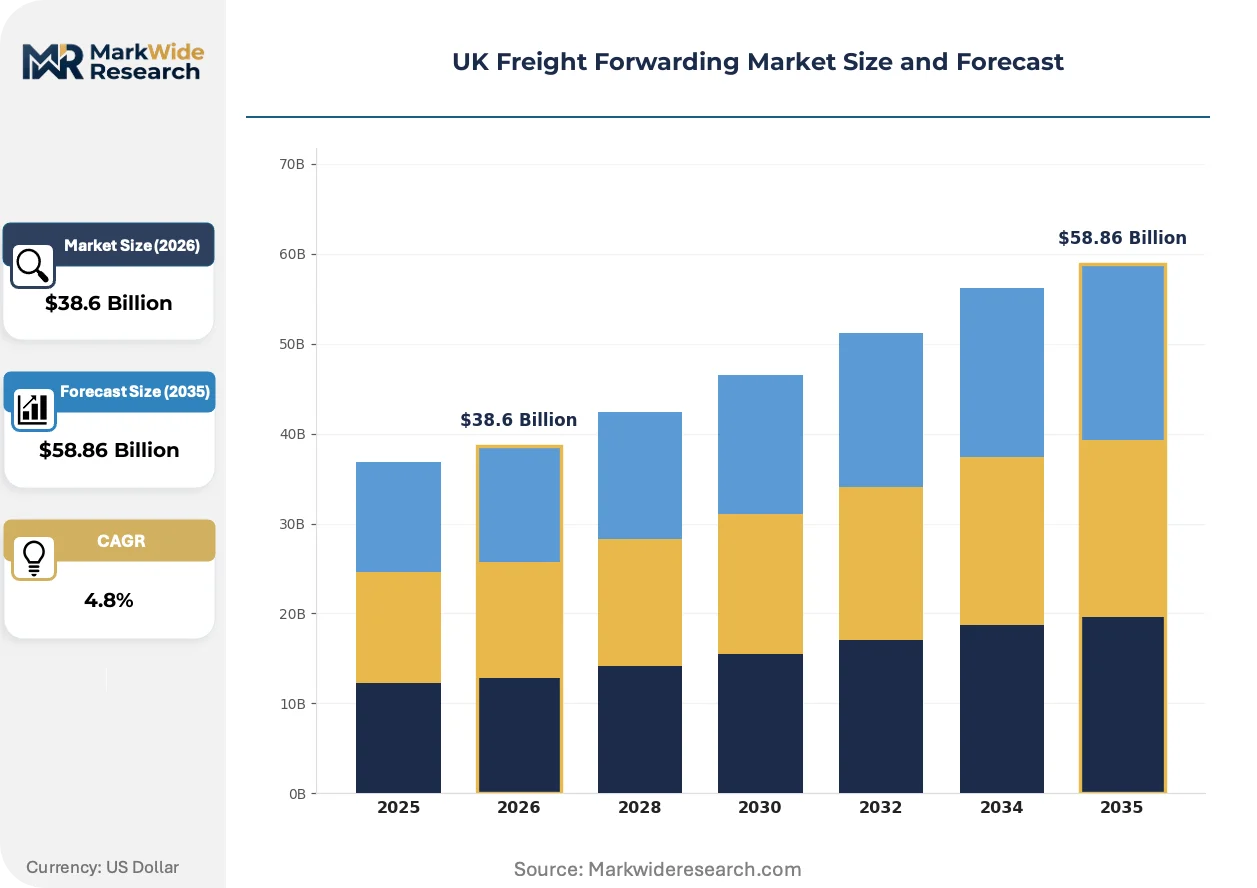
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Sea Freight, Road Freight, Rail Freight, Multimodal Transport Customer Type: Manufacturers, Retailers, Wholesalers, Exporters, Importers Distribution Channel: Direct Booking, Online Platforms, Freight Brokers, Logistics Agents, Third-Party Providers Application: Perishable Goods, Industrial Equipment, Consumer Electronics, Automotive Components, Pharmaceuticals |
| Companies Covered | Kuehne + Nagel, DHL Global Forwarding, DB Schenker, CEVA Logistics, Barrington Freight, Hemisphere Freight Services, Spatial Global, Mango Logistics Group, Maersk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Freight Forwarding Market Trends and Innovations
Digital automation and sustainability mandates are converging to reshape how UK freight forwarders compete, with platform-based booking and emissions transparency becoming baseline requirements rather than differentiators.
Blockchain-enabled documentation is overtaking paper-based bills of lading and customs declarations. Pharmaceutical and automotive shippers are adopting distributed-ledger verification for chain-of-custody compliance. This technology is overtaking traditional notarization and reducing dispute resolution cycles from weeks to hours.
HM Revenue and Customs' phased border operating model is mandating pre-arrival declaration systems and trusted trader accreditation. The industrial consequence is a bifurcation between accredited forwarders with fast-track clearance and non-accredited operators facing inspection delays. Pharmaceutical and perishable segments are prioritizing accredited partners to protect shelf-life and clinical trial schedules.
Direct platform booking by SME shippers is fragmenting the traditional broker-intermediary channel. Online quotation and booking interfaces are displacing relationship-based procurement for shipments under container-load thresholds. This behavioral shift is most visible among e-commerce retailers and light manufacturing exporters in the Midlands and South East England clusters.
UK Freight Forwarding Market Segmentation
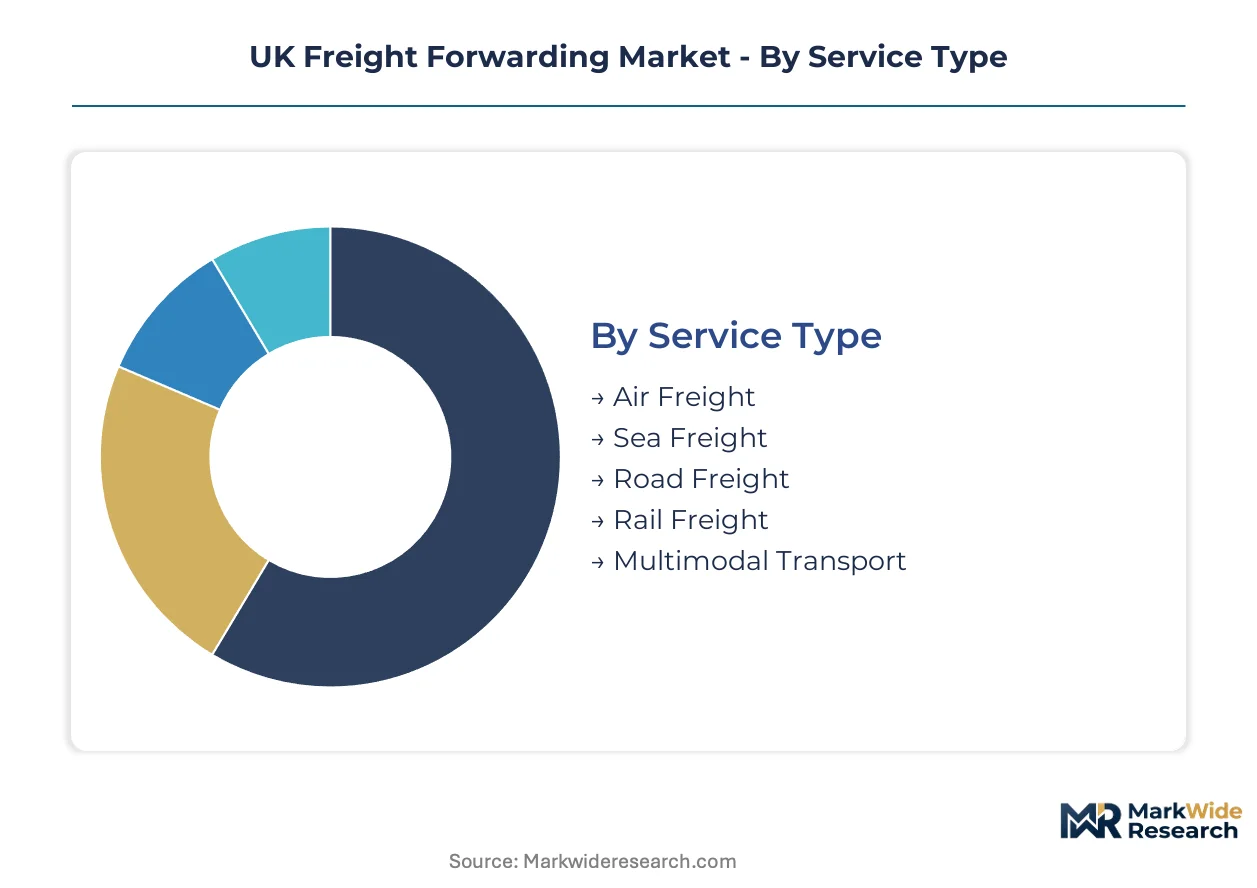
Freight forwarding segmentation reveals how shippers prioritize speed, cost, and compliance differently across cargo types. Understanding these splits allows forwarders to align service tiers with margin profiles and regulatory exposure.
Service Type:
Shippers select transport modes based on cargo value density and time sensitivity rather than pure rate comparison.
- Air Freight:High-velocity transport for time-critical shipments requiring controlled transit windows. Pharmaceutical cold-chain and automotive just-in-time parts concentrate demand here, with GDP certification and temperature validation commanding premium positioning.
- Sea Freight:Containerized bulk movement dominates UK-EU volume flows despite fuel surcharge volatility. Industrial equipment and consumer goods shippers absorb longer lead times to capture unit cost advantages on heavy or non-urgent cargo.
- Road Freight:Flexible point-to-point distribution across Channel crossings and domestic UK networks. DVSA enforcement of cabotage and drivers' hours rules constrains capacity availability on key corridors.
- Rail Freight:Intermodal trunk haulage connecting UK terminals to continental European hubs. DB Schenker and competitors leverage rail-sea combinations to bypass Channel Tunnel congestion and road border delays.
- Multimodal Transport:Integrated carrier combinations optimizing cost-time trade-offs across legs. Brexit-related customs fragmentation accelerates demand for forwarders orchestrating mode switches at UK border points.
Sea Freight leads on scale; Multimodal Transport leads on momentum.
Customer Type:
Procurement sophistication varies sharply across buyer categories, with direct shippers demanding API integration and smaller traders accepting broker intermediation.
- Manufacturers:Production-linked inbound supply chains requiring scheduled replenishment and customs deferment arrangements. Automotive and pharmaceutical producers prioritize accredited forwarders with trusted trader status.
- Retailers:Seasonal volume spikes and returns logistics drive demand for flexible capacity contracts. E-commerce cross-border expansion reshapes fulfillment network design toward direct-to-consumer customs clearance.
- Wholesalers:Consolidated shipment aggregation serving fragmented downstream distribution. Margin pressure pushes this segment toward freight brokers and volume-based rate negotiations.
- Exporters:Outbound-focused shippers navigating UK Global Tariff classification and rules of origin documentation. Post-Brexit regulatory rupture elevates demand for specialized customs brokerage expertise.
- Importers:Inbound cargo owners managing supplier coordination and duty liability. Pre-arrival declaration mandates under HMRC's border operating model favor forwarders with integrated customs systems.
Manufacturers anchor revenue concentration; Retailers are expanding most quickly.
Distribution Channel:
Channel selection reflects shipment scale and digital maturity, with platform adoption fragmenting traditional broker relationships.
- Direct Booking:Large-volume shippers negotiating annual contracts with asset-based carriers. Multinational manufacturers bypass intermediaries to secure capacity commitments and customized SLAs.
- Online Platforms:Digital quotation and booking interfaces capturing SME segments previously served by traditional brokers. E-commerce retailers in Midlands and South East England clusters drive adoption velocity.
- Freight Brokers:Relationship-based intermediaries matching irregular shippers with carrier capacity. Margin compression from platform competition forces brokers toward specialized vertical expertise.
- Logistics Agents:Local representatives coordinating first-mile collection and documentation. Geographic coverage gaps in peripheral UK regions sustain agent relevance for SME access.
- Third-Party Providers:Integrated 4PL arrangements bundling forwarding with warehousing and distribution. Retailers seeking single-accountability partnerships consolidate spend with these operators.
Freight Brokers retain volume leadership; Online Platforms gain share fastest.
Application:
Cargo characteristics determine compliance burden and pricing power, with temperature-sensitive and regulated goods commanding structural premiums.
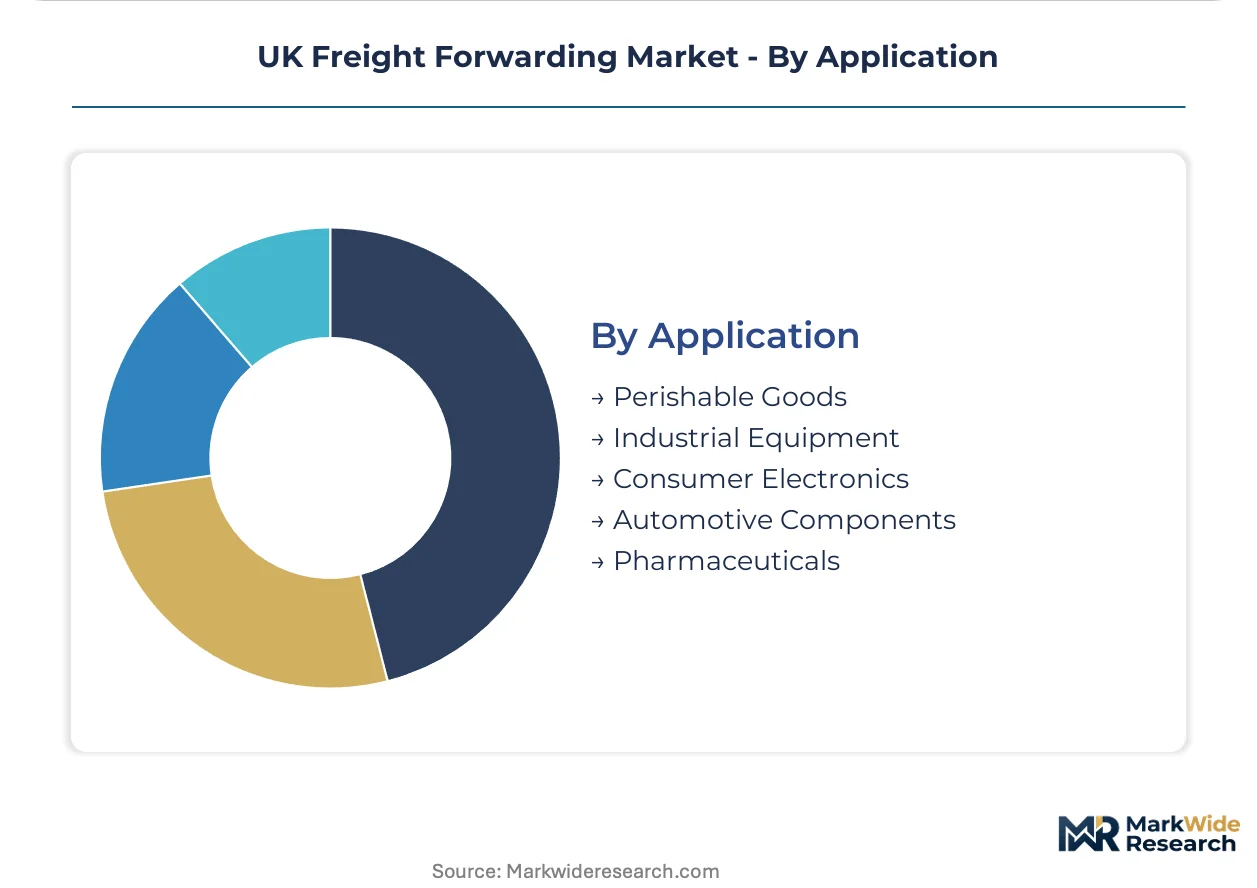
- Pharmaceuticals:GDP-compliant cold-chain forwarding requiring continuous temperature monitoring and chain-of-custody documentation. Biologics and vaccine distribution concentrate in certified forwarder networks with validated packaging capabilities.
- Automotive Components:Just-in-time sequencing and production line synchronization demanding precise arrival windows. Tier-1 suppliers prioritize forwarders with dedicated automotive vertical teams and EDI integration.
- Perishable Goods:Time-definite delivery for food products and agricultural exports with shelf-life constraints. Port of entry proximity and expedited customs clearance protect product integrity.
- Industrial Equipment:Project cargo and heavy machinery requiring specialized handling and out-of-gauge transport arrangements. Engineering procurement teams value forwarders with lift planning and route survey capabilities.
- Consumer Electronics:High-value density shipments with theft-sensitive profiles and rapid obsolescence cycles. Security-sealed containers and expedited air freight dominate this segment's modal mix.
Industrial Equipment dominates shipment volume; Pharmaceuticals show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK freight forwarding industry traces its modern structure to Liverpool and London's nineteenth-century shipping exchanges, where cargo consolidation and customs brokerage first professionalized. Post-Brexit regulatory rupture has fragmented these historic trade corridors, forcing forwarders to rebuild routing economics around new border operating models.
England
London and the Southeast cluster dominates pharmaceutical and financial services forwarding, with Heathrow anchoring temperature-controlled air freight for biologics exports. HM Revenue and Customs enforces the UK Global Tariff and rules of origin declarations from its Canary Wharf headquarters, reshaping documentation workflows. The Midlands manufacturing belt around Birmingham and Leicester drives automotive component forwarding, with Tier-1 suppliers demanding just-in-time sequencing through Channel ports.
Scotland
Edinburgh and Glasgow serve North Sea energy logistics and whisky export corridors, with Aberdeen's oil services sector generating project cargo demand. Scotland's distinct regulatory alignment discussions with the EU create compliance complexity for cross-border shipments. The Grangemouth port complex functions as Scotland's primary container gateway, handling petrochemical and perishable exports to continental markets.
Wales
South Wales ports at Cardiff and Newport concentrate steel and automotive forwarding, with Tata Steel operations generating bulk commodity flows. Welsh Government investment in Milford Haven energy infrastructure supports LNG and renewable component logistics. The A55 corridor along the north coast links Anglesey manufacturing to Irish Sea ferry services, bypassing English Channel congestion.
Northern Ireland
Belfast and Larne operate under the Windsor Framework's dual customs regime, creating arbitrage potential for forwarders mastering both UK and EU compliance. The region's pharmaceutical manufacturing base, anchored by Belfast's Almac and Randox facilities, generates GDP-certified cold-chain demand. Dublin-Belfast road freight corridors face unique documentary requirements distinct from GB-EU lanes.
North England
Manchester and Leeds anchor e-commerce fulfillment networks serving northern consumer markets, with direct-to-consumer customs clearance expanding rapidly. The Teesport and Hull maritime terminals handle containerized manufacturing inputs for Yorkshire industrial clusters. DVSA enforcement of cabotage rules constrains road freight capacity on cross-Pennine routes to Scottish distribution centers.
UK Freight Forwarding Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and vertical specialization. The UK market exhibits tiered consolidation, with global integrators controlling pharmaceutical and automotive accounts while regional specialists capture SME e-commerce segments. Three archetypes dominate: asset-light digital platforms, GDP-certified cold-chain specialists, and multimodal rail-sea integrators. Competitive intensity centers on M&A consolidation of customs brokerage capabilities and strategic partnerships with port terminal operators.
Among global integrators, Kuehne + Nagel and DHL Global Forwarding exemplify platform-scale archetypes with digital emissions reporting and pharmaceutical certification. DB Schenker occupies a position within the multimodal specialization tier, leveraging continental rail connectivity. These three represent contrasting strategic postures: technology-led customer interface, vertical-certified service depth, and infrastructure-controlled routing economics.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| DHL Global Forwarding |
| DB Schenker |
| CEVA Logistics |
| Barrington Freight |
| Hemisphere Freight Services |
| Spatial Global |
| Mango Logistics Group |
| Maersk |
| Others |
Pricing and Supply Chain Analysis
Horizontal consolidation among customs brokerage specialists anchors both supply positioning and pricing power in UK freight forwarding. Kuehne + Nagel and DHL Global Forwarding leverage integrated digital platforms to capture premium margins on pharmaceutical GDP certification while compressing rates in commoditized sea freight segments.
Pricing Analysis
Three-tier pricing structure across GDP-certified premium, standard brokerage, and economy digital tiers dominates UK freight forwarding. Price differentiation rests on customs accreditation depth and vertical specialization in pharmaceutical cold-chain or automotive just-in-time sequencing. Cost compression in sea freight intensifies because marine fuel surcharge volatility destabilizes contract structures. SME e-commerce retailers exhibit highest price sensitivity, while pharmaceutical manufacturers accept premium positioning for temperature-validated chain-of-custody guarantees.
Supply Chain Analysis
GDP certification and trusted trader accreditation gate access to premium forwarding tiers and fast-track HMRC clearance pathways. Carrier capacity concentrates in Belgium, Netherlands, and Germany as continental European hub feeders into UK corridors. Raw material dependencies span marine fuel, refrigerated container units, and specialized pharmaceutical packaging. Single-source vulnerability runs through Channel Tunnel congestion points. Distribution runs through multimodal rail-sea combinations and direct port-to-warehouse road haulage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK freight forwarding market functions as a regulatory compounder, where HM Revenue and Customs' phased border operating model continuously escalates compliance complexity and accreditation value.
For Market Incumbents: Extend trusted trader certification coverage across Northern Ireland dual-regime operations to capture Windsor Framework arbitrage opportunities. Deepen backward integration into port terminal partnerships at Grangemouth and Teesport to secure capacity priority during Channel disruption events. For New Entrants and Emerging Players: Mid-sized Midlands manufacturers with fragmented customs brokerage relationships represent the most penetrable buyer archetype. White-space targets include GDP-certified cold-chain specialization for Scottish biologics exporters and digital platform interfaces for South East England e-commerce clusters. A direct-booking SaaS layer with API-native customs integration offers viable go-to-market positioning. For Investors and Strategic Acquirers: Roll-up economics work for regional customs brokerage specialists because post-Brexit talent scarcity concentrates classification expertise among veteran practitioners. Long-term viability favors accredited operators with integrated pharmaceutical and automotive vertical teams. Monitor HMRC trusted trader accreditation expansion rates as the key inflection signal for premium tier capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Trusted Trader Accreditation Expansion | HMRC fast-track clearance separates accredited forwarders from inspection-delayed competitors in perishable segments. |
| Pharmaceutical GDP Certification Investment | Biologics and vaccine distribution commands structural premium pricing through validated temperature monitoring capabilities. |
| Rail-Sea Multimodal Corridor Development | Continental European rail connectivity bypasses Channel Tunnel congestion and DVSA cabotage constraints. |
| Digital Platform Integration for SME Access | Direct booking interfaces capture e-commerce retailers migrating from traditional freight broker relationships. |
| Northern Ireland Dual-Regime Specialization | Windsor Framework compliance arbitrage creates distinct competitive positioning against GB-only operators. |
Research Methodology
Bottom-up shipper demand modeling reconciled against top-down carrier capacity tracking forms the analytical core of this study. Primary interviews with freight forwarding operations directors, pharmaceutical supply chain managers, automotive logistics procurement leads, and HMRC policy officials combined with secondary validation from UK trade statistics, DVSA enforcement data, and port authority throughput records. Triangulation across these sources ensures segment-level precision.
Input-output matrix framing connects macro trade flow assumptions to micro shipment-level economics across the projection horizon. Segmentation dimensions modeled include service type, customer category, distribution channel, and application vertical. CAGRs derive from shipment volume trajectory analysis adjusted for modal shift patterns and regulatory compliance cost inflation. Industry-specific forecast inputs incorporate EU Green Deal emissions reporting mandates and UK Global Tariff classification complexity indices.
Underlying measurement precision varies by segment; pharmaceutical GDP-certified forwarding carries tighter precision than commoditized sea freight brokerage. Forecasts reflect documented assumptions regarding customs documentation burden evolution and driver capacity availability. Brexit alignment shift scenarios and fuel price volatility represent material revision triggers warranting model refresh.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Military Logistics Market
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
South Africa Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
Tank Container Shipping Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
LAOS Freight and Logistics Market
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Texas Freight and Logistics Market
Logistics and Shipping
Smart Shipping Containers Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market