
 China Freight and Logistics Market | 2026-2036
China Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
China Freight and Logistics Market Outlook
The shift from fragmented single-source trucking contracts toward integrated multi-modal outsourcing is realigning procurement patterns across Chinese supply chains. SF HOLDING leverages its air-ground express network to dominate time-critical deliveries in coastal manufacturing zones. COSCO Shipping Lines anchors ocean freight capacity through port infrastructure investments along the Belt and Road corridor. SINOTRANS Limited competes across rail-sea intermodal lanes linking interior production bases to export gateways.
China freight and logistics encompasses the physical movement, storage, and information management of goods across road, rail, air, and sea modalities, typically measured by ton-kilometers and container throughput volumes. The sector coordinates cargo consolidation, customs clearance, and last-mile distribution to connect manufacturing output with domestic consumption and export markets. Road freight maintains the largest volume share due to flexible routing across China's extensive expressway network, though rail freight captures expanding bulk flows along electrified corridors. E-commerce end users are driving fastest growth in automated warehousing technology adoption, while 3PL providers concentrate margin pools through integrated inventory management services.
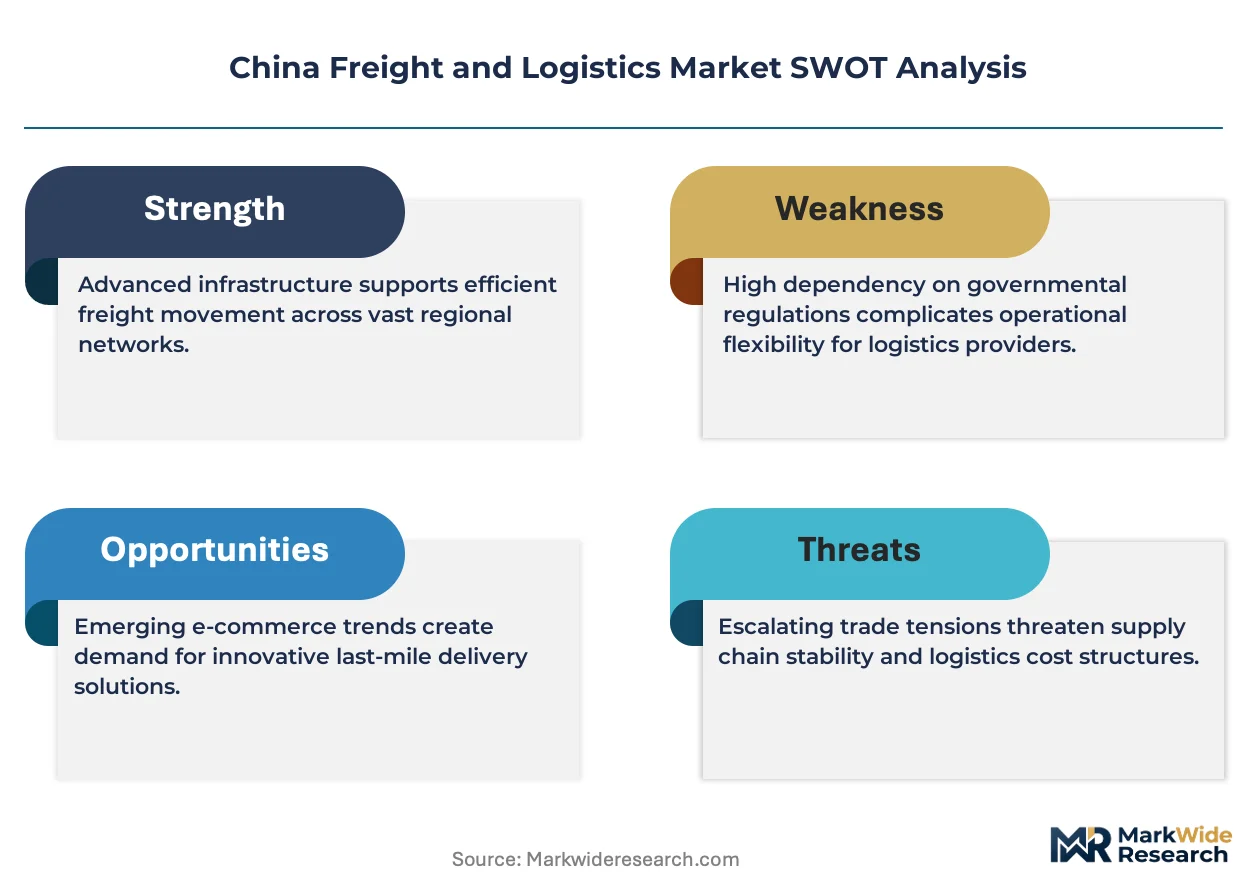
SAMR enforces logistics service standards and pricing transparency rules that reshape contract structures between shippers and carriers. MIIT mandates connected-vehicle data protocols and IoT integration timelines that determine technology procurement requirements for fleet operators. GB standards for emissions and safety certification control market access for trucking equipment and warehouse automation systems. Stakeholders must monitor how evolving carbon accounting rules from MEE will redistribute operating costs between asset-heavy carriers and technology-enabled platform operators.
Market Dynamics
China's dual carbon goals from MEE are compressing diesel truck economics while electrified rail corridors and automated port infrastructure redraw modal competition across interior manufacturing belts.
Growth Catalysts
- E-commerce fulfillment expansion:Platform operators are extending same-day delivery networks into Henan, Sichuan, and Hubei provinces, generating demand for automated sortation hubs and electric last-mile fleets.
- MIIT connected-vehicle mandates:IoT data protocols for commercial fleets now require real-time cargo monitoring, accelerating telematics adoption among asset-heavy carriers.
- GB warehouse automation standards:New certification requirements for green building envelopes and robotic systems are driving retrofit cycles in aging logistics parks across the Pearl River Delta.
Market Restraints
- Lithium price volatility:Battery pack costs for electric heavy-duty trucks remain exposed to cathode material fluctuations, constraining fleet electrification timelines for mid-size operators.
- Port concentration risk:Container throughput at Shanghai-Ningbo corridor facilities creates single-point vulnerability for export-oriented 3PL contracts during seasonal congestion.
- Driver shortage structural ceiling:Aging workforce demographics in long-haul trucking limit capacity expansion regardless of vehicle availability or freight rates.
Strategic Opportunities
- Central China rail-sea intermodal:Wuhan-Chongqing manufacturing clusters lack integrated logistics providers, opening white space for operators controlling both inland terminal access and coastal vessel slots.
- Carbon accounting services:MEE emissions disclosure rules for listed manufacturers create demand for third-party freight emissions verification and offset procurement platforms.
- Cold chain pharmaceutical distribution:NMPA Good Distribution Practice requirements for biologics are expanding temperature-controlled warehouse specifications beyond coastal hubs.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems require expensive middleware development to comply with MIIT data format standards.
- Cross-provincial permit fragmentation:Provincial-level operating licenses for oversized cargo create administrative friction on intermodal corridors linking interior production bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Freight and Logistics Market |
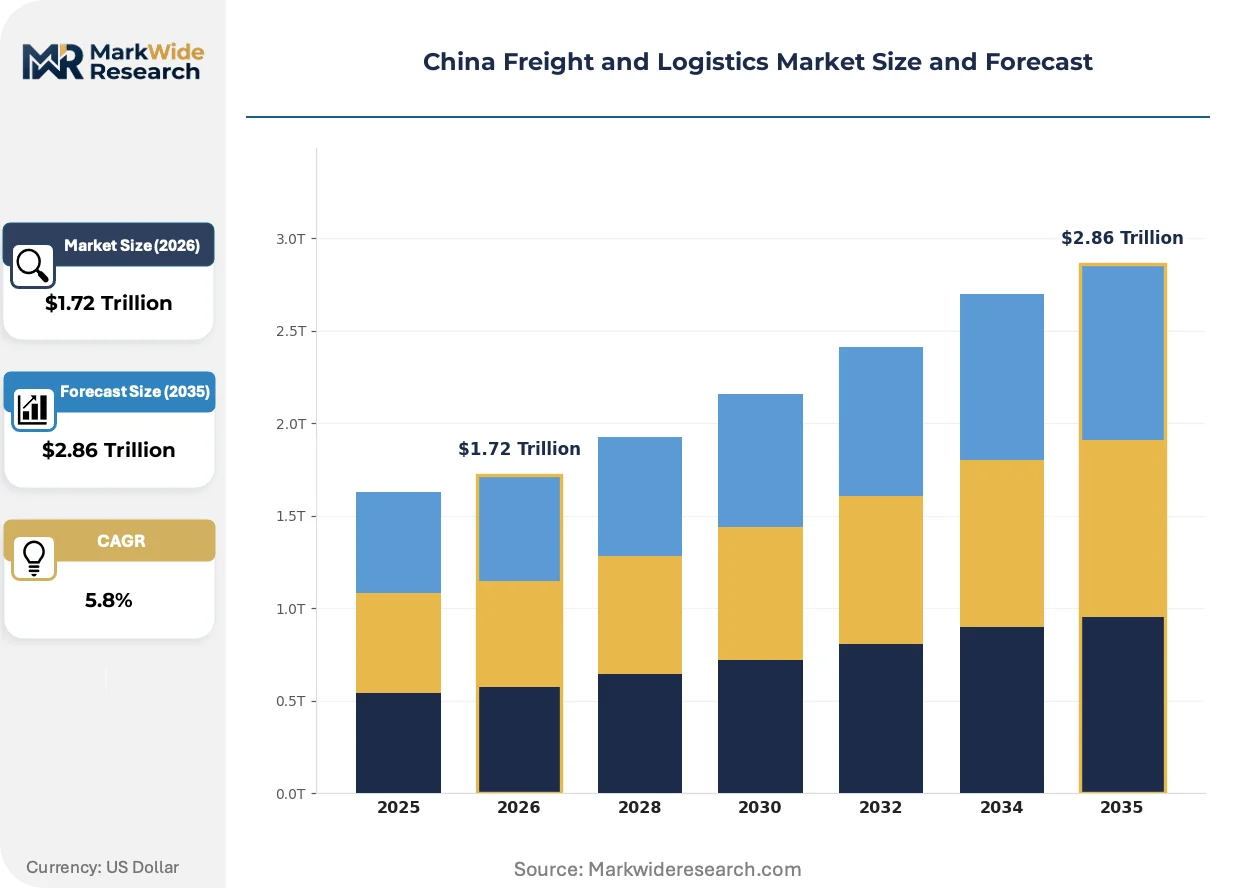
| Market Size in 2026 | $1.72 Trillion |
| Market Size in 2035 | $2.86 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Rail Freight, Air Freight, Sea Freight End User: E-commerce, Retail, Manufacturing, Automotive Distribution Channel: Direct Sales, Online Platforms, Freight Forwarders, 3PL Providers Technology: GPS Tracking, IoT Solutions, Automated Warehousing, Blockchain |
| Companies Covered | SF HOLDING, Bansar, COSCO Shipping Lines, ET International Logistics, DDPCH, SINOTRANS Limited, SINO Shipping, Shenzhen Fly International Logistics, China Merchants Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Freight and Logistics Market Strategic Shifts
Autonomous yard trucks and AI-powered freight matching platforms are compressing labor dependency and asset utilization gaps across China's logistics infrastructure.
Autonomous electric yard tractors at Ningbo-Zhoushan Port and Shanghai Yangshan terminals are rewriting dockside labor economics. Terminal operators deploy these vehicles for 24-hour container repositioning without shift-change downtime. The technology is compressing vessel turnaround times and reducing quay crane idle rates during peak export windows.
MEE carbon intensity benchmarks for logistics service providers now require Scope 3 emissions disclosure from contracted carriers. Heavy manufacturing exporters in Jiangsu and Zhejiang are selecting 3PL partners based on verified electric fleet percentages. This regulatory pressure is fragmenting carrier procurement pools between certified green operators and conventional diesel fleets.
Shippers in automotive and electronics verticals now unbundle freight procurement from inventory management, contracting separate specialists for each function. This disintermediation is displacing full-service 3PL incumbents in the Yangtze River Delta corridor. Component manufacturers in Suzhou and Wuxi increasingly direct-source trucking capacity through digital freight platforms while retaining separate warehouse operators for storage and fulfillment.
China Freight and Logistics Market Segmentation
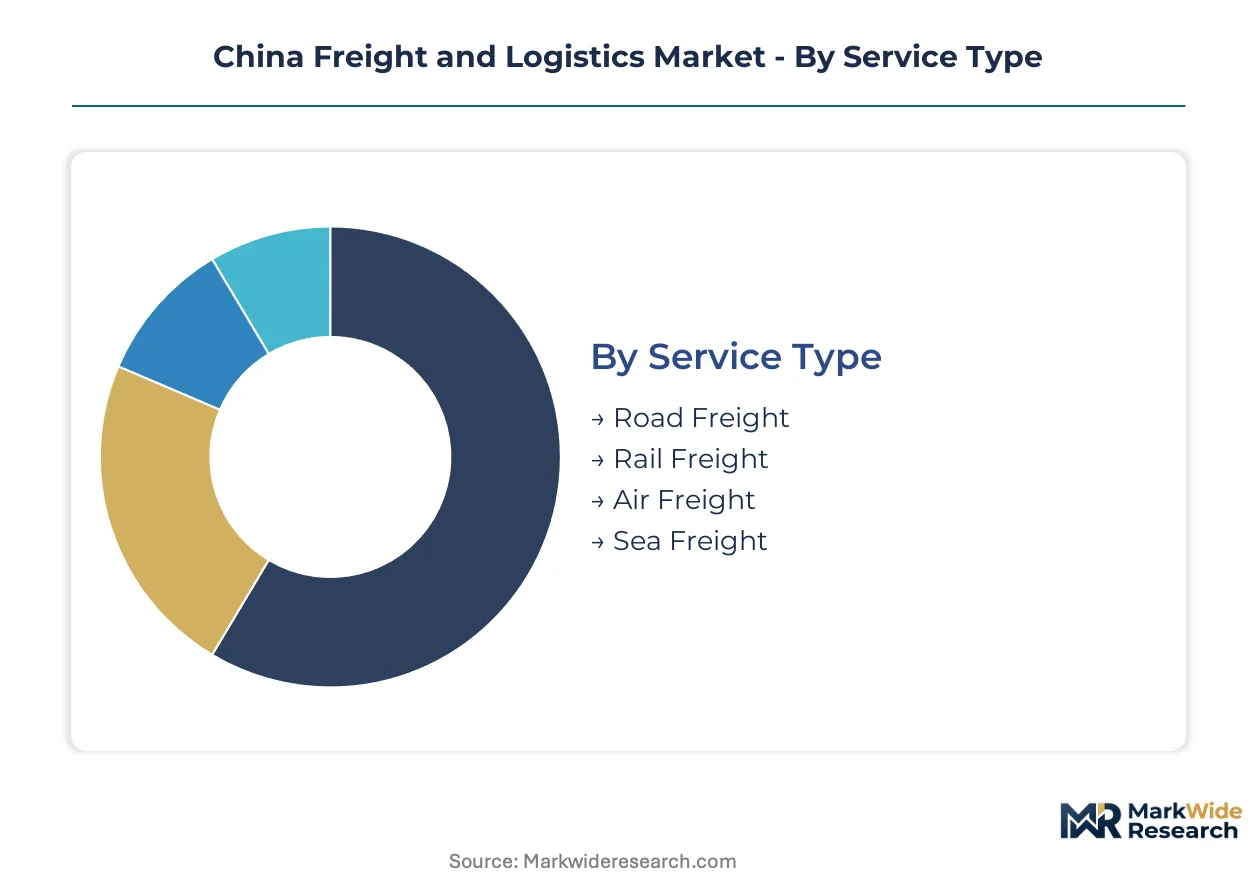
Segmentation in China's freight and logistics market reveals how modal specialization, end-use concentration, and technology adoption create distinct competitive arenas. Procurement patterns diverge sharply between asset-heavy carriers serving bulk manufacturing flows and platform operators capturing e-commerce velocity. Understanding these splits enables targeted positioning across diverging margin pools and regulatory exposure zones.
Service Type:
Road freight commands volume dominance while rail and air capture premium positioning on speed and carbon efficiency metrics.
- Road Freight:Flexible routing across China's 180,000-kilometer expressway network enables door-to-door delivery for fragmented manufacturing supply chains. Demand concentrates in Yangtze River Delta corridor connecting Shanghai, Jiangsu, and Zhejiang clusters where just-in-time automotive and electronics production requires rapid response capability. SAMR enforcement of driver hour limits and GB emissions standards is compressing fleet economics for non-compliant operators.
- Rail Freight:Electrified corridors along Belt and Road interior routes offer carbon-advantaged bulk movement for coal, steel, and containerized exports. Wuhan-Chongqing manufacturing belt generates expanding demand as MEE dual carbon goals penalize diesel-dependent shippers. MIIT mandates for connected freight cars are accelerating telematics retrofit investment among state rail operators.
- Air Freight:Time-critical pharmaceutical and electronics shipments dominate cargo hold allocation at Shanghai Pudong and Beijing Capital hubs. Biologics cold chain requirements from NMPA are expanding temperature-controlled terminal specifications.
- Sea Freight:Container throughput at Ningbo-Zhoushan and Shanghai Yangshan anchors export manufacturing economics. COSCO Shipping Lines controls vessel slot allocation through port infrastructure investments along coastal corridors.
Today's leader: Road Freight. Tomorrow's challenger: Rail Freight.
End User:
Customer type determines service velocity requirements and technology procurement intensity.
- E-commerce:Platform operators like Alibaba and JD.com are extending same-day delivery networks into Henan, Sichuan, and Hubei provinces. Automated sortation hubs and electric last-mile fleets represent the fastest-expanding capital deployment category as consumer delivery expectations compress fulfillment windows.
- Manufacturing:Component suppliers in Suzhou and Wuxi increasingly unbundle freight procurement from inventory management, direct-sourcing trucking capacity through digital platforms while retaining separate warehouse operators. This disintermediation is displacing full-service 3PL incumbents.
- Retail:Omnichannel distribution requirements are merging store replenishment with direct-to-consumer fulfillment, forcing consolidation between regional distribution center networks and last-mile delivery nodes.
- Automotive:Just-in-sequence production schedules at Jiangsu and Zhejiang assembly plants demand precise arrival windows for tiered component suppliers, favoring dedicated contract logistics over spot market capacity.
E-commerce climbs the fastest; manufacturing retains the deepest contract value.
Distribution Channel:
Channel structure reflects the unbundling of physical movement from information coordination and working capital management.
- 3PL Providers:Integrated inventory management and transportation services concentrate margin pools through multi-year contracts with multinational manufacturers. SF HOLDING leverages air-ground express network dominance to capture premium time-definite deliveries.
- Freight Forwarders:Customs clearance expertise and carrier relationship management provide value on international lanes, though digital platforms are compressing information arbitrage opportunities.
- Direct Sales:Large automotive and electronics shippers bypass intermediaries to contract dedicated fleet capacity, internalizing route optimization and carbon accounting compliance.
- Online Platforms:Digital freight matching services are aggregating fragmented trucking supply, though driver shortage constraints limit effective capacity expansion regardless of platform scale.
3PL Providers hold current margin concentration; Online Platforms gain transaction velocity.
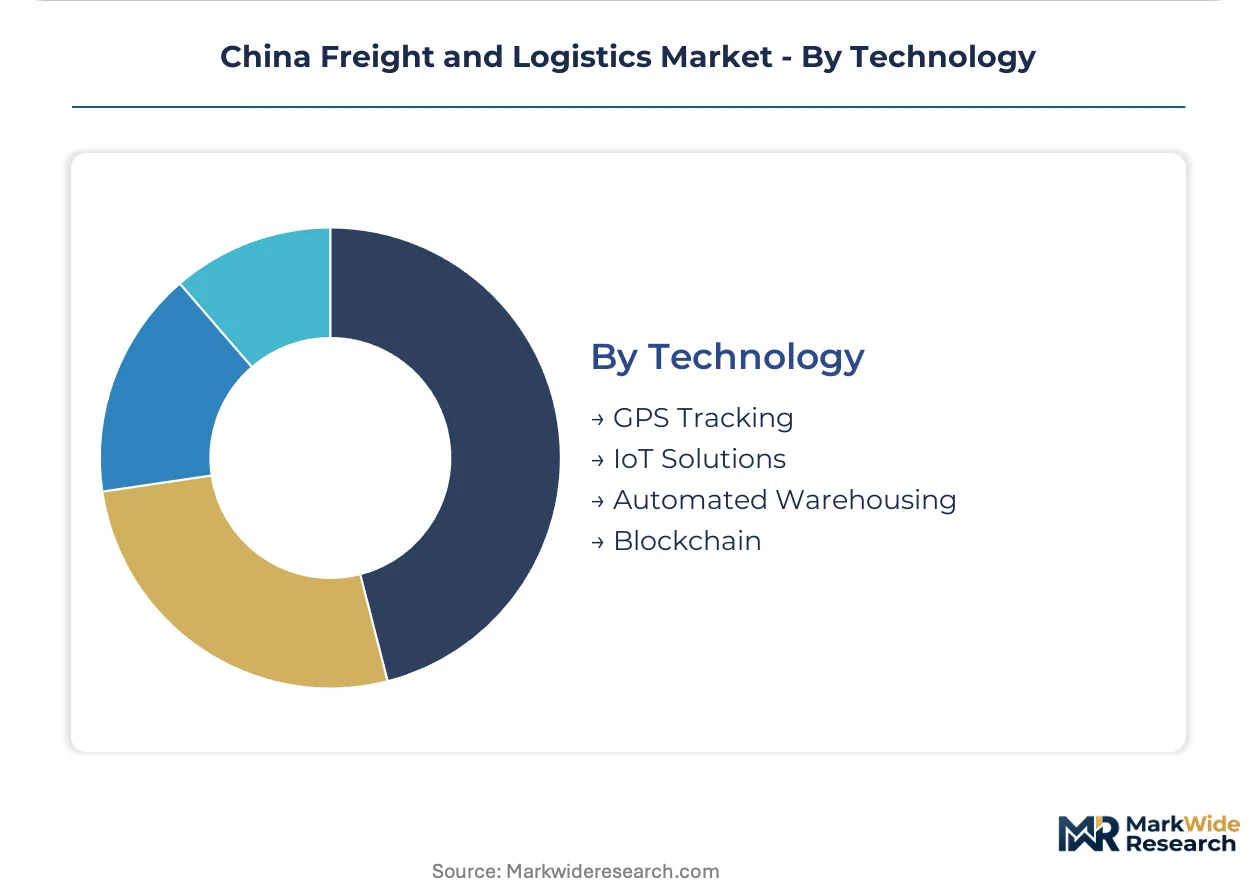
Technology:
Regulatory mandates and labor cost pressures are accelerating technology deployment timelines across fleet and warehouse assets.
- IoT Solutions:MIIT connected-vehicle data protocols now require real-time cargo monitoring for commercial fleets, accelerating telematics adoption among asset-heavy carriers. Legacy fleet management systems require expensive middleware development to comply with MIIT data format standards.
- Automated Warehousing:GB standards for green building envelopes and robotic systems are driving retrofit cycles in aging logistics parks across Pearl River Delta. E-commerce fulfillment density justifies capital investment in goods-to-person systems and autonomous mobile robots.
- GPS Tracking:Basic location services are commoditizing as standard equipment, with differentiation shifting to predictive ETA algorithms and exception management workflows.
- Blockchain:Document verification and cross-border trade finance applications remain pilot-stage, with adoption constrained by inter-enterprise data sharing governance challenges.
IoT Solutions lead regulatory-driven deployment; Automated Warehousing scales fastest on labor substitution economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration within China follows compliance-cost gradients, with exporters relocating from coastal zones to interior provinces where MEE carbon enforcement timelines lag by 18-24 months. This arbitrage is redrawing logistics demand maps as production clusters seek freight corridors with lower emissions-accounting burdens.
Yangtze River Delta
Shanghai-Ningbo container throughput anchors export volume, though SAMR driver-hour enforcement and MEE carbon audits are compressing fleet economics. SAMR mandates real-time telematics for all commercial vehicles operating across Jiangsu-Zhejiang corridors. Suzhou and Wuxi automotive component suppliers now unbundle freight procurement from warehouse contracts, direct-sourcing trucking through digital platforms.
Pearl River Delta
Shenzhen-Dongguan electronics manufacturing generates premium air freight demand for time-critical semiconductor shipments. GB warehouse automation standards are forcing retrofit cycles in aging logistics parks across Guangdong province. Guangzhou's automated sortation hubs are expanding capacity to handle cross-border e-commerce volumes directed at Southeast Asian markets.
Sichuan-Chongqing
Wuhan-Chongqing manufacturing clusters lack integrated logistics providers, creating white space for rail-sea intermodal operators. MIIT connected-vehicle protocols are accelerating telematics adoption among fleet operators serving interior automotive plants. Chengdu's bonded logistics zones are attracting 3PL investment as electronics manufacturers relocate from coastal cost pressures.
Beijing-Tianjin-Hebei
Pharmaceutical cold chain requirements from NMPA are expanding temperature-controlled warehouse specifications beyond traditional coastal hubs. MEE dual carbon goals are accelerating electric truck deployment in municipal delivery fleets across the capital region. Tianjin Port's rail-sea intermodal terminals are capturing container flows from Hebei steel exporters seeking carbon-advantaged routing.
Central China
Henan and Hubei provinces are receiving e-commerce fulfillment network expansion as platform operators extend same-day delivery coverage inland. SAMR logistics service standards are reshaping contract structures between shippers and carriers in Zhengzhou's emerging logistics corridor. Wuhan's rail terminals are upgrading electrified infrastructure to capture manufacturing migration from Yangtze Delta cost inflation.
China Freight and Logistics Market Competitive Environment
Established operators occupy the integrated service tier; emerging entrants pursue digital freight matching and carbon-accounting specialization. The market structures around three player tiers: asset-heavy carriers controlling port and rail infrastructure, platform operators aggregating fragmented trucking supply, and specialists in temperature-controlled or time-definite verticals. Strategic moves concentrate on M&A to secure terminal access, partnerships to lock in vessel slot allocation, and technology licensing for telematics compliance.
Among integrated logistics providers, SF HOLDING and COSCO Shipping Lines exemplify the infrastructure-control archetype, while SINOTRANS Limited occupies a position across rail-sea intermodal lanes. These entities represent contrasting strategic postures: one leveraging air-ground express density in coastal manufacturing zones, another anchoring ocean capacity through port investments, and the third bridging interior production bases to export gateways.
| Leading Market Players |
|---|
| SF HOLDING |
| Bansar |
| COSCO Shipping Lines |
| ET International Logistics |
| DDPCH |
| SINOTRANS Limited |
| SINO Shipping |
| Shenzhen Fly International Logistics |
| China Merchants Group |
| Others |
Value Chain & Pricing Dynamics
Electrified rail corridor investments and automated port infrastructure deployments are compressing diesel-dependent cost structures while redrawing modal competition across interior manufacturing belts. MIIT connected-vehicle mandates and MEE carbon accounting rules simultaneously reshape operating cost economics and concentrate procurement power among compliant fleet operators.
Pricing Analysis
Freight forwarder margin compression dominates channel economics as digital platforms erode information arbitrage on international lanes. Contract-based long-term offtake agreements anchor pricing for multinational manufacturers, with differentiation hinging on verified electric fleet percentages and GB emissions certification tiers. Pricing pressure stems from lithium price volatility constraining mid-size operator electrification timelines. E-commerce platform operators show least price sensitivity due to fulfillment density requirements, while commodity bulk shippers in coal and steel verticals exhibit highest sensitivity to per-ton-kilometer rates.
Supply Chain Analysis
Domestic-content mandates under MIIT connected-vehicle protocols and SAMR logistics service standards are reshaping sourcing requirements for telematics hardware and warehouse automation systems. Equipment manufacturing concentrates in China, Germany, and Japan for automated sortation systems and electric powertrain components. Critical input dependencies include lithium carbonate cathode materials, high-precision servo motors, and IoT sensor arrays. Single-source vulnerability runs through Shanghai-Ningbo container throughput concentration. Distribution runs through integrated 3PL providers controlling both inland terminal access and coastal vessel slots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China freight and logistics represents a late-cycle quality story as MEE dual carbon goals and SAMR enforcement timelines shift procurement criteria toward verified green fleet operators and certified warehouse automation. Biologics cold chain requirements from NMPA are expanding temperature-controlled specifications beyond traditional coastal hubs, elevating service quality thresholds.
For Market Incumbents: Extend electrified fleet deployment ahead of MEE carbon intensity benchmark enforcement to capture premium contract renewals from Jiangsu and Zhejiang exporters. Consolidate terminal access through rail-sea intermodal partnerships along Wuhan-Chongqing corridors before digital freight platforms aggregate sufficient inland capacity. Vertical integration into carbon accounting services addresses emerging Scope 3 disclosure requirements from listed manufacturers. For New Entrants and Emerging Players: Begin with autonomous yard truck deployment at secondary ports where labor cost compression economics justify capital investment against established terminal operators. Target pharmaceutical cold chain distribution in Beijing-Tianjin-Hebei where NMPA Good Distribution Practice requirements exceed incumbent capability. Partner with MIIT-certified telematics providers to bypass legacy middleware development barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size rail-sea intermodal operators lacking integrated coastal vessel slot control but possessing interior terminal access rights. Long-term viability hinges on carbon accounting service capabilities and electric fleet certification percentages rather than pure asset scale. Monitor MEE emissions disclosure rule expansion to listed manufacturers as the inflection signal for third-party verification platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Sea Intermodal Partnership | Wuhan-Chongqing corridor access captures manufacturing migration from Yangtze Delta cost pressures. |
| Electric Fleet Certification Program | Verified green percentages unlock premium contracts from MEE-compliant Jiangsu exporters. |
| Carbon Accounting Platform Launch | Scope 3 disclosure mandates from listed manufacturers create third-party verification demand. |
| Automated Warehouse Retrofit | GB green building standards force upgrade cycles across aging Pearl River Delta logistics parks. |
| Pharmaceutical Cold Chain Expansion | NMPA biologics requirements extend temperature-controlled specifications beyond coastal hubs. |
Study Parameters
Multiple input streams — fleet operator telematics data, port throughput records, and 3PL contract disclosure patterns — were reconciled against primary interviews with logistics park developers, SAMR compliance officers, and MIIT certification specialists. Secondary validation drew from customs export statistics, state rail operator electrification reports, and NMPA pharmaceutical distribution filings. Bottom-up ton-kilometer modeling and top-down GDP elasticity approaches were cross-checked for segmentation consistency.
Historical volume trajectories were cross-referenced against expert panel assessments of carbon policy implementation timelines across the projection horizon. Segmentation dimensions modeled include service modality, end-user vertical, distribution channel structure, and technology adoption tier. CAGRs were derived from elasticity-adjusted demand curves incorporating e-commerce fulfillment density metrics and manufacturing relocation patterns. Industry-specific forecast inputs include MIIT connected-vehicle mandate compliance schedules and MEE dual carbon enforcement intensity gradients.
Several conditions sit outside the modeled scope, including sudden lithium commodity price spikes, port labor action events, and cross-provincial permit harmonization breakthroughs. Forecasts reflect documented assumptions regarding SAMR enforcement consistency and MEE audit expansion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Hong Kong Freight and Logistics Market
Logistics and Shipping
Renewable Resources Logistics Market
Logistics and Shipping
Digital Freight Management Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
Poland Freight and Logistics Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
Chile Third-Party Logistics (3PL) Market
Logistics and Shipping
US Cross-Border Road Freight Transport Market
Logistics and Shipping
Europe Automotive Logistics Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Egypt 3PL Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Smart Shipping Containers Market
Logistics and Shipping
Global Freight Broker Software Market