
 Europe Automotive Logistics Market | 2026-2036
Europe Automotive Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Logistics Market Foresight
The EU Green Deal is broadening compliance obligations for automotive supply chains across Europe. DHL Supply Chain leverages its multimodal European network to manage battery-grade freight corridors from Central European plants to Nordic assembly sites. Kuehne + Nagel anchors its automotive vertical through specialized EV battery logistics protocols and temperature-controlled transport assets. GEODIS competes on cross-border rail integration, offering consolidated wagonload services that reduce road dependency for just-in-sequence deliveries to French and German factories.
Europe automotive logistics encompasses the planning, execution, and control of material and vehicle flows across inbound parts distribution, finished vehicle transport, and aftermarket spare parts fulfillment, typically operating within tolerance windows of under four hours for just-in-sequence assembly line feeds. The service type dimension shows transportation and warehousing commanding the core spend pool, while inventory management gains traction as OEMs adopt vendor-managed inventory models to reduce working capital. Electric vehicles within the vehicle type split are pulling dedicated lithium-ion battery logistics infrastructure, requiring thermal runaway containment systems and UN 38.3-certified packaging that command premium pricing over conventional powertrain parts handling.
The European Chemicals Agency enforces REACH compliance for automotive coatings and adhesives in transit, while the F-Gas Regulation governs refrigerant logistics for climate-controlled vehicle shipments across member states. The EU AI Act will soon classify automated warehouse robotics and autonomous yard trucks under risk-based conformity requirements, reshaping capital deployment timelines for logistics automation. Stakeholders must weigh regulatory compliance spend against automation returns as the European Commission tightens supply chain due diligence rules under the Corporate Sustainability Due Diligence Directive.
Market Dynamics
Electrification of European vehicle fleets is compressing legacy powertrain logistics networks while forcing capital redeployment toward battery-grade corridors and thermal containment infrastructure. This structural force is redrawing warehouse locations, transport modes, and supplier proximity requirements across the continent.
Growth Catalysts
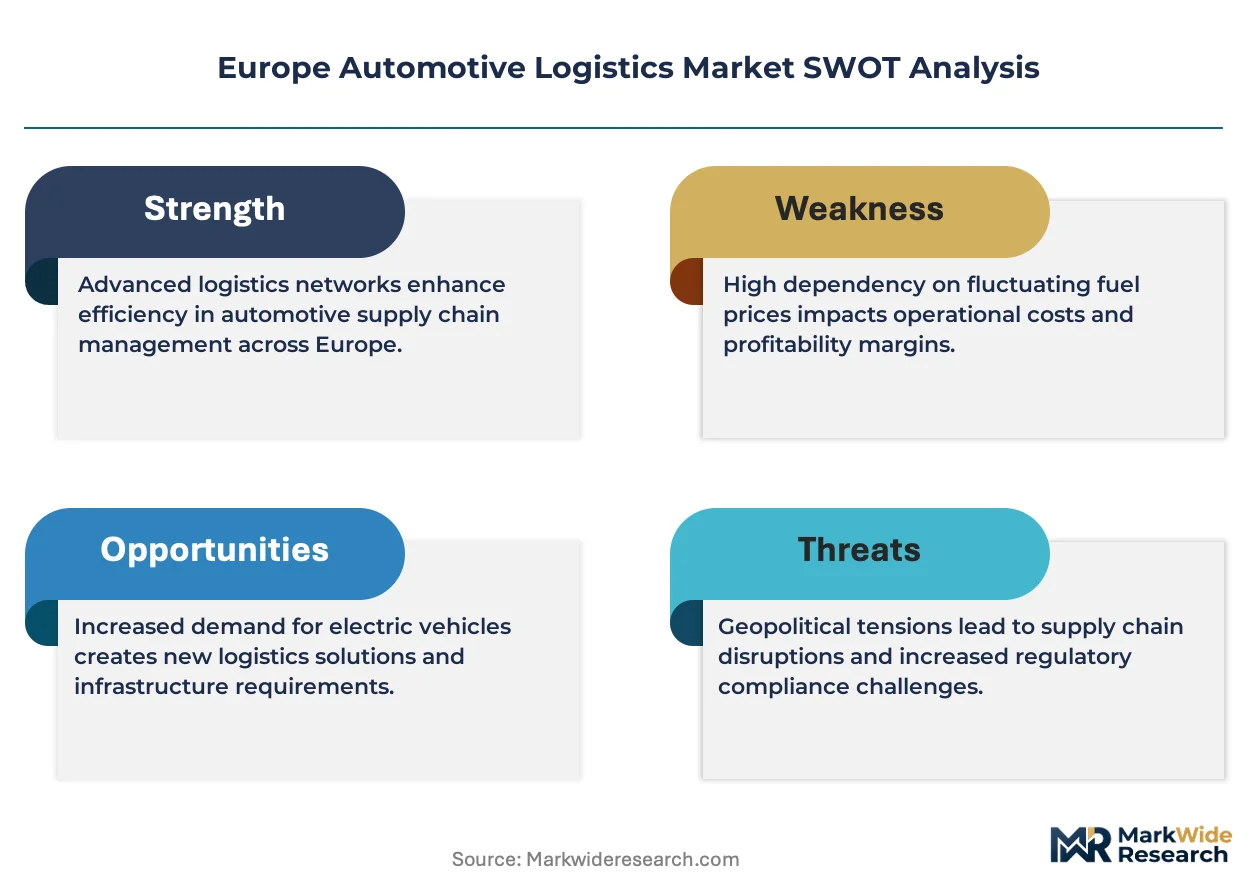
- EU Green Deal supply chain mandates:Binding emissions benchmarks for automotive supply chains are compelling OEMs to re-source components from lower-carbon European suppliers, shortening transport distances and increasing intra-regional freight density.
- Polish battery corridor concentration:Central European gigafactory clusters are generating dedicated inbound logistics demand for cathode precursors and separator films that bypass traditional automotive parts distribution networks.
- Just-in-sequence assembly integration:Tier-1 suppliers are co-losing sequencing centers adjacent to German and French OEM plants, reducing inventory buffers and increasing high-frequency delivery requirements.
Market Restraints
- Lithium supply geographic concentration:European cell manufacturers remain dependent on Chilean and Australian hard-rock lithium concentrates, exposing logistics networks to maritime bulk shipping volatility and port congestion at Rotterdam and Hamburg.
- REACH compliance cost escalation:The European Chemicals Agency's expanded substance restrictions are forcing logistics providers to segregate automotive coatings and adhesives in transit, adding handling complexity and documentation overhead.
- Rail gauge incompatibility:Finished vehicle movements between Iberian Peninsula factories and Central European markets face gauge breaks at the French-Spanish frontier, limiting modal shift potential for Spanish OEM exports.
Strategic Opportunities
- Romanian aftermarket logistics underpenetration:The country's expanding vehicle parc lacks dedicated spare parts distribution infrastructure, creating whitespace for regional hub-and-spoke networks serving Southeastern European repair chains.
- EU AI Act automation pathway:Risk-based conformity requirements for autonomous yard trucks and warehouse robotics will clarify capital deployment timelines, enabling logistics providers to accelerate automation investments with regulatory certainty.
- Battery second-life reverse logistics:End-of-life electric vehicle batteries from Nordic markets require collection and redistribution to stationary energy storage refurbishers, establishing new circular economy freight corridors.
Industry Challenges
- UN 38.3 certification bottleneck:Lithium-ion battery packagers face extended testing timelines at notified bodies, delaying new logistics service launches and constraining capacity expansion for EV-dedicated fleets.
- Cross-border customs fragmentation:Post-Brexit UK-EU customs formalities continue disrupting just-in-time delivery windows for British component suppliers serving Continental assembly plants.
- Thermal runaway containment capex:Dedicated fire suppression systems and segregated storage infrastructure for battery warehouses require substantial upfront investment that strains mid-sized logistics operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Logistics Market |
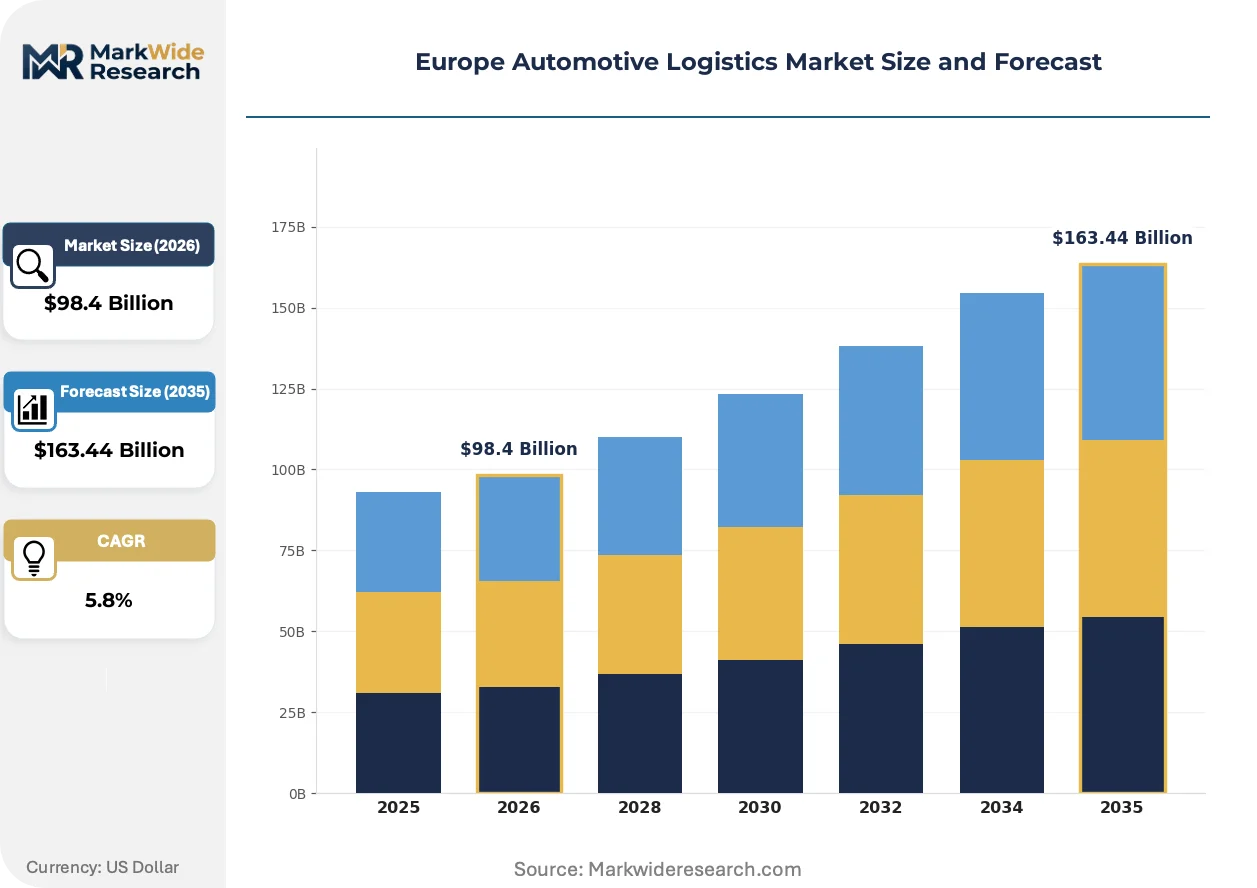
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $163.44 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Freight Forwarding End User: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Providers Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Distribution Channel: Direct Sales, Distributors, Online Portals, Third-Party Logistics |
| Companies Covered | BLG Logistics, Schnellecke Logistics, GEODIS, DSV A/S, CMA CGM Group, DHL Supply Chain, Kuehne + Nagel, DB Schenker, Hellmann Worldwide Logistics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Logistics Market Shifts & Advancements
Digital twin technology is compressing planning cycles across European automotive logistics networks, enabling real-time disruption response that was previously impossible with static routing systems.
Autonomous mobile robots equipped with computer vision and fleet orchestration software are absorbing repetitive pallet transport tasks in sequencing centers serving German OEM plants. Tier-1 suppliers in Stuttgart and Munich are deploying these systems at scale, reducing labor dependency for high-frequency line-feed operations. The technology is absorbing floor space previously allocated to fixed conveyor infrastructure, enabling layout reconfiguration for mixed-model battery and powertrain handling.
The EU AI Act's risk-based classification framework for automated logistics equipment is forcing providers to front-load conformity assessment costs. Warehouse robotics and autonomous yard trucks now face mandatory third-party auditing before deployment in member states. French and German logistics operators are responding by consolidating automation procurement timelines to align with the regulation's phased implementation.
OEM procurement teams are unbundling transportation from warehousing contracts, creating separate competitive tenders for each service layer. This pattern is displacing integrated 3PL relationships that dominated European automotive logistics for two decades. The shift is most visible in battery logistics, where specialized temperature-controlled carriers win transport awards while dedicated warehousing providers secure storage and sequencing contracts.
Europe Automotive Logistics Market Segmentation
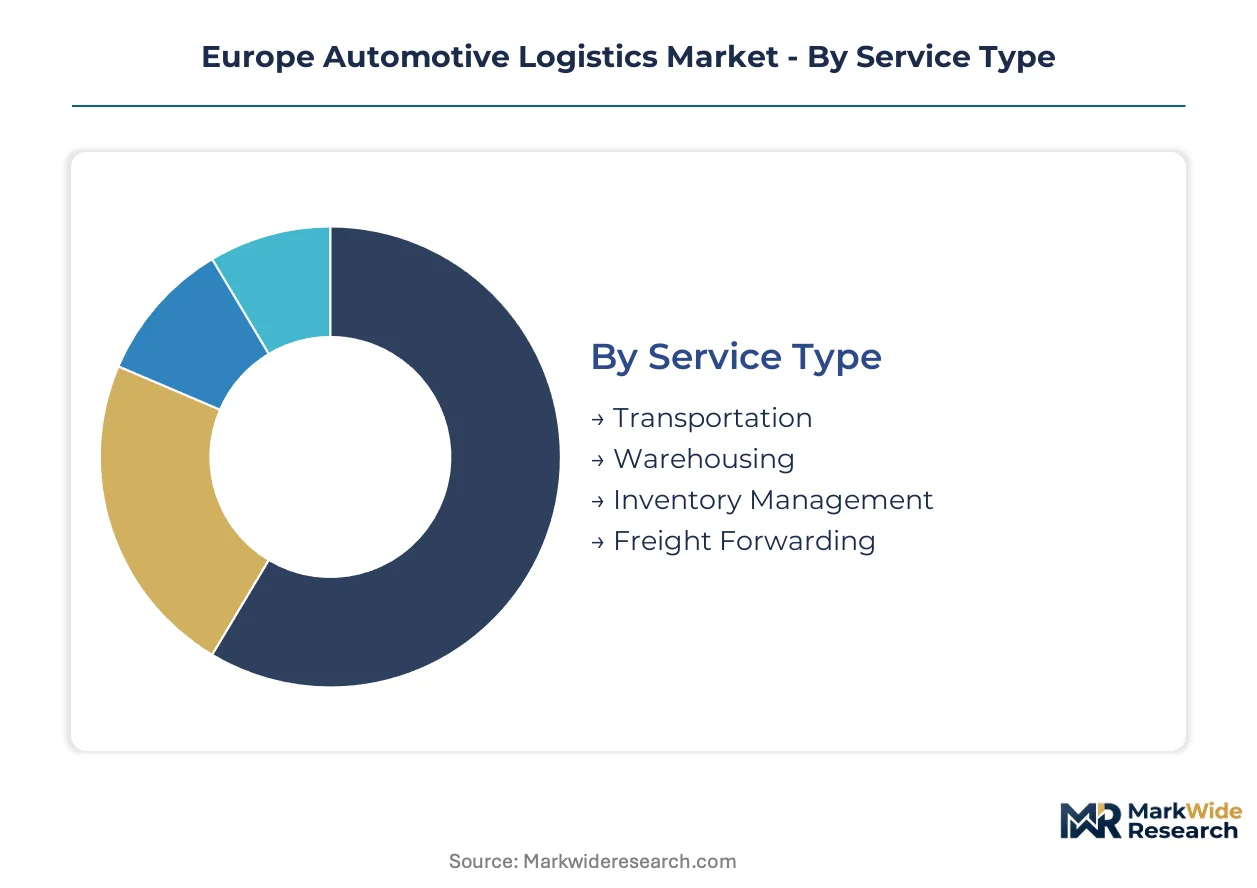
Automotive logistics providers in Europe configure service portfolios around distinct operational rhythms. Each segment demands specialized assets, from thermal-controlled battery corridors to just-in-sequence sequencing centers. Understanding these divisions reveals where capital deployment and margin capture concentrate across the value chain.
Service Type:
Replacement cycles for logistics infrastructure accelerate as electrification forces asset redeployment from legacy powertrain networks to battery-grade corridors and thermal containment systems.
- Transportation:Road, rail, and multimodal freight movements absorb the largest share of logistics spend. German OEM clusters generate dense inbound parts traffic requiring sub-four-hour delivery windows. Polish battery corridor expansion is pulling dedicated cathode precursor and separator film transport demand that bypasses conventional automotive distribution networks.
- Warehousing:Storage and sequencing facilities co-located adjacent to assembly plants enable just-in-sequence line feeds. Tier-1 suppliers in Stuttgart and Munich operate these centers at scale, reducing inventory buffers while increasing delivery frequency. EU Green Deal compliance obligations are shortening acceptable transport distances, pushing warehouse locations closer to final assembly.
- Inventory Management:Vendor-managed inventory models transfer working capital risk from OEMs to logistics providers. Real-time visibility systems track component flows across supplier networks.
- Freight Forwarding:Cross-border coordination manages customs documentation and modal handoffs. Post-Brexit UK-EU formalities continue disrupting just-in-time windows for British suppliers serving Continental plants.
Volume placements concentrate in Transportation; the faster expansion belongs to Warehousing.
End User:
Cost tier differentiation separates high-frequency just-in-sequence feeds from lower-velocity aftermarket fulfillment.
- OEMs:Original equipment manufacturers demand integrated inbound logistics spanning supplier collection through assembly line sequencing. Volkswagen, BMW, and Stellantis facilities in Germany, France, and Italy anchor the continent's densest logistics demand. Battery electric vehicle production is forcing these customers to unbundle transportation from warehousing contracts, creating separate competitive tenders for each layer.
- Tier-1 Suppliers:Component manufacturers operating sequencing centers adjacent to OEM plants manage high-frequency line-feed operations. Bosch, Continental, and ZF facilities absorb specialized warehousing and transport services. These stakeholders face compressed margins from OEM price-down programs while funding automation investments to offset labor costs.
- Dealerships:Finished vehicle distribution from assembly plants to retail networks requires specialized car-carrying equipment and yard management. Spanish OEM exports face rail gauge breaks at the French-Spanish frontier, limiting modal shift options.
- Aftermarket Providers:Spare parts distribution serves repair chains across expanding vehicle parcs. Romanian aftermarket infrastructure remains underpenetrated, creating whitespace for regional hub-and-spoke networks.
Revenue concentration sits with OEMs; aftermarket providers are climbing the fastest as vehicle parcs age and electrification diversifies parts portfolios.
Vehicle Type:
Application-specific requirements dictate packaging standards, transport modes, and regulatory compliance obligations across vehicle categories.
- Passenger Cars:High-volume production generates predictable logistics demand with established just-in-sequence rhythms. German and French assembly plants maintain the continent's most mature inbound parts networks. These flows face gradual compression as electrification reduces powertrain component counts.
- Electric Vehicles:Dedicated lithium-ion battery logistics requires UN 38.3-certified packaging, thermal runaway containment systems, and temperature-controlled transport assets. Nordic assembly sites source cells from Central European gigafactories, establishing new freight corridors with premium pricing over conventional powertrain handling. ECHA REACH compliance adds documentation overhead for coatings and adhesives in battery pack assembly.
- Commercial Vehicles:Heavy truck and van production operates at lower volumes with larger component dimensions. Cab and chassis assembly requires specialized sequencing for bulky stampings.
- Luxury Vehicles:Low-volume, high-value finished vehicle transport demands enclosed carriers and enhanced security protocols. Bentley and Rolls-Royce facilities in Britain face post-Brexit customs complexity for Continental component sourcing.
Shipment volumes concentrate in Passenger Cars; Electric Vehicles command the steepest expansion trajectory as EU Green Deal mandates tighten.
Distribution Channel:
Customer type and procurement sophistication determine contract structures and service integration depth.
- Direct Sales:OEM-managed logistics operations retain control over critical inbound flows. Volkswagen Group and BMW maintain captive fleets for high-value battery and powertrain components. These arrangements are contracting as procurement teams unbundle services to access specialized providers.
- Distributors:Independent parts wholesalers aggregate demand across multiple supplier brands. These intermediaries serve fragmented aftermarket repair chains with lower service level requirements than OEM direct feeds.
- Online Portals:Digital procurement platforms for aftermarket parts create last-mile complexity. Small-order, high-frequency shipments to independent garages require different network economics than bulk OEM supply.
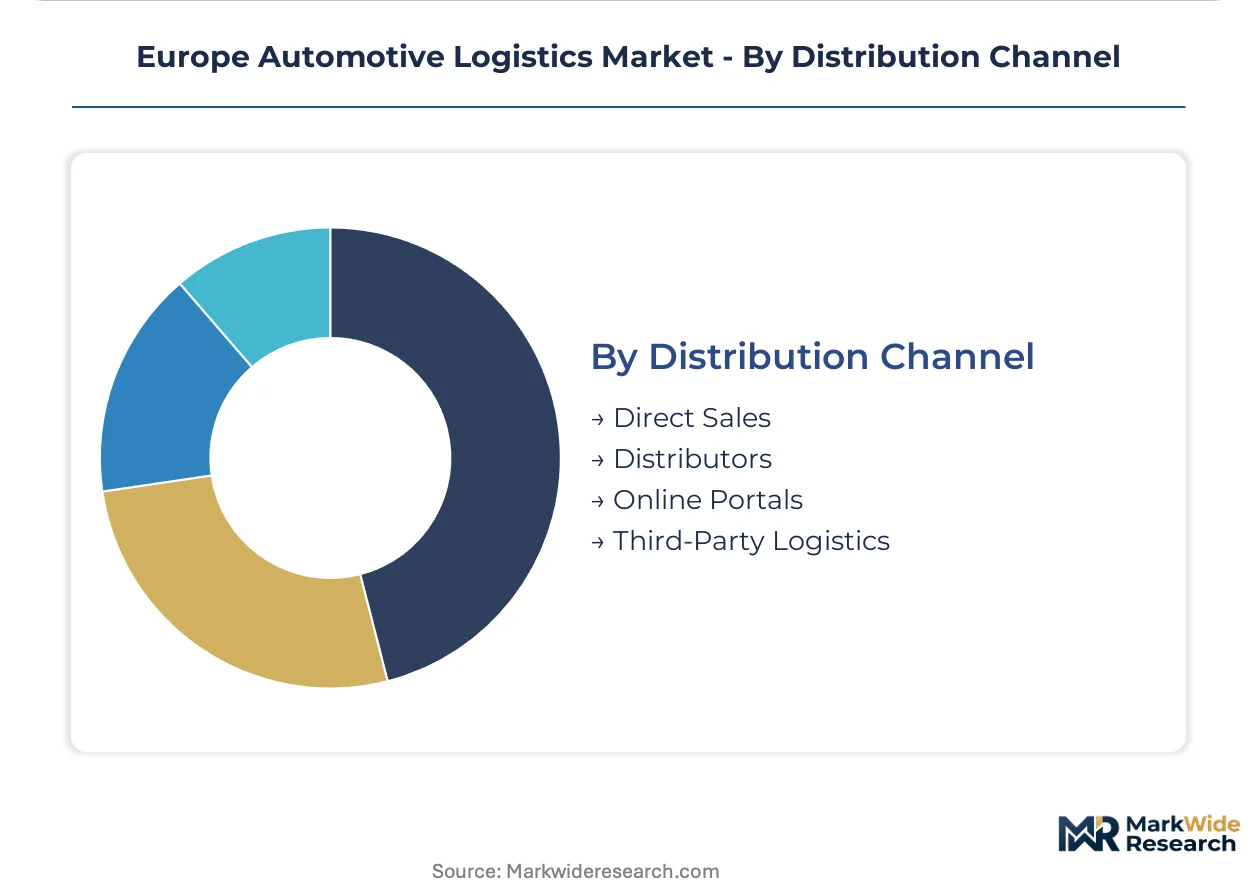
- Third-Party Logistics:Outsourced providers manage integrated transportation, warehousing, and inventory services. DHL Supply Chain, Kuehne + Nagel, and GEODIS compete across this layer with specialized EV battery protocols and cross-border rail integration. The EU AI Act's risk-based conformity requirements are reshaping automation investment timelines for these providers.
Contract value concentrates in Third-Party Logistics; Online Portals are expanding most quickly as aftermarket digitalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish Special Economic Zones anchor battery logistics concentration as gigafactory clusters generate dedicated freight corridors across Central Europe.
Germany
Bavarian and Baden-Württemberg OEM clusters absorb the densest inbound parts logistics demand on the continent. The EU Green Deal tightens supply chain emissions benchmarks, compelling Volkswagen and BMW facilities to re-source from lower-carbon European suppliers. Stuttgart sequencing centers co-located with Tier-1 suppliers operate sub-four-hour just-in-sequence delivery windows.
Poland
Central European gigafactory concentration generates dedicated cathode precursor and separator film logistics demand. REACH compliance obligations enforced by ECHA force segregation of automotive coatings in transit through Polish battery corridors. Lower Silesian and Silesian Voivodeship logistics hubs bypass traditional automotive distribution networks for cell manufacturer supply.
France
Paris Basin and Auvergne-Rhône-Alpes assembly plants anchor finished vehicle distribution networks. The EU AI Act's risk-based conformity requirements reshape automation investment timelines for French logistics operators deploying autonomous yard trucks. Cross-border rail integration at the French-Spanish frontier faces gauge incompatibility constraints for Iberian Peninsula exports.
Spain
Catalan and Basque Country automotive production faces modal shift limitations due to rail gauge breaks at the French border. Post-Brexit customs formalities complicate British component sourcing for Continental assembly plants served by Spanish suppliers. Madrid logistics operators manage specialized car-carrying equipment for finished vehicle distribution to retail networks.
Romania
Expanding vehicle parc drives aftermarket spare parts distribution whitespace across Southeastern Europe. The country's underpenetrated repair chain infrastructure lacks dedicated regional hub-and-spoke networks. Bucharest and Transylvanian logistics zones attract capital for battery second-life reverse logistics corridors serving Nordic end-of-life collection.
Europe Automotive Logistics Market Competitive Landscape
German producers anchor one tier; French and Danish specialists hold differentiated positions in multimodal integration. The vendor base concentrates around integrated 3PL networks with specialized EV battery protocols, though procurement teams increasingly unbundle transportation from warehousing contracts. Two strategic archetypes dominate: asset-heavy rail-road integrators and temperature-controlled battery corridor specialists. Competitive moves center on cross-border rail consolidation and automation capital deployment aligned with EU AI Act timelines.
Within the integrated logistics tier, DHL Supply Chain and Kuehne + Nagel exemplify providers with multimodal European networks and specialized EV battery handling protocols. GEODIS occupies a position among cross-border rail integrators offering consolidated wagonload services. DB Schenker anchors German-origin asset-heavy operations with dense OEM cluster proximity. These companies represent the strategic archetypes reshaping contract structures as procurement patterns shift toward unbundled service tenders.
| Leading Market Players |
|---|
| BLG Logistics |
| Schnellecke Logistics |
| GEODIS |
| DSV A/S |
| CMA CGM Group |
| DHL Supply Chain |
| Kuehne + Nagel |
| DB Schenker |
| Hellmann Worldwide Logistics |
| Others |
Supply & Pricing Matrix
OEM procurement teams unbundling transportation from warehousing contracts are forcing logistics providers to price services separately rather than as integrated bundles, compressing margins on standardized road freight while enabling premium capture for specialized EV battery corridors with UN 38.3 certification and thermal containment systems.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent just-in-sequence feeds commanding premium rates from scheduled bulk movements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, geographic proximity to German OEM clusters, and volume commitment scale. Cost compression in conventional powertrain logistics is intensifying because electrification reduces component counts and transport frequency. Tier-1 suppliers operating sequencing centers exhibit highest price sensitivity due to OEM price-down programs, while captive OEM fleets for battery components show lowest sensitivity given compliance mandates.
Supply Chain Analysis
Lithium concentrate supply rests on Chilean and Australian hard-rock mining operations, with cathode precursor processing concentrated in China and South Korea. European cell manufacturers source separator films from Japanese specialty producers and electrolyte salts from Belgian and German chemical plants. Single-source vulnerability for maritime bulk shipping through Rotterdam and Hamburg port congestion threatens just-in-time battery production schedules. Distribution runs through multimodal corridors combining rail consolidation across Central Europe with final-mile road feeds to assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe automotive logistics is traversing a technology-transition phase where battery-electric vehicle production infrastructure displaces legacy powertrain networks, with autonomous yard trucks and warehouse robotics governed by EU AI Act conformity requirements reshaping capital deployment timelines.
For Market Incumbents: Hedge against margin erosion in conventional automotive parts handling by accelerating thermal containment infrastructure investments for lithium-ion battery logistics. Secure UN 38.3 certification capacity ahead of competitor expansion. Deepen backward integration into cross-border rail assets to defend modal share against pure-play road carriers as EU Green Deal emissions benchmarks tighten.
For New Entrants and Emerging Players: Digital freight platforms for spot battery transport capacity offer the most penetrable entry vector, bypassing long-term contract barriers that protect established 3PL relationships. Target Romanian aftermarket spare parts distribution, where vehicle parc expansion outpaces dedicated logistics infrastructure. Pursue vendor-managed inventory contracts with mid-sized Tier-1 suppliers seeking to transfer working capital risk.
For Investors and Strategic Acquirers: The window for entry favors temperature-controlled battery corridor specialists with established ECHA REACH compliance protocols and Nordic-Central European route density. Long-term viability hinges on automation scalability aligned with EU AI Act phased implementation. Watch Polish gigafactory expansion announcements as inflection indicators for dedicated inbound logistics demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cathode precursor flows from Polish gigafactories to Nordic assembly sites. |
| Cross-Border Rail Integration | Reduces road dependency for French and German just-in-sequence deliveries. |
| Automation Capital Deployment | Aligns warehouse robotics investments with EU AI Act conformity timelines. |
| Reverse Logistics Network Buildout | Captures end-of-life battery collection from Nordic markets to refurbishers. |
| REACH Compliance Certification | Enables premium handling of automotive coatings and adhesives in transit. |
Research Methodology
Multi-period observation of vehicle production volumes, battery gigafactory commissioning timelines, and logistics contract award patterns anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution executives, and sequencing center operations managers. Secondary validation drew from EU vehicle registration databases, ECHA regulatory filings, IHS Markit production data, and customs trade statistics. Bottom-up segment sizing triangulated against top-down market value estimates.
Segment-weighting across service type, end user, vehicle type, and distribution channel dimensions informed the analytical framework. CAGRs were derived from production volume trajectories, electrification penetration curves, and logistics intensity per vehicle class across the projection horizon. Industry-specific forecast inputs included battery cell capacity expansion schedules and EU Green Deal compliance cost assumptions.
The model holds under stable regulatory implementation timelines for EU AI Act and Corporate Sustainability Due Diligence Directive; deviation in lithium supply disruptions or Polish gigafactory delays would shift corridor demand projections. Forecasts reflect documented assumptions with acknowledged sensitivity to maritime shipping volatility and cross-border customs formalities evolution. A small set of named triggers—battery chemistry transitions, rail gauge harmonization progress, and automation conformity acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Refrigerated Container Shipping Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
Spare Part Logistics Market
Logistics and Shipping
Shipping Container Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market