
 ASEAN Courier, Express, and Parcel (CEP) Market | 2026-2036
ASEAN Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Courier, Express, and Parcel (CEP) Market Insights
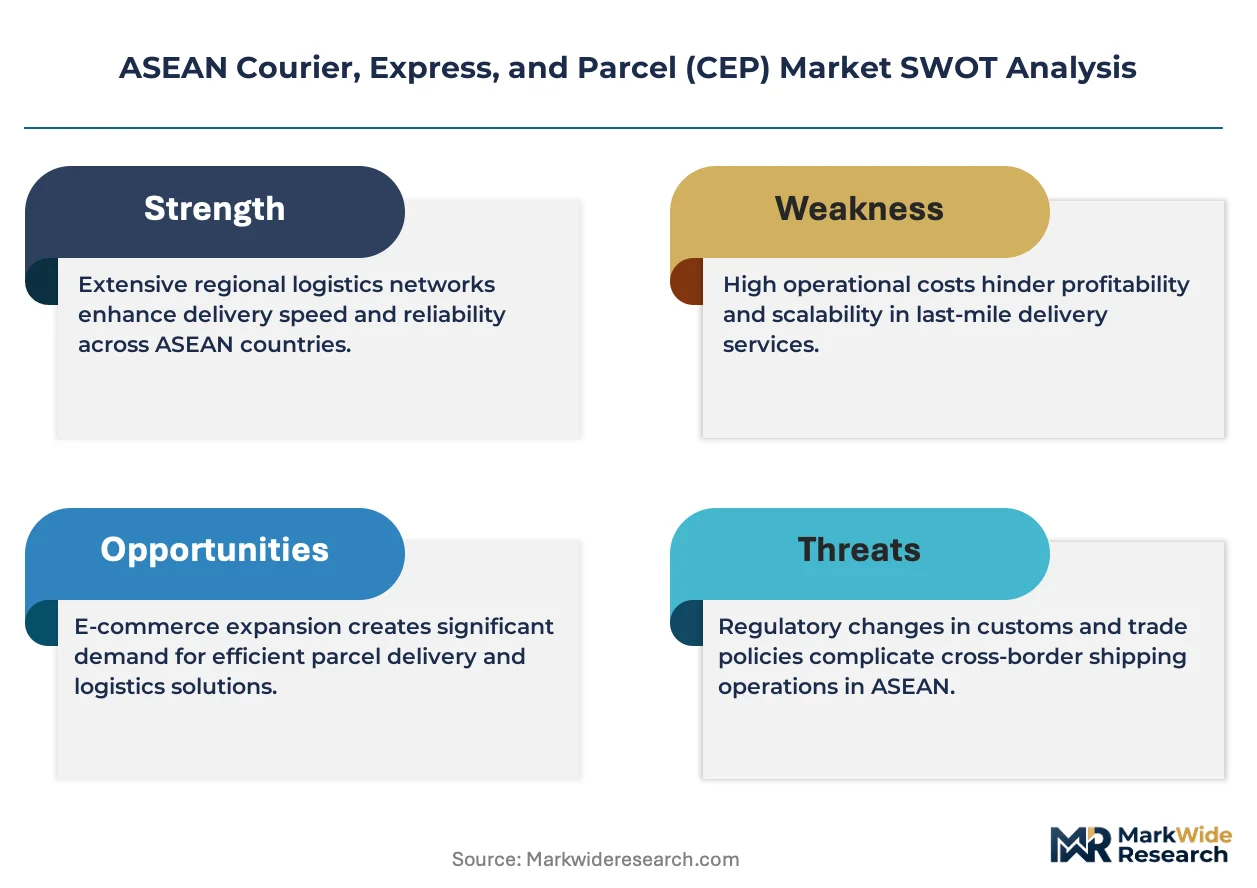
Biodegradable packaging films are rebalancing last-mile delivery economics across humid ASEAN climates. J&T Express leverages its Indonesia-origin density to sustain cost leadership in archipelagic routing. FedEx anchors premium express corridors connecting ASEAN manufacturing zones to North American and European destinations.
Courier, Express, and Parcel (CEP) services constitute a logistics infrastructure layer encompassing time-definite collection, sortation, line-haul transport, and final delivery of documents and merchandise, typically operating within service level agreements of 24 to 72 hours for express products and 3 to 7 days for standard products. The primary commercial purpose is enabling supply chain velocity for businesses and direct-to-consumer fulfillment. Express delivery commands premium pricing power in cross-border lanes where customs brokerage integration determines speed reliability, while same-day delivery represents the fastest-growing structural segment as urban consolidation centers proliferate in metro Manila and Kuala Lumpur. E-commerce end users dominate volume absorption, though healthcare cold-chain parcels generate disproportionate margin pools due to temperature compliance requirements.
Thailand Post operates under the Electronic Transactions Act and postal regulator oversight, while cross-border flows face customs harmonization pressures from the ASEAN Economic Community framework and individual member state revenue authorities. Vietnam's Ministry of Industry and Trade enforces e-commerce logistics standards that shape warehouse certification and last-mile operator licensing. Stakeholders must monitor how divergent national data localization rules affect parcel tracking infrastructure investments and cross-platform interoperability.
Market Dynamics
E-commerce parcel density in Jakarta, Bangkok, and Ho Chi Minh City is compressing delivery windows and forcing warehouse placement decisions closer to urban cores. This demand concentration is restructuring last-mile networks across archipelagic and mainland ASEAN markets alike.
Growth Catalysts
- ASEAN Single Window:Cross-border customs harmonization is reducing clearance friction for parcel flows between member states, accelerating intra-regional trade velocity.
- Cold-chain pharmaceuticals:Temperature-controlled parcel demand from healthcare logistics is expanding premium service tiers and specialized fleet investments.
- Digital payment penetration:Mobile wallet adoption across Indonesia, Thailand, and Vietnam is converting cash-on-delivery volumes to prepaid transactions, reducing failed delivery rates and route optimization complexity.
Market Restraints
- Fuel cost volatility:Diesel price fluctuations directly impact line-haul economics across Indonesia's 17,000-island archipelago, where inter-island ferry and air freight dependencies concentrate cost exposure.
- Customs divergence:Despite ASEAN Economic Community framework commitments, national revenue authorities maintain divergent valuation rules and de minimis thresholds that fragment cross-border parcel processing.
- Last-mile labor scarcity:Motorcycle courier turnover rates in metro Manila and Kuala Lumpur exceed 40% annually, inflating recruitment and training overhead for same-day operators.
Strategic Opportunities
- Secondary city penetration:Surabaya, Bandung, and Da Nang exhibit parcel volume growth rates double those of capital cities, with warehouse vacancy rates 15-20 percentage points higher.
- Biodegradable packaging mandate alignment:Vietnam's Ministry of Industry and Trade e-commerce logistics standards are creating certification premiums for sustainable last-mile operators.
- Cross-border B2B integration:Manufacturing supply chains linking ASEAN production zones to China and India require time-definite component delivery services currently underserved by generalist parcel networks.
Industry Challenges
- Fleet electrification capex:Two-wheeler and light commercial vehicle conversion requirements under national decarbonization commitments demand capital deployment without proven total-cost-of-ownership models for tropical humidity conditions.
- Data localization fragmentation:Divergent national rules on parcel tracking data storage are forcing redundant infrastructure investments that compromise cross-platform interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Courier, Express, and Parcel (CEP) Market |
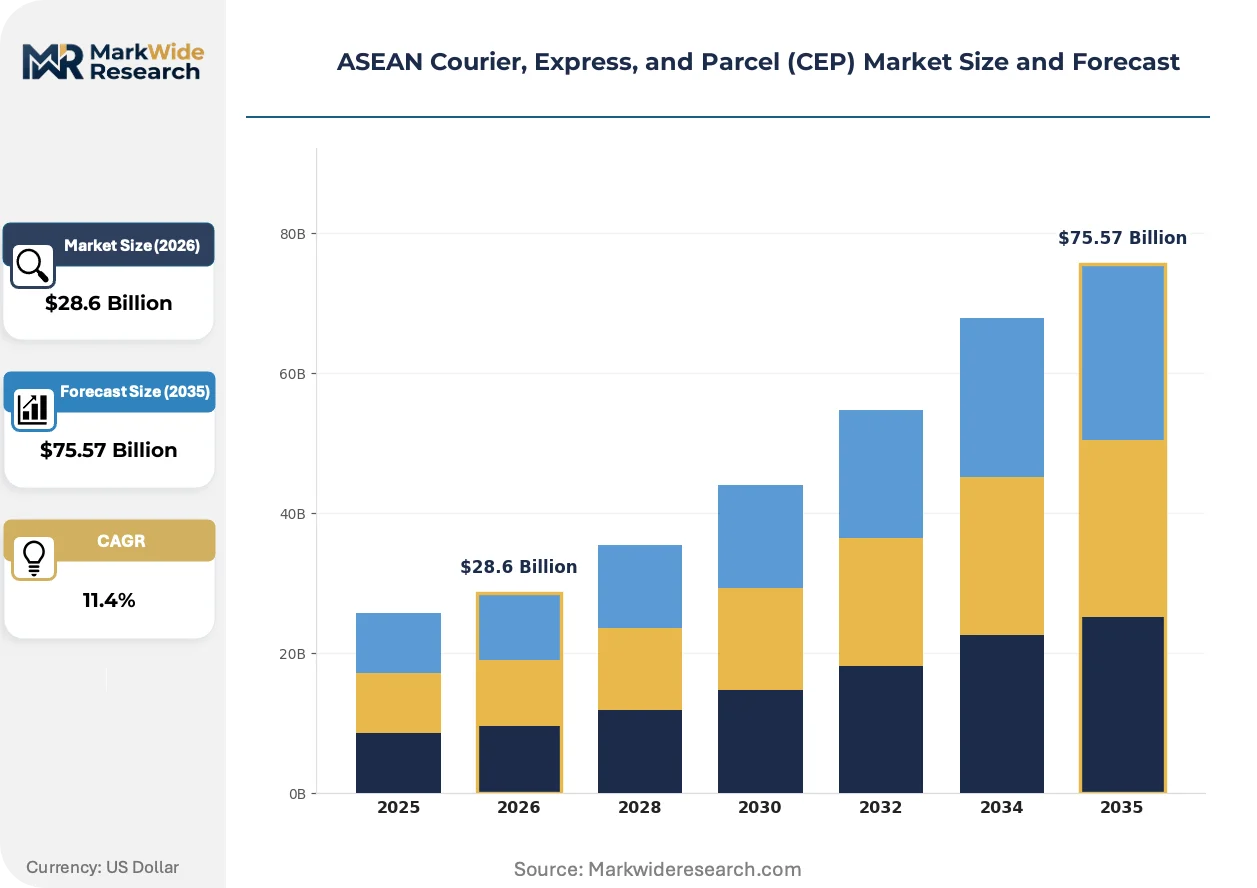
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Express Delivery, Same Day Delivery, Next Day Delivery Packaging Type: Box, Envelope, Crate, Pallet End User: E-commerce, Retail, Healthcare, Manufacturing Distribution Channel: Online, Offline, Third-Party Logistics, In-house |
| Companies Covered | DHL Group, FedEx, J&T Express, SF Express (KEX-SF), United Parcel Service of America, Inc. (UPS), Ninja Logistics, Pos Malaysia Berhad, PT Pos Indonesia (Persero), Thailand Post, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Courier, Express, and Parcel (CEP) Market Trends and Innovations
Automation is penetrating sortation and final-mile handoff processes as labor costs rise and service-level guarantees tighten. These shifts are compressing the viable technology adoption window for mid-scale operators.
Autonomous mobile robots in warehouse sortation facilities are absorbing repetitive parcel handling tasks previously performed by manual labor. E-commerce fulfillment centers in Singapore and Bangkok are deploying these systems at commercial scale. The technology is absorbing floor space optimization constraints and enabling higher throughput per square meter in land-scarce urban logistics zones.
Vietnam's e-commerce logistics standards under the Ministry of Industry and Trade are mandating warehouse certification tiers that differentiate operator licensing eligibility. Facilities meeting Grade A certification gain preferential access to cross-border e-commerce clearance lanes. Cold-chain parcel operators are responding fastest due to existing compliance infrastructure for temperature validation protocols.
Buyer expectations for delivery window precision are compressing switching costs between competing platforms. Urban consumers in Jakarta and Ho Chi Minh City now evaluate couriers on 30-minute delivery slot accuracy rather than day-definite guarantees. This behavioral shift is most visible in grocery and quick-commerce verticals, where basket size thresholds for free delivery are declining while frequency rises.
ASEAN Courier, Express, and Parcel (CEP) Market Segmentation
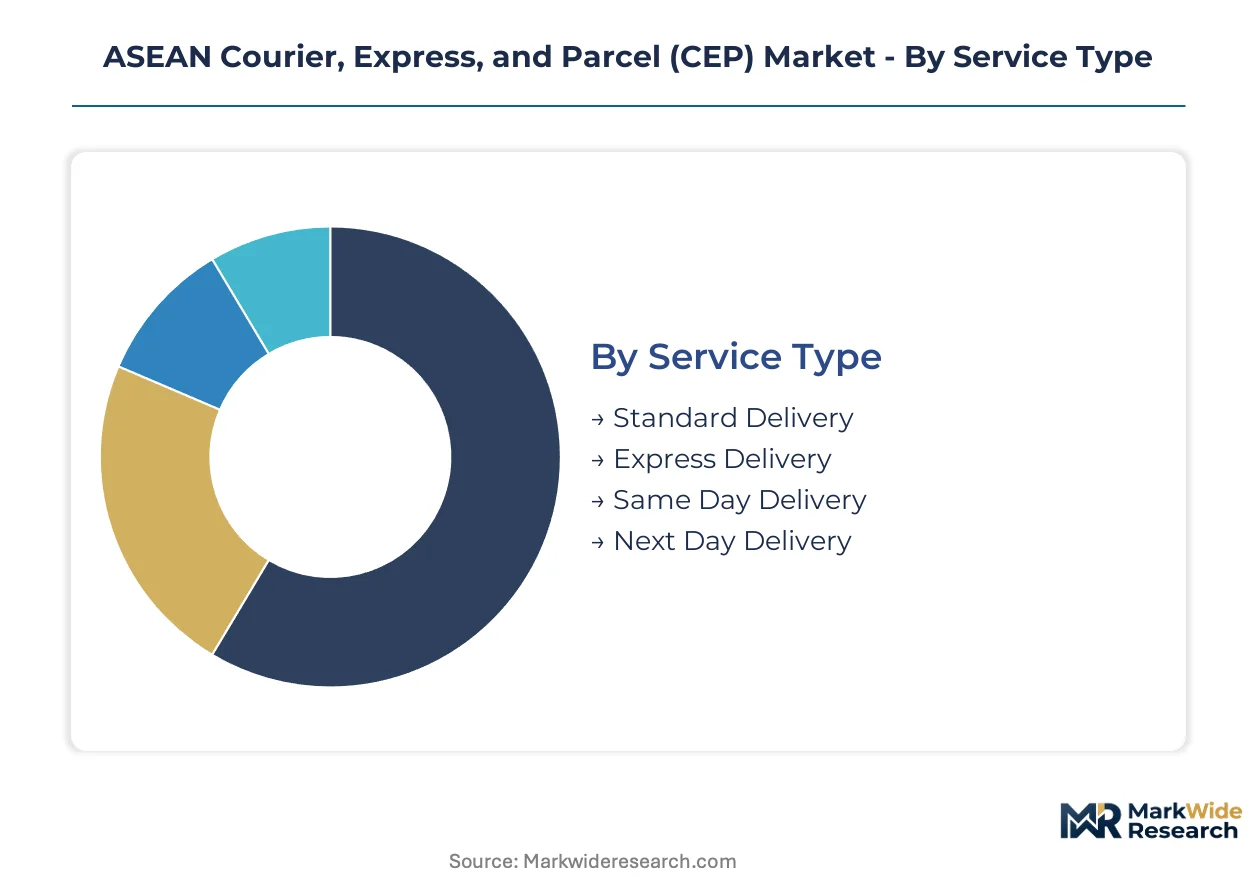
Segmentation in ASEAN CEP markets reveals how service tiers, packaging formats, and channel structures align with divergent cost sensitivities across archipelagic and mainland geographies. Understanding these divisions exposes where margin pools concentrate versus where volume commoditization pressures dominate.
Service Type:
Standalone express products command premium positioning, while same-day and next-day offerings embed increasingly into integrated logistics platforms.
- Standard Delivery:Three-to-seven-day service level agreements with minimal tracking granularity. Demand concentrates in secondary Indonesian cities where infrastructure gaps limit faster alternatives and cost sensitivity overrides velocity requirements.
- Express Delivery:Twenty-four-to-seventy-two-hour time-definite services with customs brokerage integration. Bangkok and Jakarta manufacturing zones drive absorption for cross-border document and component flows where reliability premiums justify pricing.
- Same Day Delivery:Urban-constrained fulfillment from micro-fulfillment centers.
- Next Day Delivery:Overnight line-haul networks with morning delivery guarantees.
Standard delivery leads volumes today; same-day delivery is gaining share fastest.
Packaging Type:
Cost tiers separate disposable single-use formats from returnable assets, with humidity resistance and stack density determining suitability for tropical ASEAN conditions.
- Box:Corrugated fiberboard containers in standardized cubic dimensions. E-commerce apparel and electronics shipments from Ho Chi Minh City fulfillment centers dominate demand, with Vietnam's biodegradable packaging mandates reshaping material specifications.
- Envelope:Lightweight document pouches with tamper-evident seals. Financial services and legal documentation flows between Singapore and Kuala Lumpur sustain this segment despite digitization headwinds.
- Crate:Reusable plastic or wooden containers for high-value merchandise.
- Pallet:Unitized load platforms for B2B freight parcel consolidation.
Box formats dominate shipment counts; envelope volumes are contracting most rapidly.
End User:
Customer-type segmentation separates high-frequency low-margin e-commerce absorption from specialized compliance-heavy verticals with divergent service requirements.
- E-commerce:Direct-to-consumer parcel flows from marketplace sellers and brand.com operations. Indonesia's Tokopedia and Shopee volumes compress per-unit economics while forcing last-mile network densification in Jakarta, Surabaya, and Bandung.
- Healthcare:Temperature-controlled pharmaceutical and medical device logistics. Cold-chain compliance requirements for vaccines and biologics generate disproportionate margin contributions despite lower absolute shipment counts.
- Retail:Omnichannel fulfillment bridging physical stores and digital orders.
- Manufacturing:Just-in-time component delivery for production line feeding.
E-commerce absorbs the greatest parcel volumes; healthcare delivers the steepest margin expansion trajectory.
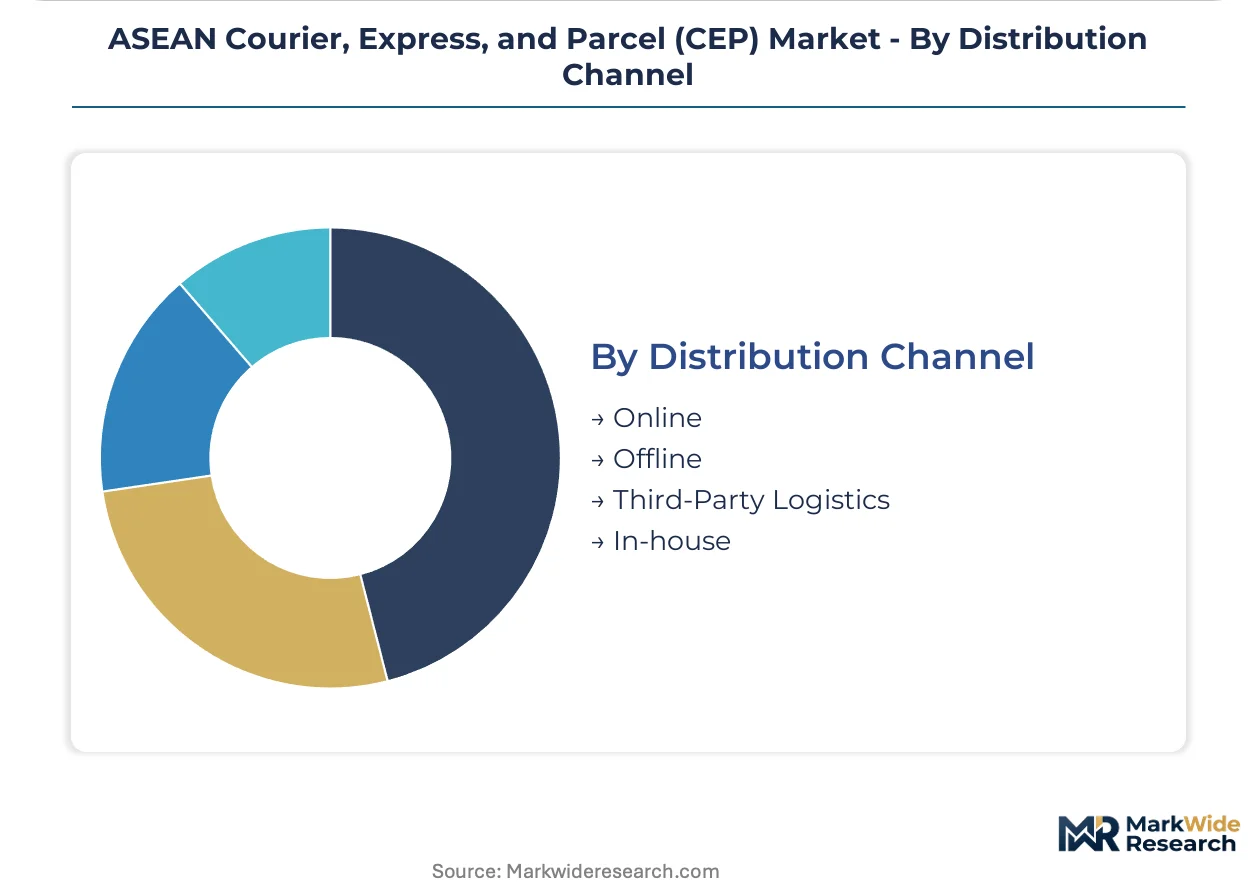
Distribution Channel:
Channel structure determines capital intensity and control depth, with asset-heavy in-house operations contrasting against variable-cost third-party arrangements.
- Third-Party Logistics:Outsourced fulfillment and delivery execution by specialized operators. Thailand's Kerry Express and Indonesia's J&T Express leverage network density to serve mid-market e-commerce merchants lacking captive infrastructure.
- In-house:Captive logistics operations owned by major platforms or retailers. Shopee Xpress and Lazada Logistics control vertical delivery stacks to guarantee service levels and capture data flows in the Philippines and Vietnam.
- Online:Digital-native booking and tracking interfaces.
- Offline:Physical counter and agent-based parcel submission.
Third-party logistics handles the majority of external merchant volumes; in-house channels are expanding most quickly among major platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta-Bandung-Surabaya corridor commands the densest parcel flows in ASEAN, with warehouse placement decisions increasingly favoring secondary city penetration over capital-centric concentration.
Indonesia
Archipelagic routing complexity and e-commerce volume surges from Tokopedia and Shopee drive logistics network densification. The Ministry of Communication and Informatics enforces data localization requirements affecting parcel tracking infrastructure. Surabaya and Bandung exhibit parcel growth rates double those of Jakarta, with warehouse vacancy rates 15-20 percentage points higher.
Thailand
Bangkok manufacturing zones generate cross-border express demand for time-definite component delivery to North American and European destinations. The Electronic Transactions Act and postal regulator oversight shape Thailand Post operations and market entry conditions. Same-day delivery corridors in Greater Bangkok concentrate logistics investment and micro-fulfillment center development.
Vietnam
Ho Chi Minh City fulfillment centers dominate e-commerce apparel and electronics shipment volumes as digital payment penetration deepens. The Ministry of Industry and Trade enforces e-commerce logistics standards that mandate warehouse certification tiers and differentiate operator licensing eligibility. Da Nang exhibits parcel volume growth rates exceeding capital city benchmarks.
Singapore
Intermodal transshipment hub status generates premium express corridor demand connecting ASEAN manufacturing zones to global destinations. The Infocomm Media Development Authority governs data governance frameworks affecting cross-platform parcel tracking interoperability. E-commerce fulfillment centers deploy autonomous mobile robots at commercial scale to absorb floor space constraints.
Philippines
Metro Manila's motorcycle courier networks face labor scarcity pressures with annual turnover rates exceeding 40%. The Department of Trade and Industry oversees e-commerce logistics frameworks affecting last-mile operator licensing. Shopee Xpress and Lazada Logistics control vertical delivery stacks to guarantee service levels and capture data flows.
ASEAN Courier, Express, and Parcel (CEP) Market Competitive Landscape
Global majors compete with regional champions across network density and cost leadership, producing a tiered market structure where premium express corridors sit alongside archipelagic volume specialists. The vendor base separates into three strategic archetypes: integrated global networks with customs brokerage depth, Indonesia-origin archipelagic specialists leveraging origin density, and platform-captive logistics operations controlling vertical delivery stacks. Dominant competitive moves include warehouse placement optimization toward urban cores and fleet electrification investments under national decarbonization commitments.
Within the integrated global network tier, DHL Group and FedEx anchor premium express corridors with customs brokerage integration determining speed reliability. J&T Express exemplifies the archipelagic specialist archetype, leveraging Indonesia-origin density to sustain cost leadership in complex routing environments. United Parcel Service of America, Inc. occupies a position bridging premium international lanes with intra-ASEAN connectivity.
| Leading Market Players |
|---|
| DHL Group |
| FedEx |
| J&T Express |
| SF Express (KEX-SF) |
| United Parcel Service of America, Inc. (UPS) |
| Ninja Logistics |
| Pos Malaysia Berhad |
| PT Pos Indonesia (Persero) |
| Thailand Post |
| Others |
Pricing and Supply Chain Analysis
E-commerce platform procurement concentration in Indonesia, Thailand, and Vietnam anchors pricing power with volume-scale operators, compressing per-unit economics while rewarding network density with contract premiums. Fuel cost pass-through mechanisms and last-mile labor rates determine margin sustainability across archipelagic and mainland routing environments.
Pricing Analysis
Fuel cost pass-through clauses dominate contract structures for inter-island ferry and air freight dependencies across Indonesia's archipelago, with diesel price volatility directly impacting line-haul economics. Three-tier pricing structure across premium express, standard parcel, and economy deferred delivery separates time-definite guarantees from cost-optimized alternatives. Pricing pressure stems from motorcycle courier turnover exceeding 40% annually in metro Manila and Kuala Lumpur, inflating recruitment overhead for same-day operators. E-commerce merchants exhibit highest price sensitivity, while healthcare cold-chain logistics tolerate premium rates for temperature compliance certification.
Supply Chain Analysis
Regional distribution centers in Jakarta, Bangkok, and Ho Chi Minh City anchor hub-and-spoke patterns, with secondary city penetration into Surabaya, Bandung, and Da Nang absorbing growth overflow. Fleet assets draw from Japanese and Korean commercial vehicle manufacturers, while biodegradable packaging materials feed from Vietnamese and Thai film extrusion facilities. Single-source vulnerability concentrates in Indonesia-origin archipelagic routing specialists controlling critical inter-island ferry connections. Distribution runs through third-party logistics networks for external merchants, though platform-captive vertical stacks are expanding fastest among major e-commerce operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ASEAN CEP markets rests on cold-chain premium tier penetration and fleet electrification cost-down curves, with digital payment conversion reducing failed delivery waste.
For Market Incumbents: Cement archipelagic density advantages through warehouse placement optimization toward Surabaya and Bandung corridors, where vacancy rates exceed capital city benchmarks by 15-20 percentage points. Defend against platform-captive logistics verticalization by deepening customs brokerage integration for cross-border express lanes. Certification investment in Vietnam's Grade A warehouse tiers secures preferential e-commerce clearance access. For New Entrants and Emerging Players: The mid-market price-point gap between J&T Express cost leadership and FedEx premium positioning offers white-space entry for regional specialists. Target secondary city same-day corridors in Da Nang and Cebu, where parcel growth doubles capital city rates with lower competitive saturation. Go-to-market through biodegradable packaging mandate alignment captures Vietnam certification premiums. For Investors and Strategic Acquirers: E-commerce platforms are the most active acquirer in this space, seeking vertical delivery stack control to guarantee service levels and capture data flows. Long-term viability favors operators with cold-chain compliance infrastructure and archipelagic routing algorithms. Watch for ASEAN Single Window harmonization completion as inflection indicator for cross-border express margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Secondary City Warehouse Expansion | Surabaya and Bandung vacancy premiums enable 15-20 point cost advantages over Jakarta saturation. |
| Biodegradable Packaging Certification | Vietnam's Ministry of Industry and Trade standards create licensing eligibility differentiation for compliant operators. |
| Cold-Chain Fleet Investment | Temperature-controlled pharmaceutical demand generates disproportionate margin pools despite lower shipment counts. |
| Customs Brokerage Integration | ASEAN Single Window harmonization reduces clearance friction for cross-border parcel velocity premiums. |
| Platform Vertical Integration | Shopee Xpress and Lazada Logistics captive stacks guarantee service levels and capture consumer data flows. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with logistics network planners, e-commerce operations directors, cold-chain compliance officers, and last-mile fleet managers with secondary validation from customs authority publications, Ministry of Industry and Trade regulatory filings, and ASEAN Single Window implementation reports. Bottom-up parcel volume modeling triangulated against top-down GDP-correlation approaches.
Segment-weighting across service type, packaging format, end user vertical, and distribution channel dimensions shaped the analytical framework across the projection horizon. CAGRs derived from logistics infrastructure investment cycles, e-commerce penetration trajectories, and digital payment adoption curves. Forecast inputs incorporated fuel cost volatility scenarios and national decarbonization commitment timelines for fleet electrification.
Caveats apply where ASEAN Single Window harmonization delays, fuel subsidy policy reversals, or data localization rule divergence could materially shift the outlook. Forecasts reflect documented assumptions about e-commerce growth sustainability and customs processing efficiency gains. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Digital Freight Forwarding Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
India Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
China Digital Freight Forwarding Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Cold Chain Logistics Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Netherlands Freight and Logistics Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
Rail Logistics Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
Italy Freight and Logistics Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Canada Freight and Logistics Market