
 North America Last Mile Delivery Market | 2026-2036
North America Last Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Last Mile Delivery Market Insights
California's Advanced Clean Trucks regulation is hardening compliance costs for diesel-dependent carriers entering the state's logistics corridors. United Parcel Service leverages its integrated ground network to sustain density advantages in suburban zones. Amazon Logistics anchors fulfillment capacity within two-day delivery radii of major metropolitan clusters. FedEx Corp. competes through specialized healthcare and temperature-controlled delivery infrastructure.
Last mile delivery denotes the final transportation leg from distribution hub to end recipient, typically spanning distances under 100 miles with delivery windows compressed to same-day or next-day service. Electric vans now dominate fleet procurement decisions as operators balance payload capacity against zero-emission mandates in urban cores. Route optimization software leads technology adoption by reducing per-stop costs, while drone delivery remains nascent due to FAA operational restrictions over populated areas. Grocery chains represent the fastest-growing customer segment as cold-chain capabilities expand.
The EPA, FAA, and DOT collectively shape market access through emissions standards, unmanned aircraft integration rules, and hours-of-service regulations for commercial drivers. California's Air Resources Board enforces the most stringent state-level truck electrification timeline, forcing cross-border operators to maintain dual fleet configurations. Stakeholders must monitor evolving state-level zero-emission vehicle mandates to determine capital allocation between electric infrastructure and compliance hedging strategies.
Market Dynamics
EPA's Phase 3 greenhouse gas standards are compressing fleet turnover timelines across U.S. logistics corridors. Carriers must now reconcile diesel asset depreciation against electrification capex cycles measured in months rather than years.
Growth Catalysts
- California's Advanced Clean Trucks Regulation:Mandates zero-emission vehicle sales quotas that force fleet operators into electric van procurement, expanding charging infrastructure deployment across the state's logistics corridors.
- Grocery chains:Cold-chain capability investments by supermarket operators are generating dedicated last mile capacity demands that specialized carriers are racing to fulfill.
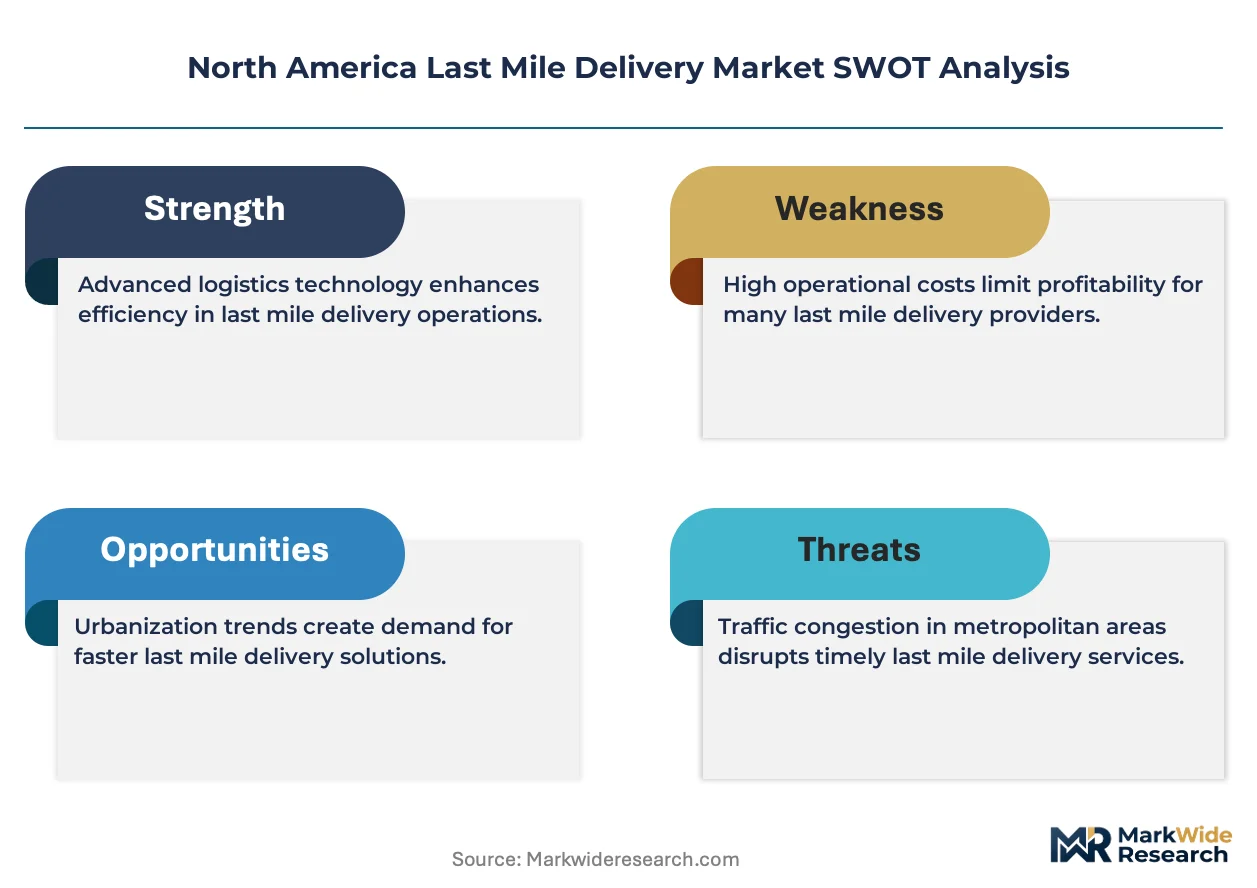
- Route optimization software:Algorithmic dispatch systems are reducing per-stop costs by consolidating delivery windows and minimizing empty miles in dense suburban zones.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing dominance in East Asian supply chains creates input cost volatility for North American electric van operators.
- FAA Part 135 operational restrictions:Unmanned aircraft delivery remains structurally blocked over populated areas, limiting drone network expansion to rural exurbs.
- Driver hours-of-service regulations:DOT compliance requirements cap daily delivery capacity per vehicle, constraining same-day fulfillment scaling without proportional fleet expansion.
Strategic Opportunities
- Texas logistics corridors:Absence of California-equivalent zero-emission mandates creates arbitrage space for diesel-efficient fleets serving cross-border freight flows.
- Healthcare temperature-controlled delivery:Biopharma cold-chain requirements are opening premium service tiers that command specialized certification premiums.
- Renewable natural gas infrastructure:RNG refueling networks offer compliance bridge strategy for carriers hedging against full electrification capex exposure.
Industry Challenges
- Commercial driver qualification standards:CDL certification timelines and retention pressures constrain fleet scaling velocity during demand surges.
- Dual fleet configuration complexity:Cross-border operators maintaining California-compliant electric assets alongside diesel units face maintenance skill fragmentation and parts inventory duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Last Mile Delivery Market |
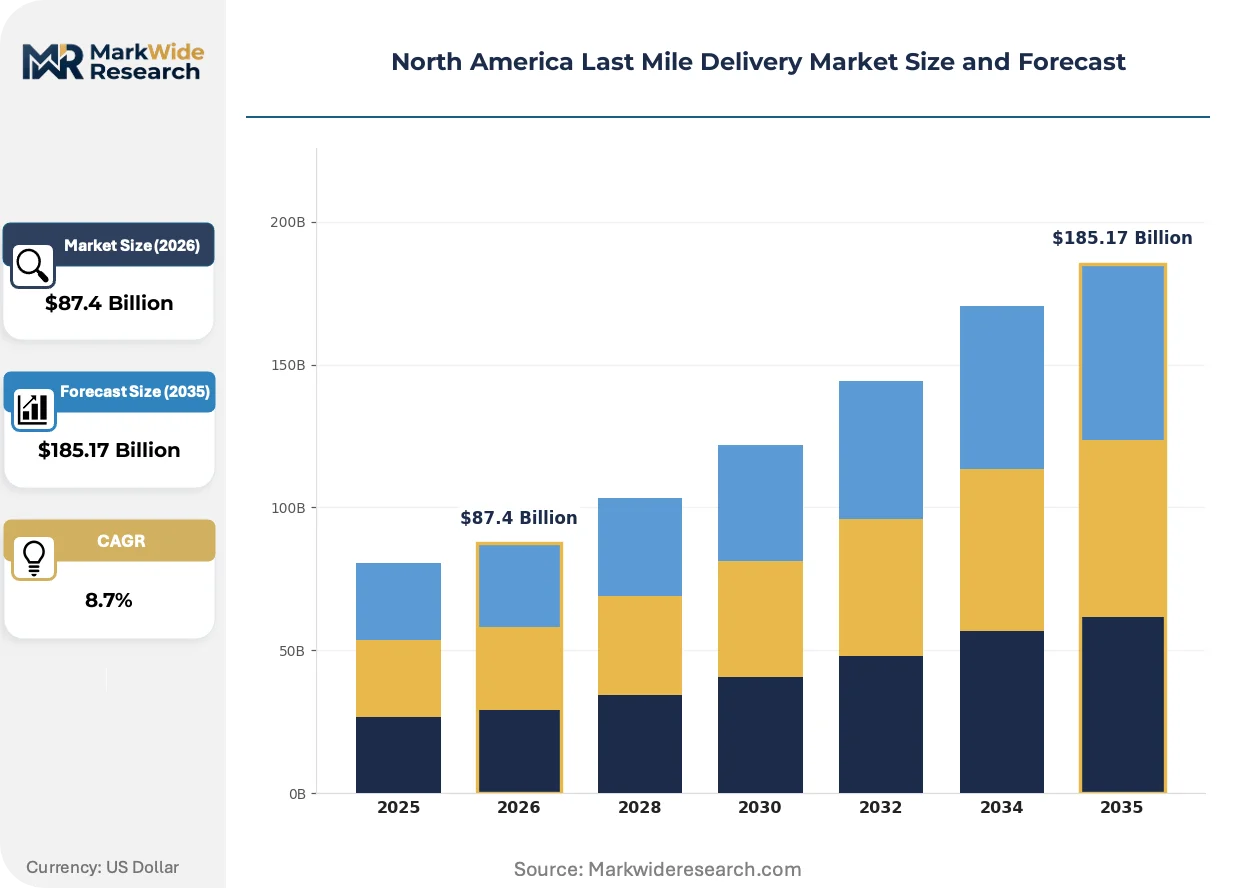
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, Express Delivery Delivery Vehicle: Bicycles, Electric Vans, Motorcycles, Drones Customer Segment: E-commerce Retailers, Grocery Chains, Restaurants, Pharmaceutical Companies Technology: Route Optimization Software, Real-Time Tracking, Automated Dispatch, Mobile Apps |
| Companies Covered | FedEx Corp., United Parcel Service, Amazon Logistics, XPO Inc., ArcBest Corp., Ryder System Inc., United States Postal Service, Instacart, DoorDash, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Last Mile Delivery Market Trends and Innovations
Delivery infrastructure is fragmenting into specialized nodes optimized for speed-tier segmentation. Technology deployment now precedes regulatory clarity, forcing operators into speculative asset positioning.
Electric van battery architecture is modularizing around swappable pack designs that separate vehicle chassis from energy storage assets. Fleet operators in California's South Coast Air Basin are piloting battery-as-a-service models to decouple vehicle procurement from cell technology obsolescence risk. This structure is compressing total cost of ownership calculations by shifting degradation risk to third-party energy providers.
EPA Phase 3 standards are mandating CO2 emissions reductions of 85% below current baselines for heavy-duty vehicles by model year 2032. Fleet operators must now front-load electrification investments ahead of residual diesel asset value collapse. California-based carriers face the steepest compliance curve, with the Air Resources Board enforcing interim targets that precede federal deadlines.
Same-day fulfillment expectations are compressing delivery window commitments from next-day to four-hour and two-hour slots. Grocery and quick-commerce verticals are displacing traditional e-commerce as the primary demand drivers, forcing warehouse repositioning into urban cores. This shift concentrates operational risk in high-real-estate-cost zones where density economics determine survival.
North America Last Mile Delivery Market Segmentation
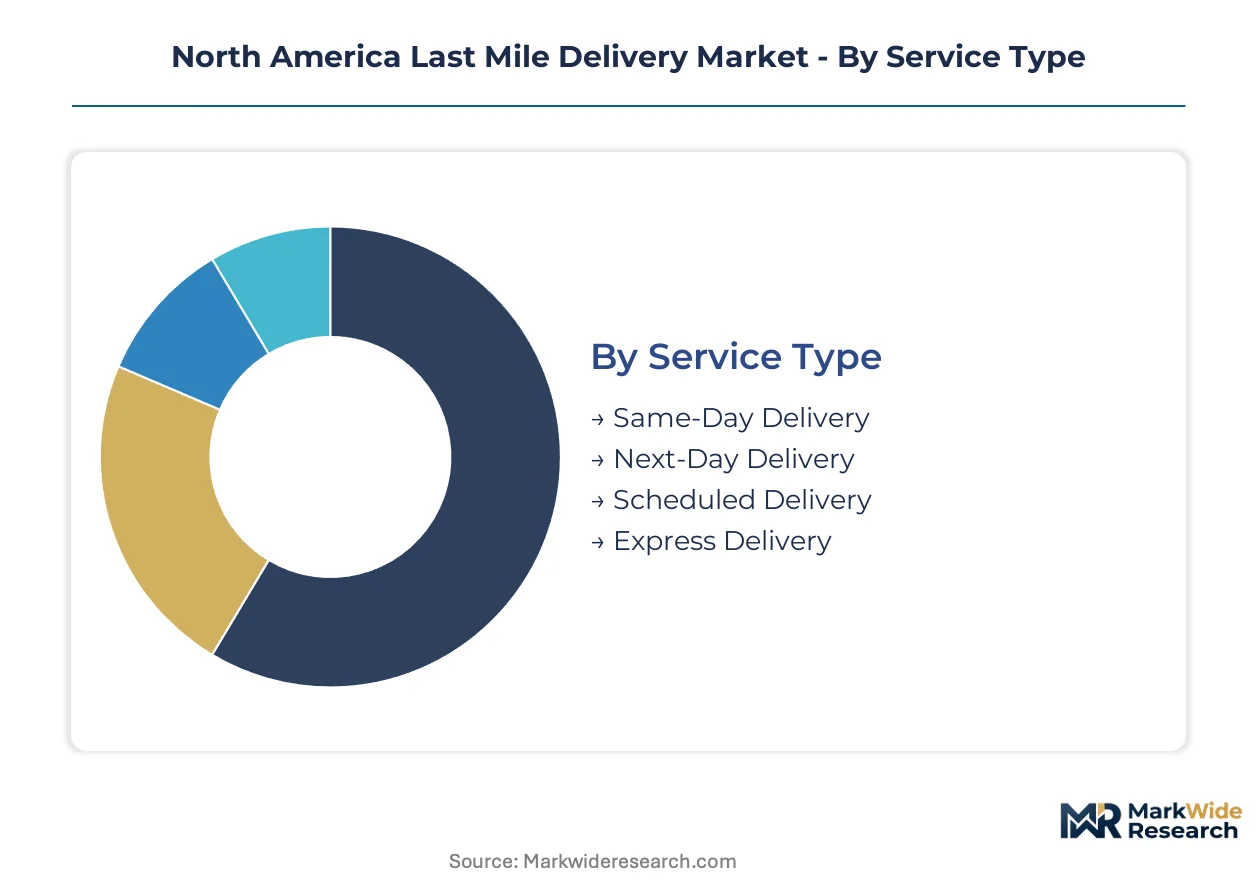
Segmentation in last mile delivery reveals how carriers align capital deployment with service-level economics. Fleet configuration, customer contract structures, and technology stacks vary sharply across these dimensions.
Service Type:
Upgrade cycles in service tiers track e-commerce fulfillment expectations, with retailers compressing delivery windows to capture basket share.
- Same-Day Delivery:Requires urban micro-fulfillment nodes positioned within 15-mile radii of dense population centers. Demand clusters in California's Los Angeles Basin and New York metro corridors where real estate costs force warehouse stacking strategies. Amazon Logistics and Instacart anchor capacity here, absorbing premium labor costs through subscription bundling.
- Next-Day Delivery:Balances network reach against inventory positioning, utilizing regional sortation hubs 50-100 miles from end recipients. United Parcel Service and FedEx Corp. dominate this tier through integrated ground networks that amortize fixed infrastructure across predictable volume flows.
- Scheduled Delivery:Targets furniture, appliance, and large-format goods requiring white-glove handling or installation coordination. Carriers optimize route density through appointment clustering rather than speed.
- Express Delivery:Commands highest per-package yields for time-critical documents, medical specimens, and replacement parts. FedEx Priority Overnight and UPS Next Day Air maintain dedicated aircraft and morning delivery guarantees.
Volume placements concentrate in Next-Day Delivery; the faster expansion belongs to Same-Day Delivery.
Delivery Vehicle:
Vehicle procurement decisions now hinge on regulatory compliance timelines rather than total cost of ownership alone.
- Electric Vans:Dominating fleet replacement programs as EPA Phase 3 standards and California's Advanced Clean Trucks regulation force zero-emission adoption. Ford E-Transit and Rivian Commercial Van lead North American deployments, with payload tradeoffs accepted to secure CARB compliance credits.
- Bicycles:Courier fleets in Manhattan, San Francisco, and Chicago central business districts exploit bicycle lane infrastructure to bypass congestion pricing zones. Caviar and DoorDash deploy pedal-powered units for sub-3-mile food and grocery circuits.
- Motorcycles:Retain niche in Sun Belt metros where parking scarcity matters less than speed, particularly for document and pharmaceutical courier services.
- Drones:FAA Part 135 restrictions limit operations to rural exurbs and select suburban zones; Wing Aviation and Zipline pilot programs in Texas and North Carolina test beyond-visual-line-of-sight frameworks.
Fleet investments cluster on Electric Vans; regulatory pressure is steepest in this segment.
Customer Segment:
Customer mix determines warehouse location strategy and cold-chain capital intensity.
- Grocery Chains:Kroger, Albertsons, and regional supermarket operators are expanding dedicated last mile capacity with temperature-controlled compartmentalization. Same-day grocery fulfillment demands urban dark stores that reconfigure retail footprints into fulfillment nodes.
- E-commerce Retailers:Amazon, Walmart, and Target anchor volume, pushing delivery windows toward four-hour and two-hour commitments. These operators internalize logistics to capture data and control customer experience.
- Restaurants:DoorDash, Uber Eats, and Grubhub aggregate fragmented local supply, utilizing gig driver pools rather than captive fleets.
- Pharmaceutical Companies:CVS Health and Walgreens Boots Alliance require HIPAA-compliant chain of custody with temperature validation, opening premium service tiers that specialized carriers command.
Contract values concentrate with E-commerce Retailers; Grocery Chains are climbing the fastest.
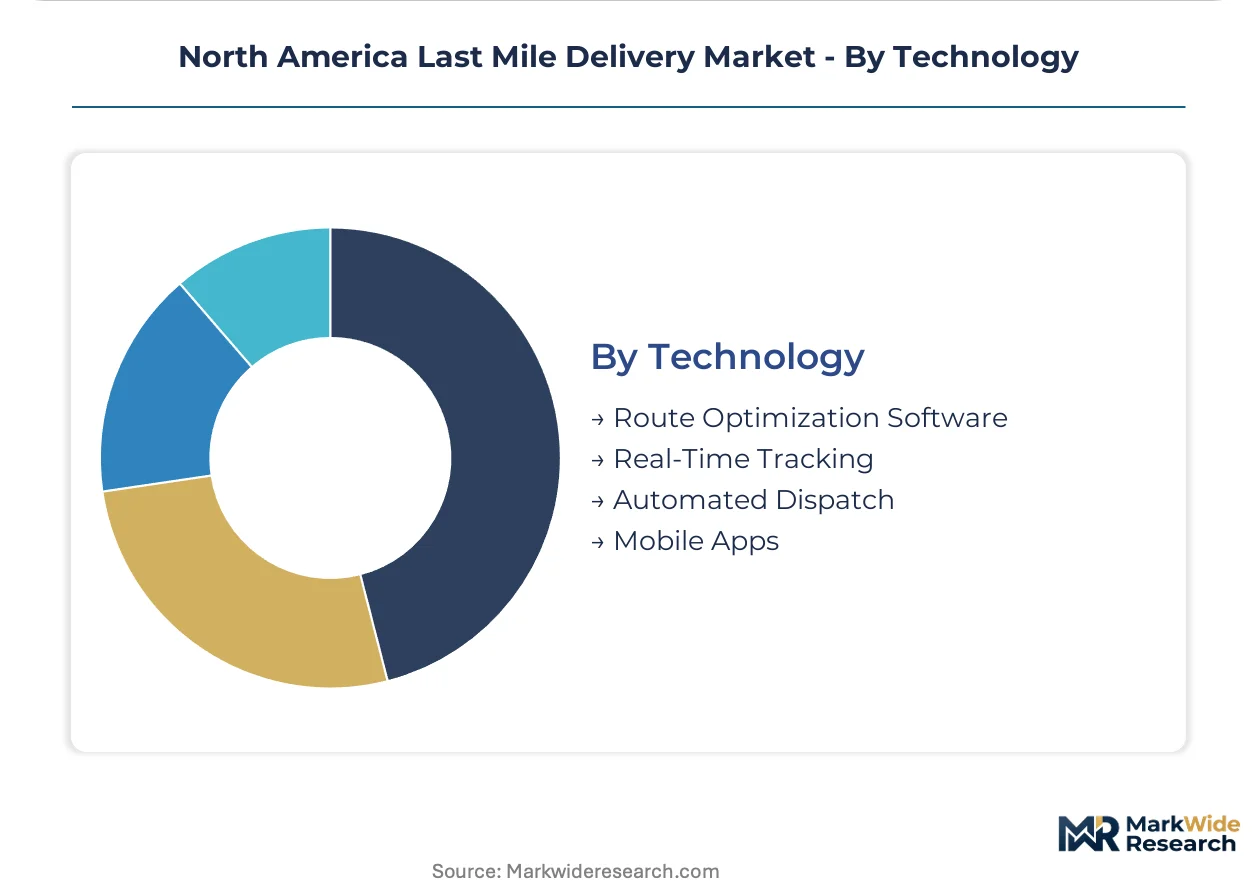
Technology:
Technology deployment precedes regulatory clarity, forcing operators into speculative platform commitments.
- Route Optimization Software:Algorithmic dispatch from vendors like OptimoRoute and Onfleet consolidates delivery windows to minimize per-stop costs. Machine learning models ingest traffic patterns, parking availability, and customer presence probability to compress miles between drops.
- Real-Time Tracking:GPS-telemetry integration provides customers with minute-level arrival estimates and proof-of-delivery capture. This capability has become table stakes for enterprise contracts.
- Automated Dispatch:Matches driver availability with order influx through dynamic pricing and incentive structures, particularly critical for gig-dependent restaurant delivery.
- Mobile Apps:Driver-facing applications handle navigation, customer communication, and payment collection, with offline functionality essential for tunnel and garage dead zones.
Adoption concentrates in Route Optimization Software; Automated Dispatch shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zone incentives along the US-Mexico border concentrate warehousing investment in Laredo and El Paso corridors. Cross-border e-commerce fulfillment networks exploit these zones to defer duty payments until final delivery.
United States
EPA Phase 3 standards mandate heavy-duty fleet electrification by 2032, compressing carrier capital cycles. California's Air Resources Board enforces interim zero-emission targets that precede federal deadlines. The Los Angeles-Long Beach port complex anchors the nation's densest last mile corridor, with operators stacking urban micro-fulfillment nodes to serve same-day demand.
Canada
Provincial zero-emission vehicle mandates in British Columbia and Quebec mirror California's compliance trajectory. Transport Canada coordinates with EPA standards to avoid cross-border fleet configuration complexity. The Greater Toronto Area functions as the primary distribution hub, with Vancouver's port corridor serving Asia-Pacific import flows.
Mexico
Nearshoring manufacturing relocation drives cross-border freight volumes through Nuevo León and Tamaulipas. Mexico's Secretariat of Environment and Natural Resources maintains lighter emissions standards than US counterparts. The Mexico City metropolitan zone concentrates domestic e-commerce fulfillment demand, while northern border states handle transloading for US final-mile delivery.
Texas
Absence of California-equivalent zero-emission mandates creates arbitrage space for diesel-efficient fleet operations. The Texas Commission on Environmental Quality regulates vehicle emissions without sales quotas. Dallas-Fort Worth and Houston logistics corridors absorb freight flows seeking to bypass California compliance costs while maintaining continental reach.
North America Last Mile Delivery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service segments. Integrated parcel carriers leverage density advantages in suburban zones through established ground networks. Gig-platform aggregators dominate restaurant delivery through variable-cost driver pools. Strategic moves concentrate on fleet electrification partnerships and urban micro-fulfillment site acquisition.
Within the integrated carrier tier, FedEx Corp. and United Parcel Service occupy positions defined by specialized infrastructure investments. Amazon Logistics exemplifies captive vertical integration, internalizing fulfillment to capture customer data and control experience. These three entities represent divergent capital deployment strategies—asset-heavy network ownership versus technology-platform intermediation—shaping competitive dynamics across delivery speed tiers.
| Leading Market Players |
|---|
| FedEx Corp. |
| United Parcel Service |
| Amazon Logistics |
| XPO Inc. |
| ArcBest Corp. |
| Ryder System Inc. |
| United States Postal Service |
| Instacart |
| DoorDash |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate price volatility cascading from Chilean and Australian extraction operations compresses margins for electric van fleet operators, forcing carriers to tier service pricing around charging infrastructure access and battery lease structures rather than traditional distance-based rates.
Pricing Analysis
Short lead-time premiums dominate contract structures, with same-day delivery slots commanding substantial markups over next-day windows while spot capacity during peak periods triggers dynamic surge mechanisms. Three-tier pricing structure across premium, standard, and economy levels segments customers by delivery speed commitment and volume predictability. Cost compression in the standard tier is intensifying because gig-economy labor pools erode dedicated fleet economics. E-commerce retailers exhibit highest price sensitivity, while pharmaceutical and healthcare buyers absorb premiums for temperature-validated chain of custody.
Supply Chain Analysis
Reverse logistics flows for returned e-commerce merchandise and end-of-life electric van batteries create secondary material streams that specialized processors in Mexico and Texas are capturing for refurbishment and cell recovery. Cathode active material production concentrates in China, South Korea, and Japan, while lithium extraction anchors in Chile, Australia, and Argentina. Battery cell supply draws from East Asian manufacturing clusters, exposing North American fleet operators to tariff exposure on imported energy storage systems. Distribution runs through port-adjacent warehousing in Los Angeles-Long Beach and cross-border transloading facilities in Laredo before final-mile deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Phase 3 compliance deadlines are accelerating carrier consolidation, as capital-constrained regional operators lack balance sheet capacity to fund dual-fleet transitions and charging infrastructure buildouts.
For Market Incumbents: Cement density advantages in California's South Coast Air Basin by acquiring urban micro-fulfillment real estate ahead of zoning restrictions, while hedging electrification capex through battery-as-a-service partnerships that shift degradation risk to third-party energy providers. Amazon Logistics and United Parcel Service already anchor positions here; smaller carriers must match this infrastructure commitment or exit premium same-day tiers. For New Entrants and Emerging Players: Launch via renewable natural gas bridge strategies in Texas logistics corridors, where absence of California-equivalent zero-emission mandates permits diesel-efficient fleet operations with lower compliance overhead. Target healthcare temperature-controlled delivery as the most penetrable premium segment, exploiting specialized certification requirements that deter generalist competition. White-glove installation services for furniture and appliance verticals offer additional entry points with lower capital intensity than parcel networks. For Investors and Strategic Acquirers: The window for entry favors mid-scale carriers with established California electric fleet deployments and cross-border Mexican operating authority. Long-term viability in this market rests on securing charging infrastructure access rights and warehouse positioning within 15-mile radii of dense population centers. Monitor CARB zero-emission credit pricing and EPA enforcement timelines as inflection indicators for residual diesel asset values and electrification capex urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Battery-as-a-service models decouple vehicle procurement from cell technology obsolescence risk for California carriers. |
| Urban Micro-Fulfillment Site Acquisition | Dark store positioning within 15-mile radii of Los Angeles and New York metro clusters captures same-day grocery demand. |
| Cross-Border Operating Authority Expansion | Mexican transloading capabilities exploit nearshoring manufacturing relocation through Nuevo León corridors. |
| Healthcare Cold-Chain Certification Investment | HIPAA-compliant temperature validation opens premium service tiers with specialized carrier premiums. |
| Route Optimization Platform Integration | Algorithmic dispatch from vendors like OptimoRoute consolidates delivery windows to minimize per-stop costs. |
Research Methodology
Independent corroboration across fleet operator interviews, logistics real estate developers, and charging infrastructure providers underwrites the qualitative findings in this study. Primary fieldwork engaged fleet procurement directors, warehouse operations managers, last-mile technology vendors, and regulatory compliance officers at CARB and EPA. Secondary validation drew from DOT hours-of-service filings, EPA Phase 3 regulatory dockets, customs trade data on electric van imports, and SEC disclosures from publicly traded carriers. Bottom-up volume triangulation across service type, vehicle category, and customer segment reconciled against top-down market sizing from macroeconomic freight flow indicators.
Comparable-period anchoring to pre-pandemic baseline volumes established trajectory boundaries for the projection horizon. The analytical framework modeled segmentation across service speed tiers, vehicle propulsion architecture, customer vertical, and regional regulatory clusters. CAGRs were derived from logistic diffusion curves applied to electrification mandate compliance timelines. Forecast inputs incorporated battery cost decline curves, charging infrastructure deployment schedules, and e-commerce penetration rates by product category.
The model assumes a particular technology adoption path; alternative pathways for autonomous delivery or drone integration would alter the outlook if FAA Part 135 restrictions ease faster than baseline assumptions. Practitioners should monitor CARB zero-emission credit pricing, lithium carbonate spot markets, and cross-border freight flow shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
China Digital Freight Forwarding Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US FTL Brokerage Market
Logistics and Shipping
China Local Courier Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
Global Freight Broker Software Market
Logistics and Shipping
Freight and Logistics Market
Logistics and Shipping
Europe Courier Market