
 Project Logistics Market | 2026-2036
Project Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Project Logistics Market Analysis
Software-defined route optimization is broadening what project logistics providers sell beyond physical haulage to predictive scheduling platforms. Deutsche Post DHL leverages its digital twin infrastructure to coordinate multi-modal heavy-lift sequences across continents. Kuehne + Nagel anchors its competitive position through specialized chartering networks for oversized energy infrastructure. DB Schenker differentiates via integrated customs brokerage tied to real-time cargo visibility systems.
Project logistics encompasses the engineered planning, specialized handling, and multi-modal execution of oversized, overweight, or time-critical cargo for capital-intensive industrial undertakings, typically involving crane-liftable modules exceeding standard container dimensions and requiring route surveys with structural load assessments. Its primary commercial purpose is to synchronize the physical movement of complex assets with construction timelines, minimizing demurrage and ensuring just-in-time site arrival. Freight forwarding commands the dominant margin pool due to the complexity of charter negotiations and customs orchestration, while renewable energy verticals represent the fastest-expanding demand segment as offshore wind turbine components scale beyond road-transportable limits. Warehousing for project cargo is structurally constrained by the need for heavy-load-bearing floors and outdoor laydown areas, creating regional supply bottlenecks near port industrial zones.
The International Maritime Organization's carbon intensity indicators are reshaping vessel chartering decisions for heavy-lift operators, while EU ETS expansion into maritime shipping adds compliance cost layers on trans-Atlantic project routes. OSHA's crane and rigging standards in the United States govern site-lift safety protocols, directly influencing equipment certification requirements and contractor qualification criteria. Stakeholders must monitor how emerging carbon accounting rules for scope-three logistics emissions reshape contractor selection criteria and capital project bidding structures.
Market Dynamics
Offshore wind turbine scaling is compressing project logistics timelines as single-blade lengths exceed 115 meters and nacelle weights surpass 500 metric tons, forcing route surveys and heavy-lift sequencing to integrate earlier into engineering design cycles.
Growth Catalysts
- EU F-Gas Regulation:Carbon border adjustments on imported industrial equipment are accelerating demand for low-emission heavy-lift transport modes across North Sea offshore wind corridors.
- Modular construction:Prefabricated industrial plant components are expanding project cargo volumes as developers compress on-site assembly schedules through factory-built module integration.
- Germany:Industrial clustering around Hamburg and Bremen is concentrating specialized heavy-lift port infrastructure investment, creating dedicated logistics corridors for renewable energy components.
Market Restraints
- Specialized vessel scarcity:Heavy-lift ship availability concentrates among a limited pool of owner-operators, creating charter rate volatility during peak offshore wind installation windows.
- EU ETS maritime expansion:Carbon pricing on trans-Atlantic routes is adding compliance cost layers that compress margins on long-haul project cargo movements.
- Site access limitations:Bridge clearance constraints and rural road load ratings permanently exclude certain oversized modules from land-based transport options.
Strategic Opportunities
- Floating offshore wind:Mooring system and floating foundation logistics represent an emerging application segment with distinct heavy-lift requirements from fixed-bottom installations.
- Digital twin integration:Convergence of IoT sensor networks with predictive analytics platforms is enabling real-time cargo stress monitoring and route recalculation capabilities.
- India:Underpenetrated renewable energy infrastructure is creating white space for specialized project logistics providers as domestic solar and wind manufacturing scales.
Industry Challenges
- Crane operator certification:OSHA rigging standards and specialized heavy-lift qualifications are extending contractor onboarding timelines and constraining available labor pools.
- Multi-modal coordination:Synchronization failures between port handling, barge transport, and final site delivery are generating demurrage costs that erode project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Project Logistics Market |
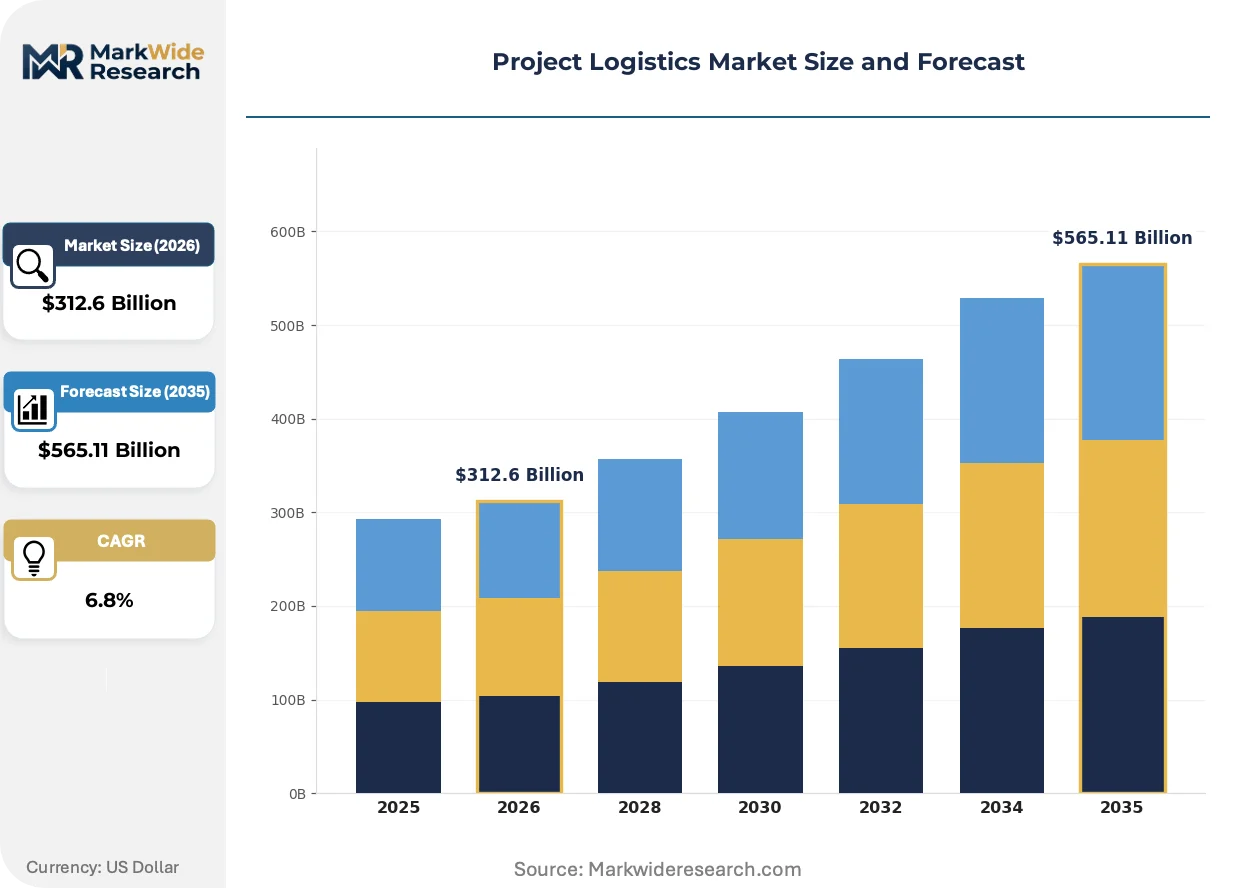
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
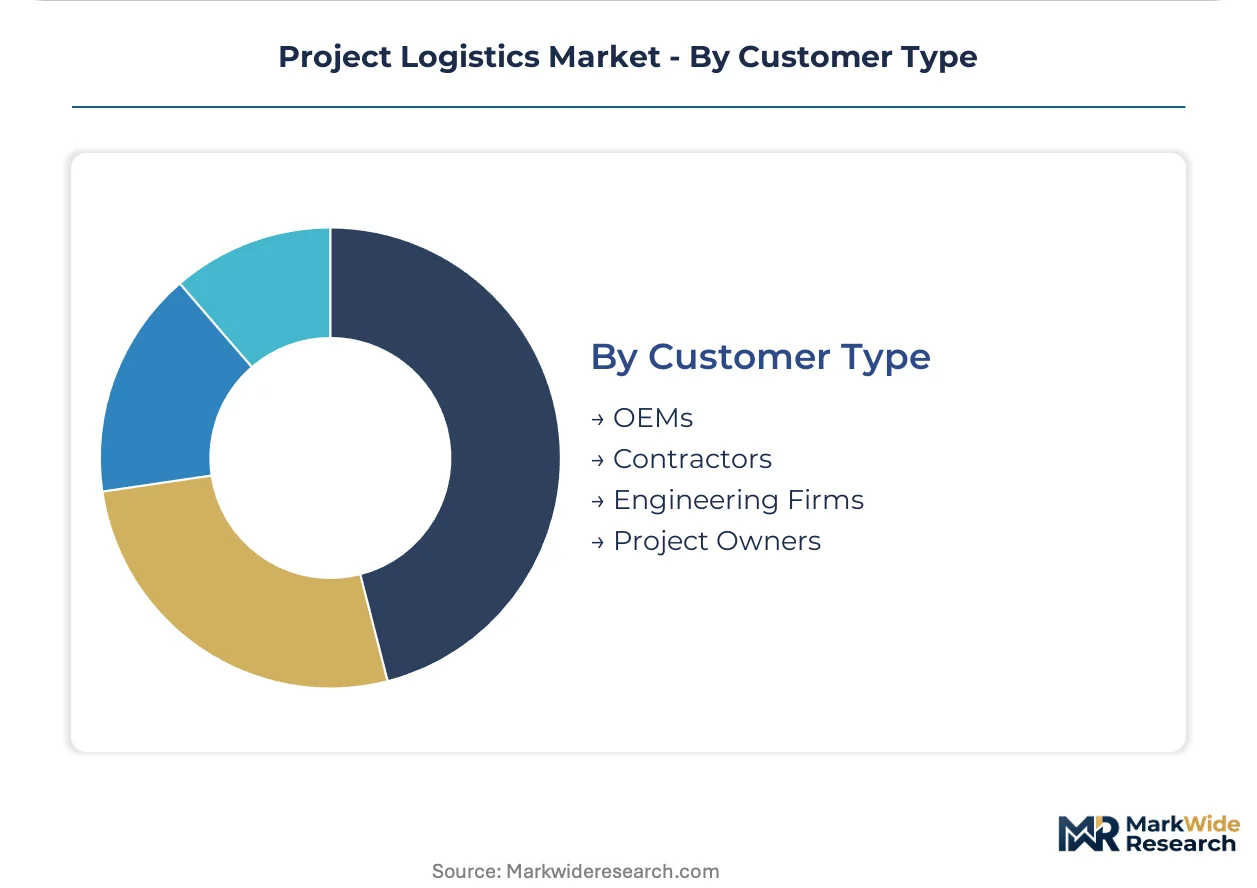
| Segmentation | Service Type: Freight Forwarding, Warehousing, Transportation, Customs Brokerage Industry Vertical: Construction, Oil & Gas, Mining, Renewable Energy Delivery Model: Direct Shipping, Just-In-Time, Cross-Docking, Project Management Customer Type: OEMs, Contractors, Engineering Firms, Project Owners |
| Companies Covered | DSV, Hellmann Worldwide Logistics, Deutsche Post DHL, DB Schenker, C.H. Robinson, Kuehne + Nagel, Rhenus Logistics, EMO Trans, CEVA Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Project Logistics Market Emerging Trajectories
Software-defined logistics platforms are displacing traditional freight brokerage relationships as predictive scheduling and digital twin coordination become core service differentiators rather than operational support tools.
Blockchain-enabled cargo documentation is decentralizing trust architectures across multi-modal heavy-lift sequences. Renewable energy developers in the North Sea basin are adopting distributed ledger systems for component provenance tracking. This technology is decentralizing verification responsibilities away from centralized customs brokers toward automated smart-contract execution.
The EU F-Gas Regulation's carbon border adjustment mechanism is tightening emissions accountability across heavy-lift supply chains. Industrial project sponsors now embed scope-three logistics emissions into contractor selection scorecards. Offshore wind developers in Germany and Denmark are responding by mandating low-sulfur marine fuels and shore-power connections at laydown yards.
Buyer procurement patterns are compressing from long-term framework agreements toward project-specific competitive tenders. Engineering-procurement-construction contractors are unbundling logistics from turnkey contracts to access specialized heavy-lift providers directly. This behavior is most visible in German offshore wind auctions where developers optimize capital structures through granular supplier selection.
Project Logistics Market Segmentation

Project logistics providers structure service portfolios around cargo complexity tiers and timeline sensitivity. Segmentation reveals where margin pools concentrate versus where commoditization pressures operate.
Service Type:
Standalone advisory services contrast with embedded execution functions across the value chain.
- Freight Forwarding:Charter negotiations, vessel brokering, and customs orchestration for oversized modules. Demand clusters in German North Sea offshore wind corridors where turbine component scaling outstrips standard vessel capacity. The F-Gas Regulation's carbon border adjustments are tightening emissions accountability in contractor selection.
- Transportation:Heavy-haul road movements, barge sequences, and multi-modal handoffs requiring route surveys with structural load assessments. Mining and oil & gas capital projects in remote geographies drive specialized low-loader and modular trailer demand. Bridge clearance constraints and rural road load ratings permanently exclude certain modules from land-based options.
- Warehousing:Heavy-load-bearing floors and outdoor laydown areas near port industrial zones create regional supply bottlenecks.
- Customs Brokerage:Documentation orchestration and duty optimization for cross-border project cargo movements.
Freight forwarding leads volumes today; customs brokerage is gaining share fastest.
Industry Vertical:
Capital intensity and component scale differentiate margin profiles across end-use sectors.
- Renewable Energy:Offshore wind turbine logistics with single-blade lengths exceeding 115 meters and nacelle weights surpassing 500 metric tons. German and Danish developers compress installation windows around weather-limited seasons, forcing heavy-lift sequencing into early engineering design cycles. The EU ETS maritime expansion adds compliance cost layers on trans-Atlantic component routes.
- Construction:Prefabricated industrial plant modules and modular building components. Factory-built integration compresses on-site assembly schedules across German industrial clusters around Hamburg and Bremen. OSHA crane and rigging standards govern site-lift safety protocols and equipment certification requirements.
- Oil & Gas:Upstream module logistics and pipeline construction materials.
- Mining:Processing plant components and bulk materials handling infrastructure.
Construction anchors revenue concentration today; renewable energy climbs the fastest.
Delivery Model:
Coordination depth separates transactional shipments from engineered project sequences.
- Project Management:End-to-end planning, risk allocation, and timeline orchestration across multi-modal sequences. Engineering-procurement-construction contractors unbundle logistics from turnkey contracts to access specialized heavy-lift providers directly. Digital twin integration enables real-time cargo stress monitoring and route recalculation.
- Just-In-Time:Synchronized arrival sequencing to minimize demurrage and site holding costs. Offshore wind installation vessels command charter premiums during narrow weather windows, forcing precision handoffs from feeder barges. Synchronization failures between port handling and final site delivery erode project margins.
- Direct Shipping:Point-to-point vessel chartering without intermediate consolidation.
- Cross-Docking:Rapid modal transfers at port terminals with minimal storage duration.
Project management dominates value capture today; just-in-time shows steepest expansion trajectory.
Customer Type:
Procurement sophistication and risk tolerance shape service bundling preferences.
- Contractors:Engineering-procurement-construction firms managing capital project execution. German offshore wind auctions show unbundling behavior as developers optimize capital structures through granular supplier selection. Contractors bear demurrage exposure from multi-modal coordination failures.
- Project Owners:Asset developers and infrastructure funds with direct logistics procurement. Scope-three carbon accounting rules reshape contractor selection criteria and bidding structures. Industrial project sponsors embed logistics emissions into selection scorecards.
- OEMs:Original equipment manufacturers shipping factory-built modules to installation sites.
- Engineering Firms:Design consultants specifying logistics constraints during front-end engineering.
Contractors lead procurement volumes today; project owners are expanding direct engagement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands specialized heavy-lift port infrastructure investment while India scales domestic manufacturing capacity for renewable energy components.
United States
Offshore wind lease auctions along the Atlantic seaboard are mobilizing heavy-lift vessel demand for turbine component installation. OSHA crane and rigging standards govern site-lift safety protocols and contractor qualification criteria. The Port of New York and New Jersey anchors East Coast logistics corridors with heavy-load-bearing terminal infrastructure.
Germany
Industrial clustering around Hamburg and Bremen concentrates specialized port infrastructure for North Sea offshore wind corridors. The EU F-Gas Regulation's carbon border adjustments tighten emissions accountability in contractor selection scorecards. Heavy-lift sequencing integrates earlier into engineering design cycles as single-blade lengths exceed 115 meters.
China
Domestic wind turbine manufacturing scale drives demand for oversized component logistics across coastal provinces. MEE dual carbon goals shape low-emission transport mode preferences for capital equipment movements. The Yangtze River Delta anchors manufacturing clusters with integrated heavy-lift terminal capacity.
India
Underpenetrated renewable energy infrastructure creates white space for specialized project logistics providers as domestic solar and wind manufacturing scales. BIS standards govern equipment certification for heavy-lift operations. Gujarat and Tamil Nadu industrial corridors concentrate port infrastructure investment for component import and export.
United Kingdom
North Sea offshore wind auction rounds compress installation windows around weather-limited seasons. The UK Emissions Trading Scheme adds compliance cost layers on maritime component routes. Scottish ports around Aberdeen develop heavy-laydown capacity for floating offshore wind foundation logistics.
Project Logistics Market Vendor Landscape
Top-tier vendors anchor multi-modal coordination capabilities, while mid-tier specialists concentrate on regional heavy-lift niches. The market structure fragments across freight forwarders with charter networks, asset-heavy port operators, and digital-native scheduling platforms. Three archetypes dominate: integrated logistics conglomerates with customs brokerage depth, specialized heavy-lift chartering boutiques, and software-defined coordination platforms. Competitive moves concentrate on M&A for charter fleet access and strategic partnerships for digital twin integration.
Among European-integrated providers, Deutsche Post DHL, Kuehne + Nagel, and DB Schenker occupy positions exemplifying the convergence of physical haulage with predictive scheduling platforms. DHL leverages digital twin infrastructure for multi-modal heavy-lift sequences. Kuehne + Nagel anchors competitive positioning through specialized chartering networks. DB Schenker differentiates via integrated customs brokerage tied to real-time visibility systems.
| Leading Market Players |
|---|
| DSV |
| Hellmann Worldwide Logistics |
| Deutsche Post DHL |
| DB Schenker |
| C.H. Robinson |
| Kuehne + Nagel |
| Rhenus Logistics |
| EMO Trans |
| CEVA Logistics |
| Others |
Supply Flow & Price Mechanics
Charter-rate bifurcation between specialized heavy-lift vessels and standard multipurpose tonnage manifests in divergent contract structures and procurement timelines across North Sea offshore wind corridors. Premium vessel access commands longer-term offtake commitments from German developers, while commodity spot markets serve smaller modular construction projects with compressed lead times.
Pricing Analysis
Capacity additions in Chinese shipyards are reshaping price floors for standard heavy-lift tonnage, though specialized offshore wind installation vessels remain supply-constrained. Project-based charter contracts with demurrage clauses dominate renewable energy logistics, while spot-rate volatility concentrates in mining and oil & gas verticals. Price differentiation rests on vessel crane capacity certification and IMO carbon intensity ratings. Margins are tightening due to EU ETS compliance cost layering on trans-Atlantic routes. EPC contractors exhibit highest price sensitivity; asset developers with long-dated power purchase agreements absorb premium logistics costs.
Supply Chain Analysis
Crane operator certification bottlenecks in German and Danish port zones are extending contractor onboarding timelines and constraining available labor pools for heavy-lift sequences. Manufacturing concentration centers on China for wind turbine components, South Korea for specialized vessel construction, and Germany for port infrastructure equipment. Raw material dependencies span high-strength steel for crane fabrication, marine-grade lubricants for heavy-lift systems, and low-sulfur bunkers for EU-compliant vessel operations. Single-source vulnerability concentrates in heavy-lift vessel owner-operators with limited fleet expansion. Distribution runs through port-centric laydown yards with heavy-load-bearing floors and integrated customs brokerage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Project logistics offers margin expansion through digital twin integration reducing demurrage exposure, and through premium-tier positioning on carbon-accounted supply chains serving EU offshore wind developers.
For Market Incumbents: Cement multi-modal coordination capabilities through strategic charter fleet partnerships, particularly for turbine installation vessels with 1,500+ metric ton lift capacity. Invest in IoT sensor networks for real-time cargo stress monitoring to defend against software-native scheduling platforms. Prioritize customs brokerage depth in Hamburg and Bremen corridors where EU F-Gas Regulation compliance accelerates contractor selection complexity. For New Entrants and Emerging Players: Port operators with heavy-laydown capacity in Gujarat and Tamil Nadu represent the most penetrable channel partner type for India renewable energy manufacturing scale-up. Target floating offshore wind foundation logistics as a white-space application with distinct mooring system requirements from fixed-bottom installations. Pursue joint venture structures with established heavy-lift chartering boutiques to access vessel availability without capital-intensive fleet ownership. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized heavy-lift vessel scarcity intersects with carbon compliance cost layering on trans-Atlantic routes. Long-term viability favors asset-light digital coordination platforms with predictive scheduling capabilities over pure-play charter operators. Monitor EU ETS maritime expansion implementation pace and OSHA crane certification backlog duration as inflection indicators for contractor margin compression versus technology-enabled differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Enables real-time cargo stress monitoring and route recalculation for heavy-lift sequences. |
| Specialized Charter Fleet Expansion | Addresses vessel scarcity during peak North Sea offshore wind installation windows. |
| Carbon-Accounted Logistics Certification | Aligns contractor selection with EU F-Gas Regulation scope-three emissions scorecards. |
| Heavy-Laydown Yard Development | Creates regional bottlenecks near Hamburg and Bremen industrial clusters. |
| Predictive Scheduling Platform Launch | Displaces traditional freight brokerage relationships with software-defined coordination. |
Methodological Framework
Coverage spans Germany, China, India, the United States, and the United Kingdom, with primary inputs from each market cluster. The analysis combines interviews with offshore wind project developers, EPC contractor logistics directors, heavy-lift vessel chartering managers, port terminal operators, and customs brokerage specialists with secondary validation. Sources include IMO carbon intensity disclosures, EU ETS regulatory filings, OSHA crane certification databases, and customs trade records for oversized cargo movements. Bottom-up project cargo volume estimates triangulate against top-down market sizing from freight forwarding revenue disclosures.
Rate-of-change decomposition separates volume growth from price/mix effects across the projection horizon. Segmentation dimensions modeled include service type, industry vertical, delivery model, and customer procurement sophistication. CAGRs derive from logistic curve fitting to offshore wind capacity installation schedules and modular construction adoption patterns. Forecast inputs incorporate EU F-Gas Regulation implementation timelines and IMO marine fuel sulfur standards.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to floating offshore wind technology maturation and specialized vessel newbuild delivery schedules. Projections reflect assumptions on carbon border adjustment enforcement intensity and crane operator certification throughput capacity. Practitioners should monitor EU ETS maritime expansion scope and India renewable energy manufacturing scale-up pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
China Local Courier Market
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Fleet of Containers Market
Logistics and Shipping
Canada 3PL Market
Logistics and Shipping
Europe Third Party Logistics Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Unit Load Device Market
Logistics and Shipping
Digital Freight Management Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Courier Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market