
 Saudi Arabia Integrated Cold Chain Logistics Market | 2026-2036
Saudi Arabia Integrated Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Integrated Cold Chain Logistics Market Insights
Pharmaceutical distributors is rotating toward dedicated cold chain capacity as biologics and vaccine volumes expand across the kingdom. Agility Logistics anchors pharmaceutical-grade warehousing through specialized temperature zones in Riyadh and Jeddah. Almajdouie dominates heavy-lift refrigerated transport for oversized pharma cargo entering King Abdullah Port. Coldstores Group of Saudi Arabia specializes in multi-temperature distribution centers serving quick-service restaurant chains.
Integrated cold chain logistics coordinates temperature-controlled storage, refrigerated transport, and real-time monitoring systems to preserve product integrity across the supply chain. Systems typically maintain temperature bands from minus 25 degrees Celsius to plus 25 degrees Celsius with continuous data logging for regulatory traceability. Refrigerated transport leads solution type revenue due to highway fleet expansion connecting Riyadh, Jeddah, and Dammam. IoT Solutions within temperature monitoring commands premium pricing as pharmaceutical clients mandate cloud-based alert systems. Third-Party Logistics channels capture growing share as food manufacturers outsource distribution to avoid capital-intensive warehouse construction.
SFDA enforces pharmaceutical cold chain standards through facility licensing and periodic GDP audits. The Saudi Food and Drug Authority's traceability requirements compel investment in RFID and blockchain verification systems. Saudi Aramco Logistics and NAQEL Express must navigate evolving customs clearance protocols at land borders with UAE and Bahrain. Stakeholders should monitor SFDA's anticipated expansion of temperature excursion reporting rules for ambient-to-cold conversions.
Market Dynamics
SFDA's GDP mandate for real-time temperature monitoring is compressing operational timelines across pharmaceutical distribution networks, forcing logistics providers to retrofit legacy fleets with cloud-connected sensor arrays.
Growth Catalysts
- Biologics sector expansion:Riyadh's pharmaceutical manufacturing corridor is drawing temperature-sensitive production from multinational drug makers seeking regional hub status.
- SFDA traceability mandates:The Saudi Food and Drug Authority's blockchain verification requirements are accelerating RFID adoption across vaccine distribution networks.
- Quick-service restaurant penetration:Western and regional QSR chains are scaling frozen and chilled SKUs, requiring multi-temperature last-mile capacity in Jeddah and Dammam.
Market Restraints
- Refrigerant cost volatility:Hydrofluorocarbon phase-down schedules are squeezing margins for fleet operators dependent on conventional cooling units.
- Specialized driver scarcity:The kingdom's commercial license pipeline lacks HAZMAT-certified operators for pharmaceutical-grade cargo.
- Cross-border customs friction:Land bridge delays at the UAE-Saudi border disrupt just-in-time temperature protocols for Bahrain-originating biologics.
Strategic Opportunities
- Tabuk agricultural corridor:Northern province dairy and poultry output lacks integrated cold storage, creating greenfield development potential.
- IoT-ERP convergence:Cloud-based warehouse management systems are merging with predictive maintenance platforms to cut pharmaceutical spoilage rates.
- Third-party logistics outsourcing:Food manufacturers are divesting captive distribution assets, opening contract logistics contracts for regional specialists.
Industry Challenges
- Certification timeline compression:SFDA facility licensing cycles for new GDP-compliant warehouses now exceed 18 months, delaying network expansion.
- Legacy fleet retrofit complexity:Existing refrigerated trucks lack CAN bus architecture for seamless IoT sensor integration, requiring expensive hardware overhauls.
- Pharmaceutical spoilage liability:Temperature excursion disputes between manufacturers and logistics providers are driving insurance premium spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Integrated Cold Chain Logistics Market |
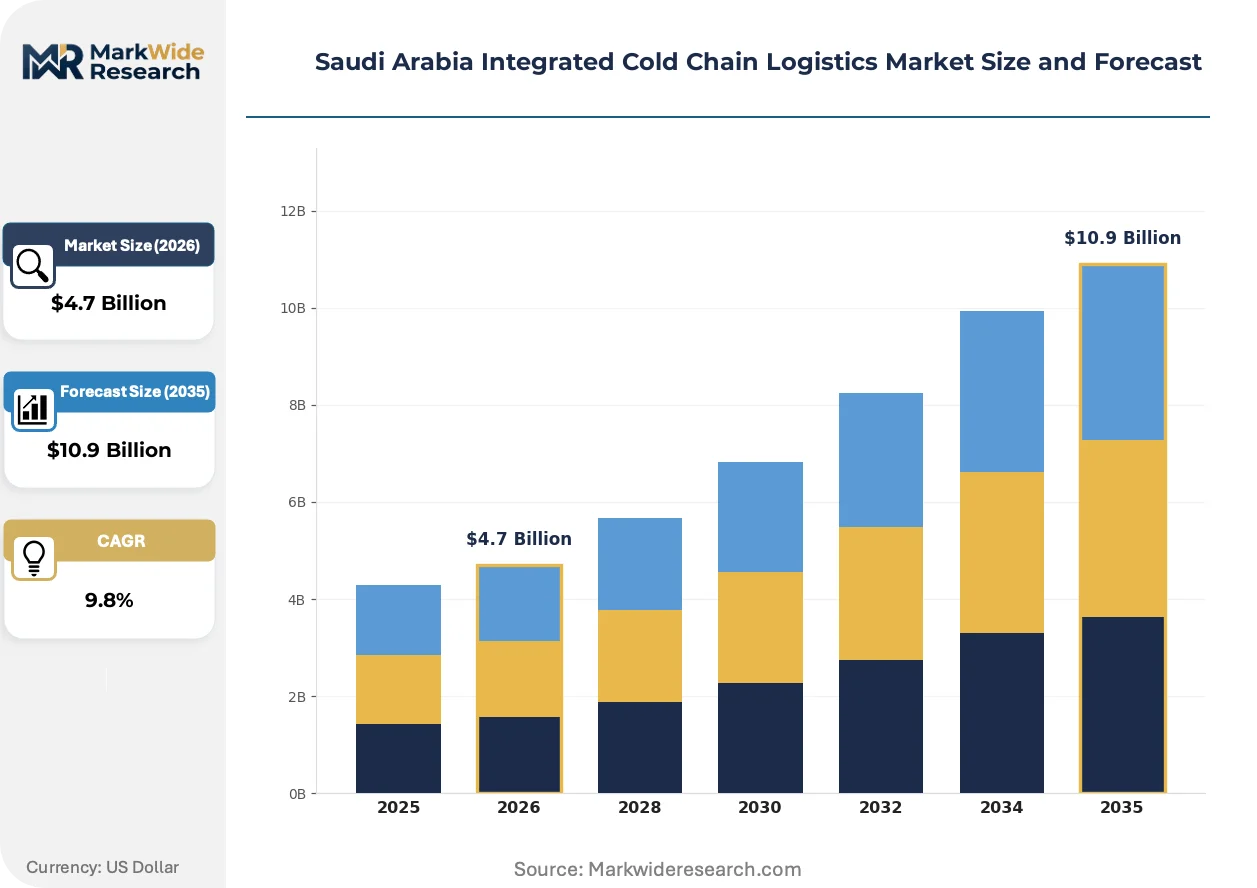
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $10.9 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Refrigerated Transport, Temperature-Controlled Storage, Monitoring Solutions, Packaging Solutions End User: Food & Beverage, Pharmaceuticals, Biotechnology, E-Commerce Technology: IoT Solutions, Blockchain, Automation, RFID Technology Distribution Channel: Direct Sales, Online Platforms, Retail Partnerships, Third-Party Logistics |
| Companies Covered | Agility Logistics, Almarai, Coldstores Group of Saudi Arabia, CEVA Logistics, Almajdouie, NAQEL Express, Tamer Logistics, Saudi Aramco Logistics, Mosanada Logistics Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Integrated Cold Chain Logistics Market Trends and Innovations
Digital infrastructure is displacing paper-based compliance workflows across Saudi cold chain operations, with sensor networks and automated documentation now baseline expectations for pharmaceutical contracts.
Telematics platforms is decomposing traditional fleet management by embedding predictive analytics directly into refrigerated transport units. Pharmaceutical distributors are adopting these systems fastest, with real-time route optimization cutting vaccine delivery windows by half. The technology is decomposing the separation between logistics execution and quality assurance, merging them into unified operational dashboards.
SFDA's updated Good Distribution Practice guidelines are mandating continuous data logging for all temperature-sensitive pharmaceutical shipments. The regulation compels investment in redundant sensor arrays and cloud-based alert systems. Vaccine distributors face the steepest compliance burden, with many retrofitting existing warehouses rather than building new capacity.
Consolidated procurement of integrated cold chain services is displacing fragmented spot-market arrangements for temperature-controlled transport. Food manufacturers are bundling storage, transport, and monitoring under single-provider contracts to reduce vendor management overhead. This pattern is most visible in Riyadh's industrial corridor, where QSR supply chains demand synchronized multi-temperature handling.
Saudi Arabia Integrated Cold Chain Logistics Market Segmentation
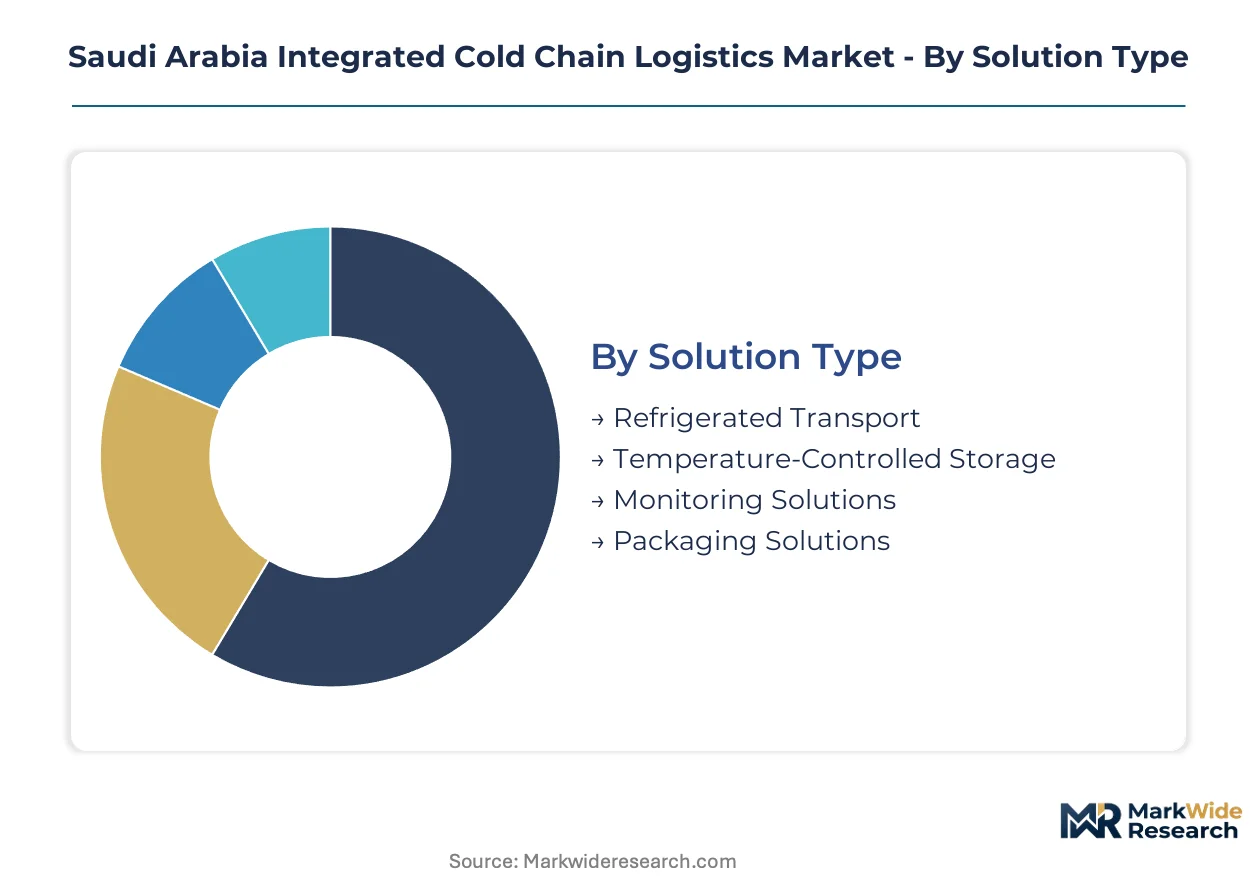
Saudi Arabia's cold chain logistics market segments along four operational dimensions that determine compliance burden and capital intensity. SFDA's tiered regulatory requirements create divergent investment profiles across solution types and end-use verticals.
Solution Type:
SFDA's Good Distribution Practice mandates differentiate compliance costs across solution categories, with pharmaceutical-grade specifications commanding premium infrastructure investments.
- Refrigerated Transport:Highway fleets connecting Riyadh, Jeddah, and Dammam maintain temperature bands from minus 25 to plus 25 degrees Celsius through multi-compartment trailer configurations. Food manufacturers and pharmaceutical distributors in the Eastern Province corridor drive fleet expansion as biologics volumes climb.
- Temperature-Controlled Storage:Warehouse facilities deploy redundant cooling systems and backup power generation to meet SFDA facility licensing requirements. King Khalid International Airport's cargo zone anchors pharmaceutical-grade capacity serving multinational drug makers establishing regional hub operations.
- Monitoring Solutions:Real-time sensor arrays and cloud-based alert platforms.
- Packaging Solutions:Insulated containers and phase-change materials for last-mile vaccine delivery.
Refrigerated transport handles the majority of throughput; temperature-controlled storage is the fastest mover on share as SFDA licensing timelines compress available warehouse capacity.
End User:
Customer concentration varies sharply by margin profile, with pharmaceutical clients accepting 40-60% cost premiums over food sector benchmarks for GDP-certified handling.
- Pharmaceuticals:Vaccine and biologics distributors mandate continuous data logging and blockchain verification under SFDA traceability rules. Riyadh's pharmaceutical manufacturing corridor concentrates demand as multinational producers regionalize temperature-sensitive output.
- Biotechnology:Cell therapy and gene therapy products require ultra-low temperature chains below minus 60 degrees Celsius.
- Food & Beverage:Quick-service restaurant chains and dairy processors in Jeddah and Dammam drive multi-temperature distribution center demand.
- E-Commerce:Online grocery platforms and meal-kit services are expanding chilled last-mile capacity in urban centers.
Pharmaceuticals dominates revenue contribution; biotechnology is expanding most quickly as advanced therapy medicinal products enter regional clinical trials.
Technology:
Adoption velocity correlates with customer compliance requirements, creating a bifurcated supplier base serving either premium pharmaceutical or cost-optimized food segments.
- IoT Solutions:Cloud-connected sensor networks enable real-time temperature monitoring and automated excursion alerts. SFDA's GDP mandate for vaccine shipments has made IoT infrastructure non-negotiable for pharmaceutical distributors retrofitting legacy fleets.
- Blockchain:Distributed ledger systems create immutable temperature records for regulatory audits.
- RFID Technology:Wireless identification tags streamline inventory tracking in high-throughput distribution centers.
- Automation:Robotic handling systems reduce human error in temperature-sensitive picking operations.
IoT Solutions commands the largest installed base; blockchain is climbing the fastest as SFDA evaluates expanded traceability requirements for ambient-to-cold conversions.
Distribution Channel:
Channel selection reflects customer scale and internal logistics capabilities, with mid-size food manufacturers most prone to outsourcing.
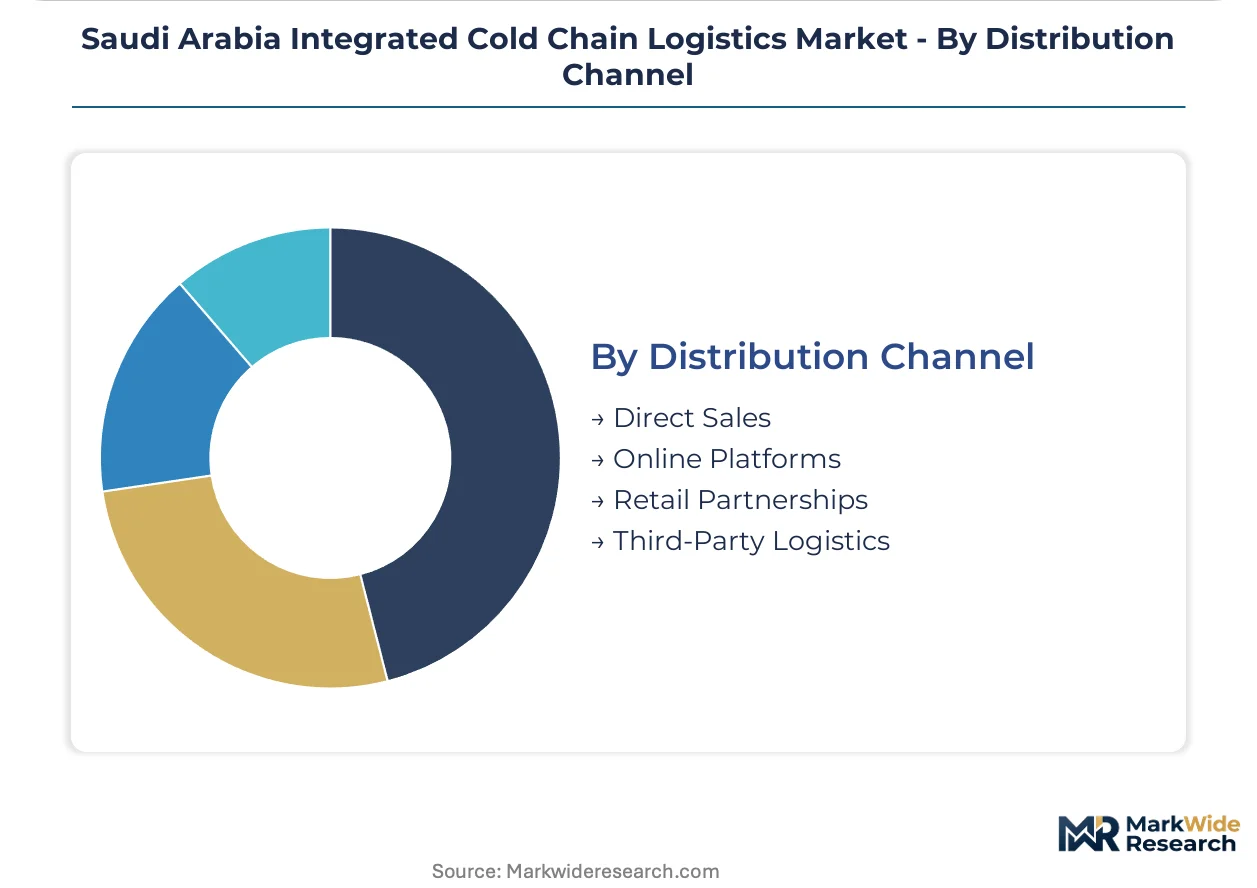
- Third-Party Logistics:Contract operators assume capital-intensive warehouse construction and fleet ownership for clients avoiding fixed asset deployment. Coldstores Group of Saudi Arabia and Agility Logistics anchor this channel through multi-temperature facilities in Riyadh and Jeddah.
- Direct Sales:Vertically integrated pharmaceutical manufacturers operate captive distribution networks.
- Retail Partnerships:Supermarket chains coordinate inbound consolidation for frozen and chilled SKUs.
- Online Platforms:Digital freight marketplaces match spot refrigerated capacity with seasonal agricultural exporters.
Third-Party Logistics captures the dominant contract value; online platforms are gaining share fastest among seasonal date and dairy exporters seeking flexible capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's cold chain logistics network funnels temperature-sensitive cargo from Red Sea and Arabian Gulf ports into Riyadh's inland distribution spine, with cross-border flows from UAE and Bahrain feeding pharmaceutical corridors.
Riyadh
Pharmaceutical manufacturing clusters near King Khalid International Airport's cargo zone concentrate GDP-certified warehouse demand as multinational drug makers regionalize biologics production. SFDA's facility licensing requirements compress available cold storage capacity, extending approval timelines beyond 18 months. The industrial corridor between the airport and Second Industrial City anchors multi-temperature distribution centers serving quick-service restaurant chains.
Eastern Province
Dammam's petrochemical and food processing base generates chilled transport demand connecting King Fahd Industrial Port to inland consumption centers. The region's dairy and poultry output lacks integrated cold storage infrastructure, creating greenfield development opportunities. Jubail's industrial city hosts specialty chemical cold chains requiring minus 25 degree Celsius handling for export-oriented production.
Western Region
Jeddah's King Abdulaziz International Airport cargo terminal serves as the primary entry point for temperature-sensitive biologics entering the kingdom from European and Asian origins. The city's quick-service restaurant density drives last-mile refrigerated capacity expansion across multi-temperature configurations. Mecca and Medina pilgrimage logistics create seasonal spikes in pharmaceutical and food cold chain throughput.
NEOM Northwest
The giga-project's planned food security and biotechnology zones will require ultra-low temperature infrastructure for cell therapy and gene therapy product chains. MOHAP coordination with SFDA is establishing regulatory precedents for advanced therapy medicinal product handling in greenfield zones. The Tabuk agricultural corridor's dairy and poultry output currently lacks integrated cold storage, positioning NEOM-adjacent development for future capture.
Saudi Arabia Integrated Cold Chain Logistics Market Competitive Landscape
Listed logistics conglomerates compete with private specialists across pharmaceutical-grade certification tiers, with capital access determining warehouse construction pace against SFDA's compressed licensing timelines. Market structure tilts toward consolidated contract logistics operators controlling multi-temperature assets in Riyadh and Jeddah, while specialized heavy-lift refrigerated transport remains fragmented. Three archetypes dominate: GDP-certified pharmaceutical specialists, multi-temperature food distribution operators, and captive logistics arms of energy and dairy conglomerates. Competitive moves center on fleet retrofit partnerships for IoT sensor integration and strategic land banking near airport cargo zones ahead of licensing queue bottlenecks.
Within the pharmaceutical-certified tier, Agility Logistics anchors specialized temperature zone operations through Riyadh and Jeddah facilities, while Almajdouie occupies a position in heavy-lift refrigerated transport for oversized cargo entering King Abdullah Port. Coldstores Group of Saudi Arabia exemplifies the food distribution archetype, anchoring multi-temperature last-mile capacity for quick-service restaurant chains. These three operators represent divergent strategic positions: international contract logistics scale, domestic heavy-transport specialization, and sector-specific food retail integration.
| Leading Market Players |
|---|
| Agility Logistics |
| Almarai |
| Coldstores Group of Saudi Arabia |
| CEVA Logistics |
| Almajdouie |
| NAQEL Express |
| Tamer Logistics |
| Saudi Aramco Logistics |
| Mosanada Logistics Services |
| Others |
Pricing and Supply Chain Analysis
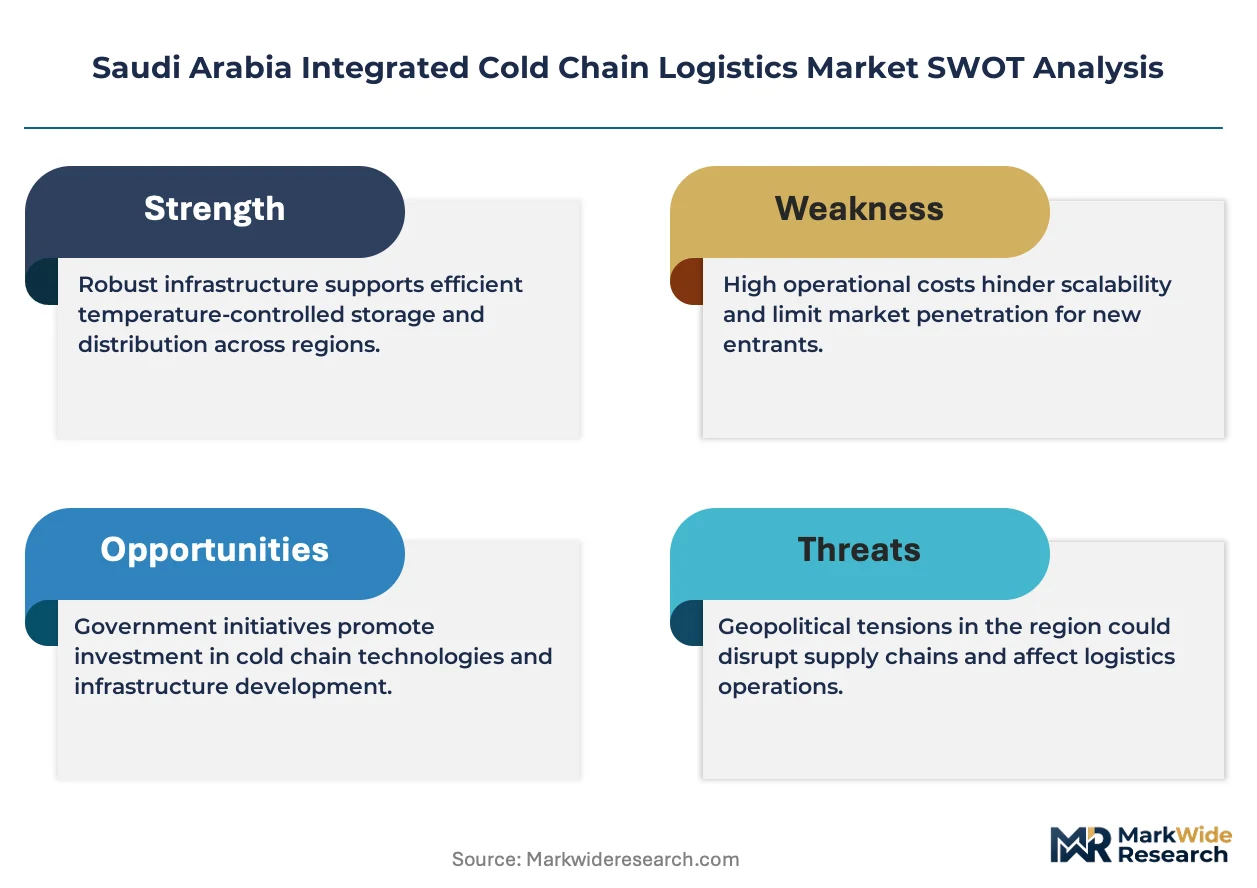
SFDA's Good Distribution Practice certification tiers gate both supplier qualification and price differentiation simultaneously, with GDP-compliant pharmaceutical handling commanding substantial premiums over food-grade benchmarks while compressing the qualified vendor pool.
Pricing Analysis
IoT-enabled next-generation monitoring systems price at premiums against legacy sensor arrays and paper-based logging alternatives. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-certified GDP operations from multi-temperature food distribution and basic refrigerated transport spot markets. Cost compression in economy-tier food logistics is intensifying because fleet operators absorb refrigerant phase-down expenses without pass-through mechanisms. Quick-service restaurant chains exhibit highest price sensitivity, while vaccine distributors accept premium positioning for redundant cold chain assurance.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical inventory strategy, contrasting with just-in-time protocols in food retail distribution. Equipment and sensor hardware draws from Germany, China, and South Korea, while refrigerant chemicals and phase-change materials rest on specialized chemical producers in Europe and Asia. Single-source vulnerability concentrates in IoT sensor chipset supply, where semiconductor fabrication bottlenecks threaten fleet retrofit timelines. Distribution runs through consolidated third-party logistics operators controlling multi-temperature assets in Riyadh and Jeddah, with captive pharmaceutical networks serving multinational drug makers directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's integrated cold chain logistics market represents early-cycle expansion, with biologics manufacturing regionalization and SFDA traceability mandates accelerating infrastructure buildout faster than qualified supply can respond.
For Market Incumbents: Consolidate GDP-certified warehouse capacity near King Khalid International Airport's cargo zone before licensing queue bottlenecks extend further. Acquire HAZMAT-certified driver pipelines through vocational training partnerships to preempt specialized labor scarcity. Lock in long-term refrigerant supply contracts ahead of hydrofluorocarbon phase-down deadlines.
For New Entrants and Emerging Players: Ultra-low temperature infrastructure gaps in Tabuk's agricultural corridor offer greenfield development potential unaddressed by established Riyadh-Jeddah operators. Target biotechnology cold chains for cell therapy products requiring minus 60 degree Celsius handling, where incumbent capacity remains nascent. Pursue joint-venture structures with regional dairy processors seeking to outsource captive distribution assets.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade cold storage as SFDA facility licensing timelines extend facility construction cycles. Five-to-ten year viability favors operators with land positions near airport cargo zones and pre-qualified GDP certification status. Monitor SFDA's anticipated expansion of temperature excursion reporting rules as the signal for accelerated compliance spending inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | SFDA licensing compliance unlocks pharmaceutical contract access at premium pricing tiers. |
| IoT Fleet Retrofit Program | Cloud-connected sensor arrays satisfy real-time monitoring mandates for vaccine distribution networks. |
| Multi-Temperature Warehouse Construction | Quick-service restaurant chains demand synchronized frozen, chilled, and ambient handling capacity. |
| HAZMAT Driver Pipeline Development | Specialized certification scarcity threatens pharmaceutical-grade transport capacity expansion timelines. |
| Strategic Land Banking Near Airports | Cargo zone proximity reduces last-mile delivery windows for temperature-sensitive biologics imports. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical distribution executives, cold chain fleet managers, SFDA regulatory affairs specialists, and quick-service restaurant supply chain directors. Secondary validation drew from SFDA regulatory filings, Saudi Customs trade statistics, pharmaceutical industry association reports, and refrigerated transport equipment import records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across solution types and end-use verticals.
Across the analysis window, volume and value outputs reflect modeled projections incorporating solution type penetration rates, end-user vertical growth differentials, and technology adoption curves specific to IoT and blockchain traceability systems. CAGRs were derived from regression analysis of historical infrastructure investment patterns against pharmaceutical manufacturing output forecasts. Modeled inputs included SFDA licensing approval timelines, fleet expansion rates from commercial vehicle registration data, and cold storage construction permits by region.
Underlying assumptions cover sustained biologics manufacturing regionalization and stable SFDA regulatory enforcement intensity, with deviation risk concentrated in cross-border customs friction and refrigerant cost volatility. Forecasts reflect these documented assumptions. Revision becomes warranted when SFDA licensing timelines or biologics production commitments cross material threshold changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asia-Pacific FMCG Logistics Market
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
Central and Eastern Europe Freight and Logistics Market
Logistics and Shipping
North America FMCG Logistics Market
Logistics and Shipping
Europe Third Party Logistics Market
Logistics and Shipping
China less than Truckload Road Freight Transport Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market
Logistics and Shipping
Dry Van Container Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
Finished Vehicle Logistics Market