
 Integrated Quantum Optical Circuits Market | 2026-2036
Integrated Quantum Optical Circuits Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Quantum Optical Circuits Market Outlook
Modular packaging of photonic chips with integrated beam splitters and couplers is expanding buyer choice across quantum computing and telecommunications verticals. Intel Corporation leverages its semiconductor fabrication expertise to anchor silicon photonics production at scale. Lumentum Operations LLC specializes in high-performance optical components for defense and telecom applications. Aifotec AG competes through precision polymer-based waveguide manufacturing for research institutions.
Integrated quantum optical circuits combine waveguides, photonic chips, couplers, and beam splitters on monolithic or hybrid substrates to manipulate single photons for quantum information processing, typically operating at cryogenic temperatures with linewidths below 100 MHz. Silicon photonics technology leads commercial deployment due to CMOS-compatible foundry infrastructure, while lithium niobate segments capture premium margins in high-speed modulator applications. Quantum computing applications show the fastest trajectory as hardware developers demand packaged photonic interconnects for trapped-ion and superconducting qubit systems.
The United States National Institute of Standards and Technology and the Department of Energy shape domestic demand through quantum networking testbed standards and funding mechanisms. European REACH regulations and the EU Chips Act govern material sourcing and semiconductor fabrication incentives across member states. Stakeholders must monitor which regulatory frameworks prioritize export controls on quantum components versus domestic subsidy programs.
Market Dynamics
Defense procurement of quantum-encrypted communication systems is compressing development cycles for photonic interconnects, pulling manufacturing scale toward silicon photonics foundries in Germany and the Netherlands while federal funding mechanisms in the United States reshape domestic capacity allocation.
Growth Catalysts
- EU Chips Act semiconductor incentives:Fabrication subsidies across member states are accelerating cleanroom expansion for photonic chip production. Netherlands-based equipment suppliers report order backlogs extending eighteen months.
- NATO quantum communication mandates:Defense agencies are mandating quantum key distribution for classified networks. Procurement specifications now require integrated beam splitters and couplers with sub-100 MHz linewidth tolerances.
- Trapped-ion qubit scaling:Hardware developers demand packaged photonic interconnects for modular quantum computing architectures. Cryogenic-compatible waveguide assemblies are becoming standard procurement items.
Market Restraints
- Indium phosphide supply concentration:III-V compound semiconductor substrates rely on a limited supplier base concentrated in East Asian foundries. Price volatility for 2-inch and 3-inch wafers compresses margin structures for discrete component manufacturers.
- Cryogenic packaging complexity:Dilution refrigerator integration requires thermal cycling compatibility that polymer-based waveguides struggle to achieve. Research institutions report yield losses above forty percent in multi-layer stack assemblies.
- REACH material restrictions:European chemical regulations constrain solvent choices for polymer waveguide fabrication. German manufacturers face reformulation costs for photoresist chemistries.
Strategic Opportunities
- Quantum networking testbed expansion:United States Department of Energy funding for metropolitan-scale quantum networks creates demand for deployable photonic switch fabrics. Chicago and Boston corridor projects require rack-mounted integrated circuits.
- Lithium niobate modulator convergence:Thin-film processing advances enable hybrid integration with silicon photonics platforms. Telecom equipment vendors are evaluating co-packaged transmitter assemblies for 800G coherent optics.
- Research institution direct sourcing:National laboratories are bypassing traditional distribution channels to commission custom waveguide designs. Direct engagement models reduce specification iteration cycles.
Industry Challenges
- Cryogenic systems engineering talent scarcity:The intersection of photonics design and millikelvin instrumentation expertise remains shallow. University programs produce fewer than two hundred qualified graduates annually across relevant disciplines.
- Multi-foundry qualification timelines:Porting designs between silicon photonics foundries requires extensive process characterization. Product developers face eighteen-month requalification cycles when switching fabrication partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Quantum Optical Circuits Market |
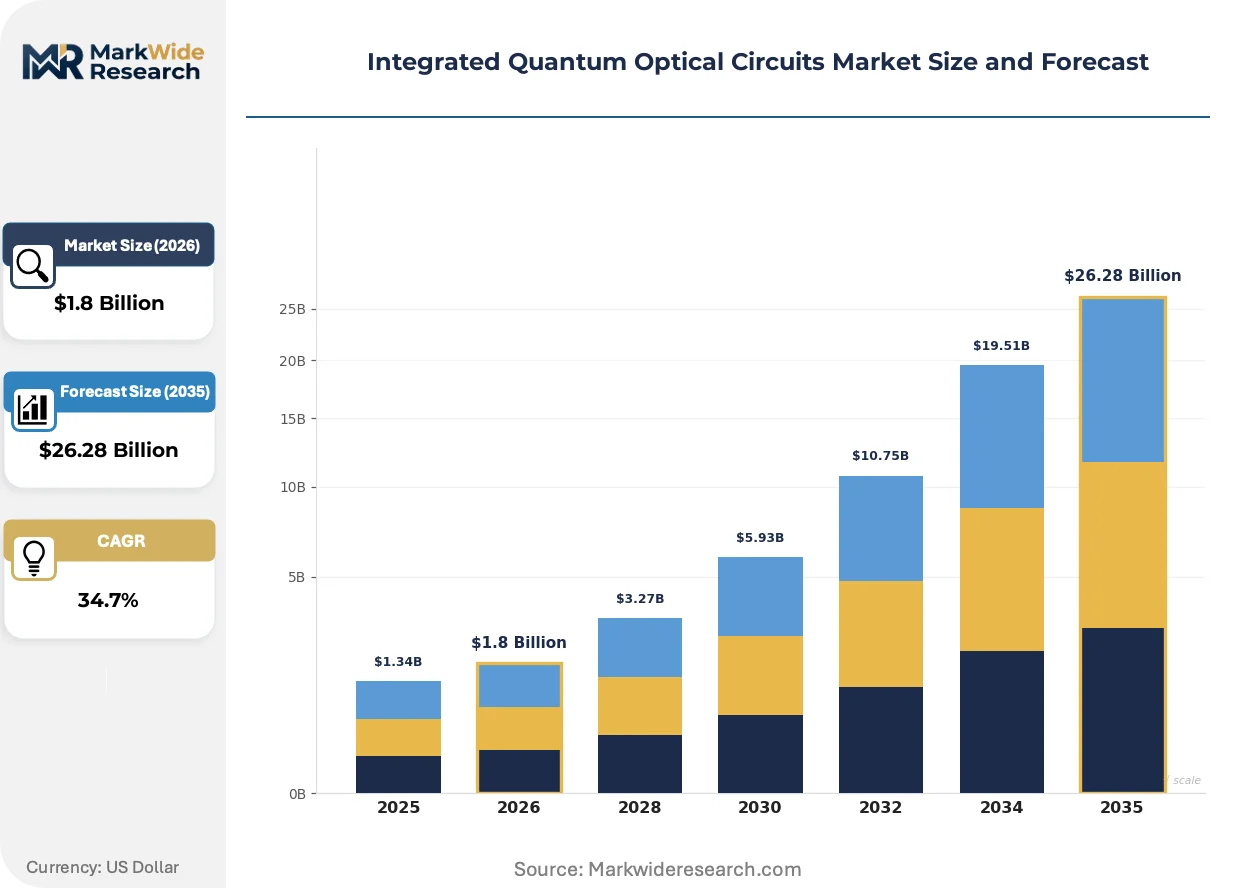
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waveguides, Photonic Chips, Couplers, Beam Splitters Technology: Silicon Photonics, Lithium Niobate, Indium Phosphide, Polymer-based Application: Telecommunications, Quantum Computing, Sensors, Imaging End User: Telecom Providers, Research Institutions, Defense, Healthcare |
| Companies Covered | Ciena Corporation, Emcore Corporation, Intel Corporation, Neophotonics Corporation, Aifotec AG, Infinera Corporation, Finisar Corporation, Lumentum Operations LLC, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Quantum Optical Circuits Market Strategic Shifts
Photonic integration architectures are fragmenting across competing substrate technologies, with hybrid platforms gaining traction as single-material solutions hit performance ceilings in quantum coherence preservation.
Thin-film lithium niobate on insulator is decentralizing modulator performance leadership away from legacy electro-optic materials. Telecom infrastructure vendors are adopting hybrid silicon-lithium niobate platforms for 400G and 800G coherent transmission. The technology is decentralizing supply chain influence from indium phosphide foundries toward specialized thin-film processing facilities.
REACH chemical registration requirements are forcing reformulation of photoresist and solvent chemistries used in polymer waveguide manufacturing. German and Dutch equipment suppliers face eighteen-month requalification cycles for modified process chemistries. Research institutions purchasing precision waveguides are absorbing extended delivery timelines as suppliers navigate compliance transitions.
Buyer concentration among national laboratories and defense agencies is compressing vendor qualification cycles and unbundling after-sales technical support. Equipment vendors report contract structures separating hardware procurement from on-site integration assistance. The United States national quantum initiative funding channels are accelerating this unbundling, with explicit budget line items for independent systems integrators.
Integrated Quantum Optical Circuits Market Segmentation
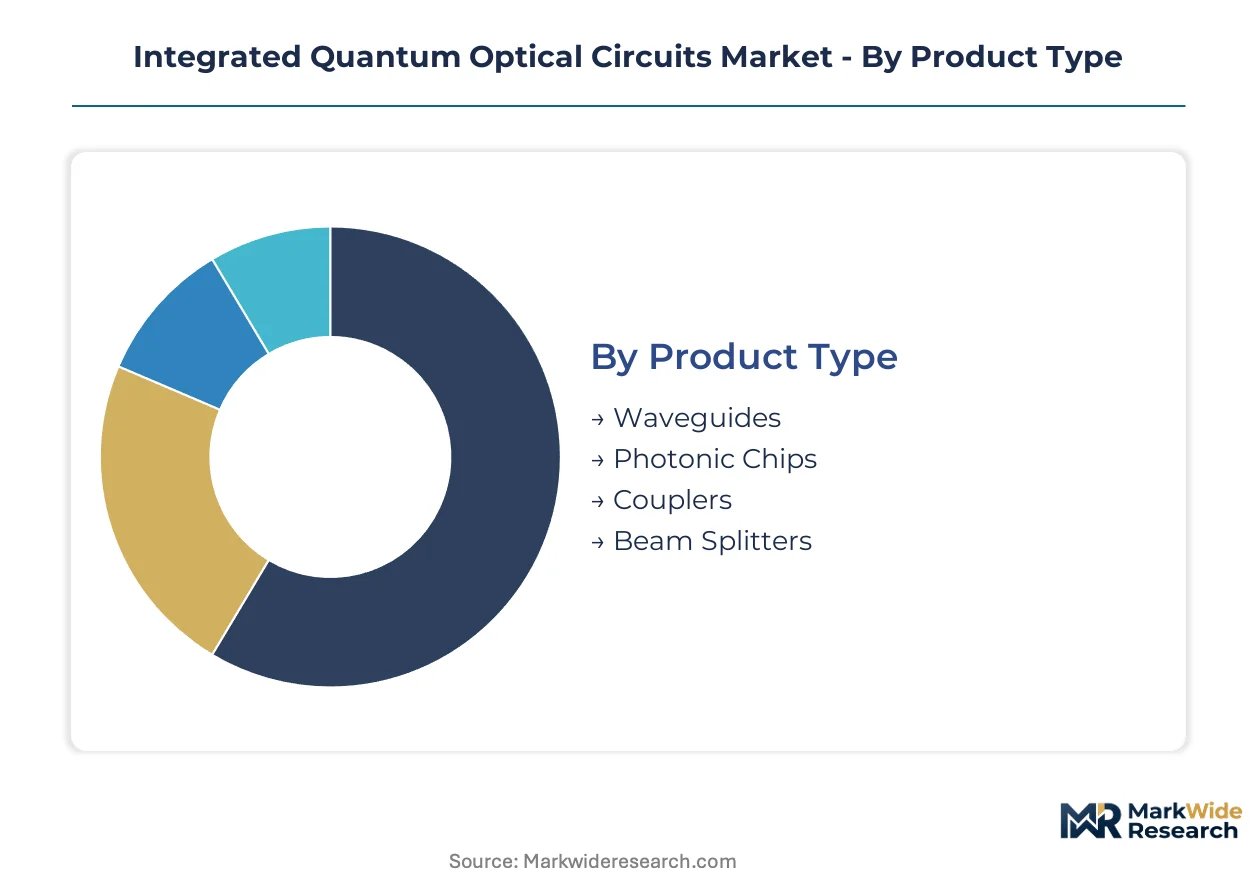
Segmentation in integrated quantum optical circuits reveals how substrate technologies, packaging formats, and end-use requirements fragment procurement specifications. Buyers in defense and quantum computing verticals impose linewidth tolerances below 100 MHz, while telecom applications prioritize CMOS-compatible foundry scale.
Product Type:
Upgrade cycles in quantum hardware are accelerating replacement demand for modular photonic components that integrate multiple optical functions on single substrates.
- Waveguides:Cryogenic-compatible silica and silicon nitride structures route single photons with propagation losses below 0.1 dB/cm. Trapped-ion qubit developers in the United States specify multi-layer stack assemblies for dilution refrigerator integration, though yield losses above forty percent constrain supply.
- Photonic Chips:Monolithic substrates combining active and passive optical elements enable dense integration of quantum gates. Germany and Netherlands-based foundries are expanding cleanroom capacity to serve NATO quantum communication mandates requiring sub-100 MHz linewidth tolerances.
- Couplers:Directional couplers split and combine optical signals with precise power ratios for interferometric measurements.
- Beam Splitters:Integrated Mach-Zehnder interferometers provide tunable splitting ratios for quantum state preparation.
Photonic chips sit at the top of the volume ranking, with waveguides climbing the fastest as cryogenic packaging standards harden.
Technology:
Cost tiers separate mass-deployable silicon platforms from premium materials commanding specialized foundry premiums.
- Silicon Photonics:CMOS-compatible fabrication at 300mm wafer scale leverages existing semiconductor infrastructure. Intel Corporation anchors production capacity for telecom and defense applications where volume and cost predictability outweigh peak performance.
- Lithium Niobate:Thin-film-on-insulator processing achieves electro-optic coefficients an order of magnitude higher than silicon. Hybrid integration with silicon platforms is gaining traction for 800G coherent optics in metropolitan quantum networks.
- Indium Phosphide:III-V compound semiconductors enable direct bandgap emission for integrated lasers and amplifiers.
- Polymer-based:Precision waveguide manufacturing serves research institutions requiring rapid prototyping cycles.
Silicon photonics dominates volume production, with lithium niobate expanding most quickly in high-speed modulator segments.
Application:
Application-specific performance requirements fragment procurement patterns across end-use verticals with divergent temperature and coherence specifications.
- Quantum Computing:Hardware developers demand packaged photonic interconnects for modular architectures spanning superconducting and trapped-ion modalities. United States Department of Energy funding for metropolitan testbeds is pulling manufacturing scale toward deployable switch fabrics.
- Telecommunications:Quantum key distribution systems for classified networks require integrated beam splitters with stability across thermal cycling. NATO procurement specifications are compressing vendor qualification timelines for European suppliers.
- Sensors:Interferometric configurations enable precision measurement applications in metrology and navigation.
- Imaging:Photon-counting arrays support low-light quantum imaging for defense and scientific applications.
Telecommunications maintains volume leadership, with quantum computing gaining share fastest as hardware platforms approach commercial utility.
End User:
Customer concentration among national programs and defense agencies is unbundling procurement into separate hardware and integration contracts.
- Defense:NATO member states mandate quantum-encrypted communication for classified networks, specifying components with sub-100 MHz linewidths. Procurement is compressing development cycles and pulling manufacturing toward qualified foundries in Germany and the Netherlands.
- Research Institutions:National laboratories bypass distribution channels to commission custom waveguide designs, absorbing extended delivery timelines as suppliers navigate REACH reformulation requirements.
- Telecom Providers:Infrastructure vendors evaluate co-packaged transmitter assemblies for coherent optics scaling.
- Healthcare:Quantum sensing applications in medical imaging and diagnostics represent emerging demand.
Defense agencies anchor current procurement volume, with research institutions expanding fastest as direct engagement models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated quantum optical circuits trace their commercial lineage to Bell Labs' foundational photonics research in the United States during the 1980s, with subsequent scaling concentrated in German precision optics clusters and Dutch semiconductor equipment corridors.
United States
The National Institute of Standards and Technology and Department of Energy channel federal funding toward metropolitan quantum networking testbeds in Chicago and Boston. NIST standards for quantum key distribution interoperability shape component procurement specifications. Research institutions in Greater Boston commission custom waveguide designs directly from domestic foundries.
Germany
Defense procurement from NATO member states mandates quantum-encrypted communication systems with sub-100 MHz linewidth tolerances. REACH chemical regulations constrain solvent choices for polymer waveguide fabrication, forcing reformulation costs on photoresist suppliers. The Munich-Stuttgart corridor hosts expanding cleanroom capacity for silicon photonics production.
Netherlands
Equipment suppliers based in the Eindhoven region report order backlogs extending eighteen months for photonic chip fabrication tools. EU Chips Act semiconductor incentives accelerate cleanroom expansion for integrated optical component manufacturing. ASML's lithography ecosystem supports precision patterning for quantum-grade waveguide structures.
United Kingdom
The national quantum programme funds photonic interconnect development for trapped-ion qubit systems at Oxford and Cambridge research clusters. UK Research and Innovation governs grant allocation for quantum technology commercialization. The Cambridge-Imperial corridor concentrates hardware developers demanding cryogenic-compatible packaged components.
Japan
METI's quantum technology roadmap prioritizes domestic photonic chip fabrication capacity for quantum computing applications. The Kansai region's precision manufacturing base supplies optical components for telecommunications and sensing verticals. Osaka-based research consortia advance thin-film lithium niobate processing for high-speed modulator integration.
Integrated Quantum Optical Circuits Market Competitive Environment
Premium-margin players sit above commodity-margin players across substrate material specialization and cryogenic packaging capability. The vendor base organizes into three tiers: semiconductor foundries leveraging CMOS infrastructure, specialized photonics component manufacturers, and precision polymer waveguide suppliers serving research markets. Consolidation pressure concentrates among mid-scale players lacking captive access to 300mm silicon fabrication or thin-film lithium niobate processing. Dominant competitive moves include strategic partnerships between equipment vendors and national quantum programs, plus capacity expansion in qualified European foundries serving NATO defense procurement.
Among United States-based technology conglomerates, Intel Corporation anchors scale-driven production of silicon photonics platforms. Lumentum Operations LLC and Ciena Corporation exemplify the optical systems integration tier, occupying positions between component fabrication and end-use deployment. Aifotec AG represents the precision manufacturing archetype within European specialist circles.
| Leading Market Players |
|---|
| Ciena Corporation |
| Emcore Corporation |
| Intel Corporation |
| Neophotonics Corporation |
| Aifotec AG |
| Infinera Corporation |
| Finisar Corporation |
| Lumentum Operations LLC |
| TE Connectivity |
| Others |
Value Chain & Pricing Dynamics
Thin-film lithium niobate processing advances are compressing modulator production costs while decentralizing supply chain influence from indium phosphide foundries toward specialized European thin-film facilities. This substrate transition simultaneously reshapes cost economics across hybrid silicon-lithium niobate platforms and concentrates premium-component sourcing within Netherlands-based equipment corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates cryogenic-compatible photonic chips from telecom-grade silicon platforms from research-batch polymer waveguides. Price differentiation rests on linewidth tolerance certification and volume scale, with sub-100 MHz specifications commanding substantial premiums. Cost compression in standard-tier silicon photonics is intensifying because CMOS foundry capacity expansion outpaces defense procurement growth. Research institutions exhibit highest price sensitivity due to grant-funded budget constraints, while NATO defense agencies prioritize performance over unit economics.
Supply Chain Analysis
Domestic-content mandates in United States national quantum initiatives and EU Chips Act incentives are reshaping sourcing patterns toward qualified foundries in Germany, the Netherlands, and domestic United States facilities. Raw material dependencies center on indium phosphide wafers, lithium niobate substrates, and specialized photoresist chemistries. Single-source vulnerability concentrates in East Asian III-V compound semiconductor foundries. Distribution runs through direct commissioning channels for national laboratories alongside traditional component distributors serving telecom equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in cryogenic packaging capabilities and thin-film lithium niobate processing, justified by silicon photonics cost-down curves and premium-tier demand from defense agencies.
For Market Incumbents: Anticipate consolidation pressure from mid-scale players lacking captive 300mm silicon fabrication or thin-film lithium niobate processing. Defend position by deepening backward integration into indium phosphide wafer sourcing and expanding cleanroom capacity in Germany-Netherlands corridors before EU Chips Act subsidies expire. Prioritize cryogenic systems engineering talent acquisition to offset qualified graduate scarcity. For New Entrants and Emerging Players: Launch via direct engagement models with United States national laboratories bypassing traditional distribution channels. Target research institution procurement of custom waveguide designs, the most penetrable segment given extended delivery timelines from incumbent suppliers navigating REACH reformulation. Emphasize rapid prototyping cycles for polymer-based precision manufacturing. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale photonics component manufacturers lacking multi-foundry qualification capabilities. Long-term viability favors specialists with hybrid integration expertise spanning silicon photonics and lithium niobate platforms. Watch trapped-ion qubit hardware developer procurement volumes as the inflection indicator for modular photonic interconnect demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Platform Integration | Combines silicon photonics scale with lithium niobate performance for 800G coherent optics deployment. |
| Cryogenic Packaging Capability Buildout | Addresses yield losses above forty percent in multi-layer stack assemblies for dilution refrigerator integration. |
| Direct National Laboratory Engagement | Bypasses distribution channels to capture custom waveguide procurement from United States Department of Energy funded testbeds. |
| Thin-Film Lithium Niobate Processing Investment | Decentralizes modulator supply chain from indium phosphide concentration toward Netherlands-based equipment corridors. |
| Multi-Foundry Qualification Expansion | Reduces eighteen-month requalification risk when porting designs between silicon photonics fabrication partners. |
Study Parameters
Coverage spans the United States, Germany, Netherlands, United Kingdom, and Japan, with primary inputs from each market cluster combining executive interviews with quantum hardware developers, photonics foundry operations directors, defense procurement officers, research institution principal investigators, and telecom equipment vendor supply chain managers. Secondary validation draws from NIST standards documentation, EU Chips Act regulatory filings, Department of Energy funding announcements, METI technology roadmaps, and SEC filings from publicly traded optical component manufacturers. Bottom-up demand modeling triangulates against top-down market sizing across substrate technology categories.
Granularity-level modeling extends to individual substrate technologies, packaging formats, and end-use verticals with divergent temperature and coherence specifications. Segment-level CAGRs derive from hardware deployment timelines in quantum computing, NATO defense procurement cycles, and telecom infrastructure upgrade patterns. Forecast inputs incorporate cleanroom capacity expansion backlogs, REACH chemical registration timelines, and trapped-ion qubit system commercialization trajectories across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control tightening on quantum components or indium phosphide supply disruption. Analytical boundaries exclude speculative quantum computing hardware volumes beyond demonstrated qubit coherence benchmarks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Isolator Market
Optical Components
Display Optical Film Market
Optical Components
Optical Image Stabilization (OIS) Actuators Market
Optical Components
Global Optical Network Hardware Market
Optical Components
Mobile Optical Pluggable Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
Liquid Lenses Market
Optical Components
Diode Laser Module Market
Optical Components
Digital Optical Transmitter Market
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Optical Sensor Market
Optical Components
Photointerrupter Market
Optical Components
Liquid Light Guides Market
Optical Components
ROADM WSS Component Market
Optical Components
Pancake Optical Module Market
Optical Components
China Lithium Niobate Modulator Market