
 100G Optical Transceivers Market | 2026-2036
100G Optical Transceivers Market Size, Share, and Industry Trends Forecast 2026-2036
100G Optical Transceivers Market Insights
Project finance tied to hyperscale data center buildouts is tilting competitive access toward vendors with balance-sheet scale. Coherent Corp. leverages vertical integration across laser chips and module assembly to protect margin pools. INNOLIGHT anchors its position through manufacturing scale in Suzhou and Wuhan, serving both domestic Chinese carriers and export demand. Broadcom Inc. competes by controlling merchant silicon supply for DSPs and drivers that power third-party module designs.
A 100G optical transceiver converts electrical signals into optical pulses for transmission over fiber at 100 gigabits per second, typically employing PAM4 modulation or coherent detection with wavelengths near 1310 nm or 1550 nm depending on reach requirements. QSFP28 dominates volume in data center interconnects where density and power efficiency matter most, while coherent CFP2 variants sustain premium pricing in metro and long-haul telecommunications. Cloud Services as an application segment is outpacing Enterprise Networking in absolute port growth, though Telecom Operators remain the stickiest end user due to multi-year wavelength division multiplexing refresh cycles.
FCC equipment authorization rules govern transceiver deployment in US telecommunications infrastructure, while the EU AI Act and CSRD reporting requirements are pushing European data center operators toward energy-efficient optical interconnects with documented carbon footprints. China's GB standards and MIIT certification requirements create a dual-track compliance burden for multinational suppliers. Stakeholders must monitor how NIST post-quantum cryptography timelines intersect with optical encryption modules embedded in 100G form factors.
Market Dynamics
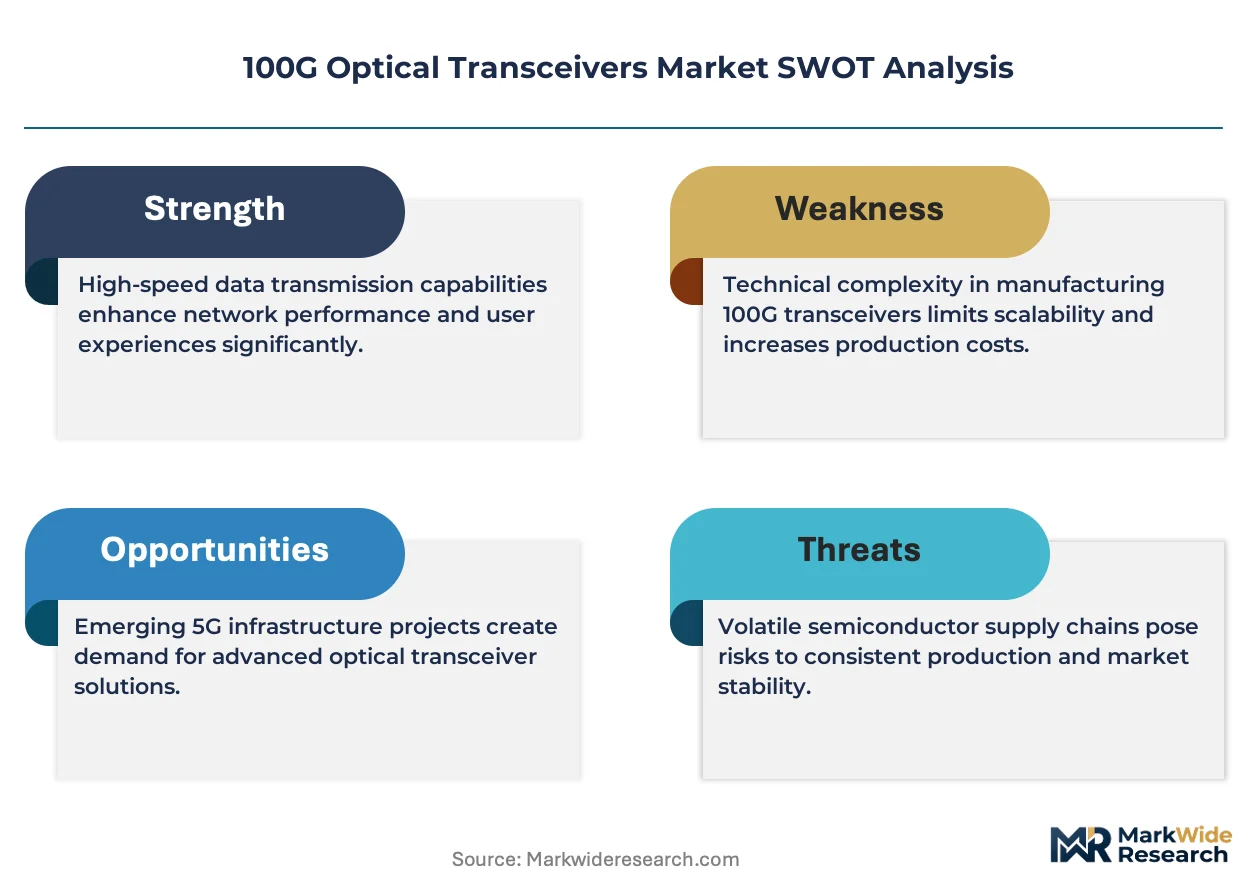
AI training clusters are forcing hyperscale operators to double 100G port density per rack, compressing power budgets and collapsing traditional refresh cycles from five years to eighteen months.
Growth Catalysts
- Hyperscale buildouts:Cloud providers in Ashburn and Hillsboro are deploying 100G transceivers at rack-scale density to feed GPU interconnect fabrics for large language model training.
- MIIT localization mandates:China's Ministry of Industry and Information Technology procurement rules are redirecting state-owned carrier spending toward domestic-qualified 100G module suppliers.
- PAM4 modulation maturation:Four-level pulse amplitude modulation is extending 100G reach over multimode fiber without coherent optics, cutting cost-per-bit for data center interconnects.
Market Restraints
- Indium phosphide supply concentration:Laser chip foundries cluster in Taiwan and Japan, creating single-source risk for 100G CWDM4 and LR4 transmitter assemblies.
- FCC equipment authorization friction:Transceiver vendors face twelve-to-eighteen month certification timelines for US telecom infrastructure, gating revenue recognition.
- Silicon photonics yield limits:Monolithic integration of modulators and photodetectors on silicon substrates remains below commercial yield thresholds for 100G coherent variants.
Strategic Opportunities
- Edge AI inference nodes:Distributed machine learning workloads in secondary US metros are creating 100G demand outside traditional hyperscale hubs.
- EU CSRD carbon disclosure:European data center operators must document optical interconnect energy intensity, favoring suppliers with ISO 14040-compliant lifecycle data.
- Linear drive pluggable optics:Eliminating DSPs from 100G modules cuts power by forty percent, opening retrofit opportunities in thermally constrained legacy facilities.
Industry Challenges
- Coherent DSP firmware talent scarcity:Algorithm engineers capable of optimizing 100G DSP ASICs for power and dispersion compensation command premium compensation packages.
- QSFP28 thermal validation:Module vendors must recertify existing designs for eighty-five degree Celsius ambient operation in AI server environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 100G Optical Transceivers Market |
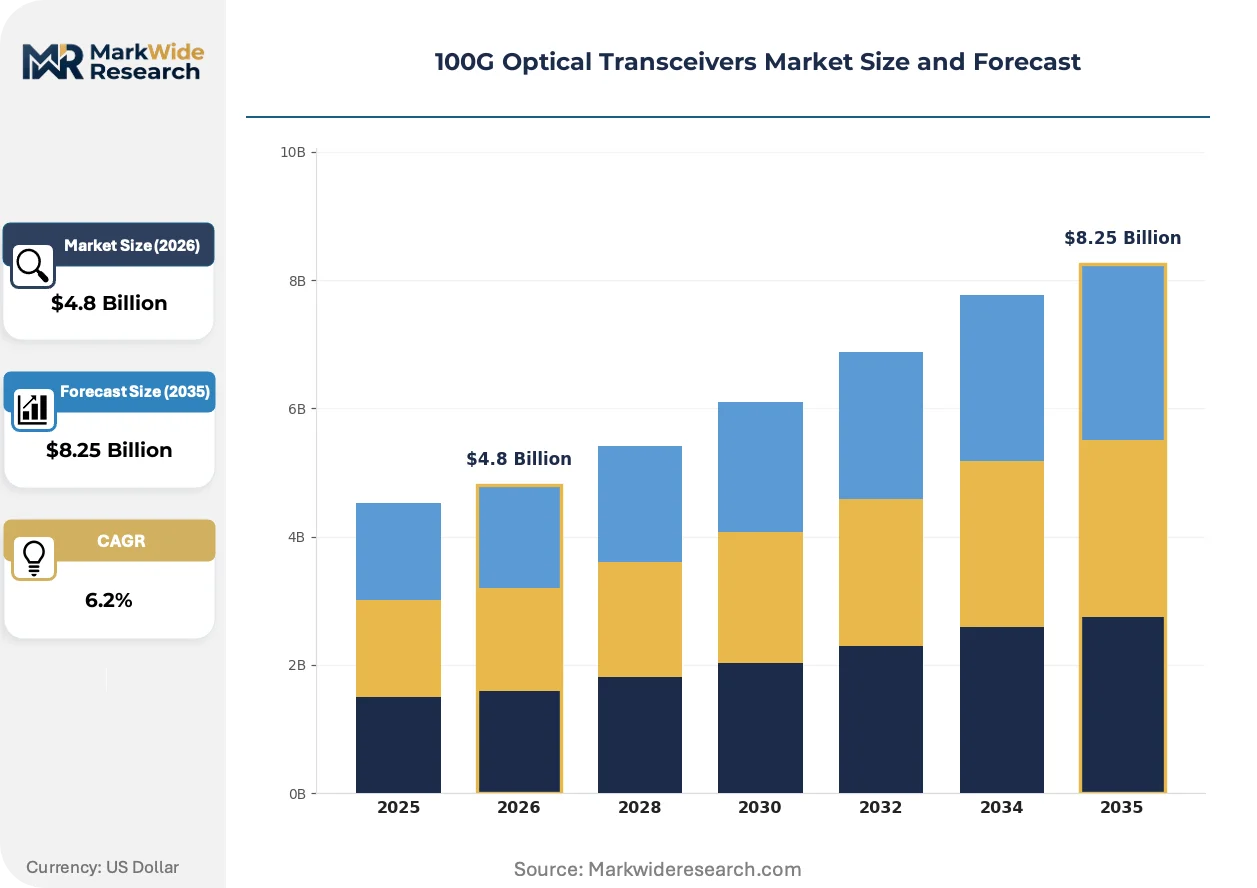
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SFP28, QSFP28, CFP2, XFP Application: Data Center, Telecommunications, Enterprise Networking, Cloud Services End User: Telecom Operators, Data Center Providers, Enterprises, Network Service Providers Technology: Optical Fiber, Coherent Technology, Single-Mode Fiber, Multi-Mode Fiber |
| Companies Covered | Coherent Corp., INNOLIGHT, Lumentum Operations LLC, Accelink Technology Co. Ltd., Cisco Systems, Inc., Broadcom Inc., Sumitomo Electric Industries, Ltd., Source Photonics, Eoptolink Technology Inc., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
100G Optical Transceivers Market Trends and Innovations
Three concurrent shifts are compressing 100G transceiver development cycles: silicon photonics process maturation, regulatory pressure on optical power consumption, and hyperscale procurement consolidation around vertically integrated suppliers.
Linear drive pluggable (LPO) technology is digitizing the electrical-optical interface by removing retimers and DSPs from the signal path. Hyperscale operators in Oregon and Virginia are piloting LPO 100G modules for intra-cluster links where reach stays under two kilometers. This compression of the optoelectronic stack is digitizing margin structures by collapsing the merchant DSP vendor layer.
EU CSRD reporting requirements are mandating granular energy disclosure for data center optical interconnects. Operators must now submit watt-per-gigabit metrics for 100G deployments across their European footprints. German and Dutch facility managers are responding by specifying modules with documented thermal design power and supplier-provided lifecycle carbon footprints.
Hyperscale procurement teams are consolidating vendor lists to suppliers with captive laser fabrication. Cloud operators in the United States now require direct fab access as a qualification criterion for 100G multi-source agreements. This concentration is visible in RFP structures that weight backward integration into III-V semiconductor manufacturing above module-level pricing.
100G Optical Transceivers Market Segmentation
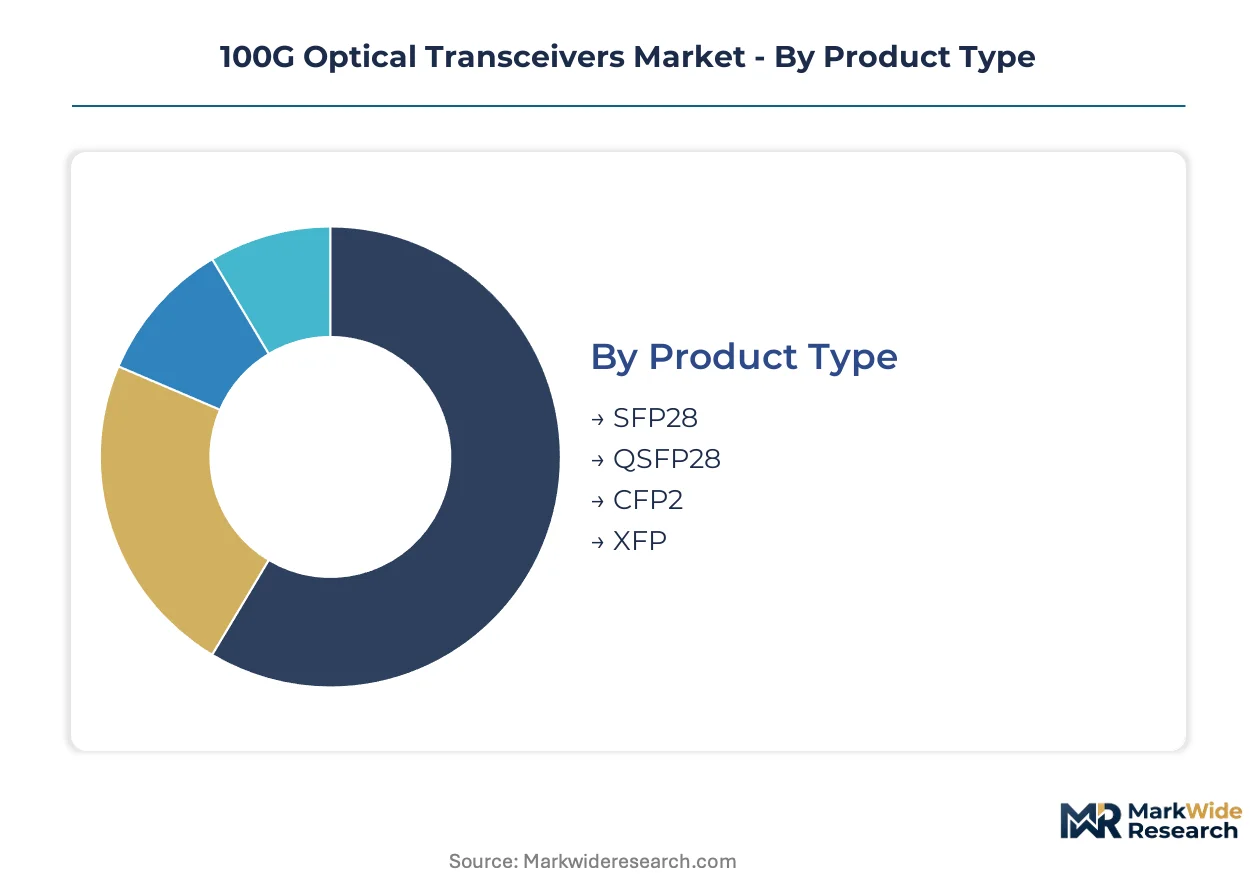
100G transceiver procurement splits across incompatible form factors, divergent reach requirements, and contrasting customer technical capabilities. Understanding these fault lines clarifies why pricing and supplier access vary dramatically within the same headline data rate.
Product Type:
Mature QSFP28 variants dominate volume shipments while emerging linear-drive formats reshape power-constrained deployments.
- QSFP28:The quad small form-factor pluggable design packs four 25G electrical lanes into a single port, delivering 100G over multimode fiber for intra-data center links. Hyperscale operators in Ashburn and Hillsboro specify QSFP28-SR4 variants for GPU cluster interconnects where reach stays under 100 meters and port density governs rack economics. QSFP28 retains volume leadership; SFP28 holds the steepest expansion curve.
- SFP28:The single-lane 25G form factor enables 100G through breakout cables or aggregated links, appealing to enterprises with legacy 10G infrastructure and limited fiber plant. German automotive manufacturers deploying edge AI inference nodes favor SFP28 for incremental upgrades without full switch replacement.
- CFP2:The C form-factor pluggable second generation supports coherent 100G transmission over thousands of kilometers, sustaining premium pricing in submarine and long-haul terrestrial routes where dispersion compensation demands complex DSP architectures.
- XFP:The 10 gigabit small form-factor pluggable serves 100G through ten-lane aggregation, persisting in telecom transport networks where equipment refresh cycles extend beyond a decade and backward compatibility outweighs density gains.
QSFP28 retains volume leadership; SFP28 holds the steepest expansion curve.
Application:
Cost tier separation runs deepest between hyperscale data center buildouts and regulated telecommunications infrastructure.
- Data Center:Internal fiber interconnects between compute, storage, and network tiers demand hot-pluggable modules with sub-3.5W power draw. Dutch facility operators under EU CSRD mandates specify modules with documented thermal design power and supplier-provided lifecycle carbon footprints.
- Cloud Services:Public cloud providers provision 100G at rack scale to feed distributed training clusters, collapsing traditional five-year refresh cycles to eighteen months. Oregon-based operators pilot linear-drive pluggable variants for intra-cluster links under two kilometers.
- Telecommunications:Wavelength division multiplexing systems require coherent 100G with advanced modulation formats and forward error correction, sustaining longer procurement timelines and stricter FCC equipment authorization protocols.
- Enterprise Networking:Corporate campus and branch office deployments favor lowest-cost PAM4-based direct detect optics, with procurement concentrated through systems integrators rather than direct module sourcing.
Cloud Services commands the steepest expansion trajectory; Data Center maintains absolute port volume leadership.
End User:
Customer type determines technical qualification depth, procurement consolidation patterns, and acceptable supplier risk profiles.
- Data Center Providers:Colocation and hyperscale facility operators negotiate multi-source agreements requiring direct fab access as a qualification criterion, consolidating vendor lists to suppliers with captive laser fabrication in Taiwan or Japan.
- Telecom Operators:State-owned carriers in China redirect procurement toward domestic-qualified suppliers under MIIT localization mandates, while European incumbents prioritize ISO 14040-compliant lifecycle documentation for regulatory disclosure.
- Enterprises:Corporate IT departments purchase through channel partners with limited technical evaluation capabilities, creating vulnerability to counterfeit or out-of-specification gray market modules.
- Network Service Providers:Wholesale bandwidth aggregators balance cost optimization against service level guarantees, specifying industrial temperature grade modules for uncontrolled outdoor cabinet deployments.
Data Center Providers drive specification evolution; Telecom Operators sustain the longest contract visibility.
Technology:
Supply concentration in laser chip foundries creates divergent risk profiles across optical transmission media.
- Optical Fiber:The physical waveguide medium encompasses both silica-based single-mode and graded-index multimode variants, with fiber type selection locking in compatible transceiver form factors for the infrastructure lifecycle.
- Single-Mode Fiber:9-micron core diameter enables coherent 100G transmission over 80+ kilometers, concentrating demand in inter-data center links and metro aggregation networks where dispersion-unmanaged reach matters.
- Multi-Mode Fiber:50-micron or 62.5-micron core supports lower-cost vertical-cavity surface-emitting laser sources for sub-500-meter links, dominating intra-building connectivity in existing enterprise fiber plants.
- Coherent Technology:Dual-polarization quadrature phase shift keying with digital signal processing enables 100G over thousands of kilometers, though silicon photonics yield limits constrain monolithic integration economics.
Single-Mode Fiber anchors long-haul economics; Coherent Technology commands the steepest specification premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in optical transceivers track the geographic dispersion of laser chip fabrication and module assembly capacity. The United States runs a structural deficit in finished modules while maintaining surplus positions in merchant silicon and test equipment. China has inverted this pattern through MIIT-directed capacity expansion.
United States
Hyperscale operators in Ashburn, Virginia and Hillsboro, Oregon anchor transceiver consumption for AI training clusters. FCC equipment authorization rules govern deployment timelines, creating twelve-to-eighteen month certification friction for telecom infrastructure. Domestic module assembly concentrates in Texas and Arizona, though laser chip sourcing remains import-dependent.
China
MIIT localization mandates redirect state-owned carrier procurement toward domestic-qualified suppliers. Suzhou and Wuhan host concentrated module manufacturing serving both domestic demand and export markets. GB standards and certification requirements impose dual-track compliance burdens on multinational suppliers seeking market access.
Japan
Indium phosphide laser foundries cluster in Tokyo and Osaka prefectures, creating single-source supply risk for CWDM4 transmitter assemblies. METI industrial policy supports advanced packaging investments for silicon photonics integration. Japanese vendors supply critical optical components to US and Chinese module integrators.
Germany
EU CSRD reporting requirements push data center operators toward energy-efficient interconnects with documented carbon footprints. Frankfurt and Munich host dense colocation facilities specifying ISO 14040-compliant lifecycle data. German automotive manufacturers deploying edge AI nodes favor incremental SFP28 upgrades over full infrastructure replacement.
Netherlands
Dutch facility operators under CSRD mandates specify modules with granular watt-per-gigabit disclosure. Eindhoven anchors photonics research commercialization through public-private partnerships. Amsterdam data centers pilot linear-drive pluggable variants for thermally constrained legacy facilities.
100G Optical Transceivers Market Competitive Landscape
On the supply side, the industry is consolidating around vendors with captive laser fabrication and merchant silicon control. Tiered competitive positions separate vertically integrated specialists from module-level assemblers dependent on external component sourcing. Three archetypes dominate: III-V semiconductor fabricators with backward integration into module assembly, merchant DSP and driver suppliers controlling critical silicon content, and pure-play module specialists scaling through manufacturing efficiency. Dominant competitive moves include multi-source agreement consolidation by hyperscale procurement teams and captive fab access becoming a qualification threshold.
Among US-based component suppliers, Coherent Corp. and Broadcom Inc. exemplify divergent strategic positions. Coherent occupies the integrated photonics archetype through in-house production of laser chips and module assembly. Broadcom anchors the merchant silicon tier, supplying DSPs and drivers that power third-party module designs. Chinese specialists INNOLIGHT and Accelink Technology Co. Ltd. represent manufacturing-scale competitors serving both domestic MIIT-qualified demand and export markets through Suzhou and Wuhan production bases.
| Leading Market Players |
|---|
| Coherent Corp. |
| INNOLIGHT |
| Lumentum Operations LLC |
| Accelink Technology Co. Ltd. |
| Cisco Systems, Inc. |
| Broadcom Inc. |
| Sumitomo Electric Industries, Ltd. |
| Source Photonics |
| Eoptolink Technology Inc., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Indium phosphide laser foundries in Taiwan and Japan concentrate upstream supply for 100G transmitter assemblies, anchoring margin pools in the III-V semiconductor tier rather than module integrators. This geographic concentration of critical laser chip fabrication enables foundries to capture value while compressing assembly margins downstream.
Pricing Analysis
Hyperscale data center operators anchor a three-tier pricing structure across premium, standard, and economy levels in the 100G transceiver market. Price differentiation rests on certification grade—FCC-authorized telecom variants command substantial premiums over data center-qualified modules—and volume scale through multi-source agreements. Cost compression in QSFP28 segments is intensifying because silicon photonics yields are improving and merchant DSP vendors are consolidating. Enterprise networking teams exhibit the highest price sensitivity, while telecom operators under multi-year wavelength division multiplexing refresh cycles accept premium pricing for coherent CFP2 variants with guaranteed supply continuity.
Supply Chain Analysis
Extended payment terms from hyperscale procurement teams are reshaping working capital requirements for module assemblers, with supply-chain finance facilities increasingly common among tier-two vendors. Manufacturing concentrates in China, Japan, and the United States, with Suzhou and Wuhan hosting captive assembly for domestic MIIT-qualified demand and export markets. Raw material dependencies center on indium phosphide substrates, germanium photodetectors, and merchant DSP silicon from specialized foundries. Single-source vulnerability in Tokyo and Osaka-based laser chip production creates concentration risk for CWDM4 and LR4 transmitter assemblies. Distribution runs through direct multi-source agreements with hyperscale operators, systems integrators serving enterprise accounts, and state-owned carrier procurement channels in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in firmware maintenance and field-upgradeable DSP programming are expanding faster than hardware shipments, as hyperscale operators prioritize operational continuity over capital cost minimization. Recurring revenue from embedded software subscriptions and thermal validation services now outpaces module ASP growth across the installed base.
For Market Incumbents: Pre-empt silicon photonics displacement by deepening in-house production of modulator and photodetector components before yield thresholds cross commercial viability. Lock in multi-source agreement renewals with hyperscale operators by offering direct fab access as a bundled qualification, neutralizing emerging Chinese competitors with MIIT-certified capacity. Prioritize thermal validation service contracts for AI server environments where eighty-five degree Celsius ambient operation demands ongoing certification support.
For New Entrants and Emerging Players: Build out edge AI inference node deployments in secondary US metros outside Ashburn and Hillsboro, where hyperscale procurement consolidation has not yet captured vendor lists. Target German automotive manufacturers deploying incremental SFP28 upgrades for factory-floor AI workloads, as their limited fiber plant and legacy switch infrastructure favor single-lane form factors over full infrastructure replacement. Lead with ISO 14040-compliant lifecycle carbon documentation to penetrate EU CSRD-mandated data center operator procurement in Frankfurt and Amsterdam.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed module assemblers lacking captive laser fabrication, as their margin compression accelerates against vertically integrated competitors. Long-term viability across the analysis window favors targets with backward integration into III-V semiconductor manufacturing or exclusive merchant silicon relationships with DSP suppliers. Monitor NIST post-quantum cryptography timeline acceleration as an inflection signal for optical encryption module demand embedded in 100G form factors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Fabrication | Captive indium phosphide foundry access secures margin pools against merchant chip price volatility. |
| Linear Drive Pluggable Module Launch | Eliminating DSPs cuts power draw forty percent for thermally constrained AI cluster deployments. |
| EU CSRD Compliance Certification | ISO 14040 lifecycle documentation opens procurement channels with Dutch and German facility operators. |
| MIIT Qualification Pathway Investment | GB standards certification enables access to state-owned carrier procurement in China's domestic market. |
| FCC Equipment Authorization Acceleration | Compressed twelve-month certification timelines improve revenue recognition speed for telecom infrastructure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capital expenditure disclosures, and customs trade data for optical component flows. Interviews with hyperscale data center procurement directors, optical module engineering leads, telecom carrier network planners, and semiconductor foundry operations managers informed demand-side and supply-side assessments. Secondary validation drew from FCC equipment authorization databases, MIIT certification registries, and EU CSRD implementation guidance documents. Bottom-up port shipment estimates triangulated against top-down infrastructure investment forecasts across the analysis window.
Forecast inputs include modeled segmentation across form factor type, reach requirement, end-user archetype, and geographic regulatory cluster. The projection horizon incorporates PAM4 modulation maturation curves, silicon photonics yield improvement trajectories, and hyperscale rack-density scaling assumptions. CAGRs derive from regression analysis of historical port deployment patterns against AI training cluster buildout schedules. Industry-specific inputs encompass FCC authorization timeline distributions and MIIT localization mandate implementation pacing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by merchant DSP vendors or Chinese state-supported foundry expansions would shift outcomes. Forecasts reflect documented assumptions about laser chip supply continuity and hyperscale procurement consolidation trajectories. Macroeconomic contraction, accelerated NIST post-quantum cryptography mandates, or breakthrough silicon photonics yield improvements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Position Sensors Market
Optical Components
Digital Cinema Lens Market
Optical Components
Diode Laser Module Market
Optical Components
South Korea Optical Detector Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Duplication Disc Market
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
CMP Polishing Machine Market
Optical Components
Laser Module Market
Optical Components
Optical Transceiver Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Objective Lens Market
Optical Components
Nonlinear Optical Crystals Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Global Optical Connectivity Solutions Market