
 Technical Fluids Market | 2026-2036
Technical Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Technical Fluids Market Analysis
Polyalkylene glycol is expanding its share in metalworking coolant formulations as shops abandon mineral oil bases to cut disposal costs and extend sump life. ExxonMobil Corporation leverages its integrated base oil supply chain to control input costs across hydraulic fluid grades. Shell plc anchors its position through synthetic lubricant R&D focused on electric vehicle thermal management. BASF SE differentiates via specialty additive packages that extend fluid change intervals in high-load manufacturing environments.
Technical fluids encompass engineered liquids formulated with precise viscosity indices, thermal stability thresholds, and additive chemistries to transfer energy, reduce friction, or regulate temperature in mechanical systems. Manufacturing processes such as catalytic hydrocracking and esterification yield base stocks with saturated molecular structures that resist oxidation in extended-service applications. Lubricants command the largest value pool given their penetration across automotive and industrial machinery, while heat transfer fluids capture above-average margins in data center and renewable energy thermal loops. Coolants represent the fastest-expanding category as electric vehicle battery thermal management and precision machining intensify demand for dielectric and low-conductivity formulations.
The EPA regulates chemical substances in technical fluids through TSCA Section 5 premanufacture notices, while REACH restricts Substances of Very High Concern in formulations sold across Europe. OEMs now face dual compliance burdens as the EU F-Gas Regulation phases down fluorinated greenhouse gases used in specialty heat transfer applications. Stakeholders must track evolving substance restrictions to avoid reformulation costs and supply chain disruptions.
Market Dynamics
The EPA's updated TSCA Section 5 rules on PFAS chemicals force formulators toward fluorine-free alternatives, compressing reformulation timelines and rewiring raw-material sourcing across coolant and heat-transfer fluid portfolios.
Growth Catalysts
- Semiconductor fabrication expansion:Taiwan and South Korea manufacturing facilities drive dielectric coolant demand for precision thermal management in advanced node production.
- REACH SVHC restrictions:European substance restrictions accelerate substitution of mineral oil bases with polyalkylene glycol formulations in metalworking applications.
- Electric vehicle thermal architecture:Battery pack cooling requirements pull low-conductivity fluids into automotive supply chains at volume scale.
Market Restraints
- Base oil supply concentration:Integrated majors control catalytic hydrocracking capacity, limiting independent formulators' feedstock flexibility.
- PFAS regulatory friction:EPA premanufacture notice requirements extend new chemistry approval timelines by 18-24 months.
- Fluorinated gas phase-down:EU F-Gas Regulation compresses availability of specialty heat transfer fluids for data center applications.
Strategic Opportunities
- Renewable energy thermal loops:Concentrated solar and offshore wind installations in Spain and Portugal create demand for high-temperature heat transfer fluids.
- Extended-drain synthetic formulations:BASF additive packages enable 8,000-hour hydraulic fluid intervals, reducing total cost of ownership for German industrial maintenance.
- Direct-to-fleet distribution:Commercial vehicle operators bypass traditional jobber networks through bulk supply agreements with formulators.
Industry Challenges
- Formulation chemist scarcity:Expertise in esterification and additive synergy design concentrates at legacy lubricant majors, constraining startup innovation.
- Dual compliance burden:OEMs must synchronize EPA TSCA notifications with REACH registration timelines for cross-Atlantic product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technical Fluids Market |
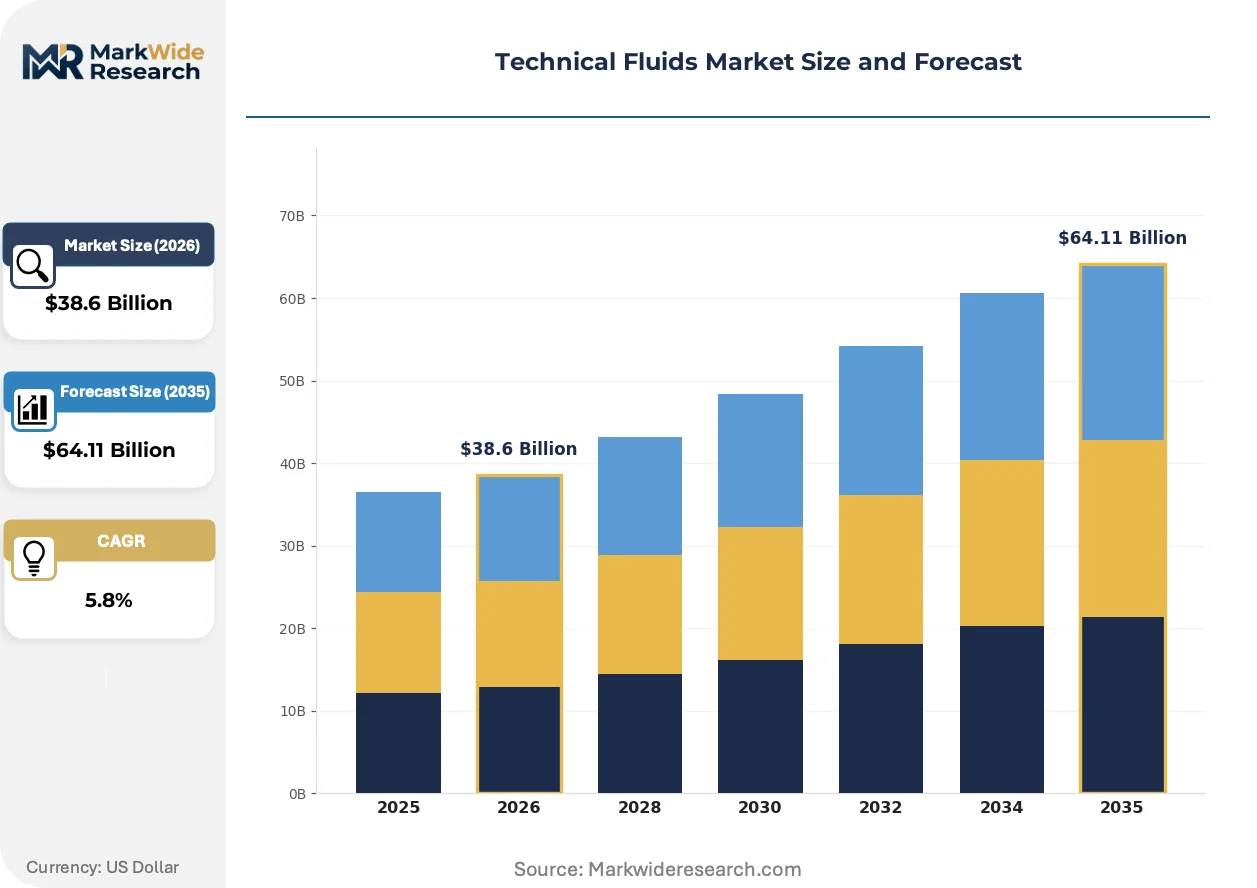
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fluid Type: Hydraulic Fluids, Lubricants, Coolants, Heat Transfer Fluids Application: Automotive, Aerospace, Manufacturing, Construction End User: OEMs, Repair Shops, Industrial Facilities, Maintenance Providers Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Distributors |
| Companies Covered | ExxonMobil Corporation, Shell plc, Arkema Group, TotalEnergies SE, Chevron Corporation, BASF SE, Eastman Chemical Company, FUCHS SE, CIMCOOL Industrial Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technical Fluids Market Emerging Trajectories
Reformulation chemistry and thermal management architecture are converging to displace legacy mineral oil and fluorinated fluid systems across precision manufacturing and electrified transport.
Dielectric nanofluid technology is integrating suspended ceramic particles into coolant bases to enhance thermal conductivity without sacrificing electrical isolation. Data center operators in Singapore and the Netherlands pilot these formulations for direct-to-chip cooling. The technology is integrating liquid-immersion cooling into mainstream server rack designs previously limited to air or water-glycol loops.
EU F-Gas Regulation phase-down mandates are compressing hydrofluorocarbon availability for specialized heat transfer applications. Industrial users face forced migration to hydrofluoroethers or hydrocarbon alternatives with narrower operating temperature windows. German chemical processors and French pharmaceutical manufacturers accelerate testing of next-generation low-GWP fluids to avoid supply interruption.
Fluid-as-a-service contracting is displacing transactional bulk purchasing among automotive tier-one suppliers. Shell and ExxonMobil retain ownership of in-sump inventory, charging per machined part or per operating hour instead of per liter delivered. This model concentrates in high-volume German and Japanese automotive component manufacturing where sump life predictability justifies vendor risk assumption.
Technical Fluids Market Segmentation
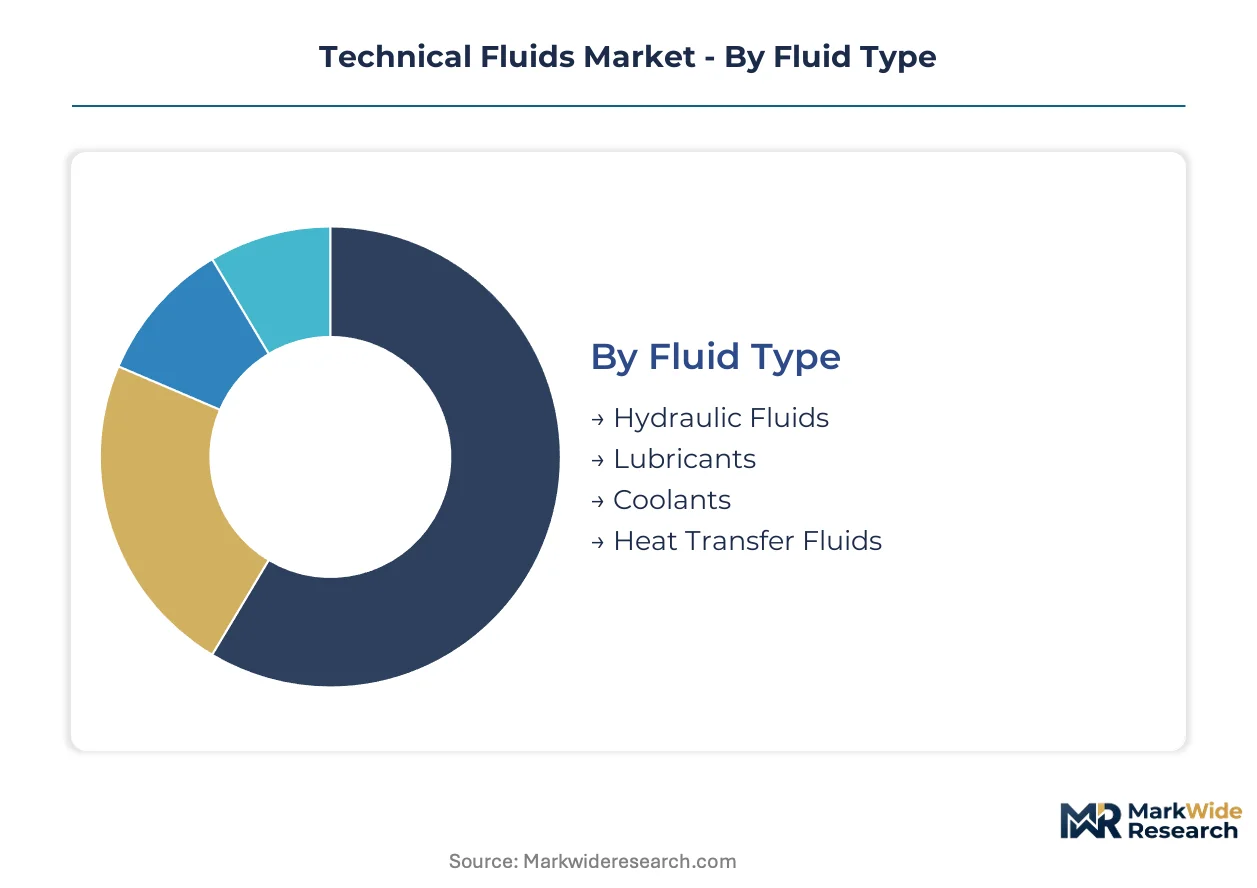
Technical fluids serve radically different thermal and friction regimes across applications. Segmentation reveals how formulation chemistry, service intervals, and procurement patterns diverge by mechanical system type and buyer sophistication.
Fluid Type:
Cost tier separates commodity mineral oil bases from synthetic formulations commanding 3-4x per-liter pricing.
- Hydraulic Fluids:Formulated with anti-wear zinc dialkyldithiophosphate additives and viscosity index improvers to maintain film strength across temperature swings. German industrial maintenance providers concentrate demand for extended-drain synthetics that compress total cost of ownership despite higher upfront pricing.
- Coolants:Dielectric formulations with controlled electrical conductivity below 0.1 μS/cm enable direct contact with live electronics. Taiwan and South Korea semiconductor fabrication facilities pull these fluids into advanced node production where precision thermal management determines yield rates.
- Lubricants:Saturated molecular structures from catalytic hydrocracking resist oxidation in extended-service automotive and industrial machinery applications.
- Heat Transfer Fluids:Engineered for thermal stability across concentrated solar and data center loops where phase-change behavior must remain predictable.
Lubricants lead volumes today; coolants are gaining share fastest.
Application:
Volume scale and specification stringency create four distinct demand profiles.
- Automotive:Electric vehicle battery thermal architecture pulls low-conductivity dielectric fluids into OEM supply chains at unprecedented scale. Cooling loop designs now prioritize dielectric properties over traditional corrosion inhibition.
- Manufacturing:Metalworking operations in Germany and Japan drive polyalkylene glycol adoption as REACH SVHC restrictions accelerate abandonment of mineral oil bases.
- Aerospace:MIL-PRF specification compliance and extreme temperature operability dominate formulation requirements.
- Construction:Equipment uptime economics favor bulk hydraulic fluid procurement through direct fleet agreements rather than jobber networks.
Automotive commands the largest value pool; manufacturing shows the steepest formulation chemistry transition.
End User:
Technical sophistication and procurement authority split the buyer landscape.
- OEMs:Original equipment manufacturers specify fluids during design phase, locking in multi-year supply agreements. Their dual compliance burden—synchronizing EPA TSCA notifications with REACH registrations—favors partners with established regulatory navigation capabilities.
- Industrial Facilities:High-volume consumers in German chemical processing and French pharmaceutical manufacturing test next-generation low-GWP heat transfer fluids ahead of EU F-Gas Regulation phase-down deadlines.
- Repair Shops:Transactional purchasers prioritize immediate availability and brand recognition over technical specification depth.
- Maintenance Providers:Service contracting models shift risk to fluid suppliers through per-operating-hour pricing rather than per-liter delivery.
OEMs concentrate premium formulation demand; industrial facilities are expanding synthetic adoption most aggressively.
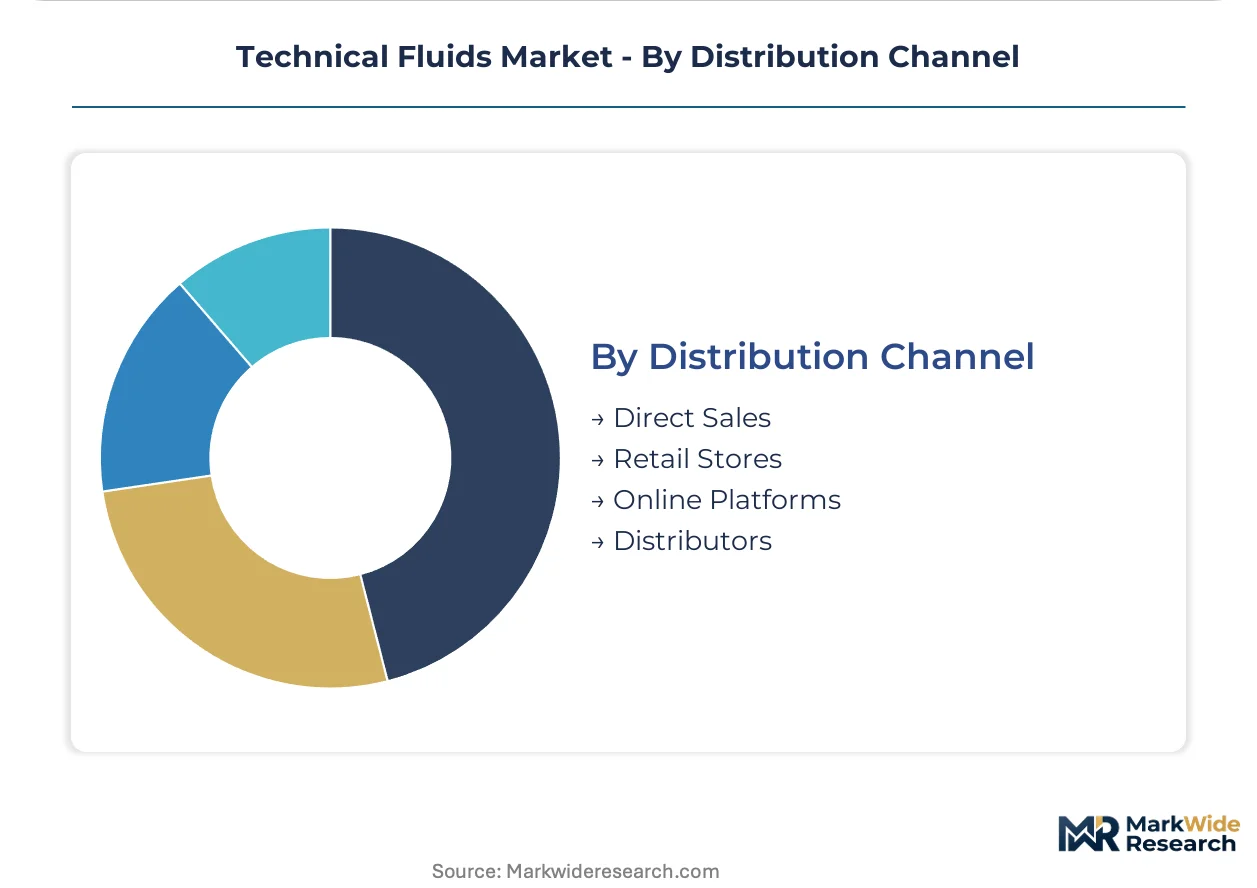
Distribution Channel:
Supply chain configuration determines margin capture and customer relationship depth.
- Direct Sales:Bulk supply agreements with automotive tier-one suppliers and semiconductor fabricators bypass traditional distribution entirely. Shell and ExxonMobil retain in-sump inventory ownership, charging per machined part in German and Japanese automotive component manufacturing.
- Distributors:Independent formulators rely on distributor networks where integrated majors control catalytic hydrocracking capacity and limit feedstock flexibility.
- Retail Stores:Consumer and light commercial vehicle maintenance products move through automotive aftermarket retailers.
- Online Platforms:Emerging channel for standardized grades where specification documentation satisfies procurement requirements without technical consultation.
Direct sales capture the highest-margin formulations; distributors remain essential for independent formulator market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's semiconductor fabrication clusters anchor technical fluids demand through precision thermal management requirements at advanced node foundries.
United States
Data center expansion in Northern Virginia and Phoenix pulls dielectric heat transfer fluids into liquid-immersion cooling pilots. EPA TSCA Section 5 premanufacture notices extend approval timelines for PFAS-free coolant chemistries. Texas petrochemical corridors concentrate catalytic hydrocracking capacity that supplies base stocks to independent formulators.
Germany
Industrial maintenance providers in the Ruhr region concentrate demand for extended-drain synthetic hydraulic fluids. REACH SVHC restrictions accelerate polyalkylene glycol substitution in Bavarian metalworking shops. BASF's Ludwigshafen complex anchors specialty additive package development for high-load manufacturing environments.
South Korea
Samsung and SK Hynix fabrication facilities drive dielectric coolant consumption for EUV lithography thermal control. MFDS chemical substance regulations align with REACH substance restrictions for cross-border formulation compliance. Pyeongtaek semiconductor clusters represent the densest concentration of low-conductivity fluid demand outside Taiwan.
Japan
Automotive tier-one suppliers in Aichi Prefecture adopt fluid-as-a-service contracting for metalworking operations. METI carbon neutrality roadmaps pressure manufacturers toward bio-based hydraulic fluid formulations. Yokohama and Nagoya industrial zones concentrate precision machining demand for polyalkylene glycol coolants.
China
CATL and BYD battery manufacturing expansion in Ningde and Shenzhen pulls low-conductivity dielectric fluids into EV thermal architecture. MEE environmental standards tighten discharge requirements for metalworking fluid waste. Yangtze River Delta chemical processors test fluorine-free alternatives ahead of anticipated PFAS restrictions.
Technical Fluids Market Vendor Landscape
Global majors compete with regional champions across formulation chemistry and base stock supply. Integrated petroleum majors control catalytic hydrocracking capacity and backward integration into base oil production. Specialty chemical houses differentiate through additive package development and regulatory navigation services. Independent formulators rely on distributor networks where feedstock flexibility remains constrained. Competitive moves concentrate on portfolio diversification toward fluorine-free formulations and direct-to-fleet supply contracting.
Within the integrated petroleum tier, ExxonMobil Corporation and Shell plc exemplify scale-driven positions anchored by captive base oil supply chains. BASF SE occupies a specialty chemical archetype focused on additive synergies that extend fluid change intervals. FUCHS SE represents the independent formulator model dependent on external feedstock sourcing. These three company structures illustrate how technical fluids competition stratifies across upstream control, midstream formulation, and downstream service integration.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Arkema Group |
| TotalEnergies SE |
| Chevron Corporation |
| BASF SE |
| Eastman Chemical Company |
| FUCHS SE |
| CIMCOOL Industrial Products |
| Others |
Supply Flow & Price Mechanics
Integrated petroleum majors with captive catalytic hydrocracking capacity anchor supply-side discipline, translating base oil cost advantages into pricing power across synthetic hydraulic fluid tiers while independent formulators absorb feedstock volatility through distributor markups.
Pricing Analysis
Input-cost pass-through from Group II/III base oil movements governs formulation pricing, with integrated producers like ExxonMobil and Shell capturing margin expansion during feedstock spikes while independents compress distributor margins to maintain share. Price differentiation rests on additive package sophistication and REACH compliance certification, with German industrial maintenance providers least sensitive to per-liter premiums when total cost of ownership calculations justify extended-drain synthetics. Cost compression in mineral oil-based metalworking fluids is intensifying as polyalkylene glycol substitution accelerates under SVHC restrictions. Automotive tier-one suppliers exhibit highest price sensitivity, negotiating fluid-as-a-service contracts that shift inventory risk to suppliers.
Supply Chain Analysis
Dual-sourcing requirements from semiconductor fabricators in Taiwan and South Korea mandate qualified secondary suppliers for dielectric coolants, constraining single-source dependence despite concentrated EUV lithography fluid demand. Geographic supply concentration centers on Texas petrochemical corridors for catalytic hydrocracking base stocks, Germany's Ruhr region for specialty additive packages, and Singapore for Asia-Pacific blending and distribution. Raw material dependencies span Group II/III base oils from integrated refiners, polyalkylene glycol feedstocks from BASF and Dow, and zinc dialkyldithiophosphate anti-wear additives from specialty chemical houses. Regulatory restriction risk dominates as EPA TSCA Section 5 PFAS rules and EU F-Gas Regulation phase-downs simultaneously compress fluorinated chemistry availability. Distribution runs through direct bulk agreements for high-volume automotive and semiconductor accounts, with independent formulators reliant on distributor networks for market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical fluids function as a regulatory compounder where EPA TSCA Section 5 PFAS restrictions and EU F-Gas Regulation phase-downs simultaneously destroy legacy formulation value and create premium pricing power for compliant substitutes.
For Market Incumbents: Deploy backward integration into catalytic hydrocracking capacity to secure base oil supply advantage as independent formulators face feedstock rationing. Lock semiconductor fabricators in Taiwan and South Korea into multi-year dielectric coolant supply agreements before fluorine-free qualification cycles complete. Accelerate additive package R&D investment to capture extended-drain synthetic demand from German industrial maintenance providers. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for hydrofluoroether and hydrocarbon heat transfer fluid specialists to displace incumbent fluorinated portfolios in data center and pharmaceutical applications. Concentrate formulation development on low-GWP alternatives for Spanish and Portuguese concentrated solar installations. Pursue direct-to-fleet distribution partnerships with commercial vehicle operators bypassing traditional jobber networks. For Investors and Strategic Acquirers: Valuations sit cheapest among independent formulators with stranded fluorinated chemistry exposure and no regulatory navigation capabilities. Long-term viability favors additive package specialists with REACH registration infrastructure and semiconductor qualification track records. Watch EPA premanufacture notice approval velocity as the inflection signal for new chemistry commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Formulation Development | EPA TSCA Section 5 compliance unlocks semiconductor coolant qualification cycles in Taiwan and South Korea. |
| Backward Integration into Base Oil Production | Catalytic hydrocracking capacity secures feedstock cost advantage against distributor-dependent independents. |
| Fluid-as-a-Service Contracting | Per-operating-hour pricing shifts inventory risk to suppliers in German and Japanese automotive manufacturing. |
| Low-GWP Heat Transfer Fluid Qualification | EU F-Gas Regulation phase-down creates substitution demand from data center operators in Singapore and Netherlands. |
| Semiconductor Direct Supply Agreements | Multi-year contracts with Samsung and SK Hynix lock in dielectric coolant volume at advanced node production. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with plant engineers at German chemical processors, procurement leads at Taiwanese semiconductor fabricators, technical R&D directors at additive suppliers, and maintenance directors at Japanese automotive tier-ones with secondary validation from EPA TSCA filings, ECHA REACH registrations, customs trade data, and SEC 10-K disclosures from integrated petroleum majors.
Input-output matrices map base oil production through formulation blending to end-use consumption across hydraulic fluids, coolants, lubricants, and heat transfer fluids, with segmentation dimensions spanning fluid type, application, end-user sophistication, and distribution channel. CAGRs derive from elasticity-adjusted demand projections and capacity expansion announcements across the analysis window, incorporating semiconductor fabrication buildout schedules, EV battery thermal architecture adoption curves, and EU F-Gas Regulation phase-down timelines as industry-specific forecast inputs.
Revisions become necessary when EPA premanufacture notice approval timelines extend materially, REACH SVHC restrictions accelerate beyond announced schedules, or semiconductor capital expenditure cycles deviate from foundry roadmaps. Deviation in fluorine-free formulation qualification velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Industrial Gear Oil Market
Lubricants
North America and Europe Forestry Lubricants Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
Anti-Static Oil Market
Lubricants
Global Finished Lubricant Market
Lubricants
United States Automotive Lubricants Market
Lubricants
Sri Lanka Lubricants Market
Lubricants
US Lubricants Market
Lubricants
Qatar Automotive Lubricants Market
Lubricants
North America Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Colombia Lubricants Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Global Process Oil Market