
 Colombia Lubricants Market | 2026-2036
Colombia Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Lubricants Market Outlook
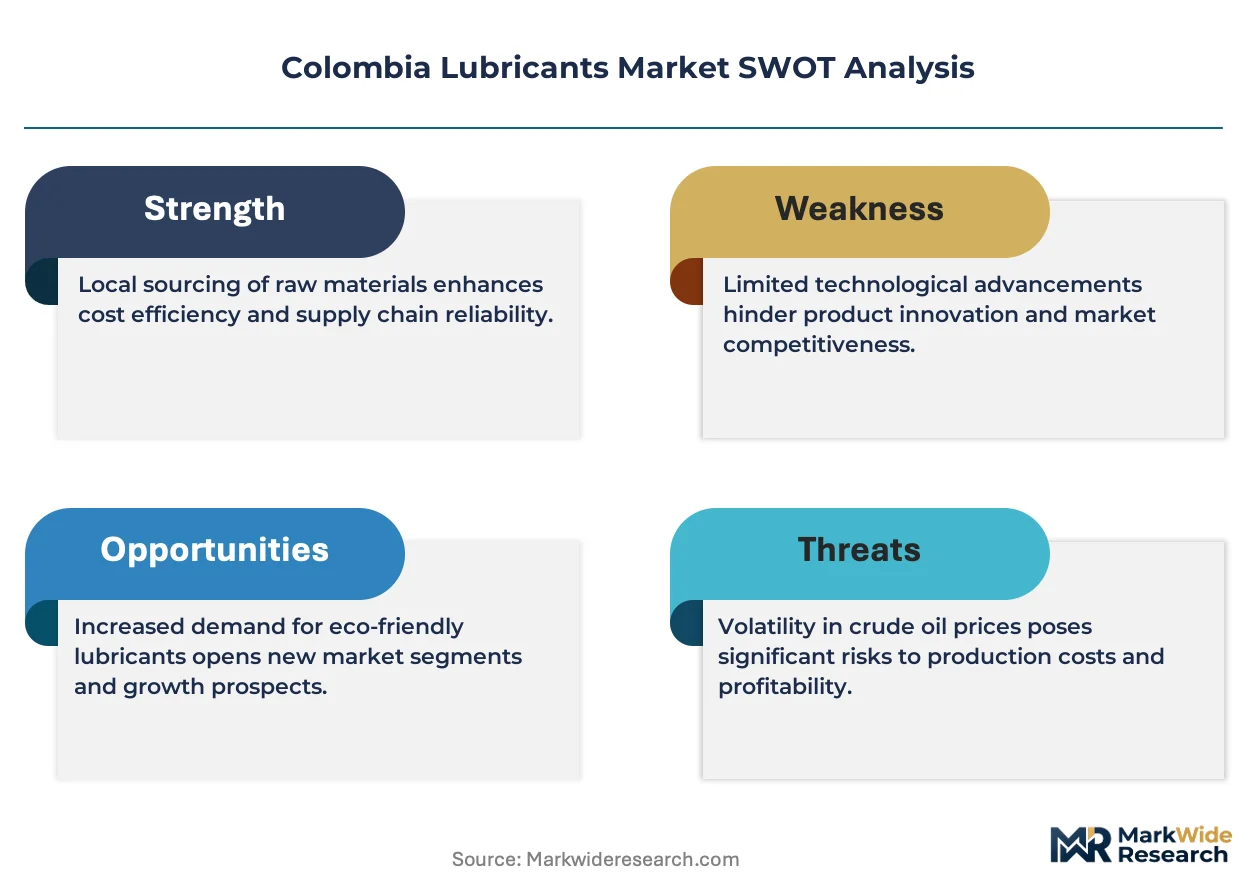
API SP and ILSAC GF-6 certification timelines for passenger car motor oils is collapsing the window for local blenders without testing partnerships. Exxon Mobil Corporation (Terpel) leverages its integrated fuel-lubricant retail network across Colombian service stations. Chevron Corporation anchors its position through specialized mining and construction lubricant formulations. Shell plc competes via direct technical service contracts with large fleet operators in the heavy-duty segment.
Lubricants are formulated mixtures of base oils and performance additives designed to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with viscosity grades such as SAE 5W-30 and 15W-40 governing cold-start flow and high-temperature film strength. Engine Oil dominates volume throughput due to Colombia's large circulating fleet of gasoline and diesel vehicles requiring routine drain intervals. Industrial Lubricants command premium positioning as manufacturing and energy operators shift toward longer-life synthetics to minimize unplanned downtime. Hydraulic Oil sustains steady pull from construction and mining equipment deployed across Colombia's extractive zones.
Colombia's Ministry of Mines and Energy enforces fuel and lubricant quality resolutions that govern base oil imports and finished product labeling, while the Superintendency of Industry and Commerce monitors anticompetitive distribution practices affecting wholesale channel access. The National Institute of Metrology sets testing protocols for viscosity and oxidation stability that determine which imported formulations qualify for commercialization. Stakeholders must track how forthcoming environmental standards on biodegradability and used-oil collection mandates reshape product development priorities and reverse logistics investments.
Market Dynamics
The Colombia Lubricants Market faces a structural compression between tightening base oil import specifications from the Ministry of Mines and Energy and fleet operators demanding extended drain intervals through synthetic formulations. This regulatory-technical squeeze rewards blenders with testing partnerships while marginalizing smaller formulators lacking laboratory infrastructure.
Growth Catalysts
- Antioquia Mining Fleet Expansion:Large-scale coal and gold operators in the Antioquia and Boyacá regions are extending equipment service intervals through synthetic lubricant procurement, creating sustained demand for high-performance industrial formulations.
- API SP Certification Windows:The collapsing timeline for passenger car motor oil certification is forcing local blenders to secure testing partnerships, accelerating consolidation among technically capable formulators.
- Bogotá-Andean Transport Density:Commercial vehicle concentration along the primary freight corridor sustains routine engine oil consumption through established drain-interval maintenance patterns.
Market Restraints
- Base Oil Import Concentration:Colombia's reliance on imported Group II and III base stocks exposes blenders to freight cost volatility and currency fluctuation risks from North American and Asian suppliers.
- Synthetic Formulation Cost Premium:Polyalphaolefin and ester base stocks command 40-60% cost premiums over mineral oils, limiting penetration among price-sensitive independent transport operators.
- Used Oil Collection Infrastructure Gaps:Reverse logistics for waste lubricant recovery remains underdeveloped outside major urban centers, constraining compliance with forthcoming environmental mandates.
Strategic Opportunities
- Pacific Coast Port Industrialization:Buenaventura's expanding logistics and maritime maintenance clusters present untapped demand for marine and industrial lubricant technical services.
- Biodegradable Hydraulic Fluids Mandate:Anticipated environmental standards for mining and construction equipment create first-mover advantage for formulators with vegetable-oil-based hydraulic oil portfolios.
- Direct Fleet Technical Contracts:Bypassing traditional distributor networks through on-site oil analysis and condition monitoring services captures margin from large mining and cement operators.
Industry Challenges
- Lubricant Formulation Chemist Scarcity:Local universities produce limited graduates with specialized training in additive chemistry and tribology, forcing blenders to recruit from Venezuela or import technical talent.
- ILSAC GF-6 Testing Bottlenecks:Single-digit accredited laboratories in Latin America extend certification timelines for passenger car motor oils, delaying product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Lubricants Market |
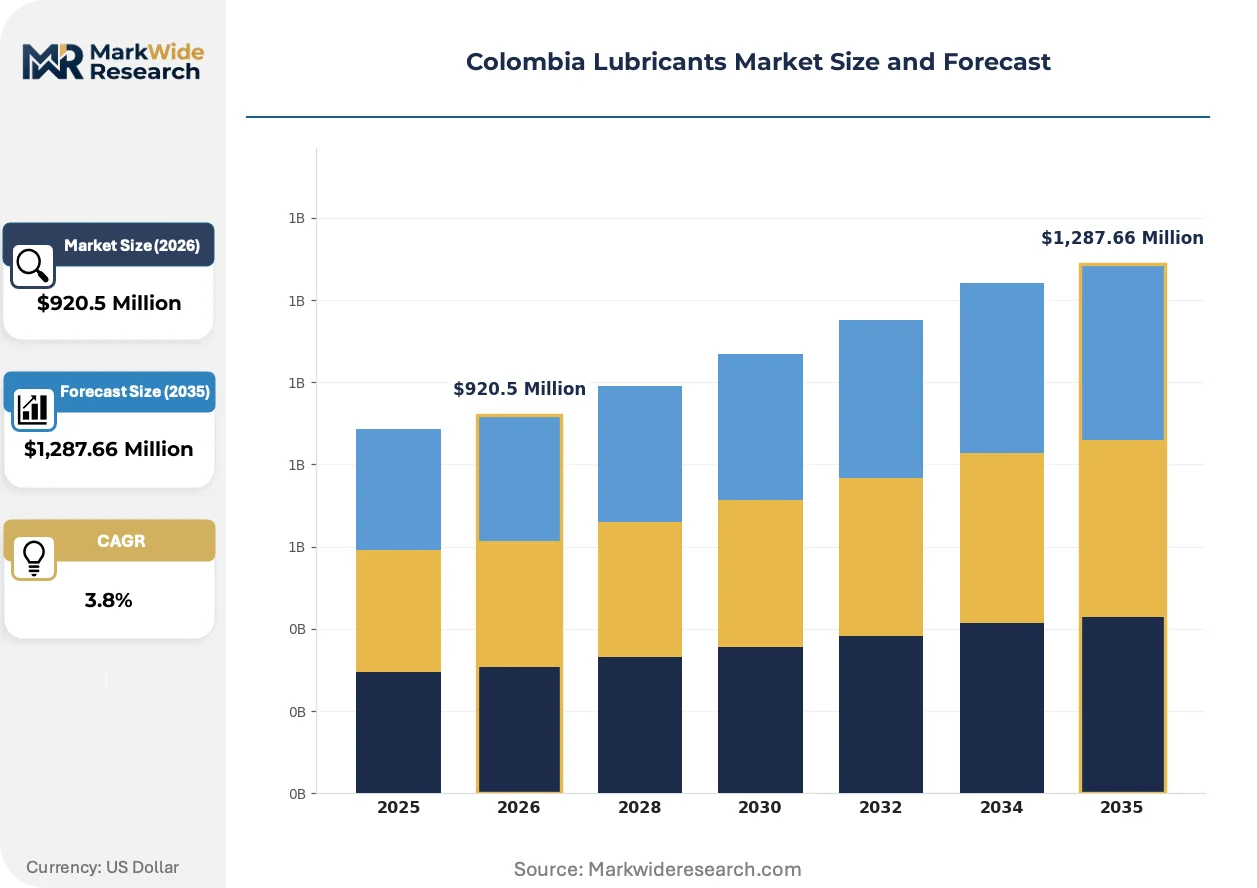
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,287.66 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Oil, Industrial Lubricants End User: Automotive, Manufacturing, Construction, Marine Distribution Channel: Retail, Wholesale, Online, Direct Sales Application: Automobiles, Heavy Machinery, Compressors, Pumps |
| Companies Covered | Petrobras, BP plc, Exxon Mobil Corporation (Terpel), Motul, Primax Colombia S.A., Chevron Corporation, TotalEnergies, Valvoline Inc., Shell plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Lubricants Market Strategic Shifts
Synthetic base oil technology is fragmenting the Colombia market into performance tiers, while regulatory quality protocols and fleet procurement centralization reshape competitive access. These intersecting forces favor capital-intensive players with integrated testing and distribution infrastructure.
Group III+ and polyalphaolefin synthetic base stocks are bifurcating the lubricant market into mineral-dominant economy segments and synthetic-premium performance tiers. Mining fleet operators in Boyacá and Antioquia are adopting 10,000-hour drain interval synthetics at accelerating rates. This technology divide is compressing margins for mid-tier blenders caught between price competition and inadequate technical positioning.
Colombia's Ministry of Mines and Energy Resolution on fuel and lubricant quality protocols tightened base oil import specifications and finished product labeling requirements. The regulation mandates viscosity and oxidation stability testing through National Institute of Metrology protocols, disqualifying lower-grade imports. Passenger car motor oil blenders without API SP certification partnerships face market exit as retail channels enforce compliance.
Fleet operators are consolidating lubricant procurement through central technical purchasing departments, displacing decentralized site-level buying. Large mining and cement groups now mandate direct supplier relationships with condition monitoring and oil analysis bundled into supply contracts. This concentration is most visible in the Bogotá-Andean corridor where transport and industrial machinery density supports dedicated technical service teams.
Colombia Lubricants Market Segmentation
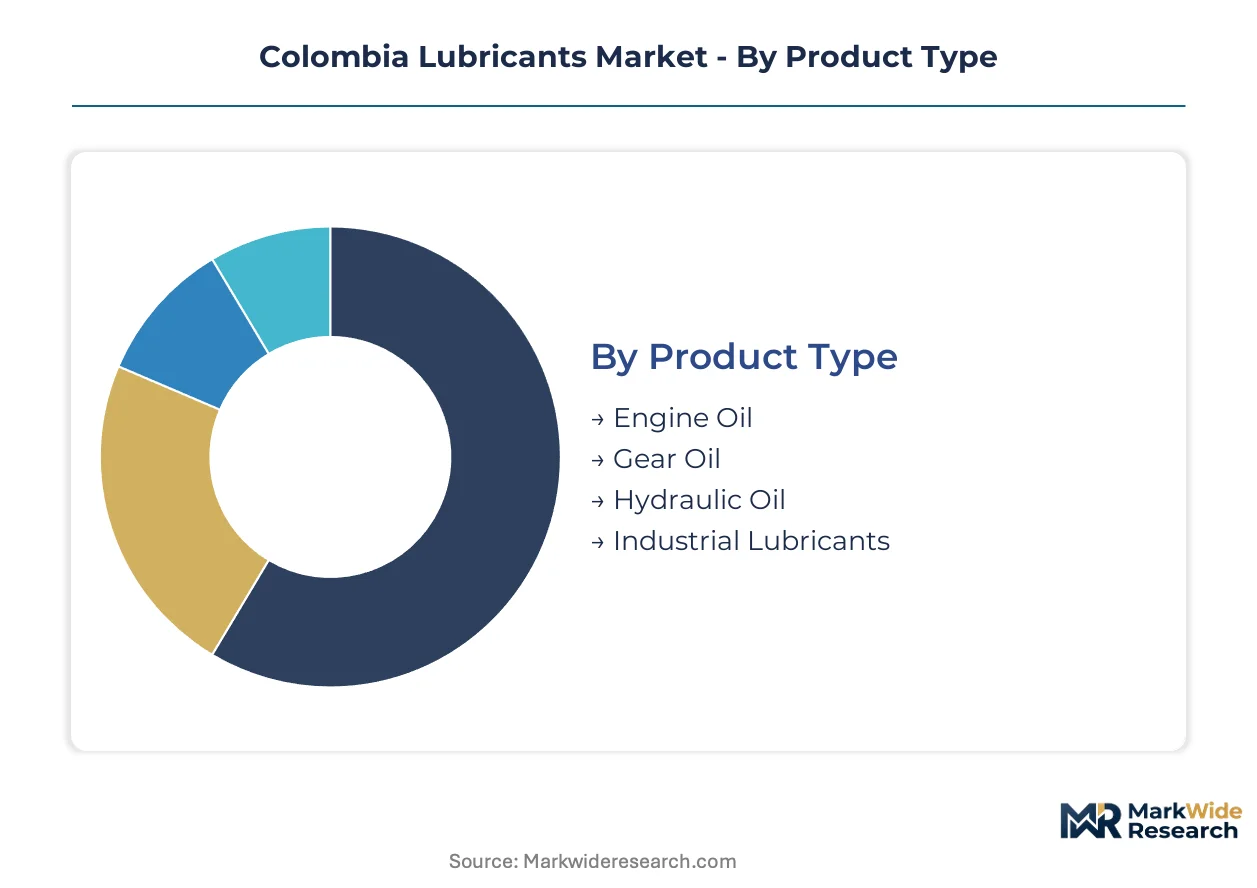
Segmentation in Colombia's lubricants market reveals how regulatory pressure from the Ministry of Mines and Energy and fleet procurement centralization concentrate value across specific product tiers and channel configurations. Understanding these divides exposes where technical capability separates winners from marginal players.
Product Type:
Ministry of Mines and Energy quality protocols enforce viscosity and oxidation stability testing that segments products by base oil grade and additive sophistication, creating divergent compliance burdens across mineral and synthetic formulations.
- Engine Oil:Formulated from Group II, III, or III+ base stocks with detergent and dispersant additive packages meeting API SP or ILSAC GF-6 specifications. Bogotá-Andean corridor commercial transport fleets sustain volume through 5,000-10,000 kilometer drain intervals, though synthetic penetration remains cost-constrained among independent operators.
- Industrial Lubricants:Synthetic and semi-synthetic formulations designed for extended service life in manufacturing and energy applications. Antioquia and Boyacá mining operators are centralizing procurement of 10,000-hour drain interval synthetics to minimize unplanned equipment downtime, compressing margins for mineral-dominant blenders.
- Hydraulic Oil:Anti-wear formulations with zinc-based or ashless additive chemistry for construction and mining equipment.
- Gear Oil:Extreme-pressure lubricants for transmission and differential applications in commercial vehicles and heavy machinery.
Established volume favors Engine Oil; emerging adoption favors Industrial Lubricants.
End User:
Cost tier differentiation separates price-sensitive owner-operators from capital-intensive mining and cement groups willing to pay premiums for condition-monitoring bundled contracts.
- Automotive:Passenger car and commercial vehicle fleets requiring routine drain interval maintenance. Bogotá's dense urban fleet sustains consistent demand for SAE 5W-30 and 15W-40 grades, though API SP certification timelines are forcing consolidation among local blenders without testing partnerships.
- Manufacturing:Food processing, textiles, and metalworking operations demanding longer-life synthetics to reduce production line interruptions. Pacific Coast industrialization around Buenaventura is creating incremental pull for technical service capabilities.
- Construction:Equipment operators in extractive zones requiring hydraulic and engine oils under severe load conditions.
- Marine:Port maintenance and coastal vessel operators with specialized lubricant needs.
Volume concentration sits with Automotive; margin expansion sits with Manufacturing.
Distribution Channel:
Customer type fragmentation—decentralized retail buyers versus centralized fleet procurement departments—determines channel profitability and technical service requirements.
- Retail:Service stations and auto parts stores serving individual vehicle owners and small fleet operators. Exxon Mobil's Terpel network leverages integrated fuel-lubricant positioning across Colombian service stations.
- Direct Sales:Technical service contracts with condition monitoring and oil analysis bundled into supply agreements. Large mining and cement groups in Antioquia and Boyacá now mandate direct supplier relationships, displacing traditional distributor networks.
- Wholesale:Bulk supply to independent distributors and regional blenders serving secondary markets.
- Online:Emerging e-commerce platforms for standardized product procurement.
Channel power is concentrating in Direct Sales; Retail maintains volume throughput.
Application:
Geography of machinery deployment—Andean corridor density versus dispersed extractive zones—shapes logistics costs and technical service coverage requirements.
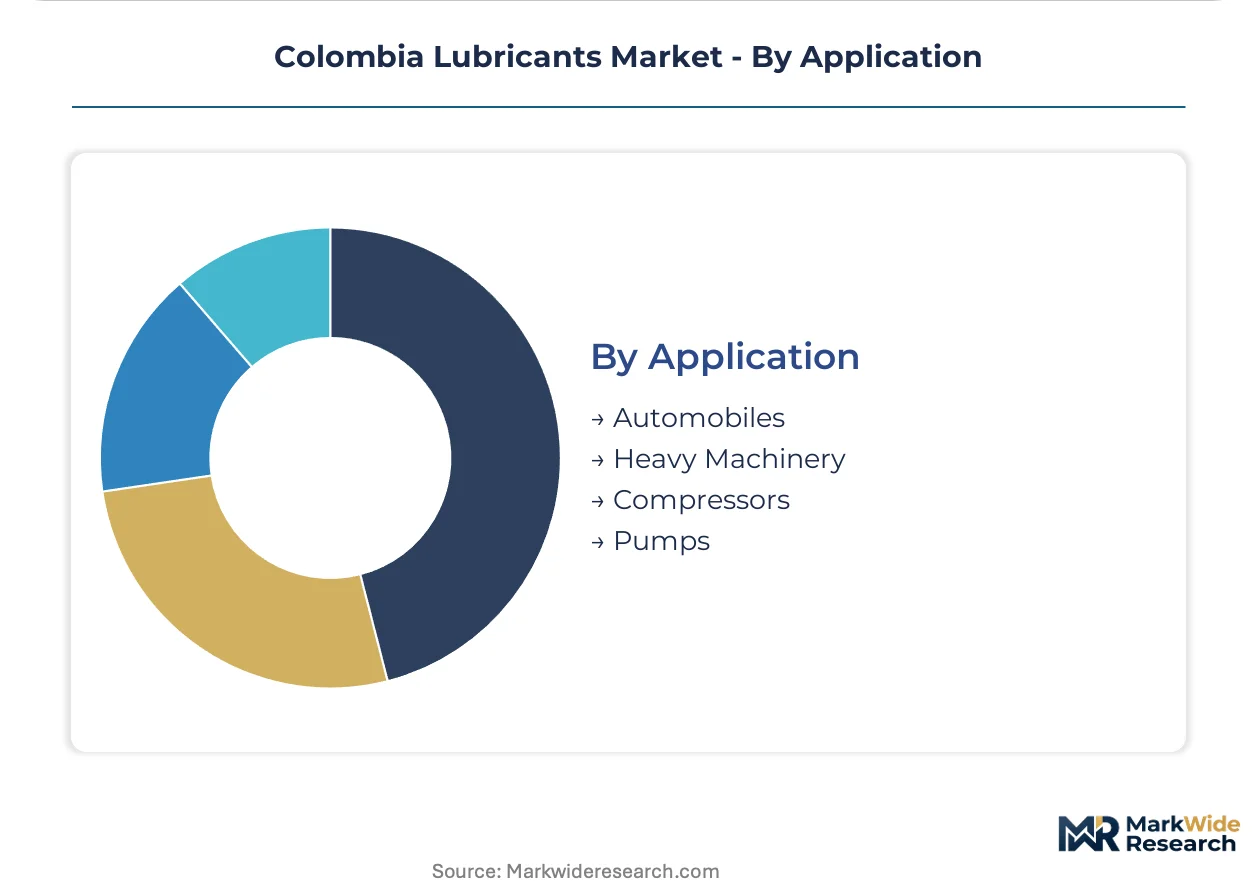
- Heavy Machinery:Mining excavators, haul trucks, and construction equipment operating in Antioquia and Boyacá extractive zones. Fleet operators are adopting synthetic formulations with extended drain intervals, creating demand for on-site oil analysis capabilities.
- Automobiles:Passenger cars and light commercial vehicles concentrated in Bogotá and Andean urban centers. Routine maintenance patterns sustain consistent engine oil consumption through established service networks.
- Compressors:Industrial air and gas compression equipment in manufacturing facilities.
- Pumps:Fluid handling equipment across mining, construction, and industrial applications.
Application demand is broadening in Heavy Machinery; Automobiles anchor current volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in Colombia's lubricants market clusters around three distinct profiles: mining fleet operators in extractive zones, commercial transport fleets along the Andean corridor, and industrial manufacturers in Pacific Coast logistics hubs. These archetypes drive divergent demand patterns across the country's sub-regions.
Bogotá-Andean Corridor
Commercial transport density along the Bogotá-Cali-Medellín axis sustains routine engine oil consumption through established service networks. Colombia's Ministry of Mines and Energy enforces fuel and lubricant quality resolutions governing base oil imports and finished product labeling. Fleet operators in this corridor centralize procurement through technical purchasing departments, displacing decentralized site-level buying patterns.
Antioquia Mining Belt
Large-scale coal and gold operators in Antioquia extend equipment service intervals through synthetic lubricant procurement, creating sustained demand for high-performance industrial formulations. The National Institute of Metrology sets testing protocols for viscosity and oxidation stability that determine which imported formulations qualify for commercialization. Mining clusters around Medellín and the northeastern extractive zones adopt 10,000-hour drain interval synthetics at accelerating rates.
Boyacá Extractive Zone
Heavy machinery deployment in Boyacá's mining corridors pulls hydraulic and gear oil demand under severe load conditions. Colombia's Ministry of Mines and Energy updated fuel and lubricant quality protocols, tightening base oil import specifications. Fleet operators in this sub-region mandate direct supplier relationships with condition monitoring and oil analysis bundled into supply contracts.
Pacific Coast Logistics Cluster
Buenaventura's expanding logistics and maritime maintenance clusters present untapped demand for marine and industrial lubricant technical services. Anticipated environmental standards for biodegradability reshape product development priorities for formulators targeting this corridor. Port industrialization around Colombia's primary Pacific gateway creates incremental pull for technical service capabilities beyond traditional Andean markets.
Colombia Lubricants Market Competitive Environment
Player mix skews toward integrated petroleum majors with fuel-lubricant retail networks and specialized industrial formulators with mining sector relationships. The market structure concentrates around capital-intensive blenders with laboratory infrastructure and testing partnerships. Three strategic archetypes dominate: petroleum majors leveraging retail distribution, industrial specialists bundling technical services, and regional blenders serving price-sensitive segments. Competitive moves center on securing API SP certification partnerships and establishing direct fleet technical contracts with condition monitoring capabilities.
Among petroleum majors with integrated Colombian operations, Exxon Mobil Corporation (Terpel), Chevron Corporation, and Shell plc exemplify distinct positioning vectors. Exxon Mobil's Terpel unit leverages fuel-lubricant retail integration across Colombian service stations. Chevron anchors its presence through specialized mining and construction lubricant formulations. Shell competes via direct technical service contracts with large fleet operators in heavy-duty segments. These three represent how multinational petroleum companies occupy differentiated competitive positions without overlapping core strategies.
| Leading Market Players |
|---|
| Petrobras |
| BP plc |
| Exxon Mobil Corporation (Terpel) |
| Motul |
| Primax Colombia S.A. |
| Chevron Corporation |
| TotalEnergies |
| Valvoline Inc. |
| Shell plc |
| Others |
Value Chain & Pricing Dynamics
Group III+ synthetic base oil substitution for mineral stocks simultaneously shifts procurement geography toward North American and Asian suppliers while compressing margin structures for Colombian blenders caught between freight cost volatility and fleet demands for extended drain intervals.
Pricing Analysis
Cost-plus contracts indexed to Singapore Group II and III base oil spot markets dominate procurement between importers and large mining fleet operators. Pricing stratifies across premium synthetic, standard semi-synthetic, and economy mineral tiers, with API SP certification grade and bundled condition monitoring services as primary differentiation drivers. Cost compression in the mineral tier is intensifying because independent transport operators resist 40-60% synthetic premiums. Owner-operators in Bogotá's peripheral zones exhibit highest price sensitivity; Antioquia mining groups with centralized technical purchasing show least.
Supply Chain Analysis
The United States and South Korea anchor Group II and III base oil production for Colombian import dependency, with Singapore serving as the regional pricing benchmark hub. Colombian blenders draw from polyalphaolefin, ester, and vegetable oil feedstocks alongside mineral base stocks. Single-source vulnerability concentrates in the Buenaventura port corridor where customs clearance bottlenecks delay inventory turns. Distribution runs through Terpel's integrated fuel-lubricant retail network, direct technical service contracts with mining operators, and wholesale channels to independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's lubricants market fragments across performance tiers and procurement centralization patterns, with fleet operator consolidation creating defendable niches for technically capable formulators.
For Market Incumbents: Secure API SP certification partnerships before retail channels enforce compliance deadlines, eliminating non-certified blenders. Deepen backward integration into base oil storage infrastructure at Buenaventura to buffer freight cost volatility from North American suppliers. Lock in direct technical service contracts with Boyacá mining groups before competitors establish condition monitoring relationships.
For New Entrants and Emerging Players: Lead with biodegradable hydraulic fluid formulations targeting anticipated Ministry of Mines and Energy environmental mandates for mining equipment. The Pacific Coast logistics cluster around Buenaventura offers lowest competitive density for marine and industrial lubricant technical services. Pursue on-site oil analysis capabilities as the go-to-market wedge against established distributor relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors blenders with laboratory infrastructure and testing partnerships over capital-light formulators. Long-term viability hinges on regulatory compliance capability and mining sector relationships rather than retail channel presence. Watch for Ministry of Mines and Energy announcements on used oil collection mandates as the inflection signal for reverse logistics investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Storage | Captive inventory at Buenaventura insulates blenders from Singapore spot price volatility and customs delays. |
| API SP Certification Partnership | Testing access through accredited Latin American laboratories collapses product launch timelines for passenger car motor oils. |
| Direct Fleet Technical Contract | Condition monitoring bundled supply agreements with Antioquia mining operators displace traditional distributor margins. |
| Biodegradable Hydraulic Fluid Portfolio | Vegetable-oil-based formulations position first-movers for forthcoming Ministry of Mines and Energy environmental standards. |
| Used Oil Collection Infrastructure Buildout | Reverse logistics capabilities outside Bogotá prepare compliance with anticipated federal waste lubricant recovery mandates. |
Study Parameters
Operator-level perspectives from maintenance directors at Antioquia mining fleets, procurement leads at cement operators, aftermarket service heads at commercial vehicle distributors, and technical R&D directors at base oil importers anchored the qualitative base. Secondary validation drew from Ministry of Mines and Energy resolutions, National Institute of Metrology testing protocols, customs import records, and SEC filings of multinational petroleum majors. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down base oil import flow analysis.
Sensitivity analysis around synthetic penetration rates, mining fleet expansion scenarios, and regulatory compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user industry, distribution channel configuration, and regional machinery deployment density. CAGRs derived from regression analysis against historical base oil import volumes and fleet operator procurement surveys. Forecast inputs incorporated API SP certification adoption curves and biodegradable fluid mandate probability assessments.
The analysis sits within stated boundaries; outcomes outside sustained mining investment in Boyacá and Antioquia, stable base oil import access, and incremental regulatory tightening would require recalibration. Forecasts reflect documented assumptions on fleet centralization velocity and synthetic cost premium erosion. Recalibration cycles align with material shifts in Ministry of Mines and Energy resolution timing and Pacific Coast port industrialization momentum.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
India Industrial Lubricants Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
India Lubricants Market
Lubricants
Global Fire Resistant Hydraulic Fluid Market
Lubricants
Europe Lubricants Market
Lubricants
Mexico Lubricants Market
Lubricants
Synthetic Ester Lubricants Market
Lubricants
Lubricants for Cement Industry Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
United States Automotive Lubricants Market
Lubricants
Poland Metalworking Fluids Market
Lubricants
Lubricated Tracks Market
Lubricants
Qatar Lubricants Market
Lubricants
Sri Lanka Lubricants Market
Lubricants
Fire Resistant Fluids Market