
 Cold Flow Improvers Market | 2026-2036
Cold Flow Improvers Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Flow Improvers Market Analysis
Specialist polymer chemists with wax crystal modification expertise is redrawing competitive boundaries in cold flow improvers, as fewer universities train formulators in fuel-specific rheology. BASF SE leverages its Ludwigshafen integrated sites to sustain captive supply of polyalkyl methacrylate backbones. The Lubrizol Corporation anchors North American demand through direct technical service relationships with major refiners. Evonik Industries AG competes via high-purity ester chemistry developed for arctic-grade diesel applications.
Cold flow improvers comprise polymeric additives—typically polyalkyl methacrylates, ethylene-vinyl acetate copolymers, or polyolefin esters—that modify wax crystal morphology in middle distillate fuels, depressing pour point and cold filter plugging point by 10–30°C below base fuel properties. The esters product category dominates volume given compatibility across paraffinic feedstocks, while olefins represent the fastest-growing segment as bio-based feedstock integration expands. Fuel additives applications command the largest value pool due to treat-rate sensitivity and seasonal procurement urgency, whereas pipeline transport applications concentrate margin in specialized winter-blend logistics contracts.
EPA fuel sulfur and operability standards in the United States, REACH chemical registration requirements in Europe, and China's GB 19147 diesel quality standards collectively mandate cold flow performance verification before market release. These frameworks elevate testing costs but lock in incumbent suppliers with established homologation records. Stakeholders must monitor biofuel blending mandate expansions, as fatty acid methyl ester compatibility with conventional cold flow polymers remains unresolved across multiple regulatory jurisdictions.
Market Dynamics
Polymer ester chemistry is decomposing traditional treat-rate economics as refiners pursue sub-500 ppm dosage thresholds for winter diesel operability. This molecular-level efficiency drive is compressing additive volumes per barrel while demanding higher-purity backbones from integrated chemical complexes.
Growth Catalysts
- EPA winter fuel operability mandates:United States refiners must certify cold filter plugging point performance, creating seasonal procurement cycles that lock in additive volumes regardless of crude price volatility.
- Pipeline infrastructure expansion:Midstream operators in Canada and Russia now require continuous-flow additives to prevent gel formation in above-ground storage and long-haul transit systems.
- Polyalkyl methacrylate backbone advances:Controlled radical polymerization yields narrower molecular weight distributions, improving wax crystal nucleation efficiency across paraffinic feedstocks.
Market Restraints
- Specialty monomer supply concentration:C12-C18 methacrylate ester precursors depend on Southeast Asian oleochemical complexes, exposing formulators to palm kernel oil price swings and shipping bottlenecks.
- FAME incompatibility limitations:Fatty acid methyl ester blends above B7 disrupt conventional polymer crystal modification, forcing dual-additive strategies that erode treat-rate advantages.
- REACH registration cost barriers:ECHA data requirements for new polymeric substances exceed €300,000 per substance, freezing small-formulator innovation pipelines in Europe.
Strategic Opportunities
- Arctic marine diesel applications:Russian and Norwegian shipping corridors above 70°N latitude require pour point depression below -40°C, a specification few incumbent suppliers satisfy.
- Bio-based ester feedstocks:Tall oil fatty acid derivatives from Scandinavian pulp mills offer renewable carbon content for EU Green Deal-aligned procurement tenders.
- Direct-to-refiner technical service models:Bypassing traditional distributor networks allows real-time dosage optimization at blending terminals, capturing margin from emergency winter specification failures.
Industry Challenges
- Wax crystal rheology modeling expertise:Universities have shuttered fuel-specific polymer physics programs, forcing additive houses to train formulators in-house over multi-year apprenticeships.
- Homologation timeline compression:GB 19147 revisions in China now require 18-month field trials across three climate zones before additive approval, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Flow Improvers Market |
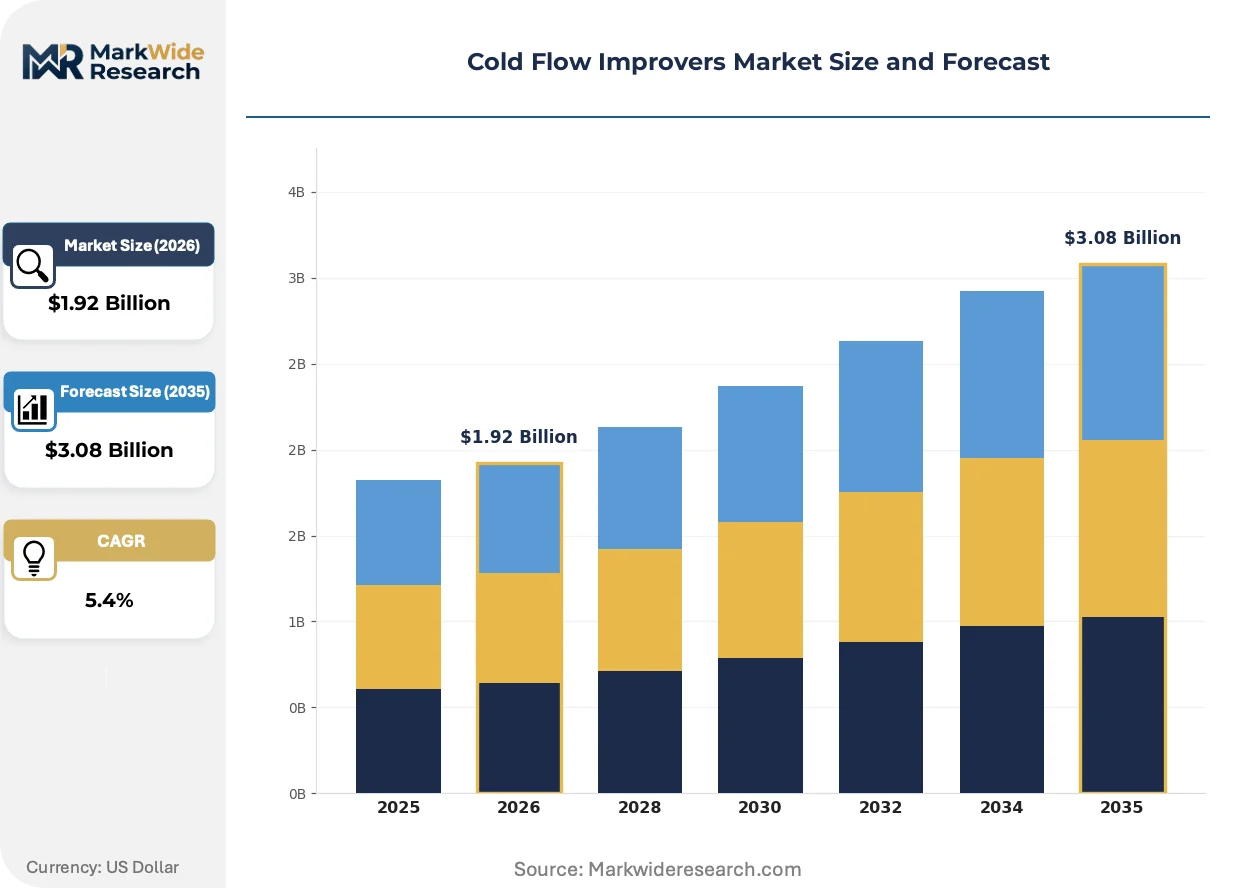
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.08 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Esters, Diesters, Alcohols, Olefins Application: Fuel Additives, Oil Refining, Pipeline Transport, Lubricants End User: Fuel Producers, Oil Companies, Transportation Sector, Industrial Users Distribution Channel: Direct Sales, Online Retail, Distributors, Retailers |
| Companies Covered | BASF SE, The Lubrizol Corporation, Afton Chemical, Evonik Industries AG, Clariant AG, Infineum International Limited, Chevron Corporation, Innospec Inc., Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Flow Improvers Market Emerging Trajectories
Formulation science is pivoting from universal additives to feedstock-specific architectures as paraffinic crude slates diversify and bio-blend ratios escalate. This specialization is fragmenting product portfolios while elevating technical service intensity.
Hyperbranched polyolefin ester architectures are decomposing the linear polymer paradigm that dominated cold flow chemistry for three decades. These dendritic structures nucleate wax crystals at lower concentrations than conventional polyalkyl methacrylates. Major European refiners piloting arctic-grade formulations have reduced treat rates by 40 percent in bench tests. The technology is compressing volume-based revenue models across established supplier tiers.
REACH authorization timelines for polymer additives are tightening as ECHA scrutinizes persistent, bioaccumulative, and toxic characteristics in long-chain acrylates. Registration dossiers now require sediment toxicity data that previous submissions omitted. Specialty additive houses in Germany and the Netherlands face reformulation costs to exclude C20+ alkyl chains from backbone structures.
Refiner procurement teams now specify performance-based contracts with penalty clauses for cold filter plugging point failures rather than purchasing additives by volume. This unbundles chemical supply from technical risk, transferring operability liability to additive suppliers. The shift is most pronounced in United States Midwest terminals where winter specification violations trigger EPA enforcement actions and downstream customer claims.
Cold Flow Improvers Market Segmentation
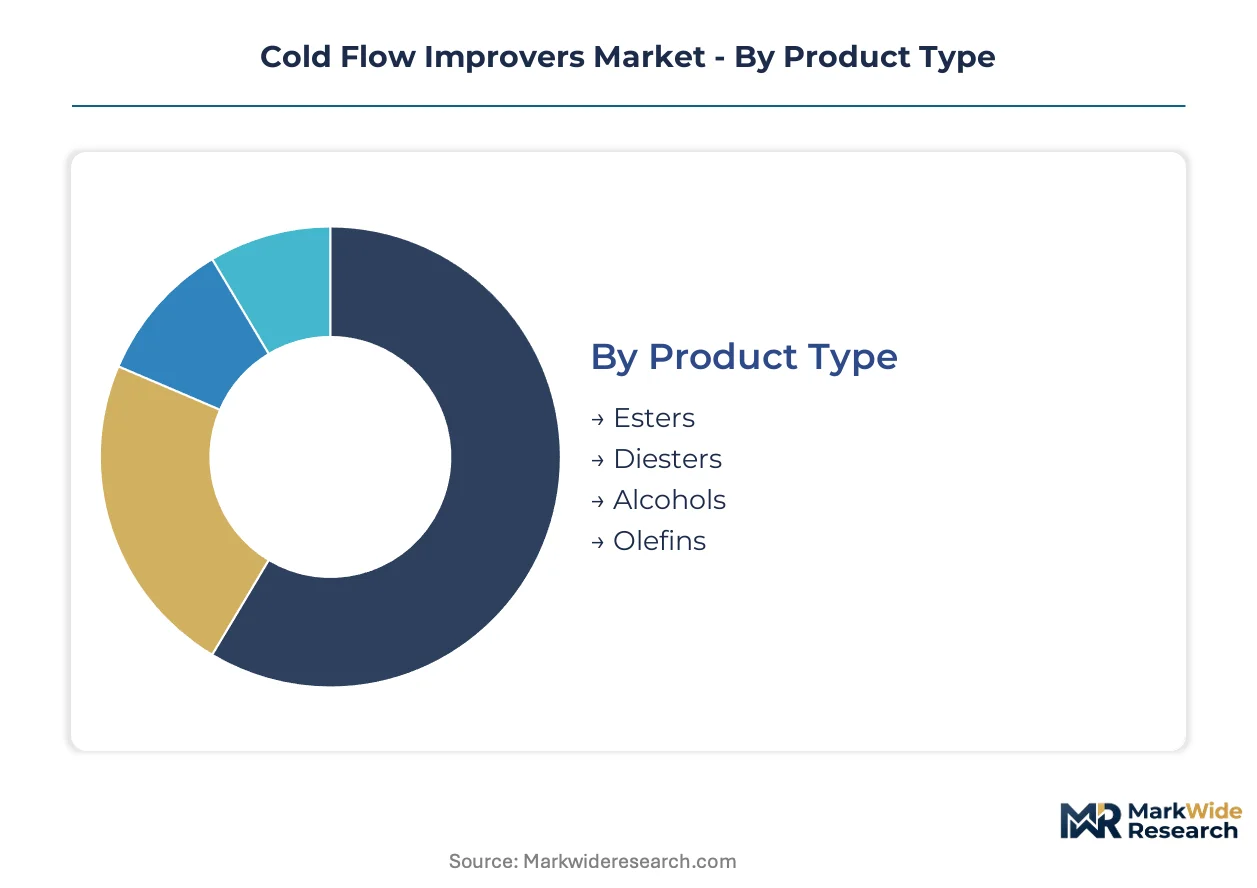
Cold flow improver formulations fragment across molecular architectures and delivery channels, with margin concentration shifting toward feedstock-specific designs and direct technical service relationships. Understanding these segment boundaries clarifies where formulation houses capture value versus where commoditization pressures dominate.
Product Type:
Polymer backbone chemistry determines treat-rate economics and winter specification compliance, concentrating margin in ester formulations while olefin architectures gain traction from bio-based feedstock mandates.
- Esters:Polyolefin esters and polymer esters modify wax crystal morphology through controlled nucleation, dominating volume across paraffinic diesel and heating oil applications. United States refiners specify ester-based cold flow improvers for EPA winter operability certification, with treat rates compressing below 500 ppm as molecular weight distribution narrows.
- Olefins:Ethylene-vinyl acetate copolymers and hyperbranched polyolefin structures represent the fastest-growing trajectory, with dendritic architectures reducing dosage requirements by 40 percent in arctic-grade bench tests. Scandinavian pulp mills supply tall oil fatty acid derivatives for EU Green Deal-aligned procurement, though FAME compatibility above B7 blends remains unresolved.
- Diesters:Dual-functionality molecules combine pour point depression with lubricity enhancement, finding niche deployment in marine diesel and industrial heating systems where multi-property additives reduce logistics complexity.
- Alcohols:Short-chain alcohol derivatives serve as co-solvents and crystal dispersants in legacy formulations, losing share to polymer architectures as refiners pursue lower treat-rate thresholds.
Esters hold installed capacity. Olefins are rotating up the share rankings.
Application:
Volume concentration clusters in fuel additives where seasonal procurement urgency and specification failure penalties elevate pricing power, while pipeline transport contracts concentrate margin in specialized winter-blend logistics.
- Fuel Additives:Diesel and heating oil formulations command the largest value pool, with United States Midwest terminals specifying performance-based contracts that transfer cold filter plugging point liability to additive suppliers. EPA enforcement actions for winter specification violations reinforce procurement rigidity regardless of crude price volatility.
- Pipeline Transport:Continuous-flow additive systems prevent gel formation in above-ground storage and long-haul transit, with Canadian and Russian midstream operators requiring specialized winter-blend logistics contracts that concentrate margin in technical service relationships.
- Oil Refining:Catalytic dewaxing unit additives and refinery process chemicals represent steady demand from integrated operators seeking operational flexibility across variable crude slates.
- Lubricants:Industrial gear oils and hydraulic fluids deploy cold flow modifiers for arctic operating conditions, though volumes remain constrained by extended drain intervals and synthetic base oil substitution.
Fuel additives anchor procurement volume. Pipeline transport is climbing the fastest.
End User:
Customer scale and technical sophistication fragment pricing power, with fuel producers capturing volume discounts while transportation sector buyers prioritize emergency response capabilities over unit cost.
- Fuel Producers:Integrated refiners and blenders in Germany, the United States, and China drive procurement cycles, with direct technical service relationships locking in incumbent suppliers through multi-year formulation development partnerships.
- Transportation Sector:Marine operators above 70°N latitude and arctic trucking fleets specify pour point depression below minus 40 degrees Celsius, a performance tier few suppliers satisfy.
- Oil Companies:Exploration and production divisions deploy cold flow improvers for waxy crude handling and flow assurance in subsea pipelines.
- Industrial Users:Heating oil distributors and mining operations purchase through distributor networks, with price sensitivity elevated and technical service intensity reduced.
Fuel producers concentrate procurement scale. Transportation sector is gaining share fastest.
Distribution Channel:
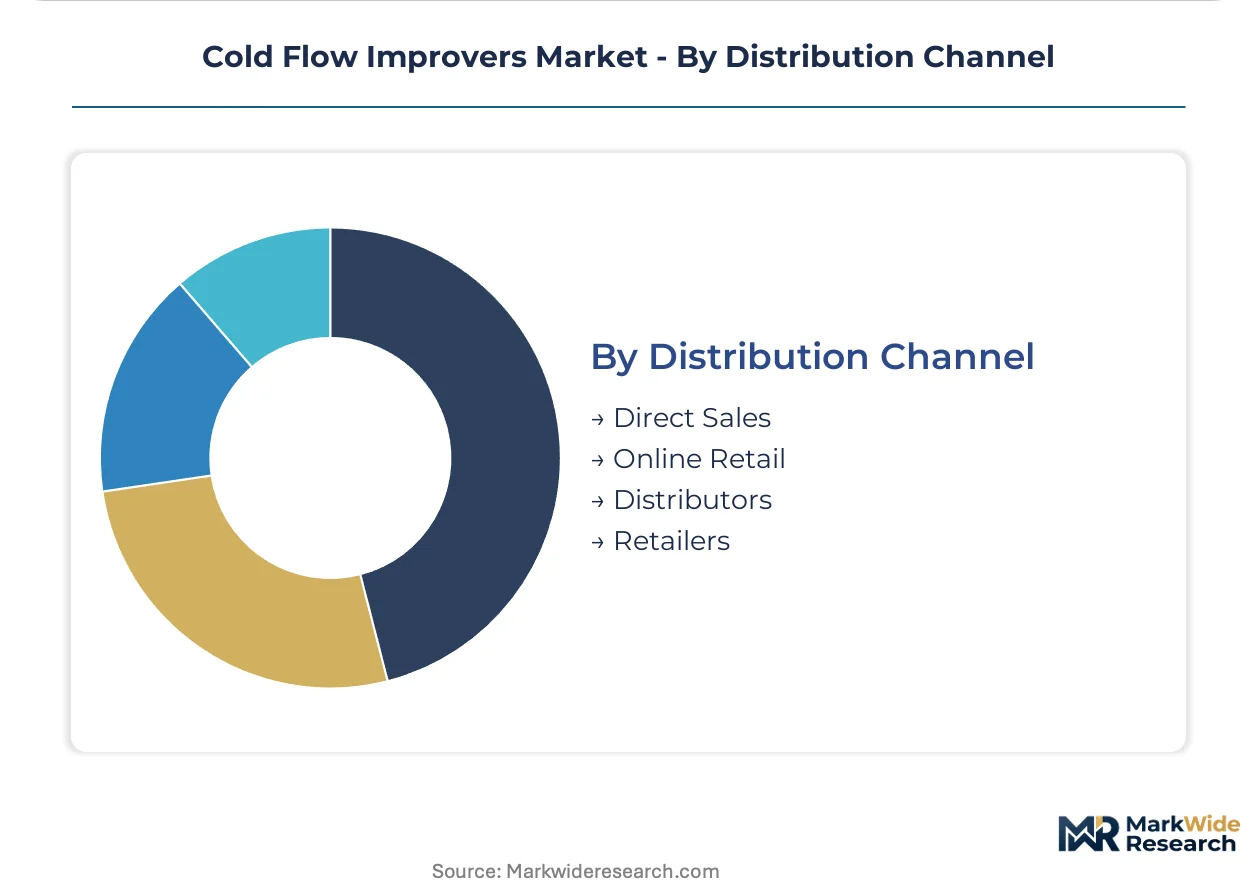
Channel selection reflects customer technical capability and urgency requirements, with direct sales capturing premium pricing for specification-critical applications while distributor networks serve price-sensitive volume segments.
- Direct Sales:Technical service teams embedded at blending terminals enable real-time dosage optimization and emergency winter specification failure response, capturing margin from penalty-clause contracts in the United States and Germany.
- Distributors:Regional chemical distributors serve industrial heating oil and secondary refinery accounts, with inventory carrying costs and technical support limitations compressing margins.
- Online Retail:E-procurement platforms penetrate small industrial users and aftermarket lubricant blenders, though cold flow improver complexity limits digital channel expansion.
- Retailers:Agricultural supply cooperatives and fleet maintenance depots represent fragmented, low-volume endpoints with minimal formulation customization.
Direct sales holds relationship density. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA winter fuel operability mandates anchor procurement cycles in the United States, while REACH chemical registration requirements in Europe and China's GB 19147 diesel quality standards collectively shape formulation requirements across major demand centers.
United States
Midwest refiners drive seasonal procurement urgency through performance-based contracts that transfer cold filter plugging point liability to additive suppliers. EPA enforcement actions for winter specification violations reinforce rigid procurement regardless of crude price swings. The Gulf Coast petrochemical corridor concentrates polyalkyl methacrylate backbone production for captive supply integration.
Germany
Ludwigshafen's integrated chemical complexes sustain high-purity ester chemistry for arctic-grade diesel applications across European refiners. ECHA data requirements for new polymeric substances exceed substantial registration costs, freezing small-formulator innovation pipelines. The Rhine-Ruhr industrial cluster anchors technical service relationships with major blenders through direct terminal embedding.
China
GB 19147 revisions now require extended field trials across multiple climate zones before additive approval, delaying product launches for international suppliers. State-owned refiners in Shandong and Jiangsu provinces concentrate procurement scale for winter diesel formulations. The Yangtze River Delta pipeline infrastructure creates consistent demand for continuous-flow additive systems.
Russia
Arctic marine diesel applications above 70 degrees north latitude require pour point depression below minus 40 degrees Celsius, a specification few incumbent suppliers satisfy. Transneft pipeline operators mandate specialized winter-blend logistics contracts for above-ground storage and long-haul transit systems. The Yamal-Nenets autonomous region concentrates procurement for extreme-climate flow assurance.
Canada
Midstream operators across Alberta and Saskatchewan require continuous-flow additives to prevent gel formation in above-ground storage and transcontinental pipeline systems. Cold temperature swings in the Prairie Provinces create extended seasonal procurement windows compared to United States markets. The Edmonton-Jasper corridor concentrates blending terminal capacity for western Canadian diesel distribution.
Cold Flow Improvers Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive supply of polymer backbones separating scale players from formulation houses dependent on merchant monomer markets. The competitive terrain fragments across three strategic archetypes: integrated petrochemical majors with backward control into methacrylate ester precursors, specialty additive houses competing through technical service intensity, and regional blenders serving price-sensitive industrial heating oil segments. Capacity expansion in Southeast Asian oleochemical complexes and strategic partnerships for bio-based ester feedstocks represent the dominant competitive moves reshaping supply security.
Among German-based integrated chemical majors, BASF SE and Evonik Industries AG exemplify the captive-supply archetype through Ludwigshafen production complexes. The Lubrizol Corporation anchors North American positioning through direct technical service relationships. These three entities occupy distinct competitive positions: integrated backbone production, regional technical service density, and high-purity ester specialization respectively.
| Leading Market Players |
|---|
| BASF SE |
| The Lubrizol Corporation |
| Afton Chemical |
| Evonik Industries AG |
| Clariant AG |
| Infineum International Limited |
| Chevron Corporation |
| Innospec Inc. |
| Baker Hughes |
| Others |
Supply Flow & Price Mechanics
Polyalkyl methacrylate backbone substitution for conventional ethylene-vinyl acetate copolymers is redrawing supply geography toward Ludwigshafen and Gulf Coast petrochemical corridors while compressing treat-rate economics and elevating purity premiums across winter diesel formulations.
Pricing Analysis
United States Midwest refiners pay 15-25 percent premiums over European counterparts for emergency specification failure response capabilities embedded in performance-based contracts. Three-tier pricing structure across arctic-grade, standard winter, and industrial heating oil levels stratifies by certification stringency and technical service intensity. Pricing pressure stems from FAME incompatibility above B7 blends forcing dual-additive strategies that erode dosage efficiency. Fuel producers exhibit lowest price sensitivity given penalty clause exposure, while industrial heating oil distributors negotiate aggressively on volume.
Supply Chain Analysis
Just-in-time inventory strategies dominate United States and German blending terminals where seasonal procurement windows compress delivery lead times, while Russian and Canadian midstream operators maintain strategic stockpiles for arctic logistics corridors. Supply concentrates in Germany, the United States, and Southeast Asian oleochemical complexes. C12-C18 methacrylate ester precursors and tall oil fatty acid derivatives constitute critical raw material dependencies. Single-source vulnerability around palm kernel oil feedstocks from Malaysian and Indonesian complexes exposes formulators to shipping bottlenecks. Distribution runs through direct technical service teams at major refiners and regional chemical distributors for secondary accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based contract standardization is transforming cold flow improvers into platform-mediated technical risk transfer, with interoperability between additive architectures and refinery blending systems emerging as the decisive ecosystem battleground.
For Market Incumbents: Shield formulation expertise advantages by deepening captive supply of polyalkyl methacrylate backbones through Ludwigshafen and Gulf Coast capacity additions. Accelerate certification investment for GB 19147 homologation before China's extended field trial requirements freeze out international competitors. Technical service team embedding at Midwest terminals reinforces switching cost architecture against merchant monomer-dependent challengers. For New Entrants and Emerging Players: Differentiate on bio-based ester feedstock architectures leveraging Scandinavian tall oil derivatives for EU Green Deal-aligned procurement tenders. Arctic marine diesel above 70°N latitude represents the most penetrable white-space given specification stringency that incumbent suppliers struggle to satisfy. Direct-to-refiner technical service models bypassing traditional distributor networks capture margin from emergency winter specification failures. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated petrochemical majors with backward control into methacrylate ester precursors over formulation houses dependent on merchant monomer markets. Long-term viability across the next decade hinges on REACH authorization timelines and biofuel blending mandate trajectories. The signal to watch is ECHA scrutiny of persistent, bioaccumulative, and toxic characteristics in long-chain acrylates that could force expensive backbone reformulation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methacrylate Ester Precursors | Ludwigshafen and Gulf Coast complexes secure supply against Southeast Asian oleochemical volatility. |
| Arctic-Grade Formulation Development | Pour point depression below minus 40 degrees Celsius unlocks Russian and Norwegian shipping corridors. |
| Direct Technical Service Team Embedding | Real-time dosage optimization at blending terminals captures performance-based contract premiums. |
| Bio-Based Ester Feedstock Partnerships | Scandinavian tall oil derivatives align procurement with EU Green Deal carbon content requirements. |
| GB 19147 Homologation Investment | Extended field trial completion before regulatory deadlines locks in state-owned refiner relationships. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with refinery blending terminal managers, additive formulation chemists, midstream logistics procurement leads, and polymer R&D directors at integrated chemical complexes. Secondary validation drew from EPA fuel sulfur and operability standard filings, ECHA REACH registration dossiers, China GB 19147 revision notices, customs and trade data for methacrylate ester precursor flows, and SEC 10-K disclosures from petrochemical majors. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value trajectories by polymer backbone chemistry, application intensity across fuel additives and pipeline transport, end-user procurement scale, and regional regulatory cluster stringency. CAGRs were derived from segment-level growth rate synthesis incorporating treat-rate compression curves, biofuel blending mandate expansion scenarios, and arctic-grade specification penetration patterns.
The analysis sits within stated boundaries; outcomes outside sustained EPA winter operability enforcement, stable palm kernel oil feedstock pricing, and incremental rather than disruptive FAME blend ratio increases would require recalibration. Forecasts reflect documented assumptions around seasonal procurement cycle regularity and incumbent supplier homologation record persistence. Revision becomes warranted when REACH authorization timelines for long-chain acrylates compress or bio-based ester feedstock cost parity thresholds cross.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
India Feed Additives Market
Additives
Ethoxyquin Market
Additives
Calcium Acetate Market
Additives
Dipotassium Guanylate Market
Additives
Global Low-Profile Additive Market
Additives
Sodium Benzoate Market
Additives
Global Calcium Formate Market
Additives
Carboxymethylcellulose (CMC) Market
Additives
Europe Feed Additives Market
Additives
Guanylic Acid Market
Additives
North America Citric Acid Market
Additives
1,4 Butanediol Derivatives Market
Additives
Choline Chloride Market
Additives
Enzyme Stabilizer Market
Additives
Binder Excipients Market
Additives
Additives for Metalworking Fluids Market