
 Sri Lanka Lubricants Market | 2026-2036
Sri Lanka Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Sri Lanka Lubricants Market Analytics
Fleet operator consolidation across Sri Lanka's commercial transport sector is expanding the addressable base for bulk lubricant procurement. Chevron Lubricants Lanka PLC anchors its position through backward integration into blending and distribution infrastructure. LAUGFS Lubricants Limited differentiates via specialized product lines serving agricultural equipment and marine applications. Indian Oil Corporation Limited competes aggressively on wholesale channel penetration along coastal logistics corridors.
Lubricants comprise formulated oils and greases engineered from base stocks and additive packages to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades and oxidation stability determining performance boundaries. The Sri Lanka Standards Institution mandates specific quality benchmarks for engine oils used in tropical operating conditions. Engine oil dominates product type revenue pools given the density of automotive and fleet applications across the island. Industrial oil represents the fastest-growing application segment as manufacturing capacity expands in the Western and Central Provinces. Marine lubricant demand concentrates around Colombo and Hambantota port operations.
The Ceylon Petroleum Corporation's regulatory oversight of petroleum product standards shapes lubricant formulation requirements and import licensing protocols. Sri Lanka's national environmental regulator enforces waste oil disposal and recycling standards that elevate compliance costs for distributors. Fleet operators and industrial procurement teams must monitor evolving SLS certification timelines and additive import duty structures to secure supply continuity.
Market Dynamics
Fleet operator consolidation across Sri Lanka's commercial transport corridor is concentrating procurement volumes into fewer hands, forcing lubricant suppliers to reconfigure distribution networks around bulk delivery infrastructure and long-term supply agreements.
Growth Catalysts
- Western Province manufacturing expansion:Industrial capacity additions in Colombo's manufacturing belt are expanding demand for hydraulic and compressor oils.
- Sri Lanka Standards Institution certification mandates:Mandatory SLS quality benchmarks for tropical-grade engine oils are elevating product specifications and locking out substandard imports.
- Port infrastructure modernization:Hambantota and Colombo port expansion projects are accelerating marine lubricant throughput requirements.
Market Restraints
- Additive import dependency:Specialty chemical packages for high-performance formulations rely on concentrated Asian supply sources, exposing blenders to currency volatility and shipping disruptions.
- Base oil supply concentration:Regional refinery capacity limitations constrain domestic formulation flexibility and elevate working capital requirements for inventory buffers.
- Waste oil disposal compliance:National environmental regulator enforcement of recycling standards imposes fixed-cost burdens on distributor networks serving dispersed agricultural and marine accounts.
Strategic Opportunities
- Central Province industrial corridor penetration:Manufacturing zones outside Colombo remain underserved by technical lubricant distribution, creating first-mover positioning for specialized industrial oil portfolios.
- Synthetic lubricant conversion:Extended-drain formulations are displacing mineral oils in fleet applications, opening premium pricing tiers for oxidation-stable products.
- Direct fleet contracting models:Large transport operators are bypassing traditional distributor tiers, enabling volume-based supply relationships with integrated service bundling.
Industry Challenges
- Technical sales force scarcity:Qualified lubrication engineers capable of conducting used-oil analysis and equipment-specific recommendations remain concentrated in Colombo, limiting rural market development.
- SLS certification timeline compression:Accelerated product registration requirements are stretching quality assurance laboratory capacity and delaying new product introductions.
- Legacy equipment compatibility:Aging agricultural and marine machinery fleets operate on obsolete viscosity specifications, fragmenting inventory requirements for distributors serving mixed-equipment customer bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sri Lanka Lubricants Market |
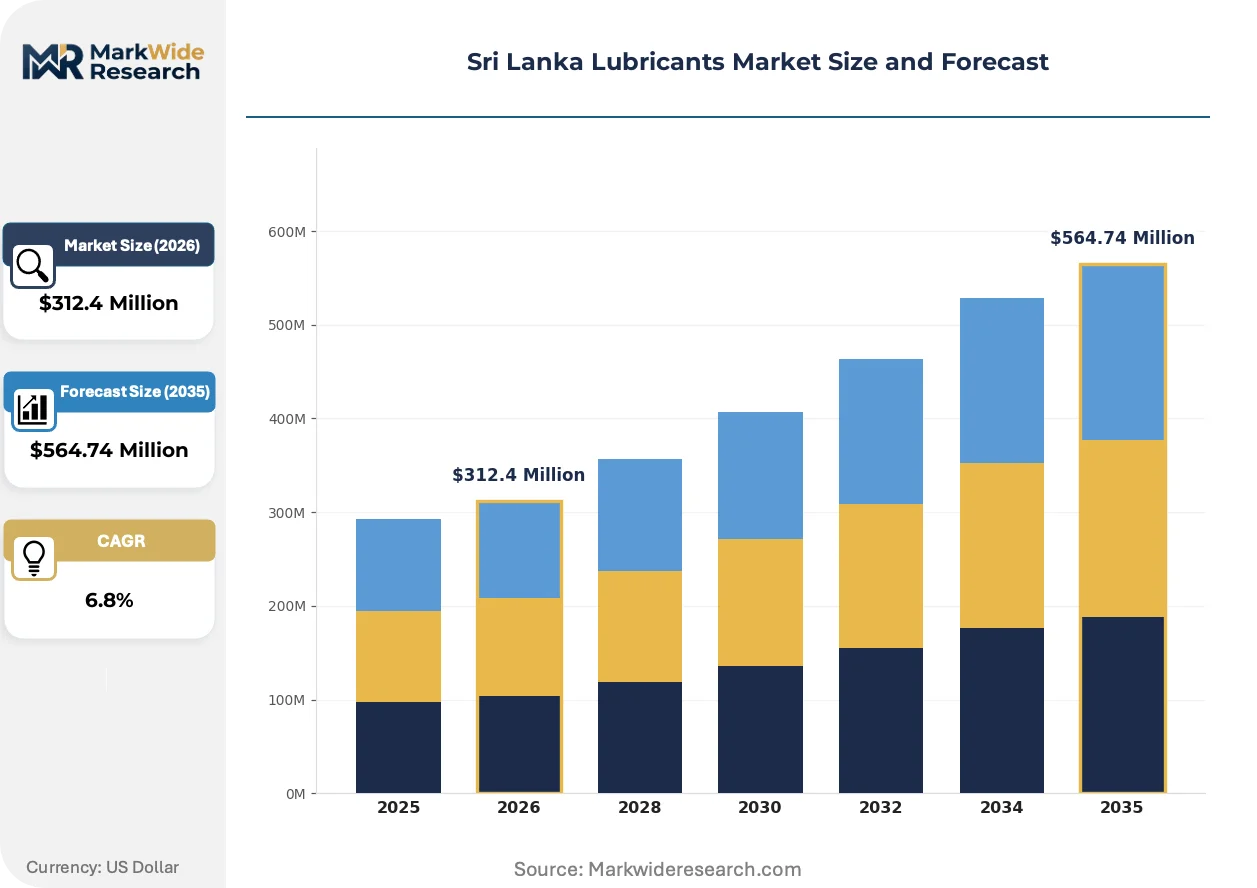
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Hydraulic Oil, Gear Oil, Industrial Oil Application: Automotive, Marine, Industrial Equipment, Agriculture Distribution Channel: Retail, Wholesale, Online, Direct Sales Customer Type: Commercial, Residential, Government, Fleet Operators |
| Companies Covered | Chevron Ceylon Limited, Ceylon Petroleum Corporation, LAUGFS Lubricants Limited, Indian Oil Corporation Limited, Bharat Petroleum Corporation Limited, ExxonMobil Asia Pacific Pte., BP Middle East LLC, Shell Markets (Middle East) Limited, Chevron Lubricants Lanka PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sri Lanka Lubricants Market Evolving Landscape
Digital monitoring systems and formulation chemistry advances are compressing maintenance intervals and reshaping how lubricant value is captured across Sri Lanka's fleet and industrial segments.
Predictive oil condition monitoring is automating fleet maintenance scheduling for commercial transport operators. Sensor-equipped vehicles transmit real-time viscosity and contamination data to centralized diagnostics platforms. This capability is automating the transition from calendar-based drain intervals to condition-based lubricant replacement, compressing total fluid consumption per vehicle while elevating demand for premium synthetic formulations compatible with extended service life.
Sri Lanka Standards Institution tropical-grade specifications are tightening additive package requirements for oxidation resistance and deposit control. Blenders must reformulate existing product lines to meet elevated thermal stability benchmarks. Engine oil portfolios targeting the Western Province fleet corridor face the most intensive compliance recertification timelines as SLS implementation deadlines approach.
Consolidated procurement departments at large logistics operators are unbundling lubricant supply from historical equipment vendor tie-ins. Direct negotiations with specialized blenders are displacing bundled maintenance contracts. This pattern is most visible across the Colombo-Hambantota freight corridor where container fleet operators now separately tender lubricant requirements from mechanical service agreements.
Sri Lanka Lubricants Market Segmentation
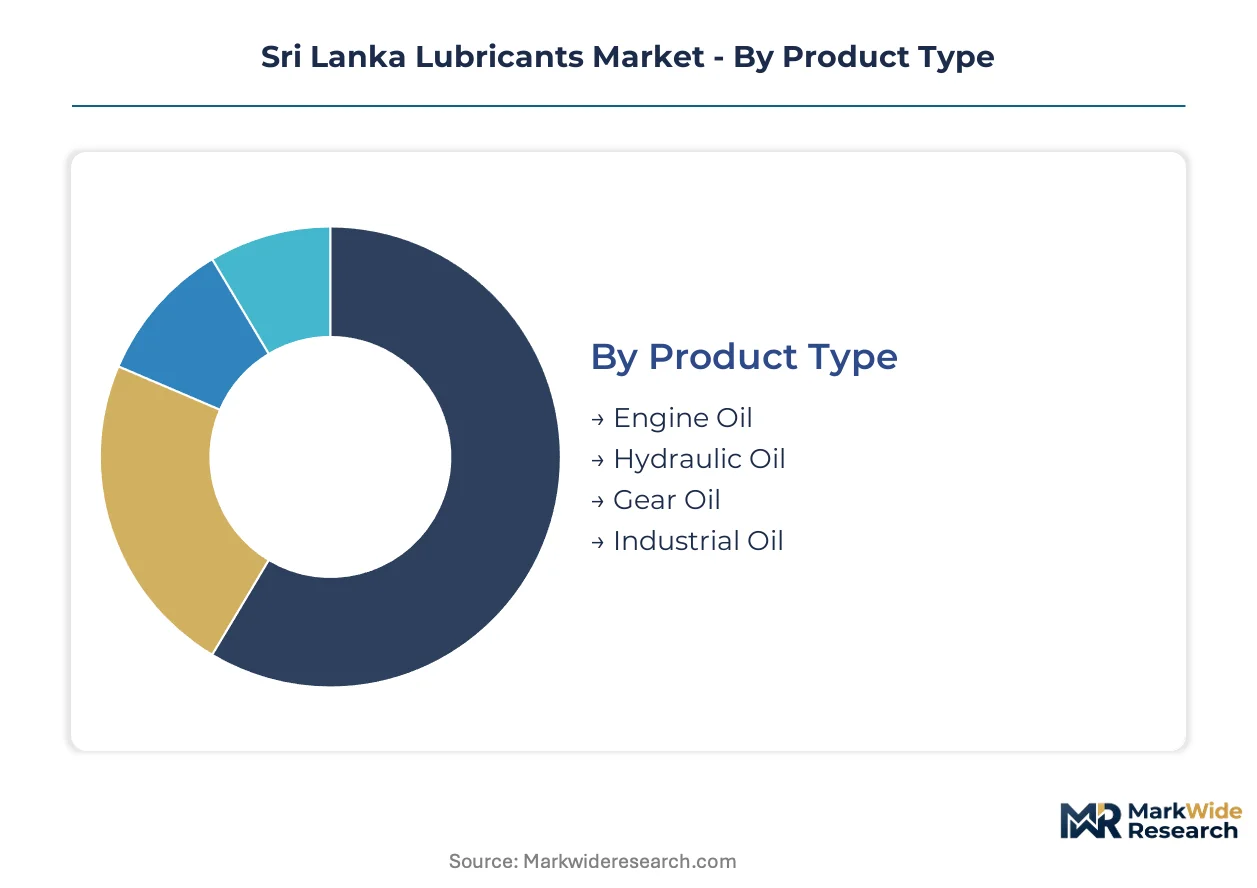
Sri Lanka's lubricant market fragments across formulation chemistry, equipment compatibility, and procurement scale. Each segmentation axis carries distinct margin profiles and regulatory exposure, requiring suppliers to maintain parallel inventory and certification strategies.
Product Type:
Standardization dominates commodity-grade mineral formulations, while synthetic and semi-synthetic blends demand customized additive packages calibrated to tropical operating conditions.
- Engine Oil:Formulated from Group I-III base stocks with detergent-dispersant and anti-wear additive packages, these lubricants must meet Sri Lanka Standards Institution tropical-grade specifications for oxidation resistance. Demand concentrates in Colombo's commercial transport corridor where fleet operators enforce extended-drain intervals. SLS certification mandates are elevating product specifications and compressing margins for non-compliant imports.
- Industrial Oil:Hydraulic fluids and compressor oils engineered for manufacturing equipment thermal stability represent the fastest-expanding product category. Western Province factory clusters around Colombo and Biyagama drive procurement volumes as industrial capacity additions accelerate. These formulations require specialized anti-foam and rust inhibitor packages distinct from automotive specifications.
- Hydraulic Oil:Zinc-based and ashless formulations serve construction and material handling equipment across Sri Lanka's infrastructure project sites.
- Gear Oil:Extreme-pressure lubricants for transmission and axle applications in commercial vehicles and marine propulsion systems.
Leading the category by volume: Engine Oil. Growing fastest: Industrial Oil.
Application:
Marine and industrial applications command premium pricing through specialized formulation requirements, while agricultural equipment operates on thinner margin, obsolete-specification products.
- Automotive:Passenger cars, motorcycles, and light commercial vehicles consume multi-grade engine oils with viscosity ranges calibrated to ambient temperature swings. Fleet density in Colombo, Gampaha, and Kalutara districts concentrates demand, with service stations and authorized workshops dominating procurement channels. SLS implementation timelines are forcing rapid product line recertification.
- Industrial Equipment:Manufacturing machinery in the Western and Central Provinces requires hydraulic, compressor, and turbine oils with extended service life specifications. These applications are displacing mineral-based formulations with synthetic alternatives as equipment OEMs tighten warranty requirements. Technical lubrication engineering support remains concentrated in Colombo, limiting rural market penetration.
- Marine:Two-stroke and four-stroke engine oils for fishing vessels and port operations in Colombo and Hambantota, plus stern tube and cylinder lubricants for commercial shipping.
- Agriculture:Tractor and harvester lubricants serving tea, rubber, and coconut plantation equipment across the Central and Southern Provinces.
Automotive generates the largest absolute volume. Industrial Equipment shows the steepest expansion trajectory.
Distribution Channel:
Channel selection tracks customer scale and technical service requirements, with bulk procurement bypassing traditional tiers entirely.
- Wholesale:Distributor networks supplying retail outlets, workshops, and smaller fleet operators across provincial markets. These channels carry inventory breadth requirements that strain working capital, particularly for distributors serving mixed agricultural and marine equipment bases with obsolete viscosity specifications.
- Direct Sales:Large transport operators and industrial procurement departments negotiate volume-based supply agreements directly with blenders, unbundling lubricant supply from equipment vendor maintenance contracts. This pattern is most visible across the Colombo-Hambantota freight corridor.
- Retail:Service stations, auto parts shops, and independent workshops serving individual vehicle owners and small commercial operators.
- Online:Emerging e-commerce platforms targeting DIY consumers and small fleet managers with packaged lubricant delivery.
Wholesale maintains the widest geographic coverage. Direct Sales is climbing the fastest as fleet consolidation accelerates.
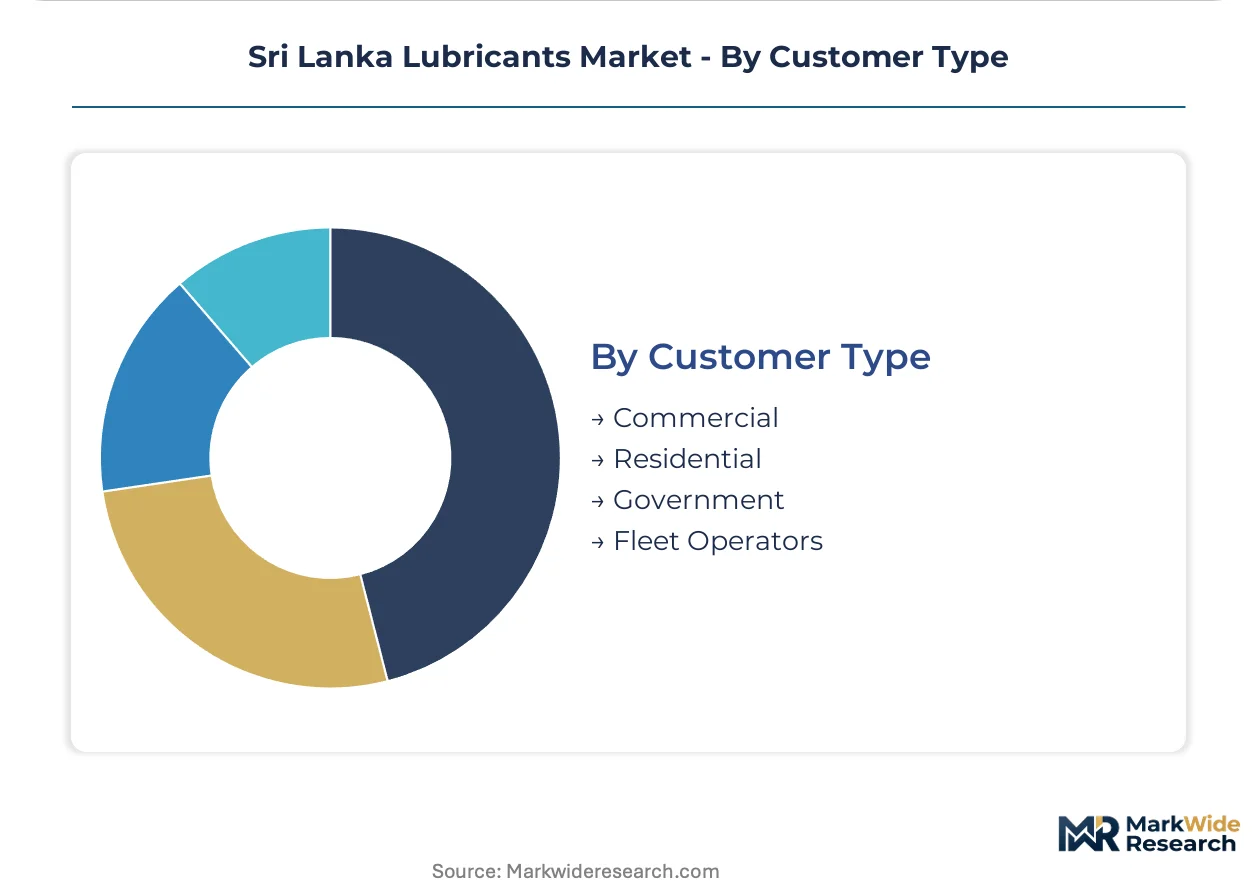
Customer Type:
Procurement sophistication varies dramatically, from centralized technical specifications at fleet operators to price-driven spot purchasing in residential segments.
- Fleet Operators:Consolidated logistics and transport companies across Sri Lanka's commercial transport corridor are concentrating procurement volumes into fewer hands. These buyers demand predictive oil condition monitoring compatibility, extended-drain synthetic formulations, and integrated service bundling. Their technical specifications are displacing distributor-tier product recommendations.
- Commercial:Small and mid-sized transport operators, construction contractors, and independent workshops with less centralized procurement.
- Government:State-owned transport and utility fleets with formal tender processes and SLS certification requirements.
- Residential:Individual vehicle owners purchasing through retail channels with minimal technical specification knowledge.
Fleet Operators command the highest per-account revenue. Commercial represents the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sri Lanka's lubricant demand concentrates along the Western Province corridor, with Colombo's port and manufacturing belt anchoring procurement volumes. Fleet operators and industrial facilities drive consumption patterns across distinct provincial clusters.
Western Province
Colombo's manufacturing belt and Hambantota port operations generate the densest lubricant consumption. The Sri Lanka Standards Institution enforces tropical-grade engine oil specifications here first. Biyagama factory clusters absorb hydraulic and compressor oils as industrial capacity expands.
Central Province
Tea and rubber plantation equipment across Kandy and Nuwara Eliya districts creates scattered agricultural lubricant demand. The country's national environmental regulator enforces waste oil recycling standards that elevate compliance costs for rural distributors. Technical sales force scarcity limits penetration of synthetic formulations in this zone.
Southern Province
Fishing vessel operations around Galle and Matara sustain marine lubricant requirements for two-stroke outboard engines. Port infrastructure investments at Hambantota are accelerating stern tube and cylinder lubricant throughput. Coastal logistics corridors here attract wholesale channel competition from Indian suppliers.
Sabaragamuwa Province
Ratnapura's gem mining machinery and rubber processing equipment consume industrial oils with obsolete viscosity specifications. The Ceylon Petroleum Corporation's distribution network reaches this region through provincial depot infrastructure. Aging equipment fleets fragment inventory requirements for local distributors.
Northern and Eastern Provinces
Post-conflict reconstruction and agricultural resettlement are gradually expanding addressable demand in Jaffna and Trincomalee. The Sri Lanka Standards Institution certification mandates apply here with delayed implementation timelines. Marine lubricant demand concentrates around Trincomalee port operations and fishing harbors.
Sri Lanka Lubricants Market Competitive Landscape
International oil majors anchor one competitive tier; domestic blenders and regional state-owned enterprises hold procurement relationships with fleet and government accounts. Market structure reflects a concentrated premium segment alongside fragmented mid-market supply. Three archetypes dominate: vertically integrated multinationals with captive blending plants, regional state-owned petroleum corporations leveraging import licensing advantages, and specialized domestic formulators serving agricultural and marine niches. Capacity expansion in Colombo-area blending facilities and direct fleet contracting models represent the dominant competitive vectors.
Within the multinational tier, Chevron Lubricants Lanka PLC and ExxonMobil Asia Pacific Pte. exemplify integrated blending and distribution strategies. Among regional state-owned competitors, Indian Oil Corporation Limited and Bharat Petroleum Corporation Limited occupy positions shaped by cross-border petroleum product agreements. Domestic specialists LAUGFS Lubricants Limited represents the specialized formulator archetype targeting equipment-specific applications outside commodity engine oils.
| Leading Market Players |
|---|
| Chevron Ceylon Limited |
| Ceylon Petroleum Corporation |
| LAUGFS Lubricants Limited |
| Indian Oil Corporation Limited |
| Bharat Petroleum Corporation Limited |
| ExxonMobil Asia Pacific Pte. |
| BP Middle East LLC |
| Shell Markets (Middle East) Limited |
| Chevron Lubricants Lanka PLC |
| Others |
Value Network & Pricing Analysis
Sri Lanka Standards Institution waste oil recycling mandates gate qualified supply access and premium-tier pricing power, forcing distributors to absorb fixed compliance costs that stratify market participation between capitalized blenders and marginal importers.
Pricing Analysis
High-volume mineral formulations trade on thin margins while synthetic extended-drain products capture premium returns. Pricing stratifies across SLS-certified tropical grades, uncertified imports, and direct fleet contract tiers. Cost compression in commodity engine oils intensifies as Indian state-owned suppliers undercut wholesale benchmarks. Fleet operators show lowest price sensitivity due to total cost of ownership modeling, whereas residential retail buyers drive spot-market volatility.
Supply Chain Analysis
SLS certification requirements filter supplier eligibility before commercial entry, compressing qualified blender counts. Base oil feedstocks draw from Singapore, South Korea, and regional Middle Eastern refineries. Specialty additive packages hinge on concentrated Malaysian and Thai chemical manufacturers. Single-source vulnerability runs through Colombo port logistics chokepoints. Distribution runs through Ceylon Petroleum Corporation depot infrastructure layered with private wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Base oil refinery capacity constraints across South Asia prop pricing power for integrated blenders with captive supply arrangements, sustaining margin structures despite import competition.
For Market Incumbents: Acquire Colombo-area blending and storage assets to lock distribution density before SLS certification deadlines accelerate. Chevron Lubricants Lanka PLC's backward integration into formulation infrastructure demonstrates the defensive logic. Counter Indian Oil Corporation Limited's coastal wholesale penetration through direct fleet contracting capabilities. Prioritize technical sales force expansion into Central Province manufacturing corridors. For New Entrants and Emerging Players: Sri Lanka Standards Institution tropical-grade certification timelines open a window for specialized industrial oil portfolios in underserved Central Province factory zones. Target hydraulic and compressor oil applications outside Colombo's saturated corridor. Pursue predictive oil condition monitoring integration as a service-differentiation wedge against commodity distributors. For Investors and Strategic Acquirers: Accelerated direct fleet contracting announcements from consolidated logistics operators is the leading indicator that distribution margin pools are shifting upstream. Five-to-ten-year viability favors blenders with SLS laboratory accreditation and Colombo port-adjacent storage. Watch for Ceylon Petroleum Corporation infrastructure privatization signals as capacity bottleneck relief.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive feedstock access insulates margin pressure from Singapore and Middle Eastern refinery volatility. |
| SLS Certification Laboratory Investment | In-house tropical-grade testing accelerates product registration timelines against compressed regulatory deadlines. |
| Direct Fleet Contracting Model | Volume-based supply relationships with integrated service bundling displace distributor-tier margin extraction. |
| Central Province Distribution Expansion | First-mover positioning in Biyagama manufacturing clusters captures industrial oil growth outside Colombo saturation. |
| Predictive Oil Condition Monitoring Platform | Sensor-enabled maintenance scheduling locks fleet operator loyalty through extended-drain synthetic conversion. |
Research Methodology
Customs and trade databases, Ceylon Petroleum Corporation distribution records, and Sri Lanka Standards Institution certification filings formed the secondary backbone. Primary interviews with lubricant blending plant managers, fleet procurement directors at Colombo-Hambantota logistics operators, industrial maintenance heads at Western Province factories, and wholesale distributor principals validated volume assumptions. Bottom-up triangulation across product-type demand curves and top-down reconciliation against national petroleum product consumption statistics anchored value estimates.
Bottom-up modeling built product-level forecasts across engine oil, industrial oil, hydraulic oil, and gear oil segments, then aggregated through application channels and customer-type procurement scales. Top-down validation cross-checked against Ceylon Petroleum Corporation throughput data and import licensing records. CAGRs derived from regression-adjusted trend extrapolation incorporating SLS implementation phase-ins, port infrastructure completion schedules, and manufacturing capacity addition pipelines. Base oil price volatility and rupee-dollar exchange trajectory sensitivity tested scenario boundaries.
The model assumes a particular synthetic conversion technology adoption path; alternative pathways for mineral oil retention in legacy agricultural equipment would alter the outlook. Forecasts reflect documented assumptions around fleet consolidation velocity and SLS enforcement intensity. A model refresh is warranted upon material change in Ceylon Petroleum Corporation infrastructure privatization timelines or Indian state-owned supplier import licensing protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market
Lubricants
South America Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
Friction Reducers Market
Lubricants
China Lubricants Market
Lubricants
Synthetic Ester Lubricants Market
Lubricants
Angola Lubricants Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Slideway Oil Market
Lubricants
Indonesia Lubricants Market
Lubricants
Cold Rolling Oils/Lubricants Market
Lubricants
Polyurea Greases Market
Lubricants
Bangladesh Lubricants Market
Lubricants
Global Aerospace Lubricant Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Singapore Lubricants Market