
 Europe Metalworking Fluids Market | 2026-2036
Europe Metalworking Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Metalworking Fluids Market Analysis
Synthetic ester formulation is tilting metalworking fluid design away from mineral oil bases across European machine shops. FUCHS leverages its Stuttgart R&D campus to anchor high-performance cutting fluid development for automotive powertrain machining. Blaser Swisslube specializes in minimum quantity lubrication systems that reduce coolant volumes for Swiss precision manufacturers. TotalEnergies competes through backward integration into base oil refining, sustaining margin control across its European blending network.
Metalworking fluids are engineered lubricants and coolants applied during machining, grinding, and forming operations to reduce friction, dissipate heat, and extend tool life, typically formulated with base oils, emulsifiers, corrosion inhibitors, and extreme-pressure additives at oil-to-water ratios between 5% and 15%. Cutting Fluids generates the largest revenue pool due to pervasive deployment in high-speed CNC machining centers across European aerospace and automotive tiers. Synthetic Fluids represents the fastest-expanding product category as manufacturers seek extended sump life and reduced waste disposal costs under tightening environmental protocols. Metal Cutting applications command premium positioning because tool wear reduction directly correlates with throughput economics in precision component manufacturing.
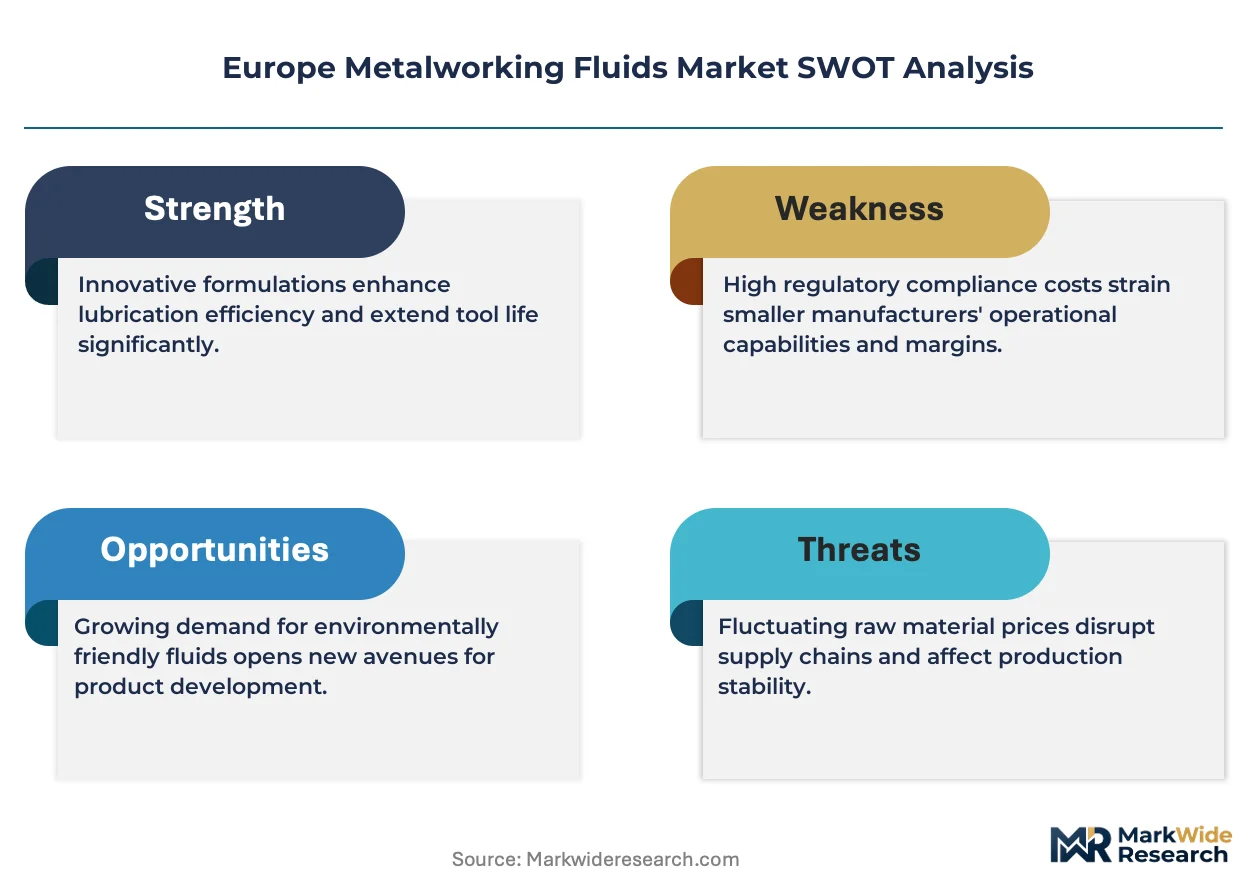
REACH regulation and the EU Green Deal framework compel reformulation away from boron, formaldehyde-releasing biocides, and chlorinated paraffins, reshaping R&D priorities for every supplier serving European metal fabrication. ECHA substance evaluation drives classification updates that restrict market access for legacy formulations lacking biodegradability credentials. Machinery OEMs and contract manufacturers must monitor regulatory substance lists quarterly to avoid supply discontinuity.
Market Dynamics
REACH substance restrictions and the EU Green Deal are forcing wholesale reformulation of metalworking fluid chemistries, eliminating boron carriers and formaldehyde-releasing biocides while elevating bio-based ester demand across European precision machining corridors.
Growth Catalysts
- REACH compliance deadlines:Automotive OEMs in Germany and France accelerate procurement of biodegradable cutting fluids to preempt ECHA classification updates that restrict legacy formulations.
- Extended sump life technology:Synthetic ester bases reduce coolant change frequency by half, cutting waste disposal costs for Swiss precision manufacturers operating under strict cantonal environmental rules.
- Spain and Italy:Contract machining clusters in Barcelona and Milan adopt minimum quantity lubrication systems to reduce coolant volumes and comply with regional wastewater discharge limits.
Market Restraints
- Base oil supply concentration:European refiners control Group II/III paraffinic base stock output, creating input cost volatility for independent blenders without backward integration into refining.
- Additive technical limitations:Bio-based extreme-pressure additives from vegetable sources lack thermal stability above 180°C, restricting deployment in high-speed aerospace titanium machining.
- Substitution by dry machining:Cryogenic cooling systems using liquid CO2 or nitrogen eliminate fluid entirely in select German automotive powertrain applications.
Strategic Opportunities
- Poland and Czech Republic:Underpenetrated precision machining sectors in Wrocław and Brno seek fluid suppliers capable of local technical service and rapid formulation customization.
- CSRD reporting requirements:Large EU manufacturers must disclose Scope 3 emissions, creating procurement preference for suppliers with verified lifecycle carbon data on bio-based formulations.
- Digital fluid monitoring:IoT sensors tracking pH, conductivity, and bacterial load converge with predictive maintenance platforms to enable condition-based coolant management contracts.
Industry Challenges
- Formulation chemist scarcity:European universities produce few graduates with combined expertise in tribology, microbiology, and polymer chemistry required for next-generation bio-stable fluids.
- Biocide re-registration timelines:ECHA substance evaluation processes extend 18-36 months, forcing blenders to maintain dual formulation pipelines during regulatory uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Metalworking Fluids Market |
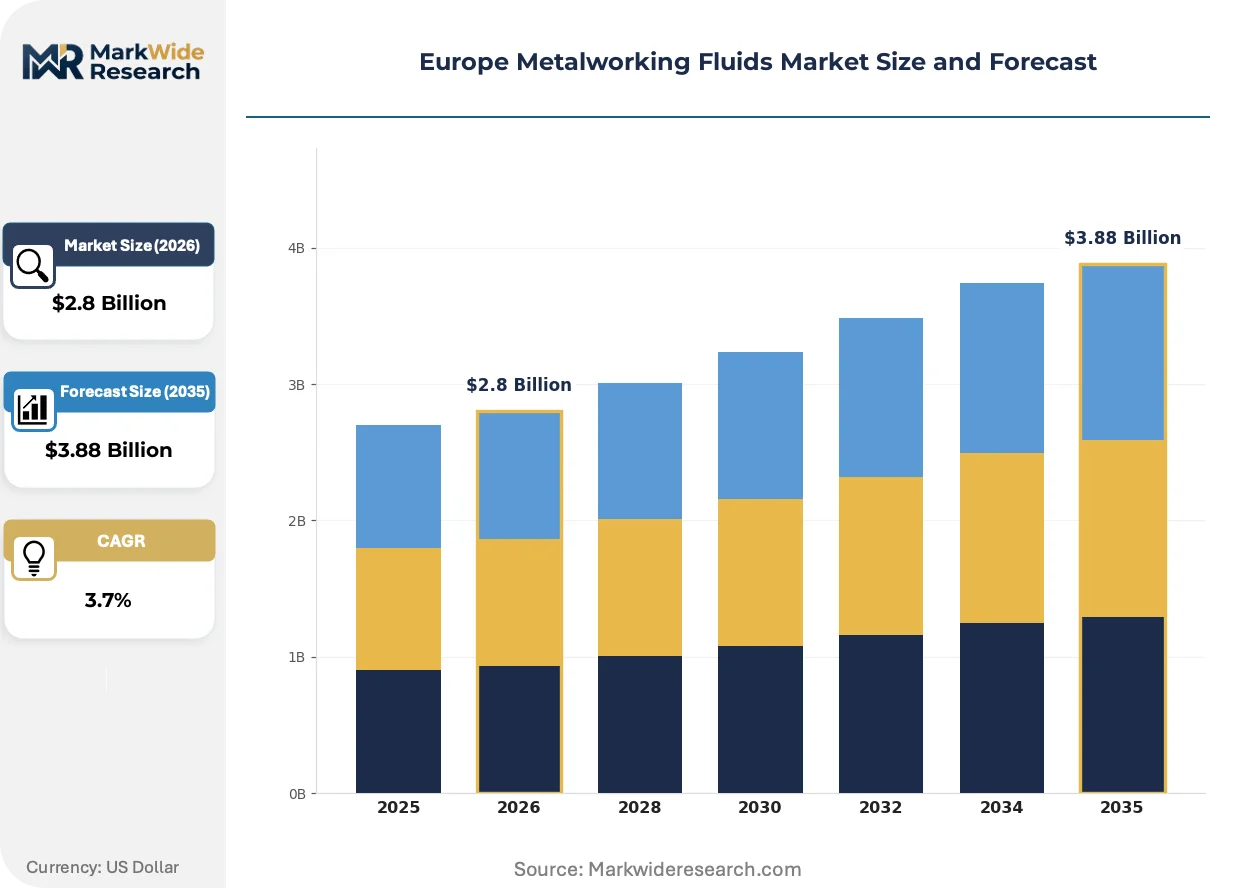
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.88 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Fluids, Grinding Fluids, Rust Preventive Fluids, Synthetic Fluids Application: Metal Cutting, Metal Forming, Surface Treatment, Tool Lubrication End User: Aerospace, Automotive, Machinery, Manufacturing Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | FUCHS, Quaker Houghton, TotalEnergies, Exxon Mobil Corporation, Chevron Corporation, BP, Blaser Swisslube, BASF, Castrol, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Metalworking Fluids Market Emerging Trajectories
Synthetic chemistry advances and digital integration are compressing traditional fluid lifecycle economics while regulatory substance bans accelerate material transitions across European metal fabrication.
Vegetable-based synthetic esters formulated from rapeseed and sunflower feedstocks deliver comparable lubricity to mineral oil bases with superior biodegradability profiles. Automotive powertrain machinists in Stuttgart and Munich adopt these esters at accelerating rates. The technology is collapsing the historical price premium between bio-based and petroleum-derived cutting fluids.
REACH Annex XIV authorization requirements and the EU Green Deal's chemical sustainability targets eliminate chlorinated paraffins and boric acid derivatives from approved substance lists. Fluid blenders must reformulate corrosion inhibitors and extreme-pressure packages using approved alternatives. German aerospace tier suppliers face the most compressed compliance timelines as ECHA substance evaluations conclude.
Fluid-as-a-service contracting is displacing traditional volume-based procurement in high-throughput machining operations. Swiss and German contract manufacturers now pay per liter of metal removed rather than per drum of concentrate purchased. This model concentrates most visibly in automotive component machining corridors where tool life guarantees and waste handling obligations shift entirely to fluid suppliers.
Europe Metalworking Fluids Market Segmentation
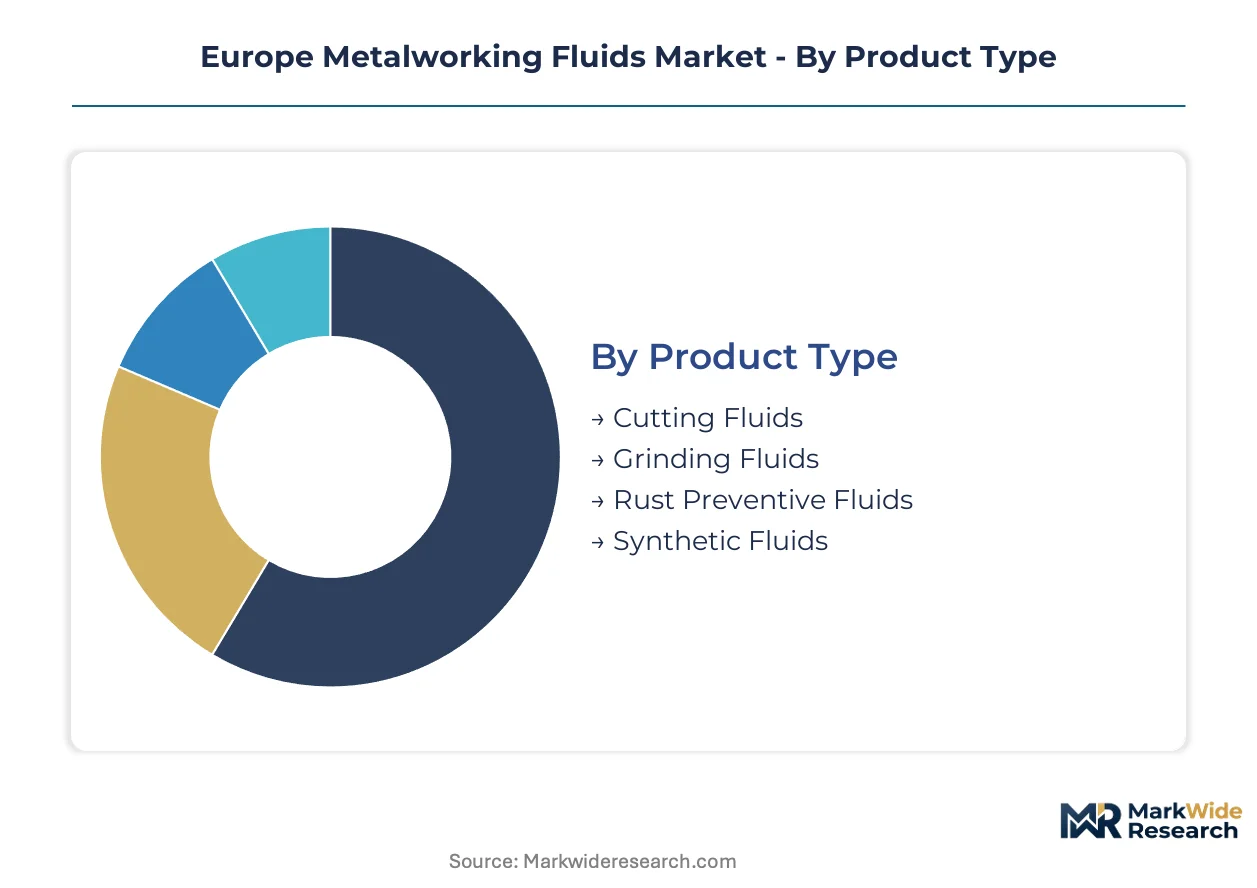
Metalworking fluid procurement in Europe stratifies across performance tiers, application intensities, and channel configurations that determine formulation chemistry and service models. Understanding these divisions reveals where REACH compliance costs concentrate and where bio-based premiums command buyer attention.
Product Type:
Cost tier differentiation separates commodity mineral oil emulsions from high-performance synthetics with extended sump life and reduced waste disposal burdens.
- Cutting Fluids:Oil-in-water emulsions and synthetics formulated for high-speed CNC machining operations dominate procurement volumes across German and French automotive powertrain plants. Stuttgart and Munich machining corridors specify these fluids for tool life guarantees in precision component manufacturing.
- Synthetic Fluids:Ester-based formulations deliver biodegradability credentials required under REACH substance restrictions while reducing coolant change frequency by half for Swiss precision manufacturers operating under strict cantonal environmental rules.
- Grinding Fluids:Low-foam formulations with enhanced flushing properties serve surface finish requirements in bearing and gear manufacturing clusters.
- Rust Preventive Fluids:Thin-film corrosion inhibitors protect machined components during inter-process storage and shipment for export-oriented machinery builders.
Cutting Fluids commands the established base. The steepest expansion runs through Synthetic Fluids.
Application:
Volume intensity and process thermal loading determine formulation selection, with high-speed operations demanding superior heat dissipation and extreme-pressure additive packages.
- Metal Cutting:Turning, milling, and drilling operations consume the largest fluid volumes per machine hour, with aerospace titanium machining in Germany requiring thermal stability above 180°C that bio-based additives currently struggle to deliver.
- Metal Forming:Stamping, drawing, and extrusion lubricants emphasize boundary lubrication for die protection in automotive body panel production across Spanish and Italian contract manufacturing clusters.
- Surface Treatment:Cleaning and phosphating chemistries prepare substrates for coating adhesion in appliance and machinery manufacturing.
- Tool Lubrication:Minimum quantity lubrication systems reduce coolant volumes to aerosol mist levels for Swiss precision manufacturers seeking compliance with regional wastewater discharge limits.
Metal Cutting absorbs the majority of volume. Metal Forming is climbing the fastest as automotive lightweighting intensifies stamping complexity.
End User:
Customer type determines specification stringency, with aerospace and automotive OEMs imposing formulation approval processes that lock out unqualified suppliers.
- Automotive:Powertrain machining operations in Germany and France drive specification of bio-based esters as REACH compliance deadlines approach, with procurement teams mandating biodegradability credentials from tier suppliers.
- Aerospace:Titanium and nickel alloy machining for engine components requires thermal stability and fire resistance that constrains bio-based additive selection, compressing compliance timelines for German aerospace tier suppliers.
- Machinery:General equipment manufacturers balance performance requirements against total cost of ownership in fluid selection for gear and bearing production.
- Manufacturing:Diverse metal fabrication shops across Poland and Czech Republic seek local technical service capabilities for rapid formulation customization.
Automotive anchors the demand base. Aerospace is gaining share fastest as production rates recover and material specifications tighten.
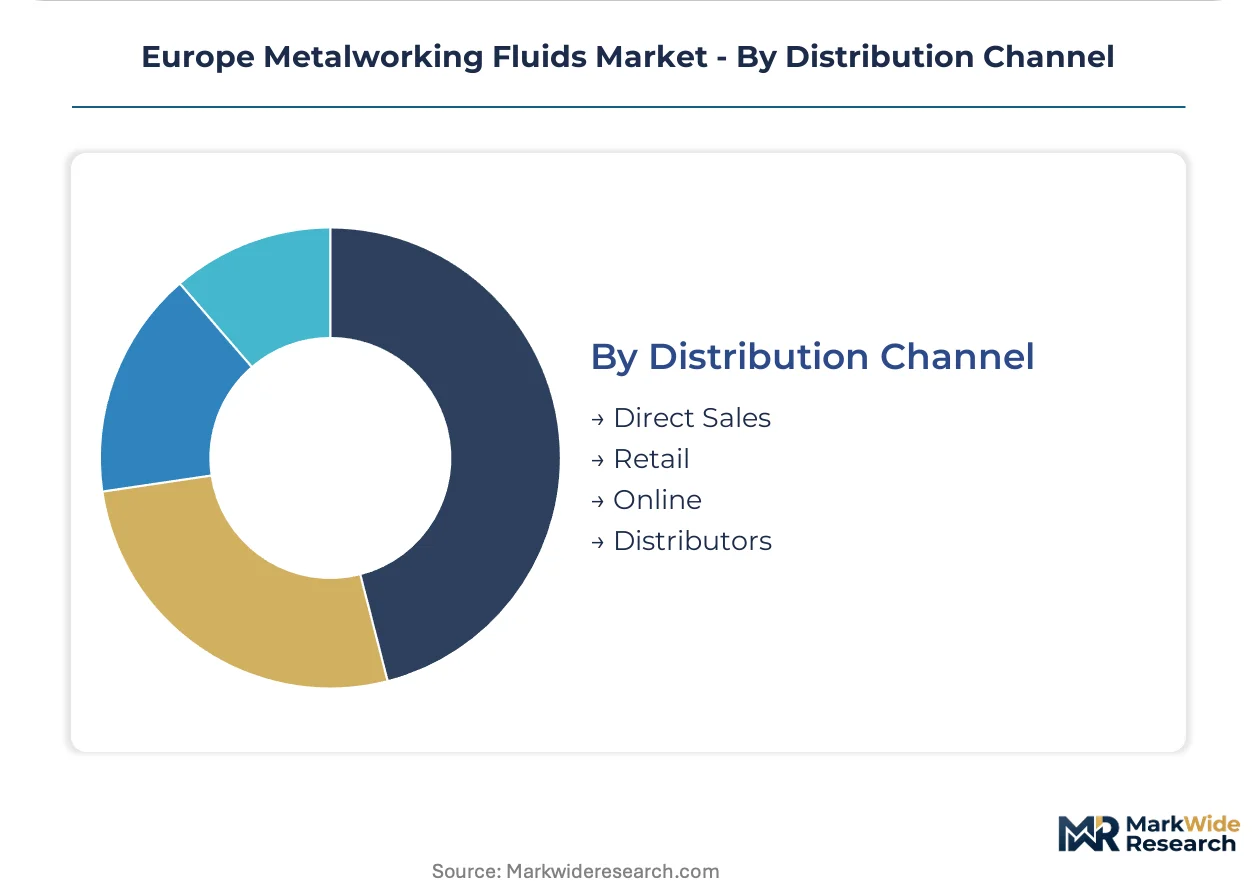
Distribution Channel:
Supply concentration and service intensity separate direct relationships with large consumers from fragmented retail and digital channels serving smaller shops.
- Direct Sales:Fluid suppliers maintain dedicated technical service teams for high-volume automotive and aerospace manufacturers, embedding chemists within customer plants for sump monitoring and formulation optimization.
- Distributors:Regional blending and logistics networks serve mid-tier machinery builders and contract manufacturers across underpenetrated precision machining sectors in Wrocław and Brno.
- Retail:Packaged concentrates and ready-to-use emulsions reach small job shops through industrial supply merchants with limited technical support.
- Online:Digital procurement platforms capture standard formulations for price-sensitive buyers with predictable consumption patterns and in-house fluid management expertise.
Direct Sales controls the premium tier. Distributors are expanding most quickly as supplier networks penetrate Central European manufacturing growth corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's metalworking fluids trade flows reflect a manufacturing core concentrated in Germany, France, and Switzerland, with peripheral markets in Central and Eastern Europe importing formulated products and technical services from established Western suppliers.
Germany
Automotive powertrain machining in Stuttgart and Munich drives specification of bio-based ester formulations as REACH compliance deadlines approach. ECHA substance evaluations targeting boron carriers and chlorinated paraffins compress reformulation timelines for fluid suppliers serving German aerospace tiers. The precision machining corridor spanning Baden-Württemberg and Bavaria concentrates demand for extended sump life synthetics.
Switzerland
Swiss precision manufacturers operating under strict cantonal environmental rules accelerate adoption of minimum quantity lubrication systems to reduce coolant volumes. The country's national pharmaceutical regulator aligns with EU REACH frameworks while maintaining independent biocide approval processes. Geneva and Zurich machining clusters contract fluid-as-a-service models that shift waste handling obligations entirely to suppliers.
France
Aerospace component manufacturing around Toulouse and Nantes sustains demand for thermal-stable formulations where bio-based additives face performance constraints. ANSM chemical substance oversight converges with EU Green Deal targets to eliminate formaldehyde-releasing biocides from approved fluid chemistries. The Île-de-France machinery belt seeks local technical service capabilities for rapid formulation customization.
Poland
Underpenetrated precision machining sectors in Wrocław and Poznań attract distributor expansion from Western European fluid suppliers. The country's national chemical regulator implements REACH-aligned substance restrictions with transitional periods for domestic blenders. Contract manufacturing clusters serving German automotive tiers import high-performance synthetics lacking local production capacity.
Italy
Metal forming lubricant demand from automotive body panel stamping in Turin and Milan climbs as lightweighting intensifies process complexity. Regional wastewater discharge limits in Lombardy and Piedmont accelerate minimum quantity lubrication adoption among contract machinists. The Emilia-Romagna machinery corridor balances performance requirements against total cost of ownership in fluid procurement.
Europe Metalworking Fluids Market Vendor Landscape
On the supply side, the industry is consolidating around integrated energy majors, specialized lubricant formulators, and regional technical service providers. Three strategic archetypes dominate: backward-integrated refiners controlling base oil supply, R&D-focused specialists with embedded customer technical teams, and distributor-dependent regional blenders serving fragmented job shop markets. Competitive moves concentrate on formulation reformulation partnerships with automotive OEMs and digital fluid monitoring platform development.
Within the integrated energy major tier, TotalEnergies and BP anchor positions through captive base oil refining and European blending network control. FUCHS exemplifies the specialist archetype with dedicated technical service teams embedded in customer plants. Quaker Houghton occupies a position bridging formulation expertise with aerospace and automotive tier supplier relationships. Blaser Swisslube represents the precision-focused segment serving Swiss and German minimum quantity lubrication demand.
| Leading Market Players |
|---|
| FUCHS |
| Quaker Houghton |
| TotalEnergies |
| Exxon Mobil Corporation |
| Chevron Corporation |
| BP |
| Blaser Swisslube |
| BASF |
| Castrol |
| Others |
Supply Flow & Price Mechanics
REACH substance authorization delays create single-source dependency risks for bio-based extreme-pressure additives, compressing both premium-mineral price spreads and forcing blenders toward dual-supply qualification programs across German automotive corridors.
Pricing Analysis
The mineral-to-synthetic-to-bio pricing gap spans three technology generations. Premium-mid-economy pricing differentiation rests on REACH biodegradability certification and sump-life extension guarantees. Cost compression in mineral oil emulsions is intensifying because independent blenders lack backward integration into Group II/III base stock refining. Small Polish and Czech job shops exhibit highest price sensitivity, while Swiss precision manufacturers prioritize performance over unit cost.
Supply Chain Analysis
EU dual-use export controls on chlorinated paraffin alternatives limit additive technology flows to non-EU blenders. Base oil supply concentrates in Germany, Belgium, and the Netherlands. Formulation chemists with combined tribology-microbiology expertise remain scarce. Single-source vulnerability runs through rapeseed and sunflower ester feedstocks. Distribution runs through regional blending networks serving mid-tier machinery builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe metalworking fluids market tracks automotive production cycles, with German powertrain machining rates serving as the primary cyclical driver.
For Market Incumbents: Harden formulation pipelines against ECHA substance evaluation delays by maintaining parallel biocide approvals. Deepen backward integration into bio-based ester production to defend margin position against commodity base oil volatility. Anchor technical service teams within Stuttgart and Munich automotive clusters to lock out distributor-dependent competitors. For New Entrants and Emerging Players: Underpenetrated precision machining sectors in Wrocław and Brno offer white-space entry points. Target minimum quantity lubrication system adoption among Italian contract manufacturers facing Lombardy wastewater discharge limits. Lead with fluid-as-a-service contracting models that shift waste handling obligations from buyers. For Investors and Strategic Acquirers: Regional blenders with embedded technical service capabilities in Central Europe represent compelling acquisition targets. Long-term viability hinges on REACH-aligned formulation portfolios rather than legacy mineral oil dependence. Monitor ECHA authorization timelines for boron-free corrosion inhibitors as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Ester Production | Captures margin from rapeseed feedstock through finished formulation for German automotive tiers. |
| Fluid-as-a-Service Contracting Model | Shifts revenue from volume sales to performance guarantees in Swiss precision manufacturing. |
| REACH-Aligned Formulation Pipeline | Preempts ECHA substance bans on boron carriers and formaldehyde-releasing biocides. |
| Digital Fluid Monitoring Platform | Converges IoT sump sensors with predictive maintenance for condition-based coolant management. |
| Central European Technical Service Expansion | Establishes local formulation customization capability in Wrocław and Brno machining clusters. |
Methodological Framework
A spread of perspectives from fluid formulators, automotive procurement leads, aerospace tier suppliers, and ECHA regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with plant engineers at German powertrain facilities, Swiss precision manufacturers, and Polish contract machinists. Secondary validation drew from ECHA substance evaluation databases, Cefic chemical industry reports, EU customs trade flows, and SEC filings of listed lubricant suppliers. Bottom-up demand modeling triangulated against top-down market sizing from production capacity and consumption intensity benchmarks.
Demand-supply balance framing anchored the forecast architecture across the analysis window. Segmentation dimensions modeled include product chemistry tier, application intensity, end-use industry, and regional regulatory cluster. CAGRs derived from production volume trajectories and value-per-unit expansion paths. Industry-specific inputs incorporated automotive powertrain machining rates, aerospace titanium alloy consumption, and Swiss cantonal environmental enforcement timelines.
Macroeconomic conditions sit as an overlay; deviation in German automotive output, EU chemical feedstock costs, or ECHA authorization pacing would shift the trajectory. Forecasts reflect documented assumptions on regulatory compliance deadlines and technology substitution rates. Cross-checking against IHS Markit vehicle production data and Cefic chemical consumption indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Norway Automotive Lubricants Market
Lubricants
Fire Resistant Fluids Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Open Gear Lubricants Market
Lubricants
Kenya Lubricants Market
Lubricants
Poland Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
Global Group IV and V Lubricants Market
Lubricants
Plastic Lubricants Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market
Lubricants
Colombia Lubricants Market
Lubricants
Egypt Lubricants Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Neat Cutting Oil Market
Lubricants
Germany Commercial Vehicles Lubricants Market