
 United States Automotive Lubricants Market | 2026-2036
United States Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
United States Automotive Lubricants Market Analytics
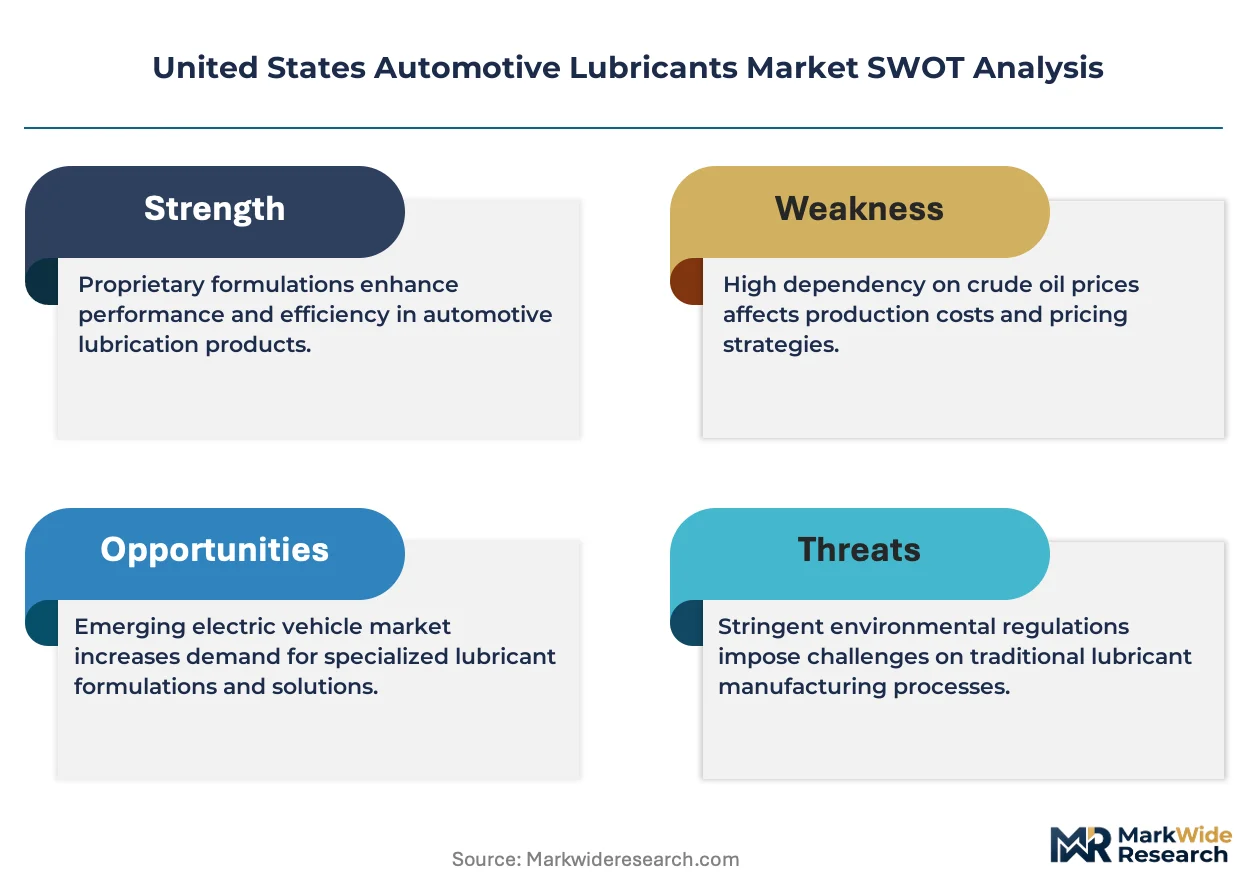
Electrification of powertrains is tilting lubricant formulation priorities away from traditional engine oils toward thermal management fluids and e-axle greases. ExxonMobil Corporation leverages its integrated refining and chemical operations to sustain cost-advantaged base stock supply. Valvoline Inc. anchors its position through quick-lube service bay density and direct fleet relationships. AMSOIL Inc. specializes in premium synthetic formulations for severe-duty applications, competing on performance guarantees rather than price.
Automotive lubricants are formulated mixtures of base oils and additive packages engineered to reduce friction, dissipate heat, and prevent wear in vehicle powertrain and drivetrain components, with Society of Automotive Engineers viscosity grades and American Petroleum Institute service categories defining performance benchmarks. Engine oil retains the largest revenue pool among product types, though high-mileage formulations occupy a profitable niche as the US vehicle fleet ages. Synthetic and semi-synthetic grades capture expanding share as OEMs specify thinner oils to meet CAFE targets, while conventional lubricants face margin compression in the aftermarket. Fleet operators represent the fastest-growing end user channel as centralized procurement shifts toward long-drain synthetic products.
The EPA regulates lubricant environmental claims and disposal protocols, while the Department of Transportation's National Highway Traffic Safety Administration enforces fuel economy standards that indirectly dictate OEM lubricant specifications. California's Air Resources Board imposes additional low-emission vehicle requirements that filter into national formulation standards through the state's market scale. Stakeholders must monitor how state-level zero-emission vehicle mandates reshape lubricant demand in commercial segments where electrification timelines remain contested.
Market Dynamics
The United States automotive lubricants market is restructuring around electrification timelines, where powertrain fluid demand is fragmenting into thermal management and e-axle specialties while internal combustion engine volumes plateau.
Growth Catalysts
- CAFE Standards:The NHTSA Corporate Average Fuel Economy program mandates OEMs to specify lower-viscosity synthetic formulations, pulling demand toward advanced base stocks and additive packages that reduce friction losses.
- Fleet Centralization:Large logistics operators in Texas and California are consolidating procurement around long-drain synthetic products, compressing maintenance intervals and raising per-unit spending on premium lubricants.
- Oilfield Logistics Density:Permian Basin petrochemical clusters and heavy-duty fleet operations create concentrated consumption nodes that sustain regional blending capacity utilization.
Market Restraints
- Group III Base Oil Volatility:Refinery output fluctuations for high-viscosity-index feedstocks create margin pressure on synthetic blenders dependent on merchant supply.
- Electrification Substitution:Battery electric powertrains eliminate engine oil demand entirely, threatening volume pools in passenger and light commercial segments where adoption curves are accelerating.
- California ZEV Mandates:The state's Advanced Clean Trucks regulation forces premature demand erosion in commercial lubricant categories before national standards align.
Strategic Opportunities
- Thermal Management Fluids:Immersion cooling and battery thermal loop applications represent white-space formulation categories with undefined API service categories and first-mover IP potential.
- Midwest Fleet Conversion:Underpenetrated agricultural and regional trucking operators in Iowa and Ohio present synthetic upgrade potential as equipment refresh cycles accelerate.
- Used Oil Re-refining:EPA hazardous waste regulations and state-level extended producer responsibility frameworks are creating circular supply chain economics for Group II base stock recovery.
Industry Challenges
- Formulation Chemistry Talent:The specialized skill set bridging tribology and electrochemistry for e-axle grease development is scarce, constraining R&D velocity for mid-tier blenders.
- API SP-RC Certification Timelines:The resource-conserving service category's test protocol complexity extends product launch windows, compressing commercialization windows against fast-moving OEM specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Automotive Lubricants Market |
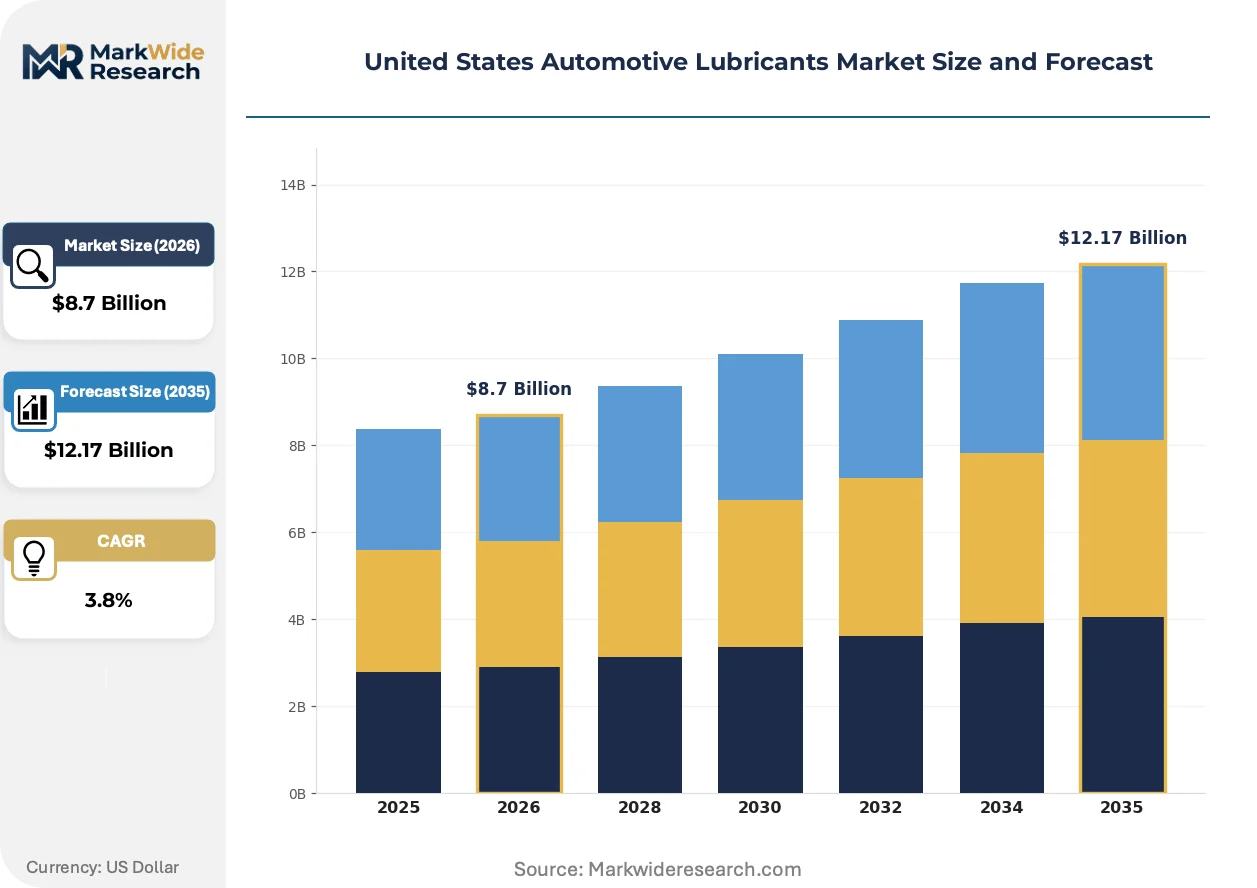
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Gear Oil End User: OEMs, Aftermarket Providers, Fleet Operators, Repair Shops Grade: Synthetic, Semi-Synthetic, Conventional, High-Mileage Packaging Type: Drums, Bottles, Pails, Bulk |
| Companies Covered | BP plc, Valvoline Inc., ExxonMobil Corporation, Fuchs Petrolub SE, Castrol (BP Castrol), Royal Dutch Shell plc, TotalEnergies, AMSOIL Inc., Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Automotive Lubricants Market Evolving Landscape
Formulation priorities are pivoting from friction reduction to thermal conductivity and electrical insulation as powertrain architectures diverge, while regulatory pressure on fuel economy compresses specification cycles.
Polyalkylene glycol-based thermal management fluids are collapsing the distinction between engine coolants and powertrain lubricants in battery electric vehicles. Tier 1 suppliers are qualifying these chemistries for immersion battery cooling and e-motor bearing lubrication simultaneously. This convergence is collapsing standalone product categories into multifunctional fluid platforms that reduce SKU complexity for OEM fill plants.
The EPA's tightened fuel economy enforcement under CAFE is forcing lubricant specification changes at 18-month intervals rather than historical 36-month cycles. OEMs are now pre-qualifying 0W-8 and 0W-12 grades for 2027 model year engines. Passenger car motor oil blenders are responding by front-loading additive development spend to maintain approved supplier lists.
Direct fleet procurement contracts are displacing distributor-mediated purchasing in Class 8 trucking and last-mile delivery segments. National logistics operators are unbundling lubricant supply from full-service maintenance agreements and negotiating standalone multi-year supply contracts with guaranteed drain interval performance. This shift is most visible in Texas and California where fleet density supports dedicated bulk delivery infrastructure.
United States Automotive Lubricants Market Segmentation
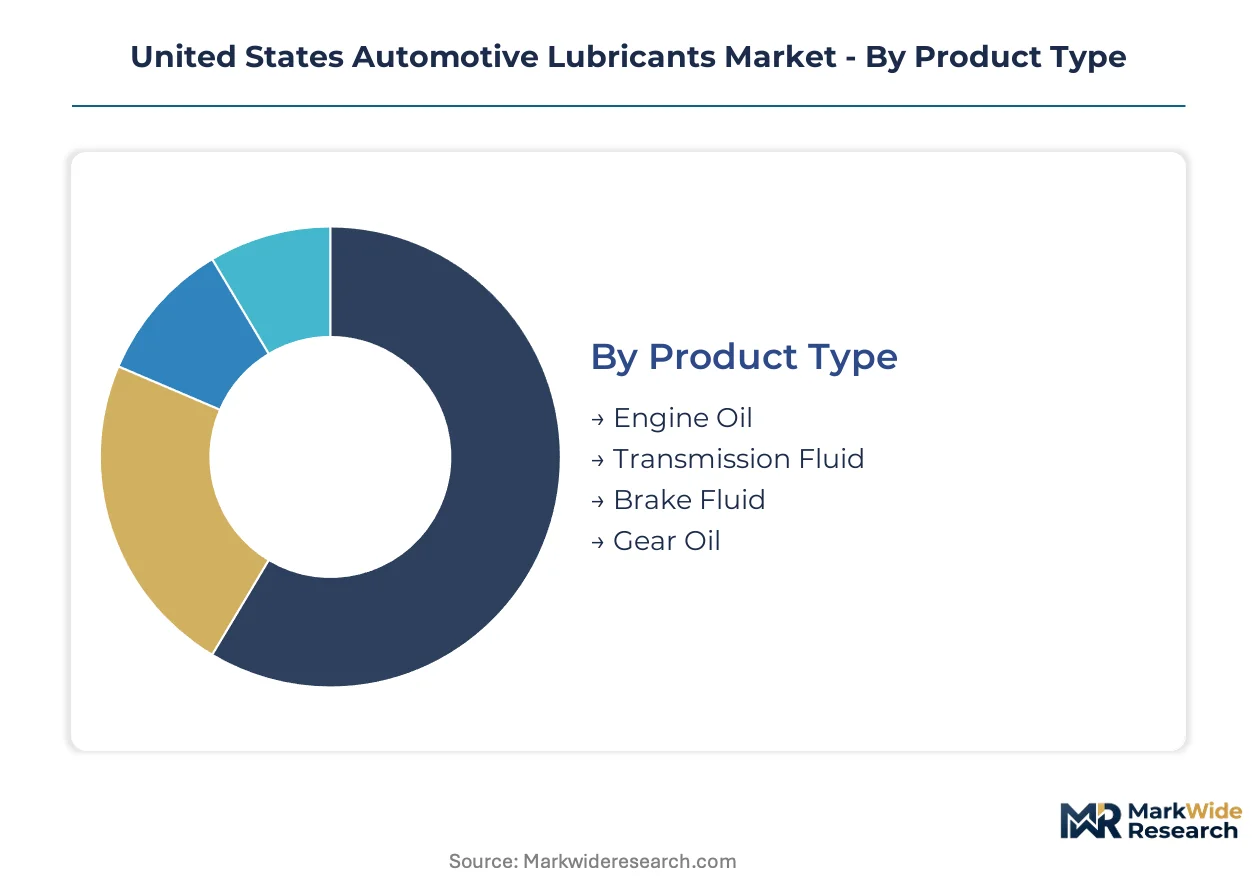
Segmentation in the United States automotive lubricants market reveals distinct service intensity profiles across product and customer dimensions. Each category carries unique margin structures and procurement behaviors that shape competitive positioning.
Product Type:
After-sales service intensity varies sharply across lubricant categories, with engine oil demanding the most frequent replacement cycles and technical support.
- Engine Oil:Formulated from base stocks and additive packages meeting SAE viscosity grades and API service categories, this segment serves internal combustion powertrains across passenger vehicles and commercial trucks. Demand concentrates in Texas oilfield logistics corridors where heavy-duty fleet density sustains high-volume consumption nodes. Fleet operators here specify long-drain synthetic formulations to compress maintenance windows.
- Transmission Fluid:Specialized lubricants engineered for torque converter and dual-clutch architectures, with OEM fill specifications diverging between automatic and manual configurations. California's centralized fleet procurement channels are pulling demand toward synthetic ATF grades that extend service intervals beyond historical benchmarks.
- Brake Fluid:Hygroscopic glycol-ether formulations meeting DOT 3, DOT 4, and DOT 5.1 specifications for hydraulic brake systems.
- Gear Oil:High-viscosity lubricants protecting differentials and manual transmissions in commercial and performance applications.
By volume, engine oil leads. By growth pace, transmission fluid is ahead.
End User:
Cost tier stratification separates premium synthetic adopters from price-sensitive conventional buyers across the customer base.
- OEMs:Original equipment manufacturers specify factory-fill lubricants during vehicle assembly, with procurement governed by CAFE compliance requirements and warranty liability frameworks. NHTSA fuel economy mandates are forcing thinner viscosity pre-qualifications at 18-month specification cycles rather than historical 36-month windows.
- Fleet Operators:National logistics and regional trucking companies consolidating procurement around standalone multi-year supply contracts with guaranteed drain interval performance. Texas and California fleet density supports dedicated bulk delivery infrastructure that bypasses traditional distributor networks.
- Aftermarket Providers:Independent retailers and jobbers serving DIY consumers and small repair facilities through packaged goods distribution.
- Repair Shops:Service bay operators selecting lubricants based on technician familiarity and inventory turnover velocity.
Fleet operators are gaining share fastest. OEMs retain the largest absolute volume position.
Grade:
Application severity determines grade selection, with synthetic formulations commanding premium positioning in high-stress operating environments.
- Synthetic:Manufactured from Group III, Group IV, or Group V base stocks delivering superior thermal stability and extended drain intervals. Permian Basin petrochemical clusters and California's low-emission vehicle corridors are concentrating adoption as OEMs specify 0W-8 and 0W-12 grades for compliance.
- High-Mileage:Formulations with seal conditioners and anti-wear additives targeting vehicles exceeding 75,000 miles, occupying a profitable niche as the national vehicle fleet ages.
- Semi-Synthetic:Blended products combining synthetic and conventional base stocks for mid-market positioning.
- Conventional:Mineral oil-based lubricants facing margin compression as specification standards tighten.
Synthetic grades lead by revenue contribution. High-mileage formulations are climbing the fastest.
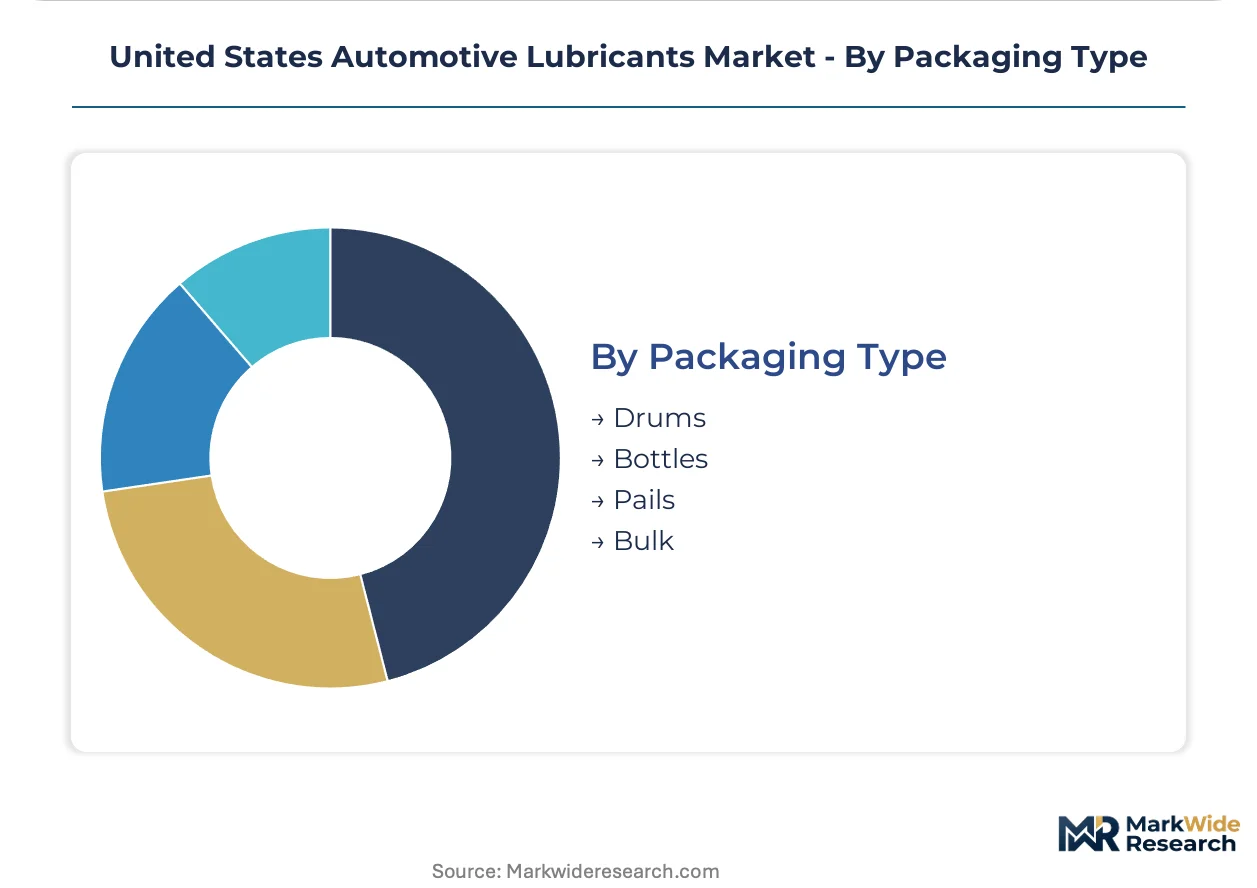
Packaging Type:
Volume scale and customer type dictate packaging economics, with bulk infrastructure requiring dedicated logistics investment.
- Bulk:Tanker and tote deliveries serving high-throughput fleet maintenance facilities and OEM fill plants. Iowa and Ohio agricultural operators present underpenetrated conversion potential as equipment refresh cycles accelerate.
- Drums:55-gallon containers for industrial maintenance bays and mid-size fleet operations.
- Bottles:Retail-packaged quarts and gallons for aftermarket DIY and small repair shop channels.
- Pails:Five-gallon containers bridging bulk and retail volume tiers for specialty applications.
Bulk packaging dominates fleet procurement. Bottles retain the widest customer reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and petrochemical infrastructure concentrate lubricant demand in distinct regional clusters across the United States. Each sub-region exhibits unique procurement patterns tied to local industrial composition and regulatory exposure.
Texas
Permian Basin oilfield logistics fleets and Gulf Coast petrochemical manufacturing sustain the densest lubricant consumption nodes nationally. EPA fuel economy enforcement under CAFE pulls OEM specification activity toward Houston-area technical centers. Midland-Odessa heavy-duty fleet density supports dedicated bulk blending capacity that bypasses traditional distribution layers.
California
CARB's Advanced Clean Trucks regulation accelerates electrification timelines that fragment traditional engine oil demand into thermal management categories. Centralized fleet procurement in Los Angeles and San Francisco logistics corridors consolidates purchasing around long-drain synthetic contracts. Sacramento's regulatory gravity filters low-emission vehicle requirements into national formulation standards.
Midwest
Agricultural equipment operators in Iowa and Ohio present underpenetrated synthetic conversion potential as machinery refresh cycles accelerate. NHTSA fuel economy mandates reach into Detroit-area OEM technical centers where 0W-8 and 0W-12 pre-qualification activity concentrates. Chicago's rail and intermodal logistics infrastructure sustains regional bulk distribution economics.
Southeast
Atlanta's last-mile delivery fleet density supports standalone multi-year supply contracts that displace distributor-mediated purchasing. Florida's aging vehicle fleet expands high-mileage formulation demand among independent repair channels. Port logistics activity in Savannah and Charleston sustains commercial trucking lubricant throughput.
United States Automotive Lubricants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that rewards either distribution density or formulation performance. Integrated refiners leverage captive base stock supply against independent blenders who anchor positions through service bay relationships or severe-duty specialization. Three archetypes dominate: vertically integrated energy majors, quick-lube service network operators, and premium synthetic specialists. Competitive moves cluster around strategic partnerships with fleet procurement departments and portfolio diversification into thermal management fluids.
Among the integrated energy majors, ExxonMobil Corporation and BP plc exemplify the refiner-blender archetype that controls upstream base stock supply. Valvoline Inc. occupies the service-channel position, while AMSOIL Inc. anchors the premium synthetic specialist tier focused on severe-duty performance guarantees rather than price competition.
| Leading Market Players |
|---|
| BP plc |
| Valvoline Inc. |
| ExxonMobil Corporation |
| Fuchs Petrolub SE |
| Castrol (BP Castrol) |
| Royal Dutch Shell plc |
| TotalEnergies |
| AMSOIL Inc. |
| Chevron Corporation |
| Others |
Value Network & Pricing Analysis
Gulf Coast petrochemical clusters around Houston anchor domestic base stock capacity, with refinery run rates and Group III output volumes directly transmitting into blenders' feedstock cost positions and downstream pricing power.
Pricing Analysis
Cost-plus contracts indexed to Group II and Group III base oil spot markets dominate procurement between refiners and synthetic blenders. Price differentiation rests on viscosity grade certification and volume scale, with OEM fill contracts commanding premiums over aftermarket channels. Pricing pressure intensifies in conventional mineral oil tiers as CAFE-driven specification upgrades compress demand. Fleet operators exhibit the lowest price sensitivity due to total-cost-of-ownership calculations, while independent repair shops remain the most price-responsive segment.
Supply Chain Analysis
Supplier-financing instruments including 90-day extended payment terms and supply-chain finance facilities have become standard between base oil producers and mid-tier blenders facing working capital constraints. Geographic supply concentration draws from United States Gulf Coast refineries, Canadian oil sands upgraders, and Korean Group III export terminals. Raw material dependencies center on high-viscosity-index base stocks, polyalphaolefin feedstocks, and specialized additive packages. Single-source vulnerability in PAO supply creates structural risk. Distribution runs through dedicated bulk terminals serving fleet maintenance facilities alongside packaged goods channels for aftermarket retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation in Texas and California logistics corridors has shifted bargaining power toward centralized buyers, fragmenting historical distributor-mediated purchasing patterns and compressing margin capture for incumbent suppliers.
For Market Incumbents: Insulate core positions through backward integration into captive base stock production and dedicated technical service teams embedded at fleet maintenance facilities. Electrification substitution in passenger segments threatens volume pools; priority investment in thermal management fluid R&D addresses emerging OEM specification requirements. Channel control through quick-lube bay density retains defensive value against direct procurement trends. For New Entrants and Emerging Players: Agricultural equipment operators in Iowa and Ohio represent the most penetrable entry point for synthetic conversion campaigns targeting machinery refresh cycles. Immersion cooling formulations for battery electric commercial vehicles offer white-space formulation categories lacking established API service categories. Go-to-market execution should anchor on regional blending partnerships with existing bulk terminal infrastructure rather than greenfield capacity investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty blenders with demonstrated e-axle grease qualification capabilities and established fleet direct relationships. Long-term viability across the analysis window hinges on portfolio diversification beyond internal combustion engine lubricants. The signal to watch is OEM pre-qualification activity for 0W-8 and 0W-12 grades as an inflection indicator for specification cycle compression and additive development spend intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Management Fluid Development | Immersion cooling qualifications with Tesla and Rivian anchor next-generation revenue pools. |
| Fleet Direct Supply Contracting | Multi-year agreements with Schneider National bypass distributor markups and secure volume commitments. |
| Re-refining Capacity Investment | Used oil recovery facilities in Texas align with EPA hazardous waste regulations and circular supply economics. |
| Additive Package Specialization | Custom friction modifier development for 0W-8 pre-qualification meets NHTSA CAFE compliance timelines. |
| Quick-Lube Service Network Expansion | Bay density in California last-mile corridors defends against Amazon Fleet direct procurement displacement. |
Research Methodology
The analysis maps engine oil, transmission fluid, and thermal management categories, each validated through procurement directors at national fleet operators, OEM lubricant specification engineers, and aftermarket distribution executives. Primary fieldwork combined structured interviews with secondary validation against EPA regulatory filings, NHTSA CAFE compliance databases, American Petroleum Institute certification records, and base oil trade flow data. Bottom-up volume builds across product grades triangulated against top-down market sizing from petrochemical production statistics.
Assumptions held fixed include NHTSA fuel economy enforcement timelines and California Air Resources Board zero-emission vehicle mandate trajectories, while electrification adoption curves and fleet replacement cycles were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, grade tier, end-user channel, and regional production cluster. CAGRs derive from regression analysis of historical specification change intervals and OEM pre-qualification activity. Forecast inputs include Permian Basin fleet density projections and agricultural equipment refresh cycle timing.
Practitioners should monitor revision triggers including EPA enforcement discretion shifts and battery electric vehicle sales penetration inflections for early signals of demand trajectory change. Forecasts reflect documented assumptions regarding regulatory continuity and technology substitution rates. Macroeconomic recession impacting fleet capital expenditure, accelerated ZEV mandate adoption, or breakthrough solid-state battery commercialization would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Israel Lubricants Market
Lubricants
Global Grease Cartridges Market
Lubricants
Synthetic Lubricants Market
Lubricants
Brazil Lubricants Market
Lubricants
Hydro Lubricants Market
Lubricants
Spain Automotive Engine Oils Market
Lubricants
Global Grease Market
Lubricants
Global Lubricant Anti Wear Agents Market
Lubricants
Global Friction Modifiers Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Construction Lubricants Market
Lubricants
Bio-Based Lubricants Market
Lubricants
Mexico Automotive Lubricants Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market