
 Saudi Arabia Commercial Vehicles Lubricants Market | 2026-2036
Saudi Arabia Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Commercial Vehicles Lubricants Market Analytics
SASO's updated lubricant quality standards is restructuring the competitive landscape for commercial vehicle oils in Saudi Arabia. Petromin Corporation leverages its domestic blending infrastructure and state-backed distribution reach to anchor its position across fleet service contracts. ExxonMobil Corporation competes through advanced synthetic formulations engineered for desert operating conditions. FUCHS specializes in high-performance hydraulic oils tailored to construction equipment deployed in NEOM and Red Sea Project sites.
Commercial vehicles lubricants are formulated mixtures of base oils and performance additives designed to reduce friction, dissipate heat, and prevent wear in engines, transmissions, and hydraulic systems operating under severe load cycles. Viscosity grades such as SAE 15W-40 and API CK-4 define thermal stability thresholds critical for turbocharged diesel engines in prolonged desert haulage. Engine oil commands the largest volume share given mandatory drain intervals for heavy-duty fleets, while synthetic formulations capture expanding margin pools as OEM specifications tighten. Mineral lubricants still dominate in price-sensitive segments serving older vehicle populations and secondary operators.
SASO enforces additive package disclosures and base oil categorization under its lubricant technical regulations, while the Saudi Energy Efficiency Center mandates fuel economy labeling that indirectly favors lower-viscosity synthetic products. SFDA oversight extends to workplace exposure limits during bulk handling and fleet maintenance operations. Stakeholders must monitor how SASO's anticipated alignment with ACEA and API sequences reshapes import certification burdens and local blending requirements.
Market Dynamics
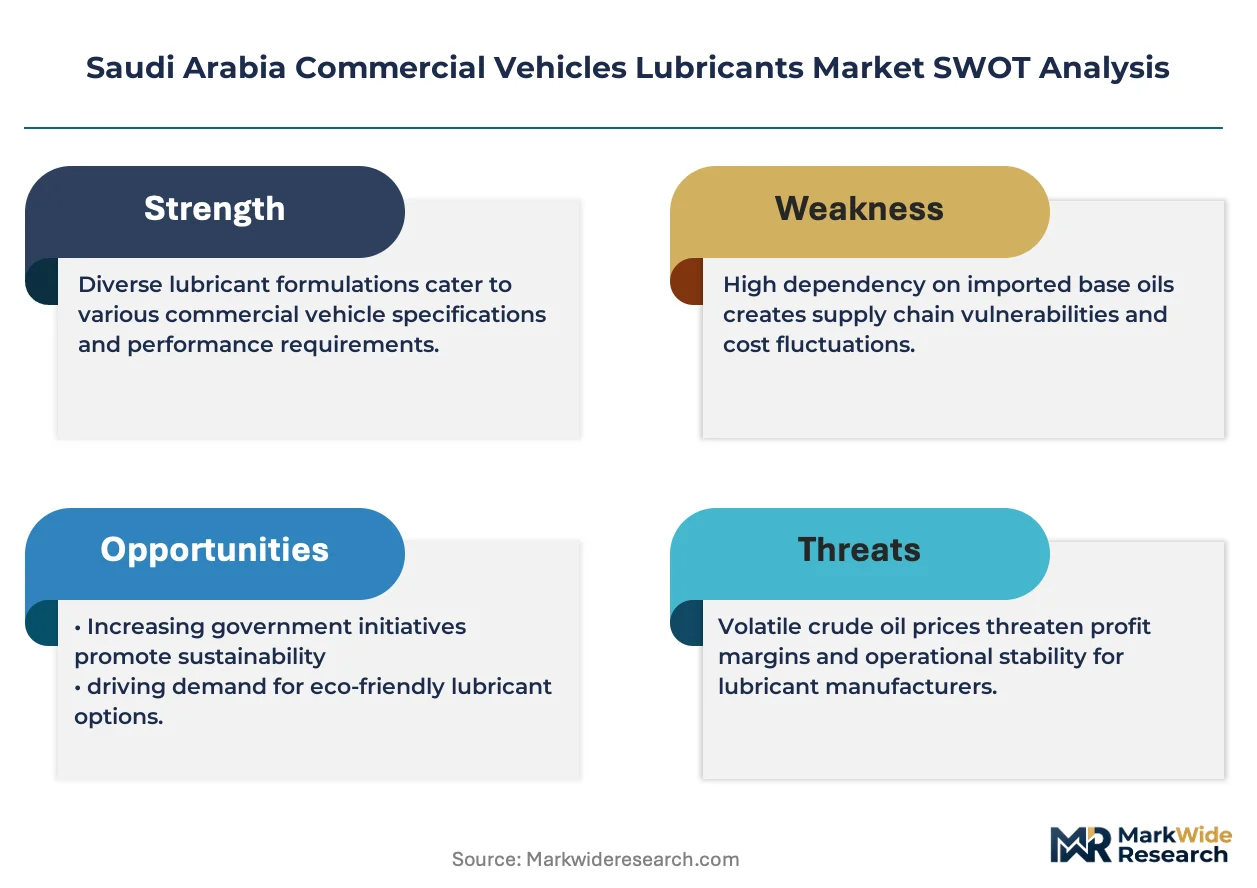
Fleet operators across Saudi Arabia's logistics corridors are extending oil drain intervals for heavy-duty trucks, compressing lubricant consumption volumes per vehicle while elevating product performance specifications. This operational shift is colliding with tightening SASO quality standards and SFDA workplace exposure mandates.
Growth Catalysts
- NEOM Infrastructure Buildout:Construction equipment fleets at the Red Sea Project and NEOM sites require specialized hydraulic and transmission fluids formulated for extreme desert duty cycles.
- SASO Quality Harmonization:Alignment with ACEA and API sequences is elevating import certification barriers, favoring domestic blenders with established testing infrastructure.
- Extended Drain Intervals:Synthetic formulations enabling 50,000+ kilometer service cycles are penetrating fleet maintenance contracts across the Eastern Province freight corridors.
Market Restraints
- Base Oil Import Dependency:Saudi Arabia lacks domestic Group II/III base oil production, exposing blenders to freight cost volatility from Asian and European suppliers.
- Price-Sensitive Secondary Operators:Older vehicle populations in the Kingdom's informal transport sector resist premium synthetic pricing, anchoring mineral oil volumes.
- SASO Certification Timelines:Extended laboratory testing protocols for new additive packages delay product launches by 8-14 months.
Strategic Opportunities
- Western Province Logistics Hubs:Jeddah Islamic Port expansion and King Abdullah Economic City freight zones remain underpenetrated relative to Eastern Province density.
- Fuel Economy Labeling Mandates:Saudi Energy Efficiency Center requirements are creating preference pull for lower-viscosity synthetics in fleet procurement tenders.
- Digital Fleet Management Integration:Telematics-enabled oil condition monitoring is opening subscription-based lubricant supply contracts linked to actual equipment wear.
Industry Challenges
- Additive Chemist Shortage:Domestic talent pipelines lack formulation specialists capable of optimizing packages for high-sulfur diesel combustion residues prevalent in Saudi fleet operations.
- SFDA Bulk Handling Compliance:Workplace exposure limit enforcement during depot maintenance operations requires capital investment in closed-loop dispensing systems.
- Legacy Fleet Heterogeneity:Mixed-age truck populations complicate inventory planning for service providers managing API CI-4 through CK-4 specification ranges simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Commercial Vehicles Lubricants Market |
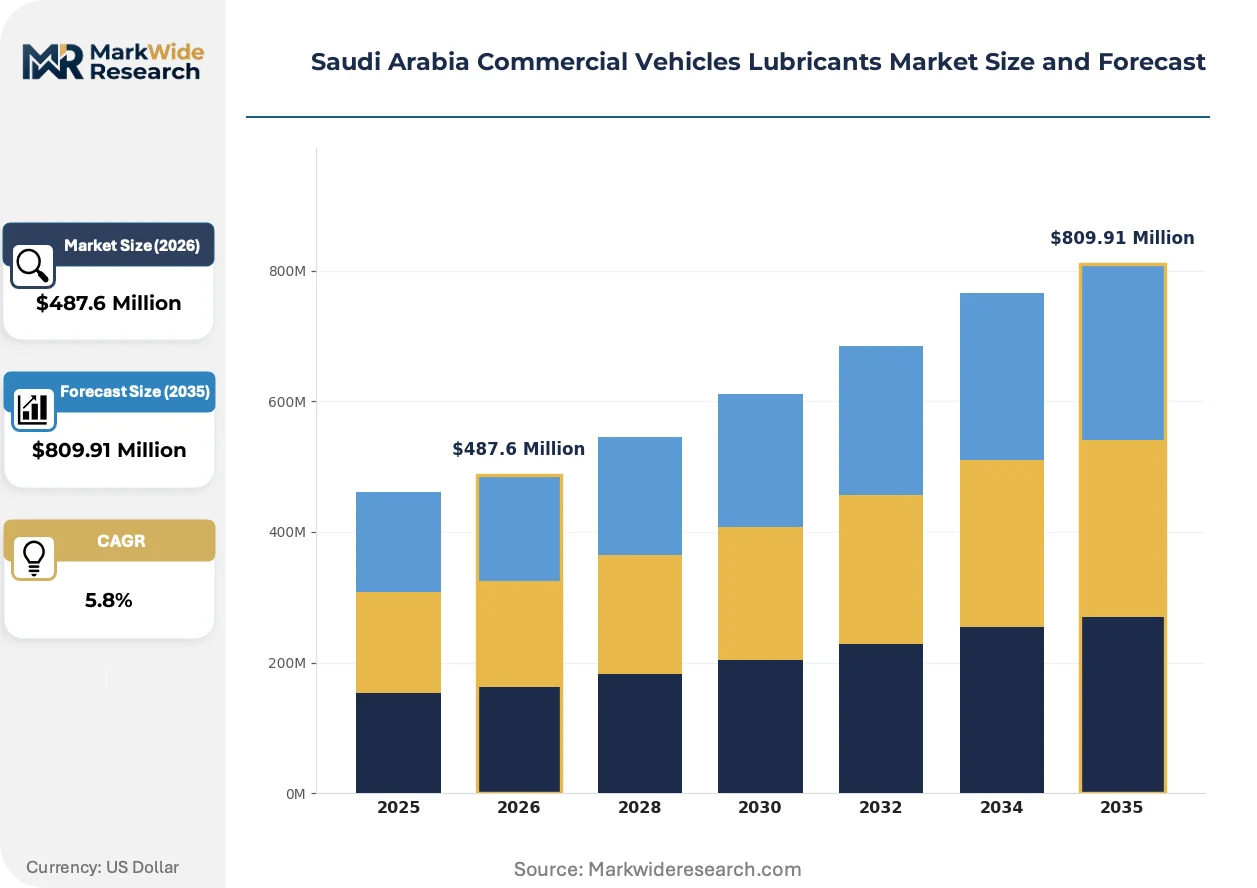
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Hydraulic Oil End User: Logistics Companies, Public Transport, Construction Firms, Freight Operators Formulation: Synthetic, Semi-Synthetic, Mineral, Bio-Based Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Petromin Corporation, Saudi Aramco, Al-Jomaih and Shell Lubricating Oil Company, TotalEnergies Marketing Saudi Arabia, BP plc, ExxonMobil Corporation, FUCHS, Castrol, Gulf Oil Middle East Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Commercial Vehicles Lubricants Market Evolving Landscape
Synthetic lubricant chemistry and digital service integration are converging to redefine how commercial vehicle fluids are specified, procured, and consumed across Saudi Arabia's freight economy. Three developments are compressing traditional supply relationships.
Low-viscosity synthetic formulations are rewriting fleet maintenance economics. SAE 5W-30 and 0W-40 grades engineered for turbocharged diesel thermal management are capturing specification share in OEM service-fill agreements. Saudi Aramco-backed fleet operators are piloting these chemistries for long-haul corridor operations between Riyadh and Dammam.
SASO's lubricant technical regulations are tightening additive disclosure requirements. The standards body now mandates base oil categorization and performance testing documentation that mirrors evolving ACEA sequences. Importers without domestic blending capabilities face escalating compliance costs and extended certification timelines.
Telematics-enabled condition monitoring is displacing fixed-interval drain schedules. Fleet managers at Jubail industrial zone operators are adopting oil analysis subscriptions that trigger replacement based on oxidation and soot loading rather than calendar mileage. This consumption-pattern shift compresses volume predictability for traditional distributor relationships.
Saudi Arabia Commercial Vehicles Lubricants Market Segmentation
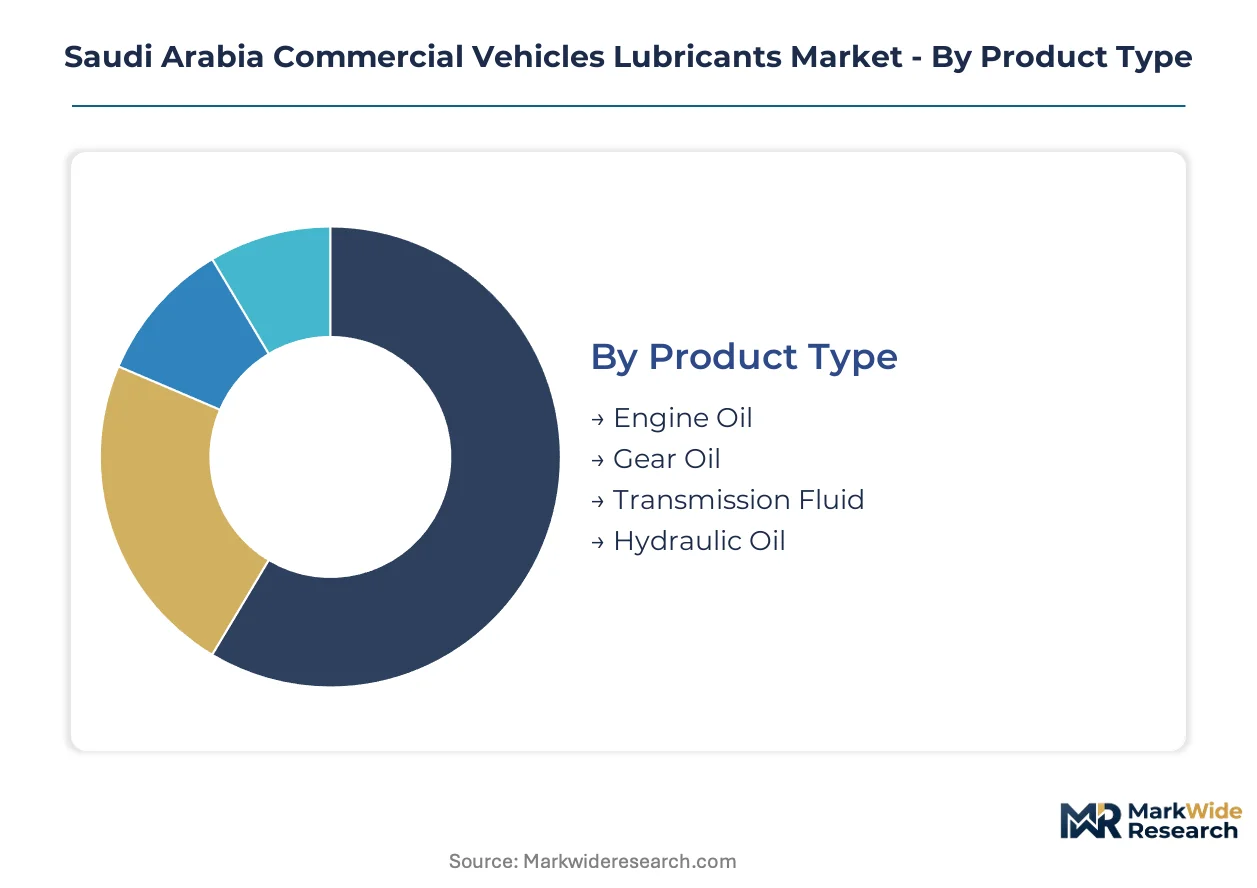
Saudi Arabia's commercial vehicles lubricants market fragments across four critical dimensions that determine procurement patterns and margin structures. Fleet operators, construction contractors, and logistics providers each trigger distinct specification requirements and channel preferences.
Product Type:
Technical specifications and drain interval economics drive product selection across Saudi Arabia's heavy-duty fleet base.
- Engine Oil:Formulated with API CK-4 additive packages for turbocharged diesel thermal management under prolonged desert haulage. Jubail and Dammam logistics corridors concentrate demand as fleet operators extend service intervals beyond 50,000 kilometers, elevating synthetic penetration in procurement tenders.
- Hydraulic Oil:High-viscosity index formulations engineered for construction equipment deployed at NEOM and Red Sea Project sites. Extreme duty cycles and dust contamination risks at these gigaprojects create specification pull for zinc-free anti-wear chemistries.
- Gear Oil:Hypoid gear lubricants meeting API GL-5 standards for commercial vehicle differentials operating under severe load conditions.
- Transmission Fluid:Automated manual transmission fluids formulated for synchronized shifting in long-haul trucks traversing Riyadh-Dammam freight corridors.
Engine Oil leads on scale; Hydraulic Oil leads on momentum.
End User:
Customer-type economics segment the market between contracted fleet operators and project-based equipment deployers.
- Freight Operators:Long-haul trucking fleets managing Riyadh-Dammam and Eastern Province corridor operations. These operators negotiate volume-based supply agreements with domestic blenders, prioritizing extended drain synthetic formulations to minimize downtime across high-utilization assets.
- Construction Firms:Equipment fleets deployed at NEOM, Red Sea Project, and King Abdullah Economic City sites. Project timelines and equipment heterogeneity create spot procurement patterns favoring hydraulic and transmission fluid bundles from distributors with on-site logistics capabilities.
- Logistics Companies:Third-party fleet managers serving retail and industrial supply chains with mixed-age truck populations requiring CI-4 through CK-4 specification ranges.
- Public Transport:Municipal bus fleets operating under Saudi Energy Efficiency Center fuel economy mandates that favor lower-viscosity synthetic engine oils.
Freight Operators anchor volume concentration; Construction Firms generate the steepest specification escalation.
Formulation:
Base oil chemistry and additive investment tiers stratify the market across performance and price sensitivity axes.
- Synthetic:Group III and PAO base stocks with advanced dispersant and antioxidant packages enabling 50,000+ kilometer drain intervals. SASO alignment with ACEA sequences is accelerating specification capture in OEM service-fill agreements and premium fleet contracts.
- Mineral:Group I base oils serving older vehicle populations and secondary operators in Saudi Arabia's informal transport sector. Price resistance anchors volumes despite tightening emissions standards.
- Semi-Synthetic:Blended formulations targeting mid-tier fleet operators balancing performance requirements against per-liter cost constraints.
- Bio-Based:Ester and vegetable-derived base stocks with biodegradability credentials for environmentally sensitive project sites and SFDA workplace exposure compliance.
Synthetic formulations command margin leadership; Mineral lubricants retain volume anchoring.
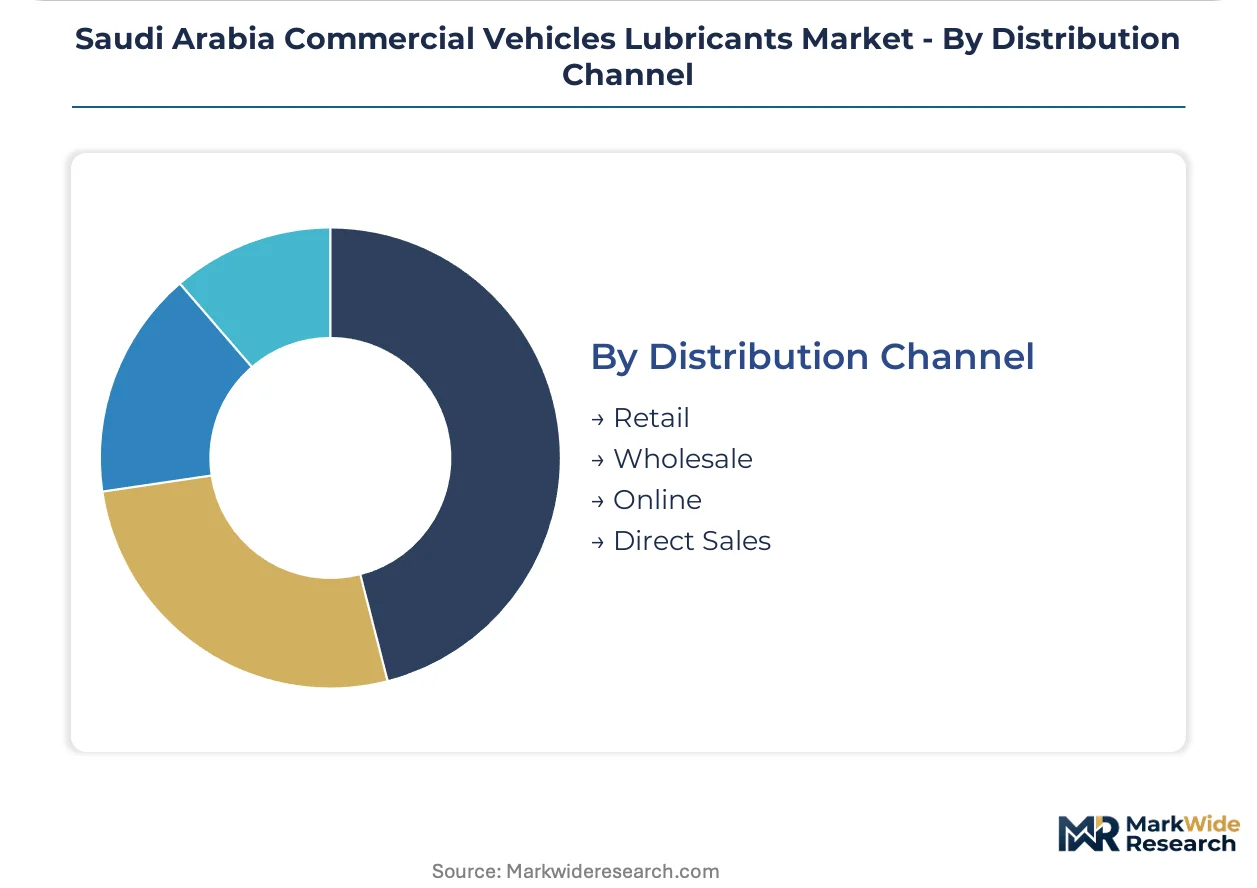
Distribution Channel:
Channel structure reflects fleet scale, procurement centralization, and service integration requirements.
- Direct Sales:Manufacturer-to-fleet supply relationships dominating large logistics operators and Aramco-affiliated transport divisions. These contracts bundle lubricant supply with oil analysis subscriptions and telematics-enabled condition monitoring across Eastern Province freight corridors.
- Wholesale:Distributor networks serving independent service stations and secondary fleet operators with bulk storage and delivery logistics. SASO certification documentation flows through these intermediaries for import-dependent blenders.
- Retail:Service station and parts counter sales targeting owner-operators and small fleet maintenance shops.
- Online:E-procurement platforms emerging for standardized specification products with predictable replenishment cycles.
Direct Sales concentrates value capture; Wholesale maintains reach breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's lubricant formulation specialists and fleet maintenance engineers concentrate in the Eastern Province's industrial corridor, anchoring technical service capacity for heavy-duty commercial vehicle operations.
Eastern Province
Jubail's petrochemical complexes and Dammam's King Abdulaziz Port generate concentrated demand for API CK-4 engine oils serving container haulage and bulk freight fleets. SASO's lubricant technical regulations mandate additive package disclosures that domestic blenders navigate through established testing partnerships. The Dammam-Riyadh freight corridor anchors the Kingdom's highest lubricant consumption density per kilometer of highway infrastructure.
Riyadh
Central Saudi Arabia's logistics operators manage mixed-age truck populations requiring simultaneous CI-4 and CK-4 specification inventories. The Saudi Energy Efficiency Center's fuel economy labeling mandates create procurement preference for lower-viscosity synthetics in municipal bus and government fleet tenders. Riyadh's King Khalid International Airport freight zone concentrates cold-chain logistics operators with specialized transmission fluid requirements.
Western Region
Jeddah Islamic Port expansion and King Abdullah Economic City development generate underpenetrated demand relative to Eastern Province density. Construction equipment fleets at Red Sea Project sites require zinc-free hydraulic oils formulated for extreme dust contamination cycles. Makkah Province's pilgrimage transport operators maintain seasonal surge capacity with mineral oil inventories for older vehicle populations.
NEOM Northwest
The linear city's construction equipment deployments operate on specialized duty cycles demanding high-viscosity index hydraulic formulations. SFDA workplace exposure compliance during bulk handling operations requires closed-loop dispensing infrastructure investment at remote site depots. NEOM's sustainability mandates create specification pull for bio-based lubricants in environmentally sensitive coastal zones.
Asir and Southern Regions
Mountain corridor trucking between Abha and Jazan faces thermal management challenges distinct from desert operations, elevating demand for synthetic formulations with enhanced oxidation stability. Secondary operators in the informal transport sector anchor mineral oil volumes despite tightening emissions standards. Border logistics serving Yemen and Red Sea shipping lanes concentrate lubricant consumption at Najran and Jazan depot facilities.
Saudi Arabia Commercial Vehicles Lubricants Market Competitive Landscape
The competitive structure tilts toward state-affiliated domestic blenders with captive distribution infrastructure. Market concentration reflects the dominance of integrated petroleum producers and licensed joint ventures with international majors. Three archetypes define positioning: national oil company affiliates with refinery-linked supply chains, global lubricant specialists competing through synthetic formulation portfolios, and regional distributors serving spot procurement patterns. Capacity expansion in domestic blending facilities and strategic partnerships for additive technology licensing represent the dominant competitive vectors.
Within the state-affiliated tier, Petromin Corporation and Saudi Aramco exemplify domestic blending dominance through integrated supply chains and fleet service contract anchoring. Among international specialists, ExxonMobil Corporation and FUCHS occupy positions defined by advanced synthetic chemistries and construction equipment specialization. Al-Jomaih and Shell Lubricating Oil Company represents the joint-venture archetype combining international formulation expertise with established local distribution reach.
| Leading Market Players |
|---|
| Petromin Corporation |
| Saudi Aramco |
| Al-Jomaih and Shell Lubricating Oil Company |
| TotalEnergies Marketing Saudi Arabia |
| BP plc |
| ExxonMobil Corporation |
| FUCHS |
| Castrol |
| Gulf Oil Middle East Limited |
| Others |
Value Network & Pricing Analysis
Fleet procurement tenders mandating extended drain intervals and API CK-4 certification are compressing mineral oil margins while elevating synthetic premiums. Domestic blenders with captive testing infrastructure capture pricing power as SASO compliance timelines stretch import certification cycles.
Pricing Analysis
Bundled service contracts combining lubricant supply with oil analysis subscriptions command 15-25% premiums over unbundled transactional sales. Three-tier pricing structure across premium synthetics, standard semi-synthetics, and economy mineral grades stratifies the market by drain interval performance and OEM approval status. Cost compression in the mineral tier intensifies as secondary operators resist specification upgrades. Construction firms at NEOM sites exhibit lowest price sensitivity due to equipment downtime costs, while informal transport operators in southern regions anchor volume at economy tiers.
Supply Chain Analysis
Dual-sourcing requirements from Aramco-affiliated fleet operators mandate qualification of at least two additive package suppliers, fragmenting procurement concentration. Base oil feedstocks draw from South Korea, Singapore, and the UAE, with Group II/III grades dominating synthetic formulation inputs. Additive chemistries rest on Lubrizol, Infineum, and Afton supply agreements. Single-source vulnerability concentrates in specialized hydraulic oil packages for desert construction duty. Distribution runs through domestic blending facilities at Jubail and Riyadh, with wholesale networks extending to Jeddah and NEOM site depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's lubricant market functions as a geographic-arbitrage play where domestic blending capacity captures margin pools that leak to importers in neighboring Gulf states lacking comparable SASO-aligned infrastructure.
For Market Incumbents: Acquire additive formulation laboratories to compress SASO certification timelines from 14 months toward 6-8 months. Backward integration into Group III base oil supply through offtake agreements with UAE and South Korean refiners reduces freight cost volatility. Defensive positioning requires locking 3-5 year fleet service contracts before API FA-4 specifications displace CK-4 in OEM service-fill agreements.
For New Entrants and Emerging Players: E-procurement platforms targeting standardized CI-4 mineral specifications offer the lowest barrier to fleet penetration. Western Province logistics hubs around Jeddah Islamic Port remain underpenetrated relative to Eastern Province density. White-space capture demands on-site logistics capabilities for construction equipment fluid bundles at Red Sea Project sites, with telematics-enabled condition monitoring subscriptions as the anchor go-to-market wedge.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier domestic blenders possessing SASO certification infrastructure but lacking international brand equity. Long-term viability hinges on positioning for synthetic formulation share capture as OEM specifications tighten and drain intervals extend. The signal to watch is Aramco fleet pilot adoption of SAE 5W-30 grades for Riyadh-Dammam corridor operations, which would accelerate specification displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captures margin pools currently leaking to Singapore and South Korean refiners through long-term offtake structures. |
| Telematics-Enabled Condition Monitoring Launch | Transforms transactional lubricant sales into subscription revenue anchored to actual equipment wear patterns. |
| Western Province Distribution Expansion | Addresses underpenetrated Jeddah and King Abdullah Economic City freight zones relative to Eastern Province density. |
| Bio-Based Lubricant Certification Investment | Positions for NEOM sustainability mandates and SFDA workplace exposure compliance in environmentally sensitive coastal zones. |
| Additive Package Laboratory Acquisition | Compresses SASO certification timelines from 14 months toward 6-8 months for new product launches. |
Research Methodology
Multiple input streams — fleet maintenance director interviews, blender procurement lead discussions, and distributor operational assessments — were reconciled against customs trade data, SASO regulatory filings, and Aramco fleet specification disclosures. Primary fieldwork captured maintenance contract structures across Eastern Province logistics corridors and NEOM construction equipment deployment patterns. Secondary validation drew from Saudi Energy Efficiency Center fuel economy labeling databases, API licensing records, and base oil import manifests. Bottom-up volume estimates from fleet operator consumption rates were triangulated against top-down blender production capacity assessments.
Data-stream reconciliation across the projection horizon applied segment-specific growth drivers: synthetic penetration rates by fleet size tier, mineral oil retention in informal transport sectors, and hydraulic oil intensity per construction equipment hour. Modeled dimensions spanned product type, end-user category, formulation chemistry, and distribution channel. CAGRs were derived from equipment fleet expansion trajectories, drain interval extension elasticities, and specification upgrade adoption curves. Forecast inputs incorporated NEOM construction phase transitions, Jeddah Islamic Port throughput expansion, and SASO-ACEA alignment implementation pacing.
The model assumes a particular technology adoption path; alternative pathways for low-viscosity synthetic engine oils would alter the outlook if OEM service-fill specifications accelerate beyond current fleet pilot timelines. Forecasts reflect assumptions regarding base oil import cost stability and additive chemist talent pipeline development. Deviation in SASO certification timeline enforcement or Aramco fleet procurement centralization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Brazil Lubricants Market
Lubricants
Jordan Lubricants Market
Lubricants
Spain Automotive Engine Oils Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
US Industrial Lubricants Market
Lubricants
Poland Metalworking Fluids Market
Lubricants
Spain Automotive Lubricants Market
Lubricants
ASEAN Lubricants Market
Lubricants
Global Friction Modifiers Market
Lubricants
Automotive Die Casting Lubricants Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Malaysia Automotive Lubricants Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
Biolubricants Market
Lubricants
Sri Lanka Lubricants Market