
 North America and Europe Forestry Lubricants Market | 2026-2036
North America and Europe Forestry Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Forestry Lubricants Market Analysis
Aging certified lubrication technicians is collapsing across Nordic and Appalachian forestry equipment fleets. Fuchs Petrolub SE leverages its Stuttgart technical center to sustain specialized grease portfolios for extreme cold-weather skidders. Shell Plc dominates biodegradable hydraulic oil distribution through direct mill supply contracts in British Columbia and Finland. Frontier Performance Lubricants Inc. anchors its position with biodegradable chain saw lubricants formulated for Pacific Northwest old-growth harvesting conditions.
North America and Europe forestry lubricants are formulated products engineered to withstand high-pressure hydraulic systems, extreme ambient temperature swings, and prolonged exposure to wood sap and silica dust in mechanized timber harvesting. These fluids typically incorporate zinc-free anti-wear additives and ester-based base oils to meet OEM warranty requirements for harvesters and forwarders while preventing soil contamination in sensitive watershed zones. Hydraulic oils command the largest volume share across both regions due to the proliferation of high-tonnage wheeled harvesters, though biodegradable lubricants represent the fastest-expanding margin pool as forestry contractors face tightening environmental permit conditions. Greases for centralized lubrication systems on booms and grapple attachments occupy a mature but stable segment tied to equipment replacement cycles rather than fleet expansion.
EPA VGP permitting in the United States and the EU Ecolabel framework in Europe are reshaping product registration requirements for lubricants used near water bodies, forcing reformulation of traditional mineral-based chain bar oils. REACH substance restrictions and state-level forestry best-management-practice codes in Oregon and Washington further narrow the acceptable additive chemistry palette for equipment operating on public timber leases. Stakeholders must monitor evolving biodegradability certification thresholds and OEM fluid specification updates to avoid stranded inventory positions when regulatory deadlines activate.
Market Dynamics
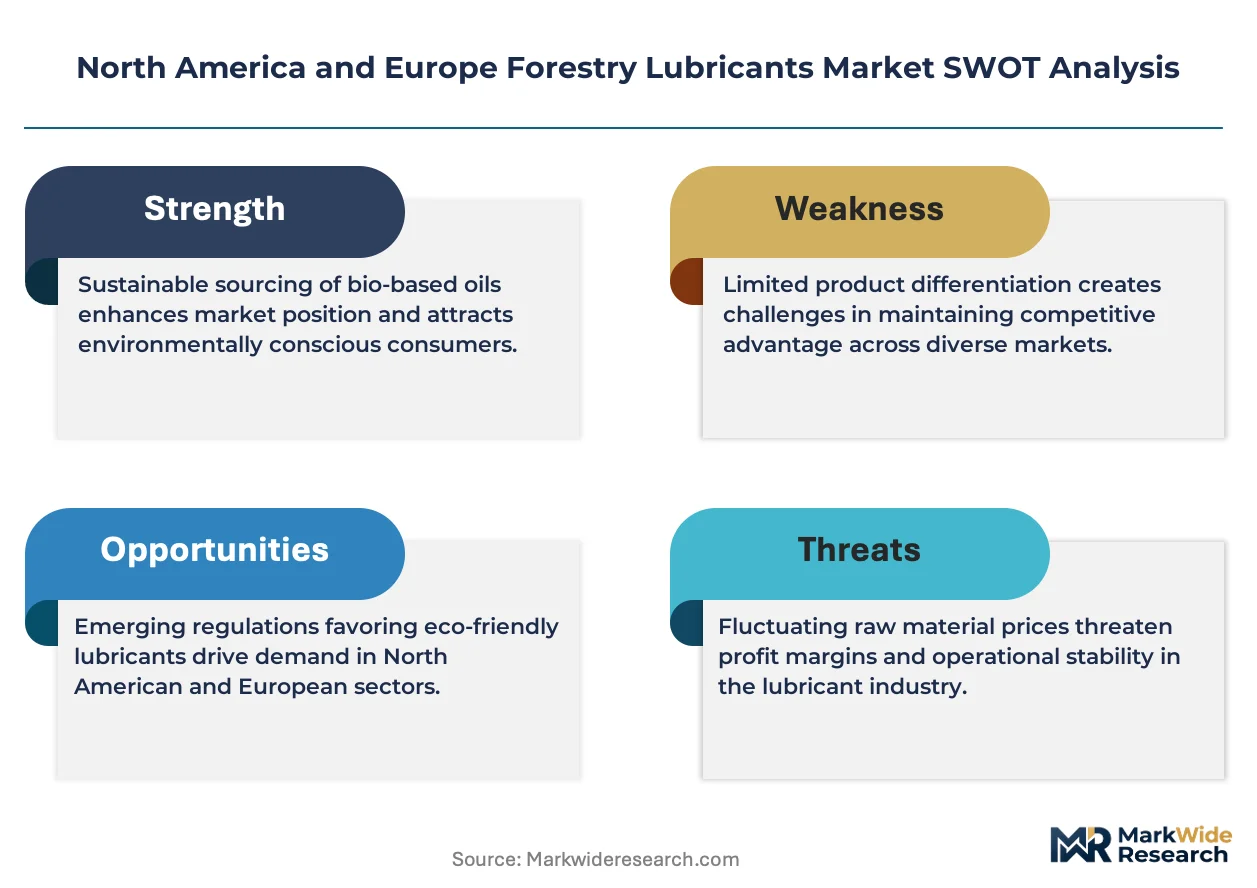
EU F-Gas Regulation and EPA VGP permitting are forcing simultaneous reformulation of hydraulic and chain bar oil portfolios, collapsing the viable chemistry palette for legacy mineral-based products while opening margin pools for ester-based alternatives.
Growth Catalysts
- REACH substance restrictions:Phased bans on zinc-based anti-wear additives in European forestry equipment are redirecting R&D spending toward ashless additive packages that satisfy OEM warranty terms.
- Pacific Northwest old-growth harvesting:British Columbia and Oregon coastal contractors face watershed protection mandates that require immediate biodegradable lubricant conversion for equipment operating near salmon-bearing streams.
- Centralized lubrication systems:Automated grease delivery on high-tonnage harvester booms reduces manual servicing intervals and extends component life in Scandinavian sub-zero operating conditions.
Market Restraints
- Vegetable base oil price volatility:Rapeseed and sunflower ester feedstocks fluctuate with agricultural commodity cycles, compressing margins on biodegradable formulations versus stable mineral oil costs.
- Scandinavian additive supply concentration:Specialty pour-point depressants for arctic-grade hydraulic fluids source from a limited German and Finnish supplier base, creating single-source vulnerability.
- Biodegradability certification friction:EU Ecolabel and Blue Angel standards impose divergent test protocols, forcing dual-registration costs for products serving both German and broader European markets.
Strategic Opportunities
- Appalachian hardwood harvesting revival:West Virginia and Kentucky timber contractors lag Pacific Northwest environmental compliance curves, creating a conversion window for biodegradable product lines ahead of anticipated state-level mandates.
- Drone-based aerial application:Unmanned aerial systems for selective forestry management introduce new lubrication points in electric drivetrains and precision spray equipment.
- IRA clean energy tax credits:United States equipment fleet electrification incentives accelerate demand for dielectric hydraulic fluids compatible with hybrid harvester architectures.
Industry Challenges
- Certified lubrication technician attrition:Nordic and Appalachian forestry equipment fleets face collapsing technical workforce pipelines as aging specialists retire without trained replacements for complex centralized lubrication system maintenance.
- Reformulation timeline compression:REACH authorization sunsets and state-level forestry best-management-practice code updates in Oregon and Washington impose overlapping compliance deadlines that strain product development bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Forestry Lubricants Market |
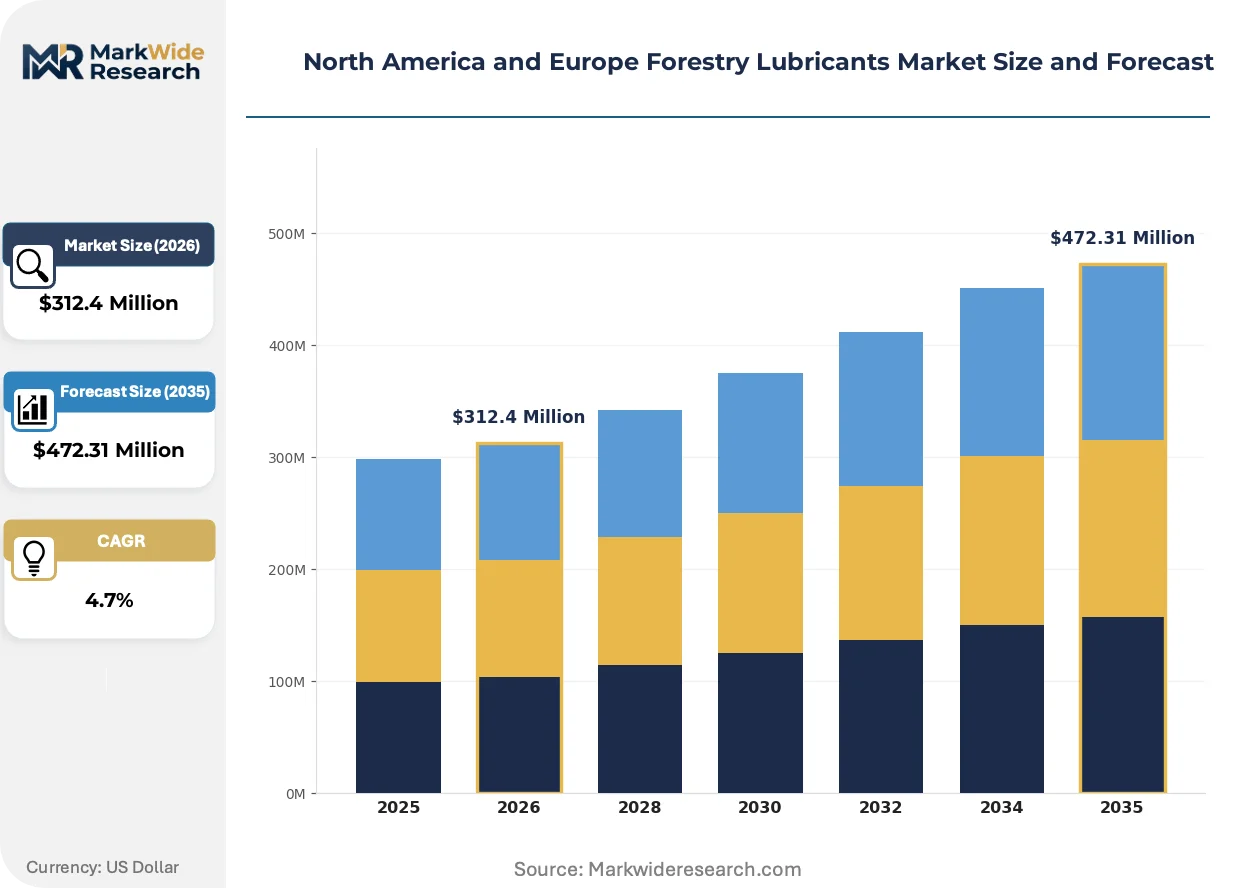
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Oils, Greases, Motor Oils, Biodegradable Lubricants Application: Chain Saws, Harvesters, Skidders, Tractors End User: Forestry Companies, Equipment Manufacturers, Maintenance Providers, Contractors Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Fuchs Petrolub SE, TotalEnergies, ExxonMobil Corporation, Frontier Performance Lubricants Inc., Phillips 66 Company, Shell Plc, Kluber Lubrication, BP plc, Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Forestry Lubricants Market Emerging Trajectories
Formulation chemistry is pivoting decisively toward ester-based base stocks as regulatory thresholds tighten, while equipment electrification and automated servicing systems are restructuring traditional lubricant consumption patterns across both regions.
Synthetic ester base stocks are displacing Group II mineral oils in high-pressure hydraulic circuits. German and Finnish harvester OEMs now specify ester fluids for warranty coverage in cold-climate operations. This chemistry shift is decomposing the historical volume advantage of mineral oil suppliers and fragmenting procurement contracts around biodegradability certification tiers.
EPA VGP permitting requirements for incidental lubricant discharge near United States water bodies are tightening test methodology for aquatic toxicity. Forestry contractors operating on federal timber leases in Oregon and Washington must document compliance through third-party certification. The regulatory pressure is accelerating inventory turnover toward pre-certified products and compressing shelf life for legacy mineral-based stocks held by Pacific Northwest distributors.
Mill-direct supply contracting is consolidating purchasing authority away from independent equipment dealers. British Columbia coastal harvesting operators now negotiate consolidated hydraulic and grease supply agreements directly with lubricant blenders, bypassing traditional forestry equipment dealer networks. This channel compression is visible most acutely in Finland's mechanical logging sector, where large contractor cooperatives have established captive supply relationships with specialized biodegradable lubricant producers.
North America and Europe Forestry Lubricants Market Segmentation
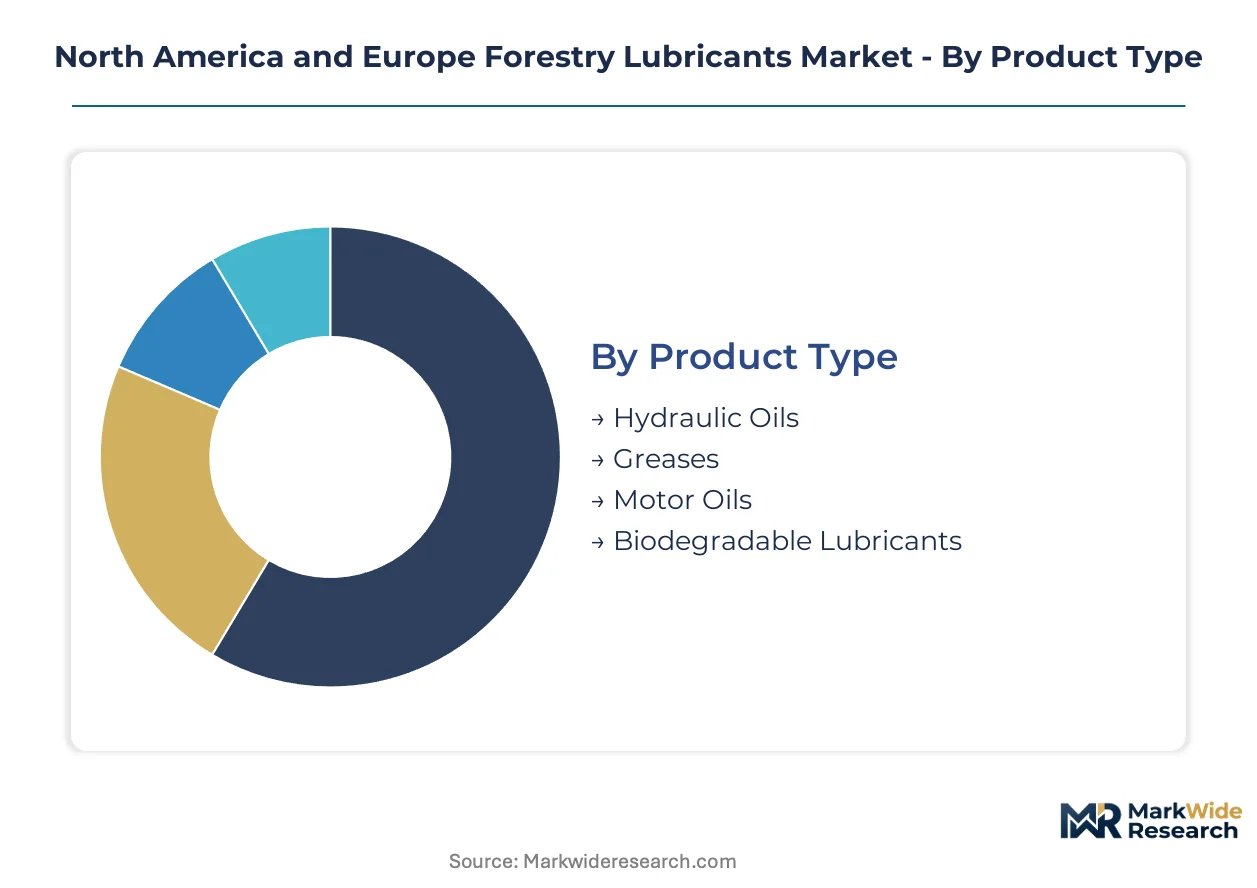
Segmentation in forestry lubricants reveals how regulatory pressure and equipment specialization fragment procurement patterns. Contractors in British Columbia and Finland now specify fluids by biodegradability tier rather than viscosity grade alone.
Product Type:
Margin pools concentrate in biodegradable formulations as REACH substance restrictions and EPA VGP permitting collapse demand for legacy mineral-based products.
- Hydraulic Oils:Ester-based fluids with zinc-free anti-wear packages dominate high-pressure circuits in German and Finnish harvesters. British Columbia coastal operators specify these for warranty compliance on wheeled high-tonnage equipment. Demand concentrates where centralized lubrication systems require extended drain intervals in sub-zero conditions.
- Biodegradable Lubricants:Vegetable-derived esters from rapeseed and sunflower feedstocks serve chain bar and hydraulic applications near salmon-bearing streams in Oregon and Washington. Pacific Northwest old-growth harvesting mandates drive immediate conversion, though agricultural commodity volatility compresses margins versus mineral alternatives.
- Greases:Ashless thickener systems lubricate boom and grapple attachments on Scandinavian skidders through automated delivery systems.
- Motor Oils:Synthetic formulations protect diesel engines in forwarders operating across Appalachian hardwood terrain.
Hydraulic oils hold installed capacity. Biodegradable lubricants are rotating up the share rankings.
Application:
Volume distribution tracks equipment replacement cycles rather than fleet expansion, with harvester lubrication systems consuming multiples of chain saw volumes per machine.
- Harvesters:Integrated hydraulic, grease, and motor oil specifications from German and Finnish OEMs require unified biodegradable certification tiers. British Columbia contractors negotiate mill-direct supply contracts covering all fluid categories for high-tonnage wheeled units.
- Chain Saws:Bar and chain oils face the most stringent aquatic toxicity thresholds under EPA VGP methodology. Oregon and Washington federal timber leases mandate third-party certified products with documented discharge compliance near water bodies.
- Skidders:Extreme cold-weather grease formulations with specialty pour-point depressants protect centralized lubrication systems in Scandinavian operations.
- Tractors:Auxiliary forestry equipment uses standard agricultural lubricant specifications with limited biodegradable conversion pressure.
Harvesters hold installed capacity. Chain saws are rotating up the share rankings.
End User:
Procurement authority is shifting from equipment dealers toward large contractor cooperatives with captive supply relationships.
- Forestry Companies:British Columbia and Finland's largest mechanical logging operators consolidate hydraulic and grease purchasing through direct blender negotiations, bypassing traditional dealer networks. These entities specify biodegradability certification tiers across entire fleets.
- Contractors:Pacific Northwest and Appalachian independent operators face compressed reformulation timelines as REACH sunsets and state-level best-management-practice codes activate simultaneously. Smaller fleets lack technical staff to evaluate additive chemistry shifts.
- Equipment Manufacturers:German and Finnish OEMs now warranty-cover only ester-based fluids for cold-climate harvester operations.
- Maintenance Providers:Aging certified lubrication technician pipelines in Nordic and Appalachian regions constrain service capacity for complex centralized systems.
Forestry companies hold installed capacity. Contractors are rotating up the share rankings.
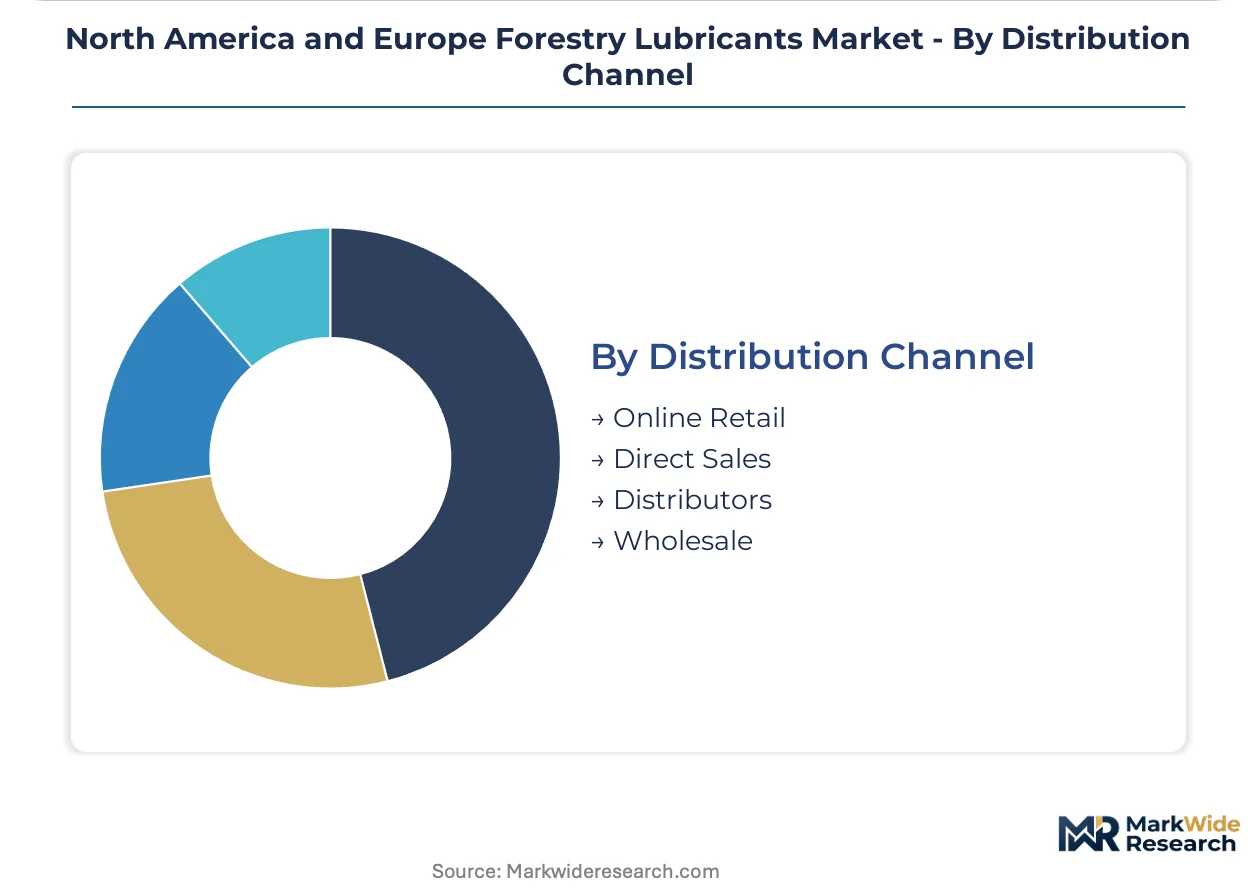
Distribution Channel:
Channel compression accelerates as mill-direct contracting eliminates intermediary margins in high-volume coastal harvesting zones.
- Direct Sales:British Columbia and Finnish contractor cooperatives establish captive supply relationships with specialized biodegradable lubricant producers. These agreements consolidate hydraulic, grease, and motor oil procurement under single-source frameworks.
- Distributors:Pacific Northwest independent dealers face inventory obsolescence as legacy mineral-based stocks lose eligibility for federal timber lease operations. Shelf life compression forces accelerated turnover toward pre-certified products.
- Wholesale:Volume aggregation serves smaller Appalachian contractors lagging Pacific Northwest environmental compliance curves.
- Online Retail:Limited penetration due to hazardous material shipping restrictions and technical specification complexity.
Distributors hold installed capacity. Direct sales are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA VGP permitting and the EU F-Gas Regulation are fragmenting procurement patterns across the North America and Europe forestry lubricants market, with coastal harvesting zones in British Columbia and the Pacific Northwest driving immediate biodegradable conversion while Nordic operations prioritize arctic-grade formulations.
United States
Oregon and Washington federal timber leases mandate third-party certified chain bar oils for equipment operating near salmon-bearing streams. EPA VGP methodology tightening on aquatic toxicity accelerates inventory turnover at Pacific Northwest distributors. Appalachian hardwood contractors in West Virginia and Kentucky lag this compliance curve, creating a conversion window ahead of anticipated state-level mandates.
Canada
British Columbia coastal harvesting operators negotiate mill-direct supply contracts covering hydraulic oils, greases, and motor oils for high-tonnage wheeled harvesters. The province's watershed protection codes for old-growth harvesting exceed federal baselines. Vancouver Island and mainland coastal contractor cooperatives have established captive supply relationships with specialized biodegradable lubricant producers.
Germany
The Black Forest equipment servicing hubs concentrate demand for ester-based hydraulic fluids specified by domestic harvester OEMs for warranty coverage. REACH substance restrictions on zinc-based anti-wear additives redirect R&D spending toward ashless additive packages. Stuttgart-based technical centers sustain specialized grease portfolios for extreme cold-weather applications.
Finland
Scandinavian mechanical logging cooperatives consolidate purchasing authority through direct blender negotiations, bypassing traditional dealer networks entirely. The EU Ecolabel framework imposes biodegradability certification thresholds that diverge from German Blue Angel standards, forcing dual-registration costs. Arctic-grade hydraulic fluids with specialty pour-point depressants protect centralized lubrication systems in sub-zero operating conditions.
Sweden
Nordic timber belts face collapsing pipelines of certified lubrication technicians as aging specialists retire without trained replacements. Swedish harvester OEMs now warranty-cover only ester-based fluids for cold-climate operations. Automated grease delivery systems on high-tonnage harvester booms reduce manual servicing intervals and extend component life.
North America and Europe Forestry Lubricants Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America and Europe forestry lubricants market. The vendor base separates into integrated petroleum majors with mineral oil scale, specialized biodegradable formulators with ester chemistry expertise, and regional blenders serving captive contractor relationships. Three archetypes dominate: global majors leveraging direct mill supply contracts, mid-cap specialists with OEM technical partnerships, and regional players anchored in single geography procurement consolidation. Competitive moves concentrate on backward integration into base ester production and geographic expansion through distributor acquisition.
Among Germany-based lubricant specialists, Fuchs Petrolub SE and Kluber Lubrication occupy positions within the premium technical tier, while Shell Plc represents the integrated major archetype with mill-direct supply scale. These three exemplify how competitive positioning fragments between chemistry-led specialization and procurement-led consolidation across the North America and Europe forestry lubricants market.
| Leading Market Players |
|---|
| Fuchs Petrolub SE |
| TotalEnergies |
| ExxonMobil Corporation |
| Frontier Performance Lubricants Inc. |
| Phillips 66 Company |
| Shell Plc |
| Kluber Lubrication |
| BP plc |
| Chevron Corporation |
| Others |
Supply Flow & Price Mechanics
Mill-direct offtake agreements between British Columbia contractor cooperatives and specialized biodegradable lubricant producers lock in multi-year supply access while fixing base ester feedstock costs against agricultural commodity swings. These contracts transfer price visibility risk from end-users to blenders, who must hedge rapeseed and sunflower oil positions through forward agricultural markets.
Pricing Analysis
Price spreads between Pacific Northwest and Appalachian markets reflect divergent regulatory compliance timelines, with Oregon and Washington contractors absorbing premium biodegradable certification costs while West Virginia operators still access legacy mineral formulations. Three-tier pricing structure across premium biodegradable-certified, mid-tier ester-based, and economy mineral grades segments buyers by environmental permit stringency. Cost compression in the premium tier intensifies as REACH authorization sunsets and EPA VGP methodology tightening compress reformulation windows. Independent contractors in the Appalachian hardwood belt exhibit highest price sensitivity due to thin margins and absent state-level mandate pressure.
Supply Chain Analysis
German and Finnish specialty additive production for arctic-grade pour-point depressants creates a chokepoint constraining formulation flexibility for Scandinavian sub-zero hydraulic fluids. Supply concentrates in Germany's Black Forest technical centers for ester-based base stocks, Finland's mechanical logging cooperatives for captive grease blending, and British Columbia's coastal mill-direct distribution hubs. Raw material dependencies on rapeseed and sunflower agricultural cycles, zinc-free ashless additive packages, and synthetic ester feedstocks expose blenders to commodity volatility and REACH substance restriction timelines. Single-source vulnerability in Nordic specialty additive supply amplifies disruption risk from regulatory authorization delays. Distribution runs through consolidated contractor cooperative procurement with diminishing independent dealer intermediary roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA VGP, REACH, and EU F-Gas frameworks is fragmenting procurement authority and creating niche entry points for specialized formulators with targeted certification expertise.
For Market Incumbents: Compound technical service capabilities around centralized lubrication system maintenance to offset collapsing certified lubrication technician pipelines across Nordic and Appalachian fleets. Deepen backward integration into base ester production to hedge agricultural commodity exposure threatening biodegradable formulation margins. Prioritize dual-registration investment for EU Ecolabel and Blue Angel compliance to preempt competitor capture of cross-border German-Finnish contractor procurement. For New Entrants and Emerging Players: Technical workforce training partnerships represent a service-layer gap where incumbents under-serve aging maintenance infrastructure in Scandinavian and Appalachian logging regions. Target drone-based aerial application lubrication points in electric drivetrains and precision spray equipment as the most penetrable white-space segment ahead of fleet electrification curves. Pursue go-to-market alignment with IRA clean energy tax credit beneficiaries seeking dielectric hydraulic fluid compatibility for hybrid harvester architectures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized biodegradable formulators with captive mill-direct supply relationships in British Columbia and Finland. Long-term viability over the next decade rests on regulatory compliance trajectory rather than mineral oil scale economies. Acquisition focus should center on mid-cap ester chemistry specialists with OEM technical partnerships and established biodegradability certification tiers. Monitor state-level forestry best-management-practice code activation in Oregon and Washington as the signal for inventory obsolescence inflection in legacy mineral-based distribution channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Ester Production | Captive supply of rapeseed and sunflower feedstocks insulates margins from agricultural commodity volatility. |
| Dual-Registration Investment for EU Ecolabel and Blue Angel | Preemptive compliance captures cross-border procurement consolidation between German and Finnish contractor cooperatives. |
| Technical Workforce Training Partnerships | Addresses certified lubrication technician attrition threatening centralized lubrication system maintenance capacity. |
| Dielectric Hydraulic Fluid Development | Positions formulators for IRA-incentivized hybrid harvester electrification in Pacific Northwest and Appalachian fleets. |
| Drone-Based Aerial Application Lubrication Entry | First-mover positioning in unmanned aerial system drivetrains ahead of selective forestry management adoption curves. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with British Columbia coastal harvesting contractors, Finnish mechanical logging cooperative procurement directors, German harvester OEM technical specification leads, and Pacific Northwest distributor inventory managers. Secondary validation drew from EPA VGP permitting databases, ECHA REACH authorization sunset schedules, EU Ecolabel and Blue Angel certification registries, and customs trade data on ester base stock imports. Bottom-up volume triangulation across hydraulic oil, biodegradable lubricant, grease, and motor oil product categories was cross-checked against top-down expenditure estimates from forestry equipment fleet operators.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, application equipment category, end-user procurement archetype, and distribution channel structure. CAGRs were derived from segment-level growth rate differentials weighted by installed base replacement cycles and regulatory compliance deadline clustering. Key inputs included REACH substance restriction implementation timelines, EPA VGP methodology revision schedules, and OEM fluid specification update frequencies for cold-climate warranty coverage.
Underlying assumptions cover steady-state agricultural commodity volatility for vegetable base oil feedstocks, with deviation risk concentrated in accelerated REACH authorization sunsets or state-level mandate front-running in Oregon and Washington. Forecasts reflect documented compliance pathway assumptions for biodegradability certification thresholds and OEM technical specification evolution. Practitioners should keep alternative scenarios live as EU F-Gas Regulation enforcement intensity and IRA clean energy tax credit utilization rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Hydro Lubricants Market
Lubricants
Global Mineral Oil Market
Lubricants
America Lubricants Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
India Industrial Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
Myanmar Lubricants Market
Lubricants
US Industrial Lubricants Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
ASEAN Lubricants Market