
 Portugal PVC Pipes Market | 2026-2036
Portugal PVC Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Portugal PVC Pipes Market Intelligence
Maintenance and lifecycle service contracts is rebalancing how Portuguese utilities procure PVC pipe systems, shifting capital expenditure into operational frameworks. Pipelife Portugal leverages its European manufacturing network to sustain competitive positioning in pressure-rated distribution lines. Valente Indústria de Plásticos anchors its presence through specialized fittings and custom fabrication capabilities for regional contractors. General Pvc Portugal competes aggressively on volume throughput for standard drainage specifications across Iberian export channels.
PVC pipes are thermoplastic conduits manufactured through extrusion of polyvinyl chloride resin compounded with stabilizers and plasticizers, delivering corrosion-resistant fluid conveyance across pressure and gravity-flow applications. Rigid PVC dominates structural installations due to superior ring stiffness and dimensional stability in buried infrastructure, while flexible PVC captures trenchless rehabilitation and seismic-adaptable layouts. Construction and water supply end-use industries concentrate the largest procurement volumes, though agriculture irrigation segments show accelerated specification migration toward pressure-rated Schedule 40 systems. Drainage systems and sewage applications absorb the majority of municipal capital allocation, with margin pools shifting toward engineered joint systems and leak-detection-integrated installations.
Portuguese PVC pipe compliance falls under IPQ-instituted EN standards harmonization, EU REACH chemical registration protocols, and national DGADR water quality directives governing potable conveyance materials. REACH substance restrictions on legacy plasticizers and heavy-metal stabilizers are forcing compound reformulation across domestic extrusion operations. DGADR certification requirements for potable water contact surfaces create asymmetric compliance burdens between import distributors and local manufacturers. Stakeholders must monitor evolving ECHA candidate list expansions and anticipated Portuguese transposition of revised Construction Products Regulation durability benchmarks to preempt specification lock-in risks.
Market Dynamics
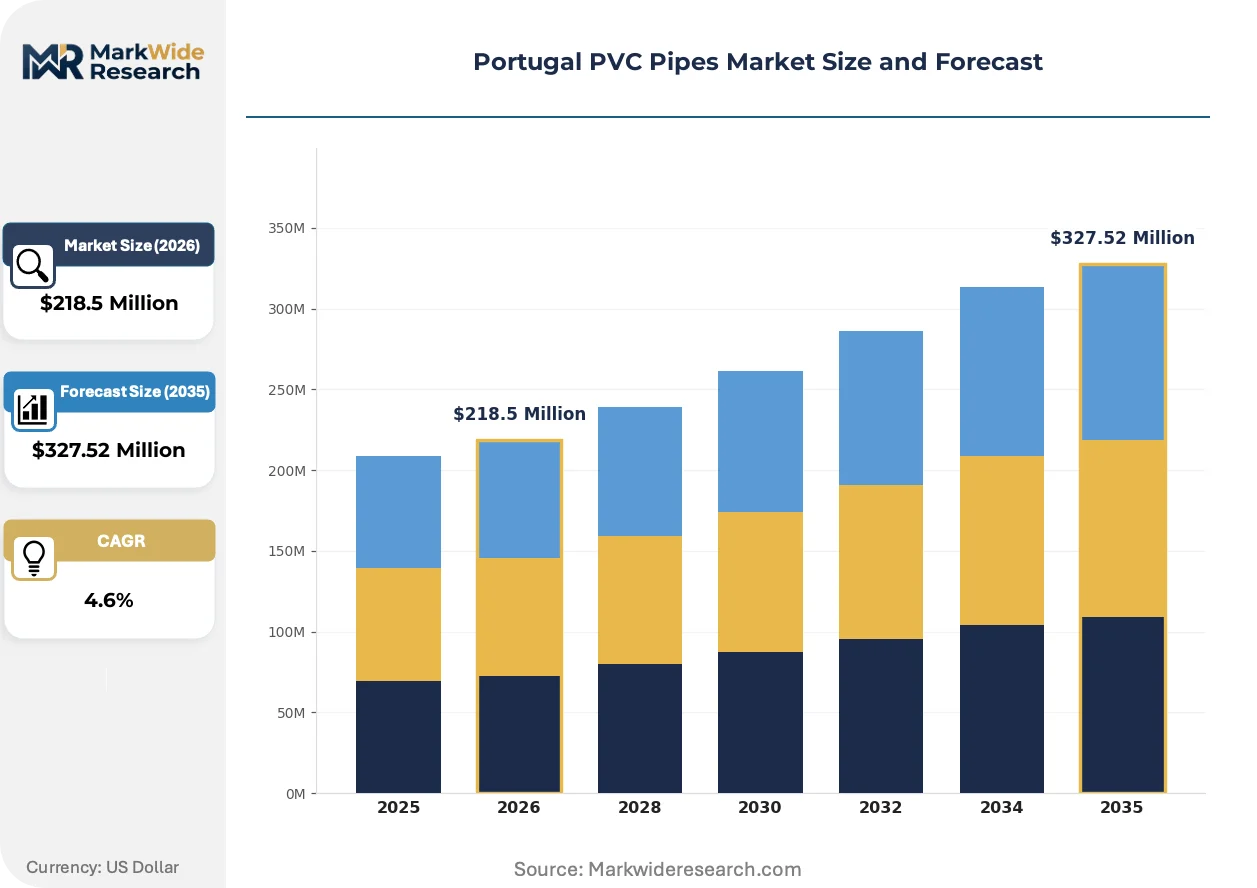
Portuguese municipalities are accelerating PVC pipe specification upgrades through operational procurement frameworks that convert capital expenditure into lifecycle service agreements, fundamentally restructuring supplier relationships across the Algarve and Greater Lisbon corridors.
Growth Catalysts
- EU F-Gas Regulation alignment:Portuguese building codes are tightening material performance thresholds, forcing specification upgrades toward higher-grade PVC compounds in municipal water distribution networks.
- Drainage infrastructure renewal:The Porto metropolitan belt is channeling substantial capital allocation toward sewage system rehabilitation, creating sustained demand for rigid PVC structural installations with superior ring stiffness.
- REACH chemical reformulation:Legacy plasticizer and heavy-metal stabilizer restrictions are compelling domestic extrusion operations to modernize compound formulations, differentiating compliant domestic producers from import distributors.
Market Restraints
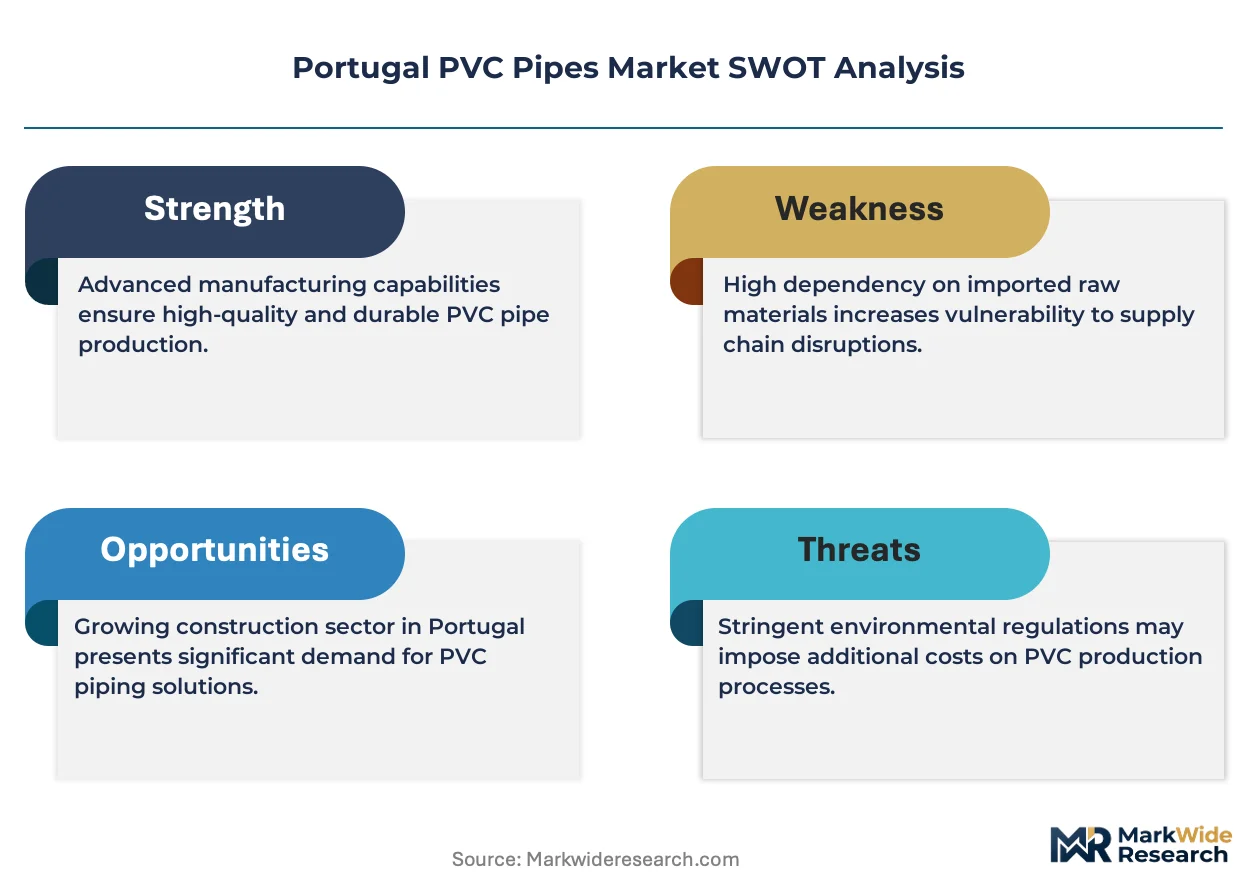
- Chlorine feedstock volatility:PVC resin production depends on chlor-alkali electrolysis economics, exposing Portuguese extruders to European energy price fluctuations that compress margin predictability.
- Import dependency for specialty compounds:High-performance pressure-rated formulations concentrate among German and Benelux chemical suppliers, creating asymmetric supply security for domestic manufacturers.
- HDPE substitution in trenchless applications:Flexible high-density polyethylene is capturing seismic-adaptable rehabilitation contracts where fused-joint integrity outperforms PVC solvent welding.
Strategic Opportunities
- Alentejo irrigation modernization:Agricultural water efficiency mandates are accelerating specification migration toward pressure-rated Schedule 40 systems in this underpenetrated southern region.
- Leak-detection integration:Smart sensor convergence with PVC joint systems creates premium positioning for engineered installations in Greater Lisbon municipal tenders.
- DGADR certification arbitrage:Potable water contact surface requirements create compliance moats that favor domestic manufacturers over import distributors lacking local certification infrastructure.
Industry Challenges
- Compound formulation expertise scarcity:REACH-driven stabilizer transitions require polymer chemistry capabilities that outpace current technical workforce development in Portuguese extrusion operations.
- Legacy infrastructure compatibility:Victorian-era cast iron and asbestos-cement networks in Porto demand specialized adaptation fittings that complicate standard PVC system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portugal PVC Pipes Market |
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $327.52 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid PVC, Flexible PVC, Schedule 40 PVC, Schedule 80 PVC End Use Industry: Construction, Agriculture, Infrastructure, Water Supply Application: Drainage Systems, Plumbing, Irrigation, Sewage Systems Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | General Pvc Portugal, Valente Indústria de Plásticos, Pipelife Portugal, Polijom, Plasdan, Tubos E.R. Internacional, ADS – Advantages Drainage Systems, FERSIL Freitas & Silva, Aqualine, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portugal PVC Pipes Market Strategic Shifts & Innovations
Material science advances and procurement model reinvention are converging to reshape competitive positioning across Portuguese PVC pipe markets, with regulatory chemistry mandates and smart infrastructure integration defining the innovation frontier.
Calcium-zinc stabilizer systems are absorbing the technical burden of legacy lead and cadmium replacement in rigid PVC extrusion, enabling Portuguese manufacturers to maintain EN standard compliance without sacrificing processing stability. Municipal utilities in the Algarve corridor are specifying these reformulated compounds for potable water pressure lines, compressing the competitive window for non-compliant import distributors.
ECHA candidate list expansions are forcing systematic substance screening across Portuguese compound supply chains, with DGADR water quality directives layering additional certification requirements for potable conveyance surfaces. Domestic extruders with captive laboratory testing capabilities are securing preferential positioning in Greater Lisbon tender processes, while smaller import-reliant distributors face asymmetric compliance cost burdens.
Lifecycle service contracting is displacing traditional capital purchase models across Portuguese municipal procurement, with maintenance-inclusive agreements now dominating drainage and sewage infrastructure awards. Regional contractors in the Porto metropolitan belt are restructuring supplier relationships around performance guarantees rather than unit pricing, compressing margins for volume-focused competitors while rewarding engineered joint system specialists.
Portugal PVC Pipes Market Segmentation
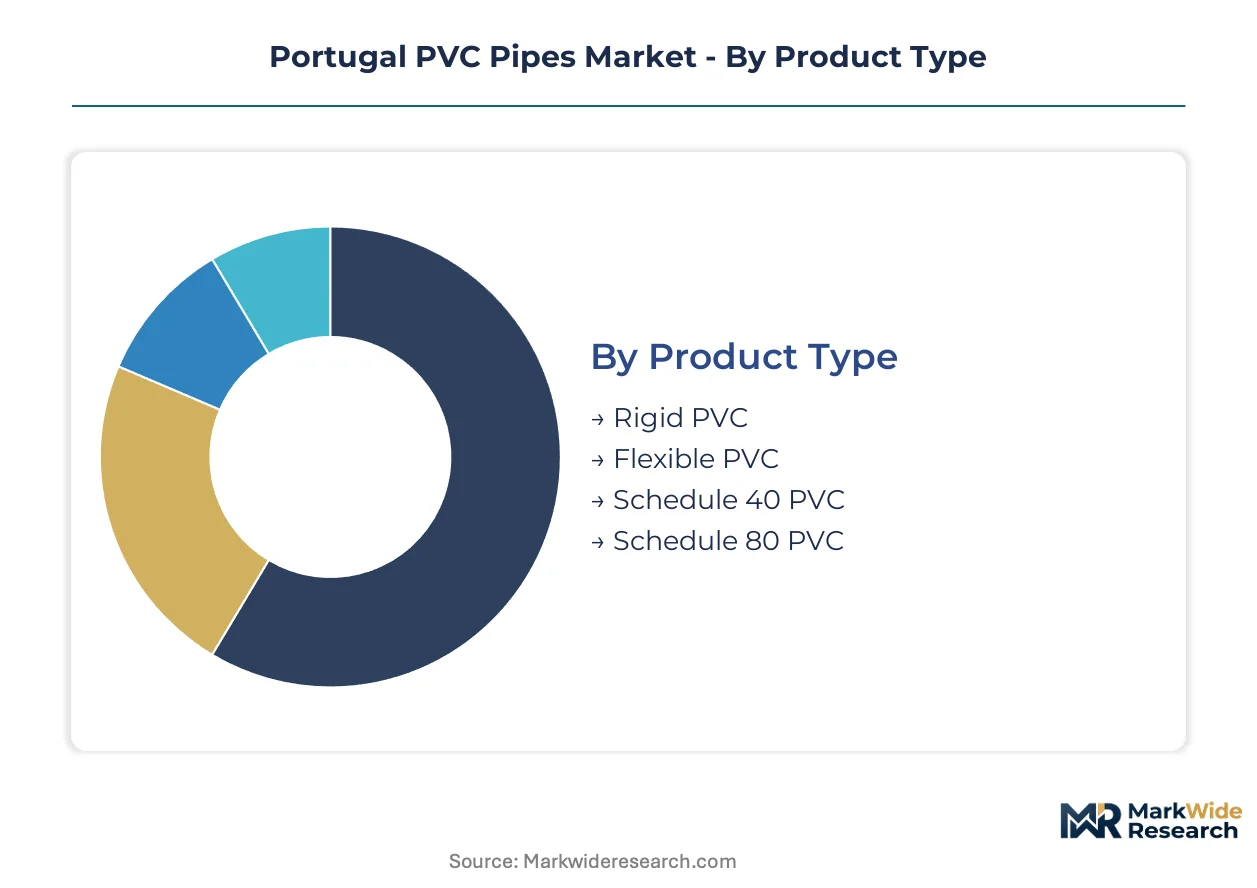
PVC pipe procurement in Portugal fragments across technical specifications, end-use requirements, and channel economics. Understanding these divides reveals where margin pools concentrate and which buyer segments drive specification authority.
Product Type:
Buyers differentiate primarily by structural performance requirements and installation methodology rather than price alone.
- Flexible PVC:Thermoplastic formulations with plasticizer additives enable coiling and trenchless deployment. Seismic-adaptable rehabilitation contracts in Greater Lisbon favor these systems where ground movement tolerance outweighs ring stiffness requirements.
- Rigid PVC:Unplasticized compounds deliver superior dimensional stability and crush resistance for buried gravity-flow infrastructure. Municipal drainage tenders across the Porto metropolitan belt specify rigid formulations for sewer main renewal where long-term deflection limits govern design.
- Schedule 40 PVC:Standard wall thickness for pressure-rated water distribution with moderate pressure tolerance.
- Schedule 80 PVC:Thicker-walled variants for high-pressure industrial process lines and pumped irrigation headers.
Rigid PVC leads volumes today; flexible PVC is gaining share fastest in rehabilitation applications.
End Use Industry:
Volume concentration and margin structure diverge sharply between project-based construction procurement and recurring agricultural replacement cycles.
- Construction:Building contractors specify PVC for non-pressure drainage, ventilation, and electrical conduit within residential and commercial structures. Portuguese building codes aligned with EU F-Gas Regulation are tightening material performance thresholds for pressure-rated distribution in high-rise developments.
- Infrastructure:Municipal utilities dominate procurement scale through lifecycle service contracts that convert capital expenditure into operational frameworks. The Algarve corridor rehabilitation programs channel substantial specification authority toward engineered joint systems with integrated leak detection.
- Water Supply:DGADR certification requirements for potable contact surfaces create asymmetric compliance burdens between domestic manufacturers and import distributors.
- Agriculture:Alentejo irrigation modernization is accelerating specification migration toward pressure-rated systems as water efficiency mandates tighten.
Infrastructure commands the largest procurement volumes; agriculture shows the steepest specification upgrade trajectory.
Application:
Fluid conveyance duty and contamination risk determine material grade and joint system complexity.
- Sewage Systems:Gravity-flow and pressure mains for municipal wastewater collection demand chemical-resistant formulations with gasketed or solvent-welded joints. The Porto metropolitan belt channels sustained capital allocation toward structural installations with superior ring stiffness.
- Drainage Systems:Stormwater and foundation drainage applications prioritize rapid installation and cost efficiency over pressure tolerance. Regional contractors favor standardized specifications that minimize inventory complexity across dispersed project sites.
- Plumbing:Potable water distribution within buildings requires DGADR-certified contact surfaces and pressure-rated Schedule 40 or 80 configurations.
- Irrigation:Agricultural water delivery systems in Alentejo are migrating toward pressure-rated specifications under modernization mandates.
Sewage systems absorb the majority of municipal capital allocation; drainage systems dominate unit volume through standardized specifications.
Distribution Channel:
Procurement scale and technical support requirements determine channel selection across buyer segments.
- Wholesale:Regional distributors aggregate demand from contractors and smaller municipalities, capturing volume through inventory proximity and credit terms. Portuguese utilities with operational procurement frameworks increasingly bypass wholesale tiers for direct manufacturer engagement.
- Direct Sales:Large municipal utilities and prime contractors negotiate lifecycle service agreements directly with extrusion operations. Pipelife Portugal leverages its European manufacturing network to sustain positioning in these high-volume, specification-intensive relationships.
- Retail:Hardware and building supply outlets serve residential plumbing and small-scale agricultural replacement demand.
- Online:Digital procurement channels concentrate in standardized fittings and replacement components rather than bulk pipe volumes.
Wholesale retains the broadest reach; direct sales is expanding fastest as utilities consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are concentrating Portuguese PVC pipe production in sub-regions where REACH compliance costs and DGADR certification infrastructure create asymmetric advantages for domestic extruders over import-dependent distributors.
Greater Lisbon
Municipal water supply rehabilitation across the metropolitan corridor is accelerating specification upgrades toward pressure-rated distribution systems. EU F-Gas Regulation alignment through Portuguese building codes tightens material performance thresholds for high-rise developments. Lisbon-based utilities are converting capital expenditure into lifecycle service agreements, restructuring supplier relationships around maintenance-inclusive frameworks.
Porto Metropolitan Belt
Drainage and sewage infrastructure renewal commands sustained capital allocation from municipal budgets throughout this northern region. Victorian-era cast iron and asbestos-cement network replacement demands specialized adaptation fittings that complicate standard PVC system integration. Regional contractors are consolidating procurement authority through direct manufacturer engagement, bypassing traditional wholesale tiers.
Algarve Corridor
Tourism-driven construction activity and coastal infrastructure resilience requirements channel specification authority toward engineered joint systems with integrated leak detection. Municipal programs specify calcium-zinc stabilized compounds for potable water pressure lines, compressing competitive windows for non-compliant import distributors. Seismic-adaptable rehabilitation contracts favor flexible PVC formulations where ground movement tolerance outweighs ring stiffness requirements.
Alentejo
Agricultural irrigation modernization under national water efficiency mandates is accelerating specification migration toward pressure-rated Schedule 40 systems. This underpenetrated southern region presents expansion opportunities for domestic extruders with captive laboratory testing capabilities. DGADR certification requirements for potable water contact surfaces create compliance moats favoring local manufacturers over import distributors lacking regional certification infrastructure.
Portugal PVC Pipes Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with domestic extruders holding structural advantages in potable water applications where DGADR certification creates compliance barriers. The vendor base concentrates around three strategic archetypes: European manufacturing network leveraged players, specialized fittings and custom fabrication specialists, and volume-focused standard specification competitors. Consolidation pressure is intensifying through lifecycle service contract procurement models and REACH-driven compound reformulation requirements that favor technical capabilities over pure scale.
Among Portugal-based fabricators, General Pvc Portugal occupies a position exemplifying the volume-driven competitive vector, while Valente Indústria de Plásticos represents the specialized fittings archetype through its custom fabrication capabilities for regional contractors. Pipelife Portugal anchors the European network-leveraged tier, sustaining positioning in high-volume, specification-intensive municipal relationships.
| Leading Market Players |
|---|
| General Pvc Portugal |
| Valente Indústria de Plásticos |
| Pipelife Portugal |
| Polijom |
| Plasdan |
| Tubos E.R. Internacional |
| ADS – Advantages Drainage Systems |
| FERSIL Freitas & Silva |
| Aqualine |
| Others |
Cost & Logistics Intelligence
Backward integration into chlor-alkali feedstock operations anchors pricing power for Portuguese PVC extruders facing volatile European energy markets, while domestic compound formulation capabilities create compliance arbitrage against import-dependent distributors lacking DGADR certification infrastructure.
Pricing Analysis
Distributor margin compression runs through wholesale tiers as municipal utilities consolidate procurement authority through direct manufacturer engagement. Three-tier pricing structure across engineered joint systems, standard pressure-rated lines, and commodity drainage specifications reflects certification grade and volume scale differentiation. Cost compression in commodity drainage segments is intensifying because Iberian export channel competition rewards throughput over technical service. Small regional contractors exhibit highest price sensitivity, while Greater Lisbon utilities with lifecycle service frameworks prioritize performance guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for high-performance pressure-rated formulations concentrate among German and Benelux chemical suppliers, creating asymmetric supply security for domestic manufacturers. Portuguese extrusion operations draw from Spanish and Italian resin supply bases, with specialty stabilizer and plasticizer inputs anchored in German chemical production. Single-source vulnerability in calcium-zinc stabilizer qualification creates exposure for compound reformulation timelines. Distribution runs through regional wholesale aggregators serving contractors and smaller municipalities, though direct sales channels are expanding fastest among large utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portuguese PVC pipe markets represent a late-cycle quality story as REACH-driven compound reformulation and DGADR certification requirements shift procurement toward technically capable domestic manufacturers over price-focused import distributors.
For Market Incumbents: Deepen captive laboratory testing capabilities to secure preferential positioning in Greater Lisbon municipal tender processes. Expand calcium-zinc stabilizer formulation expertise to preempt ECHA candidate list expansions. HDPE substitution in trenchless rehabilitation contracts threatens PVC share in seismic-adaptable applications; defend through engineered joint system integration with leak-detection sensors.
For New Entrants and Emerging Players: Agricultural contractors in Alentejo represent an underserved buyer archetype with accelerating specification migration toward pressure-rated systems. Target this underpenetrated southern region through technical sales support for irrigation modernization mandates. Establish DGADR certification infrastructure early to create compliance moats against import distributors.
For Investors and Strategic Acquirers: Roll-up economics work for specialized fittings and custom fabrication specialists because lifecycle service contracting rewards technical capabilities over pure scale. Five-to-ten year viability favors domestic extruders with compound formulation expertise and captive testing infrastructure. Monitor ECHA candidate list expansion velocity as inflection indicator for compound reformulation cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stabilizer Supply | REACH compliance costs favor captive compound formulation over external sourcing from German suppliers. |
| DGADR Certification Infrastructure Investment | Potable water contact surface requirements create asymmetric barriers against import-dependent distributors. |
| Lifecycle Service Contract Expansion | Greater Lisbon utilities are converting capital expenditure into operational frameworks with maintenance guarantees. |
| Leak-Detection Sensor Integration | Engineered joint systems with smart infrastructure positioning capture premium municipal tender awards. |
| Alentejo Irrigation Modernization Partnership | National water efficiency mandates accelerate specification migration toward pressure-rated Schedule 40 systems. |
Research Approach
Bottom-up infrastructure and agriculture modeling reconciled against top-down resin supply tracking forms the analytical core of this study. Primary interviews with municipal utility procurement officers, regional irrigation contractors, compound formulation chemists, and wholesale distribution managers combined with secondary validation from IPQ standards documentation, ECHA substance registration databases, and DGADR certification records. Customs data on PVC resin and compound imports, alongside municipal tender award disclosures, provided triangulation points for volume estimation.
Input-output matrices mapped chlor-alkali feedstock economics through extrusion operations to end-use applications across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, application duty, and distribution channel, with regional procurement framework variations as an industry-specific overlay. CAGRs were derived from trend extrapolation of specification upgrade trajectories and infrastructure investment cycles, incorporating REACH-driven reformulation cost curves and energy price sensitivity assumptions.
Underlying measurement precision varies by segment; municipal infrastructure procurement with disclosed tender values carries tighter precision than dispersed agricultural replacement demand. Forecasts reflect assumptions on regulatory enforcement timelines, energy price stabilization, and substitution elasticity between PVC and HDPE in rehabilitation applications. Deviation in ECHA candidate list expansion velocity or Portuguese Construction Products Regulation transposition timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Hydraulic Thermoplastic Hose and Couplings Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
Germany Acid Proof Lining Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
Galvanized Steel Tubes Market
Pipes and Tubes
Saudi Arabia PE Pipes Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Saudi Arabia PVC Pipes Market
Pipes and Tubes
Global Fluoropolymer Tubing Market