
 Qatar Automotive Lubricants Market | 2026-2036
Qatar Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Automotive Lubricants Market Analytics
Market Context
Gulf Standardization Organization certification is unwinding competitive access as smaller traders lose import authorization. TotalEnergies leverages its Ras Laffan refinery integration to anchor supply security for domestic blending. QALCO sustains brand loyalty through dedicated distribution to automotive service stations. ExxonMobil Corporation differentiates via advanced synthetic formulations targeting commercial vehicle fleets.
Technical Definition and Structural Segments
Automotive lubricants comprise refined base oils blended with performance additives to reduce friction, dissipate heat, and prevent wear in internal combustion and electric powertrain systems, with viscosity grades typically ranging from 0W-16 to 20W-50 per SAE J300 specifications. Engine oils dominate value capture due to high-frequency drain intervals and OEM specification complexity, while transmission fluids represent the fastest-growing product category as automatic gearbox penetration rises in Qatar's premium passenger vehicle segment. Fleet operators command the largest end-user margin pool through volume-contracted procurement, whereas DIY customers fragment across retail and online channels with price-sensitive purchasing patterns.
Regulatory Framework and Outlook
Qatar's Ministry of Commerce and Industry coordinates with the Gulf Standardization Organization to enforce lubricant labeling, flash point minimums, and additive compliance for all imported products. The Qatar Free Zones Authority shapes market access through warehousing and re-export licensing requirements for regional distributors. Stakeholders must monitor evolving OEM factory-fill specifications and electric vehicle thermal fluid standards to align product development with powertrain transition timelines.
Market Dynamics
Fleet operators in Qatar's industrial corridor are consolidating service contracts around synthetic lubricant packages, compressing procurement cycles and forcing distributors to restructure volume commitments around long-term supply agreements rather than spot purchasing.
Growth Catalysts
- Heavy-Duty Fleet Expansion:Qatar's logistics and construction sectors are scaling commercial vehicle fleets, creating concentrated demand for high-performance engine oils with extended drain intervals.
- GSO Certification Mandate:The Gulf Standardization Organization's mandatory product registration is professionalizing import channels and elevating quality standards across the domestic market.
- Synthetic Formulation Adoption:Heat-resistant base oil technologies are penetrating Qatar's premium passenger segment as OEM specifications tighten for turbocharged engines operating in extreme climates.
Market Restraints
- Base Oil Import Dependency:Qatar lacks domestic Group III/IV base oil production, exposing blenders to freight cost volatility and supply chain disruptions from Asian refiners.
- Refinery Integration Concentration:Ras Laffan's downstream capacity anchors national supply, creating single-point vulnerability for domestic lubricant manufacturing.
- Electric Powertrain Substitution:Battery electric vehicle thermal fluids require fundamentally different additive packages, threatening long-term engine oil demand in Qatar's urban passenger fleet.
Strategic Opportunities
- Re-Export Hub Positioning:Qatar Free Zones Authority licensing enables regional distributors to warehouse inventory for GCC markets, leveraging Doha's port infrastructure for cross-border fulfillment.
- EV Thermal Fluid Development:Battery cooling and e-axle lubrication represent white-space categories as Qatar's electric vehicle adoption accelerates in municipal and luxury segments.
- Digital Fleet Management Integration:Telematics-enabled oil condition monitoring allows lubricant suppliers to embed predictive maintenance services into commercial vehicle contracts.
Industry Challenges
- Specialized Blending Talent Scarcity:Formulation chemists with GCC regulatory expertise and OEM approval navigation skills command premium compensation, constraining mid-tier distributor technical capabilities.
- GSO Registration Timeline Compression:Product approval cycles for new viscosity grades and additive systems create working capital pressure during market entry phases.
- Legacy Distribution Network Reconfiguration:Independent service stations resist switching to synthetic product lines due to inventory carrying cost increases and customer price sensitivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Automotive Lubricants Market |
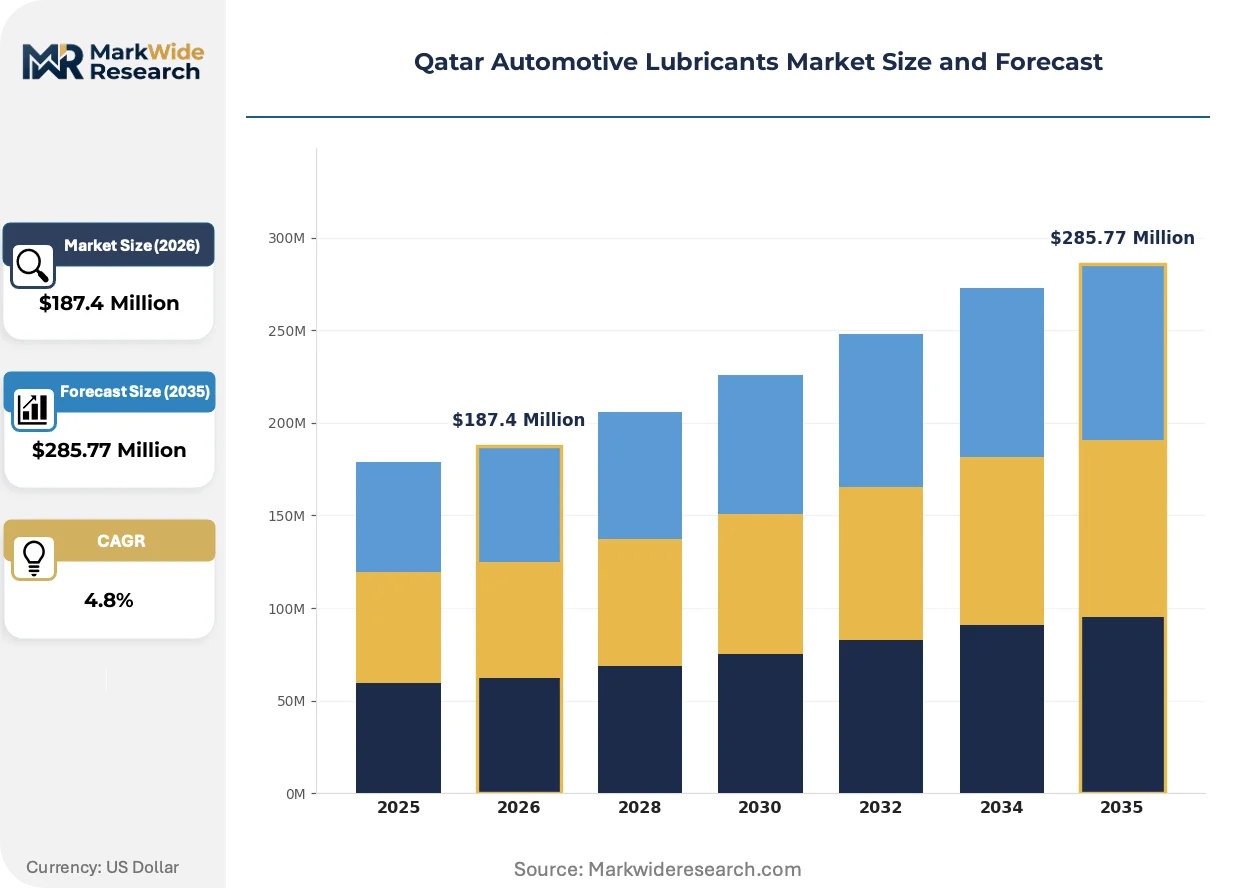
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Gear Oils, Transmission Fluids, Hydraulic Fluids Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Vehicles, Motorcycles Distribution Channel: Retail, Online, Wholesale, Direct Sales End User: Automotive Service Stations, Fleet Operators, DIY Customers, OEMs |
| Companies Covered | TotalEnergies, Qatar Lubricants Company (QALCO), ExxonMobil Corporation, Valvoline Inc, ENEOS Corporation, Shell plc, Chevron Corporation, FUCHS, BP PLC (Castrol), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Automotive Lubricants Market Evolving Landscape
Qatar's automotive lubricant landscape is experiencing fundamental formulation and procurement transformation as thermal management requirements diverge across internal combustion and electrified powertrains.
Advanced thermal fluid technologies for battery electric vehicles are miniaturizing the traditional lubricant portfolio, compressing the addressable market for conventional engine oils while opening specialized segments for dielectric coolants and e-axle greases. Fleet managers in Qatar's municipal transport and luxury passenger sectors are piloting these fluids at accelerated adoption rates compared to regional peers. This technology trajectory is forcing incumbent blenders to reallocate R&D expenditure toward electrochemical compatibility testing rather than friction modification chemistry.
The Gulf Standardization Organization's evolving additive disclosure requirements are tightening compliance documentation for all imported lubricant products. Qatar's Ministry of Commerce and Industry is coordinating enforcement with customs authorities, creating pre-clearance bottlenecks for non-compliant shipments. Doha's industrial corridor distributors are responding by pre-positioning certified inventory and establishing dedicated regulatory affairs functions to manage specification updates.
Commercial vehicle fleet operators are unbundling lubricant procurement from general maintenance contracts, creating direct supplier relationships that bypass traditional distributor markups. This pattern concentrates purchasing power among Qatar's largest logistics and construction conglomerates, fragmenting volume across specialized synthetic suppliers rather than integrated petroleum marketers. The shift is most visible in Ras Laffan's adjacent industrial zone, where long-haul trucking and heavy equipment fleets negotiate annual volume agreements with technical performance guarantees.
Qatar Automotive Lubricants Market Segmentation
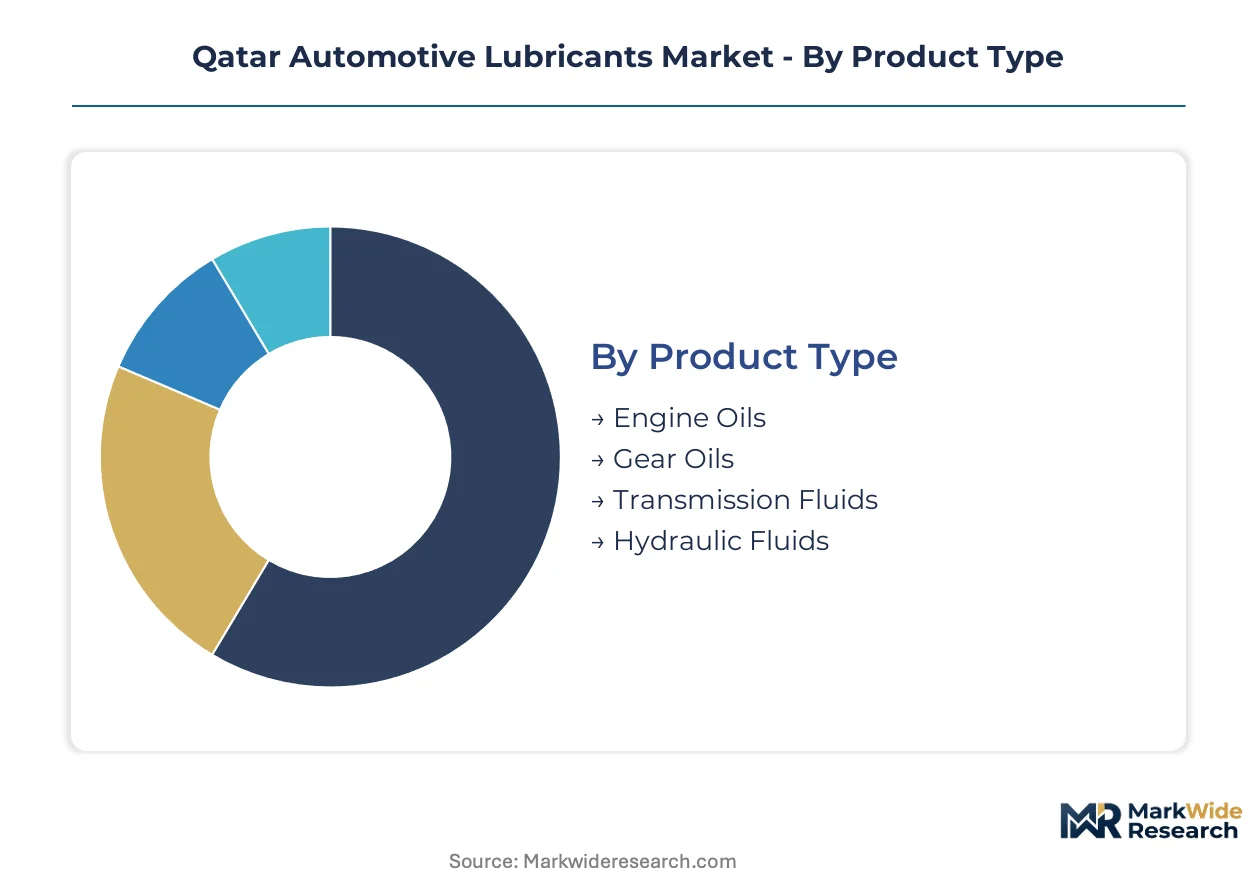
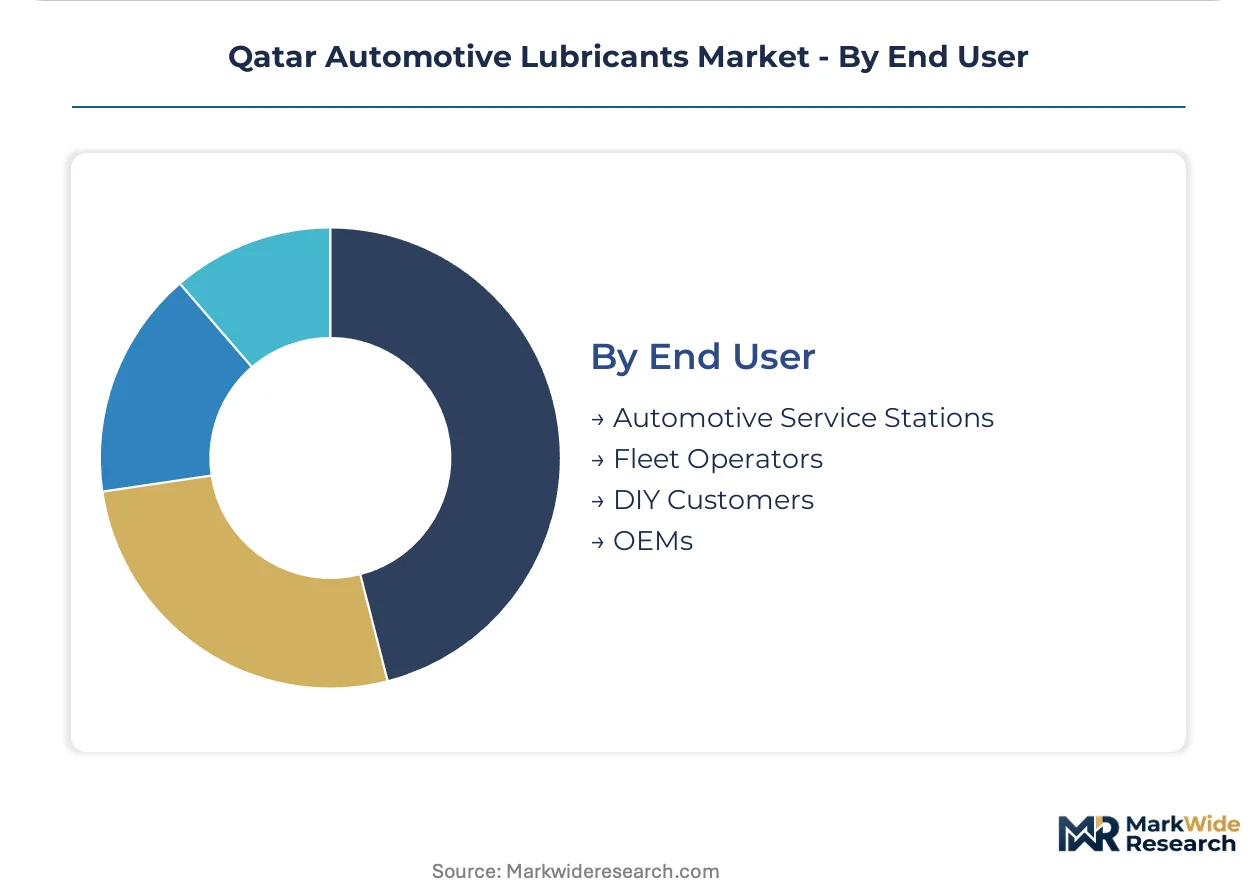
Segmentation in Qatar's automotive lubricants market reveals how procurement power concentrates among fleet operators while retail channels fragment across price-sensitive DIY consumers. Understanding these divides exposes where margin pools accumulate and where distributors must restructure service models to capture value.
Product Type:
Retail and wholesale channels carry the full product spectrum, but direct sales agreements lock in synthetic engine oil volumes for Ras Laffan's adjacent fleet operators while transmission fluids flow increasingly through OEM service networks.
- Engine Oils:Refined base oils blended with dispersant and anti-wear additive packages meeting API SP or ILSAC GF-6 specifications. Fleet operators in Doha's industrial corridor negotiate annual volume contracts for extended-drain synthetic grades, compressing distributor margins while securing supply security.
- Transmission Fluids:Specialized friction-modified formulations for automatic and dual-clutch gearboxes, with dielectric properties for hybrid transmissions. Qatar's premium passenger segment drives demand through OEM dealership service departments as automatic gearbox penetration climbs in luxury imports.
- Gear Oils:Extreme-pressure lubricants for differential and axle assemblies, typically SAE 75W-90 or 80W-140 viscosity grades. Heavy equipment servicing in construction clusters absorbs volumes through wholesale distributors.
- Hydraulic Fluids:Anti-wear and rust-inhibited oils for construction and material handling equipment. Direct sales channels dominate procurement for Qatar's logistics infrastructure projects.
Engine oils dominate installed base. Transmission fluids are where expansion concentrates.
Application:
Cost tier stratification separates premium synthetic formulations for luxury passenger vehicles from mineral-based products serving price-sensitive motorcycle owners, with commercial vehicles occupying the mid-tier volume band.
- Passenger Vehicles:Turbocharged gasoline and diesel engines in Qatar's luxury import segment demand low-viscosity synthetics (0W-20, 5W-30) with thermal stability for extreme ambient temperatures. OEM service networks control distribution, limiting independent retailer penetration.
- Commercial Vehicles:Medium-duty trucks and vans operating urban delivery routes require high-mileage formulations with soot-handling capacity. Fleet operators consolidate procurement through direct supplier relationships, bypassing traditional wholesale markups.
- Heavy-Duty Vehicles:Long-haul trucking and construction equipment in Ras Laffan's industrial zone. Extended-drain synthetic packages command premium pricing through technical performance guarantees.
- Motorcycles:Small-displacement two-wheelers for delivery and personal transport. Retail and online channels fragment volumes across price-sensitive consumers with low brand loyalty.
Commercial vehicles anchor volume throughput. Passenger vehicles concentrate margin extraction.
Distribution Channel:
Customer type determines channel selection — fleet operators and OEMs demand direct technical relationships, while DIY consumers default to retail and online price comparison.
- Retail:Automotive service stations and independent workshops stocking fast-moving viscosity grades. Inventory carrying costs pressure margins for synthetic product lines.
- Online:E-commerce platforms serving price-sensitive DIY consumers with private-label and imported formulations. Gulf Standardization Organization compliance verification challenges non-certified sellers.
- Wholesale:Regional distributors warehousing inventory for Qatar Free Zones Authority re-export operations. Volume commitments structure relationships with domestic blenders.
- Direct Sales:Long-term supply agreements between lubricant manufacturers and fleet operators or OEMs. Technical service integration locks out competitor substitution.
Direct sales capture the largest contract values. Online channels are climbing the fastest.
End User:
Volume scale separates end-user tiers — fleet operators consolidate purchasing power while DIY customers fragment across thousands of individual transactions with minimal loyalty.
- Automotive Service Stations:Independent and franchised workshops performing oil changes and maintenance. Synthetic product line adoption lags due to inventory cost increases and customer price resistance.
- Fleet Operators:Logistics, construction, and municipal transport conglomerates negotiating annual volume agreements. Telematics-enabled condition monitoring embeds lubricant suppliers into predictive maintenance contracts.
- DIY Customers:Individual vehicle owners purchasing retail or online for home servicing. Price sensitivity limits synthetic penetration despite OEM specification requirements.
- OEMs:Vehicle manufacturers specifying factory-fill and service-fill lubricants for warranty compliance. Technical approval processes create barriers for non-integrated suppliers.
Fleet operators dominate procurement scale. OEMs concentrate specification control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamad Port's container terminal expansion underwrites Qatar's position as a Gulf logistics hub, channeling lubricant imports through Doha's industrial corridor while anchoring re-export operations for GCC markets.
Doha Metropolitan Area
Luxury passenger vehicle density drives synthetic lubricant consumption in West Bay and The Pearl districts. Qatar's Ministry of Commerce and Industry enforces Gulf Standardization Organization certification through customs pre-clearance checkpoints. Ras Laffan's adjacent industrial zone concentrates heavy-duty fleet servicing operations for long-haul trucking contracts.
Al Wakrah Industrial Corridor
Construction equipment leasing clusters generate concentrated demand for hydraulic fluids and gear oils. The Qatar Free Zones Authority licenses warehousing facilities for regional distributors serving UAE and Saudi re-export markets. Mesaieed's petrochemical integration supports domestic blending capacity for Group II base oils.
Al Khor Northern Region
Municipal transport electrification pilots are testing battery thermal fluid specifications for bus fleets. The Ministry of Transport and Communications coordinates OEM factory-fill approvals with European manufacturers. Lusail's smart city infrastructure embeds predictive maintenance contracts linking telematics to lubricant supply agreements.
Al Rayyan Western Suburbs
Independent automotive service stations fragment retail demand across price-sensitive DIY consumers. Gulf Standardization Organization compliance verification creates entry barriers for online marketplace sellers. Umm Salal's logistics parks concentrate wholesale distribution inventory for construction sector procurement.
Al Shamal Northern Coast
Marine and offshore equipment servicing absorbs specialized high-viscosity formulations for extreme operating conditions. Qatar Petroleum's North Field expansion projects channel procurement through direct supplier relationships. Ruwais port facilities handle bulk lubricant imports bypassing Doha's container terminal congestion.
Qatar Automotive Lubricants Market Competitive Landscape
Listed leaders compete with private specialists across refinery integration and distribution reach. The market structure concentrates around integrated petroleum majors with captive base oil supply, while mid-tier blenders compete on formulation flexibility and fleet service contracts. Three archetypes dominate: refinery-integrated majors, regional blending specialists, and global lubricant marketers with OEM technical approvals. Competitive moves center on synthetic formulation licensing and long-term fleet supply agreements rather than capacity expansion.
Among refinery-integrated majors, TotalEnergies and Shell plc anchor supply security through Ras Laffan downstream proximity. Qatar Lubricants Company (QALCO) occupies the regional specialist position, exemplifying brand loyalty built through dedicated automotive service station distribution. ExxonMobil Corporation represents the global marketer archetype, sitting within the premium synthetic tier targeting commercial vehicle fleet specifications.
| Leading Market Players |
|---|
| TotalEnergies |
| Qatar Lubricants Company (QALCO) |
| ExxonMobil Corporation |
| Valvoline Inc |
| ENEOS Corporation |
| Shell plc |
| Chevron Corporation |
| FUCHS |
| BP PLC (Castrol) |
| Others |
Value Network & Pricing Analysis
Synthetic base oil substitution for mineral grades is compressing procurement economics across Qatar's lubricant market while simultaneously shifting supply geography toward Asian Group III/IV refiners. This input transition concentrates pricing power among blenders with direct refinery relationships, forcing distributors to absorb margin compression or restructure volume commitments.
Pricing Analysis
Gulf Standardization Organization certification level creates the primary spread between premium synthetic formulations and economy mineral products. Three-tier pricing structure separates extended-drain fleet packages from standard service-fill grades and basic retail offerings. Pricing pressure stems from fleet operator consolidation around annual volume agreements with technical performance guarantees. DIY customers exhibit highest price sensitivity, while OEM factory-fill specifications command lowest elasticity due to warranty compliance requirements.
Supply Chain Analysis
South Korea and Singapore anchor Group III/IV base oil supply for Qatar's blending operations, with Japan contributing specialized additive packages. Qatar's domestic production draws from imported base stocks, performance chemical additives, and packaging materials from regional converters. Single-source vulnerability concentrates around Ras Laffan's downstream integration as the sole domestic refinery anchor. Distribution runs through Doha's industrial corridor warehousing with Qatar Free Zones Authority licensing enabling GCC re-export fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's automotive lubricant market fragments across powertrain technologies, creating niche opportunities as electric vehicle thermal fluids diverge from conventional engine oil specifications. Fleet operator procurement unbundling from general maintenance contracts accelerates this fragmentation.
For Market Incumbents: Compound brand loyalty through embedded telematics-enabled condition monitoring services that lock fleet operators into predictive maintenance contracts. Secure backward integration into additive sourcing to defend margin position against Asian refinery price volatility. Prioritize Gulf Standardization Organization certification pipeline investment to accelerate new viscosity grade approvals before competitor entry.
For New Entrants and Emerging Players: EV thermal fluid technical service gaps in Qatar's municipal transport electrification pilots offer white-space entry points. Battery cooling and e-axle lubrication specifications remain under-served by incumbent formulation chemists with GCC regulatory expertise. Target direct technical relationships with European OEMs supplying Qatar's luxury electric vehicle segment, bypassing established distributor markups through factory-fill approval navigation.
For Investors and Strategic Acquirers: The market sits at a substitution phase that favors specialized blending specialists with electric powertrain fluid capabilities over integrated petroleum majors tethered to engine oil volumes. Acquisition targets should demonstrate Gulf Standardization Organization approval track records and fleet operator contract concentration. Monitor OEM factory-fill specification divergence between internal combustion and electric platforms as the inflection signal for portfolio reweighting.
| Strategic Initiative | Industry Significance |
|---|---|
| EV Thermal Fluid Development | Battery cooling specifications from European OEMs reshape Qatar's municipal fleet procurement. |
| GSO Certification Acceleration | Compressed approval timelines for new viscosity grades create working capital advantages for early entrants. |
| Telematics Integration Partnership | Predictive maintenance contracts embed lubricant suppliers into fleet operator technical workflows. |
| Re-Export Hub Licensing | Qatar Free Zones Authority warehousing enables cross-border GCC fulfillment from Doha port infrastructure. |
| Synthetic Formulation Licensing | Extended-drain technology agreements with Asian base oil refiners secure supply security for commercial fleets. |
Research Methodology
A standing panel of lubricant formulation chemists, fleet procurement directors, automotive service station operators, and Gulf Standardization Organization regulatory affairs specialists provided ongoing calibration throughout the research process. Primary fieldwork combined structured interviews with secondary validation against customs import records, Qatar Ministry of Commerce and Industry certification databases, and Qatar Free Zones Authority licensing disclosures. Bottom-up volume modeling across product segments triangulated with top-down macroeconomic indicators anchored the analytical framework.
Consistency checks against regional petroleum product trade flows and OEM factory-fill specification timelines validated projection outputs across the analysis window. Segmentation dimensions modeled include product type, vehicle application, distribution channel, and end-user procurement scale. CAGRs were derived from annualized growth trajectory analysis incorporating fleet expansion rates, synthetic penetration curves, and electric vehicle adoption patterns as key inputs.
Material uncertainties — base oil price volatility, electric powertrain substitution acceleration, and Gulf Standardization Organization regulatory amendments — sit outside the modeled envelope. Forecasts reflect assumptions regarding fleet operator contract structures and OEM specification stability that may require revision. Recalibration cycles align with material shifts in Qatar's transport electrification policy and regional refinery capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Canada Lubricants Market
Lubricants
Lubricated Tracks Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Egypt Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Firearm Lubricants Market
Lubricants
Poland Lubricants Market
Lubricants
Spain Automotive Lubricants Market
Lubricants
Argentina Lubricants Market
Lubricants
Iraq Lubricants Market
Lubricants
Friction Reducers Market
Lubricants
Food Grade Lubricant Market
Lubricants
China Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Global Finished Lubricant Market