
 Industrial Gear Oil Market | 2026-2036
Industrial Gear Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Gear Oil Market Analysis
Multi-source procurement for base oil feedstocks is decoupling from the traditional single-refiner dependency model that dominated industrial lubricant supply chains. FUCHS SE leverages its captive additive blending network across Central Europe to sustain formulation consistency. ExxonMobil Corporation anchors global supply through integrated Group II/III base oil production. Klüber Lubrication specializes in high-performance synthetic gear oils for precision machinery applications.
Industrial gear oil constitutes a lubricating fluid formulated with base stocks and extreme-pressure additives, typically operating within viscosity ranges of ISO VG 68 to 1500, designed to reduce friction and prevent scuffing in enclosed gearboxes under boundary lubrication conditions. Its primary commercial purpose centers on extending equipment life and minimizing unplanned downtime in power transmission systems. Synthetic formulations command premium positioning due to thermal stability advantages in high-temperature industrial environments. The mining end-user segment represents a concentrated margin pool where severe-duty requirements justify premium product selection. Mineral-based products retain volume dominance in cost-sensitive machinery applications across developing manufacturing bases.
EPA regulations in the United States govern waste oil handling and disposal, directly influencing reformulation priorities and recycling infrastructure investment. REACH in Europe and GB standards in China impose divergent substance restrictions, compelling manufacturers to maintain regional product portfolios rather than unified global formulations. OSHA workplace exposure limits further shape additive package selection for domestic industrial users. Stakeholders must monitor regulatory divergence between major jurisdictions when evaluating centralized versus distributed blending strategies.
Market Dynamics
Reformulation pressure from REACH substance restrictions is fragmenting product portfolios across Europe, forcing blenders to maintain parallel formulation streams rather than unified global SKUs.
Growth Catalysts
- Mining automation in Australia:Autonomous haul trucks operating in Pilbara iron ore pits require synthetic ISO VG 680 formulations with extended drain intervals.
- REACH Annex XIV authorization:European manufacturers are accelerating substitution of boron-containing extreme-pressure additives ahead of sunset dates.
- Wind turbine gearbox scaling:Offshore installations above 15 MW capacity demand PAO-based lubricants with micropitting resistance certification.
Market Restraints
- Group III base oil concentration:Asian refiners control 60% of high-viscosity Group III supply, creating single-source vulnerability for European blenders.
- PFAS regulatory overhang:Anticipated EPA designation of fluorinated thickeners as hazardous substances threatens PTFE-thickened synthetic grease formulations.
- Mineral oil substitution ceiling:Cost-sensitive cement plants in developing manufacturing corridors resist synthetic upgrade despite demonstrated total-cost-of-ownership benefits.
Strategic Opportunities
- India's PLI scheme for heavy machinery:Domestic construction equipment manufacturing incentives create localized blending demand outside traditional import channels.
- Used oil re-refining integration:Circular economy mandates in EU member states reward closed-loop collection-to-base-oil recovery models.
- Digital oil condition monitoring:Sensor-embedded gearboxes enable predictive drain-interval extension, creating data-service attach opportunities for lubricant suppliers.
Industry Challenges
- Additive chemist scarcity:Formulation expertise in sulfur-phosphorus EP chemistry is concentrating among retiring specialists without pipeline replacement.
- OEM approval timeline compression:Wind turbine gearbox manufacturers demand 10,000-hour field validation data within 18-month product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Gear Oil Market |
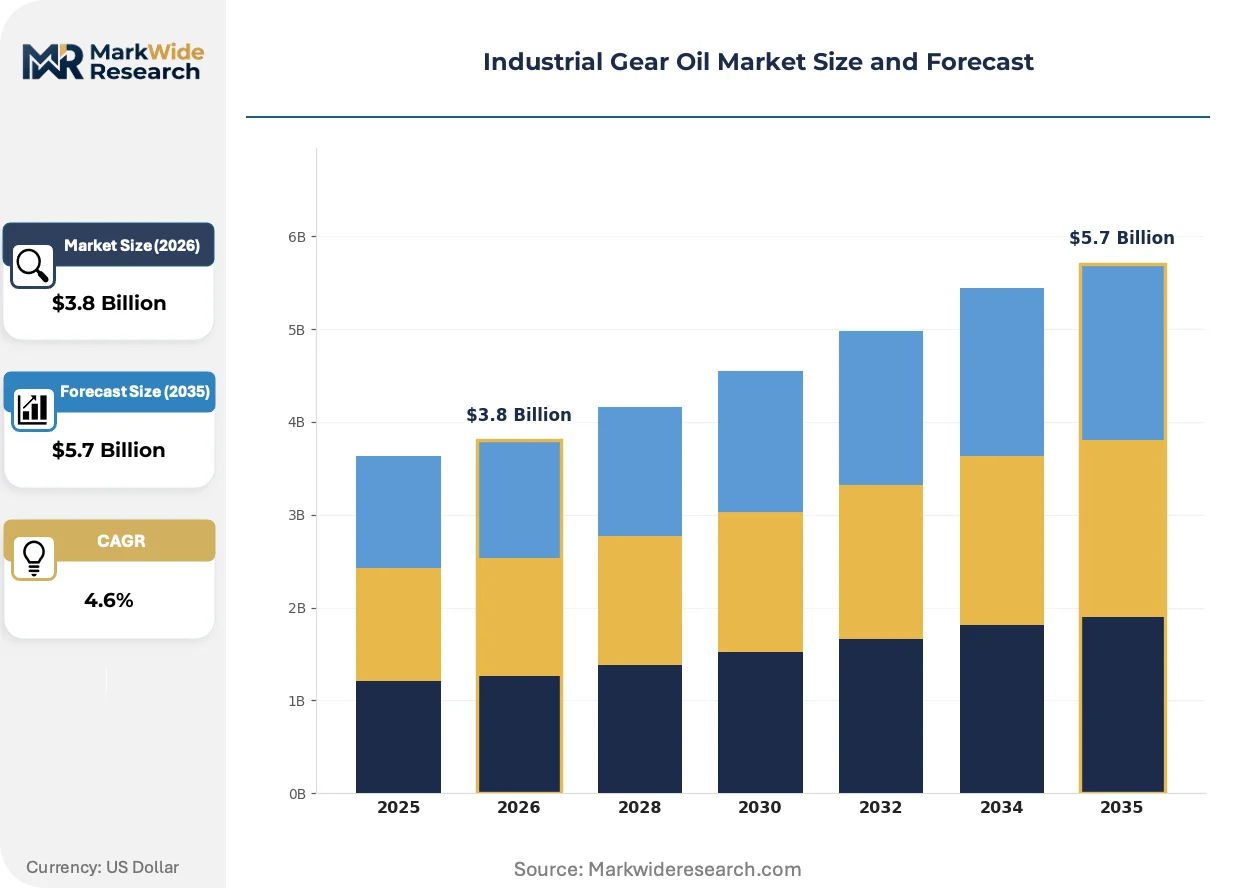
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
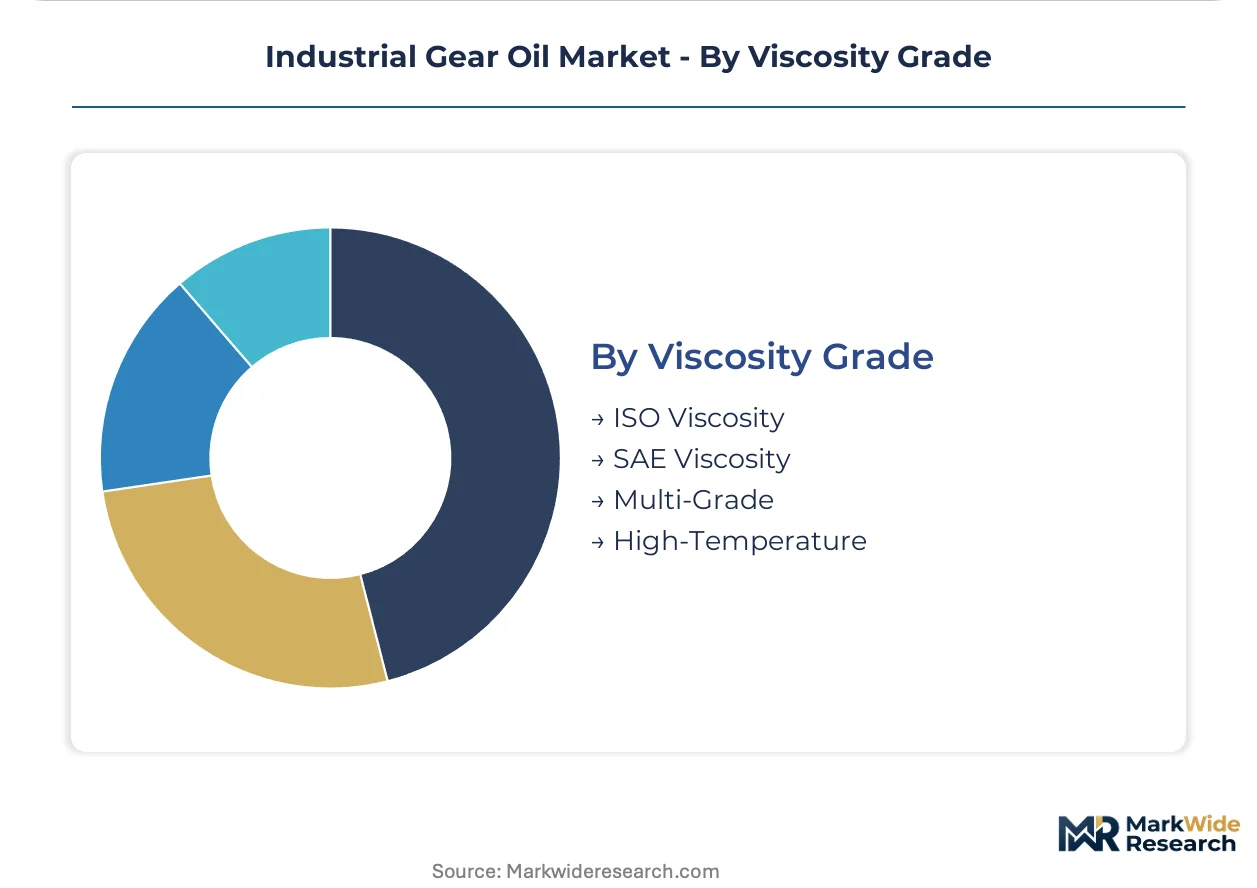
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Mineral, Bio-Based Application: Machinery, Automotive, Marine, Construction End User: Manufacturing, Transportation, Mining, Power Generation Viscosity Grade: ISO Viscosity, SAE Viscosity, Multi-Grade, High-Temperature |
| Companies Covered | TotalEnergies SE, FUCHS SE, ExxonMobil Corporation, Klüber Lubrication, Valvoline Inc., Shell plc, BP plc, Lubrizol Corporation, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Gear Oil Market Emerging Trajectories
Formulation science is converging with equipment telemetry, compressing the traditional separation between lubricant specification and real-time mechanical performance feedback.
Polyalkylene glycol (PAG) base stocks are unifying thermal stability and biodegradability requirements in marine gearbox applications. Offshore vessel operators in the North Sea are specifying PAG-based ISO VG 150 grades for controllable pitch propeller systems. This unification is eliminating the historical trade-off between fire resistance and environmental compliance in enclosed marine transmissions.
REACH restriction proposals on medium-chain chlorinated paraffins (MCCPs) are forcing reformulation of metalworking-adjacent gear oils by December 2025. European metal processing facilities must validate alternative EP additive packages under accelerated wear-test protocols. Gear oil blenders serving German automotive supplier parks are prioritizing calcium sulfonate complex thickeners as drop-in replacements.
Consolidated maintenance procurement at Chinese state-owned steel groups is displacing decentralized plant-level lubricant selection. Central technical committees in Baowu and Shagang now mandate enterprise-wide approved vendor lists with synthetic-preferred specifications. This concentration is visible in Hebei province, where provincial environmental inspectors enforce unified fluid management protocols across merged steel assets.
Industrial Gear Oil Market Segmentation
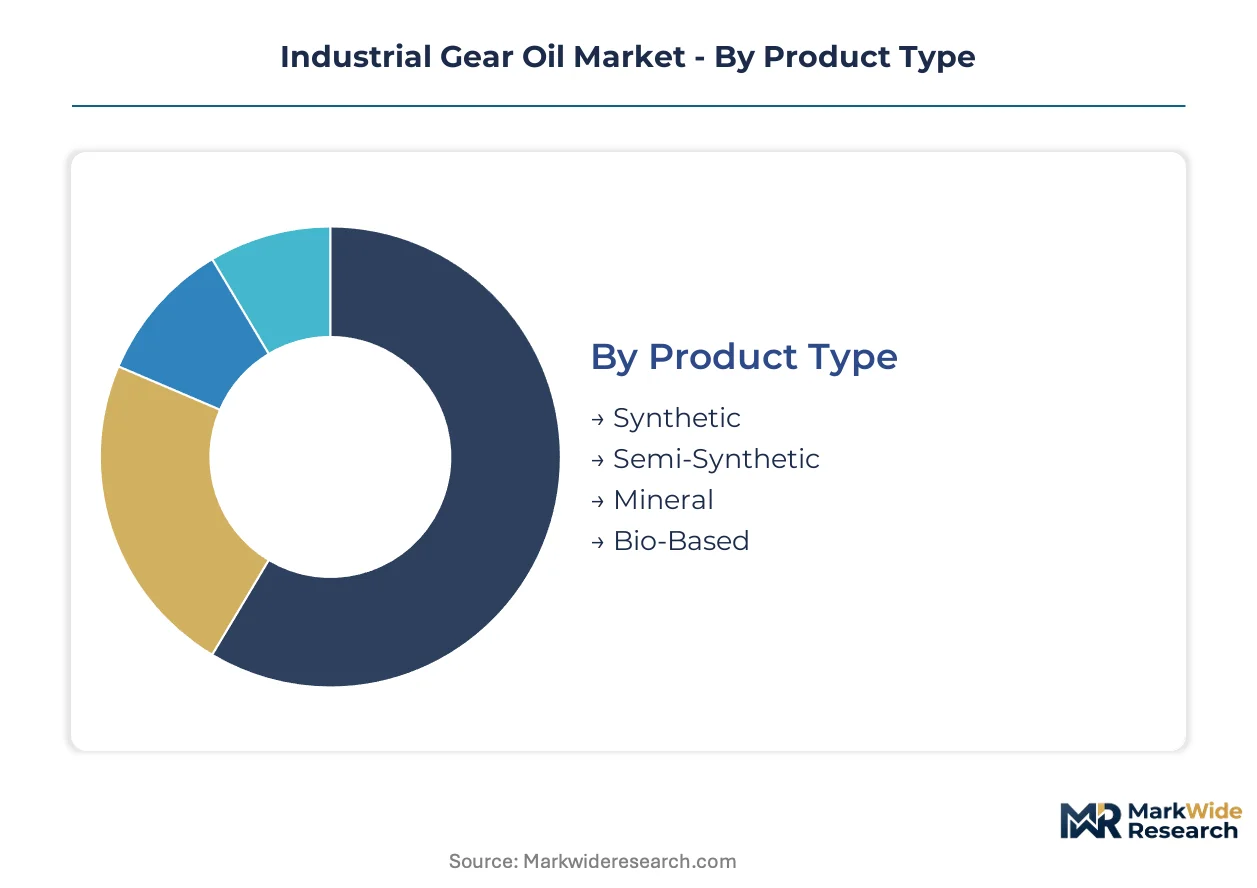
Industrial gear oil segmentation reveals divergent capital requirements across formulation technologies and end-use intensities. Equipment duty cycles and regulatory exposure determine margin architecture more than volume scale alone.
Product Type:
Capital intensity peaks with synthetic base stock production, where integrated PAO and PAG manufacturing demands petrochemical-scale investment.
- Synthetic:Formulated with polyalphaolefin (PAO) or polyalkylene glycol (PAG) base stocks delivering thermal stability above 120°C operating temperatures. Mining automation in Australia's Pilbara region specifies synthetic ISO VG 680 for autonomous haul trucks requiring extended drain intervals beyond 8,000 hours.
- Mineral:Refined from Group I/II/III petroleum distillates with sulfur-phosphorus EP additive packages. Cost-sensitive cement plants in developing manufacturing corridors resist synthetic upgrade despite demonstrated total-cost-of-ownership benefits from reduced changeout frequency.
- Semi-Synthetic:Blended base stocks combining mineral oil economics with partial synthetic performance gains.
- Bio-Based:Vegetable oil or synthetic ester formulations targeting marine and forestry applications with biodegradability mandates.
Most installed capacity flows through Mineral. Expansion is steepest in Synthetic.
Application:
Application segmentation tracks equipment replacement cycles and lubricant consumption rates rather than unit sales volume.
- Machinery:Enclosed gearboxes in metalworking, food processing, and material handling equipment operating under boundary lubrication conditions. China's heavy manufacturing corridor concentrates demand where consolidated procurement at state-owned steel groups mandates synthetic-preferred specifications.
- Marine:Controllable pitch propeller systems and deck machinery exposed to saltwater corrosion and fire-risk environments. North Sea offshore vessel operators specify PAG-based ISO VG 150 grades unifying thermal stability with environmental compliance.
- Construction:Earthmoving equipment and crane transmissions subject to contamination and shock loading.
- Automotive:Heavy-duty transmission and axle applications in commercial vehicles.
Volume concentrates in Machinery. Margin expansion is most pronounced in Marine.
End User:
End-user segmentation reflects divergent equipment utilization rates and unplanned downtime costs that lubricant selection seeks to mitigate.
- Mining:Severe-duty open-gear and enclosed gearbox applications with 24/7 operating schedules. Australia's iron ore operations drive adoption of high-load synthetic formulations where equipment availability directly ties to export volume commitments.
- Power Generation:Wind turbine gearboxes scaling above 15 MW capacity requiring micropitting-resistant PAO lubricants with 10,000-hour field validation data.
- Manufacturing:Discrete and process industry machinery with scheduled maintenance windows.
- Transportation:Rail and fleet vehicle transmissions with standardized lubricant specifications.
Revenue per liter peaks in Mining. Volume scale dominates in Manufacturing.
Viscosity Grade:
Viscosity specification governs film thickness formation under load-speed-temperature combinations across gearbox designs.
- ISO Viscosity:Standardized kinematic viscosity grades from ISO VG 32 to 1500 per ISO 3448 classification. European wind turbine OEMs demand ISO VG 320 and 680 grades with Flender micropitting certification for planetary gearbox protection.
- Multi-Grade:Viscosity index improvers enabling single lubricant across seasonal temperature swings. Arctic mining operations in northern Canada and Russia specify multi-grade synthetics for cold-start pumpability without summer thinning.
- SAE Viscosity:Automotive-derived grading system applied to off-highway equipment.
- High-Temperature:Formulations with oxidative stability for furnace drives and steel mill applications exceeding 150°C sump temperatures.
Specification diversity is widest in ISO Viscosity. Technical differentiation intensifies in Multi-Grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's heavy manufacturing corridor concentrates the largest volume consumption of industrial gear oil, with state-owned steel groups driving consolidated procurement patterns that favor synthetic-preferred specifications across Hebei province.
China
Baowu and Shagang steel groups mandate enterprise-wide approved vendor lists with synthetic-preferred gear oil specifications. GB standards impose substance restrictions that diverge from REACH, compelling blenders to maintain separate regional formulations. Hebei province enforces unified fluid management protocols across merged steel assets where provincial environmental inspectors monitor compliance.
United States
EPA regulations govern waste oil handling and disposal, directly influencing reformulation priorities and recycling infrastructure investment across domestic manufacturing. OSHA workplace exposure limits shape additive package selection for industrial users in metalworking and power generation applications. The Permian Basin energy corridor and Gulf Coast petrochemical cluster concentrate demand for high-temperature gear oil formulations in compressor and pump drive systems.
Germany
REACH Annex XIV authorization deadlines accelerate substitution of boron-containing extreme-pressure additives among European formulators. ECHA restriction proposals on medium-chain chlorinated paraffins force metalworking-adjacent gear oil reformulation by December 2025. The Ruhr industrial region and Baden-Württemberg automotive supplier parks prioritize calcium sulfonate complex thickeners as drop-in replacements for legacy EP packages.
Australia
Autonomous haul trucks operating in Pilbara iron ore pits require synthetic ISO VG 680 formulations with extended drain intervals beyond 8,000 hours. TGA-equivalent industrial chemical regulations align with OECD guidelines for lubricant substance classification. The Pilbara mining corridor drives adoption of high-load synthetic formulations where equipment availability directly ties to export volume commitments.
India
The PLI scheme for heavy machinery creates localized blending demand outside traditional import channels for domestic construction equipment manufacturing. BIS standards govern lubricant quality specifications for industrial applications. Maharashtra and Gujarat industrial corridors concentrate new blending capacity investments as OEMs localize supply chains for excavator and crane transmissions.
Industrial Gear Oil Market Vendor Landscape
Global majors compete with regional champions across formulation technology and supply chain integration, producing a tiered structure where captive base oil production separates scale players from blenders dependent on merchant feedstocks. The vendor base clusters around three strategic archetypes: integrated petrochemical majors with in-house Group II/III base oil production, specialized lubricant formulators with captive additive blending networks, and regional blenders serving cost-sensitive mineral oil segments. Dominant competitive moves include backward integration into base oil production and technology licensing partnerships for synthetic formulation expertise.
Among European-headquartered specialists, FUCHS SE exemplifies the captive additive blending archetype through its Central European network, while Klüber Lubrication occupies a position representing high-performance synthetic gear oil specialization for precision machinery. ExxonMobil Corporation anchors the integrated petrochemical tier with global supply capabilities through Group II/III base oil production assets.
| Leading Market Players |
|---|
| TotalEnergies SE |
| FUCHS SE |
| ExxonMobil Corporation |
| Klüber Lubrication |
| Valvoline Inc. |
| Shell plc |
| BP plc |
| Lubrizol Corporation |
| Chevron Corporation |
| Others |
Supply Flow & Price Mechanics
Group II/III base oil spot indices in Asia set the floor for global gear oil pricing tiers, cascading through merchant feedstock markets into finished lubricant cost structures across European and North American blending operations.
Pricing Analysis
Input-cost pass-through from base oil and additive feedstocks stratifies pricing across premium, standard, and economy tiers. Synthetic PAO and PAG formulations command substantial premiums over mineral-based alternatives due to thermal stability certification requirements. Pricing pressure stems from Asian refiner concentration in high-viscosity Group III supply. Cost-sensitive cement plants in developing manufacturing corridors exhibit highest price sensitivity, while Australian mining operations demonstrate lowest sensitivity due to unplanned downtime costs.
Supply Chain Analysis
OEM qualification protocols and micropitting certification requirements gate supply relationships, particularly for wind turbine gearbox manufacturers demanding 10,000-hour field validation data. Base oil production concentrates in South Korea, Japan, and the United States. Additive packages draw from sulfur-phosphorus EP chemistry and boron-containing compounds. Single-source vulnerability pervades high-viscosity Group III supply. Distribution runs through regional blending facilities serving approved vendor lists at consolidated industrial procurement centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial gear oil market functions as a stable compounder, with equipment replacement cycles and regulatory reformulation mandates generating predictable recurring revenue across formulation generations.
For Market Incumbents: Deploy captive additive blending networks to defend formulation consistency against merchant feedstock volatility. Accelerate backward integration into Group II/III base oil production to reduce Asian refiner dependency. Deepen OEM approval pipelines for wind turbine gearbox applications where 10,000-hour validation requirements create certification moats. Counter regional formulation fragmentation by maintaining parallel REACH-compliant and GB-standard product streams. For New Entrants and Emerging Players: Launch via India's PLI scheme for heavy machinery to access localized blending demand outside traditional import channels. Target bio-based formulations for marine applications in the North Sea where PAG-based environmental compliance unifies previously conflicting requirements. Pursue digital oil condition monitoring partnerships to attach data-service revenue streams alongside lubricant sales. Concentrate initial penetration on semi-synthetic tiers where mineral-synthetic blending expertise transfers from adjacent lubricant categories. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized formulators possessing captive additive networks and established OEM approval portfolios. The five-to-ten year viability window favors assets with demonstrated micropitting certification and wind turbine gearbox validation data. Acquisition targets should display backward integration into base oil production or technology licensing partnerships for synthetic formulation expertise. Monitor REACH Annex XIV sunset dates for boron-containing additives as inflection indicators for reformulation-driven market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Reduces dependency on Asian Group III refiners for European blenders facing supply concentration risk. |
| REACH-Compliant Additive Substitution | Positions formulators ahead of boron-containing EP additive sunset dates in European markets. |
| Digital Oil Condition Monitoring Partnerships | Creates predictive maintenance revenue attach for sensor-embedded gearbox installations. |
| India PLI Scheme Localization | Captures domestic construction equipment manufacturing incentives outside traditional import channels. |
| Used Oil Re-Refining Integration | Aligns with EU circular economy mandates for closed-loop collection-to-base-oil recovery models. |
Methodological Framework
Coverage spans Asia-Pacific, Europe, North America, and Australia, with primary inputs from each region combined through structured interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and base oil production statistics. Bottom-up volume modeling triangulates against top-down market sizing across formulation technology tiers.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window, with segmentation modeling across synthetic, mineral, semi-synthetic, and bio-based formulation types. Application dimensions include machinery, marine, construction, and automotive end-uses. End-user intensity differentiates mining, power generation, manufacturing, and transportation segments. Viscosity grade specifications incorporate ISO standard, multi-grade, SAE, and high-temperature categories. CAGRs derive from equipment replacement cycle analysis and regulatory reformulation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH restriction enforcement or Group III supply disruption scenarios. Projections reflect assumptions regarding mining automation adoption rates, wind turbine gearbox scaling trajectories, and regional regulatory divergence persistence. A model refresh is warranted upon material change in base oil refinery capacity additions or PFAS regulatory designation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Poland Industrial Lubricants Market
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
United Kingdom Automotive Lubricants Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Africa Lubricants Market
Lubricants
South Korea Automotive Lubricants Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
United States Automotive Lubricants Market
Lubricants
Global Commercial Vehicles Lubricants Market
Lubricants
Open Gear Lubricants Market
Lubricants
Contact Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Malaysia Lubricants Market
Lubricants
Plastic Lubricants Market
Lubricants
Yarn Lubricant Market
Lubricants
Synthetic Ester Lubricants Market