
 Vietnam Automotive Lubricants Market | 2026-2036
Vietnam Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Automotive Lubricants Market Analytics
Multi-source procurement among fleet operators is rebalancing toward blended supply chains that combine international brands with domestic refiners. TotalEnergies leverages its blending facility in southern Vietnam to secure channel control across workshop networks. PVOIL anchors its position through captive crude access and state-backed distribution infrastructure. Shell competes on synthetic product ranges tailored to Japanese and Korean OEM specifications.
Vietnam automotive lubricants are formulated base oil and additive packages engineered to reduce friction, dissipate heat, and protect powertrain components under tropical humidity and stop-and-go traffic conditions, typically meeting API SP or ILSAC GF-6 performance thresholds. Engine oil dominates volume as motorcycle parc expansion sustains high-frequency drain intervals across the northern highlands and central coast. Fleet operators represent the fastest-growing end-user category as logistics companies consolidate maintenance contracts under single workshop banners. Offline retail through service stations and authorized distributors still occupies the primary margin pool despite digital channels gaining traction in urban centers.
Vietnam's Ministry of Transport enforces emission and lubricant quality standards through Circular 40/2019, while the Directorate for Standards, Metrology and Quality administers TCVN labeling and viscosity-grade compliance. These frameworks compel importers and blenders to certify products against evolving OEM warranty requirements, particularly for Euro 4 and Euro 5 commercial vehicle engines. Stakeholders must monitor whether domestic refiners accelerate Group II and Group III base oil production to reduce import dependency and capture margin currently flowing to Singapore and Thai suppliers.
Market Dynamics
Circular 40/2019 is compressing lubricant formulation cycles as Vietnam's Ministry of Transport enforces Euro 4 and Euro 5 emission thresholds, forcing blenders to accelerate Group II and Group III base oil adoption ahead of domestic refinery upgrades.
Growth Catalysts
- Motorcycle parc density:Two-wheeler fleet expansion across the Mekong Delta and Red River Delta sustains high-frequency drain intervals for mineral and semi-synthetic grades.
- Logistics consolidation:Commercial vehicle operators are bundling maintenance contracts under single workshop banners, concentrating bulk procurement of engine oils and transmission fluids.
- Circular 40/2019:The Ministry of Transport's emission standards are mandating lower-viscosity lubricant reformulation, creating certified product pull-through at authorized distributors.
Market Restraints
- Base oil import dependency:Vietnam lacks domestic Group II and Group III production, forcing blenders to source from Singapore and Thai refiners at volatile feedstock spreads.
- Synthetic grade cost premiums:Full synthetic formulations meeting ILSAC GF-6 specifications carry 40-60% price elevation over mineral grades, constraining penetration in price-sensitive northern highlands workshops.
- Informal channel leakage:Unlicensed resellers in Ho Chi Minh City's peripheral districts distribute uncertified lubricants, eroding warranty-compliant volume at authorized service stations.
Strategic Opportunities
- Central Coast logistics corridor:Da Nang's emerging expressway freight hub offers untapped fleet maintenance contracts as container traffic shifts from road-rail intermodal links.
- Digital workshop platforms:Urban service stations in Hanoi are piloting app-based oil change scheduling with integrated loyalty programs, capturing younger motorcycle owners.
- Extended drain interval marketing:Synthetic products positioned for tropical humidity conditions can command premium positioning through OEM co-branding with Japanese and Korean motorcycle assemblers.
Industry Challenges
- Lubricant technician certification:Workshop networks face scarcity of personnel trained in viscosity-grade matching for Euro 4 commercial engines, slowing Circular 40/2019 compliance rollout.
- Blending facility capex cycles:Domestic refiners require significant capital deployment to upgrade from Group I to Group II base oil output, delaying margin capture from import substitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Automotive Lubricants Market |
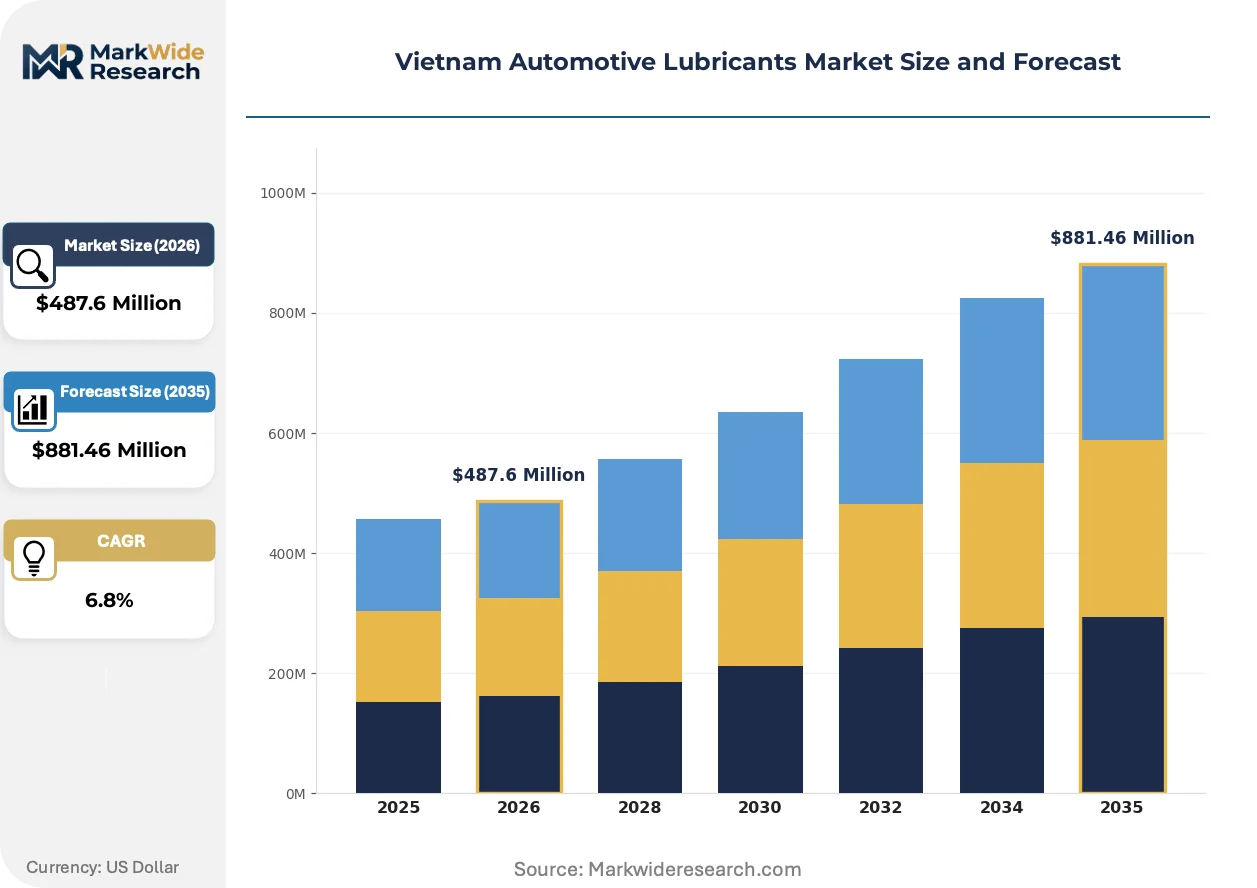
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Brake Fluid End User: OEMs, Workshops, Retailers, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Motorcycles Distribution Channel: Online Retail, Offline Retail, Distributors, Service Stations |
| Companies Covered | TotalEnergies, Mekong Petrochemical JSC, BP Plc (Castrol), PetroVietnam Oil Corporation (PVOIL), Motul S.A., Shell Plc, AP Saigon Petro JSC, Chevron Corporation, Petrolimex (PLX), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Automotive Lubricants Market Evolving Landscape
Additive package architectures are fragmenting as blenders seek tropical-specific formulations that address stop-and-go traffic heat dissipation without sacrificing fuel economy ratings.
Low-viscosity lubricant technology is modularizing around friction-modifier chemistries designed for small-displacement motorcycle engines operating under humid, high-load conditions. Fleet operators in the Red River Delta are piloting these grades ahead of drain interval extensions. The technology is modularizing service intervals into discrete, monitorable maintenance windows that align with telematics-enabled fleet management systems.
Vietnam's Ministry of Transport is tightening enforcement of TCVN labeling standards through spot inspections at border checkpoints and domestic blending facilities. Non-compliant shipments face detention until viscosity-grade verification is completed. Importers are responding by pre-certifying additive packages with the Directorate for Standards, Metrology and Quality to accelerate customs clearance.
Workshop procurement patterns are fragmenting as independent motorcycle service stations in Ho Chi Minh City diversify supplier relationships beyond single-brand dependencies. These operators now blend international synthetic ranges with domestic mineral grades to hit price points for distinct customer tiers. The shift is most visible in urban fringe districts where expressway commuter density is rising fastest.
Vietnam Automotive Lubricants Market Segmentation
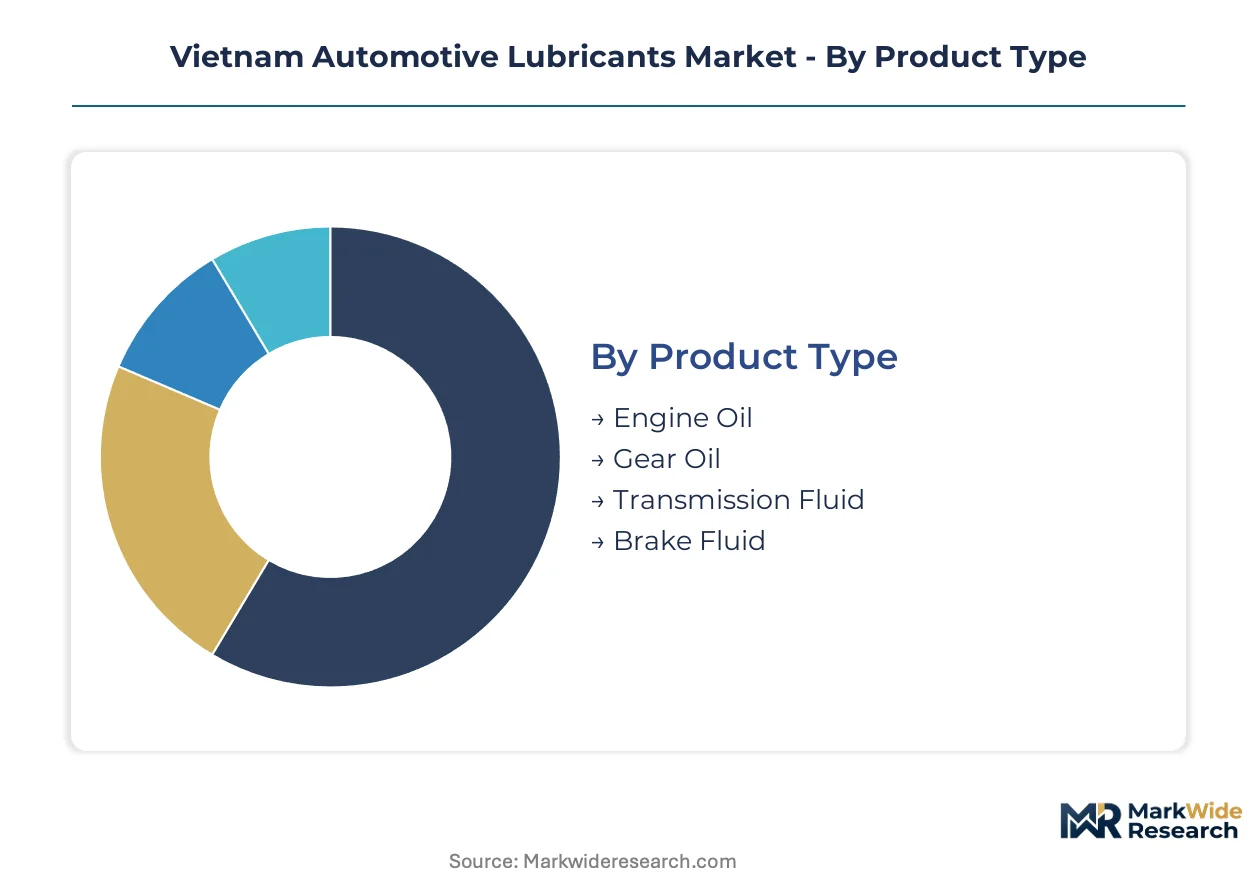
Segmentation in Vietnam's automotive lubricants market reveals how formulation requirements, procurement scale, and channel control interact to determine margin capture. Buyers across motorcycle workshops, commercial fleets, and OEM assembly plants prioritize different performance certifications and volume terms.
Product Type:
Buyers select lubricant categories based on drain interval frequency and OEM warranty compliance rather than price alone.
- Engine Oil:Formulated from Group I through Group III base stocks with additive packages meeting API SP or ILSAC GF-6 specifications. Demand concentrates in Ho Chi Minh City and Hanoi workshop networks where motorcycle parc density sustains high-frequency replacement cycles under tropical humidity and stop-and-go traffic conditions.
- Gear Oil:Extreme-pressure lubricants carrying GL-4 or GL-5 ratings for hypoid gear protection in commercial vehicle axles. Fleet operators across the Red River Delta logistics corridor are consolidating procurement of these grades under single-banner maintenance contracts as expressway freight volumes climb.
- Transmission Fluid:ATF and CVT formulations with friction-modifier chemistries for Japanese and Korean OEM specifications.
- Brake Fluid:DOT 3 and DOT 4 hygroscopic fluids requiring periodic replacement in high-humidity climates.
Volume sits with engine oil across motorcycle service intervals; growth tilts toward synthetic transmission fluids as CVT penetration expands in urban passenger vehicle fleets.
End User:
Procurement scale and technical specification authority separate these buyer categories.
- OEMs:Assembly plants specify first-fill lubricants during vehicle production, requiring direct blender relationships and batch certification against Japanese and Korean parent company standards.
- Workshops:Authorized service stations and independent repair shops in Ho Chi Minh City and Hanoi purchase bulk engine oils for drain-and-fill services, with synthetic grade uptake constrained by price-sensitive customer bases in peripheral districts.
- Retailers:General trade outlets and automotive parts stores stock packaged lubricants for DIY consumers, primarily mineral grades in 1-liter motorcycle oil formats.
- Fleet Operators:Logistics companies across the Mekong Delta and Central Coast are bundling maintenance contracts under single workshop banners, concentrating bulk procurement of engine oils and transmission fluids with extended drain interval terms.
Workshops dominate transaction frequency; fleet operators are expanding most quickly as commercial vehicle parc consolidation accelerates.
Application:
Vehicle parc composition and operating duty cycles determine lubricant performance requirements and replacement frequency.
- Passenger Vehicles:Sedans and SUVs operating on expressway corridors require synthetic and semi-synthetic grades meeting Euro 4 and Euro 5 emission compatibility, with demand clustering in Hanoi and Ho Chi Minh City urban cores.
- Commercial Vehicles:Trucks and buses traversing the North-South expressway network consume heavy-duty engine oils with extended drain intervals, with fleet procurement concentrated through Red River Delta and Mekong Delta logistics hubs.
- Heavy Machinery:Construction and agricultural equipment operating in central highland provinces requires hydraulic fluids and universal tractor transmission oils with high soot-handling capacity.
- Motorcycles:Two-wheelers dominate Vietnam's vehicle parc, sustaining high-frequency mineral and semi-synthetic oil changes across northern highlands, central coast, and southern delta regions where commuter density is highest.
Motorcycle applications anchor absolute volume; commercial vehicle lubricants are gaining share fastest as logistics fleet standardization advances.
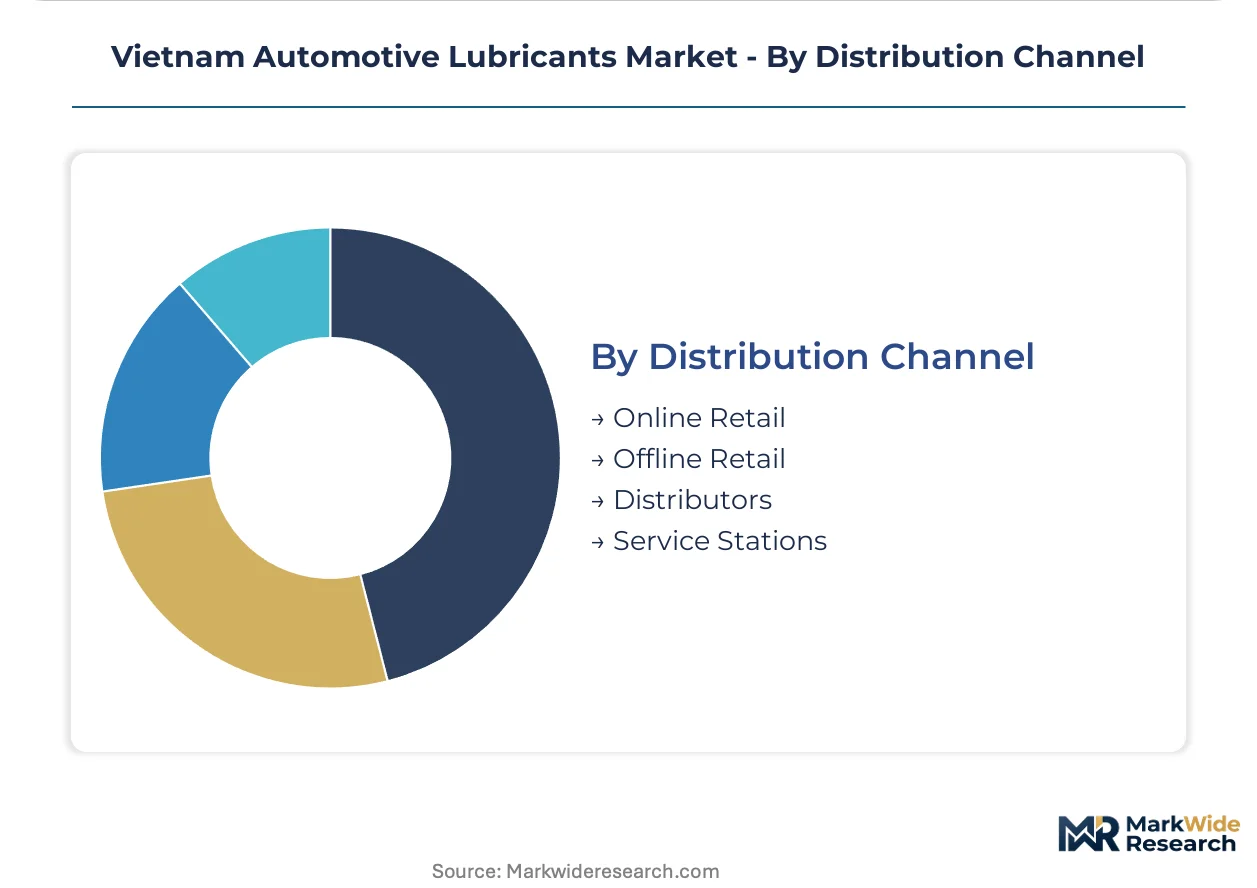
Distribution Channel:
Channel selection reflects buyer urgency, technical support needs, and certification verification requirements.
- Online Retail:E-commerce platforms and lubricant brand direct-to-consumer sites serve urban motorcycle owners seeking price transparency, though penetration remains limited by warranty verification concerns and immediate service needs.
- Offline Retail:General trade stores and automotive parts shops in Ho Chi Minh City fringe districts supply packaged lubricants to DIY consumers and small independent workshops, capturing the primary margin pool for mineral grade volumes.
- Distributors:Authorized distributors with bonded warehouse facilities manage import logistics and TCVN labeling compliance, serving as the critical intermediary between Singapore and Thai base oil suppliers and domestic blending facilities.
- Service Stations:Branded workshop networks and expressway service plazas provide drain-and-fill services with certified lubricant application, with loyalty programs and app-based scheduling emerging in Hanoi urban centers to capture younger motorcycle owners.
Service stations and distributors control certified product flow; digital channels are climbing fastest among urban commuter segments seeking convenience scheduling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Base oil import corridors from Singapore and Thai refiners anchor Vietnam's lubricant supply geography, with domestic blending capacity clustering near southern port infrastructure and northern industrial zones.
Ho Chi Minh City
Expressway logistics hubs and motorcycle workshop density sustain bulk engine oil procurement across southern Vietnam's commercial vehicle networks. Circular 40/2019 enforcement by the Ministry of Transport accelerates lower-viscosity grade adoption at authorized service stations. District 12 and Thu Duc City industrial parks concentrate blending facilities serving Mekong Delta fleet operators.
Hanoi
Red River Delta logistics consolidation drives transmission fluid demand from commercial vehicle maintenance contracts. The Directorate for Standards, Metrology and Quality administers TCVN labeling compliance at northern border checkpoints. Long Bien and Gia Lam districts host distributor warehouses managing Singapore-sourced Group II base oil inventories.
Da Nang
Central Coast expressway freight growth creates untapped fleet maintenance opportunities as container traffic shifts from road-rail intermodal links. Vietnam's emission standards push workshop networks toward certified synthetic product ranges. Lien Chieu Industrial Park anchors regional distribution for Japanese OEM specification lubricants.
Binh Duong
Manufacturing corridor expansion sustains heavy machinery hydraulic fluid demand from construction and agricultural equipment operators. Domestic refiners face capital deployment pressure to upgrade Group I base oil output. My Phuoc Industrial Zone concentrates captive blending for state-backed distribution infrastructure.
Hai Phong
Northern port logistics and manufacturing supply chains drive gear oil procurement for commercial vehicle axle protection. Import dependency on Thai Group III base stocks creates volatile feedstock spread exposure. Dinh Vu Industrial Zone handles bonded warehouse facilities for pre-certified additive package clearance.
Vietnam Automotive Lubricants Market Competitive Landscape
Capacity expansion dominates the current landscape as blenders accelerate Group II and Group III base oil adoption ahead of domestic refinery upgrades. The market structures around three tiers: international majors with captive blending facilities, state-backed domestic refiners with distribution control, and independent distributors serving price-sensitive workshop networks. Strategic archetypes include synthetic product specialists targeting OEM specifications, mineral grade volume players capturing motorcycle service intervals, and logistics-integrated fleet contract bundlers. Competitive moves concentrate on blending facility localization and distributor network exclusivity arrangements.
Among international majors with Vietnamese blending presence, TotalEnergies and Shell exemplify the synthetic-grade premium tier, while PVOIL anchors the state-backed domestic refiner archetype with captive crude access. These three occupy positions reflecting divergent strategic foundations: southern facility control, OEM specification alignment, and state distribution infrastructure respectively.
| Leading Market Players |
|---|
| TotalEnergies |
| Mekong Petrochemical JSC |
| BP Plc (Castrol) |
| PetroVietnam Oil Corporation (PVOIL) |
| Motul S.A. |
| Shell Plc |
| AP Saigon Petro JSC |
| Chevron Corporation |
| Petrolimex (PLX) |
| Others |
Value Network & Pricing Analysis
State-backed refiners with captive crude access anchor Vietnam's lubricant supply base, compressing pricing discipline as PVOIL and Petrolimex leverage distribution infrastructure to defend margin pools against international blenders. This ownership pattern ties supply security to pricing floors, with sovereign backing enabling below-market financing for blending facility upgrades that private operators cannot match.
Pricing Analysis
Warranty-compliant service bundling at authorized workshops commands 25-35% premiums over unbundled drain-and-fill transactions at independent stations. Pricing stratifies across synthetic OEM-specification grades, semi-synthetic mid-tier formulations, and mineral economy products, with differentiation driven by API certification level and volume procurement scale. Cost compression in the mineral grade tier is intensifying because informal channel leakage erodes authorized distributor volumes. Fleet operators in the Red River Delta exhibit lowest price sensitivity due to consolidated maintenance contracts, while peripheral Hanoi workshops serving individual motorcycle owners show highest elasticity.
Supply Chain Analysis
Skilled blending technician scarcity in Vietnam's southern industrial zones and northern port corridors constrains domestic capacity expansion despite feedstock availability. Supply concentrates in Singapore, Thailand, and South Korea as source markets for Group II and Group III base stocks, with Vietnamese blenders drawing from Singaporean refiners for premium feedstock and Thai suppliers for mid-tier volumes. Single-source vulnerability runs through the Singapore-Johor Strait logistics corridor where customs delays at Vietnamese border checkpoints compound lead time uncertainty. Distribution runs through authorized distributors with bonded warehouse facilities managing TCVN labeling compliance before downstream release to workshop networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's automotive lubricants sector is consolidating around blending capacity and distribution control, with Circular 40/2019 compliance costs forcing sub-scale mineral-grade distributors toward exit or acquisition.
For Market Incumbents: Deploy captive blending facility investments in District 12 and Thu Duc City industrial parks to lock in Mekong Delta fleet contracts before domestic refiners complete Group II upgrades. Channel control through exclusive workshop banners defends against synthetic-grade entrants targeting Japanese OEM specifications, while pre-certification of additive packages with the Directorate for Standards, Metrology and Quality accelerates customs clearance velocity relative to import-dependent competitors. For New Entrants and Emerging Players: The 40-60% price elevation gap between full synthetic and mineral grades opens white-space at the semi-synthetic tier for CVT transmission fluid formulations targeting urban passenger vehicle fleets in Da Nang and Hai Phong. Digital workshop platforms with app-based scheduling capture younger motorcycle owners in Hanoi urban cores where convenience premiums override brand loyalty. Partner with emerging logistics consolidators in the Central Coast corridor to embed lubricant procurement into bundled fleet maintenance contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent distributors with bonded warehouse infrastructure in Long Bien and Gia Lam districts, where import dependency on Thai Group III base stocks has compressed working capital cycles. Five-to-ten year viability hinges on whether domestic refiners accelerate Group II production or perpetuate Singaporean feedstock reliance. Monitor PVOIL capital deployment announcements for blending facility upgrades as the inflection signal for margin capture shifting from international to domestic supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Domestic Group II output reduces Singaporean import dependency and captures feedstock margin. |
| Digital Workshop Platform Launch | App-based scheduling with loyalty programs locks in Hanoi motorcycle commuter segments. |
| Extended Drain Interval Certification | OEM co-branding with Japanese assemblers commands synthetic grade premiums in tropical conditions. |
| Central Coast Logistics Corridor Expansion | Da Nang fleet maintenance contracts capture container traffic shifting from road-rail intermodal links. |
| TCVN Pre-Certification Investment | Directorate for Standards, Metrology and Quality alignment accelerates customs clearance velocity. |
Research Methodology
Trade databases, customs records, and SEC filings from listed energy majors formed the secondary backbone, cross-referenced with primary interviews involving lubricant blending plant managers, fleet procurement leads at Mekong Delta logistics operators, authorized distributor channel heads, and technical R&D directors at additive package suppliers. Bottom-up volume estimates from workshop transaction frequencies and top-down value projections from import value data were triangulated to constrain forecast variance.
Historical trendline analysis of base oil import volumes and lubricant production capacity informed the projection framework across the analysis window, with segmentation modeling across product type, end user category, vehicle application, and distribution channel. CAGRs were derived from regression analysis of correlated indicators including motorcycle parc expansion rates, commercial vehicle fleet consolidation trends, and emission standard implementation timelines. Forecast inputs incorporated Circular 40/2019 enforcement intensity assumptions and domestic refinery upgrade completion schedules.
Underlying measurement precision varies by segment; engine oil volumes carry tighter precision than transmission fluid projections due to higher transaction frequency visibility. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and base oil import corridor stability. Material deviation in domestic refinery upgrade timelines or Singapore-Thai feedstock pricing volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Canada Automotive Lubricants Market
Lubricants
Asia-Pacific Commercial Vehicles Lubricants Market
Lubricants
Global Lubricant Antioxidants Market
Lubricants
United Kingdom Lubricants Market
Lubricants
Russia Lubricants Market
Lubricants
Malaysia Automotive Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Yarn Lubricant Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Offshore Lubricants Market
Lubricants
Global Compressor Oil Market
Lubricants
Technical Fluids Market
Lubricants
Canada Commercial Vehicles Lubricants Market
Lubricants
South Korea Commercial Vehicles Lubricants Market