
 Europe Motor Home Market | 2026-2036
Europe Motor Home Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Motor Home Market Foresight
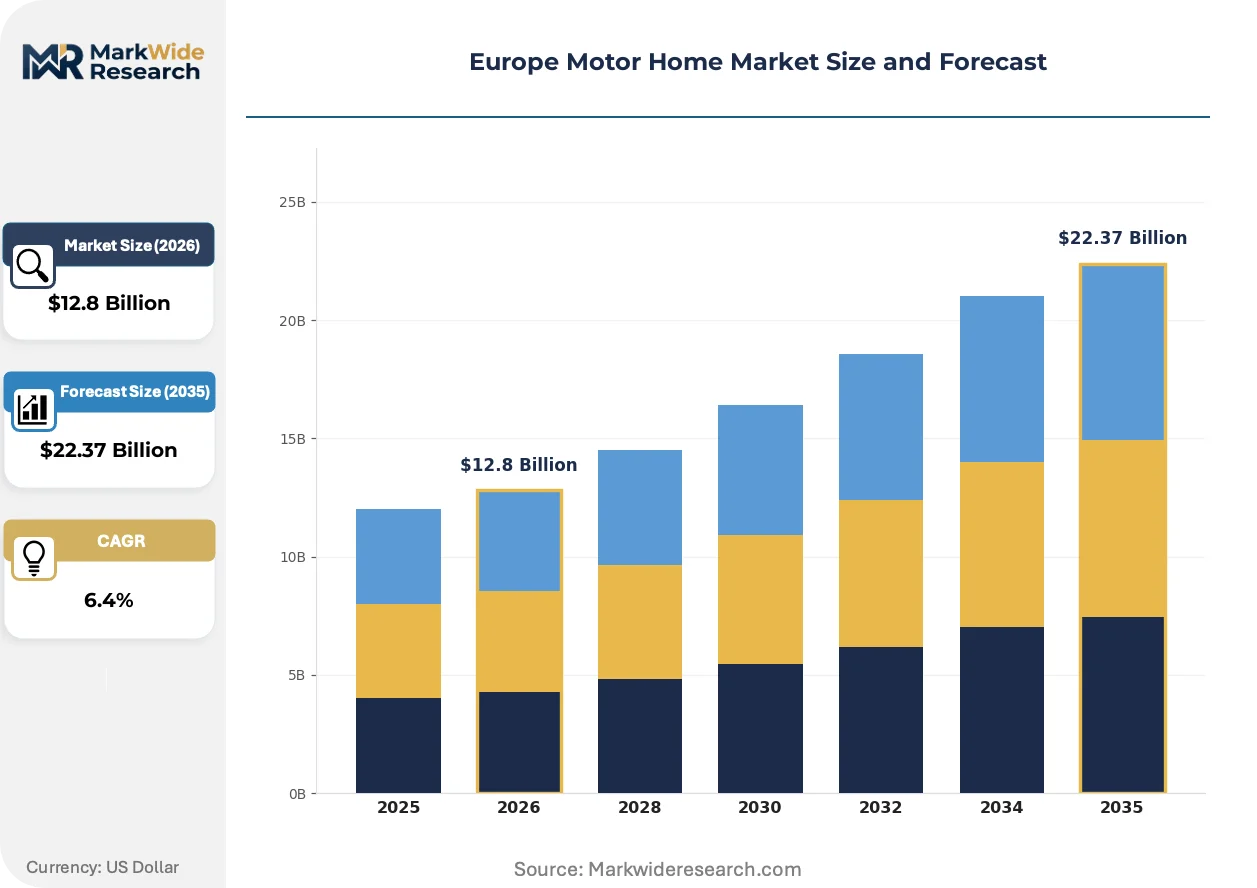
The EU Green Deal is pivoting motor home demand toward low-emission propulsion systems across European markets. Erwin Hymer Group leverages its integrated manufacturing footprint in Germany to control chassis supply and accelerate electrified platform development. Trigano anchors southern European demand through specialized brands targeting Mediterranean leisure routes. Knaus Tabbert competes on manufacturing scale, sustaining one of Europe's largest production volumes across multiple price tiers.
A motor home is a self-propelled recreational vehicle built on a truck or van chassis, incorporating living accommodations with sleeping, cooking, and sanitation facilities, typically ranging from six to twelve meters in length and constructed using composite sandwich panels or aluminum framing for weight reduction. Its primary commercial purpose is to provide mobile temporary lodging for tourism, seasonal migration, and remote work applications. Class A units dominate value pools due to premium pricing and high-margin customization options, while electric and hybrid propulsion categories represent the fastest-growing segment as battery energy density improves and charging infrastructure expands along major European transit corridors. The diesel category retains volume leadership but faces structural decline as urban access restrictions tighten in France, Germany, and Italy.
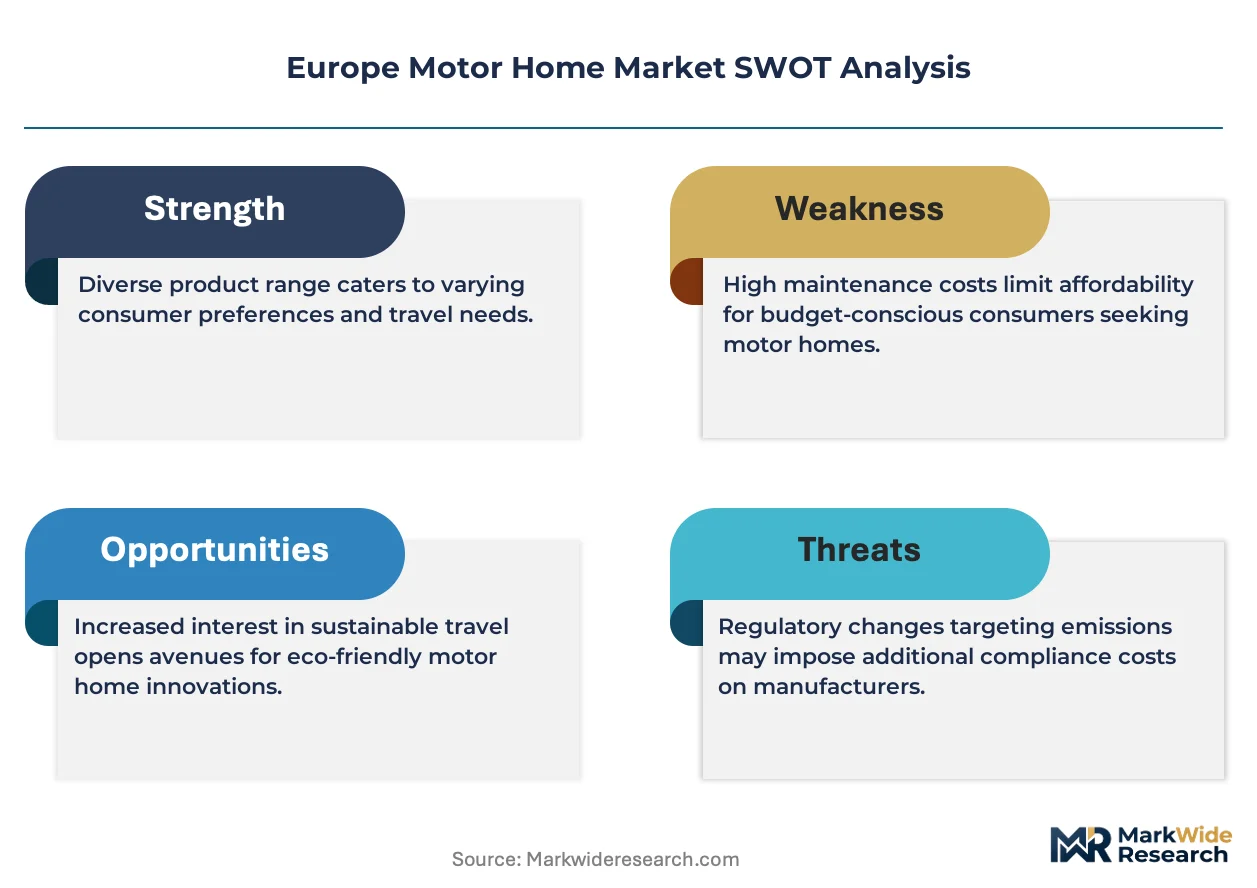
The EU Green Deal, REACH chemical standards, and national type-approval frameworks under the EU Whole Vehicle Type Approval system shape product design, material selection, and market access across member states. EMA and national regulators in Germany and France are intensifying scrutiny of interior air quality and end-of-life recyclability requirements. Stakeholders must monitor the trajectory of electric chassis availability from commercial vehicle suppliers and the pace of harmonized charging standards to align production planning with regulatory compliance timelines.
Market Dynamics
The EU Green Deal's diesel phase-out timeline is compressing chassis procurement cycles and forcing manufacturers to secure electric platform supply before commercial vehicle OEMs scale production. This regulatory velocity is restructuring competitive positioning around electrified powertrain access rather than traditional interior fit-out capabilities.
Growth Catalysts
- EU Green Deal decarbonization mandates:National diesel restrictions in France, Germany, and Italy are pulling forward replacement demand from commercial fleet operators and individual owners toward low-emission platforms. The regulatory clarity is reducing purchase hesitation among buyers who previously deferred electrified investments.
- Remote worker demographic expansion:Digital nomad visa programs in Portugal, Spain, and Croatia are creating sustained seasonal demand for fully equipped motor homes with dedicated workspace configurations. This buyer segment prioritizes connectivity infrastructure and extended off-grid capability.
- Battery energy density improvements:Lithium-ion pack configurations now enable 300+ kilometer ranges on single charges, eliminating range anxiety for Mediterranean coastal routes and Alpine transit corridors. Charging infrastructure deployment along European E-road networks is expanding into campsite locations.
Market Restraints
- Electric chassis supply concentration:Commercial vehicle OEMs in Germany and Sweden control the majority of available electric platform allocation, creating procurement bottlenecks for motor home builders without long-term supply agreements. Chassis scarcity is extending order-to-delivery timelines beyond eighteen months.
- Composite panel input cost volatility:Aluminum and fiberglass resin prices fluctuate with energy market dynamics, compressing gross margins on entry-segment units where material cost pass-through is constrained by price-sensitive buyers. Energy-intensive manufacturing clusters in Germany face additional carbon border adjustment exposure.
- Urban access restriction proliferation:Low-emission zones in Paris, Milan, and Barcelona now exclude pre-2016 diesel motor homes, creating asset depreciation risk for existing owners and dampening resale values for non-compliant used inventory.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland, Romania, and Hungary exhibit motor home ownership rates below one-third of German levels, with campsite infrastructure investment accelerating along Danube and Baltic corridors. Local dealer networks remain fragmented, creating entry pathways for established brands.
- Vehicle-to-grid integration:Bidirectional charging capability transforms motor homes into mobile power assets for campsite operators and emergency services, opening B2B revenue streams beyond traditional leisure applications. Grid services contracts in Germany and the Netherlands are piloting this model.
- EU taxonomy-aligned green financing:Sustainable finance disclosure requirements are channeling institutional capital toward electrified recreational vehicle fleets, reducing cost of capital for buyers and lease operators. National recovery funds in Italy and Spain include motor home tourism in rural development allocations.
Industry Challenges
- High-voltage technician scarcity:Service networks across France, Italy, and Spain lack certified personnel for battery system diagnostics and thermal management repairs, extending warranty resolution times and elevating customer dissatisfaction scores.
- EU Whole Vehicle Type Approval complexity:Harmonized certification for electrified platforms requires concurrent chassis and bodybuilder approvals, creating timeline coordination risks between commercial vehicle suppliers and motor home manufacturers.
- Legacy dealer system digitization gaps:Traditional distribution channels in Southern Europe lack configurators and reservation systems that remote-worker buyers expect, forcing manufacturers to absorb direct-to-consumer capability investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Motor Home Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Class A, Class B, Class C, Truck Camper Propulsion: Diesel, Petrol, Electric, Hybrid, LPG Customer Type: Tour Operators, Rental Companies, Individual Owners, Leisure Enthusiasts Distribution Channel: Dealerships, Online Marketplaces, Motor Shows, Fleet Sales |
| Companies Covered | Erwin Hymer Group, Trigano, Thor Industries, Knaus Tabbert, Adria Mobil, Swift Group, Dethleffs, Rapido Group, Bürstner, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Motor Home Market Shifts & Advancements
Electrification is rewriting product architecture requirements while connectivity and lightweight materials reshape buyer expectations. Three concurrent developments are compressing traditional design cycles and opening new competitive vectors.
Solid-state battery prototypes are expanding into motor home platform development, offering energy density improvements that enable extended off-grid operation without weight penalties. Erwin Hymer Group and Knaus Tabbert are prioritizing these configurations for premium Class A units targeting remote-worker buyers. The technology is expanding into price tiers previously reserved for combustion platforms, compressing the electrification timeline across the entire product stack.
REACH chemical standards are restricting flame-retardant and adhesive formulations used in interior panel bonding, forcing material substitutions that must satisfy ECHA substance evaluation timelines. German and French manufacturers are accelerating bio-based composite testing to preempt authorization bottlenecks. The regulation is compressing supplier qualification cycles and elevating R&D coordination costs for multi-brand portfolios.
Subscription and fractional ownership models are displacing traditional retail purchase patterns among urban buyers in Germany and the Netherlands who prioritize access over asset ownership. Peer-to-peer rental platforms are capturing younger demographic segments that manufacturers previously failed to convert. This behavioral shift is most visible in Berlin and Amsterdam, where parking constraints and seasonal usage patterns favor flexible access arrangements over permanent ownership.
Europe Motor Home Market Segmentation
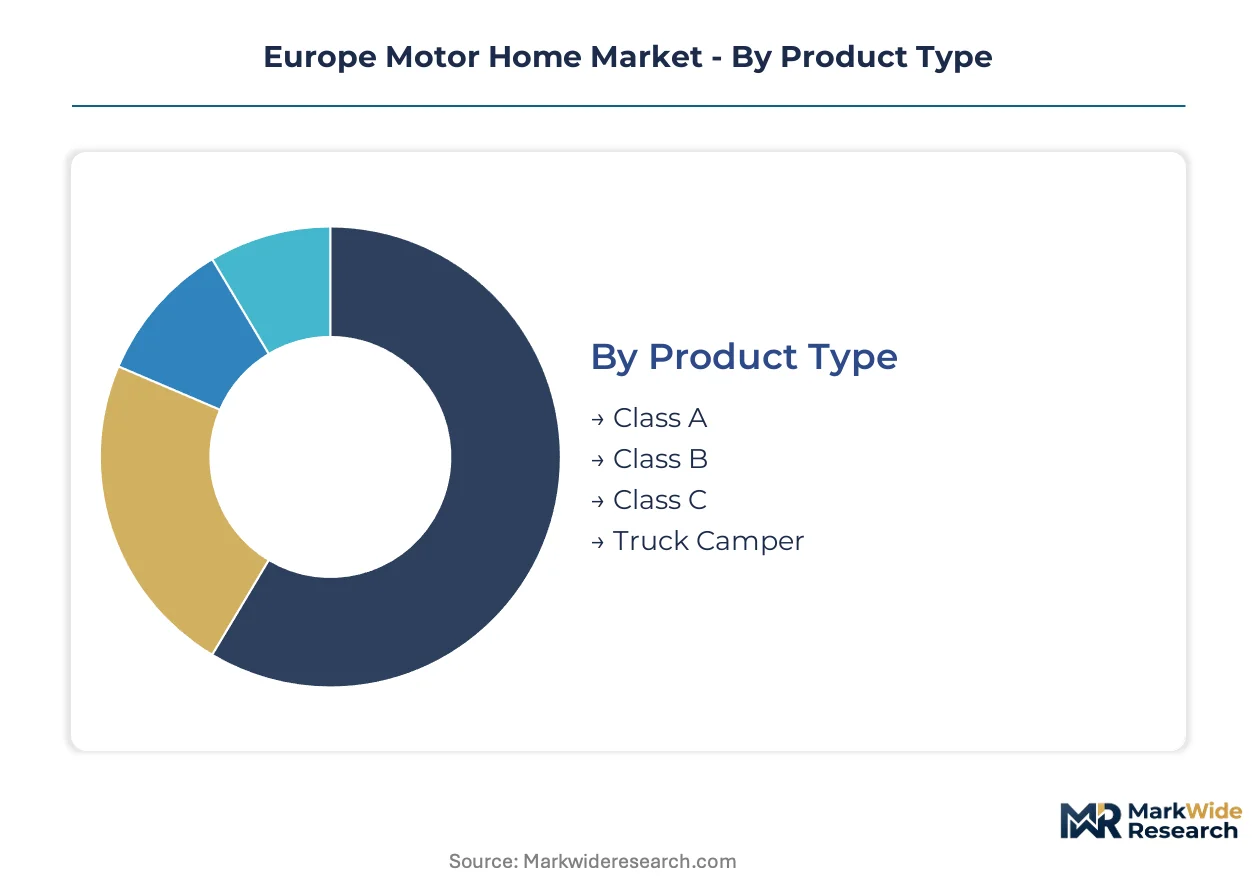
Motor home segmentation in Europe reflects divergent certification burdens across propulsion technologies and divergent margin structures across customer channels. Understanding these divides clarifies where EU Whole Vehicle Type Approval complexity concentrates and where electrification investments will reshape competitive positioning first.
Product Type:
EU Whole Vehicle Type Approval requirements intensify with vehicle mass and integrated systems complexity, placing heavier compliance burdens on larger platform categories.
- Class A:Built on dedicated bus or truck chassis with integrated living quarters extending the full vehicle width. Demand concentrates in Germany and France among retiree buyers seeking premium customization and extended Alpine touring capability.
- Class B:Van-conversion units leveraging standard commercial van platforms with modified interiors. The segment is climbing fastest among remote workers in Portugal and Spain who prioritize urban maneuverability and digital nomad visa compliance.
- Class C:Cab-over designs mounted on cutaway van or light truck chassis, balancing interior volume with drivability. French and Italian families favor these for Mediterranean coastal routes.
- Truck Camper:Detachable living modules mounted on pickup truck beds, offering modularity for off-road exploration. German outdoor enthusiasts and Eastern European hunting tourism operators drive niche demand.
Class A sits at the top of the volume ranking, with Class B climbing the fastest.
Propulsion:
Cost tier stratification separates premium electrified platforms from legacy combustion segments, with hybrid configurations capturing buyers in transition zones.
- Diesel:Dominant installed base with established service networks across France, Italy, and Germany. Urban access restrictions in Paris, Milan, and Barcelona are compressing residual values and accelerating trade-in cycles toward compliant alternatives.
- Petrol:Lower upfront cost suits entry-segment buyers in Poland and Hungary where fuel price sensitivity outweighs range optimization. Limited availability from chassis suppliers constrains manufacturer portfolio breadth.
- Electric:Battery-electric platforms with 300+ kilometer ranges are gaining share fastest among Dutch and German fleet operators piloting campsite vehicle-to-grid integration. E-road charging corridor expansion and EU Green Deal subsidies reduce total cost of ownership gaps.
- Hybrid:Plug-in hybrid architectures bridge range anxiety and zero-emission zone compliance for buyers traversing mixed urban-rural itineraries. Italian and Spanish coastal tourism routes favor this flexibility.
- LPG:Liquefied petroleum gas conversions offer cost-per-kilometer advantages in markets with refueling infrastructure, particularly rural Germany and Eastern European corridors.
Diesel retains volume leadership despite regulatory headwinds, while electric platforms are expanding most quickly in fleet and premium retail channels.
Customer Type:
Application-driven procurement patterns separate high-volume standardized orders from low-volume customized configurations with divergent margin profiles.
- Tour Operators:Fleet purchasers in Germany and France ordering standardized Class C and Class A units for packaged Alpine and Mediterranean circuits. Volume concentration enables direct manufacturer negotiations bypassing dealer networks.
- Rental Companies:Asset-light operators in Portugal, Spain, and Croatia scaling seasonal fleets to capture digital nomad visa demand. Depreciation schedules and connectivity specifications dominate procurement criteria.
- Individual Owners:German and French retirees financing purchases through EU taxonomy-aligned green lending products. Extended warranty and service package attachment rates exceed rental channel benchmarks.
- Leisure Enthusiasts:Italian and Austrian outdoor recreation buyers prioritizing off-grid capability and lightweight construction for mountain access. Customization depth and brand community affiliation drive selection.
Individual Owners sit at the top of the volume ranking, with Rental Companies climbing the fastest.
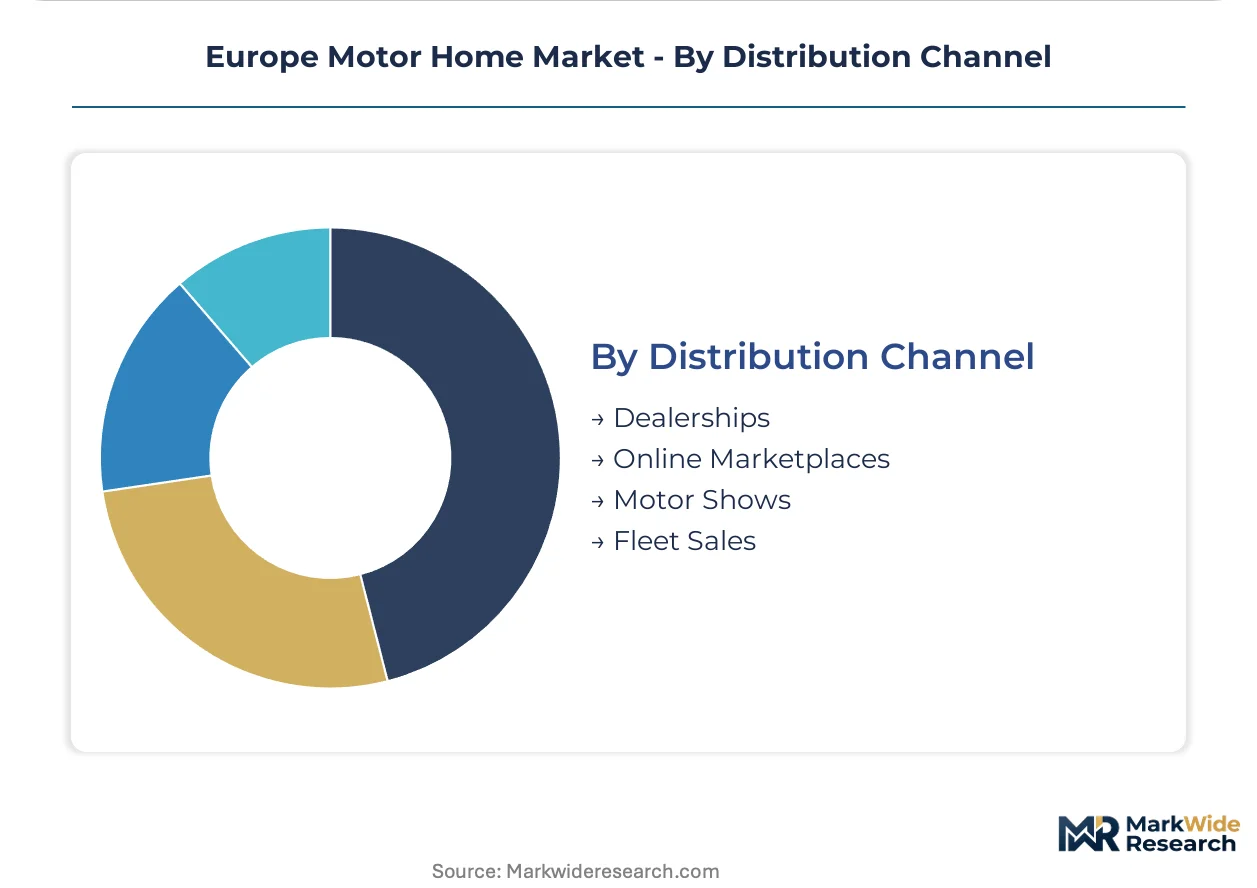
Distribution Channel:
Geographic concentration of buyer decision-making separates markets where physical inspection dominates from those transitioning toward digital configuration.
- Dealerships:Established networks in Germany, France, and Italy with service bay capacity and chassis modification expertise. Southern European dealers lag in electrified platform technical certification.
- Online Marketplaces:Configurator-based sales gaining traction among Dutch and German remote workers prioritizing specification transparency over test drive rituals. Manufacturer direct-to-consumer investments bypass legacy dealer digitization gaps.
- Motor Shows:Düsseldorf Caravan Salon and Paris Motor Show anchor annual order cycles for premium Class A and custom builds. Order-to-delivery timelines for showcased prototypes influence full-year production scheduling.
- Fleet Sales:Direct procurement by rental and tour operators concentrated in German manufacturing clusters. Long-term supply agreements with commercial vehicle OEMs secure electric chassis allocation ahead of retail channel availability.
Dealerships sit at the top of the volume ranking, with Online Marketplaces climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered motor home manufacturing in post-war Europe, establishing Baden-Württemberg and Bavaria as the continent's original production corridors where chassis engineering and bodybuilder craftsmanship first converged at scale.
Germany
Retiree buyers in Baden-Württemberg and Bavaria sustain replacement cycles for premium Class A units with extended Alpine touring capability. The EU Green Deal diesel phase-out timeline accelerates fleet renewal toward electric platforms. Manufacturing clusters around Stuttgart and Munich host Erwin Hymer Group and Knaus Tabbert production facilities with captive chassis modification expertise.
France
Families in Provence-Alpes-Côte d'Azur and Auvergne-Rhône-Alpes favor Class C cab-over designs for Mediterranean coastal routes. Low-emission zones in Paris now exclude pre-2016 diesel units, compressing residual values and pulling forward trade-in demand. Trigano anchors southern European demand through specialized brands targeting leisure tourism circuits.
Italy
Leisure enthusiasts in Lombardy and Veneto prioritize lightweight construction and off-grid capability for mountain access. National diesel restrictions in Milan and Rome tighten urban access for non-compliant inventory. Manufacturing concentration in the industrial triangle between Milan, Turin, and Bologna supports rapid customization turnaround for export markets.
Spain
Digital nomad visa programs in Catalonia and Andalusia create sustained seasonal demand for Class B van conversions with dedicated workspace configurations. E-road charging corridor expansion along Mediterranean transit routes reduces range anxiety for electrified platforms. Campsite infrastructure investment accelerates along Costa Brava and Costa del Sol corridors.
Netherlands
Remote workers in Randstad urban centers prioritize subscription and fractional ownership models over permanent asset acquisition. Vehicle-to-grid pilot programs with campsite operators transform motor homes into mobile power assets. Amsterdam and Rotterdam parking constraints favor flexible access arrangements and compact Class B configurations.
Europe Motor Home Market Competitive Landscape
Premium-margin players sit above commodity-margin players across electrification readiness and chassis supply security, with integrated manufacturers commanding pricing power over bodybuilder-only competitors. The vendor base clusters into three tiers: full-stack producers with captive chassis relationships, specialized bodybuilders dependent on external platform supply, and regional assemblers serving price-sensitive Eastern European entry segments. Dominant competitive moves include securing long-term electric chassis allocation agreements with commercial vehicle OEMs and accelerating direct-to-consumer digital configuration capabilities to bypass legacy dealer digitization gaps.
Among Germany-based integrated manufacturers, Erwin Hymer Group and Knaus Tabbert occupy positions exemplifying full-stack production archetypes with captive supply chain control. Trigano represents the southern European specialist model, anchoring Mediterranean leisure demand through brand portfolio breadth. These three entities collectively illustrate how electrification investments and chassis procurement security now determine competitive positioning more than traditional interior fit-out capabilities.
| Leading Market Players |
|---|
| Erwin Hymer Group |
| Trigano |
| Thor Industries |
| Knaus Tabbert |
| Adria Mobil |
| Swift Group |
| Dethleffs |
| Rapido Group |
| Bürstner |
| Others |
Supply & Pricing Matrix
Aluminum LME spot pricing volatility cascades through composite panel manufacturing into three distinct motor home pricing tiers, with energy-intensive German production clusters facing additional carbon border adjustment exposure that compresses margins on entry-segment units.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the European motor home market, with differentiation driven by chassis electrification status and EU Whole Vehicle Type Approval certification grade. Premium electrified Class A units from integrated German manufacturers command substantial markups over bodybuilder-assembled alternatives, while price erosion runs through the entry diesel segment as urban access restrictions in Paris and Milan depress residual values. Fleet buyers negotiating direct manufacturer contracts exhibit lowest price sensitivity, whereas Polish and Hungarian retail purchasers in the petrol segment demonstrate highest elasticity to material cost pass-through.
Supply Chain Analysis
EU Whole Vehicle Type Approval certification gating concentrates chassis supply among German and Swedish commercial vehicle OEMs, creating allocation bottlenecks that extend order-to-delivery timelines. Manufacturing gravity centers on Baden-Württemberg and Bavaria in Germany, with secondary clusters in northern Italy and eastern France drawing from shared aluminum and fiberglass resin supplier networks. Single-source vulnerability persists for lithium-ion battery packs and electric drive units, with distribution running through established dealership networks in Western Europe and fragmented local assemblers in Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European motor home market functions as a geographic-arbitrage play between Western European electrification mandates and Eastern European cost-advantaged manufacturing, with Polish and Romanian production zones offering labor and facility cost differentials exceeding German levels.
For Market Incumbents: Anchor competitive position through long-term electric chassis allocation agreements with German and Swedish commercial vehicle OEMs before platform scarcity intensifies. Secure backward integration into composite panel production to mitigate aluminum price volatility exposure. Prioritize service network electrification certification to preempt high-voltage technician scarcity that threatens warranty resolution times. For New Entrants and Emerging Players: Campsite operators and peer-to-peer rental platforms represent the most accessible channel partners for bypassing legacy dealer digitization gaps. Target Poland, Romania, and Hungary where motor home ownership rates sit below one-third of German benchmarks and local dealer networks remain fragmented. Pursue subscription-model partnerships with Dutch and German urban buyers prioritizing access over asset ownership. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale bodybuilders possessing established electric platform retrofit expertise and Eastern European manufacturing footprints. Long-term viability hinges on electrification transition completion within the next decade. Monitor electric chassis allocation agreement announcements from commercial vehicle OEMs as the critical inflection signal for production scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Chassis Supply Agreement | Secures platform allocation from German OEMs before retail channel scarcity intensifies. |
| Vehicle-to-Grid Capability Integration | Opens B2B revenue streams with Dutch campsite operators piloting grid services contracts. |
| Eastern European Manufacturing Footprint | Captures cost arbitrage in Poland and Romania while serving underpenetrated local demand. |
| Direct-to-Consumer Digital Configurator | Bypasses Southern European dealer digitization gaps that frustrate remote-worker buyers. |
| Solid-State Battery Platform Development | Positions premium Class A units for extended off-grid operation targeting Alpine and Mediterranean routes. |
Research Methodology
Multiple input streams — executive interviews with motor home manufacturer platform engineers and procurement directors, dealer network operational assessments, and regulatory filing analysis — were reconciled against vehicle production databases and national registration statistics from Germany, France, and Italy. Primary fieldwork encompassed conversations with campsite operators, commercial vehicle OEM supply chain managers, and electrification infrastructure developers. Secondary validation drew from EU Whole Vehicle Type Approval documentation, ECHA REACH substance evaluations, and national low-emission zone regulatory filings. Bottom-up unit economics modeling and top-down market sizing triangulation ensured cross-verification.
Data-stream reconciliation across the analysis window applied segmentation dimensions spanning propulsion architecture, vehicle class, customer channel, and regional regulatory cluster. CAGRs were derived through logistic adoption curve fitting for electrified platforms and replacement cycle analysis for diesel phase-out compliance. Industry-specific forecast inputs incorporated electric chassis allocation timelines from commercial vehicle suppliers and campsite infrastructure investment pipelines along Danube and Baltic corridors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery energy density improvement trajectories and harmonized charging standard adoption rates. Model outputs reflect assumptions regarding EU Green Deal implementation pacing and commercial vehicle OEM production scaling. A model refresh is warranted upon material change in electric platform supply allocation announcements or carbon border adjustment mechanism implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
Towable Tubes Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Recreational Vehicle Rental Market
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Australia Recreational Vehicle Rental Market
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Low-Speed Electric Vehicle Market