
 Asia-Pacific Recreational Vehicle Market | 2026-2036
Asia-Pacific Recreational Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Recreational Vehicle Market Analysis
The premium motorhome specification tier is collapsing the gap between commercial coach platforms and purpose-built recreational chassis. Great Wall Motor Co., Ltd. leverages its pickup-truck manufacturing base to control costs on self-contained RV platforms. Thor Industries Inc. anchors its Asia-Pacific position through localized assembly partnerships rather than pure export. Zhongtian Gaoke Special Vehicle Co., Ltd. specializes in custom fiberglass bodywork for high-altitude touring applications.
Recreational vehicles comprise self-propelled or towable living quarters engineered around sleeping, sanitation, and galley modules with gross vehicle weight ratings from 2.5 to 12 tonnes and body construction in aluminum, fiberglass, or composite sandwich panels. Motorhomes command the widest margin pools due to integrated drivetrain complexity, while campervans attract the fastest-growing segment among urban adventure seekers seeking parking-compatible footprints. Families drive volume in the mid-range price tier, whereas retirees concentrate demand in the luxury segment with extended-season thermal insulation and full-width slide-out mechanisms.
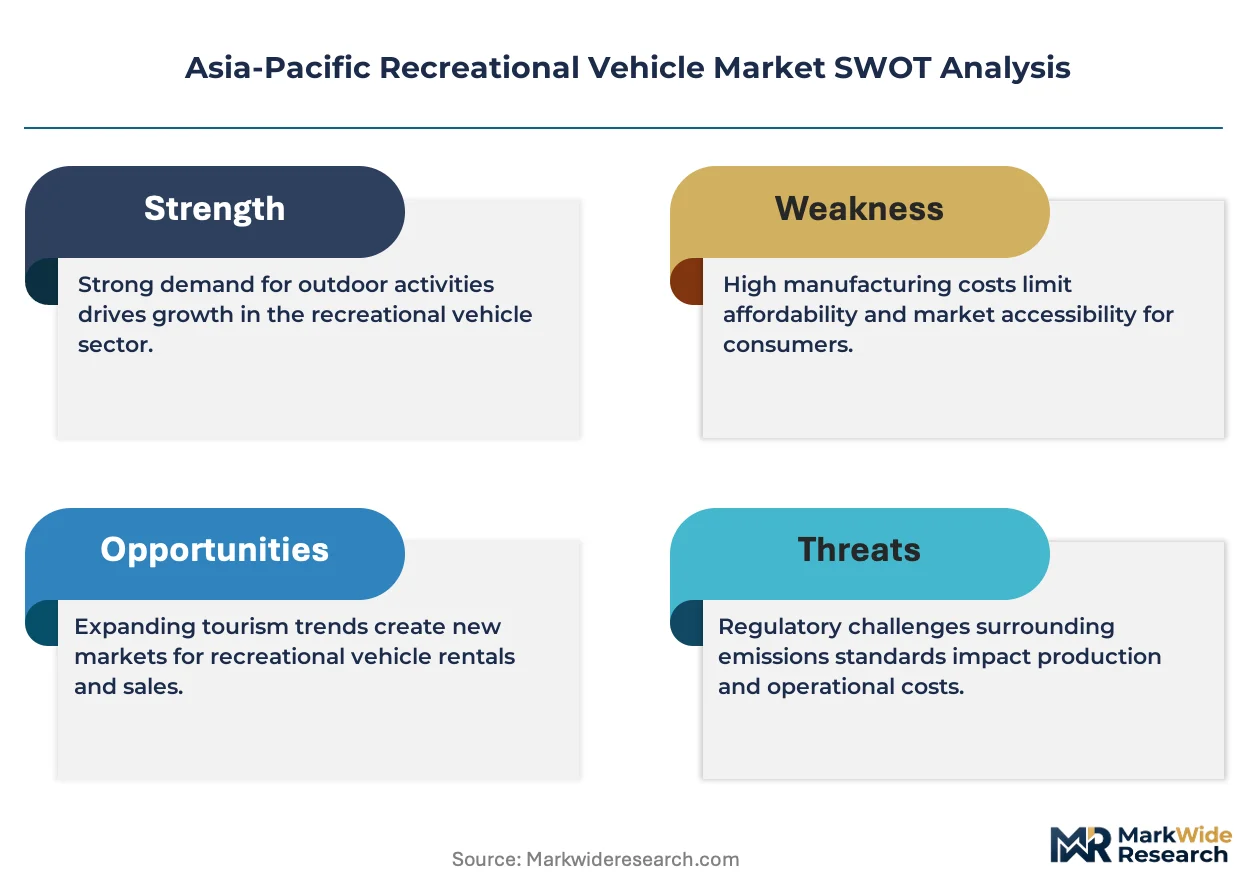
China's MIIT enforces GB-standard fuel consumption and electrification timelines that push domestic manufacturers toward hybrid and pure-electric powertrains. Australia's ADR and Japan's JIS safety frameworks govern braking performance, rollover stability, and gas-system certification for caravan and motorhome registration. India's BIS and CEA are developing camping-vehicle electrical codes as domestic tourism infrastructure expands. Stakeholders must track how Australia's ADR updates and China's dual-carbon enforcement cascade through supplier qualification requirements across the regional value chain.
Market Dynamics
China's MIIT dual-carbon enforcement is decomposing the traditional internal-combustion chassis supply base, forcing simultaneous powertrain redesign and thermal-management reengineering across the regional value chain. This regulatory compression cascades through supplier qualification protocols, procurement specifications, and manufacturing footprints from Yunnan assembly plants to Australian import channels.
Growth Catalysts
- Adventure Tourism Infrastructure:China's southwestern camping belts and eastern Australia's coastal corridors are receiving dedicated RV service networks and electrified pitch facilities. These geographic clusters concentrate demand visibility and reduce buyer hesitation around remote-area usage.
- ADR Safety Framework:Australia's braking-performance and rollover-stability mandates are accelerating chassis-platform consolidation. Manufacturers achieve scale economies by engineering to this higher baseline rather than maintaining dual specifications.
- Fiberglass Composite Bodywork:High-altitude touring applications in the Himalayan foothills and Tibetan plateau are driving adoption of thermal-efficient sandwich-panel construction. This material shift enables extended-season operation without slide-out complexity.
Market Restraints
- Aluminum Sheet Volatility:Body-panel fabrication depends on imported primary aluminum, exposing margin structures to London Metal Exchange price swings and tariff discontinuities.
- Powertrain Supply Concentration:Hybrid and pure-electric drivetrain components concentrate among a limited set of Korean and Japanese battery-cell suppliers, creating allocation risk during demand surges.
- GB Standard Compliance Friction:China's MIIT fuel-consumption testing protocols impose redesign cycles that lag behind product-planning timelines for smaller domestic manufacturers.
Strategic Opportunities
- India Camping-Vehicle Electrification:BIS and CEA code development for recreational-vehicle electrical systems creates first-mover positioning as domestic tourism infrastructure expands beyond Rajasthan and Kerala circuits.
- Campervan Parking-Compatible Footprints:Urban adventure seekers in Tokyo, Seoul, and Sydney are compressing vehicle dimensions to access standard parking structures, opening a specification tier between motorhomes and towables.
- Japan JIS Certification Alignment:Gas-system and braking-performance harmonization with Australian ADR standards would unlock cross-regional platform economics for specialized manufacturers.
Industry Challenges
- High-Voltage Technician Scarcity:Electrified powertrain service requirements outpace vocational training capacity in Australia's regional dealership networks and China's aftermarket channels.
- Slide-Out Mechanism Certification:Full-width expansion systems face extended homologation timelines under ADR structural-integrity protocols, compressing model-year launch windows.
- Multi-Regulatory Documentation Burden:Simultaneous MIIT, ADR, and JIS compliance creates engineering-resource fragmentation for platforms targeting multiple national markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Recreational Vehicle Market |
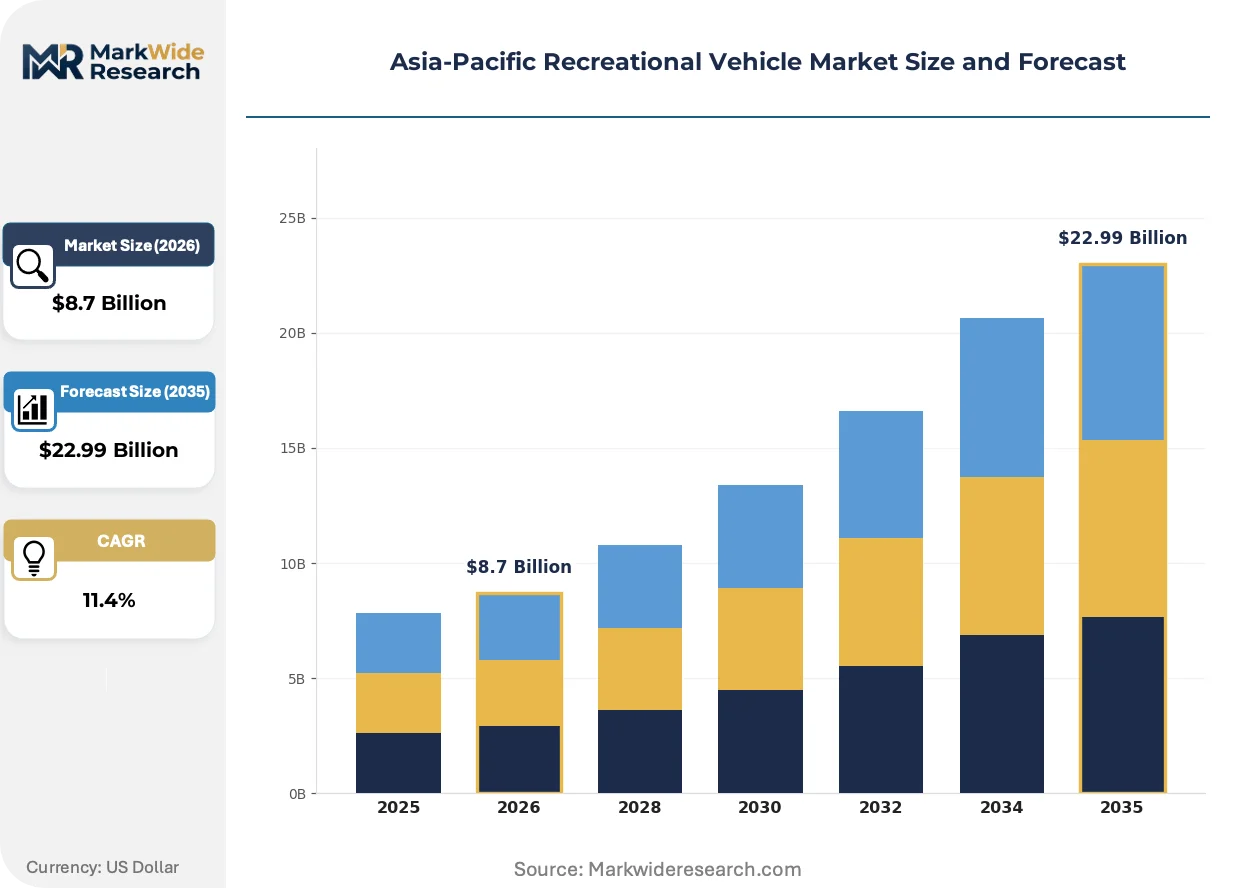
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Motorhomes, Travel Trailers, Fifth-Wheel Trailers, Campervans End User: Families, Adventure Seekers, Retirees, Tourists Price Tier: Luxury, Mid-Range, Economy, Budget Fuel Type: Gasoline, Diesel, Electric, Hybrid |
| Companies Covered | SAIC Motor, Great Wall Motor Co., Ltd., Thor Industries Inc., Zhongtian Gaoke Special Vehicle Co., Ltd., Baoding Zhongjin Braun RV Manufacturing Co., Ltd., BYD Auto, JAC Motors, Fuji Camping Loading Co., Ltd., Beijing North RV Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Recreational Vehicle Market Emerging Trajectories
Powertrain electrification is decomposing traditional chassis-engineering assumptions, while regulatory fragmentation between Chinese, Australian, and Japanese standards forces modular platform architectures. Buyer behavior is compressing around parking-compatible footprints and seasonal thermal performance.
Composite sandwich-panel body construction is decomposing the historical aluminum-monocoque dominance in premium motorhome segments. High-altitude touring operators across China's Tibetan plateau and Nepal's Annapurna circuits are specifying fiberglass-foam cores for thermal efficiency without the weight penalty of insulated metal skins. This material transition enables extended-season deployment with simpler HVAC systems, compressing the specification gap between commercial coach platforms and purpose-built recreational chassis.
China's MIIT dual-carbon timeline is mandating hybrid and pure-electric powertrain penetration across vehicle categories above 3.5 tonnes gross weight. Domestic manufacturers are reengineering thermal-management architectures to accommodate battery-pack placement within existing frame rails, while import-dependent Australian distributors face chassis-availability constraints as Chinese allocation prioritizes domestic compliance. The motorhome segment bears the heaviest redesign burden due to integrated drivetrain complexity and range-anxiety sensitivity in remote-area usage patterns.
Urban adventure seekers are fragmenting traditional family-segment demand toward campervan configurations that access standard parking structures in Tokyo, Seoul, and Sydney. Rental-channel operators are responding with fleet specifications below 5.5 metres length and 2.1 metres height, displacing the historical motorhome concentration in metropolitan pickup locations. This behavioral compression is most visible in Australia's eastern seaboard tourism corridors, where coastal township parking scarcity constrains larger vehicle maneuverability.
Asia-Pacific Recreational Vehicle Market Segmentation
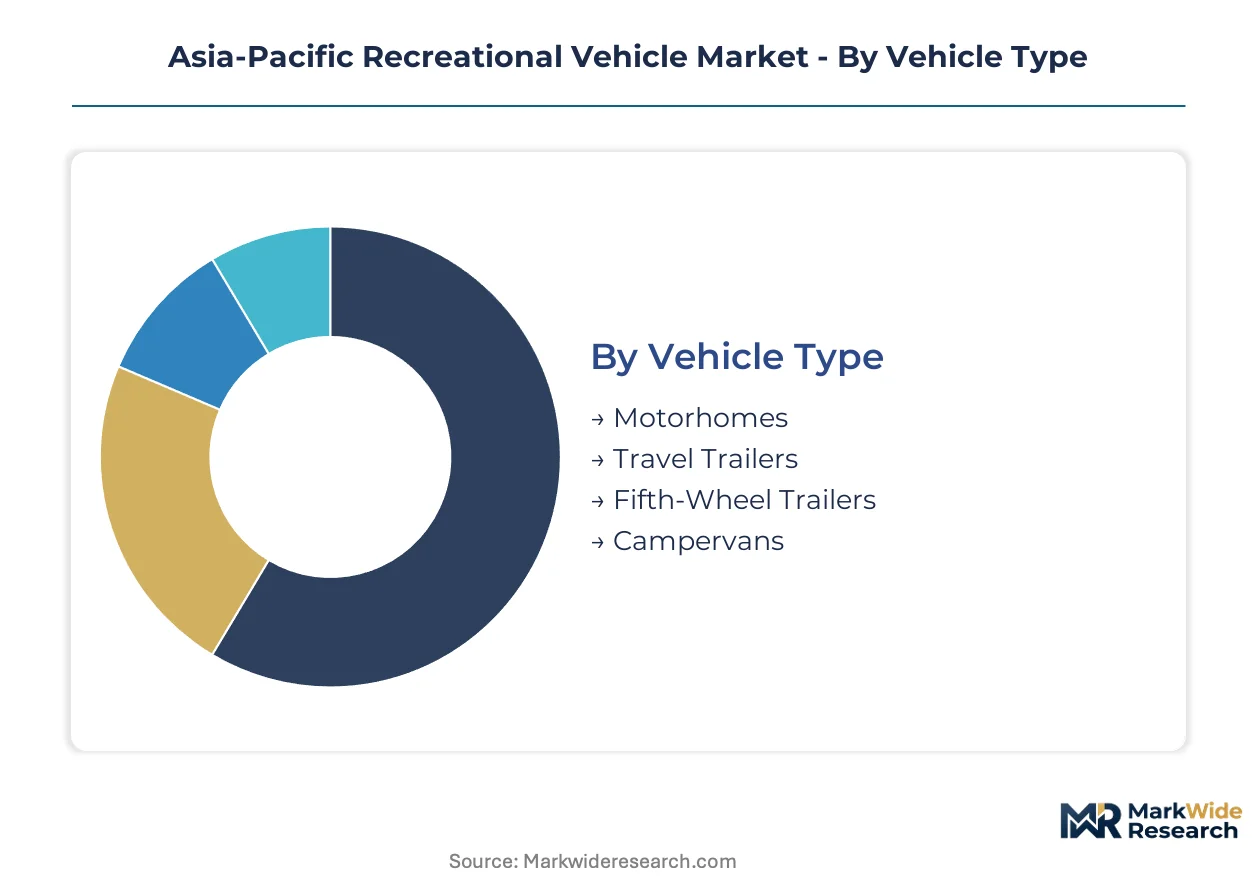
Segmentation in the Asia-Pacific recreational vehicle market reveals how channel economics and regulatory pressures reshape product mix across Australia's coastal corridors and China's southwestern camping belts. Channel partners prioritize inventory turns and service attach rates differently by segment, compressing manufacturer margin structures.
Vehicle Type:
Rental-channel operators in Sydney and Melbourne concentrate fleet acquisition in specific configurations, while private buyers in Yunnan and Sichuan provinces favor self-owned platforms for extended plateau touring.
- Motorhomes:Integrated drivetrain chassis with gross vehicle weight ratings above 3.5 tonnes command the widest margin pools due to powertrain complexity and thermal-management engineering. Australia's eastern seaboard tourism corridors concentrate demand for luxury specifications with full-width slide-out mechanisms and extended-season insulation.
- Campervans:Parking-compatible footprints below 5.5 metres length and 2.1 metres height attract urban adventure seekers in Tokyo, Seoul, and Sydney. Rental operators are displacing motorhome concentration in metropolitan pickup locations as coastal township parking scarcity constrains larger vehicle maneuverability.
- Travel Trailers:Towable living quarters with aluminum or composite body construction serve family segments seeking cost efficiency through existing vehicle tow capacity.
- Fifth-Wheel Trailers:Hitch-mounted platforms above 6 tonnes gross weight concentrate in retiree demand for residential-grade amenities and extended off-grid capability.
Motorhomes dominate installed base. Campervans are where expansion concentrates.
End User:
Customer lifecycle positioning determines specification requirements and service-interval economics, with distinct thermal-performance and technology-package expectations across cohorts.
- Families:Volume concentration in mid-range price tiers drives demand for bunk configurations, convertible dinette sleeping modules, and galley storage optimization. China's domestic tourism infrastructure expansion channels family demand toward Yunnan-Sichuan camping belts with electrified pitch facilities.
- Adventure Seekers:The fastest-expanding buyer cohort across the region compresses vehicle dimensions for parking access while demanding high-altitude thermal performance. Fiberglass composite bodywork specifications enable extended-season operation in Himalayan foothill circuits without slide-out complexity.
- Retirees:Luxury segment concentration prioritizes full-width slide-out mechanisms, residential-grade HVAC systems, and extended-warranty coverage for seasonal migration patterns.
- Tourists:Rental-channel dependence in Australia's coastal corridors and Japan's national park circuits drives fleet standardization around maneuverability and rapid turnaround cleaning protocols.
Families anchor volume throughput. Adventure seekers are climbing the fastest.
Price Tier:
Specification bundling and powertrain technology allocation stratify margin capture, with electrification mandates compressing traditional tier boundaries.
- Luxury:Residential-grade fit-out with composite sandwich-panel construction and integrated lithium power systems commands premium positioning. Retiree demand in Australia's extended-season migration corridors sustains this tier despite MIIT electrification cost pressures.
- Mid-Range:Aluminum-body motorhomes and travel trailers with selective slide-out configurations capture family volume. China's domestic manufacturers leverage pickup-truck manufacturing bases to control chassis costs in this contested segment.
- Economy:Basic galley and sanitation modules on standardized chassis platforms serve price-sensitive entry buyers and rental-fleet procurement.
- Budget:Minimal configuration towables and used-vehicle refurbishment concentrate in India's emerging camping-vehicle market as BIS electrical code development proceeds.
Mid-Range holds volume leadership. Luxury is where technology differentiation concentrates.
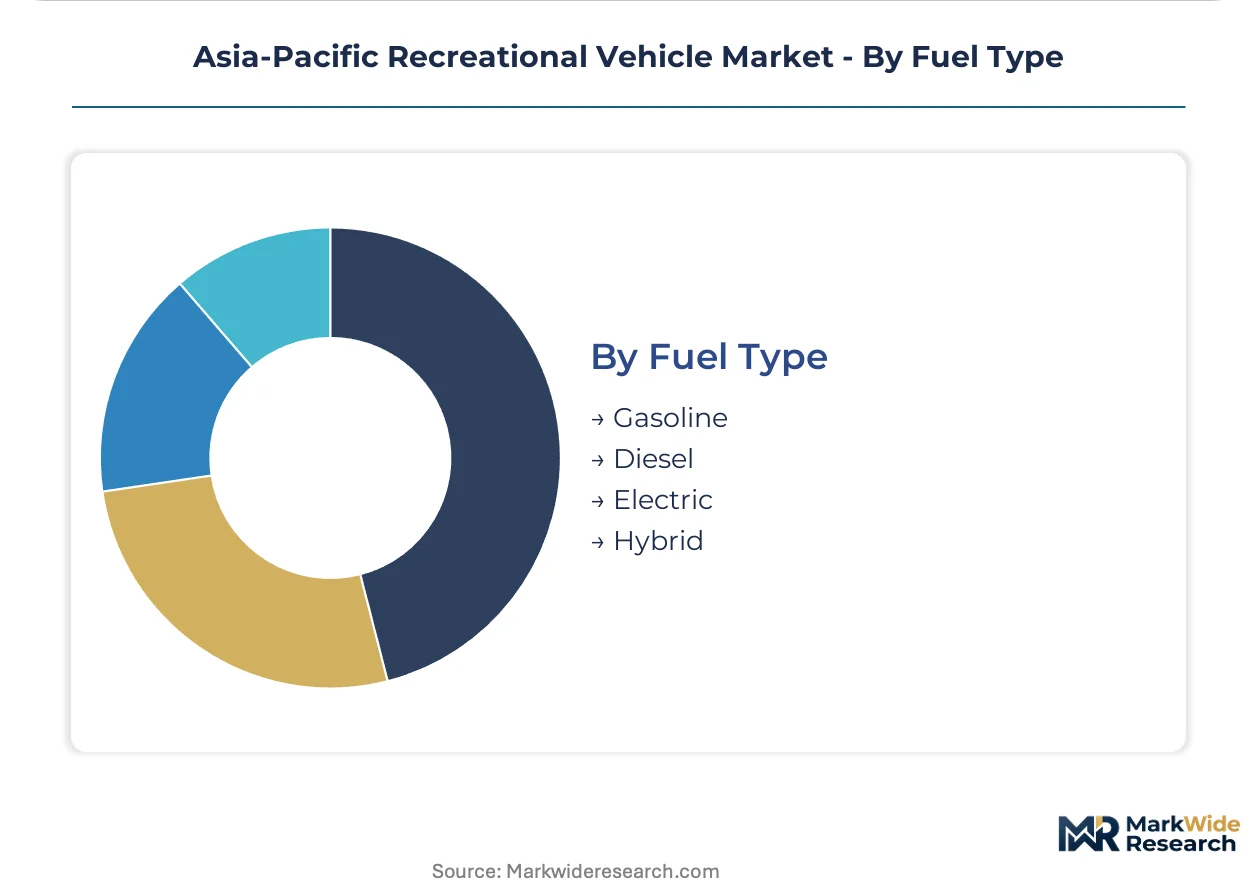
Fuel Type:
MIIT dual-carbon enforcement and Australia's ADR safety frameworks are decomposing traditional internal-combustion supply bases, forcing simultaneous powertrain redesign across manufacturer portfolios.
- Diesel:Torque density and thermal efficiency sustain demand in motorhome segments above 6 tonnes gross weight for high-altitude plateau touring. ADR braking-performance mandates accelerate chassis-platform consolidation around diesel-compatible architectures.
- Hybrid:Battery-pack placement within existing frame rails enables range-anxiety mitigation for remote-area usage patterns. Chinese manufacturers prioritize hybrid penetration to meet GB-standard fuel consumption timelines while preserving thermal-management flexibility.
- Gasoline:Campervan and light travel-trailer applications below 3.5 tonnes retain gasoline compatibility for cost-sensitive urban adventure seekers.
- Electric:Pure-electric powertrains face allocation constraints as Korean and Japanese battery-cell suppliers concentrate capacity. Australian import channels experience chassis-availability compression as Chinese domestic compliance prioritizes domestic market allocation.
Diesel dominates current installed base. Hybrid is where manufacturer engineering resources concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chassis manufacturing concentrates in China's industrial heartlands, while final assembly and consumer demand fragment across coastal Australia, Japan's metropolitan corridors, and India's emerging camping circuits. Regulatory divergence between MIIT, ADR, and JIS frameworks forces modular platform strategies rather than unified specifications.
China
Domestic manufacturers leverage pickup-truck production bases to control costs on self-contained RV platforms. MIIT dual-carbon enforcement accelerates hybrid powertrain penetration above 3.5 tonnes gross weight. Yunnan-Sichuan camping belts concentrate demand visibility with electrified pitch facilities and dedicated service networks.
Australia
Eastern seaboard tourism corridors sustain luxury motorhome demand with full-width slide-out specifications. ADR braking-performance and rollover-stability mandates compress chassis-platform consolidation timelines. Coastal township parking scarcity in New South Wales and Victoria drives campervan fleet standardization below 5.5 metres length.
Japan
Metropolitan adventure seekers in Tokyo and Osaka compress vehicle dimensions to access standard parking structures. JIS gas-system certification governs caravan and motorhome registration requirements. Rental-channel operators concentrate fleet procurement around rapid turnaround cleaning protocols for national park circuits.
India
Domestic tourism infrastructure expansion channels family demand toward Rajasthan and Kerala camping circuits. BIS and CEA electrical code development proceeds for recreational-vehicle systems as the regulatory framework matures. Budget-tier towables and refurbishment markets concentrate in emerging urban clusters.
South Korea
Battery-cell suppliers concentrate hybrid and pure-electric drivetrain component allocation for regional manufacturers. Metropolitan parking constraints in Seoul drive demand for parking-compatible footprints below 2.1 metres height. Coastal tourism development in Busan-Ulsan corridors receives dedicated RV service infrastructure.
Asia-Pacific Recreational Vehicle Market Vendor Landscape
Concentration sits with diversified automotive conglomerates that leverage existing pickup-truck and commercial vehicle manufacturing bases. The vendor base spans three strategic tiers: integrated automotive groups controlling chassis supply, specialized fiberglass bodywork fabricators, and import-dependent distributors managing localized assembly partnerships. Competitive moves center on powertrain electrification alignment with MIIT timelines and chassis-platform consolidation to meet ADR safety baselines.
Within the integrated automotive tier, SAIC Motor and Great Wall Motor Co., Ltd. exemplify scale-driven chassis control strategies. Thor Industries Inc. occupies a position among distributors anchoring Asia-Pacific presence through partnership structures rather than pure export. Zhongtian Gaoke Special Vehicle Co., Ltd. represents the specialized fabricator archetype focused on custom bodywork applications.
| Leading Market Players |
|---|
| SAIC Motor |
| Great Wall Motor Co., Ltd. |
| Thor Industries Inc. |
| Zhongtian Gaoke Special Vehicle Co., Ltd. |
| Baoding Zhongjin Braun RV Manufacturing Co., Ltd. |
| BYD Auto |
| JAC Motors |
| Fuji Camping Loading Co., Ltd. |
| Beijing North RV Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Ninety-day chassis allocation lead times from Chinese assembly plants compress distributor pricing power across Australian import channels and force inventory pre-commitment before ADR certification completion. This temporal friction concentrates margin pressure on smaller domestic manufacturers unable to secure priority hybrid powertrain allocation from Korean and Japanese battery-cell suppliers.
Pricing Analysis
China's MIIT dual-carbon mandates dictate the pricing tier structure across motorhome segments above 3.5 tonnes gross weight. Three-tier pricing structure across premium, standard, and economy levels stratifies by electrification compliance cost, with luxury composite-body specifications absorbing battery-pack premiums through retiree willingness-to-pay. Cost compression in mid-range aluminum-body motorhomes is intensifying because Great Wall Motor and SAIC leverage pickup-truck manufacturing bases for chassis cost control. Urban adventure seekers in campervan segments exhibit highest price sensitivity, while extended-season plateau touring operators in Yunnan-Sichuan belts accept premium positioning for thermal-performance specifications.
Supply Chain Analysis
China and South Korea anchor hybrid and pure-electric drivetrain component production, with Japanese suppliers concentrating gas-system certification hardware for JIS compliance. Body-panel fabrication draws from imported primary aluminum exposed to London Metal Exchange volatility, while fiberglass-foam core sandwich panels source from domestic Chinese composite manufacturers. Single-source vulnerability concentrates in Korean and Japanese battery-cell allocation during demand surges. Distribution runs through Australian import distributors managing localized ADR assembly partnerships and Chinese domestic manufacturers with direct Yunnan-Sichuan camping belt service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of high-voltage technicians certified for electrified powertrain service constrains aftermarket expansion and creates defensive moats for incumbent distributors with captive training programs.
For Market Incumbents: Consolidate chassis-platform engineering resources around ADR braking-performance and rollover-stability baselines rather than maintaining dual MIIT-JIS specifications. Deepen backward integration into fiberglass composite bodywork production to capture thermal-efficiency premiums from Himalayan foothill touring operators. Lock long-term battery-cell offtake agreements with Korean suppliers before allocation priority shifts to pure-electric passenger vehicle programs. For New Entrants and Emerging Players: Differentiate on parking-compatible campervan configurations below 5.1 metres length for Tokyo, Seoul, and Sydney urban adventure seekers underserved by motorhome-centric rental fleets. Target India's Rajasthan and Kerala camping circuits with budget-tier towables as BIS electrical code development matures. Pursue gas-system certification alignment between JIS and ADR standards to unlock cross-regional platform economics without dual engineering tracks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because MIIT electrification timelines and ADR safety framework updates create acquisition windows for distressed domestic Chinese manufacturers lacking hybrid powertrain engineering capacity. Prioritize targets with established Yunnan-Sichuan service networks and composite bodywork fabrication capabilities. Monitor Korean battery-cell supplier allocation announcements as inflection indicator for chassis availability compression in Australian import channels.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Platform Standardization | MIIT dual-carbon compliance consolidates engineering resources across motorhome and campervan segments above 3.5 tonnes. |
| Composite Sandwich-Panel Manufacturing Scale-Up | Fiberglass-foam core production expansion captures thermal-efficiency premiums from Tibetan plateau touring operators. |
| ADR-JIS Certification Harmonization Partnership | Gas-system and braking-performance alignment unlocks cross-regional platform economics for specialized manufacturers. |
| High-Voltage Technician Training Program Deployment | Captive service capacity builds defensive moats in Australia's regional dealership networks and Chinese aftermarket channels. |
| Electrified Pitch Infrastructure Joint Venture | Yunnan-Sichuan camping belt service network expansion reduces buyer hesitation around remote-area usage patterns. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of MIIT regulatory filings, ADR safety standard updates, and vehicle registration databases across Australian state transport authorities. Discussions with RV platform engineers at integrated automotive groups, procurement leads at Australian import distributors, and service operations managers at Yunnan-Sichuan camping belt facilities combined with customs trade data and IHS Markit vehicle production statistics. Bottom-up channel inventory analysis triangulates against top-down gross value added estimates from national automotive manufacturing surveys.
Segmentation dimensions modeled span vehicle type, end-user cohort, price tier, and fuel architecture across the projection horizon. Powertrain electrification penetration curves, thermal-management engineering cost trajectories, and camping infrastructure deployment schedules inform analytical framework outputs. CAGRs derive from logistic diffusion modeling of hybrid adoption rates and price-elasticity estimates for parking-compatible footprint specifications.
Material uncertainties — aluminum price volatility, battery-cell supplier allocation shocks, and ADR structural-integrity protocol revisions — sit outside the modeled envelope. Forecasts reflect assumptions around MIIT enforcement consistency and JIS-Australian regulatory convergence timelines. Recalibration cycles align with material shifts in dual-carbon policy implementation and coastal tourism infrastructure deployment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
Recreational Vehicle Parks and Campgrounds Market
Recreational Vehicles
Deck Boat Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Camping Trailer Market
Recreational Vehicles
Global Segway Consumption Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
Snowmobile Trailer Axle Market
Recreational Vehicles
Australia Recreational Vehicle Rental Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
Water Scooter Market
Recreational Vehicles
RV Leisure Battery Market