
 Recreational Boats Market | 2026-2036
Recreational Boats Market Size, Share, and Industry Trends Forecast 2026-2036
Recreational Boats Market Intelligence
Italian yacht builders is rebalancing output between superyacht and mid-size cruiser lines after supply chain disruptions in composite materials. Brunswick Corporation leverages its Mercury Marine propulsion division to control critical engine supply for its boat brands. Yamaha Motor Corporation sustains dominance in personal watercraft through continuous refinement of its WaveRunner platform. Groupe Beneteau anchors its competitive position with dual-brand strategy spanning sailing and powerboat segments across European and North American markets.
Recreational boats encompass motorized and wind-propelled vessels designed for non-commercial leisure use, typically constructed from fiberglass-reinforced polymer hulls with lengths ranging from ten feet for personal watercraft to over one hundred feet for luxury yachts, and serve the primary commercial purpose of enabling water-based leisure activities including fishing, watersports, and extended cruising. Motorboats occupy the largest volume position across global production lines due to their versatility across usage purposes from day cruising to offshore fishing, while personal watercraft represents the fastest-growing structural segment as younger demographics prioritize compact, trailerable craft for watersports access. Fiberglass hull construction dominates material demand for vessels above twenty feet where stiffness-to-weight ratios determine performance characteristics, though aluminum construction gains share in freshwater fishing boats where dock impact resistance and repairability matter more than top-speed optimization.
The EPA enforces marine engine emission standards that dictate catalytic converter requirements and fuel system designs for all gasoline-powered recreational boats sold in the United States, while the EU Green Deal's F-Gas Regulation constrains refrigerant choices in cabin climate systems for European-built cruisers. The ISO 12217 stability standard shapes hull design parameters and market access for international manufacturers seeking multi-region certification. Stakeholders must monitor evolving battery-electric propulsion regulations from the FCC and Coast Guard as lithium-ion marine powertrains transition from concept to commercial scale.
Market Dynamics
The EPA's Tier 3 marine engine emission standards are forcing propulsion system redesigns across the entire supply chain, compressing development timelines while opening competitive gaps between compliant and non-compliant manufacturers.
Growth Catalysts
- Private Maritime Leisure:Post-pandemic travel patterns favor exclusive vessel charter experiences over commercial cruise alternatives, concentrating demand in Florida's marina corridors.
- REACH Compliance:EU Green Deal directives on composite material recyclability accelerate adoption of bio-based resin systems in hull manufacturing.
- Aluminum Hull Demand:Freshwater fishing segments prioritize dock-impact durability and field repairability over fiberglass performance metrics.
Market Restraints
- Composite Supply Concentration:Carbon fiber and epoxy resin availability remains bottlenecked by Asian petrochemical feedstock dependencies.
- F-Gas Refrigerant Constraints:EU cabin climate system manufacturers face reformulation costs under tightened fluorinated gas phase-down schedules.
- Electrification Infrastructure:Marina fast-charging networks lack standardized voltage protocols, delaying lithium-ion propulsion adoption beyond early-adopter niches.
Strategic Opportunities
- Mid-Size Cruiser Gap:Italian builders are rebalancing superyacht and cruiser output, creating white space for specialized entrants in 40-60 foot segments.
- ISO 12217 Certification:Multi-region stability standard compliance enables single-hull designs to access both North American and European markets without redesign.
- Trailerable Watersports:Personal watercraft demand from younger demographics rewards compact, towable platforms with modular accessory ecosystems.
Industry Challenges
- Marine Electrician Scarcity:High-voltage lithium system installation and maintenance skills outpace vocational training pipeline expansion.
- Coast Guard Certification Timelines:Battery-electric propulsion approval pathways remain undefined, freezing commercialization schedules for emerging powertrain developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recreational Boats Market |
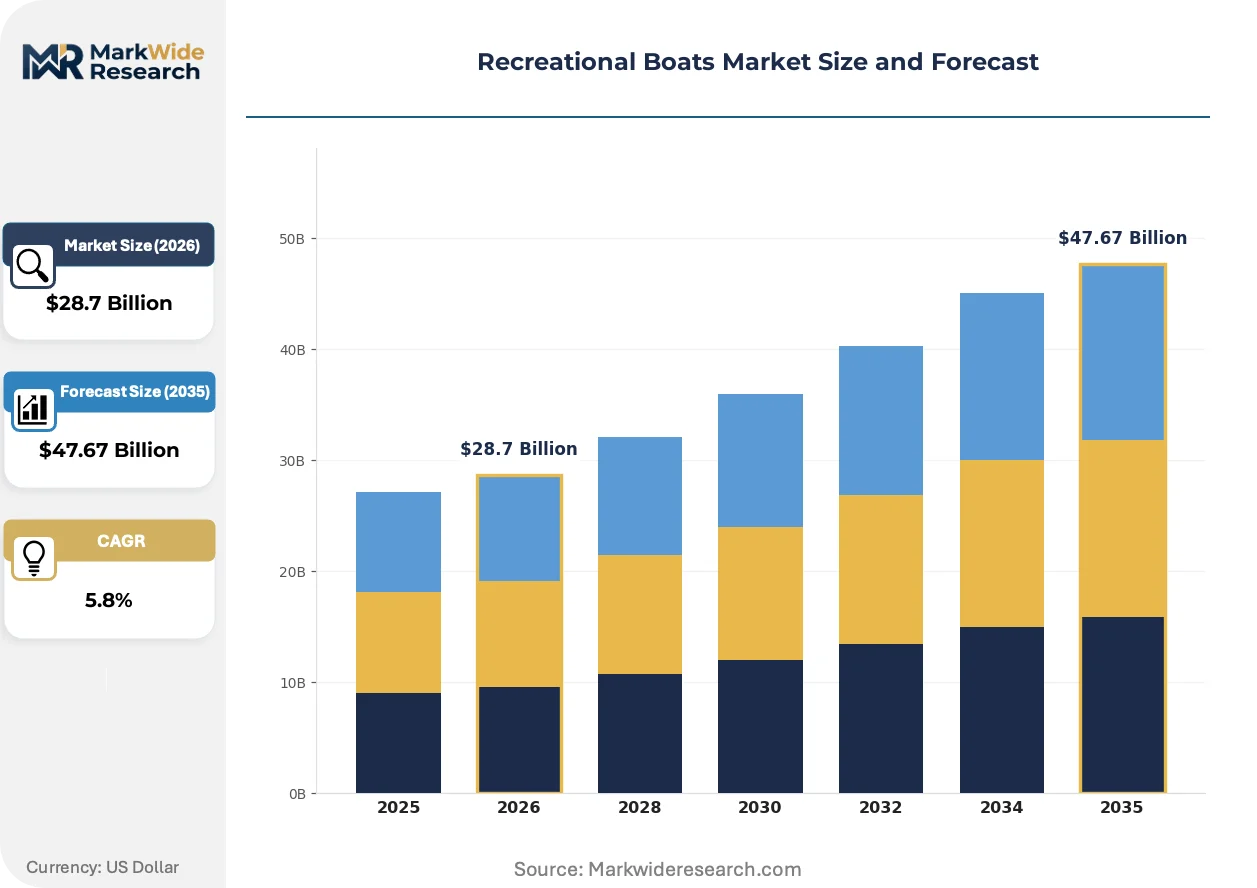
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $47.67 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Boat Type: Motorboats, Sailboats, Personal Watercraft, Deck Boats, Catamarans, Trawlers Material: Fiberglass, Aluminum, Wood, Steel, Composite, Inflatable Usage Purpose: Fishing, Watersports, Day Cruising, Overnight Trips, Racing, Leisure Sales Channel: Dealerships, Online Platforms, Boat Shows, Brokers, Rental Services, Charter Companies |
| Companies Covered | Brunswick Corporation, Yamaha Motor Corporation, Groupe Beneteau, Ferretti Group, Azimut Benetti Group, Malibu Boats, MasterCraft Boat Holdings, Bombardier Recreational Products, Polaris Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recreational Boats Market Strategic Shifts & Innovations
Propulsion electrification, regulatory harmonization, and buyer preference fragmentation are simultaneously compressing traditional manufacturing models while opening specialized service layers around vessel ownership.
Hybrid diesel-electric powertrains are consolidating position in mid-size cruiser segments where range anxiety and marina charging availability remain unresolved. Charter operators in the Mediterranean and Caribbean are specifying these systems for silent anchorage operation. The technology is consolidating supplier relationships around integrated drivetrain packages rather than discrete engine and generator sourcing.
EPA Tier 3 and EU Stage V emission frameworks are converging on common catalytic converter and closed-crankcase ventilation requirements. Engine manufacturers serving both markets now design single certification platforms rather than region-specific variants. Gasoline outboard producers face the steepest compliance cost escalation, accelerating consolidation toward integrated boat-engine bundling.
Direct-to-consumer vessel configuration tools are displacing traditional dealer specification processes among digitally native buyers. Younger owners in coastal United States markets increasingly finalize hull, powertrain, and electronics packages through manufacturer portals before physical inspection. This channel compression rewards builders with configurable production systems and punishes inventory-heavy distribution networks.
Recreational Boats Market Segmentation
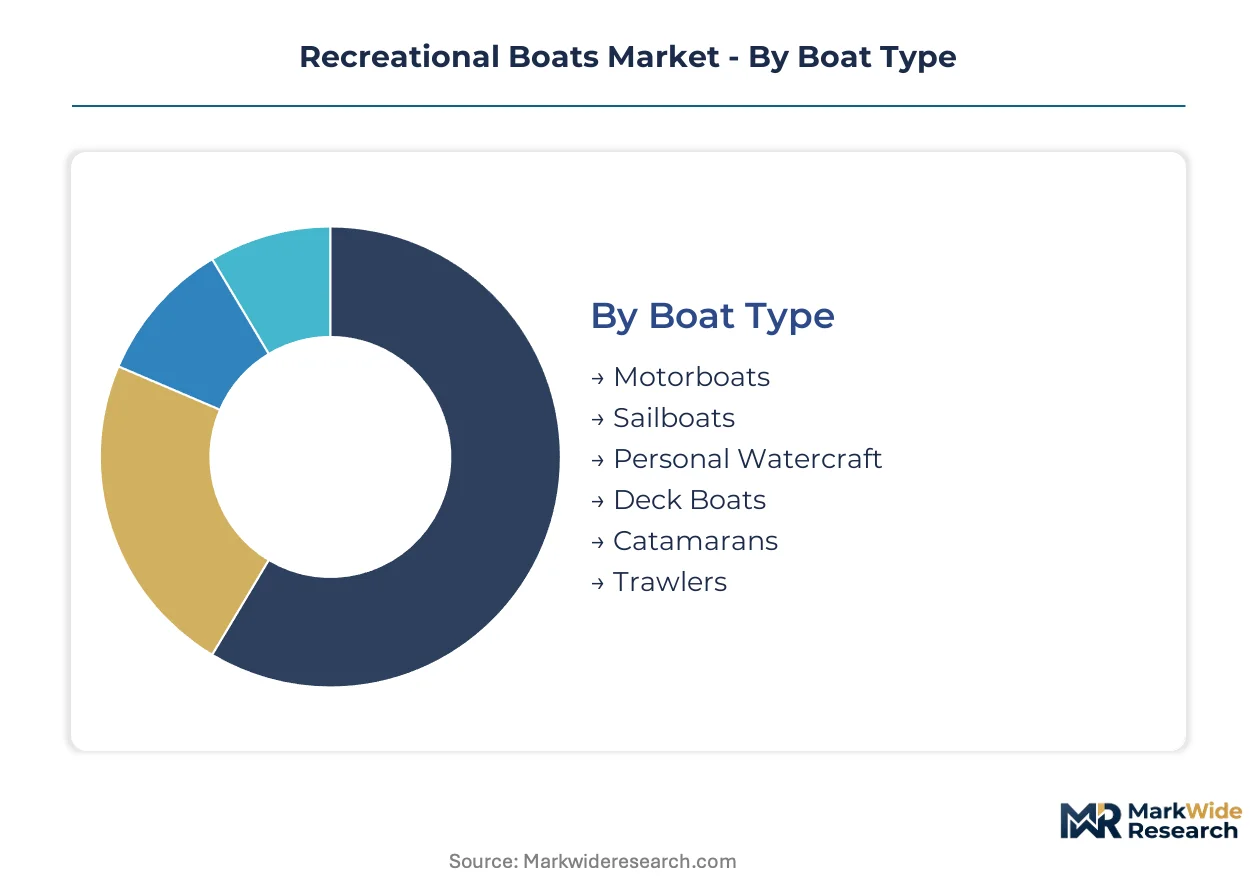
Segmentation in recreational boats reflects divergent supply chain capabilities across hull fabrication methods, propulsion architectures, and distribution infrastructure. Manufacturers optimize production lines around specific material-process combinations rather than attempting universal coverage.
Boat Type:
Supply concentration in outboard engine manufacturing favors platform families that share powertrain mounting standards and transom specifications.
- Motorboats:These vessels utilize sterndrive, inboard, or outboard propulsion configurations with fiberglass or aluminum hulls ranging from sixteen to fifty feet. Demand concentrates in coastal Florida where marina infrastructure investments and high-net-worth migration accelerate registrations for offshore fishing and day cruising applications. EPA Tier 3 emission compliance costs disproportionately impact gasoline outboard producers, accelerating bundling with hull manufacturers.
- Personal Watercraft:Compact jet-driven vessels typically under twelve feet designed for high-speed watersports and trailerable portability. Younger demographics in coastal United States markets prioritize these platforms for modular accessory ecosystems and social recreation, with Yamaha's WaveRunner platform sustaining technology leadership through continuous refinement.
- Sailboats:Wind-propelled vessels with mast, rigging, and keel systems for racing or extended cruising. European builders like Groupe Beneteau anchor competitive position through dual-brand strategies spanning monohull and multihull configurations.
- Deck Boats:Pontoon-style platforms with wide beam dimensions optimized for passenger capacity and stability in inland waterways. Lake communities in the US Midwest drive specification trends toward integrated entertainment systems and watersports towers.
- Catamarans:Twin-hull designs offering superior stability and deck space for charter operations and liveaboard cruising. Mediterranean and Caribbean charter operators specify hybrid diesel-electric variants for silent anchorage operation.
- Trawlers:Displacement-hull motor vessels prioritizing fuel efficiency and long-range capability for extended coastal cruising. Pacific Northwest builders specialize in ruggedized specifications for Inside Passage navigation.
Today's leader: Motorboats. Tomorrow's challenger: Personal Watercraft.
Material:
Cost tier differentiation separates premium composite performance from repairable aluminum utility.
- Fiberglass:Reinforced polymer construction dominates above twenty feet where stiffness-to-weight ratios determine speed and fuel efficiency. Italian yacht builders face supply chain disruptions in carbon fiber and epoxy resin availability, rebalancing output between superyacht and mid-size cruiser lines.
- Aluminum:Welded plate construction gains share in freshwater fishing boats where dock impact resistance and field repairability outweigh top-speed optimization. US heartland manufacturers leverage proximity to sheet metal stamping infrastructure.
- Wood:Traditional plank-on-frame and cold-molded techniques persist in custom sailing yacht and classic runabout restoration niches. Pacific Northwest and New England boatyards maintain specialized craftsmanship pipelines.
- Steel:Heavy-gauge plate construction for expedition yachts and commercial-to-recreational conversions prioritizing ice-strengthened hulls. Northern European builders serve polar cruising demand.
- Composite:Advanced carbon fiber and aramid honeycomb structures for high-performance racing and superyacht superstructures. REACH compliance accelerates adoption of bio-based resin systems in EU manufacturing.
- Inflatable:Hypalon or PVC tube construction for rigid-hull inflatable boats serving yacht tender and dive support roles. Mediterranean charter fleets specify these for guest transfer operations.
Volume leadership: Fiberglass. Margin expansion: Composite.
Usage Purpose:
Application fragmentation rewards specialized hull-form optimization over generalist platforms.
- Fishing:Vessels configured with livewells, rod storage, and fish-finding electronics for saltwater and freshwater angling. Tournament circuits in the US Southeast drive innovation in stepped-hull offshore designs.
- Watersports:Wakeboard and waterski boats with ballast systems, tower configurations, and specialized hull shapes for wave generation. Younger owner demographics in coastal United States markets prioritize these specifications.
- Day Cruising:Open cockpit designs emphasizing passenger capacity, sun protection, and swim platform access for harbor and coastal outings. Italian mid-size cruiser builders target this segment with convertible hardtop configurations.
- Overnight Trips:Cabin cruisers with berth, galley, and head facilities for weekend coastal passages. ISO 12217 stability compliance enables single-hull designs to access both North American and European markets.
- Racing:One-design and handicap-optimized sailing yachts with carbon fiber rigs and high-aspect foils. European and Australian sailing federations maintain active class association structures.
- Leisure:Multi-purpose platforms without single-purpose optimization, serving casual family recreation. Price sensitivity here drives aluminum utility boat specifications in inland markets.
Core revenue: Fishing. Steepest expansion trajectory: Watersports.
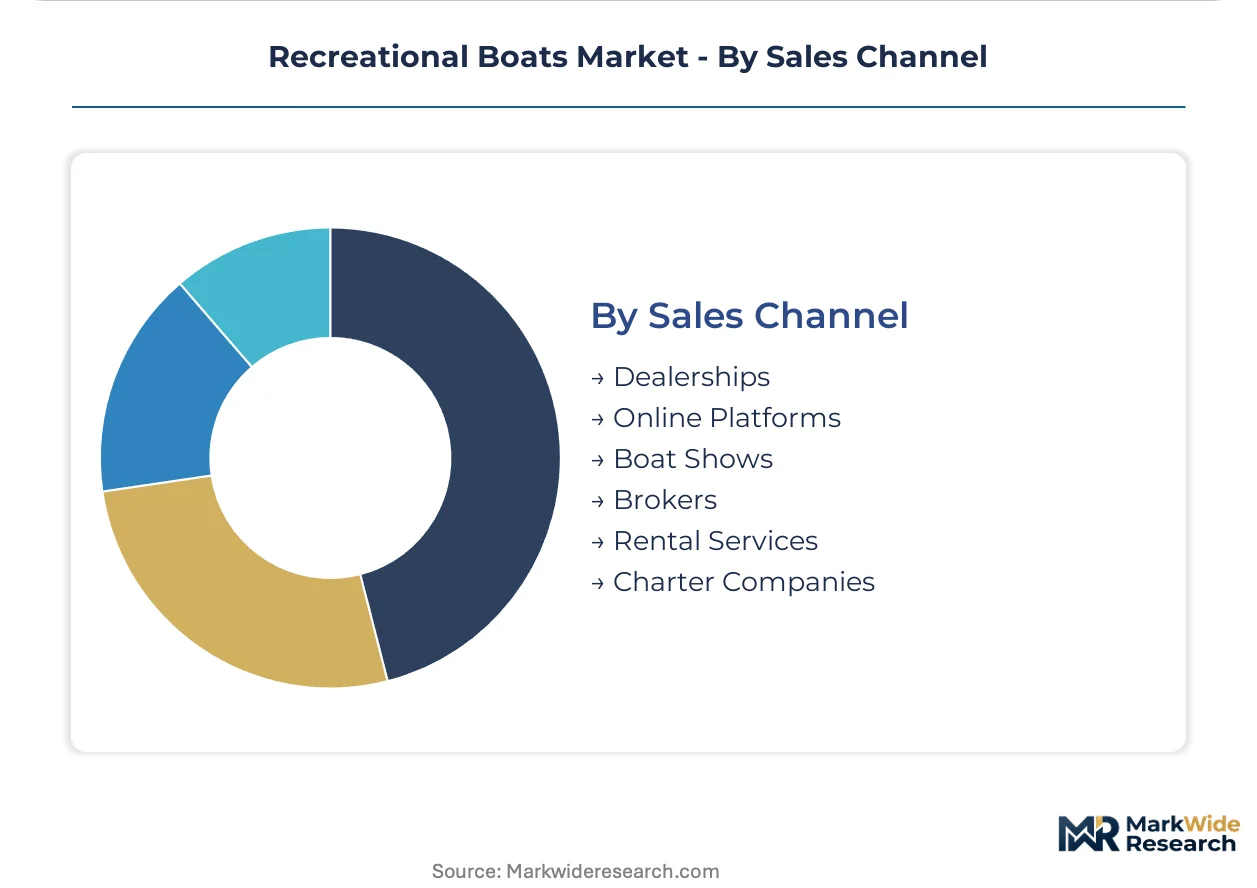
Sales Channel:
Customer type stratification separates inventory-heavy dealer networks from direct digital acquisition.
- Dealerships:Physical showrooms with service departments and parts counters representing manufacturer brand portfolios. Inventory carrying costs pressure traditional networks as direct-to-consumer configuration tools gain traction.
- Online Platforms:Manufacturer portals and third-party marketplaces enabling digital specification and purchase completion. Digitally native buyers increasingly finalize packages before physical inspection.
- Boat Shows:Annual exhibition events in Miami, Fort Lauderdale, Genoa, and Düsseldorf concentrated for model year introductions. Order intake at these events shapes production scheduling for premium builders.
- Brokers:Commission-based intermediaries specializing in pre-owned and brokerage new construction for yachts above sixty feet. Relationships with surveyors and flag state documentation services add value.
- Rental Services:Hourly and daily fleet operations in tourist destinations providing trial experiences and brand exposure. Florida marina corridors concentrate this activity.
- Charter Companies:Weekly and term vessel leasing with professional crew for luxury yacht experiences. Post-pandemic leisure travel shifts favor these private maritime alternatives over commercial cruise options.
Incumbent dominance: Dealerships. Channel compression threat: Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between emission jurisdictions is fragmenting production geography. Manufacturers now arbitrage compliance costs by shifting final assembly toward markets with lighter certification burdens while maintaining component sourcing from established industrial clusters.
United States
Florida's marina corridors concentrate demand acceleration from high-net-worth migration and charter fleet expansion. The EPA enforces Tier 3 marine engine standards that dictate catalytic converter requirements for all gasoline-powered recreational boats. Brunswick Corporation leverages its Mercury Marine division to control engine supply from Wisconsin and Illinois manufacturing bases.
Italy
Superyacht and mid-size cruiser demand drives output rebalancing after composite material supply disruptions. The EU Green Deal's F-Gas Regulation constrains refrigerant choices in cabin climate systems for European-built cruisers. Italian yacht builders in Viareggio and Ancona anchor Mediterranean production gravity for luxury charter specifications.
France
Groupe Beneteau anchors competitive position with dual-brand strategies spanning sailing and powerboat segments. REACH compliance directives on composite material recyclability accelerate adoption of bio-based resin systems in hull manufacturing. Atlantic coast shipyards in Vendée and Charente-Maritime specialize in production-line cruiser fabrication for North American export.
Japan
Yamaha Motor Corporation sustains technology leadership in personal watercraft through continuous WaveRunner platform refinement. METI industrial policy supports domestic marine manufacturing against import competition. Shizuoka prefecture production clusters concentrate outboard engine and watercraft assembly for Asia-Pacific distribution.
Canada
Freshwater fishing boat demand prioritizes aluminum hull durability and field repairability over fiberglass performance metrics. Health Canada's PMRA regulates antifouling coatings and marine biocides in hull maintenance products. Ontario and Quebec manufacturers leverage proximity to US heartland distribution networks for aluminum utility boat exports.
Recreational Boats Market Key Industry Players
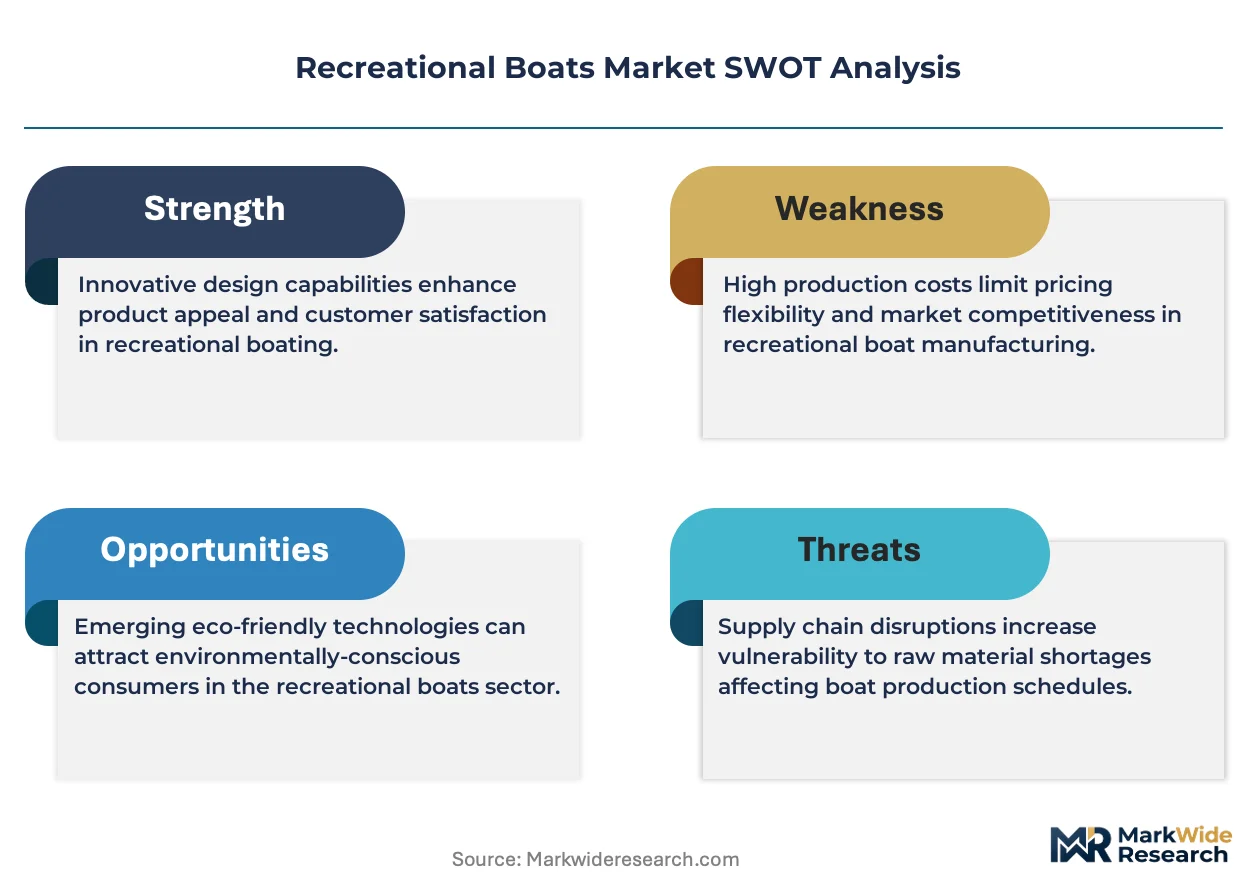
Italian and French producers anchor the premium yacht tier; American specialists hold volume positions in outboard-powered day boats and fishing platforms. The vendor base stratifies across three tiers: integrated boat-engine bundlers controlling propulsion supply, diversified marine conglomerates spanning multiple hull categories, and niche specialists in single-purpose craft. Consolidation pressure concentrates in gasoline outboard manufacturing where EPA Tier 3 compliance costs accelerate bundling strategies. Geographic expansion and capacity rebalancing toward mid-size cruiser gaps represent dominant competitive vectors.
Among North American fabricators, Brunswick Corporation and Malibu Boats exemplify divergent strategic archetypes. Brunswick's integration with Mercury Marine represents upstream control over critical propulsion supply. Malibu Boats occupies a position within the watersports specialization tier where younger demographic targeting rewards modular platform development. Yamaha Motor Corporation anchors Japanese production gravity in personal watercraft, representing technology leadership through platform continuity rather than segment diversification. These three companies illustrate how competitive positioning depends on supply chain configuration choices—captive engine production, segment focus, or geographic concentration—rather than scale alone.
| Leading Market Players |
|---|
| Brunswick Corporation |
| Yamaha Motor Corporation |
| Groupe Beneteau |
| Ferretti Group |
| Azimut Benetti Group |
| Malibu Boats |
| MasterCraft Boat Holdings |
| Bombardier Recreational Products |
| Polaris Inc |
| Others |
Cost & Logistics Intelligence
EPA Tier 3 catalytic converter mandates are forcing gasoline outboard manufacturers to absorb compliance costs or pass them downstream, compressing margins for non-integrated hull builders while rewarding Brunswick Corporation's captive Mercury Marine supply. This regulatory pressure is reshaping how pricing power distributes across the value chain.
Pricing Analysis
Dealer markup layers dominate recreational boat transactions, with physical showrooms capturing 15-25% margins on inventory carry before manufacturer rebates. Three-tier pricing structure across premium, standard, and economy levels separates ISO 12217-certified cruisers from coastal day boats and inland utility craft. Pricing pressure stems from direct-to-consumer configuration tools that bypass traditional specification processes. Charter operators and high-net-worth Florida buyers show lowest price sensitivity, while heartland freshwater fishing segments prioritize aluminum durability over premium composite performance.
Supply Chain Analysis
Single-source vulnerability sits with Asian petrochemical feedstocks for carbon fiber and epoxy resin systems that Italian superyacht builders depend on for hull fabrication. Manufacturing gravity draws from Italy, France, and the United States for premium fiberglass construction, with China and South Korea anchoring composite precursor supply. Tariff exposure runs through EU REACH compliance costs for bio-based resin transitions and EPA catalytic converter sourcing. Distribution runs through inventory-heavy dealer networks facing compression from manufacturer direct portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recreational boat manufacturing operates as a geographic-arbitrage play where final assembly shifts toward lighter certification jurisdictions while component sourcing remains anchored in established industrial clusters, exploiting the cost differential between EPA Tier 3 compliance in the United States and EU Stage V frameworks in Europe.
For Market Incumbents: To counter direct-to-consumer channel compression, defend dealer relationships through exclusive configuration rights and accelerated service bundling. Secure backward integration into outboard engine supply, mirroring Brunswick Corporation's Mercury Marine model, before EPA Tier 3 costs consolidate gasoline powertrain manufacturing. For New Entrants and Emerging Players: Begin with the 40-60 foot mid-size cruiser gap created by Italian output rebalancing, targeting Mediterranean charter specifications with hybrid diesel-electric drivetrains. Enter through ISO 12217 multi-region certification to access both North American and European markets without hull redesign, leveraging trailerable portability for younger coastal demographics. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized composite material suppliers serving REACH-compliant bio-based resin transitions. Long-term viability hinges on electrification infrastructure plays—marina fast-charging networks and lithium-ion system integration capabilities—rather than traditional hull fabrication. Watch Coast Guard battery-electric certification timelines as the inflection signal for powertrain technology shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Integration | Charter operators in the Mediterranean specify silent anchorage systems for competitive positioning. |
| Direct-to-Consumer Portal Launch | Younger coastal buyers finalize vessel configurations through manufacturer portals before physical inspection. |
| ISO 12217 Certification Investment | Single-hull designs access North American and European markets without expensive regional redesign. |
| Marina Charging Infrastructure Partnership | Fast-charging network standardization unlocks lithium-ion propulsion beyond early-adopter niches. |
| Bio-Based Resin System Adoption | EU REACH compliance accelerates hull manufacturing transitions away from petrochemical feedstocks. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with yacht builder procurement directors, marina infrastructure developers, EPA regulatory affairs specialists, and charter fleet operators with secondary validation against Coast Guard certification databases, EU ECHA REACH filings, and marina registration records across Florida, Viareggio, and Vendée production clusters. Bottom-up hull production estimates triangulated against top-down leisure expenditure tracking.
Segment-weighting approaches applied boat type, material construction, and usage purpose dimensions across the projection horizon. CAGRs derived from production line capacity utilization, order intake patterns at Fort Lauderdale and Genoa boat shows, and propulsion technology transition curves. Forecast inputs incorporated EPA Tier 3 compliance cost absorption rates and EU F-Gas refrigerant phase-down schedules.
Caveats apply where Coast Guard battery-electric certification delays or composite supply chain disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization timelines and charter demand persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Global Truck Camper Market
Recreational Vehicles
Fifth Wheel Trailer Market
Recreational Vehicles
Water Scooter Market
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Global Segway Consumption Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
US Low Speed Vehicle Market
Recreational Vehicles
United States RV Rental Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
Self Balancing Scooter Market