
 Tanker Cargo Ship Market | 2026-2036
Tanker Cargo Ship Market Size, Share, and Industry Trends Forecast 2026-2036
Tanker Cargo Ship Market Analysis
Asset-heavy ownership is rewriting competitive entry barriers for mid-size operators. Bahri leverages its state-linked crude contracts to dominate Middle East export routes. Scorpio Tankers specializes in product tanker segments with high charter rate sensitivity. Mitsui OSK Lines anchors its position through integrated LNG and crude logistics networks spanning Asian import terminals.
A tanker cargo ship is a double-hulled vessel engineered to transport liquid bulk commodities across maritime routes, typically ranging from 80,000 to 320,000 deadweight tonnes depending on vessel class and channel constraints. Its primary commercial purpose is moving crude oil, refined products, chemicals, and liquefied gases from production or storage terminals to refineries and consumption markets. VLCC tonnage commands the largest value pool on long-haul Middle East-to-Asia routes where economies of scale compress per-barrel freight costs. Chemical tankers represent the fastest-expanding segment as specialty cargo volumes outpace crude trade growth. Aframax vessels sustain premium day-rate positions in constrained ports and short-haul Atlantic basin trades.
The International Maritime Organization enforces Carbon Intensity Indicator metrics that mandate annual efficiency improvements for vessels above 5,000 gross tonnes, directly shaping newbuild specifications and retrofit investment cycles. Classification societies including Lloyd's Register and the American Bureau of Shipping certify structural and environmental compliance for hull designs and ballast water treatment installations. Port state control regimes in the European Union, Singapore, and the United States inspect for sulphur cap adherence under MARPOL Annex VI. Stakeholders must monitor scrubber retrofit payback periods against rising green methanol and ammonia bunker infrastructure commitments.
Market Dynamics
Dual-fuel engine retrofits are compressing fleet economics as IMO 2023 Carbon Intensity Indicator mandates force operators to choose between scrubber installations and alternative fuel infrastructure commitments before the 2025 enforcement window.
Growth Catalysts
- IMO CII Compliance Deadlines:Annual efficiency improvement mandates for vessels above 5,000 gross tonnes are accelerating capital deployment into hull optimization and engine upgrades across major shipping lanes.
- Refinery Feedstock Diversification:Chemical tanker demand from specialty cargo processors in Singapore and Rotterdam is outpacing crude trade expansion as biofuel blending requirements multiply port calls.
- Aframax Premium Positioning:Constrained Atlantic basin ports and short-haul routes sustain elevated day-rate structures for mid-size vessels serving US Gulf and Caribbean terminals.
Market Restraints
- Green Methanol Infrastructure Gaps:Bunkering availability at scale remains concentrated in Rotterdam and Singapore, forcing operators to carry dual-fuel compatibility without guaranteed supply chain coverage.
- Scrubber Retrofit Payback Uncertainty:High-sulphur fuel oil price spreads have compressed below break-even thresholds for installations completed during the 2019-2021 rush, stranding capital on older tonnage.
- Ballast Water Treatment System Failures:US Coast Guard port state control detentions for non-compliant BWTS installations have spiked in Houston and Long Beach, disrupting voyage schedules.
Strategic Opportunities
- Ammonia Bunker Pilot Corridors:Japan's METI-funded demonstration projects along the Australia-Japan iron ore route are creating first-mover infrastructure for zero-carbon fuel transitions.
- Product Tanker Arbitrage Windows:European diesel import dependency following Russian supply reconfiguration is extending voyage distances and tightening tonnage availability for clean product carriers.
- Digital Twin Fleet Management:Lloyd's Register-certified hull monitoring systems are enabling predictive maintenance contracts that reduce dry-docking frequency and extend asset life.
Industry Challenges
- Marine Engineer Shortage:Specialized training for dual-fuel engine operations lags fleet expansion, with Singapore Maritime Academy reporting capacity constraints for advanced certification programs.
- Classification Society Backlogs:Lloyd's Register and American Bureau of Shipping inspection queues for CII verification are extending 12-18 months, delaying charter contract renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tanker Cargo Ship Market |
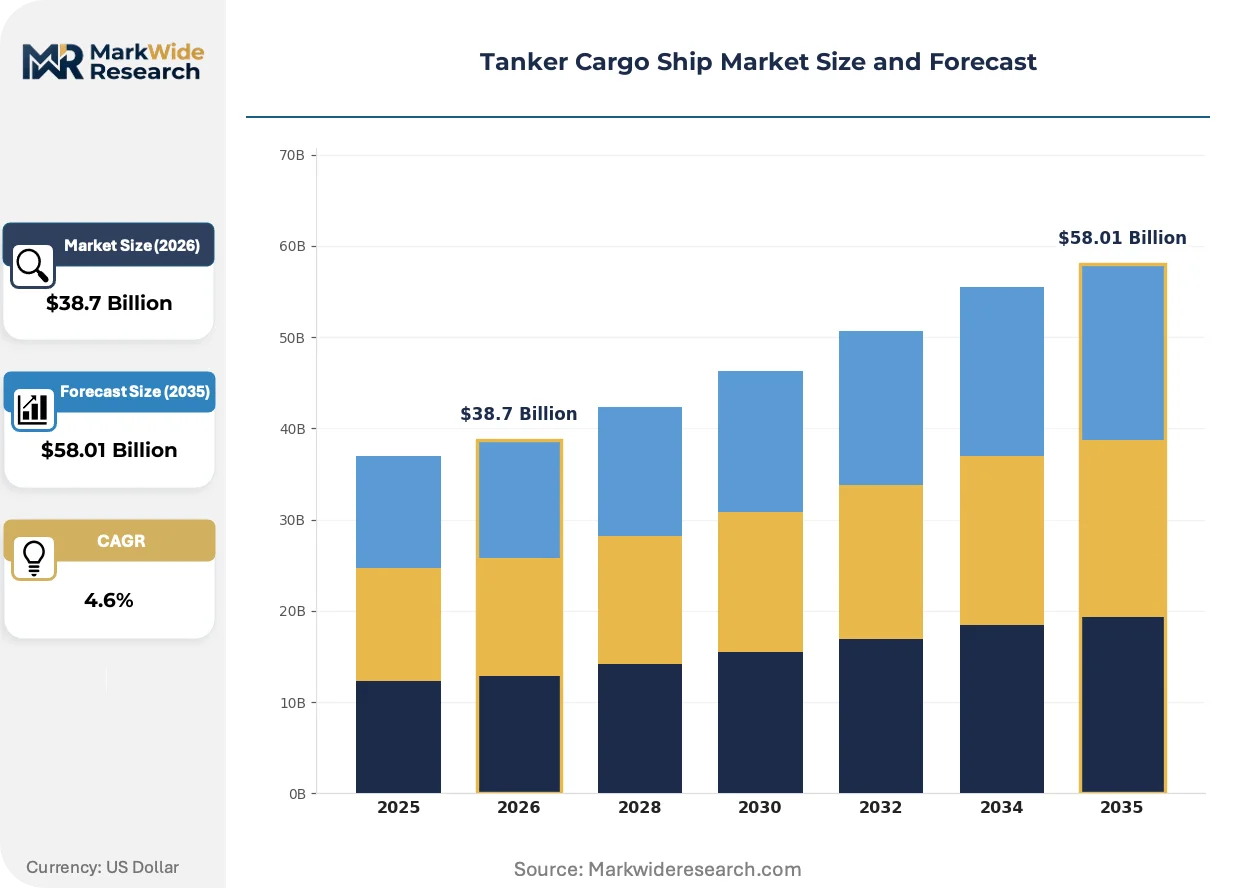
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Aframax, Suezmax, VLCC, Panamax Operation Mode: Commercial Transport, Chartering, Offshore Supply, Refinery Services Cargo Type: Crude Oil, Chemical Products, Liquefied Gas, Clean Petroleum Products End User: Oil Producers, Shipping Companies, Refineries, Energy Traders |
| Companies Covered | Bahri (National Shipping Company of Saudi Arabia), Teekay Tankers, China COSCO Shipping Energy Transportation, International Seaways, Tsakos Energy Navigation, Euronav, Scorpio Tankers, Mitsui OSK Lines, Frontline Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tanker Cargo Ship Market Emerging Trajectories
Maritime digitalization is compressing operational transparency gaps between charterers and shipowners, while regulatory enforcement tightens around emissions verification and ballast water compliance.
Digital twin hull monitoring systems are virtualizing structural integrity assessment for VLCC and Aframax fleets. Major operators in the Middle East-to-Asia crude corridor are deploying Lloyd's Register-certified platforms that replace scheduled dry-docking with continuous fatigue analysis. This virtualization is compressing maintenance cycles from five-year statutory intervals to condition-based interventions triggered by real-time stress telemetry.
The EU's FuelEU Maritime regulation imposes well-to-wake greenhouse gas intensity limits on vessels calling at European ports from 2025. Shipowners must document fuel provenance through certified mass-balance systems or face penalty surcharges per megajoule of energy consumed. Chemical tanker segments with frequent Rotterdam and Antwerp calls are responding by locking in bio-methanol offtake agreements with Dutch fuel suppliers.
Charterers are unbundling freight contracts from cargo insurance and inspection services, selecting third-party providers through competitive tender rather than accepting bundled owner arrangements. This disintermediation is fragmenting revenue pools for integrated operators while creating specialized niches for marine survey firms and P&I clubs. The shift is most visible in Singapore, where major trading houses now mandate independent cargo quantity verification for every clean product lift.
Tanker Cargo Ship Market Segmentation
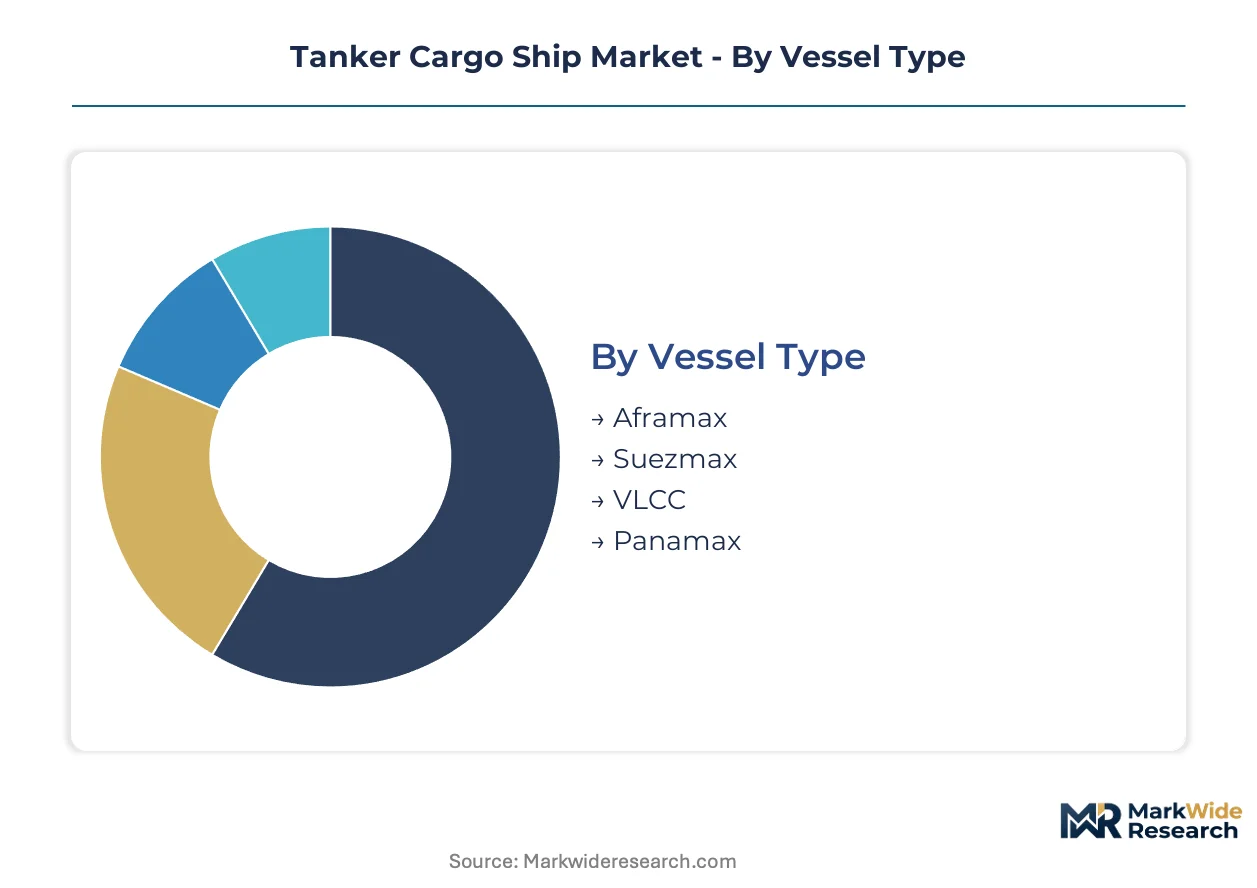
Tanker cargo ship segmentation reveals how vessel economics, cargo specifications, and operator models create distinct competitive arenas. Each dimension shapes capital deployment, regulatory exposure, and charter rate sensitivity in fundamentally different ways.
Vessel Type:
Mature tonnage classes dominate revenue pools while emerging specifications respond to channel constraints and carbon regulations.
- VLCC:These 320,000 deadweight tonne vessels achieve maximum economies of scale on Middle East-to-Asia crude corridors. Demand concentrates in Singapore and Chinese import terminals where single-vessel lifts minimize per-barrel freight costs for Saudi Aramco and ADNOC term contracts.
- Aframax:Mid-size 80,000-120,000 DWT hulls navigate constrained Atlantic basin ports including US Gulf Coast terminals and Caribbean discharge points. Premium day-rates persist in short-haul trades where Suezmax and VLCC dimensions exceed berth limits.
- Suezmax:150,000-200,000 DWT vessels optimized for Suez Canal transit economics serve West African export routes to European refineries.
- Panamax:Dimension-constrained hulls access smaller Asian and Latin American ports with limited draft infrastructure.
VLCC retains volume leadership; Aframax holds the steepest expansion curve as port infrastructure constraints tighten globally.
Operation Mode:
Contract structures range from asset-heavy ownership to service-based positioning, each carrying distinct balance sheet and revenue volatility profiles.
- Commercial Transport:Spot-market exposed operators trade voyage-by-voyage on Baltic Exchange benchmarks. Earnings fluctuate with tonne-mile demand and OPEC production quotas.
- Chartering:Time-charter and bareboat arrangements provide revenue visibility for vessel owners while transferring operational risk to charterers. Major trading houses in Geneva and Singapore lock in multi-year coverage.
- Offshore Supply:Dynamic positioning tankers serve floating production storage and offloading units in Brazilian pre-salt fields and West African deepwater developments.
- Refinery Services:Dedicated shuttle tankers and storage-integrated vessels support just-in-time feedstock delivery to Rotterdam and Houston refining complexes.
Commercial Transport captures the largest revenue pool; Chartering demonstrates the most stable cash flow characteristics across cycle turns.
Cargo Type:
Cargo chemistry determines tank coating specifications, segregation requirements, and trade route economics with minimal interchangeability between segments.
- Crude Oil:Unrefined petroleum movements from production terminals to refineries constitute the foundational volume base. Sour and sweet crude differentiation drives tank cleaning protocols between voyages.
- Chemical Products:Specialty cargoes including methanol, ethanol, and vegetable oils require stainless steel or epoxy-coated tanks with multi-grade segregation. Rotterdam and Antwerp chemical clusters generate dense port-call patterns.
- Liquefied Gas:LPG and ammonia movements in pressurized or refrigerated configurations serve petrochemical feedstock and emerging bunker fuel demand.
- Clean Petroleum Products:Gasoline, diesel, and jet fuel shipments from refining centers to consumption markets face stringent sulfur and quality certification requirements.
Crude Oil maintains tonnage dominance; Chemical Products gains share fastest as biofuel blending multiplies specialized cargo movements.
End User:
Customer procurement sophistication varies from state-linked term contracting to speculative trading positions, shaping payment terms and vessel specification demands.
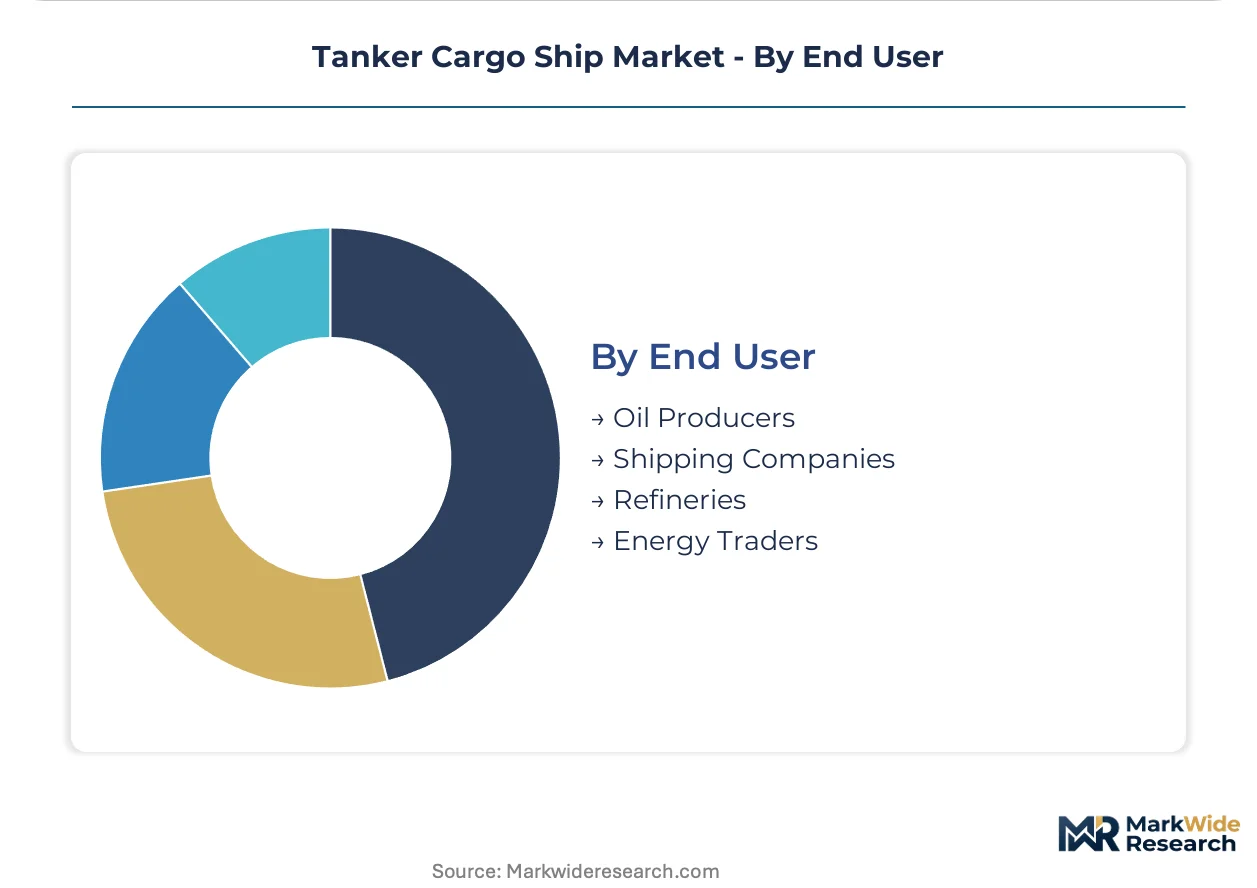
- Oil Producers:National oil companies and international majors contract dedicated tonnage for equity crude liftings from production terminals.
- Shipping Companies:Independent and state-affiliated fleet operators including Bahri and Mitsui OSK Lines balance spot exposure against long-term charter coverage.
- Refineries:Downstream processors optimize feedstock delivery timing through owned or chartered tonnage serving Singapore, Rotterdam, and Houston hubs.
- Energy Traders:Mercuria, Trafigura, and Vitol deploy vessels as floating storage and arbitrage instruments across contango and backwardated market structures.
Shipping Companies control the largest owned fleet base; Energy Traders generate the most volatile spot-market demand spikes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping tanker deployment patterns across major maritime corridors. Crude export terminals in the Middle East and West Africa face diverging vessel demand against import-dependent Asian refining centers. Regulatory fragmentation around carbon intensity metrics is forcing operators to optimize fleet positioning by jurisdiction.
Singapore
Maritime Singapore anchors the largest bunkering hub for VLCC and chemical tanker fleets serving Middle East-to-Asia crude corridors. The Maritime and Port Authority enforces strict low-sulphur fuel standards under MARPOL Annex VI implementation. Jurong Port and Tuas Mega Port concentrate storage-integrated tanker operations for biofuel blending and chemical cargo transhipment.
United States
US Gulf Coast crude exports and refined product movements sustain Aframax and Suezmax demand through Houston and Corpus Christi terminals. The US Coast Guard enforces Ballast Water Treatment System compliance under port state control regimes with elevated detention rates in Long Beach. Texas and Louisiana refining clusters generate dense shuttle tanker and clean product carrier call patterns.
Netherlands
Rotterdam ranks as Europe's largest tanker port handling crude imports and chemical cargo for German and Benelux refineries. The EU's FuelEU Maritime regulation imposes well-to-wake greenhouse gas intensity limits on vessels calling from 2025. The Port of Rotterdam Authority is developing green methanol and ammonia bunkering infrastructure through partnerships with Dutch fuel suppliers.
Japan
Japanese import dependency on Middle East crude sustains long-haul VLCC charter demand through discharge terminals in Chiba and Yokkaichi. METI funds ammonia bunker pilot corridors along the Australia-Japan iron ore route for zero-carbon fuel transition demonstration. Osaka Bay and Nagoya industrial zones concentrate chemical tanker traffic for petrochemical feedstock delivery.
Saudi Arabia
Saudi crude export terminals at Ras Tanura and Yanbu generate dedicated VLCC liftings under term contracts with Asian refiners. The Saudi Energy Efficiency Center implements national programs aligned with IMO Carbon Intensity Indicator frameworks for fleet modernization. King Abdullah Port on the Red Sea is expanding tanker handling capacity for westbound crude movements to European markets.
Tanker Cargo Ship Market Vendor Landscape
On the supply side, the industry is consolidating around state-affiliated fleets and publicly traded tanker specialists with differentiated vessel class exposure. Ownership structures fragment between national oil company-linked operators, independent listed companies, and integrated shipping conglomerates. Two strategic archetypes dominate: scale-driven crude carriers optimizing VLCC economies and product tanker specialists capturing chemical cargo premiums. Competitive moves center on dual-fuel engine retrofits for IMO 2023 compliance and time-charter contract renewals securing multi-year revenue visibility.
Within the state-linked tier, Bahri anchors Middle East export route dominance through its Saudi Aramco contract portfolio. Among independent specialists, Scorpio Tankers and Frontline Ltd. occupy positions at opposite ends of the product-crude spectrum. Mitsui OSK Lines exemplifies integrated conglomerate strategy spanning LNG and crude logistics networks. These three operators represent distinct capital deployment models: state-backed term contracting, spot-market rate sensitivity, and diversified energy transport integration.
| Leading Market Players |
|---|
| Bahri (National Shipping Company of Saudi Arabia) |
| Teekay Tankers |
| China COSCO Shipping Energy Transportation |
| International Seaways |
| Tsakos Energy Navigation |
| Euronav |
| Scorpio Tankers |
| Mitsui OSK Lines |
| Frontline Ltd. |
| Others |
Supply Flow & Price Mechanics
Regulatory chokepoints at IMO 2023 Carbon Intensity Indicator enforcement determine both charter rate tier spreads and fleet positioning economics across bunkering hubs. Single-source dependency on Rotterdam and Singapore green methanol infrastructure compresses pricing power for operators lacking dual-fuel compatibility while forcing supply chain consolidation around certified fuel corridors.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in tanker charter markets. Price differentiation centers on vessel CII rating certification and after-sales technical service bundling for engine maintenance. Cost compression in the economy tier is intensifying because scrubber retrofit payback failures strand older tonnage at discounted rates. Energy traders demonstrate highest price sensitivity on spot fixtures, while national oil companies lock in term contracts with minimal rate volatility.
Supply Chain Analysis
Extended payment terms from South Korean and Chinese shipyards are restructuring capital deployment timelines for fleet operators. Geographic supply concentration centers on South Korea, China, and Japan for specialized dual-fuel engine manufacturing. Raw material dependencies rest on high-grade steel plate from Japanese mills, European emission control systems, and Singapore-based bunkering logistics. Single-source vulnerability at Rotterdam ammonia infrastructure creates distribution bottlenecks. Distribution runs through integrated trading houses in Geneva and Singapore that control cargo aggregation and vessel scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across vessel class specializations creates entry niches as chemical tanker demand outpaces crude trade growth. Biofuel blending mandates and feedstock diversification multiply port-call patterns for smaller operators.
For Market Incumbents: Entrench Middle East-to-Asia corridor dominance through backward integration into dedicated bunkering infrastructure at Ras Tanura and Singapore. Lock in multi-year time-charter coverage with Asian refiners before CII enforcement tightens vessel availability. Prioritize Lloyd's Register certification investment to bypass inspection queue backlogs threatening contract renewals.
For New Entrants and Emerging Players: West African export terminal underpenetration offers white-space access for Aframax specialists serving Atlantic basin short-haul trades. Target chemical tanker segments in Rotterdam-Antwerp clusters where stainless steel coating capabilities create technical barriers. Deploy digital twin hull monitoring as a differentiated service layer to extend asset life for mid-size fleet owners.
For Investors and Strategic Acquirers: IMO 2025 FuelEU Maritime enforcement reshapes the acquisition landscape toward dual-fuel ready tonnage with verified green fuel offtake agreements. Long-term viability favors integrated operators spanning LNG and crude logistics networks over pure-play spot-market exposed fleets. Monitor Lloyd's Register and American Bureau of Shipping inspection queue duration as the critical inflection signal for charter rate compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Engine Retrofit Program | IMO 2023 CII compliance deadlines force capital deployment into methanol-compatible propulsion systems. |
| Ammonia Bunker Corridor Development | METI-funded Australia-Japan pilot projects create first-mover infrastructure for zero-carbon fuel transitions. |
| Digital Twin Fleet Management | Lloyd's Register-certified hull monitoring enables predictive maintenance contracts reducing dry-docking frequency. |
| Chemical Tanker Fleet Expansion | Specialty cargo volumes from Rotterdam and Singapore biofuel blending outpace crude trade growth rates. |
| Integrated Trading House Partnership | Mercuria and Vitol charter contracts provide revenue visibility across contango and backwardated market structures. |
Methodological Framework
Initial hypotheses were tested against primary input from fleet operations directors, chartering managers at trading houses, marine engineers at classification societies, and port authority compliance officers and refined through secondary validation. Bottom-up triangulation combined Lloyd's Register certification databases, Baltic Exchange fixture records, MARPOL Annex VI port state control detention reports, and customs trade flow data with top-down macroeconomic indicators.
Demand-supply-balance framing across the analysis window modeled vessel type segmentation, operation mode contract structures, cargo chemistry specifications, and end-user procurement sophistication. CAGRs were derived from tonne-mile demand projections against fleet orderbook and scrapping assumptions. Industry-specific forecast inputs incorporated OPEC production quota adjustments and refinery feedstock diversification patterns.
Practitioners should monitor scrubber retrofit failure rates, green methanol bunkering infrastructure buildout, and classification society inspection queue duration for early signals. Forecasts reflect documented assumptions about regulatory enforcement timelines and alternative fuel cost parity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Tank Container Shipping Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market
Logistics and Shipping
Hazardous Goods Logistics Market