
 Secure Logistics Market | 2026-2036
Secure Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Secure Logistics Market Intelligence
European armored vehicle fleet capacity is hardening as operators expand temperature-controlled vault networks. DHL Supply Chain & Global Forwarding leverages its pharmaceutical-certified lane infrastructure across the Benelux region. Kuehne + Nagel anchors high-value electronics flows through Swiss customs-bonded facilities. DB Schenker Logistics dominates German automotive component secure corridors with dedicated convoy protocols.
Secure logistics encompasses the specialized movement, storage, and monitoring of high-value, sensitive, or regulated goods through tamper-evident packaging, real-time GPS telemetry, and biometric access controls with chain-of-custody documentation. The primary purpose is eliminating theft, diversion, and environmental degradation during transit of pharmaceuticals, precious metals, classified documents, and semiconductor wafers. Secure Transportation services command the largest revenue pool due to recurring fuel, labor, and insurance premiums on dedicated armored and climate-controlled fleets. RFID Systems adoption is accelerating fastest among technology segments as pallet-level item authentication replaces manifest-only tracking in pharmaceutical distribution. Cold Chain Logistics solutions carry the densest margin concentration because validated thermal packaging and redundant refrigeration failure protocols require specialized engineering and regulatory certification.
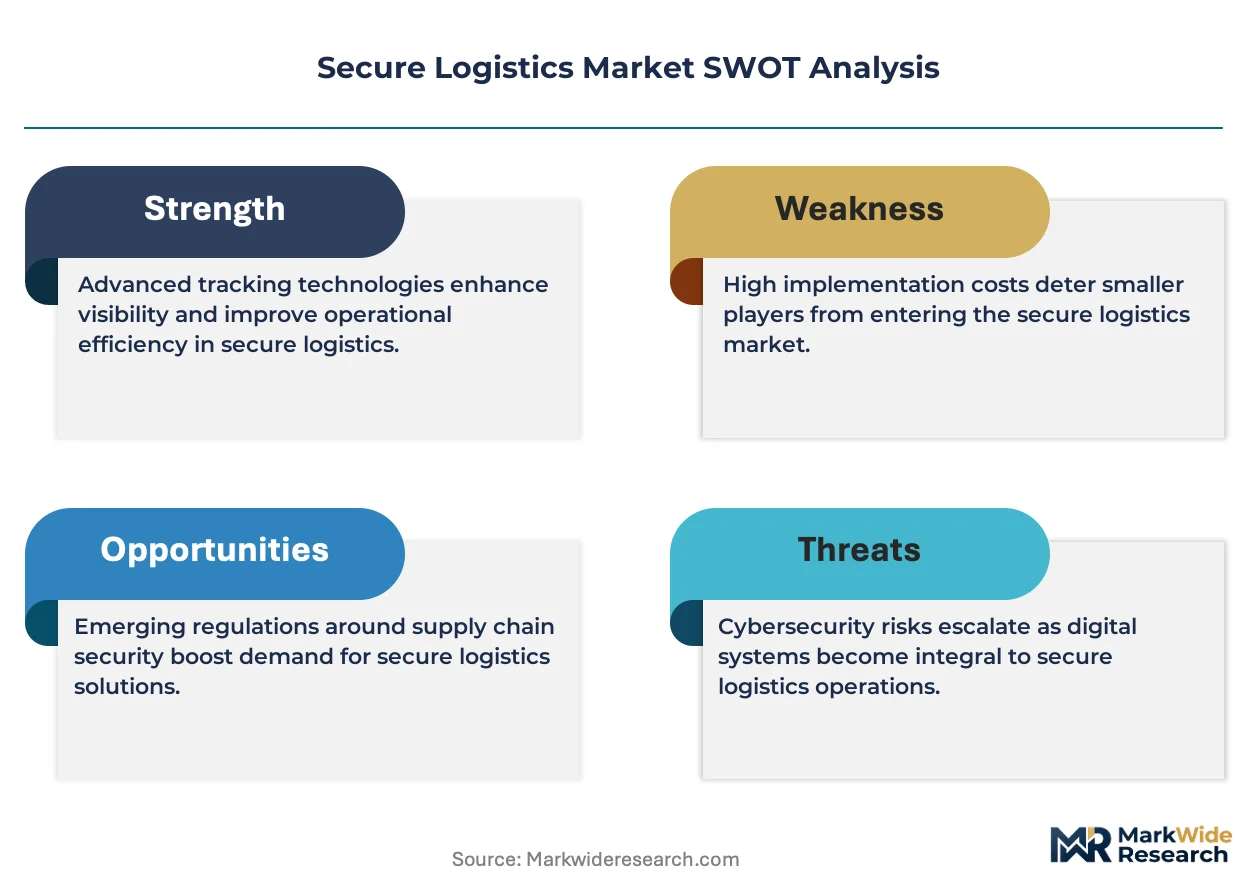
FDA's Drug Supply Chain Security Act and the EU's MDR mandate unit-level traceability for pharmaceutical shipments, forcing logistics providers to deploy serialization-capable infrastructure. Germany's KBA and France's ANSM enforce divergent vehicle security standards, fragmenting fleet specifications across Continental routes. Stakeholders must decide whether to absorb compliance costs through captive insurance subsidiaries or pass them through as transparent surcharges on per-lane contracts.
Market Dynamics
Pharmaceutical serialization mandates and EU F-Gas phase-down protocols are forcing fleet operators to rebuild temperature-controlled infrastructure from the ground up, compressing equipment replacement cycles and fragmenting certification standards across corridors.
Growth Catalysts
- EU MDR serialization:Unit-level traceability requirements for medical devices mandate RFID-capable vault networks, pulling investment into validated infrastructure.
- Biologics cold chain expansion:Cell and gene therapies require ultra-low temperature transport, creating dedicated lane demand from manufacturing clusters to clinical sites.
- Germany's Rhine-Ruhr corridor:Dense pharmaceutical and automotive component flows concentrate high-value shipment density, justifying armored fleet deployment.
Market Restraints
- Refrigerant cost volatility:EU F-Gas quota reductions spike HFC prices, inflating cold chain operating expenses beyond contract escalation clauses.
- Armored vehicle supply concentration:Specialist chassis and ballistic glass production clusters in Eastern Europe, creating single-source vulnerability for fleet expansion.
- Cross-border regulatory friction:France's ANSM and Germany's KBA enforce divergent vehicle security specifications, preventing standardized fleet deployment.
Strategic Opportunities
- Swiss customs-bonded vault expansion:Neutral jurisdiction status attracts high-value electronics and precious metals flows seeking tariff-efficient staging.
- Benelux pharmaceutical consolidation:Port of Rotterdam and Brussels Airport cluster vaccine and API distribution, rewarding lane-specialized operators.
- EU Green Deal fleet incentives:Electric armored vehicle subsidies accelerate zero-emission last-mile deployment in urban cores.
Industry Challenges
- Certified driver scarcity:Hazardous materials endorsements combined with security clearance requirements constrict qualified labor pools.
- Multi-modal integration complexity:Sea-air pharmaceutical corridors demand synchronized custody handoffs between maritime and air freight security protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secure Logistics Market |
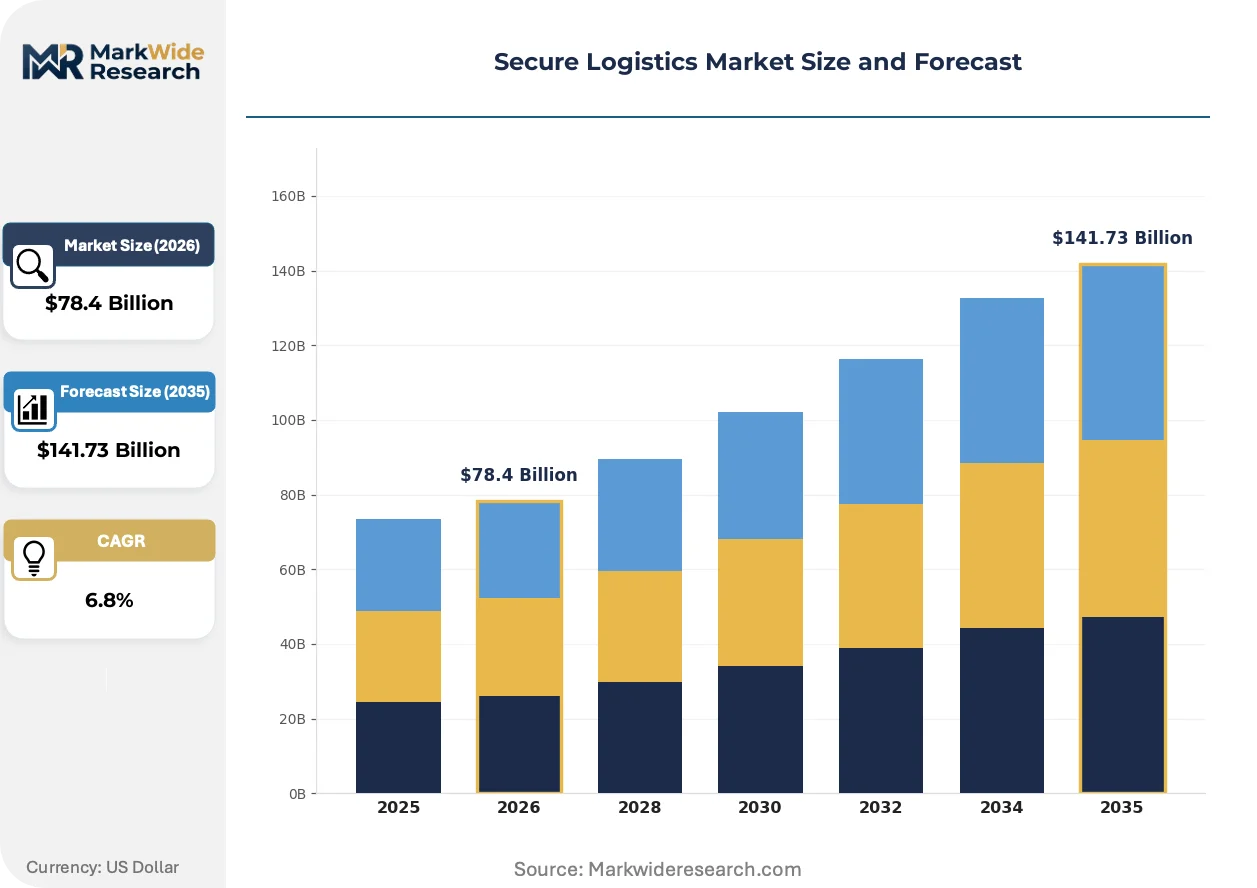
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Secure Transportation, Monitoring Services, Packaging Solutions, Risk Management End User: Pharmaceuticals, Electronics, Government, Retail Technology: GPS Tracking, Biometric Controls, RFID Systems, Encryption Solutions Solution: Cold Chain Logistics, Secure Warehousing, Inventory Management, Last-Mile Delivery |
| Companies Covered | Kuehne + Nagel, DSV, DHL Supply Chain & Global Forwarding, Nippon Express, C.H. Robinson Worldwide, FedEx, DB Schenker Logistics, CEVA Logistics, United Parcel Service (UPS), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secure Logistics Market Strategic Shifts & Innovations
Real-time telemetry and biometric authentication are compressing chain-of-custody documentation from batch-level to individual-item resolution, eliminating manifest-reconciliation delays at transfer points.
Blockchain-enabled custody logging is integrating with existing GPS telemetry stacks to create immutable timestamp records for pharmaceutical shipments. Major logistics providers deploy this across temperature-controlled lanes to preempt FDA DSCSA audit failures. The technology is integrating serialization data with customs pre-clearance systems, collapsing border dwell times.
EU F-Gas Regulation phase-down schedules are accelerating adoption of CO2 transcritical refrigeration in armored vehicles. Fleet operators in Germany and France retrofit existing chassis or specify new builds to maintain cold chain compliance. Pharmaceutical lanes through the Benelux region face the steepest equipment replacement deadlines.
Buyer procurement of secure logistics is consolidating around lane-performance guarantees rather than per-shipment rates. Large pharmaceutical manufacturers bundle multi-year contracts with penalty clauses for temperature excursions. This restructuring concentrates volume with operators holding redundant refrigeration failure protocols and captive insurance capacity.
Secure Logistics Market Segmentation
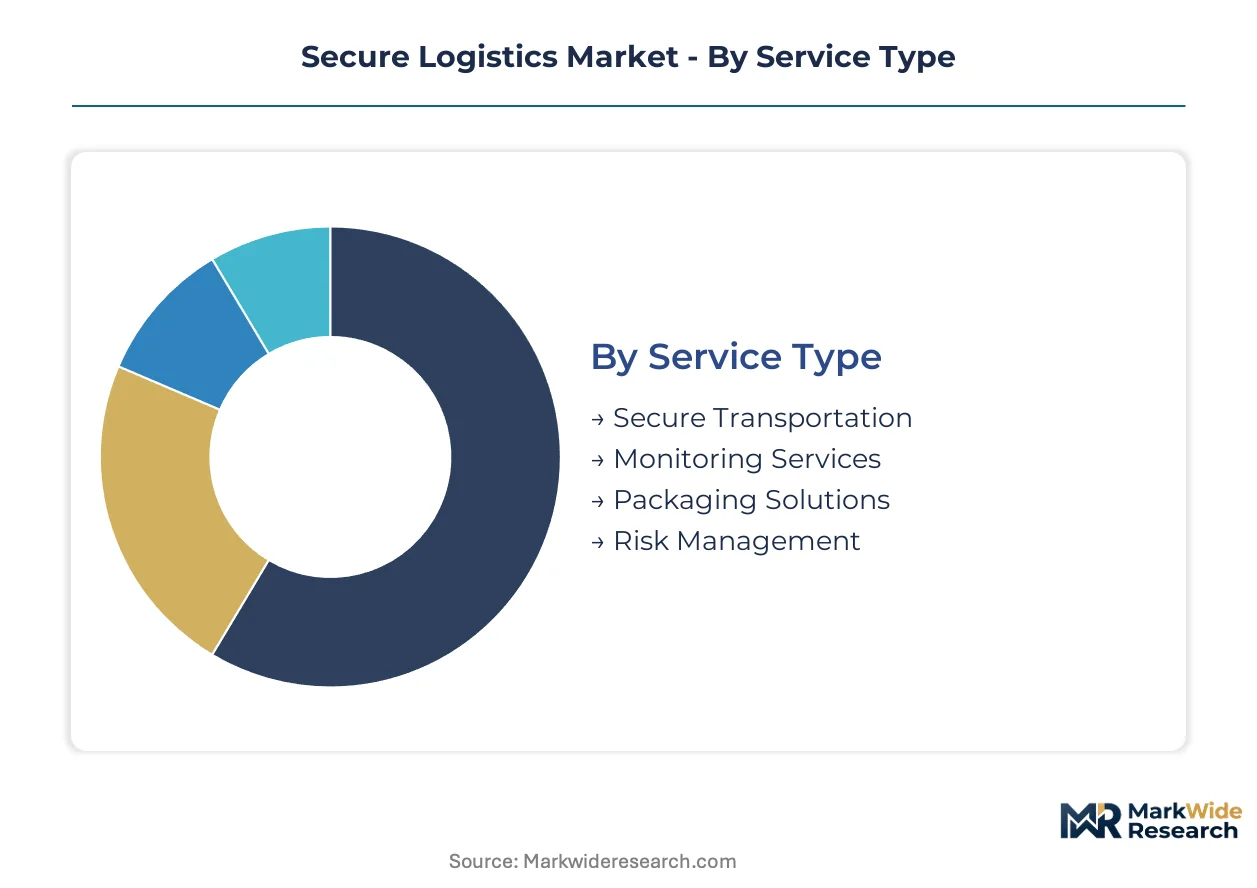
Segmentation in secure logistics determines capital allocation across divergent compliance burdens and margin structures. Service type shapes fleet composition, technology governs audit readiness, and end-use concentration dictates lane specialization.
Service Type:
Standalone services operate as discrete revenue lines with dedicated infrastructure, while embedded functions integrate into broader logistics contracts at lower visibility.
- Secure Transportation:Dedicated armored and climate-controlled fleets with trained convoy personnel carry recurring fuel, labor, and insurance premiums. Demand concentrates in Germany's Rhine-Ruhr pharmaceutical corridor and Benelux vaccine distribution lanes, driven by EU MDR serialization mandates and F-Gas refrigeration compliance.
- Monitoring Services:Real-time GPS telemetry and environmental sensors provide continuous custody verification with automated excursion alerts. Pharmaceutical manufacturers in Switzerland and the Netherlands bundle these with penalty clauses for temperature deviations, compressing documentation from batch-level to item-level resolution.
- Packaging Solutions:Tamper-evident containers and validated thermal packaging for cell and gene therapies.
- Risk Management:Captive insurance structures and lane-specific security protocols for high-value electronics flows.
Volume placements concentrate in Secure Transportation; the faster expansion belongs to Monitoring Services.
End User:
Cost tiers separate premium-validated lanes from standard security protocols, with certification requirements scaling dramatically across verticals.
- Pharmaceuticals:Biologics and cell therapies demand ultra-low temperature transport with redundant refrigeration failure protocols. EU F-Gas phase-down schedules force fleet replacement cycles in France and Germany, while FDA DSCSA and EU MDR mandate unit-level traceability infrastructure.
- Electronics:Semiconductor wafers and high-value components require Swiss customs-bonded staging and tariff-efficient routing through neutral jurisdictions.
- Government:Classified document chains with biometric access controls and security clearance requirements.
- Retail:Luxury goods and precious metals with dedicated last-mile armored deployment.
Certification intensity peaks in Pharmaceuticals; Electronics delivers the densest margin concentration per lane-kilometer.
Technology:
Maturity curves separate proven tracking stacks from emerging authentication layers still seeking standardization.
- RFID Systems:Pallet-level and item-level authentication replacing manifest-only tracking in pharmaceutical distribution. Benelux operators deploy serialization-capable infrastructure to preempt FDA audit failures, with adoption accelerating fastest among technology segments due to EU MDR mandates.
- GPS Tracking:Real-time telemetry integrating with blockchain custody logging for immutable timestamp records across temperature-controlled lanes.
- Biometric Controls:Driver and handler authentication with chain-of-custody verification at transfer points.
- Encryption Solutions:Data security protocols for documentation and sensor transmission.
Deployment scale favors GPS Tracking; RFID Systems are climbing the fastest as serialization deadlines approach.
Solution:
Application criticality determines whether solutions operate as standalone profit centers or cost-absorbed compliance functions.
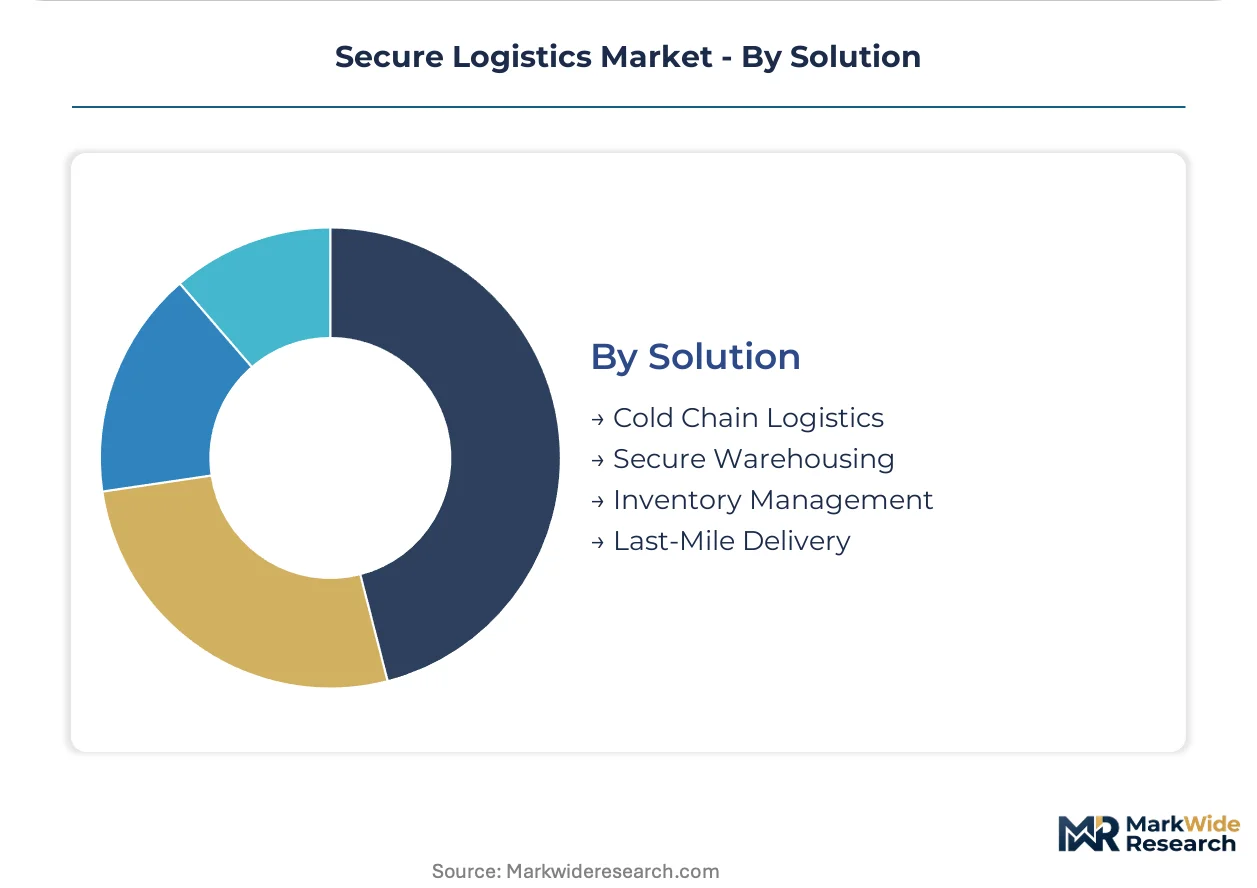
- Cold Chain Logistics:Validated thermal packaging and redundant refrigeration protocols carry the densest margin concentration due to specialized engineering and regulatory certification requirements. CO2 transcritical refrigeration retrofits dominate German and French fleet procurement as F-Gas quotas tighten.
- Secure Warehousing:Customs-bonded vault networks with biometric access in Swiss and Benelux hubs for high-value staging.
- Inventory Management:Real-time visibility systems integrating serialization data with customs pre-clearance.
- Last-Mile Delivery:Electric armored vehicle deployment in urban cores supported by EU Green Deal subsidies.
Contract value concentrates in Cold Chain Logistics; Secure Warehousing is gaining share fastest through Swiss vault expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade refrigerants and armored vehicle chassis originate from concentrated manufacturing zones in Germany, Switzerland, and the Netherlands, anchoring European secure logistics infrastructure.
Germany
Biologics manufacturing clusters in the Rhine-Ruhr corridor drive ultra-low temperature transport demand. KBA vehicle security specifications diverge from neighboring France, forcing fleet operators to maintain dual-certification inventories. Dedicated convoy protocols for automotive components dominate North Rhine-Westphalia's secure corridors.
Switzerland
High-value electronics and precious metals flows seek tariff-efficient staging in Swiss customs-bonded vaults. Swissmedic pharmaceutical regulations align with EU MDR traceability mandates, streamlining cross-border serialization. Geneva and Zurich anchor neutral-jurisdiction logistics hubs for semiconductor wafer movements.
Netherlands
Port of Rotterdam and Brussels Airport concentrate vaccine and active pharmaceutical ingredient distribution. F-Gas quota reductions accelerate CO2 transcritical refrigeration retrofits across Dutch temperature-controlled fleets. Amsterdam's logistics operators deploy RFID-capable infrastructure to preempt FDA DSCSA audit requirements.
France
ANSM enforces vehicle security standards distinct from German KBA protocols, fragmenting fleet deployment across Continental routes. Paris-region pharmaceutical manufacturers demand redundant refrigeration failure protocols for cell and gene therapies. Lyon and Marseille logistics corridors face compressed equipment replacement cycles under EU F-Gas phase-down schedules.
United Kingdom
Post-Brexit customs complexity drives demand for bonded secure warehousing at London Heathrow and Felixstowe. MHRA pharmaceutical regulations maintain serialization alignment with EU MDR, preserving traceability infrastructure investments. Midlands-based automotive component flows require dedicated armored lane protocols to Continental manufacturing sites.
Secure Logistics Market Key Industry Players
Global majors compete with regional champions across certification-intensive pharmaceutical corridors and high-value electronics lanes. Market structure tilts toward consolidated service provision at the premium tier, with fragmented specialty operators occupying niche temperature-controlled segments. Three archetypes dominate: integrated logistics conglomerates with captive pharmaceutical infrastructure, regional specialists with bonded vault networks, and technology-forward operators deploying blockchain-telemetry stacks. Competitive moves center on lane-performance guarantee contracts and captive insurance subsidiary formation to absorb compliance cost volatility.
Within the integrated logistics tier, Kuehne + Nagel and DHL Supply Chain & Global Forwarding exemplify archetypes anchored in pharmaceutical-certified infrastructure. DB Schenker Logistics occupies a position representing German automotive-secure corridor specialization. These operators sit within a competitive set where scale-driven compliance absorption separates premium-tier providers from regional challengers.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| DSV |
| DHL Supply Chain & Global Forwarding |
| Nippon Express |
| C.H. Robinson Worldwide |
| FedEx |
| DB Schenker Logistics |
| CEVA Logistics |
| United Parcel Service (UPS) |
| Others |
Cost & Logistics Intelligence
EU MDR serialization mandates and F-Gas phase-down schedules are forcing pharmaceutical manufacturers to bundle lane-performance guarantees with multi-year contracts, compelling logistics operators to absorb compliance costs through captive insurance subsidiaries or pass them through as transparent surcharges on per-lane contracts. This procurement restructuring concentrates volume with operators holding redundant refrigeration protocols, compressing margins for undifferentiated fleet providers.
Pricing Analysis
Lane-performance guarantees bundled with temperature-excursion penalties now dominate contract structures across pharmaceutical corridors. Price differentiation separates operators with EU MDR-certified RFID infrastructure from manifest-only tracking providers. Cost compression in standard secure transport is intensifying because refrigerant price volatility under F-Gas quotas outpaces contract escalation clauses. Large pharmaceutical manufacturers show least price sensitivity for validated cold chain lanes, while retail luxury goods buyers drive hardest bargain on last-mile armored deployment.
Supply Chain Analysis
Single-source vulnerability sits with Eastern European specialist chassis and ballistic glass production clusters, constraining fleet expansion timelines for armored vehicle operators. Armored vehicle chassis and refrigeration units draw from Germany, Poland, and Czech Republic manufacturing hubs. HFC refrigerants, CO2 transcritical systems, and validated thermal packaging materials rest on concentrated chemical processing inputs. Tariff exposure runs through customs-bonded vault networks in Swiss neutral jurisdiction. Distribution feeds from Rhine-Ruhr pharmaceutical clusters through Benelux port and airport hubs to clinical sites across Continental Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified driver scarcity combined with divergent KBA and ANSM vehicle security specifications creates a supply-constrained environment where operators holding dual-certification inventories command premium pricing power across fragmented Continental corridors.
For Market Incumbents: Acquire captive insurance subsidiaries to internalize compliance cost volatility from F-Gas refrigerant price spikes. Expand CO2 transcritical refrigeration capacity in German and French fleet procurement ahead of phase-down deadlines. Consolidate lane-specialized operators in Benelux vaccine distribution corridors to preempt emerging technology-forward entrants deploying blockchain-telemetry stacks.
For New Entrants and Emerging Players: Capture Swiss customs-bonded vault expansion demand for high-value electronics and semiconductor wafer staging. Target underpenetrated cell and gene therapy ultra-low temperature lanes from manufacturing clusters to clinical sites. Lead with RFID-capable infrastructure bundled with real-time telemetry to preempt FDA DSCSA audit requirements for US-facing pharmaceutical shipments.
For Investors and Strategic Acquirers: The window for entry favors operators holding redundant refrigeration failure protocols and pharmaceutical-certified lane infrastructure. Long-term viability centers on consolidation plays across fragmented temperature-controlled segments rather than greenfield fleet deployment. Watch EU F-Gas quota allocation decisions as inflection indicator for equipment replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Insurance Subsidiary Formation | Absorbs refrigerant cost volatility from EU F-Gas quota reductions across temperature-controlled fleets. |
| CO2 Transcritical Refrigeration Retrofit | Maintains pharmaceutical cold chain compliance under tightening EU F-Gas phase-down schedules. |
| RFID-Capable Infrastructure Deployment | Preempts FDA DSCSA and EU MDR audit failures through unit-level serialization authentication. |
| Swiss Customs-Bonded Vault Expansion | Captures tariff-efficient staging demand from high-value electronics and precious metals flows. |
| Dual-Certification Fleet Inventory | Resolves cross-border friction between Germany's KBA and France's ANSM divergent vehicle standards. |
Research Approach
Document review covered EU regulatory filings, pharmaceutical logistics contracts, and fleet operator certification records, complemented by interviews with secure logistics operations directors, pharmaceutical supply chain managers, cold chain engineering specialists, and customs-bonded vault operators. Secondary validation drew from EMA serialization guidelines, KBA vehicle security specifications, ANSM transport regulations, and F-Gas quota allocation data. Bottom-up lane volume estimates triangulated against top-down market sizing across service type, technology, and end-use dimensions.
Historical volume trends cross-referenced against expert panel input on equipment replacement cycles and refrigerant cost trajectories. Segmentation modeling covered service type, technology maturity, end-use certification intensity, and regional regulatory cluster variations. CAGRs derived from equipment deployment schedules, pharmaceutical serialization deadlines, and cold chain infrastructure investment flows. Forecast inputs incorporated biologics manufacturing expansion, cell therapy clinical trial site distribution, and electric armored vehicle subsidy uptake under EU Green Deal frameworks.
The model holds under stable EU F-Gas phase-down implementation and sustained pharmaceutical serialization enforcement; deviation in refrigerant quota allocation timing or MDR audit intensity would shift equipment replacement demand and lane pricing power materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
Spain Freight and Logistics Market
Logistics and Shipping
Chile Air Freight Transport Market
Logistics and Shipping
Japan Logistics Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
Dry Van Container Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
United States Digital Freight Forwarding Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
Chile Freight and Logistics Market