
 Thailand Freight and Logistics Market | 2026-2036
Thailand Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Freight and Logistics Market Outlook
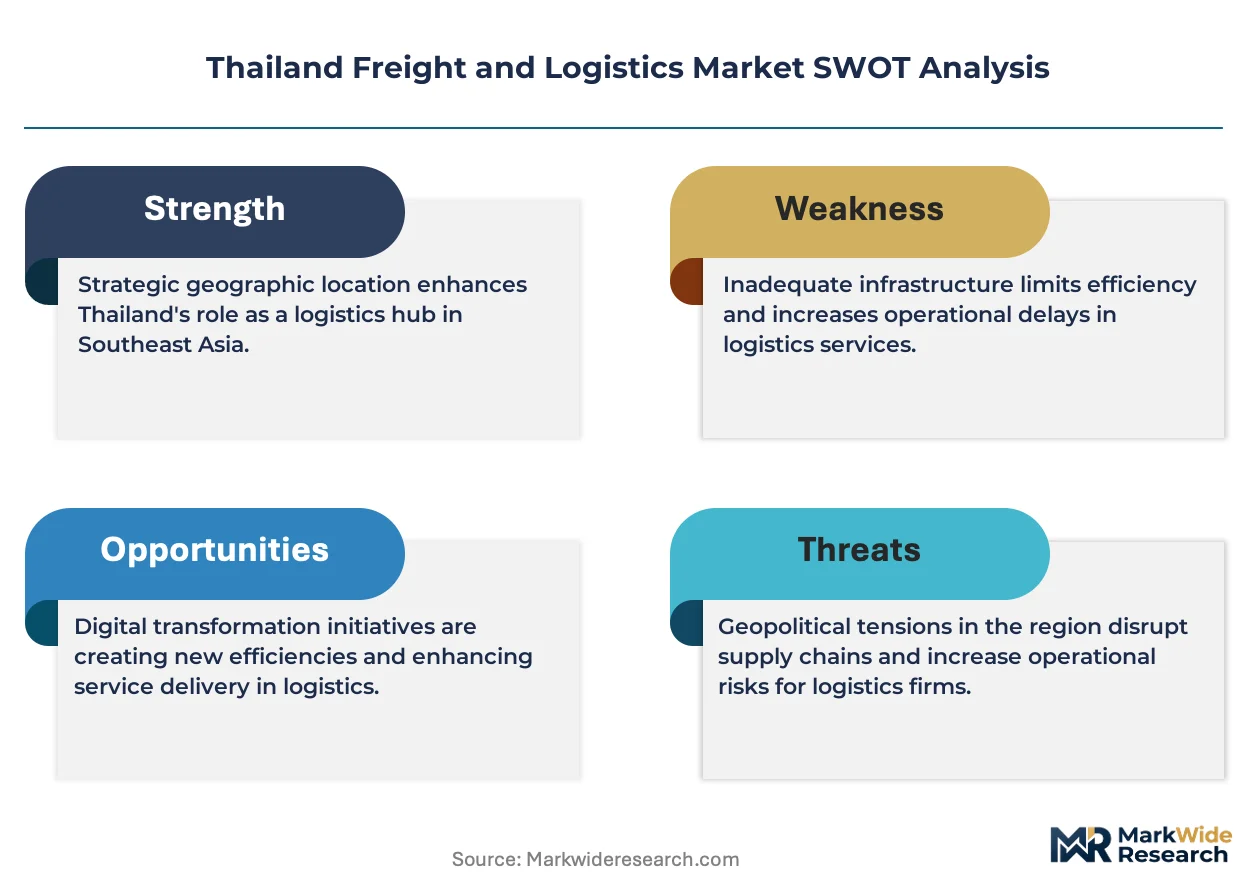
The gap between premium integrated logistics and commodity freight is expanding across Thailand. DB Schenker leverages its European network to serve automotive and electronics exporters from the Eastern Seaboard. Kerry Logistics Network Ltd. anchors its ASEAN hub operations through bonded warehouse capacity near Laem Chabang port. Flash Express competes aggressively on last-mile density in secondary cities.
Thailand freight and logistics encompasses the physical movement, storage, and information management of goods across multimodal networks operating at temperatures ranging from ambient to minus 25 degrees Celsius for cold chain applications. The sector coordinates inventory flows between manufacturing plants, distribution centers, and end consumers with transit time reliability measured in hours for express parcels and days for containerized sea freight. Road transport dominates domestic volume given Thailand's extensive highway network connecting Bangkok to industrial zones in Rayong and Chonburi. Warehousing is absorbing capital fastest as e-commerce fulfillment demands same-day delivery radii from urban distribution nodes. Value-added services including customs brokerage and inventory financing command superior margins compared to pure transport contracting.
The Department of Land Transport enforces weight limits and driver hour regulations that constrain long-haul trucking economics while promoting rail intermodal alternatives. Customs Department modernization under Thailand's National Single Window initiative reduces clearance friction for cross-border ASEAN trade. Stakeholders must weigh port capacity expansion at Laem Chabang against inland waterway investments on the Chao Phraya River as alternative freight corridors mature.
Market Dynamics
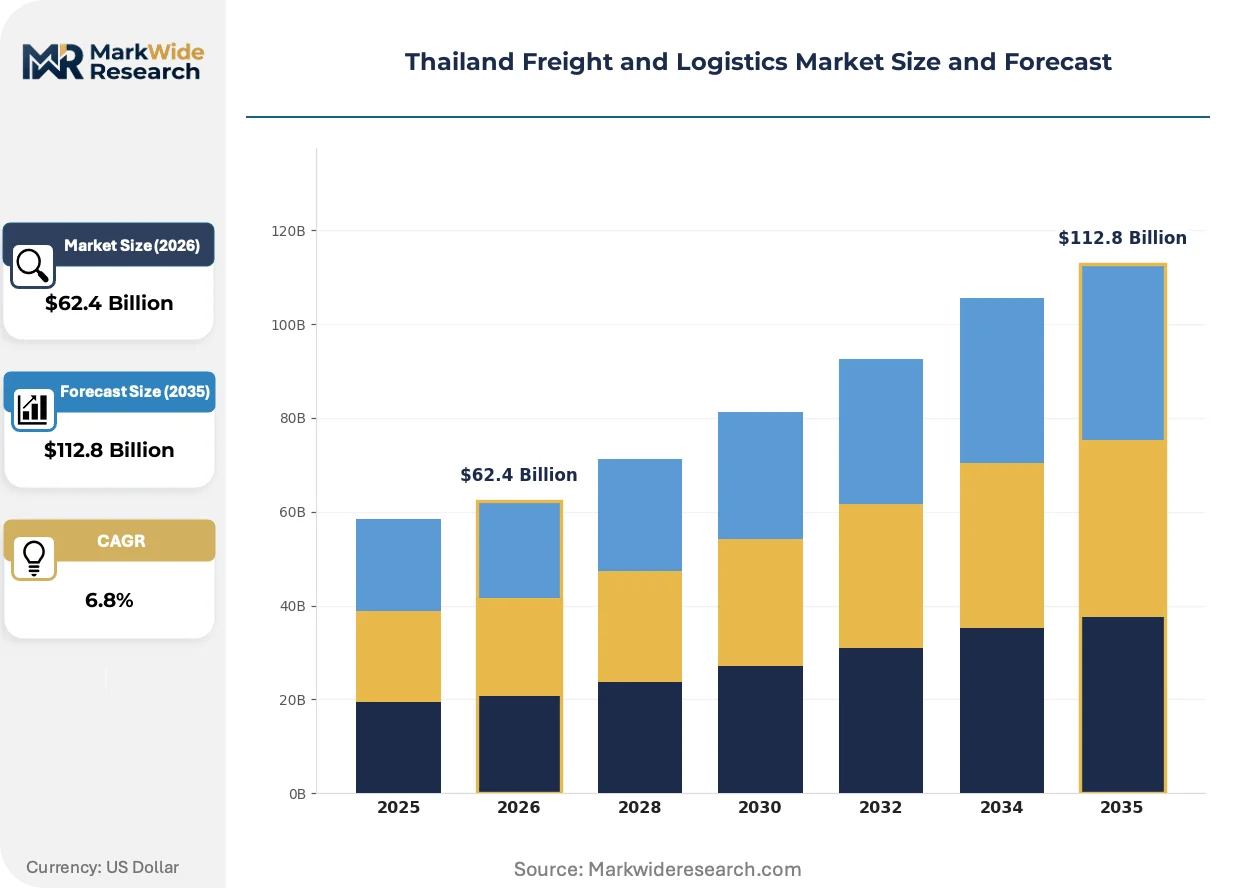
Eastern Economic Corridor incentives are redrawing Thailand's freight geography by concentrating bonded warehousing and multimodal terminals in Rayong and Chonburi provinces, while BIMSTEC transport agreements open cross-border corridors toward Myanmar, Cambodia, and India.
Growth Catalysts
- Laem Chabang Port Expansion:Deep-water berth additions accommodate 24,000 TEU vessels, reducing transshipment reliance on Singapore for Thai automotive and electronics exports.
- National Single Window:Customs Department digitization compresses cross-border clearance times for ASEAN trade lanes, accelerating inventory velocity for just-in-time manufacturers.
- Cold Chain Infrastructure:Central Plains investment in pharmaceutical-grade warehousing at minus 25 degrees Celsius supports vaccine distribution and premium seafood exports to Japan and the European Union.
Market Restraints
- Diesel Price Volatility:Road transport dominates domestic volume, exposing fleet operators to refined petroleum cost swings that erode contract margins.
- Driver Hour Regulations:Department of Land Transport enforcement limits long-haul trucking economics, forcing cargo onto rail intermodal alternatives with lower frequency.
- Weight Limit Constraints:Axle load restrictions on Highway 7 and Route 331 reduce payload efficiency for containerized freight moving between Bangkok and Eastern Seaboard industrial zones.
Strategic Opportunities
- Chao Phraya River Waterway:Inland barge investment offers alternative freight corridors bypassing road congestion for agricultural commodities moving from Central Plains to Bangkok port.
- Secondary City Last-Mile Density:E-commerce fulfillment radii expansion into Chiang Mai, Khon Kaen, and Hat Yai creates warehouse demand outside Greater Bangkok saturation.
- PLI-Aligned Electronics Logistics:Thailand's investment promotion incentives for semiconductor packaging attract specialized cold chain and hazardous materials handling services.
Industry Challenges
- Warehouse Management System Integration:Legacy ERP platforms at Thai 3PL providers resist real-time API connectivity with Shopee and Lazada marketplace order management systems.
- Refrigeration Technician Scarcity:Cold chain expansion outpaces vocational training output for ammonia and CO2 system maintenance, raising service response times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Freight and Logistics Market |
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Value-Added Services, Distribution End User: Manufacturing, Retail, E-commerce, Pharmaceuticals Transport Mode: Road, Rail, Air, Sea Technology: IoT, Blockchain, Automation, TMS |
| Companies Covered | DB Schenker, CMA CGM Group, Kerry Logistics Network Ltd., JWD Group, Thailand Post Co. Ltd., DHL Group, Nippon Express Holdings Inc., Flash Express, SCG Logistics Management Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Freight and Logistics Market Strategic Shifts
Digital freight platforms and automation are compressing planning cycles and labor dependency across Thai logistics operations, while sustainability mandates and e-commerce service-level expectations reshape capital allocation priorities.
Internet-of-Things sensors embedded in refrigerated containers are integrating real-time temperature monitoring with customs pre-clearance systems. Pharmaceutical exporters and fresh produce traders adopt these devices fastest, driven by Japanese buyer compliance requirements. This visibility layer is integrating insurance underwriting and supply chain finance products, collapsing the time between cargo discharge and working capital release.
Thailand's National Single Window initiative, administered by the Customs Department, mandates electronic submission of 52 trade documents through a unified portal. Manufacturing exporters in the automotive sector face the steepest adaptation curve due to complex rules-of-origin certification. The policy is compressing clearance times at Mae Sot and Nong Khai border crossings, redirecting some volume from sea-air transshipment through Singapore.
Same-day delivery promises from e-commerce marketplaces are compressing inventory positioning decisions for consumer electronics and fashion retailers. Third-party logistics providers respond by deploying micro-fulfillment nodes within 15-kilometer radii of Bangkok's outer ring road. This density race is most visible in Nonthaburi and Samut Prakan provinces, where land costs still permit last-mile sorting facilities at viable rent levels.
Thailand Freight and Logistics Market Segmentation
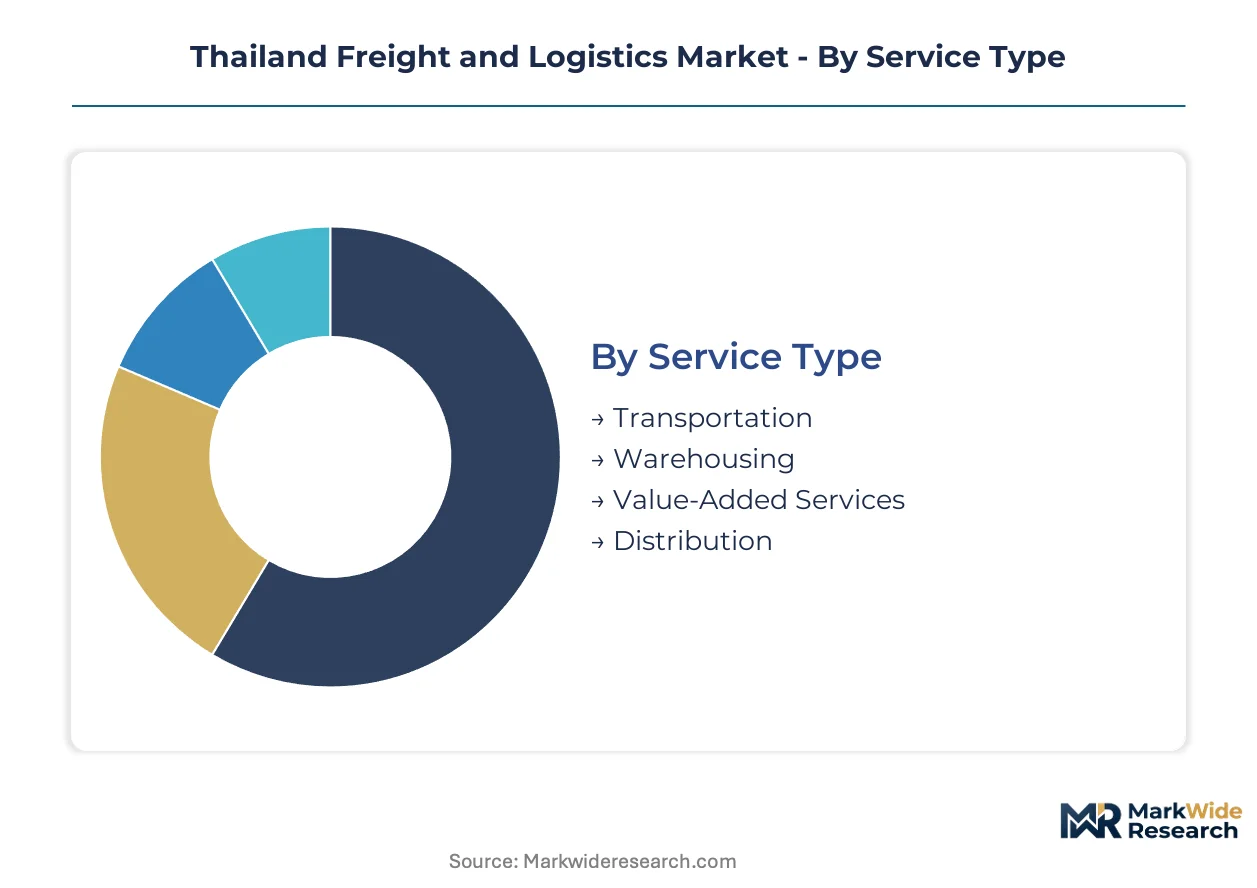
Thailand's freight and logistics market fragments across service capabilities, customer verticals, and infrastructure technologies. Segmentation reveals where capital concentrates and which regulatory burdens shape competitive positioning across the Eastern Economic Corridor and Greater Bangkok.
Service Type:
Transportation services face Department of Land Transport weight limit enforcement, while warehousing operators navigate bonded zone approvals from the Customs Department.
- Transportation:Road freight dominates domestic volume through Highway 7 and Route 331 corridors connecting Bangkok to Rayong and Chonburi industrial zones. Diesel price volatility erodes fleet operator margins on long-haul contracts to the Eastern Seaboard.
- Warehousing:Bonded facilities near Laem Chabang port absorb the fastest capital deployment as e-commerce fulfillment demands same-day delivery radii. Customs Department certification for duty suspension creates entry barriers for new entrants.
- Value-Added Services:Customs brokerage and inventory financing command superior margins than pure transport contracting under Thailand's National Single Window digitization.
- Distribution:Last-mile density in secondary cities requires micro-fulfillment nodes within 15-kilometer radii of urban centers.
Transportation sits at the top of the volume ranking, with Warehousing climbing the fastest.
End User:
Customer verticals impose distinct cold chain and hazardous materials compliance requirements on logistics providers.
- Manufacturing:Automotive and electronics exporters from the Eastern Seaboard demand just-in-time inventory velocity with rules-of-origin certification complexity.
- Retail:Fashion and consumer goods distributors compress inventory positioning decisions under same-day delivery pressure from marketplace competitors.
- E-commerce:Shopee and Lazada fulfillment requirements drive warehouse management system API integration investments across Thai 3PL providers.
- Pharmaceuticals:Vaccine distribution and temperature-sensitive biologics require minus 25 degrees Celsius warehousing with real-time IoT monitoring for Japanese buyer compliance.
Manufacturing anchors current revenue concentration, though E-commerce expands most quickly.
Transport Mode:
Infrastructure economics and regulatory enforcement reshape modal split decisions across Thai freight corridors.
- Road:Highway networks enable door-to-door flexibility but face driver hour regulation constraints and axle load restrictions on key corridors.
- Rail:Intermodal alternatives gain cargo as Department of Land Transport enforcement limits long-haul trucking economics, though frequency remains lower than road.
- Air:Express parcels and high-value electronics rely on Don Mueang and Suvarnabhumi cargo terminals for regional ASEAN distribution.
- Sea:Laem Chabang deep-water berths accommodating 24,000 TEU vessels reduce transshipment reliance on Singapore for automotive and electronics exports.
Road transport maintains volume leadership, while Rail intermodal gains share fastest.
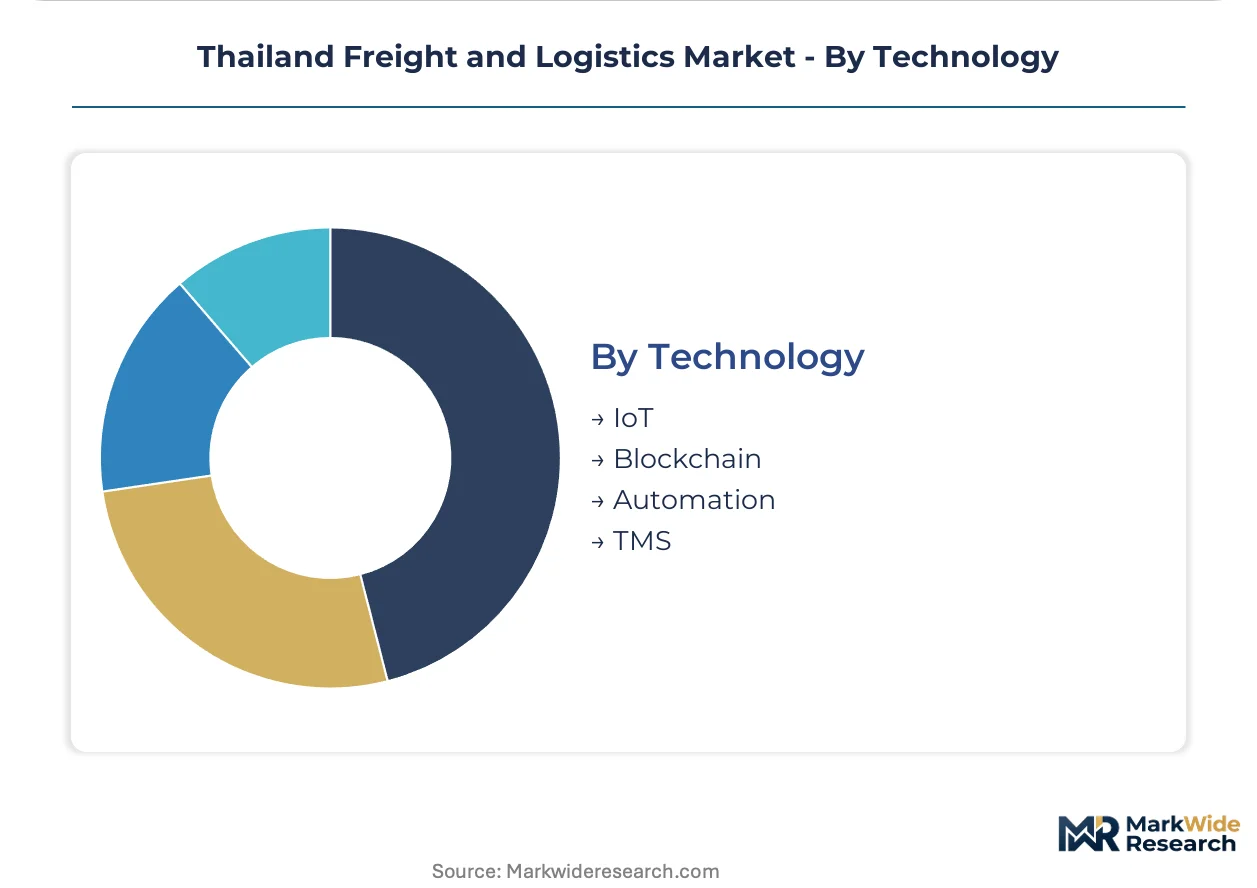
Technology:
Digital infrastructure investments separate integrated logistics providers from commodity freight operators in competitive positioning.
- IoT:Refrigerated container sensors integrate temperature monitoring with customs pre-clearance systems for pharmaceutical and fresh produce exporters.
- Blockchain:Trade document verification pilots target rules-of-origin certification complexity for automotive sector exporters.
- Automation:Micro-fulfillment nodes deploy automated sorting to compress last-mile labor dependency in Nonthaburi and Samut Prakan provinces.
- TMS:Transport management systems optimize fleet routing against diesel price volatility and weight limit constraints on containerized freight corridors.
IoT adoption leads current technology deployment, with Automation showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled logistics workforce clusters concentrate in Greater Bangkok and the Eastern Seaboard, anchoring Thailand's freight infrastructure development. Regional freight corridors radiate from these hubs toward border crossings and secondary urban centers. Provincial investment incentives redirect capital toward underdeveloped logistics nodes.
Greater Bangkok
E-commerce fulfillment demand drives micro-warehouse deployment within 15-kilometer delivery radii of the outer ring road. The Department of Land Transport enforces driver hour regulations that constrain last-mile fleet scheduling. Nonthaburi and Samut Prakan provinces absorb the fastest capital deployment for automated sorting facilities serving Shopee and Lazada order volumes.
Eastern Seaboard
Automotive and electronics exporters from Rayong and Chonburi industrial zones demand just-in-time inventory velocity with customs pre-clearance integration. Eastern Economic Corridor incentives from the Board of Investment concentrate bonded warehousing and multimodal terminals near Laem Chabang port. Deep-water berth expansions accommodating 24,000 TEU vessels reduce transshipment reliance on Singapore for Thai manufacturing exports.
Central Plains
Pharmaceutical-grade cold chain investment at minus 25 degrees Celsius supports vaccine distribution and premium seafood exports to Japanese and European Union buyers. The National Single Window initiative compresses customs clearance times for agricultural commodities moving through Bangkok port. Ayutthaya and Pathum Thani provinces host temperature-controlled warehousing clusters serving Central Plains agricultural processing.
Northern Region
Cross-border freight corridors toward Myanmar and Laos redirect volume from traditional sea-air transshipment routes. BIMSTEC transport agreements facilitate road-rail intermodal connections at Mae Sot and Chiang Rai border checkpoints. Chiang Mai anchors last-mile density expansion as e-commerce fulfillment radii extend beyond Greater Bangkok saturation.
Northeastern Region
Rail intermodal alternatives gain cargo share as driver hour enforcement limits long-haul trucking economics on Highway 2 and Route 231. The Customs Department digitizes cross-border documentation for ASEAN trade lanes at Nong Khai and Nakhon Phanom crossings. Khon Kaen emerges as a secondary distribution node for e-commerce fulfillment into Laos and Cambodia border provinces.
Thailand Freight and Logistics Market Competitive Environment
Top-tier vendors anchor integrated logistics networks spanning multimodal corridors and bonded warehousing, while mid-tier operators compete on lane-specific density and price. The market structure fragments across service archetypes: global forwarders with European network integration, ASEAN regional specialists with port-adjacent capacity, and domestic last-mile disruptors with secondary city coverage. Strategic moves concentrate on warehouse automation deployment and customs brokerage capability acquisition.
Among global forwarders operating in Thailand, DB Schenker and DHL Group exemplify the premium integrated tier with cross-border network leverage. Kerry Logistics Network Ltd. occupies a position within the ASEAN regional specialist archetype, anchoring hub operations through bonded capacity near Laem Chabang. Flash Express represents the domestic disruptor category with aggressive last-mile density expansion. CMA CGM Group and Nippon Express Holdings Inc. sit within diversified transport operator segments serving maritime and contract logistics verticals respectively.
| Leading Market Players |
|---|
| DB Schenker |
| CMA CGM Group |
| Kerry Logistics Network Ltd. |
| JWD Group |
| Thailand Post Co. Ltd. |
| DHL Group |
| Nippon Express Holdings Inc. |
| Flash Express |
| SCG Logistics Management Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap logistics operators across Thailand's Eastern Seaboard maintain pricing discipline through bonded warehousing scarcity near Laem Chabang port, while diesel cost pass-through clauses in long-haul contracts protect margins against refined petroleum volatility. Their concentrated ownership structures enable rapid capacity reallocation between automotive just-in-time lanes and e-commerce fulfillment nodes without quarterly earnings pressure.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes integrated logistics premiums from commodity freight rates. Three-tier pricing structure across premium, standard, and economy levels reflects customs brokerage sophistication and cold chain certification grade. Cost compression in standard-tier road freight is intensifying because Flash Express density investments compress per-parcel economics in secondary cities. Small manufacturing exporters exhibit highest price sensitivity, while Japanese pharmaceutical buyers accept premium rates for minus 25 degrees Celsius compliance.
Supply Chain Analysis
Thailand's domestic-content mandates under Eastern Economic Corridor incentives reshape sourcing toward Rayong and Chonburi bonded zone developers. Fleet operators draw from Chinese commercial vehicle imports, Japanese refrigeration equipment, and domestic chassis assembly. Single-source vulnerability concentrates in ammonia-based cooling systems for pharmaceutical warehousing. Distribution runs through Laem Chabang deep-water terminals, Bangkok micro-fulfillment radii, and Mae Sot cross-border corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's freight and logistics market operates as a stable compounder, with e-commerce fulfillment demand providing steady volume expansion regardless of manufacturing export cyclicality.
For Market Incumbents: To counter Flash Express last-mile density expansion, Kerry Logistics Network Ltd. and DB Schenker should deepen bonded warehouse automation in Nonthaburi and Samut Prakan provinces. Customs brokerage capability acquisition under National Single Window digitization creates defensive moats against regional ASEAN specialists. For New Entrants and Emerging Players: Digital freight platforms offer the lowest customer acquisition cost route into Thailand's fragmented long-haul trucking segment. Secondary city cold chain infrastructure in Khon Kaen and Chiang Mai presents the most penetrable white space, with API-first warehouse management systems enabling rapid Shopee and Lazada integration. For Investors and Strategic Acquirers: Valuations sit cheapest among family-owned cold chain operators lacking electronic data interchange capabilities. Long-term viability hinges on automation deployment pace rather than fleet scale. The signal to watch is BIMSTEC corridor volume share shifting from sea-air transshipment toward direct road-rail connections.| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehouse Automation Deployment | Compresses labor dependency in Nonthaburi sorting facilities serving Lazada order volumes. |
| Cold Chain Certification Investment | Enables Japanese pharmaceutical buyer compliance for Central Plains vaccine distribution. |
| API Integration with Marketplace Platforms | Resolves legacy ERP connectivity gaps blocking real-time Shopee order management. |
| Chao Phraya River Barge Fleet Expansion | Bypasses Highway 7 weight limit constraints for agricultural commodities from Ayutthaya. |
| Rail Intermodal Terminal Development | Captures cargo displaced by Department of Land Transport driver hour enforcement. |
Study Parameters
Bottom-up e-commerce fulfillment modeling reconciled against top-down bonded warehouse capacity tracking forms the analytical core of this study. Primary interviews with fleet operators, Customs Department officials, 3PL procurement managers, and cold chain facility engineers combined with secondary validation from Thailand Board of Investment filings, Department of Land Transport enforcement records, Laem Chabang Port Authority throughput data, and BIMSTEC trade corridor statistics. Triangulation between demand-side order volume projections and supply-side infrastructure investment pipelines ensures consistency.
Input-output matrices map transportation, warehousing, value-added services, and distribution segments across service type, end user, transport mode, and technology dimensions throughout the forecast period. CAGRs derive from regression analysis of historical infrastructure deployment rates against manufacturing export and e-commerce penetration trajectories. Forecast inputs include National Single Window clearance time compression, Eastern Economic Corridor incentive utilization rates, and diesel price elasticity coefficients for road freight contract renegotiation.
The model assumes a particular technology adoption path; alternative pathways for warehouse management system API standardization would alter the outlook for 3PL competitive positioning. Forecasts reflect assumptions regarding BIMSTEC corridor maturation, cold chain technician training output, and Laem Chabang berth expansion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
South Korea International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
LAMEA Last Mile Delivery Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
US Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
Nigeria Freight and Logistics Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Brazil Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
Australia Mining Logistics Market