
 Remanufacturing and Core Returns Logistics Management Market | 2026-2036
Remanufacturing and Core Returns Logistics Management Market Size, Share, and Industry Trends Forecast 2026-2036
Remanufacturing and Core Returns Logistics Management Market Insights
OEM buyer concentration in the automotive sector is hardening as vehicle assemblers consolidate supplier bases and demand integrated core recovery programs. Deutsche Post DHL anchors European remanufacturing logistics through dedicated reverse supply networks. FedEx competes on North American density with specialized handling protocols for automotive cores. Kuehne + Nagel differentiates via pharmaceutical-grade traceability systems adapted for industrial part authentication.
Remanufacturing and core returns logistics management encompasses the systematic collection, inspection, transportation, and disposition of used products and components intended for restoration to original specifications, typically requiring serialized tracking, condition grading protocols, and contamination-controlled handling to preserve material integrity for second-life industrial use. Reverse logistics services capture the largest value pool given the complexity of multi-node collection networks, while AI Analytics represents the fastest-expanding technology segment as predictive algorithms optimize core availability forecasting and reduce inventory carrying costs for OEMs.
The EPA regulates hazardous material handling in core returns through RCRA manifest requirements, while the EU F-Gas Regulation and REACH framework impose substance restrictions on recovered components entering remanufacturing streams. OEMs and logistics providers must align compliance architectures across these jurisdictions to avoid market access friction. Stakeholders should monitor how carbon border adjustment mechanisms reshape the economics of cross-border core movements between production and remanufacturing facilities.
Market Dynamics
OEM consolidation in automotive supply chains is compressing vendor counts while mandating integrated core recovery programs, forcing logistics providers to build dedicated reverse networks capable of serialized tracking and contamination-controlled handling.
Growth Catalysts
- EU Green Deal waste diversion mandates:Binding targets for member states accelerate investment in circular economy infrastructure, directly expanding remanufacturing facility capacity across Germany, France, and Italy.
- Automotive OEM core security programs:Vehicle assemblers are internalizing reverse logistics to lock in reusable component supply, creating dedicated collection networks for engines, transmissions, and electronic modules.
- AI-driven core availability forecasting:Predictive algorithms reduce inventory carrying costs by synchronizing collection timing with remanufacturing line schedules, improving asset utilization rates.
Market Restraints
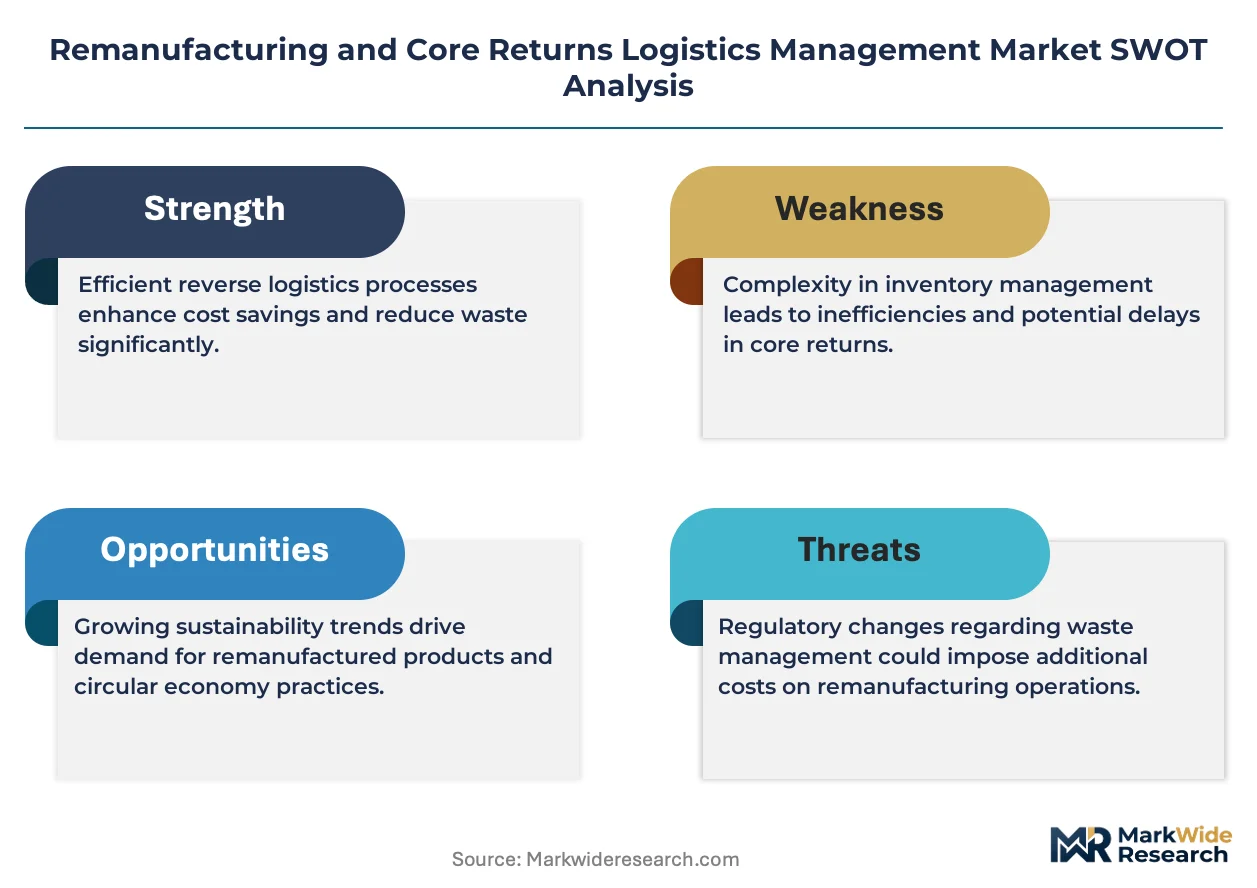
- Specialized handling infrastructure costs:Contamination-controlled transport and inspection facilities require capital intensity that excludes smaller logistics operators from core recovery contracts.
- REACH substance restriction complexity:Recovered components entering EU remanufacturing streams face cascading compliance verification for restricted chemicals, creating documentation bottlenecks.
- Geographic concentration of remanufacturing capacity:Industrial clusters around Stuttgart and Wolfsburg create collection radius constraints, inflating last-mile costs for dispersed core sources.
Strategic Opportunities
- Pharmaceutical-grade traceability adaptation:Industrial part authentication systems borrowed from cold-chain pharma logistics enable premium pricing for certified remanufactured components.
- Carbon border adjustment mechanism positioning:Cross-border core movements between production and remanufacturing facilities gain competitive advantage through embedded emissions accounting.
- Battery core recovery from electric vehicles:End-of-life lithium-ion packs from Germany's expanding EV fleet create new collection and disassembly service demand.
Industry Challenges
- Serialized tracking system integration:Legacy ERP platforms at tier-2 suppliers lack API compatibility with OEM core management portals, requiring middleware development.
- Condition grading standardization gaps:Absence of unified protocols for component wear assessment creates disputes between collectors and remanufacturers over core valuation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remanufacturing and Core Returns Logistics Management Market |
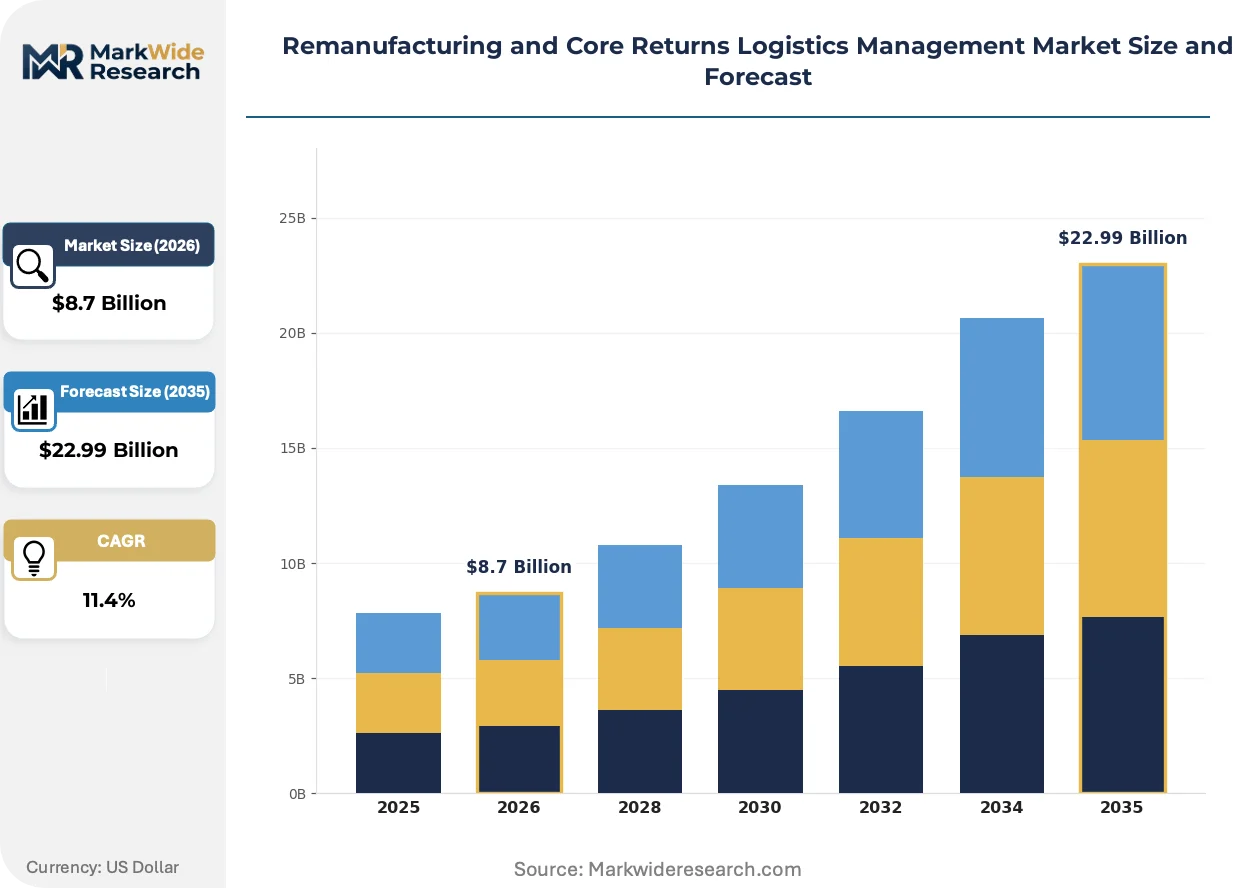
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Reverse Logistics, Repair Management, Core Collection, Quality Inspection, Refurbishment, Recycling Technology: IoT Tracking, Blockchain, RFID, AI Analytics, Cloud Platforms, Automation End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Distribution Channel: Third-Party Logistics, Direct Shipping, Warehousing, Hub & Spoke, Cross-Docking |
| Companies Covered | Deutsche Post DHL, FedEx, United Parcel Service, C.H. Robinson Worldwide, Yusen Logistics, DB Schenker, Kuehne + Nagel, CEVA Logistics, XPO Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remanufacturing and Core Returns Logistics Management Market Trends and Innovations
Digital thread technologies are redefining how used components retain value through multiple life cycles, with authentication and tracking systems becoming as critical as physical transport infrastructure.
Blockchain-enabled provenance tracking is electrifying trust mechanisms in secondary component markets. Automotive OEMs in Germany and the United States are deploying distributed ledger systems to record chain-of-custody for high-value cores. The technology is electrifying price transparency by eliminating information asymmetry between collectors, graders, and remanufacturers.
REACH substance restriction enforcement is tightening material flow documentation requirements. Industrial remanufacturers must now certify recovered components against SVHC candidate lists before re-entry to production streams. German automotive suppliers are responding by embedding chemical composition data directly into component digital passports.
After-sales service unbundling is fragmenting traditional OEM-dealer core return relationships. Independent repair networks in France and Italy are establishing direct collection contracts with specialized logistics providers, bypassing franchised distribution channels. This shift is most visible in commercial vehicle powertrain segments where fleet operators prioritize turnaround speed over brand loyalty.
Remanufacturing and Core Returns Logistics Management Market Segmentation
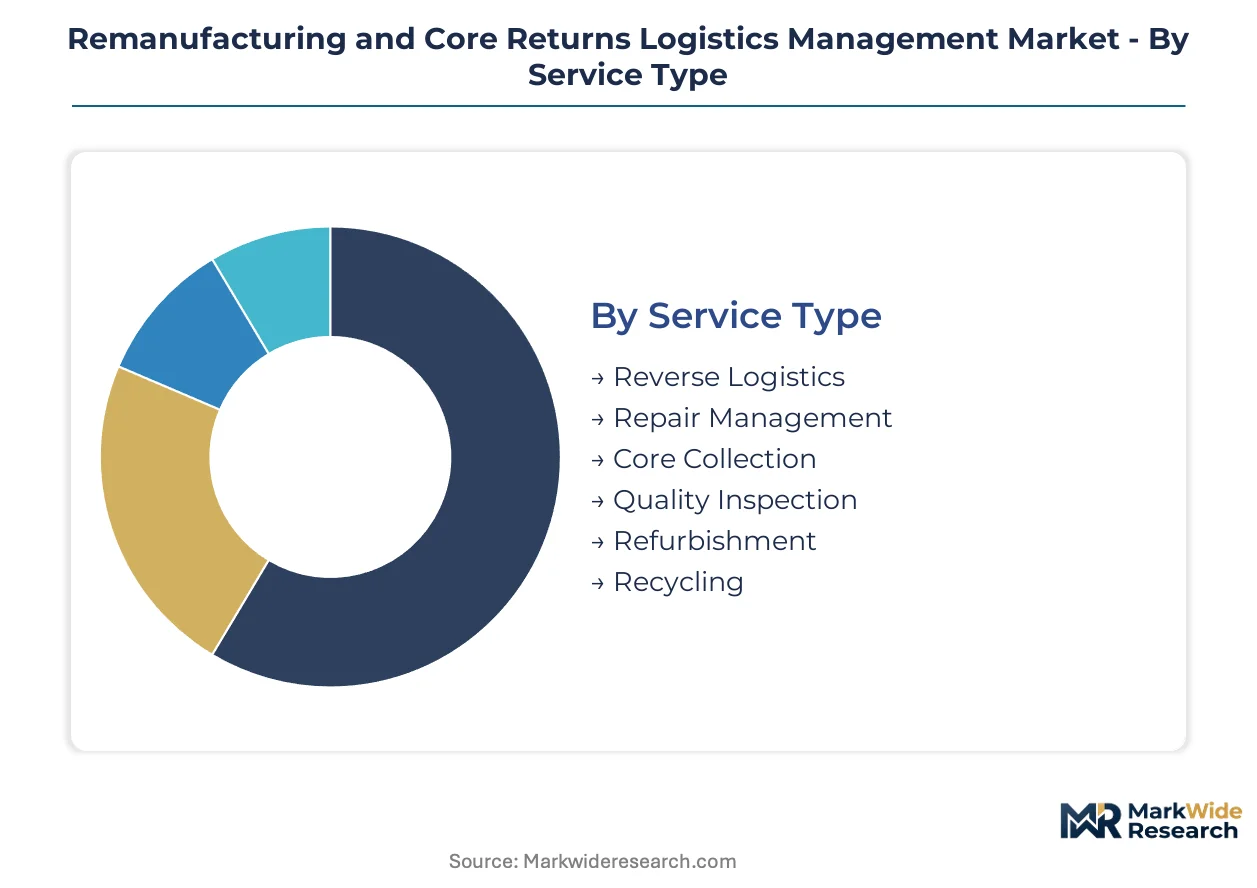
Segmentation in remanufacturing logistics reveals how service specialization, technology maturity, and channel architecture determine competitive positioning. Each category exposes distinct margin structures and capital requirements that shape provider strategies across automotive and industrial verticals.
Service Type:
Customization intensity varies sharply across this spectrum, from standardized transportation to highly protocol-driven inspection and refurbishment workflows.
- Reverse Logistics:Multi-node collection networks coordinate transportation from dispersed return points to centralized grading facilities. Demand concentrates among German vehicle assemblers securing engine and transmission cores, driven by EU Green Deal waste diversion mandates requiring documented chain-of-custody.
- Quality Inspection:Condition grading protocols assess wear patterns, contamination levels, and remanufacturability against OEM specifications. Stuttgart-based industrial clusters invest heavily here to reduce disputes over core valuation and accelerate processing throughput.
- Repair Management:Warranty recovery and field failure coordination for dealer networks.
- Core Collection:Serialized pickup scheduling synchronized with remanufacturing line demand.
- Refurbishment:Component-level restoration to original equipment specifications.
- Recycling:Material recovery for non-remanufacturable cores under REACH substance restrictions.
Most installed capacity flows through Reverse Logistics. Expansion is steepest in Quality Inspection.
Technology:
Adoption maturity separates legacy barcode-dependent operations from digitally native platforms commanding premium pricing.
- AI Analytics:Predictive algorithms forecast core availability by correlating vehicle age distributions, warranty expiration curves, and seasonal failure patterns. Tier-1 suppliers in Wolfsburg deploy these systems to synchronize collection timing with production schedules, cutting inventory carrying costs.
- Blockchain:Distributed ledger systems record immutable chain-of-custody for high-value automotive cores. German OEMs leverage this technology to eliminate information asymmetry between collectors and remanufacturers, tightening price transparency in secondary component markets.
- IoT Tracking:Sensor-enabled containers monitor location, shock, and temperature conditions during transport.
- RFID:Automated identification for high-volume, lower-value component streams.
- Cloud Platforms:Centralized data architectures integrating ERP systems across fragmented supplier bases.
- Automation:Robotic sorting and disassembly for standardized core categories.
Cloud Platforms absorb the largest share of current technology spending. Blockchain is gaining share fastest among authentication-sensitive applications.
End User:
Procurement authority and volume scale create distinct service requirements across the automotive value chain.
- OEMs:Integrated core security programs internalizing reverse logistics to lock in reusable component supply. Vehicle assemblers mandate serialized tracking and contamination-controlled handling through dedicated collection networks for engines, transmissions, and electronic modules.
- Vehicle Assemblers:Just-in-time remanufacturing lines demanding precise core availability windows.
- Tier-1 Suppliers:Mid-volume operations balancing OEM compliance with cost efficiency.
- Aftermarket Providers:Independent repair networks establishing direct collection contracts, bypassing franchised distribution channels in France and Italy.
Vehicle Assemblers command the highest service premiums. Aftermarket Providers are expanding most quickly as service unbundling accelerates.
Distribution Channel:
Asset intensity and network density determine competitive viability across channel configurations.
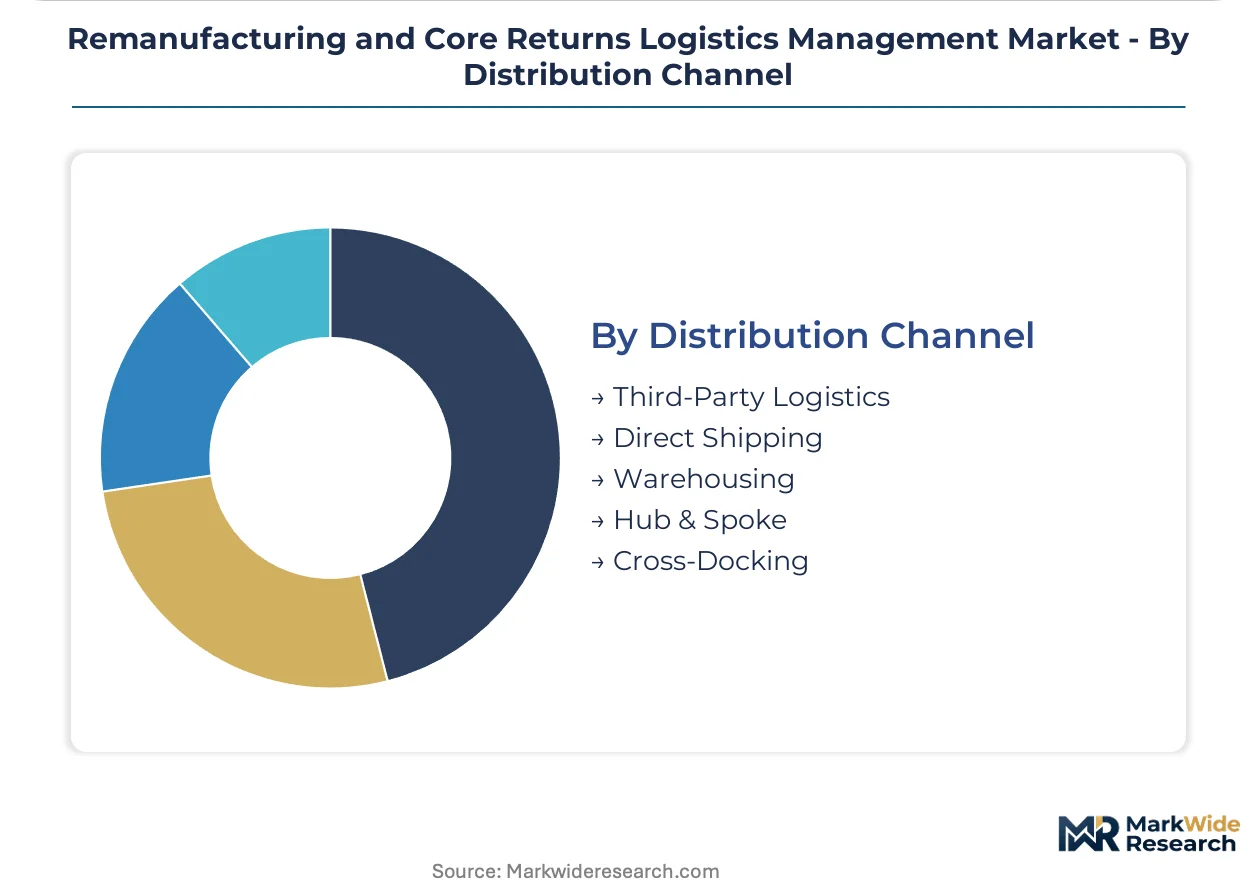
- Third-Party Logistics:Specialized providers like Deutsche Post DHL and FedEx operate dedicated reverse supply networks with contamination-controlled handling protocols. These operators capture value through multi-client density and standardized inspection facilities.
- Hub & Spoke:Consolidation points optimizing collection radius efficiency for geographically dispersed core sources.
- Direct Shipping:Point-to-point transport for high-value, time-sensitive components.
- Warehousing:Buffer inventory positioning against remanufacturing line volatility.
- Cross-Docking:Minimal-handling transfer for fast-turn core categories.
Third-Party Logistics dominates transaction volume. Hub & Spoke infrastructure is climbing the fastest as geographic concentration around Stuttgart and Wolfsburg creates collection radius constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates remanufacturing logistics infrastructure more densely than the United States, with Stuttgart and Wolfsburg anchoring specialized reverse supply networks that handle automotive core returns at industrial scale.
United States
Automotive OEMs operate dedicated core collection programs for engines and transmissions across Michigan and Ohio manufacturing corridors. The EPA enforces RCRA manifest requirements for hazardous material handling in returned components. Detroit-based logistics clusters coordinate multi-node reverse networks serving domestic vehicle assemblers.
Germany
Industrial remanufacturing clusters around Stuttgart and Wolfsburg drive specialized logistics investment for powertrain component recovery. The EU Green Deal imposes binding waste diversion targets that expand circular economy facility capacity. Baden-Württemberg hosts contamination-controlled handling infrastructure for serialized core tracking systems.
France
Independent repair networks establish direct collection contracts bypassing franchised distribution channels in commercial vehicle segments. REACH substance restrictions require SVHC verification for recovered components entering remanufacturing streams. Lyon-based logistics providers develop pharmaceutical-grade traceability adaptations for industrial part authentication.
China
Domestic EV fleet expansion generates end-of-life lithium-ion battery core recovery demand across Yangtze River Delta manufacturing zones. MIIT oversees standards for remanufactured automotive product certification under GB protocols. Shanghai logistics operators build dedicated reverse networks for electronic module collection and disassembly services.
Japan
Vehicle assemblers mandate just-in-time core availability windows for remanufacturing line synchronization. METI coordinates circular economy initiatives supporting component reuse in automotive supply chains. Nagoya-based industrial clusters invest in AI-driven forecasting systems correlating vehicle age distributions with collection timing optimization.
Remanufacturing and Core Returns Logistics Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across service tiers, creating a bifurcated structure where scale-driven operators capture volume contracts while niche providers command premiums for specialized handling protocols. The vendor base organizes around three strategic archetypes: integrated logistics conglomerates with dedicated reverse supply divisions, regional specialists offering contamination-controlled infrastructure, and technology-forward platforms deploying blockchain authentication systems. Competitive intensity centers on M&A activity consolidating mid-tier operators and strategic partnerships linking automotive OEMs with certified collection network providers.
Within the integrated logistics tier, Deutsche Post DHL anchors European remanufacturing logistics through dedicated reverse supply networks with serialized tracking capabilities. FedEx occupies a position among North American operators competing on density with specialized handling protocols for automotive cores. Kuehne + Nagel sits within the premium authentication segment, adapting pharmaceutical-grade traceability systems for industrial part verification in German automotive supply chains.
| Leading Market Players |
|---|
| Deutsche Post DHL |
| FedEx |
| United Parcel Service |
| C.H. Robinson Worldwide |
| Yusen Logistics |
| DB Schenker |
| Kuehne + Nagel |
| CEVA Logistics |
| XPO Logistics |
| Others |
Pricing and Supply Chain Analysis
Scrap metal price indices for aluminum and steel alloys cascade through remanufacturing logistics networks, compressing margins for collectors while amplifying price premiums for contamination-controlled handling tiers serving German automotive OEMs under EU Green Deal mandates.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors for standardized reverse logistics services, forcing incumbent providers toward value-added inspection protocols. Three-tier pricing structure across premium, standard, and economy levels separates certified pharmaceutical-grade traceability from basic transportation brokerage. Price differentiation hinges on serialization depth and REACH compliance documentation depth. Cost compression in economy tiers is intensifying because independent repair networks in France and Italy negotiate direct collection contracts bypassing franchised markups. Tier-1 suppliers exhibit highest price sensitivity due to OEM pass-through requirements, while vehicle assemblers absorb premium handling costs to secure core availability.
Supply Chain Analysis
Single-source vulnerability sits with specialized contamination-controlled container fleets concentrated in Baden-Württemberg and Lower Saxony. Geographic supply concentration clusters in Germany, the United States, and China, with each anchoring distinct automotive remanufacturing corridors. Raw material flows draw from end-of-life vehicle dismantlers, warranty return streams, and fleet operator direct contracts. Supply chain risk centers on REACH substance restriction documentation bottlenecks that stall core re-entry to production streams. Distribution runs through third-party logistics networks with hub-and-spoke consolidation points optimizing collection radius efficiency around Stuttgart and Wolfsburg industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Remanufacturing and Core Returns Logistics Management Market operates as a regulatory compounder where EU Green Deal waste diversion mandates create structural demand expansion for circular economy infrastructure.
For Market Incumbents: Hedge core collection network exposure by embedding chemical composition data into component digital passports before REACH SVHC candidate list expansions tighten compliance verification. Build backward integration into disassembly services to capture margin pools currently leaking to independent dismantlers. Deutsche Post DHL's dedicated reverse supply architecture demonstrates how serialized tracking capabilities defend contract renewals against technology-forward challengers deploying blockchain authentication systems. For New Entrants and Emerging Players: Independent repair networks in France and Italy represent the most penetrable channel partner type for bypassing franchised distribution relationships in commercial vehicle powertrain segments. Target battery core recovery from Germany's expanding EV fleet as a white-space service demand with minimal incumbent specialization. Pursue direct collection contracts with fleet operators prioritizing turnaround speed over brand loyalty, leveraging pharmaceutical-grade traceability adaptations as a certification wedge against established automotive logistics providers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier operators lack capital intensity for contamination-controlled infrastructure investments required by OEM core security programs. Long-term viability favors providers with embedded emissions accounting capabilities positioning for carbon border adjustment mechanism advantages in cross-border core movements. Acquisition target archetype: regional specialists with established grading protocols in Stuttgart or Wolfsburg industrial clusters. Signal to watch: API compatibility middleware development bridging legacy ERP platforms at tier-2 suppliers with OEM core management portals.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Authentication Deployment | Distributed ledger systems eliminate information asymmetry between collectors and remanufacturers in German automotive supply chains. |
| AI-Driven Forecasting Integration | Predictive algorithms at Wolfsburg tier-1 suppliers synchronize collection timing with production schedules, cutting inventory carrying costs. |
| Contamination-Controlled Infrastructure Expansion | Baden-Württemberg facilities with serialized tracking capabilities capture premium pricing from vehicle assemblers under EU Green Deal mandates. |
| Battery Core Recovery Service Launch | End-of-life lithium-ion pack collection addresses emerging demand from Germany's EV fleet expansion with limited incumbent specialization. |
| Pharmaceutical-Grade Traceability Adaptation | Lyon-based logistics providers leverage cold-chain authentication systems for industrial part verification, enabling premium component pricing. |
Research Methodology
Multiple input streams — structured interviews with reverse logistics directors, OEM procurement leads, and remanufacturing facility managers; secondary validation through EU regulatory filings, EPA RCRA documentation, and automotive production databases; plus customs trade data on core movement patterns — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured operational constraints in contamination-controlled handling protocols and serialized tracking system integration challenges. Secondary sources included REACH SVHC candidate list updates, EU Green Deal implementation timelines, and MIIT standards for remanufactured automotive product certification under GB protocols.
Historical volume trajectories were cross-referenced against expert panel assessments of OEM core security program expansion and AI analytics adoption curves across the analysis window. Segmentation dimensions modeled include service type specialization, technology maturity tier, end-user procurement authority, and distribution channel asset intensity. CAGRs were derived from correlating vehicle age distributions with warranty expiration curves and seasonal failure patterns. Industry-specific forecast inputs encompassed EV fleet penetration rates affecting battery core recovery demand and carbon border adjustment mechanism implementation timelines reshaping cross-border logistics economics.
Revisions become necessary when REACH substance restriction enforcement tightens material flow documentation requirements beyond current SVHC verification protocols, or when carbon border adjustment mechanisms alter the economics of cross-border core movements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Air Freight Market
Logistics and Shipping
Singapore Shipping Agency Services Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Asia Pacific Domestic Courier Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
Latin America Cold Chain Logistics Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
North America Refrigerated Container Shipping Market
Logistics and Shipping
Asia-Pacific Logistics Automation Market
Logistics and Shipping
China Digital Freight Forwarding Market
Logistics and Shipping
Straddle Carrier Market
Logistics and Shipping
Digital Logistics Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
Sea Freight Forwarding Market
Logistics and Shipping
Mexico Logistics Market
Logistics and Shipping
Oman Third-Party Logistics (3PL) Market