
 China Project Logistics Market | 2026-2036
China Project Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
China Project Logistics Market Outlook
State-owned energy developers is reorganizing procurement toward integrated turnkey logistics for offshore wind and petrochemical complexes. COSCO Shipping Logistics leverages its port terminal network to control heavy-lift berthing windows along China's eastern seaboard. CJ Smart Cargo anchors its position through specialized vessel chartering for abnormal loads. Zhenhua Logistics Group dominates inland project corridors with self-propelled modular transporter fleets.
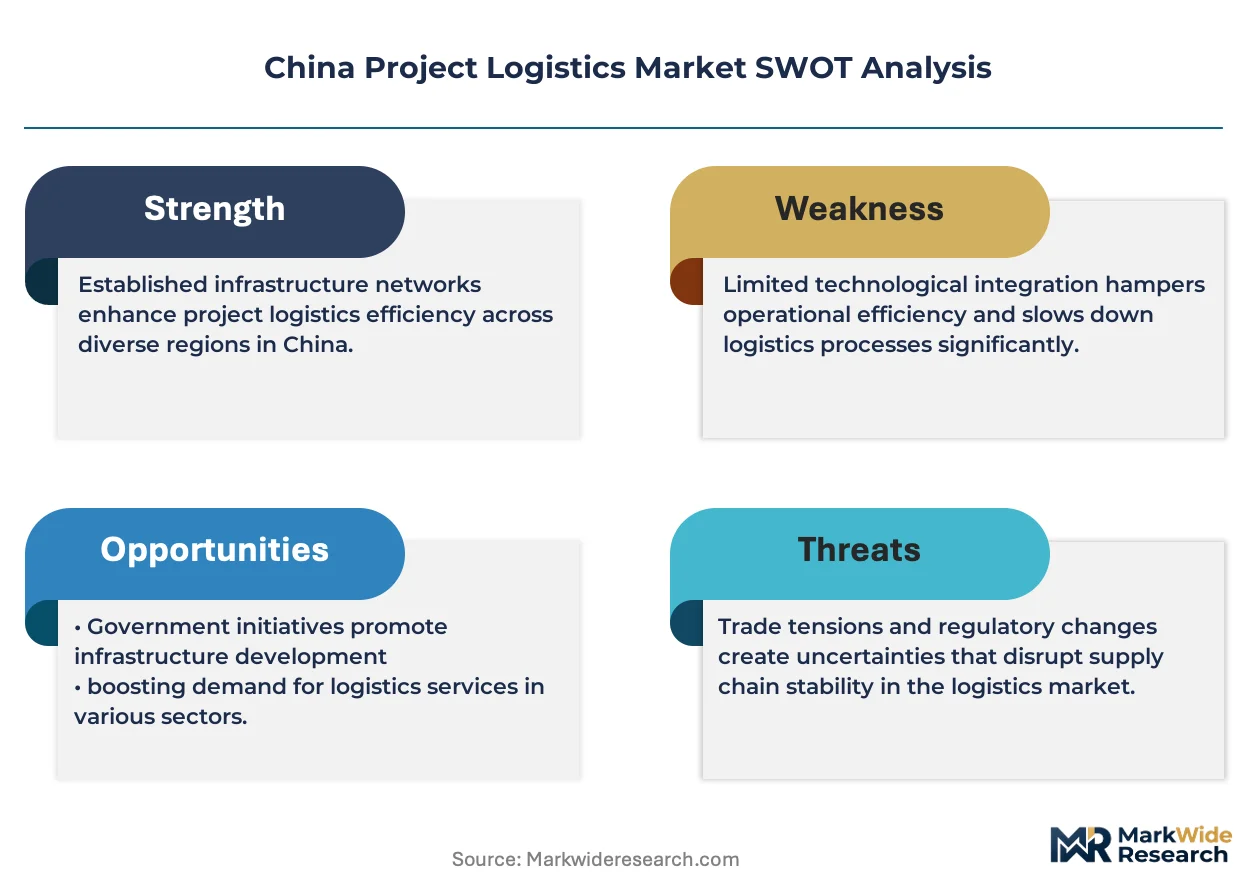
China project logistics encompasses the planning, engineering, and execution of oversized, overweight, or time-critical cargo movements requiring route surveys, temporary infrastructure modifications, and multi-modal coordination. Typical assignments involve single pieces exceeding 300 metric tons or dimensional loads surpassing standard container profiles, serving capital-intensive industries where construction schedules tie directly to facility commissioning timelines. Freight forwarding and project cargo services capture the dominant value pools, while rail transport mode segments gain traction on corridor density between western mining basins and coastal processing zones. Door-to-door delivery models command premium pricing through single-accountability structures, though site-to-site arrangements prevail in energy verticals where receiver engineering teams manage final positioning.
MIIT enforces GB standards for heavy-haul vehicle configurations, while SAMR monitors cross-provincial transport permit harmonization under unified national licensing frameworks. These regulatory layers shape fleet investment cycles and dictate which operators qualify for nuclear and aerospace logistics contracts. Stakeholders must track how NMPA-equivalent certification requirements for specialized equipment propagate across provincial enforcement regimes.
Market Dynamics
State-owned energy conglomerates are reorganizing procurement patterns around modular construction and offshore wind installation, compressing traditional freight forwarding margins while elevating engineering-integrated logistics contracts.
Growth Catalysts
- MIIT dual carbon mandates:Binding emissions targets force power developers to accelerate offshore wind farm deployment, generating demand for heavy-lift marine logistics and specialized vessel chartering.
- Yangtze River Delta clustering:Shanghai-Ningbo port infrastructure concentrates oversized cargo flows, creating density economies for abnormal load operators serving petrochemical and nuclear construction sites.
- Modular construction methods:Prefabricated process modules reduce on-site assembly time, requiring precision heavy-haul coordination from manufacturing basins to coastal installation zones.
Market Restraints
- GB standards compliance costs:MIIT certification timelines for self-propelled modular transporters extend fleet procurement cycles, freezing capital in regulatory review periods.
- Cross-provincial permit fragmentation:SAMR harmonization efforts remain incomplete, forcing operators to navigate disparate provincial licensing frameworks for single corridor movements.
- Specialized vessel supply concentration:Heavy-lift shipping capacity concentrates among limited operators, creating berthing window scarcity during seasonal installation windows.
Strategic Opportunities
- Western mining-to-coast rail corridors:Xinjiang and Inner Mongolia mineral processing expansion creates demand for multi-modal heavy-haul integration between inland extraction sites and coastal refining complexes.
- Third-party engineering logistics bundling:EPC contractors seek single-accountability partners for route surveying, temporary bridge construction, and final positioning, displacing fragmented forwarding arrangements.
- GB standard export alignment:Belt and Road infrastructure projects in Central Asia and Southeast Asia create demand for Chinese-certified heavy-lift equipment and operating protocols.
Industry Challenges
- Heavy-haul operator certification gaps:Nuclear and aerospace logistics contracts require specialized driver credentials that outpace vocational training program output.
- Legacy port infrastructure retrofitting:Eastern seaboard terminals require quay reinforcement and crane upgrades to accommodate next-generation offshore wind component dimensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Project Logistics Market |
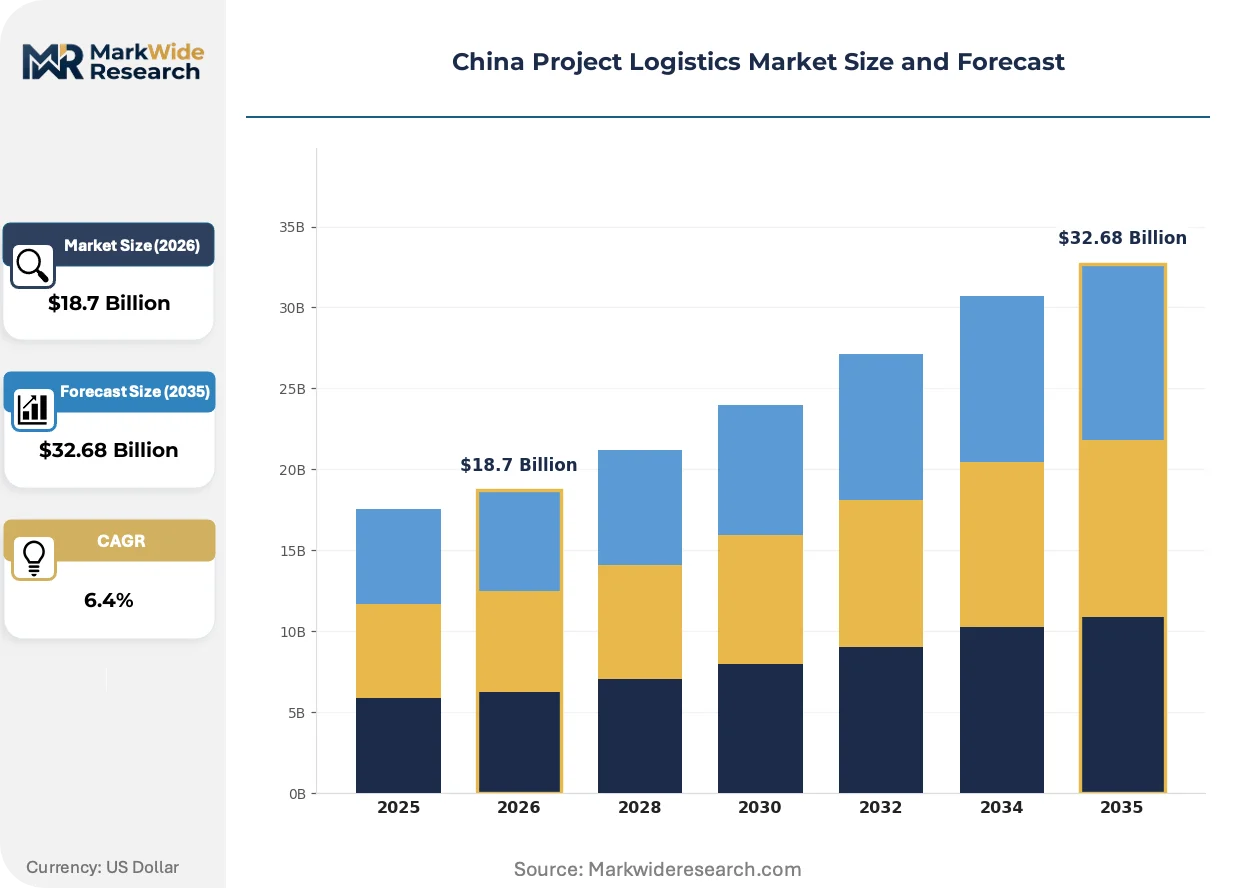
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Project Cargo, Customs Clearance, Warehousing Transport Mode: Road, Rail, Air, Sea Industry Vertical: Construction, Energy, Mining, Manufacturing Delivery Model: Door-to-Door, Port-to-Port, Site-to-Site, On-Demand |
| Companies Covered | Kuehne + Nagel, CJ Smart Cargo, COSCO Shipping Logistics, Zhenhua Logistics Group, InterMax Logistics Solution, Sinotrans, Kerry Logistics Network, ASB Logistics, DSV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Project Logistics Market Strategic Shifts
Digital route optimization platforms and autonomous heavy-haul coordination systems are compressing planning cycles for abnormal load movements, while regulatory pressure on emissions intensifies equipment electrification programs.
Self-propelled modular transporter technology is bifurcating fleet strategies across the sector. State-owned logistics operators deploy 500+ axle-line fleets for refinery module transport, while regional specialists acquire compact 48-96 axle configurations for urban infrastructure jobs. This technology divergence is compressing mid-scale operators into narrow geographic niches or forcing alliance structures to access larger project tenders.
MIIT enforcement of updated GB standards for heavy-lift vehicle configurations is tightening equipment certification timelines. Manufacturers must submit revised braking and stability documentation before provincial operating permits issue. Nuclear logistics contracts face the strictest scrutiny, with SAMR cross-provincial harmonization efforts reducing but not eliminating documentation redundancy between coastal and inland jurisdictions.
Engineering-procurement-construction contractors now consolidate logistics accountability under single-source contracts rather than fragmenting across forwarding, heavy-haul, and marine specialists. This bundling displaces traditional freight margins with premium pricing for integrated risk assumption. Offshore wind developers in Jiangsu and Fujian provinces most visibly drive this shift, where turbine installation schedules tolerate minimal interface friction between transport and positioning phases.
China Project Logistics Market Segmentation
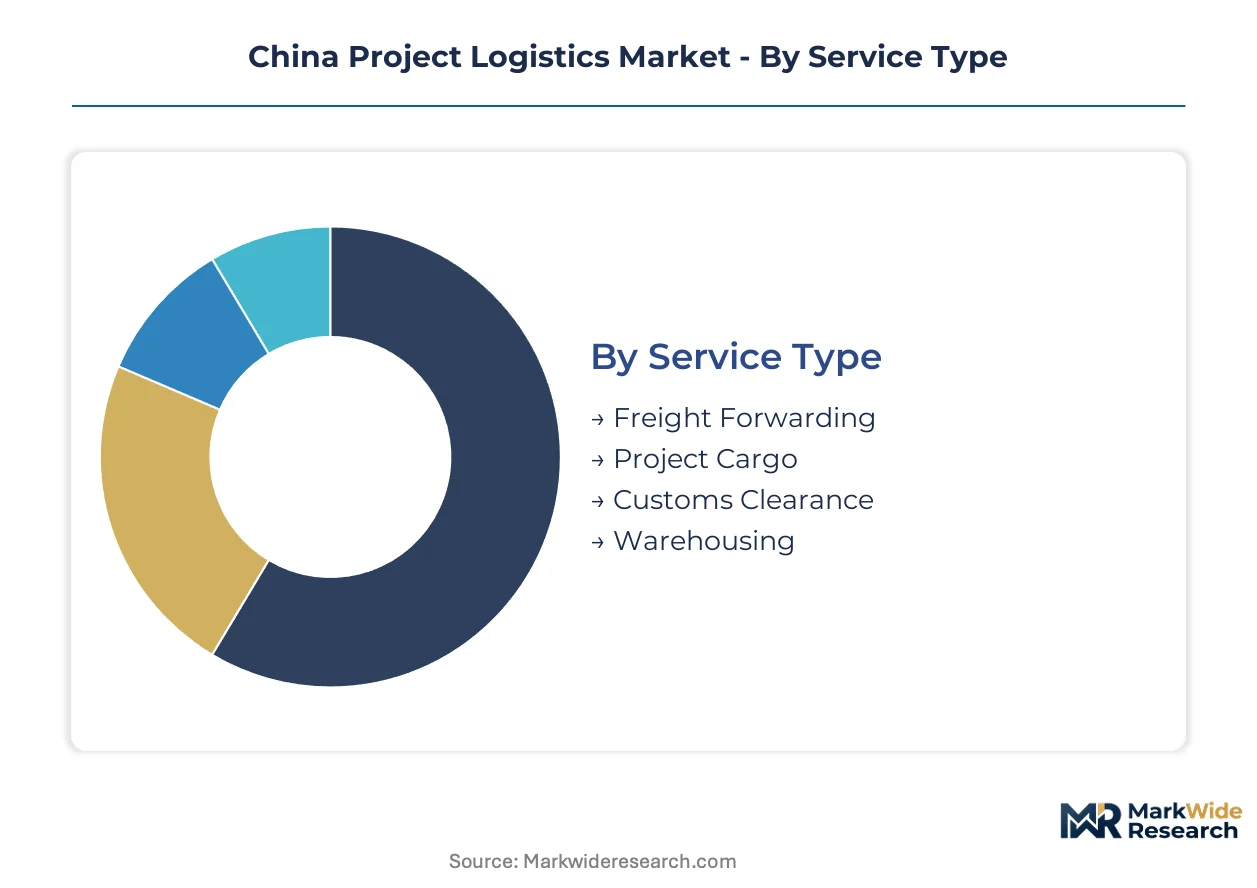
Project logistics in China fragments across service capabilities, transport infrastructure, and contracting structures that determine which operators capture value in specific cargo corridors. Understanding these divisions reveals where MIIT certification requirements and SAMR permitting frameworks create competitive moats.
Service Type:
Freight forwarding and project cargo services flow through state-owned port networks and specialized heavy-lift terminals, while customs clearance and warehousing attach to corridor density in the Yangtze River Delta.
- Freight Forwarding:Orchestrates multi-modal documentation, permit acquisition, and carrier contracting for abnormal loads. Demand concentrates with COSCO Shipping Logistics and CJ Smart Cargo along eastern seaboard heavy-lift berthing windows where MIIT dual carbon mandates accelerate offshore wind component movements.
- Project Cargo:Encompasses route surveying, temporary bridge engineering, and self-propelled modular transporter deployment for single pieces exceeding 300 metric tons. Zhenhua Logistics Group dominates inland corridors between western mining basins and coastal processing zones where GB standards compliance creates fleet investment barriers.
- Customs Clearance:Manages cross-provincial permit harmonization under SAMR frameworks for oversized cargo entering Shanghai-Ningbo port clusters.
- Warehousing:Provides staging yards for modular construction components awaiting precision delivery windows to petrochemical and nuclear construction sites.
Freight forwarding dominates installed base. Project cargo is where expansion concentrates.
Transport Mode:
Cost tiering separates capital-intensive marine and rail infrastructure from flexible road deployment, with air transport reserved for time-critical aerospace and nuclear components.
- Road:Deploys self-propelled modular transporter fleets for final-mile positioning of refinery modules and wind turbine components. Zhenhua Logistics Group's 500+ axle-line capacity anchors this segment on western mining-to-coast corridors where rail interchanges remain underdeveloped.
- Rail:Gains traction on corridor density between Xinjiang mineral processing zones and eastern refining complexes. MIIT infrastructure investment is expanding heavy-haul rail gauge clearances for abnormal loads previously forced onto road networks.
- Sea:Heavy-lift vessel chartering concentrates among limited operators serving Jiangsu and Fujian offshore wind installation seasons where berthing window scarcity elevates pricing.
- Air:Handles nuclear fuel rod transport and aerospace component movements requiring NMPA-equivalent certification protocols and specialized handling crews.
Road transport captures volume leadership. Rail is climbing the fastest as western corridor density improves.
Industry Vertical:
Application urgency and cargo value density determine which verticals absorb premium integrated logistics pricing versus fragmented forwarding arrangements.
- Energy:Offshore wind farm deployment and petrochemical complex construction drive demand for engineering-integrated logistics contracts. State-owned developers in Jiangsu province now mandate single-accountability structures that displace traditional freight margins.
- Construction:Prefabricated infrastructure modules require precision heavy-haul coordination from manufacturing basins to urban installation sites where temporary road modifications and bridge reinforcements dominate project cost structures.
- Mining:Xinjiang and Inner Mongolia mineral processing expansion creates multi-modal demand linking extraction sites to coastal refining capacity.
- Manufacturing:Semiconductor fabrication equipment movements require clean-room compatible transport protocols and vibration-controlled handling systems.
Energy verticals dominate contract value. Construction is gaining share fastest as modular methods proliferate.
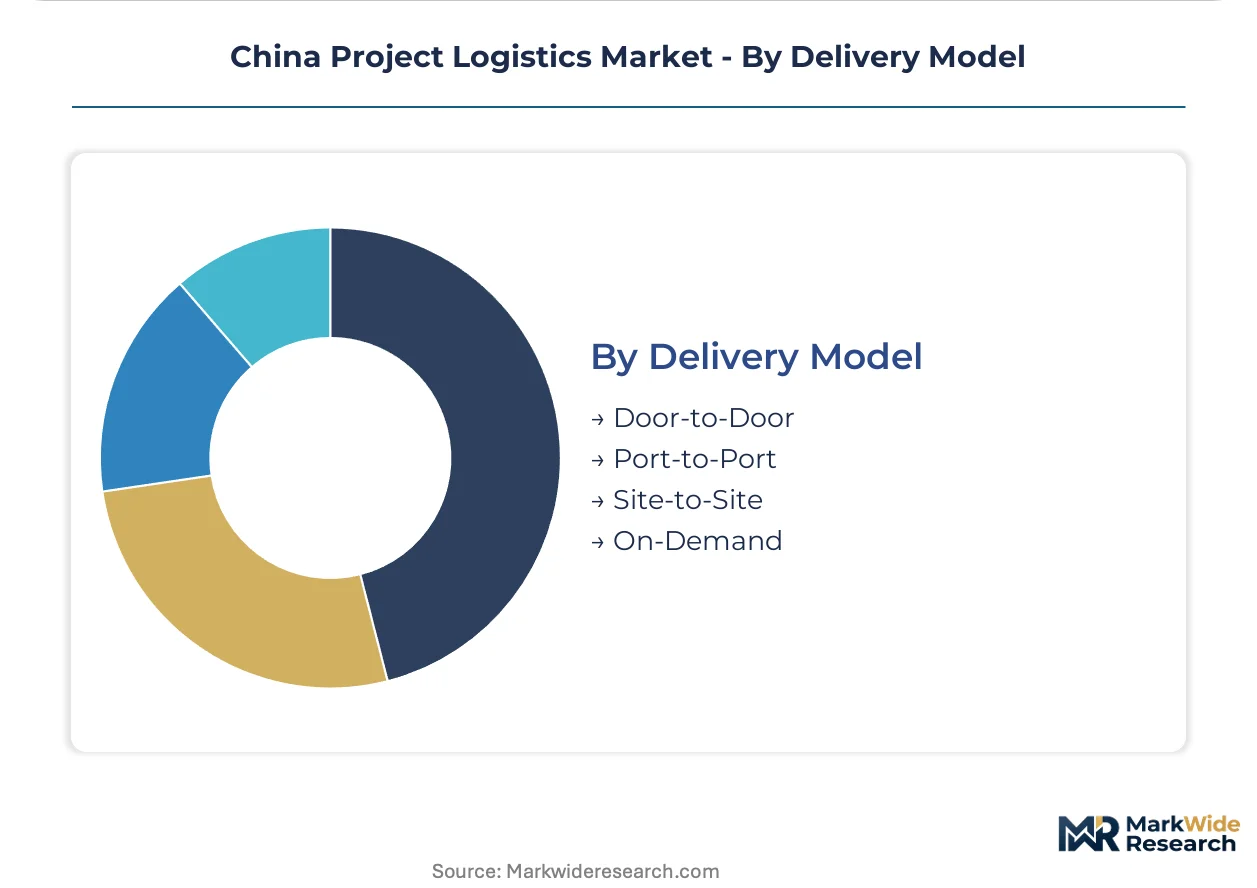
Delivery Model:
Customer type and risk tolerance stratify procurement between integrated accountability and fragmented interface management.
- Door-to-Door:Single-accountability structures command premium pricing through bundled route surveying, heavy-haul execution, and final positioning. EPC contractors increasingly mandate this model for nuclear and aerospace logistics where schedule penalties exceed transport costs.
- Site-to-Site:Prevails in energy verticals where receiver engineering teams manage final positioning and operator handoff occurs at facility boundaries. State-owned developers favor this structure to maintain technical control over critical installation phases.
- Port-to-Port:Traditional marine forwarding arrangement for standardized heavy-lift cargo where terminal handling and vessel chartering constitute the primary value chain.
- On-Demand:Emergency response and maintenance turnaround logistics requiring rapid permit acquisition and dedicated fleet mobilization.
Site-to-site arrangements dominate current procurement. Door-to-door is expanding most quickly as EPC bundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors outbound heavy-lift flows to Southeast Asian infrastructure sites, while inland corridors feed western mineral basins into coastal processing zones. Provincial licensing frameworks and port clustering patterns shape operator competitiveness across distinct sub-regional markets.
Yangtze River Delta
Shanghai-Ningbo port infrastructure concentrates oversized cargo flows serving petrochemical and nuclear construction sites. MIIT dual carbon mandates accelerate offshore wind component movements through these terminals. Heavy-lift berthing windows face seasonal scarcity as Jiangsu and Fujian developers compress installation timelines.
Pearl River Delta
Modular construction exports to Belt and Road destinations drive demand for precision heavy-haul coordination from manufacturing basins. SAMR cross-provincial permit harmonization remains incomplete across Guangdong's corridor movements. Shenzhen and Guangzhou terminals specialize in semiconductor fabrication equipment requiring clean-room compatible handling protocols.
Beijing-Tianjin-Hebei
Aerospace and nuclear logistics contracts concentrate in this corridor where specialized driver credentials outpace vocational training output. GB standards compliance for self-propelled modular transporters extends fleet procurement cycles. Tianjin port serves as the primary heavy-lift interchange for northern offshore wind installation seasons.
Western China
Xinjiang and Inner Mongolia mineral processing expansion creates multi-modal demand linking extraction sites to coastal refining capacity. MIIT infrastructure investment expands heavy-haul rail gauge clearances for abnormal loads previously forced onto road networks. Urumqi and Hohhot anchor corridor density improvements between western mining basins and eastern processing zones.
Sichuan-Chongqing
Prefabricated infrastructure modules require precision delivery to urban installation sites where temporary road modifications dominate project cost structures. Provincial enforcement regimes for GB standard equipment certification vary in timing and documentation requirements. Chongqing's inland port serves as the rail-water interchange for western cargo entering Yangtze River downstream flows.
China Project Logistics Market Competitive Environment
Player mix skews toward state-affiliated port operators and specialized heavy-haul contractors with fleet-scale advantages. The vendor base concentrates around three strategic archetypes: integrated state-owned logistics conglomerates controlling terminal networks, regional heavy-haul specialists with self-propelled modular transporter fleets, and international forwarders leveraging global chartering relationships. Competitive positioning hardens through M&A consolidation of provincial permit capabilities and strategic partnerships for vessel chartering access during seasonal installation windows.
Within the state-affiliated tier, COSCO Shipping Logistics and Zhenhua Logistics Group exemplify contrasting scale strategies. COSCO leverages its port terminal network to control heavy-lift berthing windows along China's eastern seaboard. Zhenhua anchors inland project corridors with fleet-scale self-propelled modular transporter capacity. CJ Smart Cargo represents the specialized contractor archetype through heavy-lift marine logistics positioning. These three operators illustrate how certification access and corridor density determine contract capture in MIIT-regulated environments.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| CJ Smart Cargo |
| COSCO Shipping Logistics |
| Zhenhua Logistics Group |
| InterMax Logistics Solution |
| Sinotrans |
| Kerry Logistics Network |
| ASB Logistics |
| DSV |
| Others |
Value Chain & Pricing Dynamics
MIIT's GB standards for heavy-lift vehicle configurations gate both fleet qualification and contract pricing tiers simultaneously, compressing margins for uncertified operators while elevating premiums for nuclear-grade compliance. State-owned developers exploit this bifurcation to extract engineering-integrated accountability without proportionate fee increases.
Pricing Analysis
Current-generation self-propelled modular transporter fleets command project-based pricing premiums against prior-generation axle configurations, while next-generation electrified heavy-haul platforms remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels reflects MIIT certification grade and after-sales service bundling. Cost compression in standard-tier road transport is intensifying because mid-scale operators face fleet consolidation pressure. EPC contractors demonstrate least price sensitivity for door-to-door integrated contracts, while fragmented freight forwarding buyers absorb maximum margin erosion.
Supply Chain Analysis
Port congestion at Shanghai-Ningbo heavy-lift terminals and container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for specialized vessel components. Domestic manufacturing draws from German-engineered SPMT subsystems, South Korean heavy-lift crane assemblies, and Chinese steel fabrication. Single-source vulnerability concentrates in 500+ axle-line fleet control systems sourced from limited European suppliers. Distribution runs through state-owned port terminal networks with COSCO Shipping Logistics controlling eastern seaboard berthing windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China project logistics sits in early-cycle expansion as modular construction methods penetrate petrochemical and infrastructure verticals faster than historical norms. MIIT dual carbon mandates accelerate offshore wind deployment timelines beyond traditional logistics capacity response.
For Market Incumbents: Consolidate provincial permit capabilities through targeted acquisition of regional operators holding SAMR cross-provincial licenses. Deepen upstream control over self-propelled modular transporter maintenance networks to lock out emerging fleet-scale competitors. Threat substitution from rail corridor density improvements demands preemptive corridor anchoring in Xinjiang and Inner Mongolia. For New Entrants and Emerging Players: Anchor in western mining-to-coast rail intermodal gaps where MIIT infrastructure investment lags cargo volume growth. Target Sichuan-Chongqing prefabricated infrastructure module delivery as the most penetrable segment given temporary road modification cost structures. Pursue joint venture structures with state-owned port operators to access heavy-lift berthing windows without capital-intensive terminal ownership. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across nuclear and aerospace logistics sub-segments as GB standards compliance extends fleet procurement cycles. Long-term viability favors vertically integrated operators combining port terminal control with specialized heavy-haul fleet ownership. Acquisition target archetype: regional SPMT specialists with 48-96 axle configurations and established SAMR permit relationships. Signal to watch: MIIT enforcement consistency across provincial GB standard implementation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Heavy-Lift Fleet Electrification | MIIT emissions mandates force premature replacement cycles for diesel SPMT platforms. |
| Provincial Permit Capability Acquisition | SAMR harmonization gaps create moats for operators with multi-jurisdictional license portfolios. |
| Rail-Water Intermodal Development | Chongqing and Wuhan terminals capture western cargo flows previously forced onto road networks. |
| Engineering-Procurement-Construction Bundling | Jiangsu offshore wind developers mandate single-accountability structures displacing fragmented forwarding. |
| GB Standard Export Alignment | Belt and Road Central Asian projects demand Chinese-certified heavy-lift protocols and equipment. |
Study Parameters
A standing panel of EPC contract managers, port terminal operations directors, heavy-haul fleet procurement leads, and SAMR regional enforcement officers provided ongoing calibration across the study period. Primary interviews with state-owned energy developers and specialized vessel chartering brokers combined with secondary validation from MIIT policy circulars, GB standards documentation, customs heavy-lift cargo flow records, and provincial transport bureau permit issuance databases. Bottom-up project pipeline aggregation and top-down macroeconomic demand modeling underwent iterative triangulation.
Consistency checks validated volume and value outputs against external benchmarks including port authority heavy-lift throughput disclosures and state-owned logistics conglomerate segment reporting. The analytical framework modeled service type, transport mode, industry vertical, and delivery model dimensions across the projection horizon. CAGRs derived from corridor-specific cargo flow trajectories and fleet capacity expansion schedules. Nuclear logistics contract premiums and offshore wind installation seasonality served as industry-specific forecast inputs.
Material uncertainties — MIIT enforcement timing variability, SAMR cross-provincial harmonization completion, and specialized vessel chartering market concentration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding state-owned developer procurement pattern continuity and GB standards certification timeline stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Pharmaceutical Logistics Market
Logistics and Shipping
Container Terminal Automation Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
Peru Logistics Market
Logistics and Shipping
Timber Logistics Market
Logistics and Shipping
Freight and Logistics Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Straddle Carrier Market
Logistics and Shipping
Turkey Freight and Logistics Market