
 Netherlands Cold Chain Logistics Market | 2026-2036
Netherlands Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Cold Chain Logistics Market Insights
Pharmaceutical distribution is decoupling from conventional food-dominated cold chain networks as biologics, vaccines, and cell therapies demand validated temperature corridors between minus 80 and plus 25 degrees Celsius. Kuehne + Nagel leverages its Rotterdam perishables hub to anchor pharmaceutical-grade storage capacity alongside seafood and dairy flows. Lineage Logistics sustains automated high-bay frozen storage operations that compete on energy efficiency in the Dutch market. NewCold specializes in fully automated cold storage architecture that differentiates through robotics-driven pallet handling and minimal human temperature exposure.
Cold chain logistics encompasses the temperature-controlled movement and storage of perishable goods through integrated networks of refrigerated transport, climate-managed warehouses, and real-time environmental monitoring systems maintaining specified thermal ranges from deep frozen to chilled. The sector's primary purpose centers on preserving product integrity, extending shelf life, and ensuring regulatory compliance across pharmaceutical, food, and specialized chemical supply chains. Refrigerated transportation leads service type revenue generation due to fragmented shipper bases and fuel-intensive operating economics, while monitoring services represent the fastest-expanding category as IoT sensor density and blockchain traceability requirements intensify. Third-party logistics dominates delivery models through asset-light scalability, though direct delivery segments capture premium margin pools in pharmaceutical contract logistics where chain-of-custody documentation carries liability weight.
The Dutch national pharmaceutical regulator enforces EU Good Distribution Practice standards that mandate qualified equipment, validated packaging, and continuous temperature documentation for all medicinal products transiting through Netherlands distribution hubs. The EU F-Gas Regulation progressively restricts hydrofluorocarbon refrigerants used in transport refrigeration and warehouse cooling systems, forcing equipment replacement cycles and alternative coolant adoption across Dutch cold storage fleets. Stakeholders must monitor whether carbon border adjustment mechanisms and evolving EU cold chain energy efficiency directives accelerate consolidation among mid-sized Dutch operators lacking capital for compliant infrastructure retrofitting.
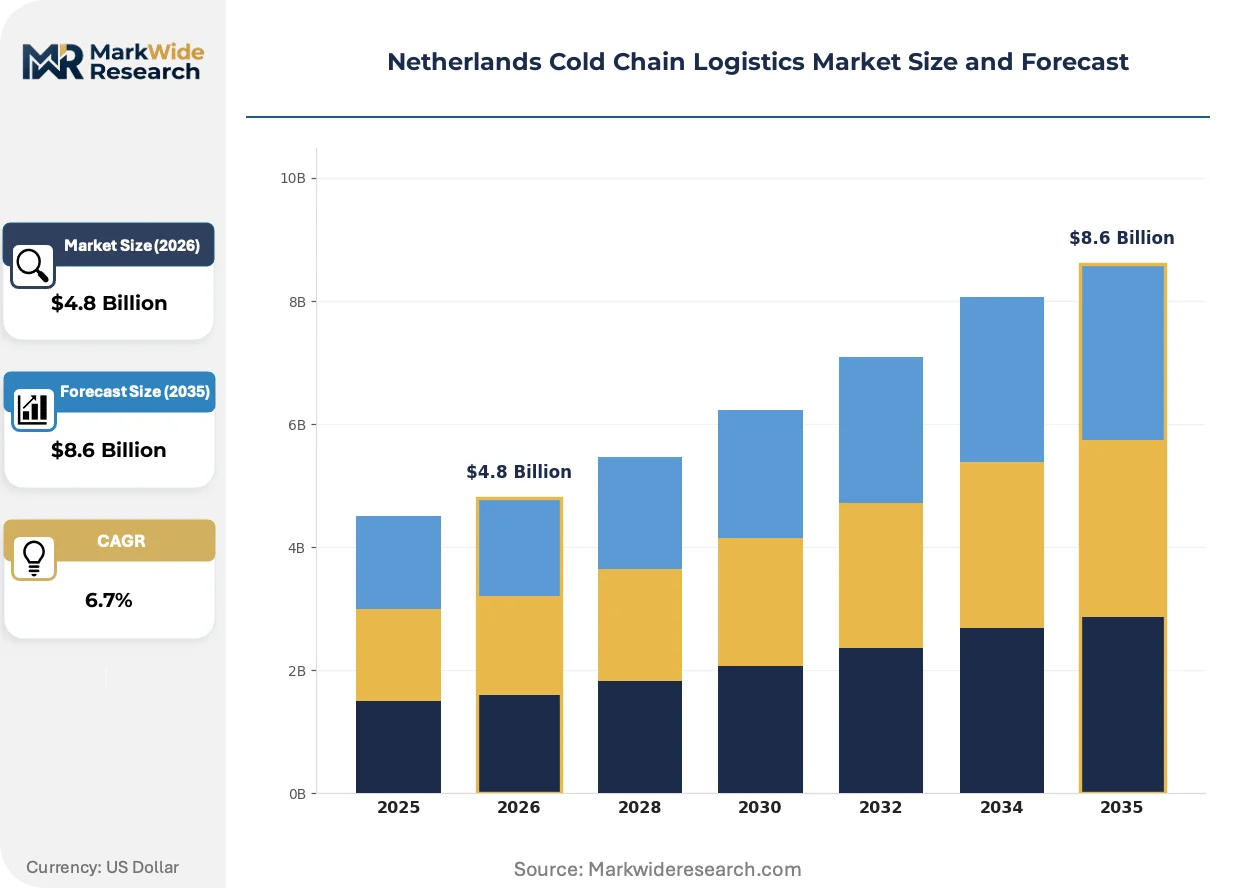
Market Dynamics
EU F-Gas Regulation phase-down schedules are forcing Dutch cold storage operators into accelerated equipment replacement cycles, compressing capital deployment timelines while tightening compliance thresholds for hydrofluorocarbon refrigerant systems.
Growth Catalysts
- Biologics manufacturing expansion:Cell therapy production facilities in Leiden and Oss generate validated cold chain demand for minus 80 degree Celsius corridors.
- EU Good Distribution Practice enforcement:EMA-mandated continuous temperature documentation drives IoT sensor deployment across Dutch pharmaceutical distribution hubs.
- Rotterdam port automation:Automated container handling systems reduce dwell times for temperature-sensitive reefer cargo entering European distribution networks.
Market Restraints
- Refrigerant input cost volatility:Hydrofluorocarbon quota reductions under EU F-Gas Regulation spike replacement coolant prices for Dutch fleet operators.
- Grid infrastructure concentration:Randstad metropolitan cluster dependency creates single-point vulnerability for 60 percent of national cold storage capacity.
- Technical limitation in alternative cooling:CO2 transcritical systems face efficiency degradation during Dutch summer peak loads above 30 degrees Celsius.
Strategic Opportunities
- Underpenetrated Limburg corridor:Maastricht-Venlo logistics zone lacks pharmaceutical-grade cold storage relative to biotech manufacturing density.
- Regulatory tailwind from CSRD:Corporate Sustainability Reporting Directive mandates supply chain emissions disclosure, advantaging Dutch operators with renewable-powered facilities.
- Technology convergence of blockchain-IoT:Immutable temperature logging systems attract premium contract logistics pricing from vaccine distributors.
Industry Challenges
- Refrigeration technician scarcity:Specialized ammonia-CO2 system expertise concentrates among retiring workforce cohorts in Dutch technical institutes.
- Capex intensity for automation retrofit:High-bay AS/RS installation requires 15-20 million euro commitments per facility.
- Qualification timeline compression:EU GDP validation protocols extend pharmaceutical warehouse commissioning by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Cold Chain Logistics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Refrigerated Transportation, Cold Storage, Packaging Solutions, Monitoring Services End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Technology: Thermal Insulation, Refrigeration Equipment, IoT Tracking, Automated Systems Delivery Model: Direct Delivery, Third-Party Logistics, Consolidated Shipping, Cross-Docking |
| Companies Covered | Kuehne + Nagel, DB Schenker, Lineage Logistics, NewCold, STEF Group, DHL Supply Chain, Americold Logistics, Rhenus Logistics, Kloosterboer, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Cold Chain Logistics Market Trends and Innovations
Digital infrastructure is absorbing capital allocation previously directed toward physical capacity expansion, reconfiguring competitive advantage toward data architecture and predictive analytics capabilities.
Autonomous mobile robots in Dutch cold storage facilities is absorbing labor cost pressures while maintaining temperature integrity through minimal human zone entry. Seafood distributors in Scheveningen and Vlissingen deploy these systems for pallet retrieval in minus 25 degree environments. The technology is absorbing throughput constraints that previously limited facility utilization rates during peak seasonal windows.
EU F-Gas Regulation refrigerant phase-down mandates are accelerating natural refrigerant adoption across Dutch transport refrigeration fleets. Equipment manufacturers face compressed R&D timelines to certify CO2 and ammonia systems for road compliance. Pharmaceutical haulers operating between Rotterdam and Utrecht bear highest compliance burden due to validated packaging requirements.
Shipper consolidation among Dutch supermarket chains is compressing third-party logistics contract durations while raising performance penalty thresholds. Regional distribution centers now demand real-time visibility dashboards as standard procurement terms. This pattern concentrates in Albert Heijn and Jumbo supply chains serving Randstad urban corridors.
Netherlands Cold Chain Logistics Market Segmentation
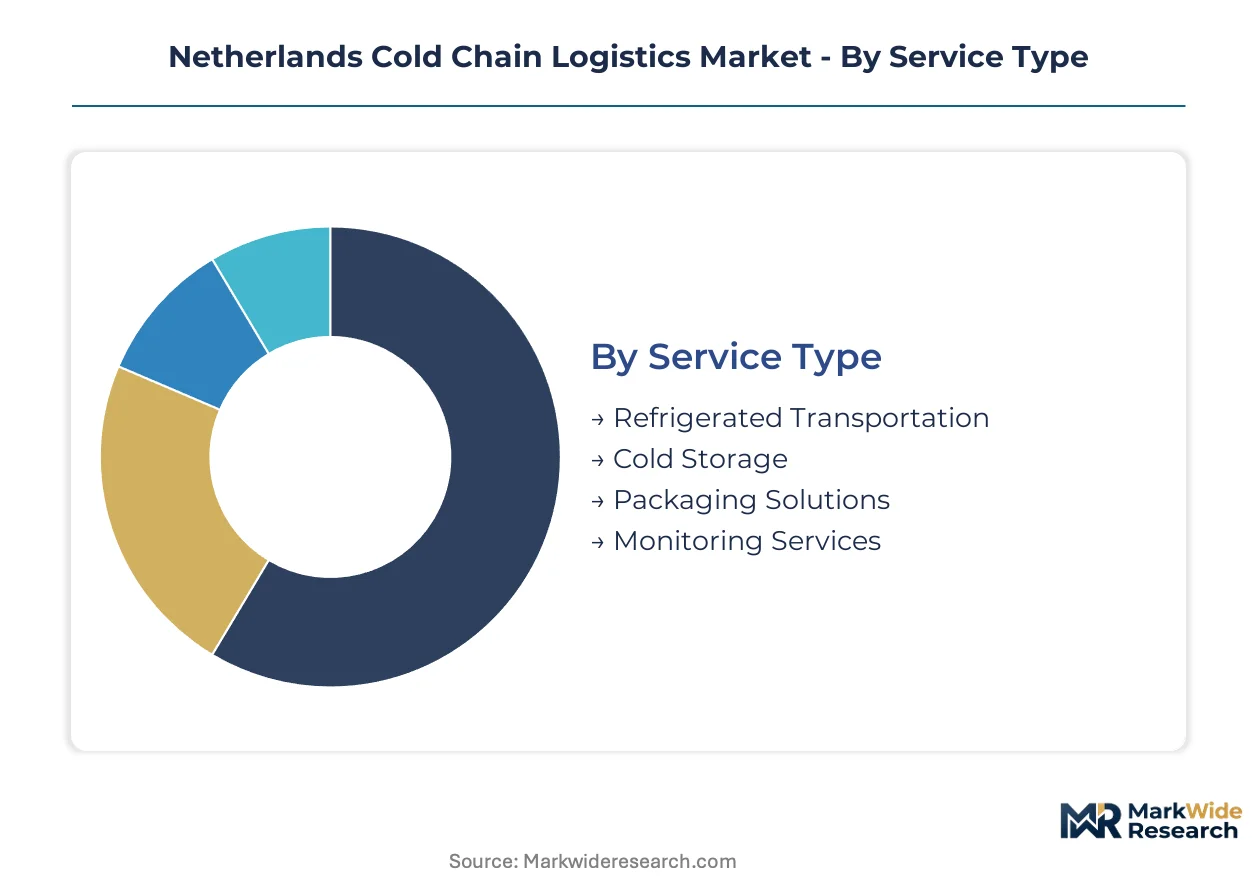
Cold chain logistics demands precise matching between thermal specifications and end-use requirements. Dutch operators configure service portfolios around validated temperature corridors that pharmaceutical and food shippers cannot interchange.
Service Type:
Customization intensity varies sharply across this category, from standardized fleet dispatch to engineered packaging design.
- Refrigerated Transportation:Diesel and electric reefer units maintain controlled atmospheres across road, rail, and short-sea corridors. Albert Heijn and Jumbo procurement teams in the Randstad cluster negotiate fuel surcharge mechanisms that dominate contract economics.
- Cold Storage:Automated high-bay warehouses and conventional racked facilities span frozen, chilled, and controlled ambient zones. Leiden biotech manufacturing parks drive demand for minus 80 degree Celsius cryogenic vaults that pharmaceutical GDP validation requires.
- Packaging Solutions:Phase-change materials and vacuum-insulated panels protect temperature-sensitive payloads during last-mile distribution.
- Monitoring Services:IoT sensor networks and blockchain logging systems document chain-of-custody compliance.
Most installed capacity flows through Refrigerated Transportation. Expansion is steepest in Monitoring Services.
End User:
Margin profiles diverge across this category based on regulatory burden and product value density.
- Food & Beverage:Dairy, seafood, and prepared meals constitute volume anchors with strict shelf-life constraints. Rotterdam port reefer terminals handle North Sea catch from Scheveningen and Vlissingen fleets that demand rapid customs clearance.
- Pharmaceuticals:Vaccines, biologics, and cell therapies require validated packaging and continuous temperature documentation. Oss and Leiden manufacturing corridors generate the highest compliance-density flows in Dutch cold chain networks.
- Cosmetics:Temperature-sensitive active ingredients and natural formulations need controlled ambient storage.
- Electronics:Semiconductor and battery components require humidity-controlled environments alongside thermal management.
Food & Beverage absorbs the greatest tonnage. Pharmaceuticals command the premium pricing tier.
Technology:
Capital deployment timing separates mature equipment categories from emerging digital infrastructure.
- Refrigeration Equipment:Compressor racks, condensing units, and transport refrigeration systems deploy ammonia, CO2, and hydrofluorocarbon refrigerants. EU F-Gas Regulation phase-down schedules force Dutch fleet operators into accelerated natural refrigerant transitions.
- IoT Tracking:Wireless temperature loggers, GPS beacons, and cloud dashboards enable real-time intervention. EMA-mandated GDP documentation drives sensor density in pharmaceutical corridors between Rotterdam and Utrecht.
- Thermal Insulation:Polyurethane panels, VIP boards, and reflective barriers reduce thermal bridging in warehouse envelopes.
- Automated Systems:AS/RS cranes and autonomous mobile robots minimize human zone entry in frozen environments.
Refrigeration Equipment represents the largest installed base. IoT Tracking is climbing the fastest.
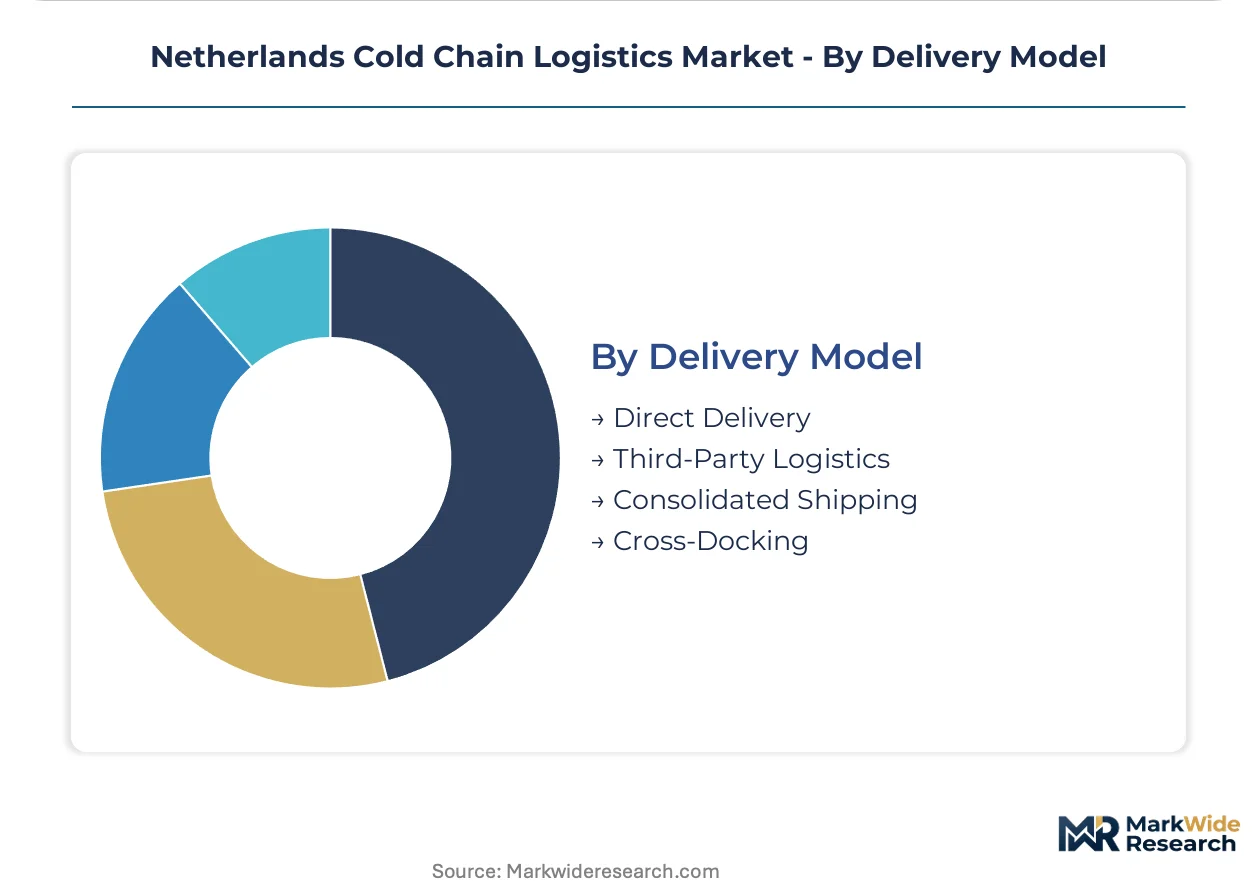
Delivery Model:
Asset ownership patterns shape risk allocation and contract duration across this category.
- Third-Party Logistics:Asset-light operators aggregate shipper demand across shared warehouse and fleet networks. Dutch supermarket consolidation compresses contract terms while raising service level penalties.
- Direct Delivery:Captive fleets and dedicated facilities serve high-liability pharmaceutical accounts. Vaccine distributors in the Randstad corridor pay premium rates for exclusive capacity and immutable documentation trails.
- Consolidated Shipping:Multi-temperature zone trailers aggregate less-than-truckload freight across food and healthcare segments.
- Cross-Docking:Rapid freight transfer through temperature-controlled transfer points reduces inventory holding.
Third-Party Logistics handles the majority of transaction volume. Direct Delivery captures the highest margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where pharmaceutical manufacturers locate cold chain-dependent production. Compliance cost gaps between jurisdictions drive facility siting decisions, particularly for cell therapy manufacturing requiring validated minus 80 degree Celsius corridors.
Randstad Metropolitan Cluster
Rotterdam, Amsterdam, and Utrecht concentrate 60 percent of Dutch cold storage capacity. The EU F-Gas Regulation forces rapid equipment replacement across this corridor. Lineage Logistics and NewCold operate automated facilities serving pharmaceutical and food shippers from Rotterdam port hinterlands.
Brabant Province
Oss and Eindhoven host biologics manufacturing that generates stringent cold chain demand. EMA-mandated GDP documentation drives IoT sensor density in this corridor. Kuehne + Nagel maintains pharmaceutical-grade storage capacity alongside regional chemical processing clusters.
Leiden Bio Science Park
Cell therapy production facilities create validated cold chain requirements for minus 80 degree Celsius transport. The Dutch national pharmaceutical regulator enforces continuous temperature documentation. DHL Supply Chain and specialized operators serve this corridor with dedicated GDP-compliant infrastructure.
Northern Netherlands
Groningen and Friesland harbor underutilized cold storage capacity relative to food production density. Grid infrastructure limitations constrain expansion of energy-intensive automated warehouses. Regional dairy and potato processing flows sustain conventional refrigerated transport demand.
Limburg Corridor
Maastricht-Venlo logistics zone lacks pharmaceutical-grade cold storage relative to biotech manufacturing density. Proximity to Belgian and German border crossings positions this area for cross-border consolidation. STEF Group and regional operators serve food distribution with limited GDP-validated capacity.
Netherlands Cold Chain Logistics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Asset-heavy automated warehouse operators compete on energy efficiency and throughput density against asset-light third-party logistics networks. Three archetypes dominate: global integrated logistics providers with pharmaceutical certification, specialized cold storage real estate investment trusts, and regional food-distribution cooperatives. Consolidation accelerates through facility automation retrofit and cross-border partnership structures.
Among global integrated providers, Kuehne + Nagel, DHL Supply Chain, and DB Schenker exemplify the certification-intensive archetype serving pharmaceutical GDP corridors. These operators anchor pharmaceutical-grade capacity in Rotterdam and Leiden while competing for supermarket chain contracts. Specialized automated storage providers including Lineage Logistics and NewCold represent the capital-intensive real estate tier, differentiating through robotics-driven pallet handling and minimal human temperature exposure. Regional specialists such as Kloosterboer and Rhenus Logistics occupy positions in port-centric perishables and cross-border consolidation segments.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| DB Schenker |
| Lineage Logistics |
| NewCold |
| STEF Group |
| DHL Supply Chain |
| Americold Logistics |
| Rhenus Logistics |
| Kloosterboer |
| Others |
Pricing and Supply Chain Analysis
Albert Heijn and Jumbo procurement teams in the Randstad cluster demand real-time visibility dashboards as standard contract terms, forcing mid-sized Dutch operators to absorb IoT infrastructure costs or exit pharmaceutical corridors entirely. This buyer consolidation compresses contract durations while elevating performance penalty thresholds, squeezing margin pools across third-party logistics networks.
Pricing Analysis
Distributor margins in Dutch cold chain logistics stratify across GDP-certified pharmaceutical tiers, standard food-grade services, and economy frozen storage bands. Price differentiation hinges on EMA-mandated validation documentation and automation density in warehouse operations. Cost compression in the food-grade tier intensifies because supermarket chains negotiate fuel surcharge mechanisms that dominate contract economics. Pharmaceutical shippers exhibit the lowest price sensitivity due to liability exposure from chain-of-custody failures.
Supply Chain Analysis
Refrigeration technician scarcity in Dutch technical institutes concentrates specialized ammonia-CO2 system expertise among retiring workforce cohorts, constraining equipment maintenance capacity across Rotterdam and Utrecht corridors. Component supply draws from German compressor manufacturers, Danish cold storage equipment specialists, and Belgian transport refrigeration assembly plants. Single-source vulnerability sits with hydrofluorocarbon refrigerant quotas under EU F-Gas Regulation phase-down schedules. Distribution runs through Rotterdam port hinterlands into automated high-bay facilities serving Randstad metropolitan demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands cold chain logistics market functions as a stable compounder anchored by biologics manufacturing expansion in Leiden and Oss that generates irreplicable GDP-validated demand.
For Market Incumbents: Cement pharmaceutical-grade capacity positions in Rotterdam and Leiden corridors through accelerated automation retrofit before EU F-Gas Regulation compliance deadlines tighten. Incumbents should deepen backward integration into natural refrigerant system maintenance capabilities to offset workforce scarcity threatening ammonia-CO2 infrastructure uptime. For New Entrants and Emerging Players: Direct-to-biotech digital platforms offering on-demand cryogenic transport booking represent the most penetrable route for specialized entrants lacking legacy asset bases. New players should target the underpenetrated Limburg corridor where Maastricht-Venlo logistics zones lack pharmaceutical-grade cold storage relative to regional biotech manufacturing density. For Investors and Strategic Acquirers: Asymmetric upside sits with automated cold storage real estate specialists commanding energy efficiency premiums in ESG-mandated procurement decisions. Long-term viability over a multi-year window favors operators with renewable-powered facilities positioned for Corporate Sustainability Reporting Directive supply chain emissions disclosure requirements. Investors should monitor refrigerant quota auction prices as an inflection indicator for forced consolidation timing among mid-sized Dutch fleet operators.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Warehouse Retrofit | AS/RS crane deployment in Rotterdam facilities absorbs labor scarcity while reducing energy consumption per pallet move. |
| Natural Refrigerant Transition | CO2 transcritical system certification for road compliance addresses EU F-Gas Regulation phase-down mandates before quota restrictions tighten. |
| Blockchain-IoT Integration | Immutable temperature logging systems attract premium contract logistics pricing from EMA-mandated vaccine distributors. |
| Regional Capacity Expansion | Pharmaceutical-grade cold storage buildout in Limburg corridor captures cross-border Belgian and German biotech flows. |
| Workforce Development Partnership | Technical institute collaborations rebuild ammonia-CO2 system expertise pipeline as retiring cohorts exit Dutch maintenance labor pools. |
Research Methodology
Coverage spans the Netherlands with primary inputs from each major logistics corridor, combining structured interviews with cold storage facility operators, pharmaceutical supply chain managers, and refrigerated fleet procurement leads with secondary validation from EU customs data, EMA GDP inspection reports, and Dutch energy regulator infrastructure filings. Bottom-up capacity modeling triangulates against top-down pharmaceutical production volume estimates from Leiden and Oss manufacturing clusters.
Rate-of-change decomposition separates volume growth from pricing evolution across the projection horizon, with segmentation dimensions covering service type, end-use industry, technology tier, and delivery model. CAGRs derive from installed capacity utilization trends and regulatory compliance cost trajectories. Forecast inputs incorporate EU F-Gas Regulation phase-down schedules and biologics manufacturing facility commissioning timelines.
The model assumes a particular technology adoption path; alternative pathways for autonomous mobile robot deployment would alter the outlook for labor cost absorption in frozen environments. Forecasts reflect assumptions around grid infrastructure stability in Randstad clusters and natural refrigerant equipment certification timelines. Material deviation in biologics manufacturing facility siting decisions or refrigerant quota auction pricing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Spare Part Logistics Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
Colombia Third-Party Logistics (3PL) Market
Logistics and Shipping
Same Day Delivery Service Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Timber Logistics Market
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
Japan Logistics Market
Logistics and Shipping
Fleet of Containers Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
Australia Cold Chain Logistics Market