
 Air Cargo Capacity and Allotment Marketplace Platforms Market | 2026-2036
Air Cargo Capacity and Allotment Marketplace Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Air Cargo Capacity and Allotment Marketplace Platforms Market Insights
Multi-source capacity procurement is shifting from fragmented broker networks toward integrated digital marketplaces. WebCargo by Freightos leverages its freight-rate database to aggregate real-time airline capacity across multiple carriers. cargo.one anchors European forwarder adoption through direct API connections with Lufthansa Cargo and Air France-KLM. CHAMP Cargosystems sustains legacy carrier relationships while extending modular booking tools to mid-tier airlines seeking marketplace participation.
Air cargo capacity and allotment marketplace platforms function as digital intermediaries that match available belly-hold and freighter space with forwarder demand through standardized electronic booking protocols, typically processing allotments in IATA-compatible Cargo-IMP or ONE Record formats. These systems automate capacity release, dynamic pricing, and block-space allocation to reduce manual allocation latency in pharmaceutical and perishable supply chains. Cloud-based deployment dominates platform architecture due to lower integration barriers for small forwarders, while artificial intelligence applications concentrate on demand forecasting and yield-optimization algorithms. Blockchain segments remain nascent, confined largely to pilot programs for pharmaceutical chain-of-custody verification where margin pools justify implementation costs.
The EU's F-Gas Regulation and CE marking requirements for cold-chain equipment shape platform feature development, particularly temperature-verification modules for pharmaceutical distribution workflows. IATA's ONE Record standard and the EU AI Act's transparency mandates for automated pricing algorithms will determine which platforms achieve carrier certification and forwarder trust. Stakeholders must monitor whether regulatory convergence around data interoperability standards accelerates platform consolidation or preserves specialized niche operators.
Market Dynamics
The pharmaceutical cold-chain sector is pulling capacity marketplace platforms toward temperature-verified allotment contracts, driven by EU F-Gas Regulation compliance deadlines and CE marking requirements for active container fleets.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is forcing carriers to document equipment emissions through digital allotment platforms, creating mandatory adoption pressure across European pharmaceutical lanes.
- Pharmaceutical distribution:Temperature-sensitive biologics now require block-space commitments with thermal integrity guarantees, converting spot-market forwarders into platform subscribers seeking contracted capacity.
- Cloud deployment:Lower integration barriers for small forwarders are accelerating platform penetration beyond legacy EDI-dependent Tier 1 operators.
Market Restraints
- Legacy carrier IT infrastructure:Mainframe-based cargo management systems at established airlines resist API modernization, delaying real-time inventory synchronization with marketplace platforms.
- Data standardization fragmentation:Coexistence of Cargo-IMP, Cargo XML, and ONE Record formats forces platforms to maintain multiple protocol gateways, inflating development overhead.
- Yield management conflict:Carriers fear disintermediation of direct forwarder relationships, restricting premium capacity release to marketplace channels.
Strategic Opportunities
- Blockchain chain-of-custody:Pilot programs for pharmaceutical verification are expanding into commercial deployments where margin pools justify implementation costs.
- India pharmaceutical exports:Cold-chain infrastructure gaps between Mumbai and Hyderabad manufacturing clusters create demand for pre-booked temperature-controlled allotments.
- IATA ONE Record standard:Regulatory convergence around this data interoperability framework will consolidate platform certification requirements, favoring early adopters.
Industry Challenges
- AI Act transparency mandates:Automated pricing algorithms face explainability requirements under EU AI Act provisions, complicating yield-optimization model deployment.
- API integration talent scarcity:Shortage of developers proficient in both aviation cargo protocols and modern cloud architectures extends carrier onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Cargo Capacity and Allotment Marketplace Platforms Market |
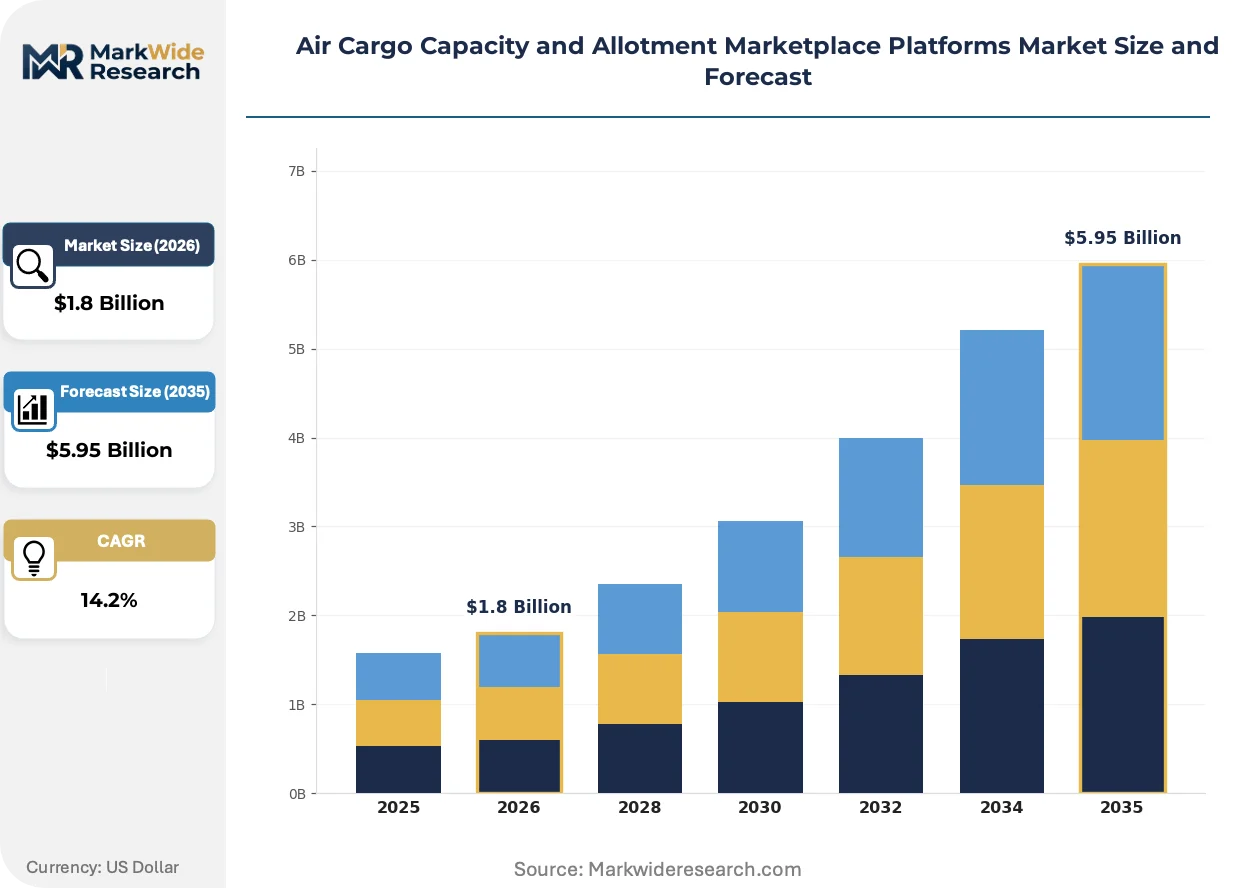
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Digital Freight Exchange, Capacity Management Suite, Booking & Allotment, Carrier Network Portal Technology: Cloud-Based, Artificial Intelligence, Blockchain, Machine Learning, Internet of Things Application: Express Shipment Coordination, Perishable Goods Transport, Heavy Machinery Logistics, Pharmaceutical Distribution, E-commerce Fulfillment End User: Freight Forwarders, Air Freight Brokers, E-commerce Retailers, Third-Party Logistics Providers, Cargo Airlines |
| Companies Covered | WebCargo by Freightos, cargo.one, TACT Air Cargo Solutions, WebCargo by Freightos Group, Freightos, CargoAi, cargoGO, CHAMP Cargosystems, WiseTech Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Cargo Capacity and Allotment Marketplace Platforms Market Trends and Innovations
Digital intermediation is compressing manual allocation cycles from days to hours, with artificial intelligence now governing dynamic pricing and demand forecasting across pharmaceutical and perishable verticals.
Artificial intelligence is integrating yield-optimization algorithms into core platform architectures. Pharmaceutical forwarders in Germany and the Netherlands are adopting these tools fastest, driven by CE-marked cold-chain compliance requirements. The technology is compressing price discovery cycles and enabling real-time block-space reallocation when temperature deviations threaten cargo integrity.
The EU AI Act's transparency requirements for automated decision-making are reshaping platform development roadmaps. Algorithmic pricing modules must now provide audit trails explaining rate quotations to forwarders. Pharmaceutical lanes between Frankfurt and Singapore are most affected, with carriers retrofitting explainability layers into existing AI stacks to maintain certification eligibility.
Forwarder procurement patterns are fragmenting across multi-carrier digital channels rather than consolidating through single-airline direct contracts. Small and mid-tier freight operators in the Benelux region are abandoning phone-and-email spot buying for platform-based allotment commitments. This behavioral shift is most visible in perishable exports from Kenya and Ecuador, where harvest timing unpredictability favors flexible pre-booked capacity over fixed annual contracts.
Air Cargo Capacity and Allotment Marketplace Platforms Market Segmentation
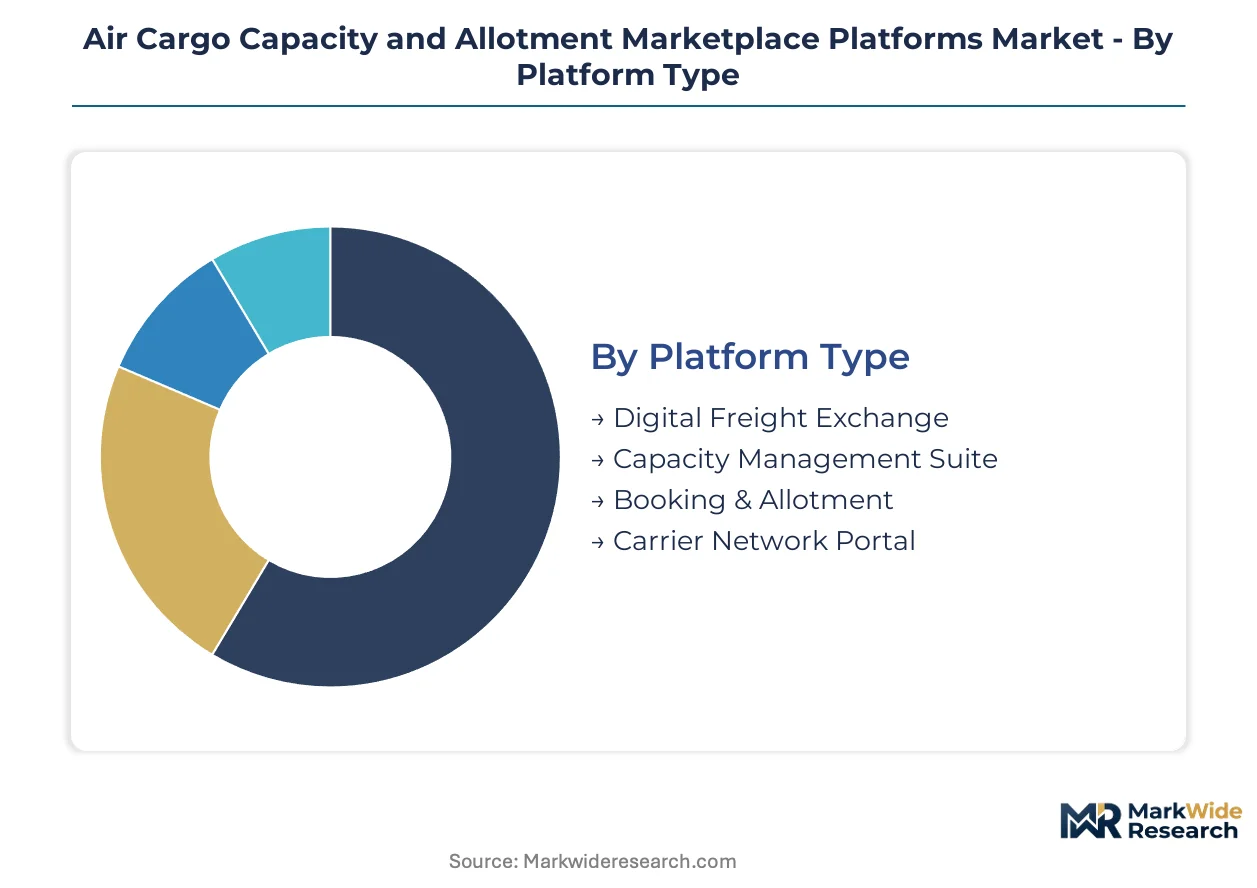
Air cargo marketplace platforms serve heterogeneous operational requirements across carrier IT maturity, forwarder scale, and cargo vertical complexity. Segmentation reveals which platform configurations command premium positioning versus commoditization pressure. The analysis tracks four intersecting dimensions that determine procurement patterns and technology investment priorities.
Platform Type:
Customization intensity varies from standardized exchange interfaces to deeply embedded carrier workflow tools, with integration depth as the primary cost differentiator.
- Digital Freight Exchange:Neutral aggregation layers connecting multiple carriers through standardized APIs, enabling forwarders to compare real-time rates and capacity without bilateral carrier negotiations. Demand concentrates among small and mid-tier forwarders in Germany and the Netherlands seeking to bypass legacy EDI dependencies. The EU's F-Gas Regulation compliance documentation requirements are accelerating adoption as carriers must prove equipment emissions transparency.
- Capacity Management Suite:Comprehensive tools spanning yield optimization, block-space allocation, and dynamic repricing for carrier internal operations. Pharmaceutical distribution channels in Frankfurt and Leipzig anchor demand, where temperature-verified allotment contracts require sophisticated reallocation logic when thermal deviations occur.
- Booking & Allotment:Transaction-focused modules processing IATA-compatible Cargo-IMP or ONE Record format bookings. E-commerce retailers expanding into cross-border fulfillment drive procurement.
- Carrier Network Portal:Single-airline proprietary interfaces preserving direct forwarder relationships. Cargo airlines with established pharmaceutical lanes favor this model to defend yield management control.
Leading the category by volume: Digital Freight Exchange. Growing fastest: Capacity Management Suite.
Technology:
Deployment architecture determines integration barriers, with cloud infrastructure lowering adoption thresholds for fragmented forwarder bases.
- Cloud-Based:Browser-accessible platforms eliminating on-premise infrastructure requirements. Small forwarders across Benelux and German automotive supply chains adopt fastest due to minimal IT capital requirements.
- Artificial Intelligence:Yield-optimization and demand forecasting algorithms governing dynamic pricing. The EU AI Act's transparency mandates for automated decision-making are forcing explainability layer retrofits into existing pharmaceutical lane deployments.
- Blockchain:Distributed ledger pilots for pharmaceutical chain-of-custody verification. Margin pools in temperature-sensitive biologics justify implementation costs where regulatory audit trails are mandatory.
- Machine Learning:Pattern recognition systems improving demand prediction accuracy for perishable harvest timing unpredictability.
- Internet of Things:Sensor integration for real-time cargo condition monitoring, particularly active container fleet emissions tracking under F-Gas phasedown schedules.
Dominant by deployment share: Cloud-Based. Expanding most quickly: Artificial Intelligence.
Application:
Cargo verticals impose distinct protocol requirements, with temperature-sensitive segments commanding platform feature prioritization.
- Pharmaceutical Distribution:Temperature-verified allotment contracts with thermal integrity guarantees and CE-marked cold-chain compliance documentation. Block-space commitments replace spot-market procurement as biologics volumes expand.
- Perishable Goods Transport:Harvest timing unpredictability in Kenya and Ecuador drives demand for flexible pre-booked capacity over fixed annual contracts. Real-time reallocation when temperature deviations threaten cargo integrity is essential.
- Express Shipment Coordination:Time-definite delivery commitments requiring guaranteed capacity access during peak demand windows.
- Heavy Machinery Logistics:Project cargo coordination with dimensional weight calculations and specialized handling requirements.
- E-commerce Fulfillment:High-velocity small parcel aggregation demanding API-native integration with retailer order management systems.
Highest revenue concentration: Pharmaceutical Distribution. Steepest expansion trajectory: Perishable Goods Transport.
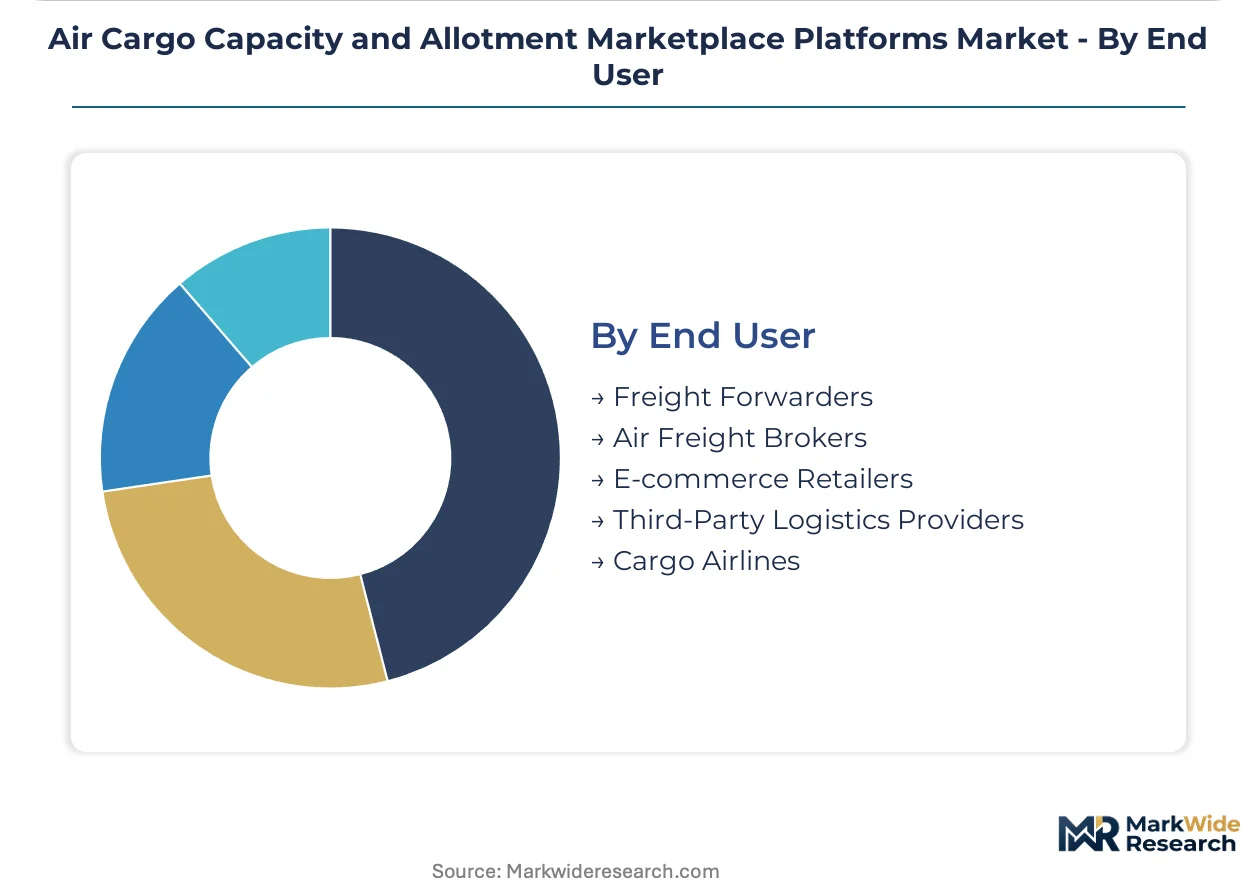
End User:
Procurement sophistication varies from phone-and-email spot buying to fully automated API-driven allotment management.
- Freight Forwarders:Primary platform subscribers seeking multi-carrier capacity aggregation and contracted block-space commitments. German forwarders serving automotive and pharmaceutical verticals show fastest adoption of AI-powered yield tools.
- Third-Party Logistics Providers:Integrated supply chain operators requiring end-to-end visibility across modal transfers. Cloud deployment preference dominates due to multi-client architecture requirements.
- Air Freight Brokers:Intermediary networks fragmenting toward digital marketplace participation or carrier direct portal relationships depending on pharmaceutical lane specialization.
- E-commerce Retailers:Cross-border fulfillment expansion creating demand for real-time capacity visibility and automated booking protocols.
- Cargo Airlines:Platform operators balancing marketplace channel participation against yield management disintermediation risks.
Largest addressable base: Freight Forwarders. Gaining share fastest: Third-Party Logistics Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical distribution hubs and automotive manufacturing clusters concentrate platform demand in Germany, the United States, India, Singapore, and the Netherlands. Each market exhibits distinct regulatory pressures and infrastructure maturity patterns that shape adoption trajectories.
Germany
Frankfurt and Leipzig cargo hubs anchor European pharmaceutical and automotive freight flows, driving demand for temperature-verified allotment contracts. The EU F-Gas Regulation mandates equipment emissions documentation through digital platforms, forcing carrier compliance across cold-chain lanes. Bavaria's automotive supply chains and Hesse's logistics corridors are migrating from legacy EDI to cloud-based marketplace procurement.
United States
Pharmaceutical distribution from New Jersey and Illinois logistics clusters requires block-space commitments with thermal integrity guarantees. FDA cold-chain validation standards intersect with EPA refrigerant tracking requirements, pushing carriers toward transparent digital allotment systems. The Pacific Northwest's perishable export corridors and Texas e-commerce fulfillment hubs are accelerating API-native platform adoption.
India
Mumbai and Hyderabad pharmaceutical manufacturing clusters generate demand for pre-booked temperature-controlled allotments bridging cold-chain infrastructure gaps. CDSCO pharmaceutical export regulations and DGFT trade documentation requirements favor platforms with standardized electronic booking protocols. Gujarat's chemical logistics corridors and Karnataka's automotive component exports are expanding marketplace participation beyond traditional broker networks.
Singapore
Transshipment hub status positions the city-state as a critical node for pharmaceutical lanes between Europe and Asia-Pacific markets. The national pharmaceutical regulator's chain-of-custody requirements align with IATA ONE Record standard adoption, favoring certified platform operators. Perishable re-export flows from Southeast Asian agricultural clusters are driving demand for real-time capacity reallocation tools.
Netherlands
Amsterdam and Rotterdam logistics corridors serve as entry points for pharmaceutical imports into the European Union, concentrating forwarder platform adoption in the Randstad region. CE marking requirements for cold-chain equipment and GDPR data handling standards shape platform feature development priorities. Eindhoven's high-tech manufacturing exports and the Port of Rotterdam's perishable handling facilities are integrating AI-powered yield tools into procurement workflows.
Air Cargo Capacity and Allotment Marketplace Platforms Market Competitive Landscape
API modernization partnerships dominate the current landscape as carriers retrofit legacy cargo management systems for real-time inventory synchronization. The vendor base clusters around three strategic archetypes: neutral aggregation exchanges connecting multiple carriers, carrier-owned portals preserving direct forwarder relationships, and modular technology providers extending booking tools to mid-tier airlines. M&A activity concentrates on acquiring freight-rate databases and cloud infrastructure capabilities, while strategic partnerships focus on IATA ONE Record certification alignment.
Within the neutral exchange tier, WebCargo by Freightos and cargo.one exemplify platform operators leveraging aggregated carrier connectivity to serve fragmented forwarder bases. CHAMP Cargosystems occupies a position bridging legacy carrier relationships with modular marketplace participation tools. These three entities represent distinct competitive positioning vectors: rate-database aggregation, European forwarder API integration, and incumbent carrier technology modernization respectively.
| Leading Market Players |
|---|
| WebCargo by Freightos |
| cargo.one |
| TACT Air Cargo Solutions |
| WebCargo by Freightos Group |
| Freightos |
| CargoAi |
| cargoGO |
| CHAMP Cargosystems |
| WiseTech Global |
| Others |
Pricing and Supply Chain Analysis
Jet fuel price indices cascade through carrier operating costs into forwarder-facing platform subscription tiers, compressing margins for small freight operators while enabling premium pricing for temperature-verified pharmaceutical allotments with CE-marked cold-chain guarantees.
Pricing Analysis
High-volume transactional bookings split from low-volume subscription margins across platform tiers. Three-tier pricing structure across premium, standard, and economy levels reflects API integration depth and carrier network breadth. Price differentiation centers on real-time inventory access and pharmaceutical lane certification status. Pricing pressure stems from cloud deployment lowering barriers for new entrants, eroding legacy EDI-dependent incumbents. Small forwarders in Benelux show highest price sensitivity; pharmaceutical distributors in Germany demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Leipzig, and Amsterdam anchor hub-and-spoke patterns for pharmaceutical and automotive cargo flows. Manufacturing concentration in Germany, the United States, and India feeds component dependencies on active container fleets, API middleware, and cloud infrastructure. Single-source vulnerability in legacy carrier mainframe systems threatens real-time synchronization. Distribution runs through carrier-direct portals and neutral exchanges to fragmented forwarder bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
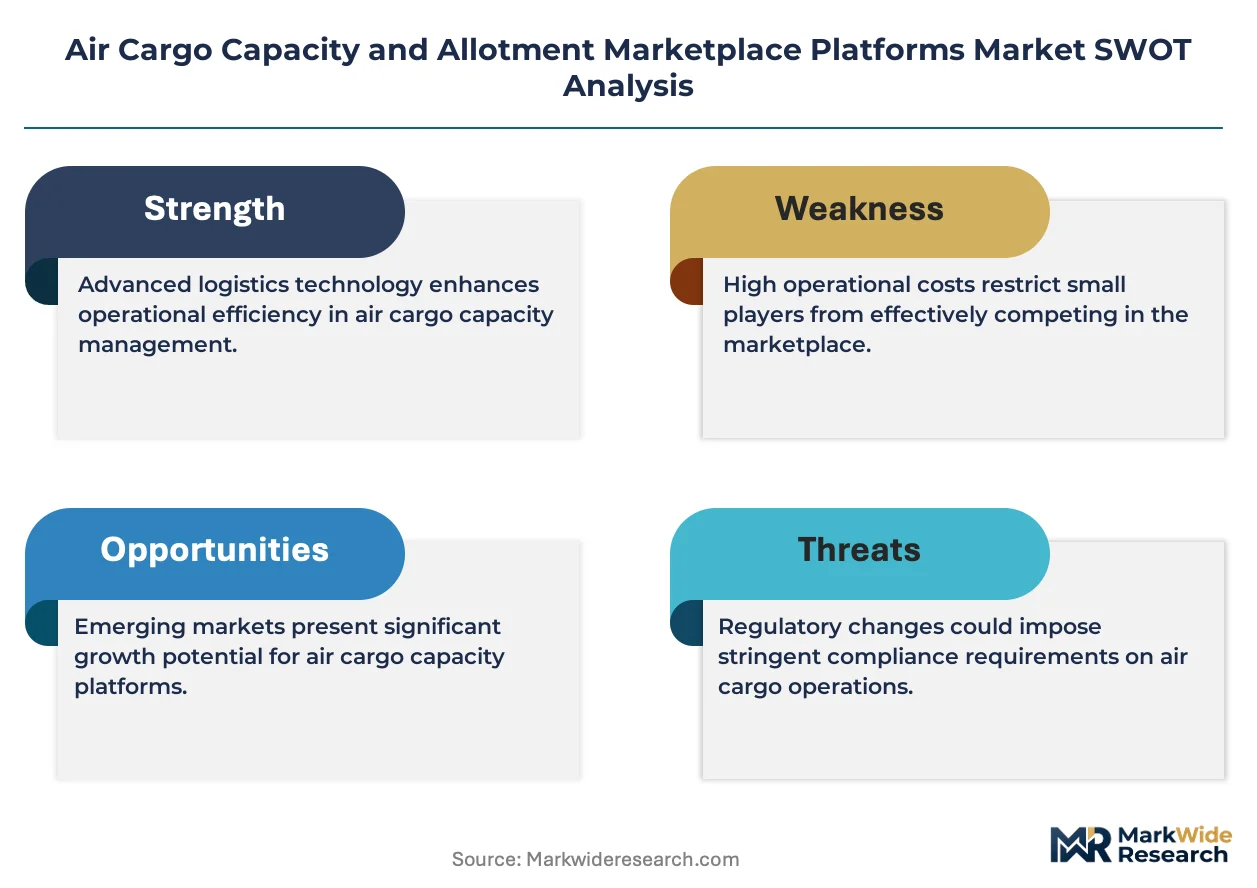
Vertical integration into proprietary carrier networks represents the decisive upstream lever as platform operators race to secure exclusive capacity commitments before regulatory certification requirements harden.
For Market Incumbents: Cement API modernization partnerships with Lufthansa Cargo and Air France-KLM to defend against neutral exchange disintermediation. Deepen backward integration into freight-rate databases through targeted data provider acquisitions. Yield management erosion from real-time pricing transparency threatens direct forwarder relationships.
For New Entrants and Emerging Players: Cloud-native deployment channels offer the fastest penetration route into mid-tier forwarders abandoned by legacy EDI systems. Target India pharmaceutical export corridors between Mumbai and Hyderabad where cold-chain infrastructure gaps create pre-booked allotment demand. Lead with IATA ONE Record certification to bypass protocol fragmentation barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor modular technology providers in European aviation IT corridors with carrier modernization backlogs. Long-term viability hinges on regulatory convergence around data interoperability standards. Watch for EU AI Act enforcement actions against opaque pricing algorithms as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| API Modernization Partnership | CHAMP Cargosystems extends modular booking tools to mid-tier airlines seeking marketplace participation. |
| Regulatory Certification Alignment | IATA ONE Record standard adoption determines platform eligibility for pharmaceutical lane contracts. |
| Freight-Rate Database Acquisition | WebCargo by Freightos leverages aggregated carrier connectivity to serve fragmented forwarder bases. |
| Cloud Infrastructure Expansion | cargo.one lowers integration barriers for small forwarders through direct European carrier API connections. |
| Blockchain Chain-of-Custody Pilot | Pharmaceutical verification programs expand where temperature-sensitive biologics margins justify implementation costs. |
Research Methodology
Independent corroboration across carrier cargo management executives, freight forwarder procurement leads, pharmaceutical supply chain directors, and aviation IT integration specialists underwrites the qualitative findings. Secondary validation draws from IATA operational data, EU regulatory filings, SEC carrier disclosures, and customs trade documentation. Bottom-up platform deployment counts triangulate against top-down carrier capacity estimates.
Comparable historical adoption curves for cargo digitization anchor projections across the analysis window. Segmentation models track platform type, deployment architecture, cargo vertical, and forwarder scale dimensions. CAGRs derive from carrier IT modernization spending patterns and pharmaceutical cold-chain volume trajectories. Forecast inputs incorporate F-Gas Regulation compliance deadlines and ONE Record certification timelines.
The model holds under steady regulatory convergence toward data interoperability standards; deviation in carrier yield management resistance or AI Act enforcement intensity would shift platform consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
North America Automotive Logistics Market
Logistics and Shipping
Australia Mining Logistics Market
Logistics and Shipping
Ocean Freight Software Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
Cross-Border Logistics Services Market