
 China Freight Forwarding Market | 2026-2036
China Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
China Freight Forwarding Market Insights
GB/T 30012 certification for multimodal transport operators is reorganizing competitive access in China freight forwarding. SINO Shipping leverages its Ningbo-Zhoushan port relationships to dominate containerized ocean exports. Winsky Freight sustains cross-border e-commerce specialization through Shenzhen customs zone positioning. DDPCHAIN anchors digital forwarding workflows with blockchain-integrated customs documentation platforms.
Freight forwarding coordinates the contractual and operational movement of goods across international trade lanes, encompassing cargo consolidation, customs brokerage, carrier selection, and documentation management under INCOTERMS governance. Ocean freight forwarding generates the largest revenue pool due to China's container export dominance, while rail freight through China-Europe corridors records the fastest route expansion as overland transit times compress against maritime alternatives. Technology segmentation shows blockchain adoption concentrating in customs clearance automation, whereas IoT deployment spreads across refrigerated container tracking for agricultural and pharmaceutical exports.
SAMR enforces logistics service standardization under national quality infrastructure mandates, while MEE carbon intensity rules for transport fleets reshape carrier procurement criteria. MIIT digital economy directives accelerate data analytics platform requirements for licensed forwarders. Stakeholders must monitor how dual carbon compliance timelines intersect with cross-border e-commerce volume thresholds to determine capacity allocation between traditional manufacturing exports and consumer direct fulfillment channels.
Market Dynamics
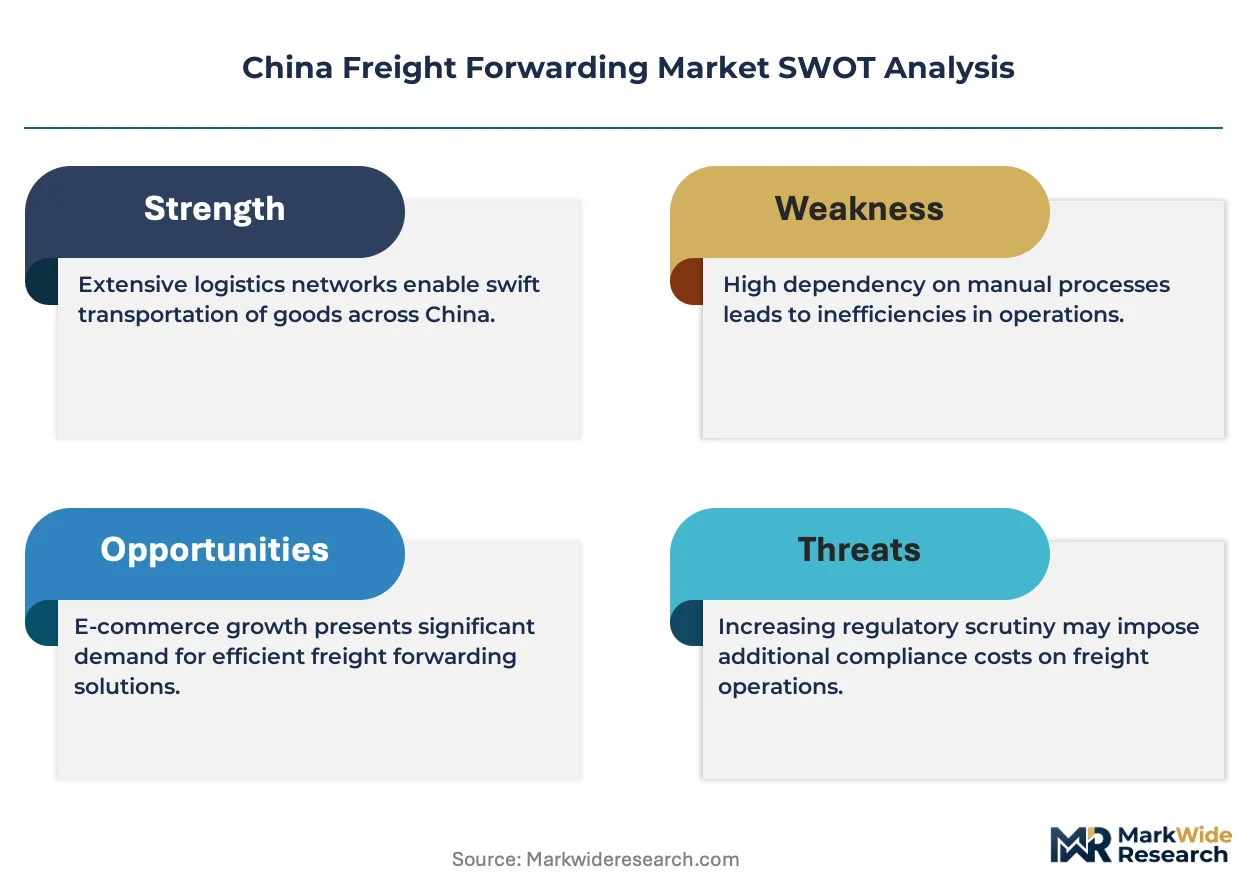
GB/T 30012 certification mandates are compressing market access for unqualified operators while concentrating volume among Ningbo-Zhoushan and Shenzhen corridor specialists with established multimodal capabilities.
Growth Catalysts
- Yangtze River Delta electronics exports:Semiconductor and consumer electronics manufacturers in Jiangsu and Zhejiang provinces are expanding bonded warehouse throughput, pulling specialized container consolidation services.
- MIIT digital platform mandates:Licensed forwarders must deploy data analytics infrastructure under national quality infrastructure directives, accelerating technology differentiation among compliant operators.
- Dual carbon compliance timelines:MEE carbon intensity rules for transport fleets are reshaping carrier procurement criteria toward lower-emission rail and short-sea options.
Market Restraints
- Carrier fuel cost volatility:Bunker price swings compress margin buffers for ocean freight operators locked into annual service contracts with shippers.
- Shenzhen customs zone concentration:Cross-border e-commerce volume dependence on single corridor infrastructure creates bottleneck vulnerability during peak season surges.
- Rail gauge incompatibility:China-Europe corridor freight requires transshipment at Dostyk and Brest due to track width differences, adding terminal handling costs and transit time variability.
Strategic Opportunities
- Western China rail terminals:Chongqing and Chengdu inland ports offer underutilized capacity for European-bound manufacturing exports seeking alternatives to coastal congestion.
- Blockchain-integrated customs documentation:Digital forwarding platforms that automate certificate-of-origin verification can capture documentation-intensive agricultural and pharmaceutical verticals.
- Guangdong-Hong Kong-Macao cold chain:Temperature-controlled pharmaceutical exports through Greater Bay Area corridors remain underserved by qualified reefer container operators.
Industry Challenges
- Licensed customs broker scarcity:GB/T 30012 certification requires specialized training in multimodal liability frameworks, constraining workforce scaling for expanding operators.
- Legacy ERP integration:Forwarders with established WMS infrastructure face API compatibility friction when connecting to MIIT-mandated national logistics data exchange platforms.
- Carbon accounting verification:Dual carbon compliance requires third-party audit trails for scope 3 emissions across subcontracted carrier networks, complicating reporting workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Freight Forwarding Market |
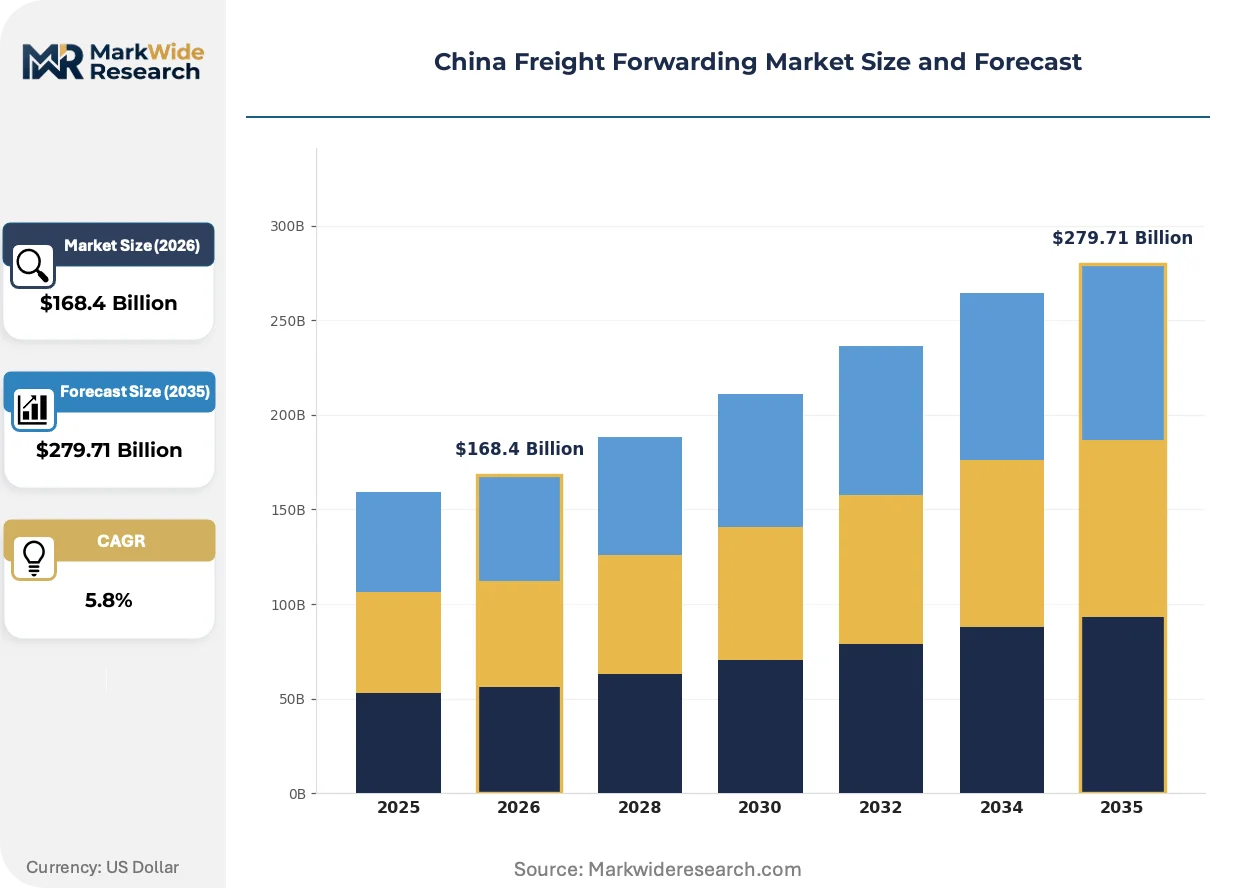
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $279.71 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Rail Freight, Road Freight End User: Manufacturers, Retailers, E-commerce, Exporters Technology: Blockchain, IoT, Automation, Data Analytics Packaging Type: Containers, Pallets, Crates, Bags |
| Companies Covered | Upfreights, Cargo From China, SINO Shipping, ET International Logistics, Shenzhen Fly Logistics, DDPCHAIN, Winsky Freight, Shenzhen Rich Fun Railway Logistics, Bansar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Freight Forwarding Market Trends and Innovations
Digital documentation protocols and sensor-enabled cargo monitoring are compressing information asymmetries between shippers and carriers, while regulatory pressure on emissions transparency accelerates technology substitution cycles.
Blockchain is decomposing traditional paper-based customs clearance workflows by creating immutable audit trails for certificate-of-origin and phytosanitary documentation. Agricultural exporters in Shandong and pharmaceutical manufacturers in Jiangsu are adopting these platforms fastest. This technology is decomposing the document preparation bottleneck that previously required 3-5 day processing windows at Shenzhen and Ningbo customs zones.
MEE carbon intensity disclosure rules now mandate fleet-level emissions reporting for all licensed multimodal operators under national quality infrastructure directives. Forwarders must procure only from carriers with verified carbon accounting systems or risk certification suspension. Rail freight through China-Europe corridors and short-sea coastal shipping are capturing volume as operators seek compliant transport modes.
Shippers in the Yangtze River Delta are consolidating freight procurement around integrated logistics service contracts that bundle ocean, rail, and last-mile delivery under single INCOTERMS governance. Traditional spot-market booking through fragmented broker networks is losing share to annual volume commitments with certified multimodal operators. Electronics manufacturers with European distribution requirements are driving this shift most aggressively.
China Freight Forwarding Market Segmentation
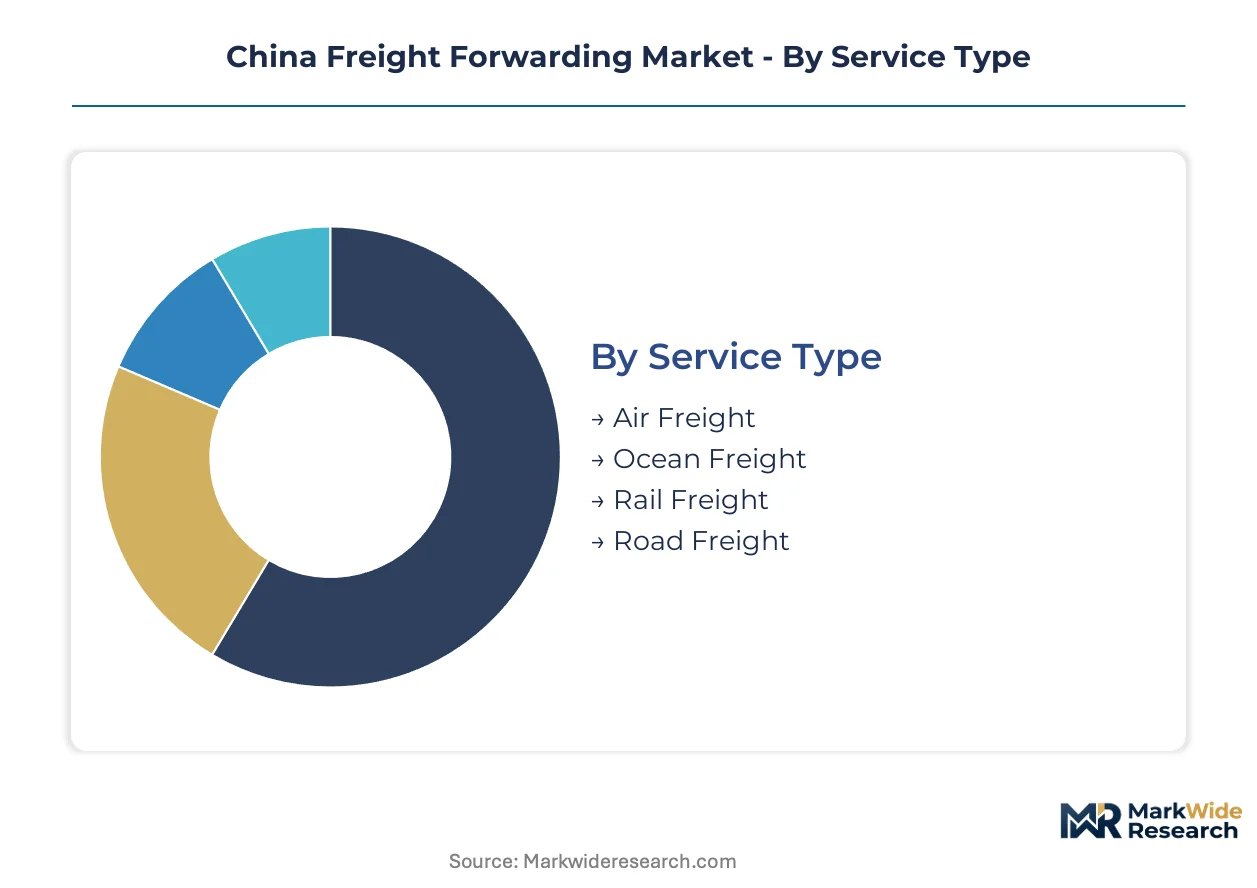
Freight forwarding segmentation in China reflects divergent margin structures across transport modes and customer verticals. Service type and technology deployment determine operator profitability, while end-user concentration shapes capacity allocation between coastal export corridors and inland rail terminals.
Service Type:
Ocean freight commands the deepest margin pools due to container export dominance through Ningbo-Zhoushan and Shenzhen ports, though rail freight is compressing transit time premiums on Europe-bound lanes.
- Ocean Freight:Full-container-load and less-than-container-load services dominate revenue concentration through Yangtze River Delta electronics exports. Annual service contracts with semiconductor manufacturers in Jiangsu and Zhejiang lock in volume commitments that stabilize forwarder margins against bunker price volatility.
- Rail Freight:China-Europe corridor services through Chongqing and Chengdu inland ports are expanding most quickly as overland transit times compress against maritime alternatives. MEE carbon intensity rules favor rail for compliant carrier procurement, though gauge incompatibility at Dostyk and Brest adds terminal handling costs.
- Air Freight:Time-definite services concentrate in pharmaceutical and high-value electronics verticals through Guangzhou and Shanghai Pudong cargo terminals.
- Road Freight:Last-mile and cross-border trucking services feed port and rail terminal consolidation networks across the Greater Bay Area corridor.
Ocean freight holds installed capacity. Rail freight is rotating up the share rankings.
End User:
Volume concentration tilts toward manufacturing exporters with bonded warehouse requirements, while e-commerce direct-to-consumer channels are fragmenting procurement patterns.
- Manufacturers:Electronics and automotive producers in Jiangsu and Zhejiang drive specialized container consolidation services through Yangtze River Delta bonded zones. GB/T 30012 certification requirements favor established multimodal operators with integrated ocean-rail capabilities.
- E-commerce:Cross-border direct fulfillment through Shenzhen customs zones demands real-time customs clearance and last-mile delivery bundling. Platform sellers require INCOTERMS-flexible contracts that shift liability at warehouse rather than port.
- Retailers:Omnichannel distributors consolidate procurement around integrated logistics service contracts spanning ocean, rail, and domestic distribution.
- Exporters:Agricultural and commodity shippers in Shandong and Hebei prioritize documentation-intensive customs brokerage for certificate-of-origin verification.
Manufacturers retain volume leadership. E-commerce is climbing the fastest among end-user categories.
Technology:
MIIT digital platform mandates are concentrating technology investment among licensed operators, with blockchain and data analytics capturing compliance-driven procurement.
- Blockchain:Immutable audit trails for phytosanitary and certificate-of-origin documentation are decomposing 3-5 day customs clearance bottlenecks at Shenzhen and Ningbo zones. Agricultural exporters in Shandong and pharmaceutical manufacturers in Jiangsu adopt these platforms fastest.
- Data Analytics:Predictive cargo routing and carrier performance scoring satisfy MIIT-mandated infrastructure requirements for licensed forwarders. Analytics platforms differentiate compliant operators from spot-market brokers.
- IoT:Sensor-enabled refrigerated container tracking serves temperature-controlled pharmaceutical exports through Greater Bay Area corridors.
- Automation:Robotic process automation for customs documentation and billing workflows reduces manual processing costs.
Blockchain holds regulatory priority. Data analytics is gaining share fastest among technology deployments.
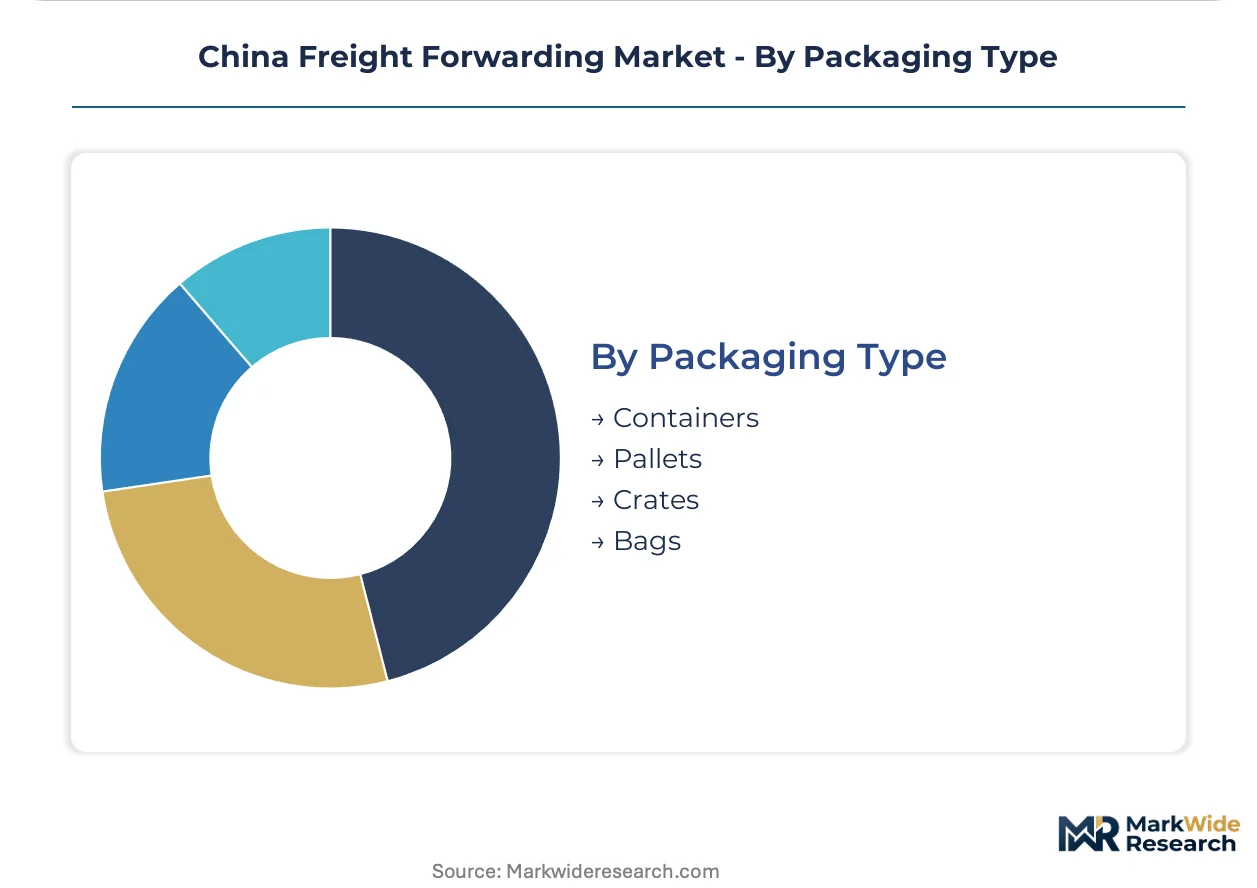
Packaging Type:
Container standardization dominates export corridors, though pallet and crate formats serve specialized agricultural and machinery verticals with non-standard dimensional requirements.
- Containers:ISO-standard dry, refrigerated, and open-top units handle 90%+ of ocean and rail export volume through Ningbo-Zhoushan and Shenzhen terminals. Electronics manufacturers specify high-cube containers for density optimization on China-Europe rail.
- Pallets:Euro-pallet and Asia-pallet formats facilitate cross-docking at Western China rail terminals for European distribution.
- Crates:Engineered wood and steel crating protects machinery and automotive components during multimodal transshipment.
- Bags:Flexible intermediate bulk containers serve agricultural commodity exports from Shandong and Henan provinces.
Containers maintain volume dominance. Pallet utilization is expanding most quickly with rail corridor growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT digital platform mandates and SAMR logistics standardization policies are concentrating freight forwarding capacity in coastal export corridors and inland rail terminals across China's major economic zones.
Yangtze River Delta
Semiconductor and consumer electronics manufacturers in Jiangsu and Zhejiang provinces are expanding bonded warehouse throughput. GB/T 30012 certification requirements favor established multimodal operators with integrated ocean-rail capabilities. Ningbo-Zhoushan port handles the densest container consolidation services for European-bound exports.
Pearl River Delta
Cross-border e-commerce platform sellers demand real-time customs clearance and last-mile delivery bundling through Shenzhen customs zones. MEE carbon intensity rules reshape carrier procurement toward lower-emission short-sea options. Guangzhou and Shenzhen terminals concentrate pharmaceutical cold chain exports.
Beijing-Tianjin-Hebei
Automotive and machinery manufacturers drive specialized container consolidation for Belt and Road corridor access. SAMR national quality infrastructure directives accelerate data analytics platform requirements for licensed forwarders. Tianjin port anchors North China ocean freight forwarding volume.
Sichuan-Chongqing
Western China rail terminals offer underutilized capacity for European-bound manufacturing exports seeking alternatives to coastal congestion. Dual carbon compliance timelines intersect with cross-border e-commerce volume thresholds. Chongqing and Chengdu inland ports expand China-Europe corridor services.
Shandong Peninsula
Agricultural exporters prioritize documentation-intensive customs brokerage for certificate-of-origin verification. Blockchain adoption concentrates in phytosanitary documentation automation. Qingdao and Yantai ports serve refrigerated container tracking for agricultural exports.
China Freight Forwarding Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and corridor positioning. The vendor base organizes around three tiers: Ningbo-Zhoushan port relationship holders, Shenzhen customs zone specialists, and blockchain-integrated digital platform operators. Strategic moves concentrate on GB/T 30012 certification acquisition and multimodal capability bundling under single INCOTERMS governance.
Within the port-relationship tier, SINO Shipping and Winsky Freight exemplify geographic anchoring strategies. SINO Shipping occupies a position tied to Ningbo-Zhoushan container export dominance, while Winsky Freight sits within the Shenzhen corridor specialization for cross-border e-commerce. DDPCHAIN represents the digital-forwarding archetype with blockchain-integrated customs documentation platforms. These three patterns—port-proximate, customs-zone-embedded, and technology-layered—capture the competitive structure reshaping under MIIT and SAMR mandates.
| Leading Market Players |
|---|
| Upfreights |
| Cargo From China |
| SINO Shipping |
| ET International Logistics |
| Shenzhen Fly Logistics |
| DDPCHAIN |
| Winsky Freight |
| Shenzhen Rich Fun Railway Logistics |
| Bansar |
| Others |
Pricing and Supply Chain Analysis
Rail freight substitution for ocean cargo on China-Europe corridors is simultaneously redrawing supply geography toward Chongqing and Chengdu inland ports while compressing transit-time premiums that previously sustained higher pricing tiers for maritime services.
Pricing Analysis
Certification level under GB/T 30012 standards creates the primary spread between premium multimodal operators and spot-market brokers. Three-tier pricing structure across certified premium, compliant standard, and uncertified economy levels segments buyer segments, with electronics manufacturers in Jiangsu showing lowest price sensitivity due to bonded warehouse integration requirements. Cost compression in economy-tier ocean freight is intensifying because bunker price volatility erodes annual contract margins. Cross-border e-commerce platform sellers through Shenzhen customs zones exhibit highest price sensitivity, driving procurement toward bundled service contracts with real-time clearance guarantees.
Supply Chain Analysis
Strategic stockpiling preferences dominate electronics and automotive verticals, with manufacturers maintaining bonded warehouse buffers at Yangtze River Delta ports to buffer against customs clearance variability. Geographic supply concentration rests on Ningbo-Zhoushan and Shenzhen as primary ocean consolidation points, with Chongqing and Chengdu emerging as rail corridor alternatives. Container equipment, bonded warehouse capacity, and licensed customs broker availability constitute critical input dependencies. Single-source vulnerability concentrates in Shenzhen customs zone infrastructure for cross-border e-commerce peak seasons. Distribution runs through multimodal operator networks with integrated ocean-rail-last-mile capabilities under single INCOTERMS governance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive access as MIIT-mandated data exchange infrastructure forces interoperability investments that favor operators with pre-integrated digital forwarding stacks.
For Market Incumbents: Compound corridor dominance through backward integration into Chongqing and Chengdu rail terminal capacity, securing underutilized Western China infrastructure before volume shifts accelerate. Defend certification moats by accelerating GB/T 30012 training pipelines to address licensed customs broker scarcity that constrains competitor scaling.
For New Entrants and Emerging Players: Anchor in blockchain-integrated documentation automation for agricultural and pharmaceutical verticals in Shandong and Jiangsu, where certificate-of-origin verification bottlenecks create service gaps. Target cold chain reefer services through Guangdong-Hong Kong-Macao corridors as qualified operator capacity lags pharmaceutical export growth.
For Investors and Strategic Acquirers: Capital is best deployed toward digital-forwarding platforms with MIIT-compliant data analytics infrastructure and established multimodal certification under GB/T 30012 frameworks. Long-term viability hinges on dual carbon compliance capabilities that align carrier procurement with MEE emissions disclosure mandates. Monitor China-Europe rail volume thresholds as the signal indicating permanent modal shift away from ocean freight dominance.
| Strategic Initiative | Industry Significance |
|---|---|
| GB/T 30012 Certification Acquisition | Unlocks multimodal operator licensing required for Yangtze River Delta electronics contracts under SAMR quality infrastructure directives. |
| Western China Rail Terminal Expansion | Captures European-bound manufacturing volume seeking alternatives to Ningbo-Zhoushan coastal congestion. |
| Blockchain Customs Documentation Platform | Automates phytosanitary verification for Shandong agricultural exporters facing 3-5 day clearance bottlenecks. |
| Dual Carbon Compliant Carrier Procurement | Satisfies MEE fleet emissions reporting requirements that condition multimodal operator licensing renewal. |
| Integrated Logistics Service Contract Bundling | Consolidates ocean-rail-last-mile procurement for electronics manufacturers under single INCOTERMS governance. |
Research Methodology
A standing panel of freight forwarding operations directors, SAMR compliance officers, bonded warehouse managers, and cross-border e-commerce logistics coordinators provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with secondary validation through MIIT policy circulars, SAMR standardization notices, MEE emissions disclosure filings, and China-Europe rail corridor volume statistics. Bottom-up carrier procurement data and top-down regional export flow estimates underwent iterative reconciliation.
Consistency checks validated volume and value outputs against external benchmarks including multimodal operator licensing registries and customs zone throughput disclosures. The analytical framework modeled service type, end user vertical, technology deployment, and packaging format segments across the projection horizon. CAGRs derived from corridor-specific volume trajectories and pricing tier evolution, with rail gauge incompatibility costs and bunker price volatility incorporated as scenario variables.
Material uncertainties — regulatory enforcement intensity for GB/T 30012 compliance, carbon accounting verification standardization, and China-Europe political corridor stability — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued electronics export growth and e-commerce platform expansion. Revision becomes warranted when rail transit time compression accelerates beyond current modal shift thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
China Same Day Delivery Market
Logistics and Shipping
Turkey Third Party Logistics (3PL) Market
Logistics and Shipping
India Contract Logistics Market
Logistics and Shipping
Logistics Visualization System Market
Logistics and Shipping
South Korea Parcel Delivery Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market