
 Delivery Tracking Platform Market | 2026-2036
Delivery Tracking Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Delivery Tracking Platform Market Outlook
API-first cloud infrastructure is rebalancing platform economics away from heavy on-premise server deployments toward lightweight, integrable SaaS models. Project44 leverages its carrier network density to sustain data-rich visibility across multimodal freight corridors. FourKites anchors its position through predictive ETA algorithms that reduce detention penalties for shippers. AfterShip competes by extending its post-purchase tracking layer into branded customer experience workflows for retailers.
A delivery tracking platform is a software system that ingests telemetry from GPS, RFID, and telematics hardware to calculate real-time shipment location, estimated arrival times, and exception alerts for logistics operators and end consumers. These platforms process location updates at sub-minute intervals through cloud-native architectures to enable proactive exception management and customer self-service. SaaS platforms currently dominate commercial uptake due to lower capital requirements and faster onboarding cycles, while integrated systems capture premium value among enterprise shippers requiring ERP and WMS connectivity. Machine learning capabilities within the technology dimension are expanding fastest as carriers deploy predictive models for route disruption and capacity forecasting.
The Federal Communications Commission governs spectrum allocation for GPS and cellular tracking devices in the United States, directly shaping hardware compatibility and signal reliability standards for platform vendors. The European Union's GDPR and the proposed EU AI Act impose data governance and algorithmic transparency requirements on cross-border shipment monitoring and automated delivery predictions. India's TRAI and the Ministry of Electronics and Information Technology are advancing data localization mandates that affect cloud hosting architectures for domestic logistics networks. Stakeholders must evaluate regulatory divergence across these jurisdictions when architecting data residency and AI model deployment strategies.
Market Dynamics
Cloud-native API architectures are compressing deployment timelines from months to weeks, forcing incumbent vendors to abandon monolithic legacy stacks and reprice subscription tiers downward to defend retention against agile challengers.
Growth Catalysts
- India's data localization mandates:TRAI and MeitY requirements are accelerating domestic cloud infrastructure buildout, creating captive demand for locally hosted tracking platforms that process telemetry within national borders.
- RFID-telephony convergence:Hybrid sensor fusion across warehousing and vehicle fleets is generating sub-minute location granularity that shippers now specify in procurement contracts.
- GDPR Article 17 compliance:Automated data deletion workflows for consumer delivery histories are becoming a table-stakes feature, pulling platform investment toward privacy-engineered architectures.
Market Restraints
- Cellular module supply concentration:GPS-GSM chipset fabrication concentrates in East Asian foundries, exposing hardware-dependent platforms to component allocation volatility during semiconductor demand surges.
- FCC spectrum licensing friction:Device certification timelines for new cellular tracking hardware extend 12-18 months, delaying feature rollouts for vendors dependent on proprietary hardware stacks.
- Open-source telemetry standards:Community-driven alternatives to proprietary location APIs are eroding vendor lock-in and compressing differentiation margins for data-layer specialists.
Strategic Opportunities
- EU AI Act algorithmic transparency:Predictive ETA engines that document decision logic will capture premium positioning among European enterprise shippers facing automated decision accountability requirements.
- Germany's pharmaceutical cold chain:GDP-compliant temperature-location fusion tracking remains underpenetrated, with specialized validation workflows creating defensible vertical moats.
- Blockchain-IoT attestation:Immutable proof-of-delivery records for high-value freight are converging with smart contract settlement, opening new revenue streams in dispute resolution and insurance verification.
Industry Challenges
- Embedded systems firmware talent:Scarce expertise in low-power GPS optimization and edge computing is extending R&D cycles and inflating compensation for specialized engineering roles.
- ERP-WMS integration complexity:Bespoke middleware requirements for SAP and Oracle connectivity are consuming 40-60% of implementation resources and delaying customer go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Delivery Tracking Platform Market |
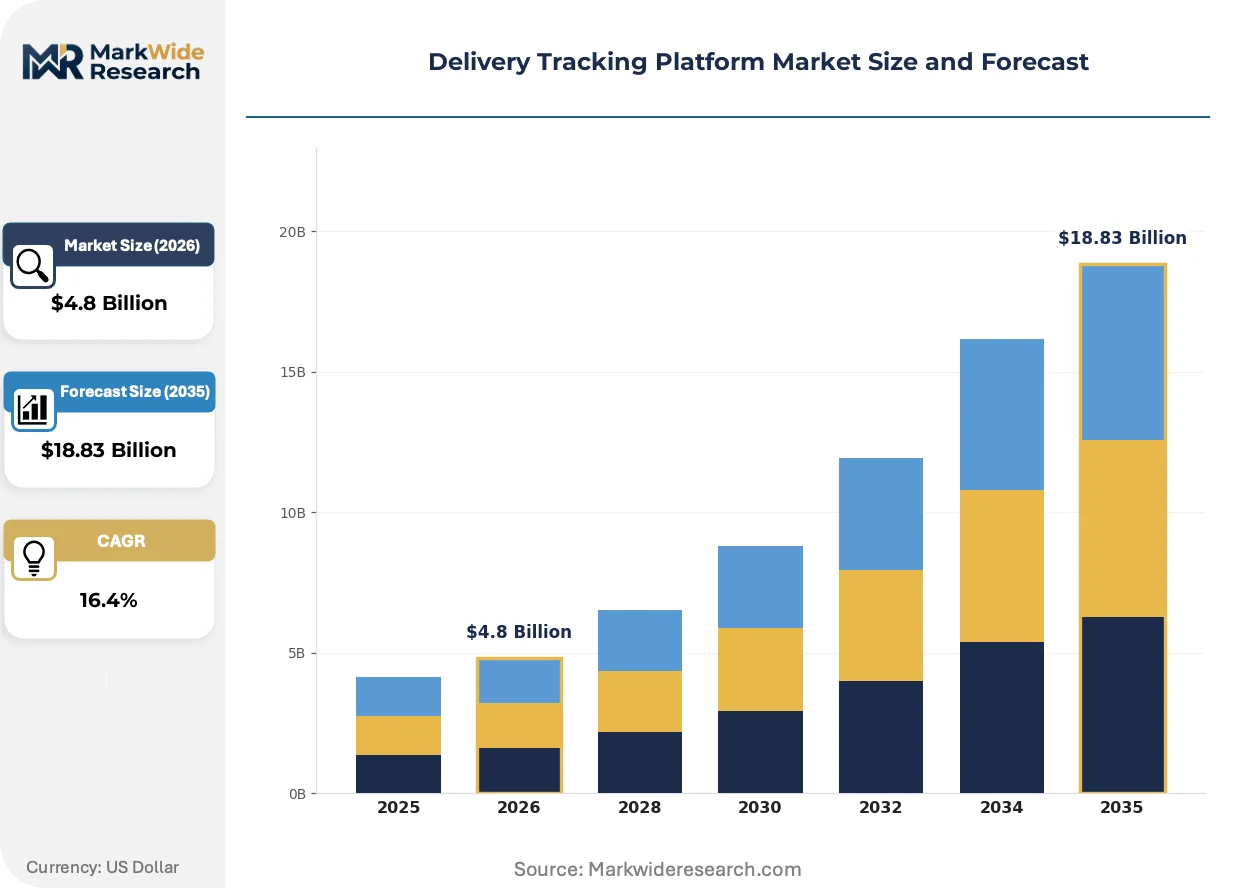
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.83 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-demand Solutions, SaaS Platforms, Integrated Systems, Mobile Applications End User: E-commerce, Retailers, Logistics Providers, Third-party Delivery Services Feature: Real-time Tracking, Notifications, Analytics, Route Optimization Technology: GPS Tracking, RFID, Cloud Computing, Machine Learning |
| Companies Covered | Project44, FourKites, AfterShip, FarEye, UPS, FedEx, DHL, ShipStation, Onfleet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Delivery Tracking Platform Market Strategic Shifts
Machine learning inference at the network edge is displacing cloud-only processing architectures, compressing latency for exception alerts while reducing data egress costs that previously eroded SaaS margins.
Computer vision is automating parcel-level identification and damage detection at sortation hubs. E-commerce fulfillment networks in the United States are deploying camera arrays at 15% annual expansion rates. This capability is automating manual quality assurance workflows and compressing labor dependency in high-throughput facilities.
The EU AI Act's risk classification framework for automated delivery predictions is mandating human-in-the-loop overrides for high-stakes logistics decisions. European platform vendors are reengineering inference pipelines to expose confidence thresholds and alternative routing options. Pharmaceutical and perishable freight segments are absorbing the steepest compliance costs as they fall under "high-risk" algorithmic application categories.
Shippers are consolidating vendor relationships around platforms that bundle visibility, carbon accounting, and invoice audit capabilities. Retail procurement teams in Germany and India are displacing point solutions with integrated suites that reduce supplier management overhead. This pattern concentrates contract value among vendors with multi-module roadmaps and compresses standalone tracking specialists into acquisition targets.
Delivery Tracking Platform Market Segmentation
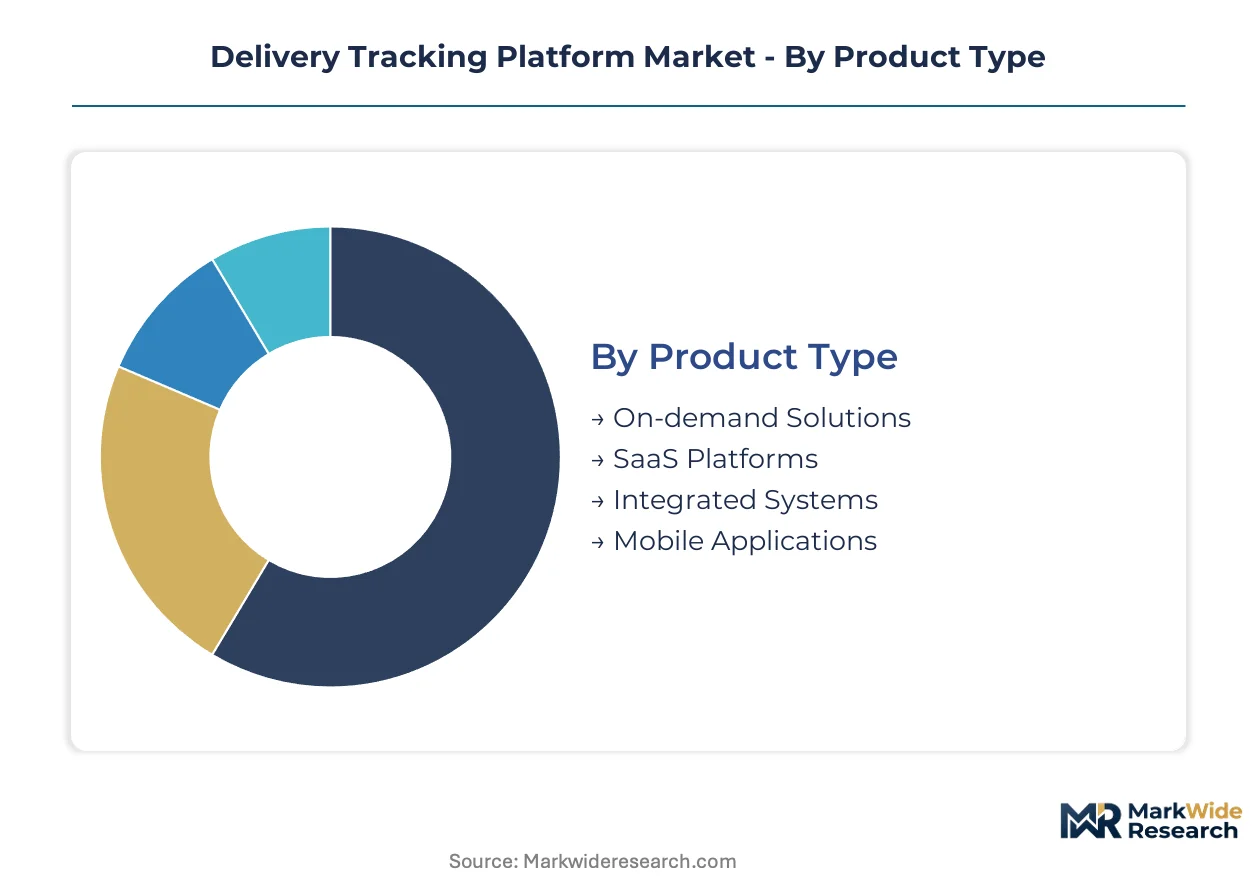
Delivery tracking platforms segment across deployment models, user workflows, and data processing layers. Procurement teams evaluate these dimensions jointly when selecting vendors for multimodal freight visibility.
Product Type:
Customization intensity varies sharply across this spectrum, from configurable SaaS tiers to deeply integrated enterprise stacks requiring bespoke middleware.
- SaaS Platforms:Multi-tenant cloud architectures deliver API-first telemetry ingestion with subscription pricing. Demand concentrates among mid-market shippers in Germany seeking rapid onboarding without capital expenditure. GDPR Article 17 automated deletion workflows differentiate compliant vendors.
- Integrated Systems:On-premise or private-cloud deployments embed directly into SAP and Oracle ERP environments. Enterprise logistics operators in the United States specify these for WMS connectivity and custom SLA enforcement. Implementation cycles extend 6-12 months due to middleware complexity.
- On-demand Solutions:Pay-per-shipment models serve seasonal volume spikes and spot freight procurement. Third-party delivery services in India deploy these for festival-period capacity surges without annual commitments.
- Mobile Applications:Driver-facing interfaces capture proof-of-delivery signatures and exception photographs. Last-mile carriers prioritize offline functionality for cellular dead zones in rural delivery corridors.
Most installed capacity flows through SaaS Platforms. Expansion is steepest in Integrated Systems as enterprise shippers consolidate point solutions.
End User:
Volume concentration and margin sensitivity diverge across buyer types, with e-commerce platforms driving API call volume while logistics providers capture contract value through SLA penalties.
- E-commerce:Marketplaces and direct-to-consumer brands consume tracking infrastructure at massive scale. Indian e-commerce fulfillment networks are expanding domestic cloud capacity to meet TRAI data localization mandates. Real-time consumer-facing maps and predictive ETAs reduce cart abandonment and support ticket volume.
- Logistics Providers:Asset-heavy carriers deploy tracking platforms for fleet optimization and detention penalty avoidance. United States trucking operators prioritize predictive ETA engines that reduce shipper penalties at distribution centers. API connectivity to shipper TMS platforms determines contract renewal rates.
- Retailers:Branded post-purchase tracking pages extend customer lifetime value. German retailers integrate carbon accounting modules to meet CSRD supply chain disclosure requirements.
- Third-party Delivery Services:Gig-economy platforms match couriers to orders through location telemetry. Driver churn drives demand for lightweight onboarding and instant activation.
Contract value concentrates with Logistics Providers. E-commerce is expanding most quickly as fulfillment networks deepen last-mile density.
Feature:
Functional depth separates premium tiers from baseline offerings, with analytics and optimization modules commanding subscription uplifts of 40-60 percent.
- Real-time Tracking:Sub-minute location updates from GPS, RFID, and telematics fusion. Pharmaceutical cold chains in Germany specify GDP-compliant temperature-location correlation for regulatory validation.
- Route Optimization:Machine learning models recalculate paths based on traffic, weather, and capacity constraints. United States parcel carriers deploy these to reduce miles per stop in urban delivery zones.
- Notifications:Automated SMS, email, and push alerts for exceptions and ETA changes. Retail procurement teams treat branded notification templates as customer experience infrastructure.
- Analytics:Historical performance dashboards and carrier scorecards. Logistics providers use these for contract renegotiation and network design decisions.
Deployment density is highest for Real-time Tracking. Route Optimization is gaining share fastest as fuel costs and detention penalties intensify.
Technology:
Processing location and inference workloads distributes across edge, cloud, and hybrid architectures with diverging latency and cost profiles.
- Cloud Computing:Centralized data lakes and API gateways enable multi-tenant scalability. Indian logistics networks are migrating to domestic cloud regions to satisfy MeitY data residency requirements.
- Machine Learning:Predictive models for ETA, route disruption, and capacity forecasting. The EU AI Act is mandating human-in-the-loop overrides and decision documentation for European deployments.
- GPS Tracking:Satellite-based positioning remains the foundational location layer. FCC spectrum allocation governs device certification timelines and signal reliability standards in the United States.
- RFID:Passive and active radio-frequency identification for yard management and parcel sortation. Hybrid RFID-telephony fusion is generating procurement-mandated sub-minute granularity.
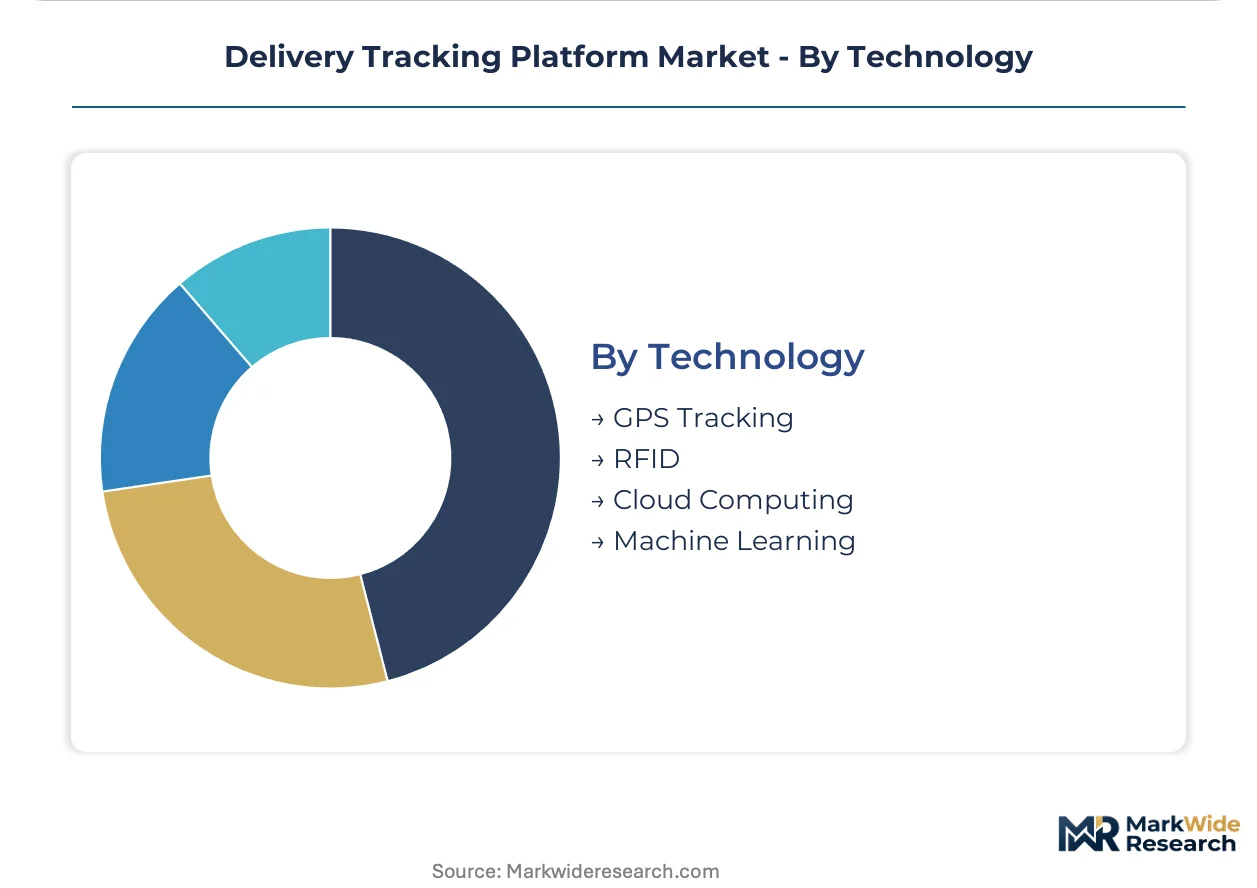
Processing volume concentrates in Cloud Computing. Machine Learning is climbing the fastest as carriers deploy predictive capabilities for exception management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr logistics corridor anchors European demand for multimodal visibility infrastructure as shippers consolidate vendor relationships around integrated platform suites.
United States
E-commerce fulfillment networks in the Midwest and Southeast drive API call volume for real-time tracking infrastructure. The Federal Communications Commission governs spectrum allocation for GPS and cellular devices, directly shaping hardware certification timelines. Chicago and Dallas-Fort Worth host dense concentrations of third-party logistics providers deploying predictive ETA engines to reduce detention penalties.
Germany
Pharmaceutical cold chain operators specify GDP-compliant temperature-location fusion tracking for regulatory validation. The EU AI Act imposes algorithmic transparency requirements on automated delivery predictions, mandating human-in-the-loop overrides. The Frankfurt-Rhine-Main logistics cluster concentrates demand for ERP-integrated systems among enterprise chemical and automotive shippers.
India
Festival-period e-commerce surges create seasonal demand spikes for on-demand tracking solutions without annual commitments. TRAI and the Ministry of Electronics and Information Technology advance data localization mandates that accelerate domestic cloud infrastructure buildout. Mumbai and Bengaluru anchor fulfillment network expansion as retailers invest in post-purchase customer experience layers.
China
Cross-border e-commerce platforms consume tracking infrastructure at massive scale for consumer-facing delivery maps. The Ministry of Industry and Information Technology shapes telematics hardware standards through GB certification requirements. The Yangtze River Delta logistics cluster generates procurement demand for sub-minute RFID-telephony fusion granularity in smart warehousing.
United Kingdom
Retail procurement teams integrate carbon accounting modules to meet CSRD supply chain disclosure requirements for EU market access. GDPR Article 17 automated deletion workflows differentiate compliant vendors in cross-border shipment monitoring. The Midlands distribution hub concentrates last-mile carrier demand for driver-facing mobile applications with offline functionality.
Delivery Tracking Platform Market Competitive Environment
Global majors compete with regional champions across API connectivity and carrier network density, producing a tiered structure where scale-driven platforms absorb contract value from point-solution specialists. The vendor base separates into three strategic archetypes: cloud-native visibility aggregators, ERP-integrated enterprise suites, and post-purchase experience layers for direct-to-consumer brands. Dominant competitive moves include strategic partnerships with telematics hardware vendors and portfolio diversification into carbon accounting and invoice audit capabilities.
Within the cloud-native tier, Project44 and FourKites occupy positions defined by carrier network density and predictive algorithm deployment respectively. AfterShip exemplifies the customer-experience archetype, extending tracking infrastructure into branded post-purchase workflows. These three companies represent the strategic vectors—multimodal freight visibility, predictive logistics intelligence, and retail-facing delivery experience—that structure competitive differentiation in platform selection.
| Leading Market Players |
|---|
| Project44 |
| FourKites |
| AfterShip |
| FarEye |
| UPS |
| FedEx |
| DHL |
| ShipStation |
| Onfleet |
| Others |
Value Chain & Pricing Dynamics
EU AI Act algorithmic transparency mandates gate qualified supply for predictive ETA engines, reserving premium-tier pricing access to vendors that document decision logic and deploy human-in-the-loop overrides for European enterprise shippers.
Pricing Analysis
Input-cost pass-through from GPS-GSM chipset fabrication concentrates in East Asian foundries, compressing margins for hardware-dependent platform tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by API call volume, ERP integration depth, and machine learning inference capability. Pricing pressure stems from open-source telemetry standards eroding proprietary data-layer margins. Mid-market shippers in Germany exhibit highest price sensitivity, while United States enterprise logistics operators absorbing detention penalty costs show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for cellular module fabrication, exposing tracking hardware platforms to semiconductor allocation volatility. Cloud-native architectures draw from domestic data center buildout in India, Germany, and the United States to satisfy data localization mandates. Supply chain risk centers on FCC spectrum licensing friction extending device certification timelines. Distribution runs through direct SaaS subscription sales for mid-market segments and systems integrator partnerships for enterprise ERP-integrated deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's data localization mandates create captive domestic cloud infrastructure demand at lower compliance cost than European GDPR-EU AI Act dual frameworks.
For Market Incumbents: To counter open-source telemetry standards eroding data-layer differentiation, Project44 and FourKites should deepen carrier network density through exclusive telematics hardware partnerships and accelerate carbon accounting module bundling to capture retail procurement consolidation in Germany and India. For New Entrants and Emerging Players: A 40-60 percent subscription uplift gap between baseline real-time tracking and premium route optimization tiers opens white-space targeting of GDP-compliant temperature-location fusion for German pharmaceutical cold chains and on-demand pay-per-shipment models for India's festival-period e-commerce surges, with API-first rapid onboarding as the go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for standalone tracking specialists facing procurement consolidation because shippers are displacing point solutions with integrated visibility-carbon-invoice suites. Long-term viability favors vendors with multi-module roadmaps spanning predictive ETA, carbon accounting, and blockchain-IoT attestation. The signal to watch is carrier scorecard consolidation into single-vendor enterprise contracts.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Cloud-native architectures compress deployment timelines from months to weeks for mid-market shippers. |
| Machine Learning Inference at Edge | Edge computing reduces latency for exception alerts and data egress costs eroding SaaS margins. |
| Carbon Accounting Module Bundling | CSRD supply chain disclosure requirements in Germany drive retail procurement consolidation around integrated suites. |
| Blockchain-IoT Attestation Partnership | Immutable proof-of-delivery records open revenue streams in high-value freight dispute resolution. |
| Domestic Cloud Infrastructure Expansion | TRAI and MeitY data localization mandates in India accelerate captive demand for locally hosted platforms. |
Study Parameters
Multiple input streams — primary interviews with logistics technology executives, carrier fleet operators, and retail procurement managers, plus secondary validation through SEC filings, customs telemetry hardware trade data, and hyperscaler cloud region capex disclosures — were reconciled through bottom-up and top-down triangulation across deployment models, end-user workflows, and technology processing layers.
Cross-referencing historical platform adoption curves against expert panel inputs anchored CAGR derivation across the analysis window. Segmentation dimensions modeled encompass SaaS versus integrated deployment, e-commerce versus logistics provider end-use, and cloud versus edge versus hybrid processing architectures. Forecast inputs incorporated carrier network density expansion rates and API call volume scaling patterns from fulfillment network buildout in the United States, Germany, and India.
Caveats apply where FCC spectrum licensing delays, EU AI Act compliance cost inflation, or cellular module supply shocks could materially shift the outlook. Forecasts reflect documented assumptions about data localization enforcement intensity and open-source telemetry standard adoption velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Mexico Containerized Shipping Market
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Hazardous Goods Logistics Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
US Dangerous-Hazardous Goods Logistics Market
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Contract Logistics Market